


SignalPlus Macro Research Report (20230907): Welcome to the Bad September Market.


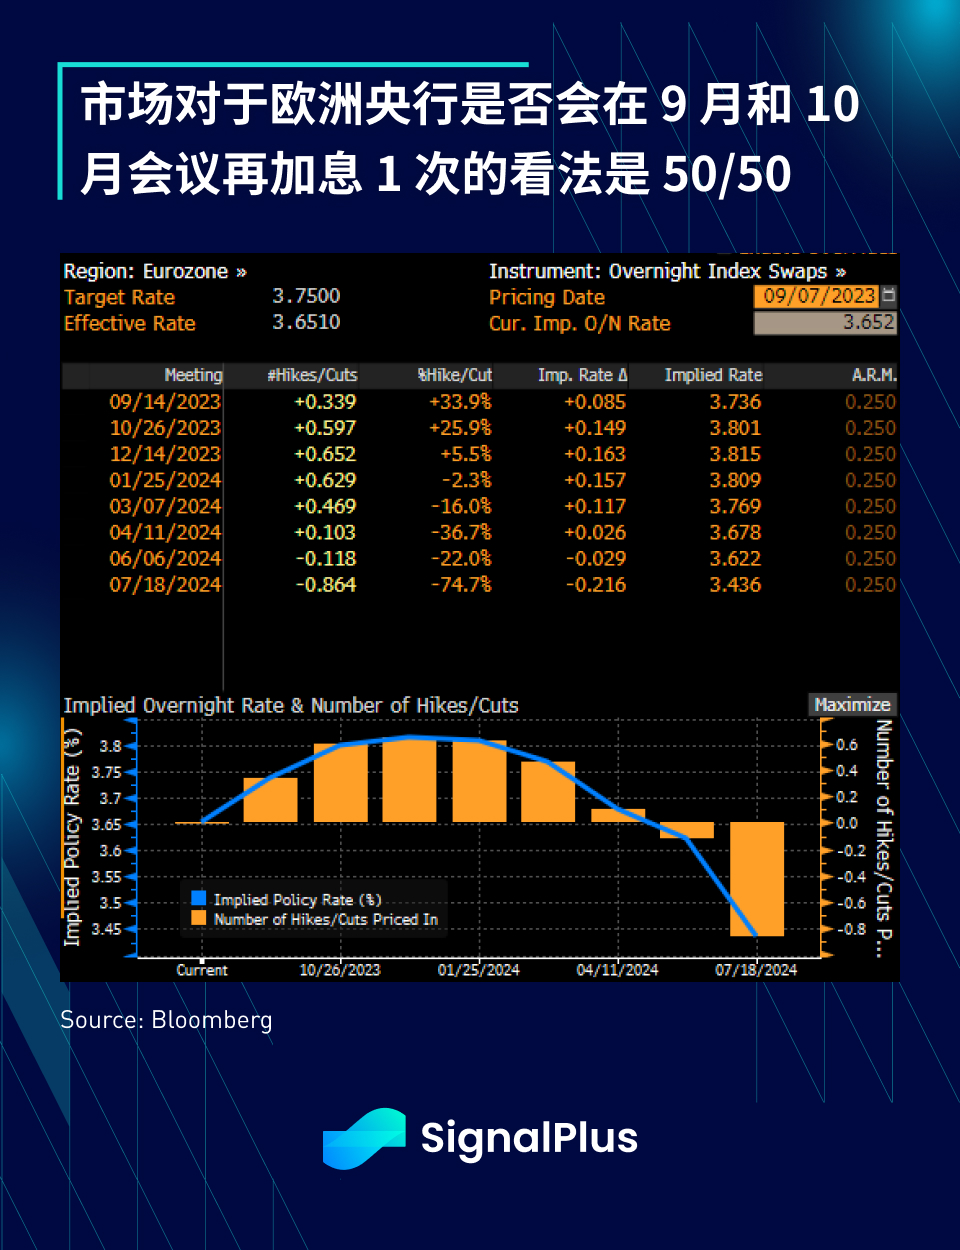
Peace in the Asian trading session was disrupted by a series of hawkish comments from the European Central Bank (Knot said "the market underestimated the possibility of a rate hike in September," Kazimir preferred to raise rates in September). This pushed up the 2-year German government bond yield by 7 basis points, overshadowing the impact of weak German factory order data (down 11.7% compared to the previous month). The current market pricing for a rate hike by the European Central Bank next week is 33%, and the market is split 50/50 on whether the European Central Bank will hike rates again.
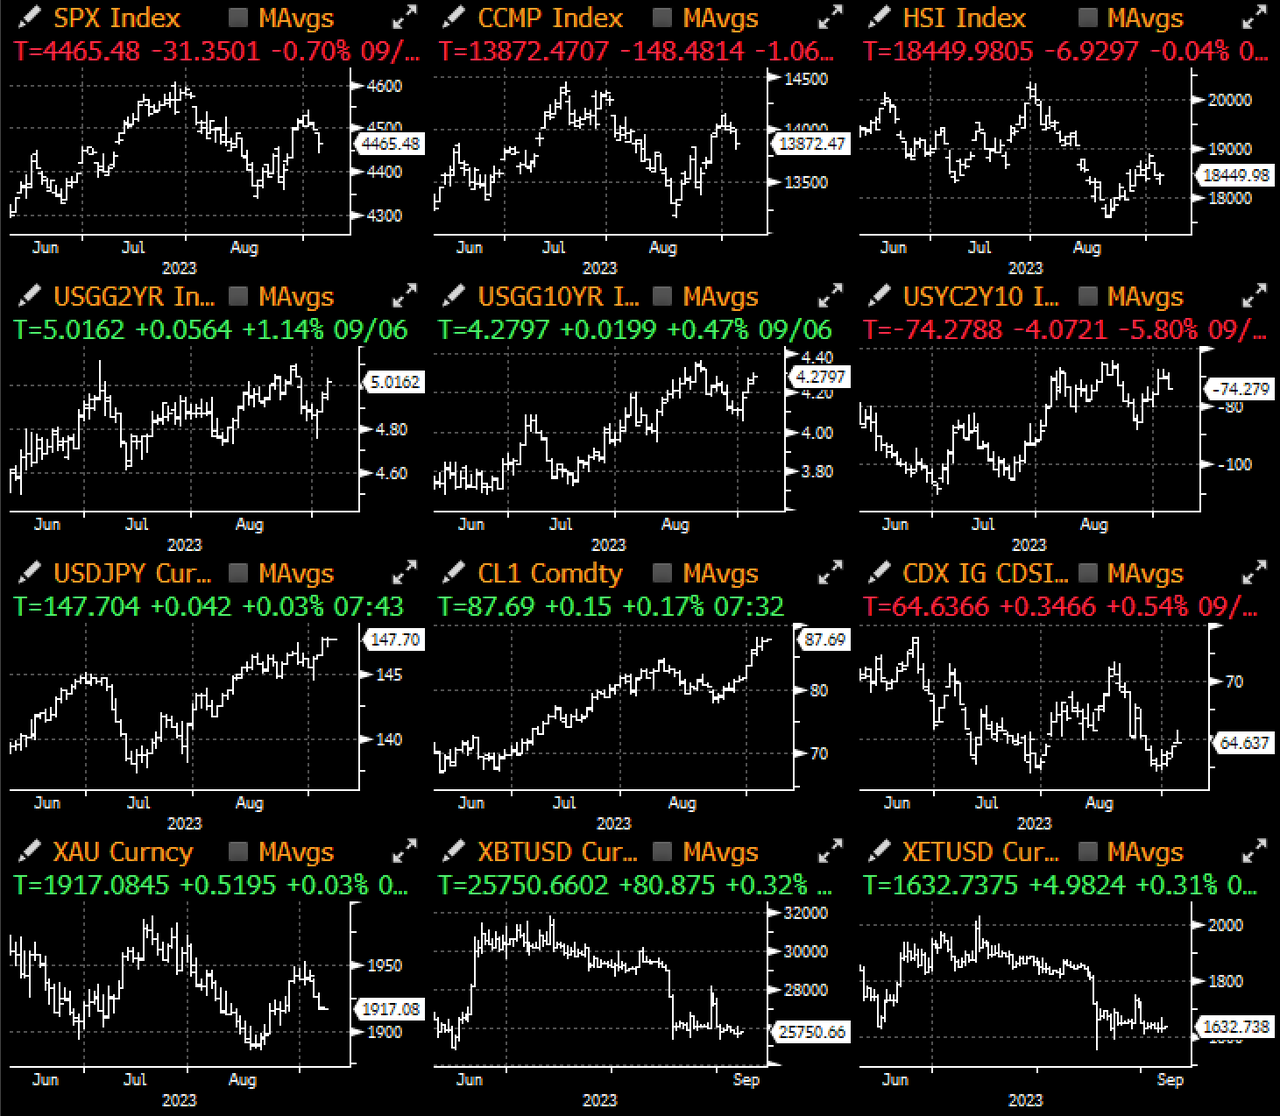
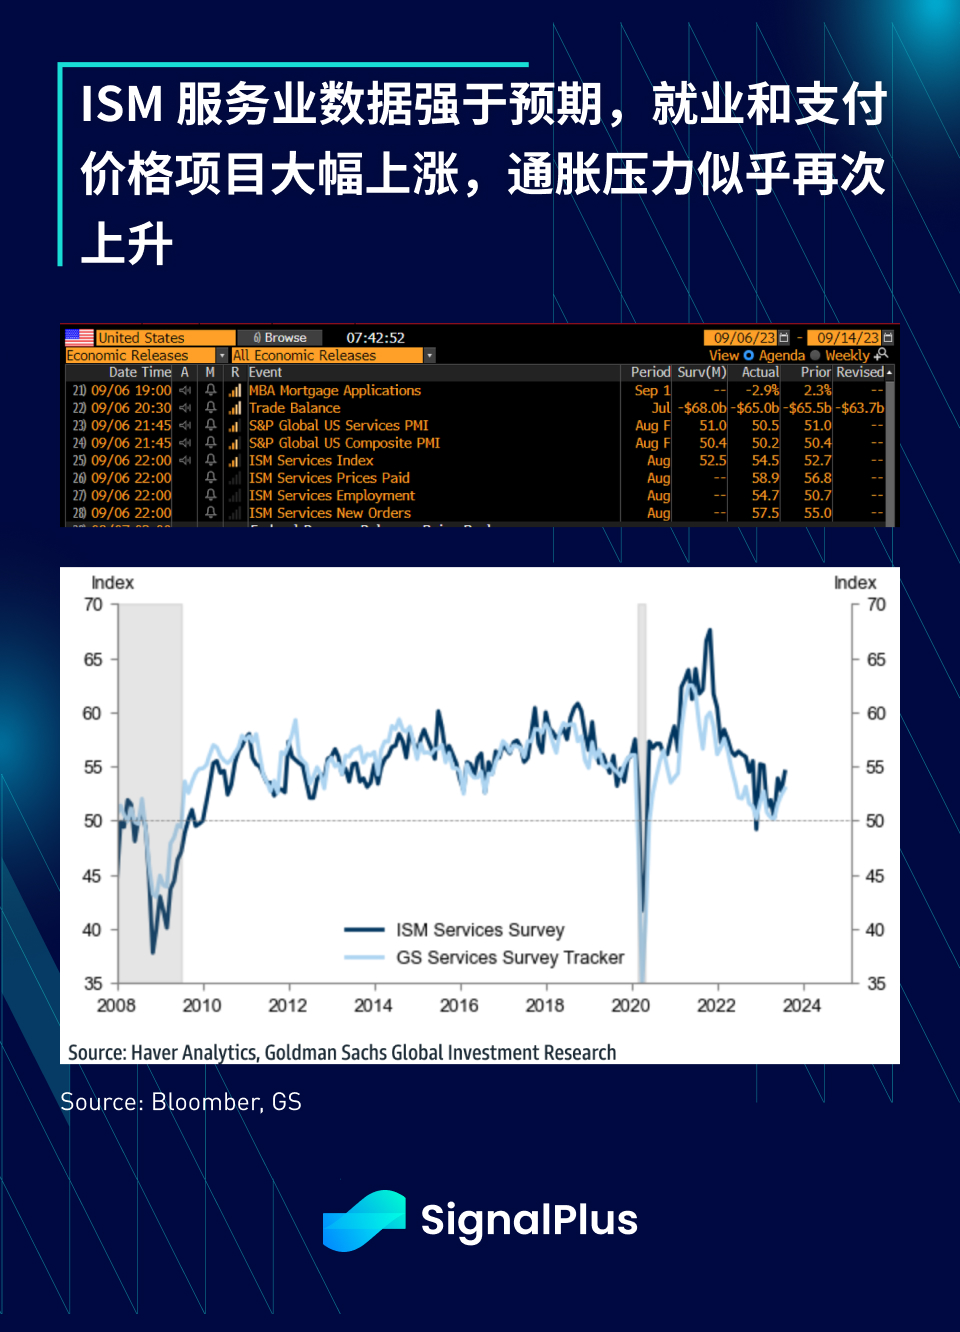
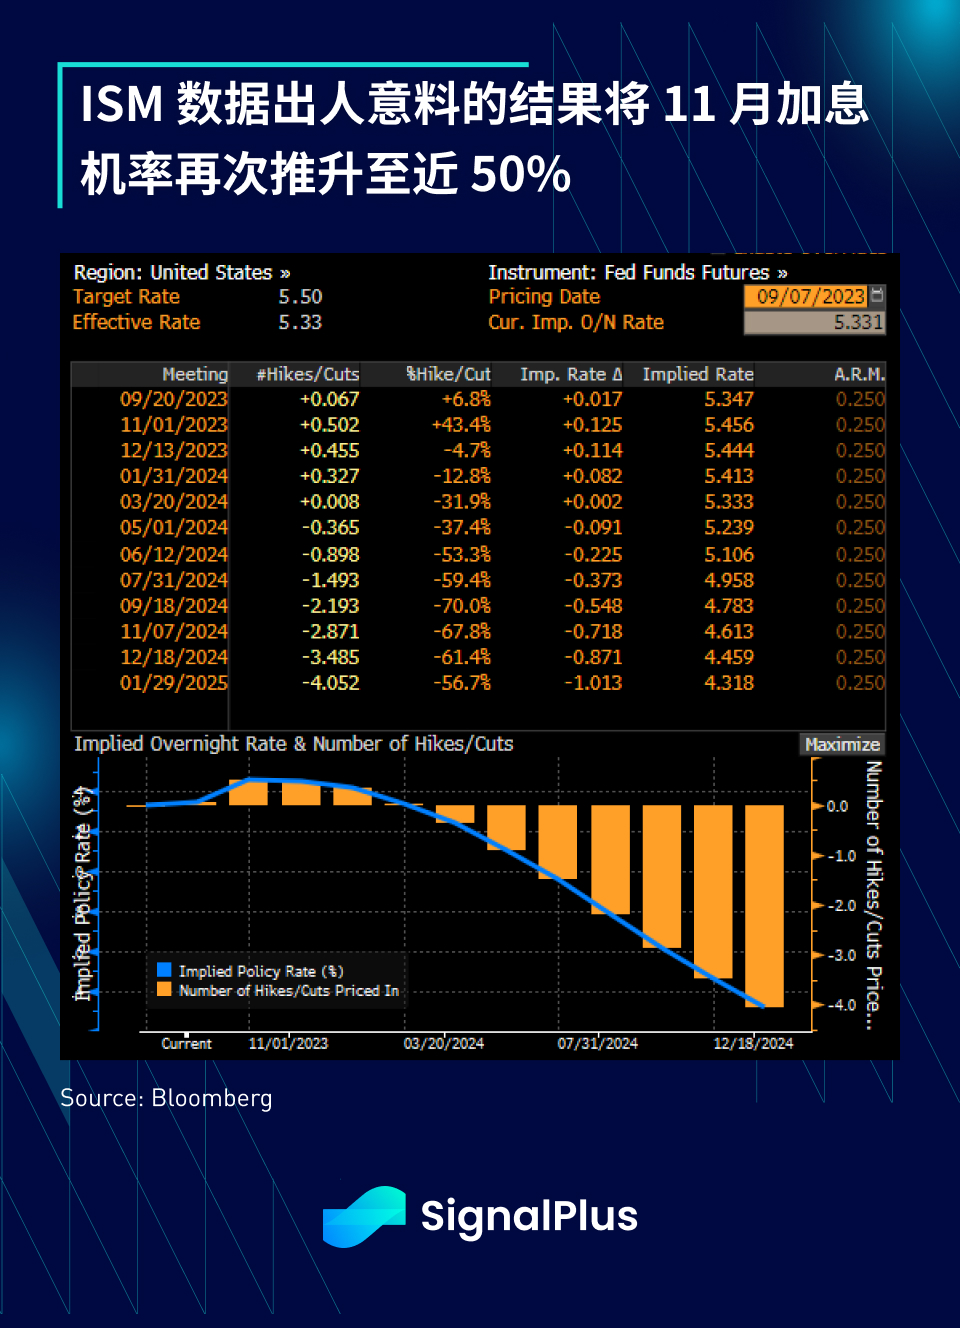
In the US bond market, more than $34 billion in bond issuance was conducted yesterday to lock in financing rates (from investment-grade corporations). Bond yields are still trying to recover, but the strong ISM Non-Manufacturing Index pushed the 2-year yield above 5% again. The probability of a rate hike in November also rose to 45%. The ISM data results contrast sharply with the recent soft job data, with the employment component reaching the highest level since November 2021, and the prices paid component jumping to 58.9 (from 56.8) and new orders rising to 57.5 (from 50).
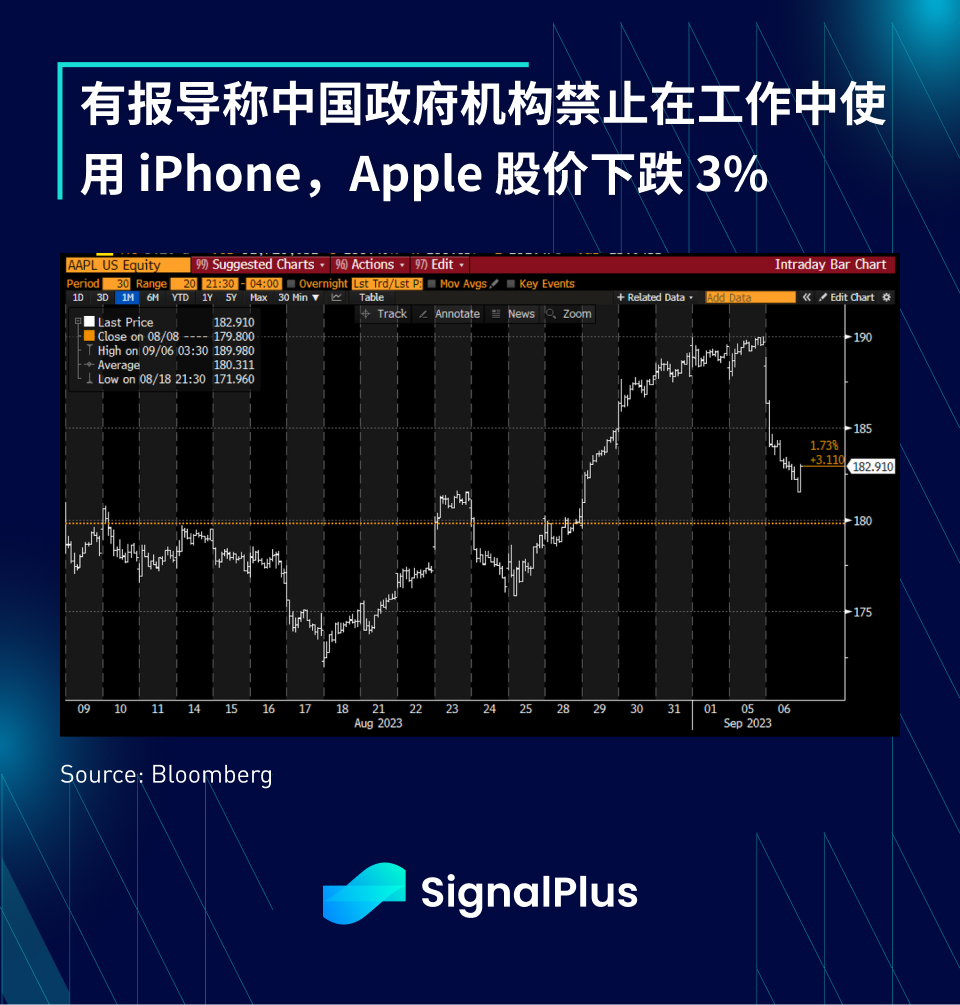
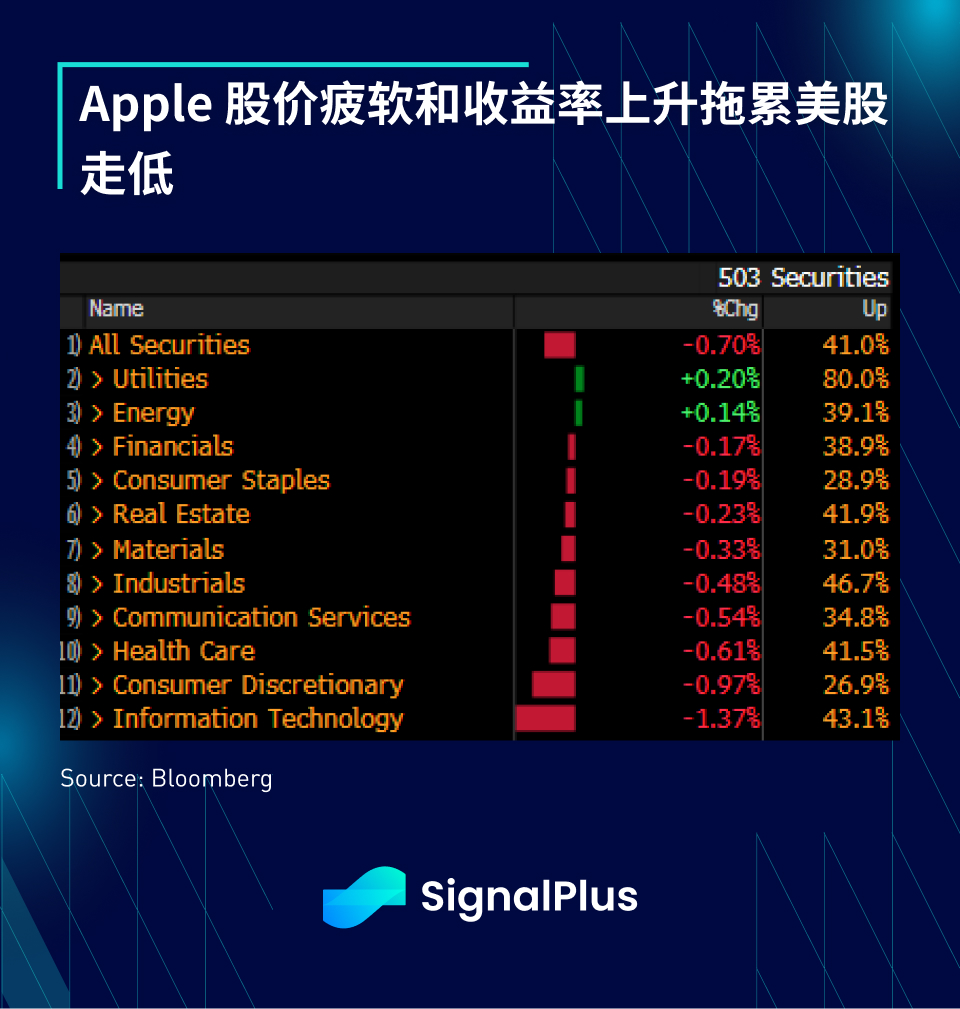
The stock market performed poorly, with the Nasdaq index falling nearly 1%. In addition to the impact of rising yields, there were also reports that Chinese government agencies had prohibited the use of iPhones and other foreign branded devices in the workplace, which dragged down Apple's stock price by 3% and led to a 1.3% drop in the SPX Technology Sector Index.
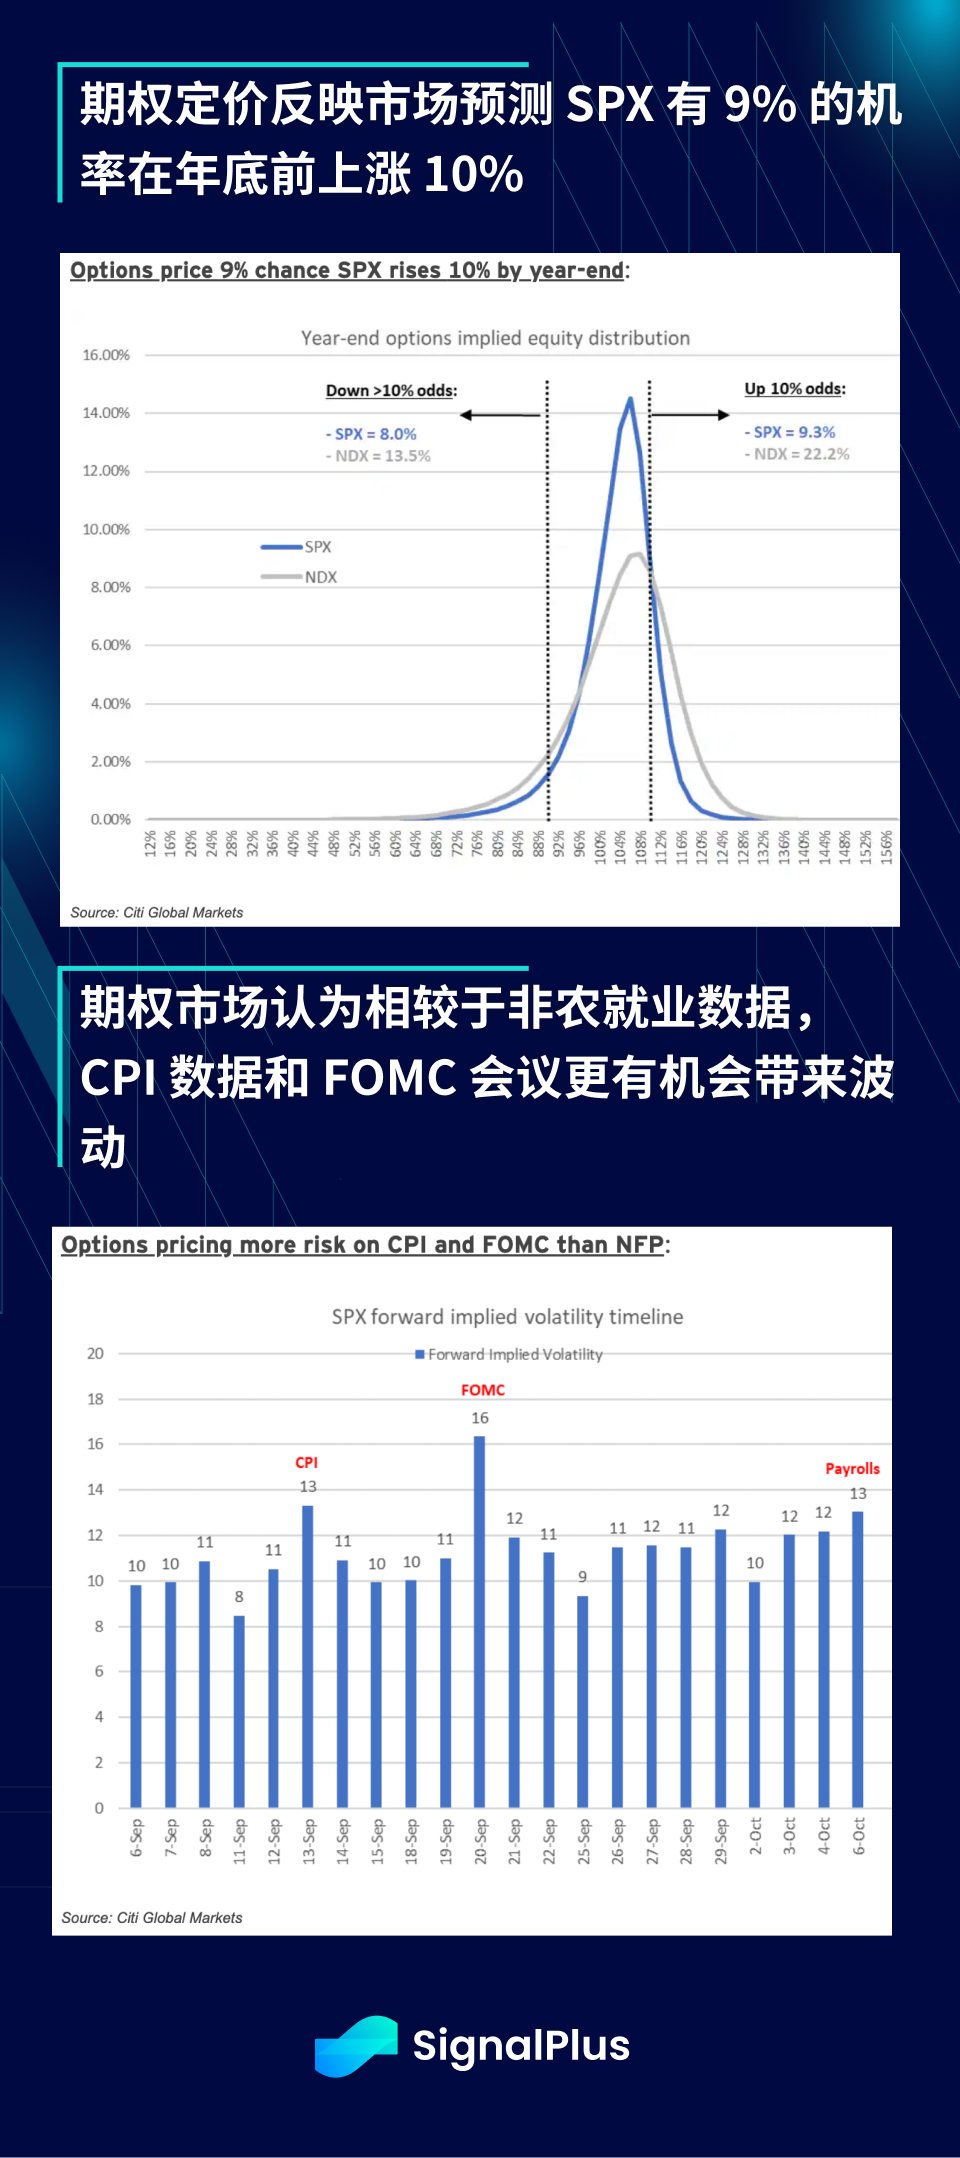
Despite the stock market downturn, stock option positions remain optimistic, with the implied price probability distribution significantly skewed to the right, indicating a bullish outlook for the SPX and Nasdaq indices. At the same time, the implied volatility of the SPX remains stable, indicating that the market does not expect significant volatility from upcoming CPI and non-farm payroll data, or even the upcoming FOMC meeting, reflecting a much smaller premium than usual.
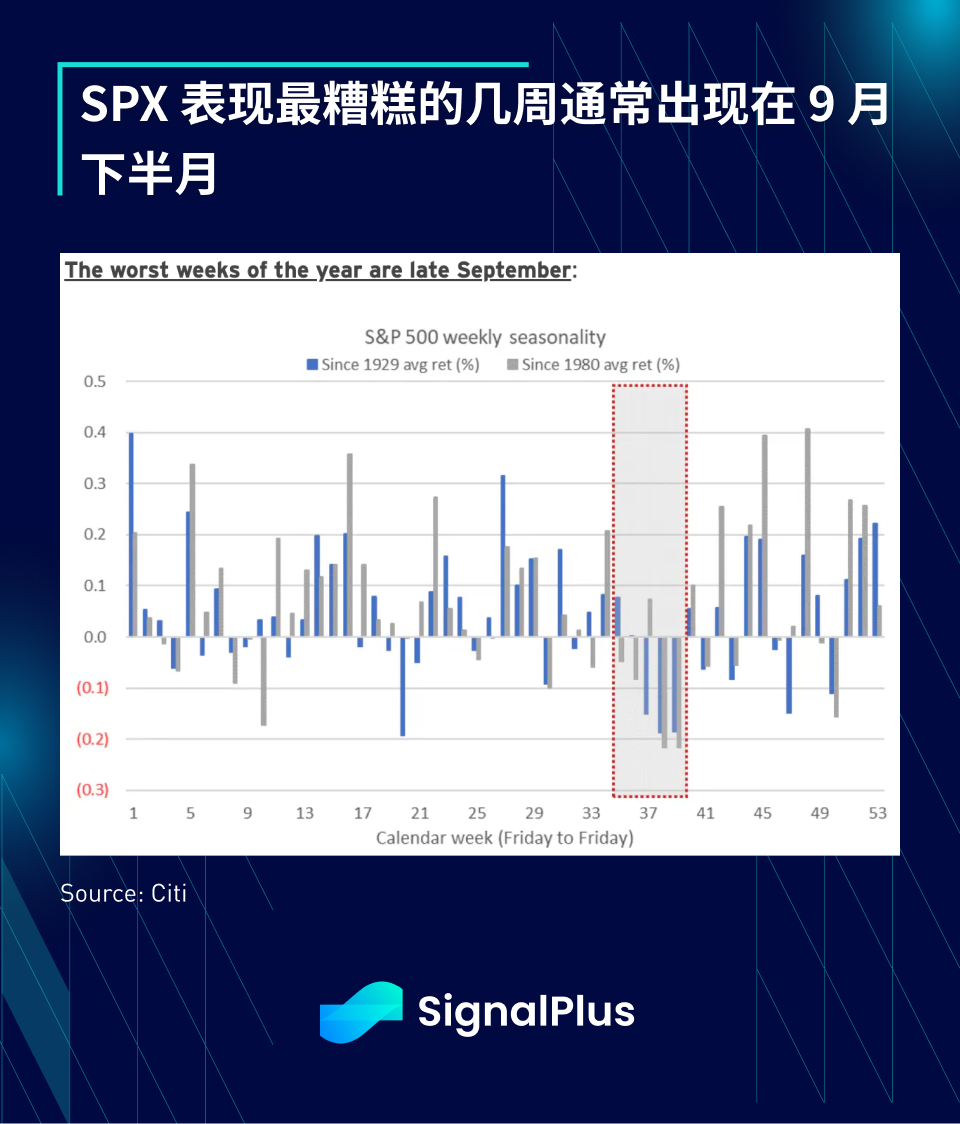
The seasonal performance of the S&P 500 is well-known for being poor, with historically the worst weeks occurring in the latter half of September. However, the market seems quite satisfied with the current risk allocation, showing great confidence as it welcomes the second half of September.
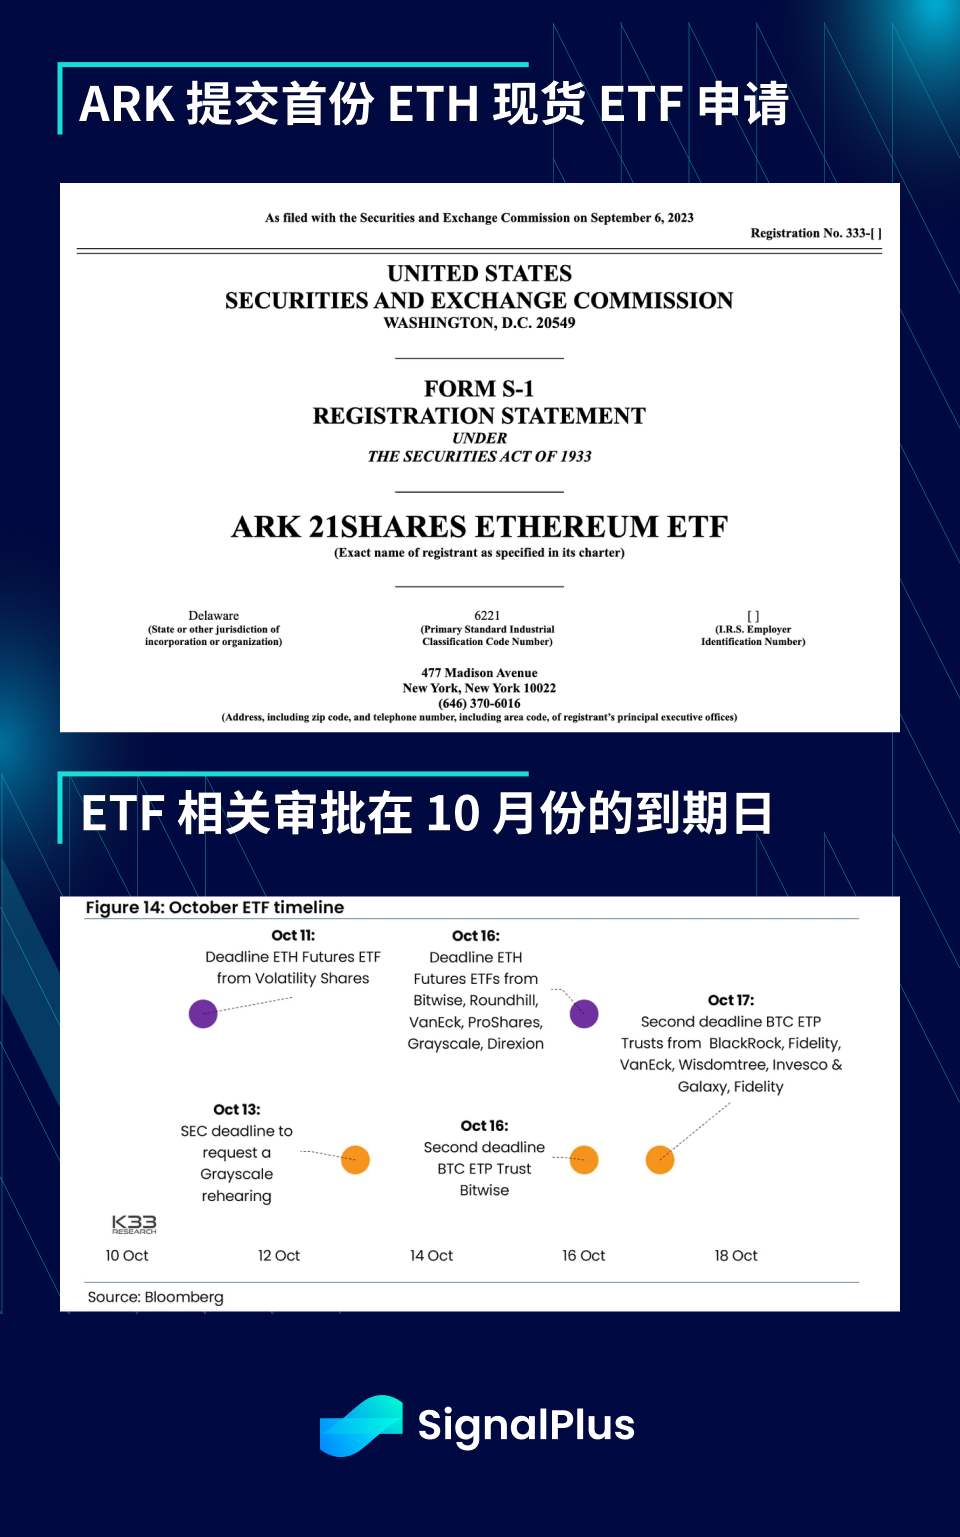
With the release of ISM services data, it is unlikely that any market-moving events will be seen this week. In the cryptocurrency space, despite Cathie Wood's ARK submitting its first spot ETF application to the SEC yesterday, there was no significant price movement in cryptocurrencies. October will be a busy month for the SEC and ETF applications, with many BTC ETF approval "second deadlines" approaching, the "final" deadline for ETH futures ETF, and the window for the SEC to demand a re-meeting of the Grayscale case.
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption news. If you want to receive our updates instantly, please follow our Twitter account @SignalPlus_Web3, or join our WeChat group (add assistant WeChat: chillywzq), Telegram group, and Discord community to interact and communicate with more friends.
SignalPlus Official Website: https://www.signalplus.com





