


SignalPlus Macro Research Report Special Edition: This is the best of times and the worst of times


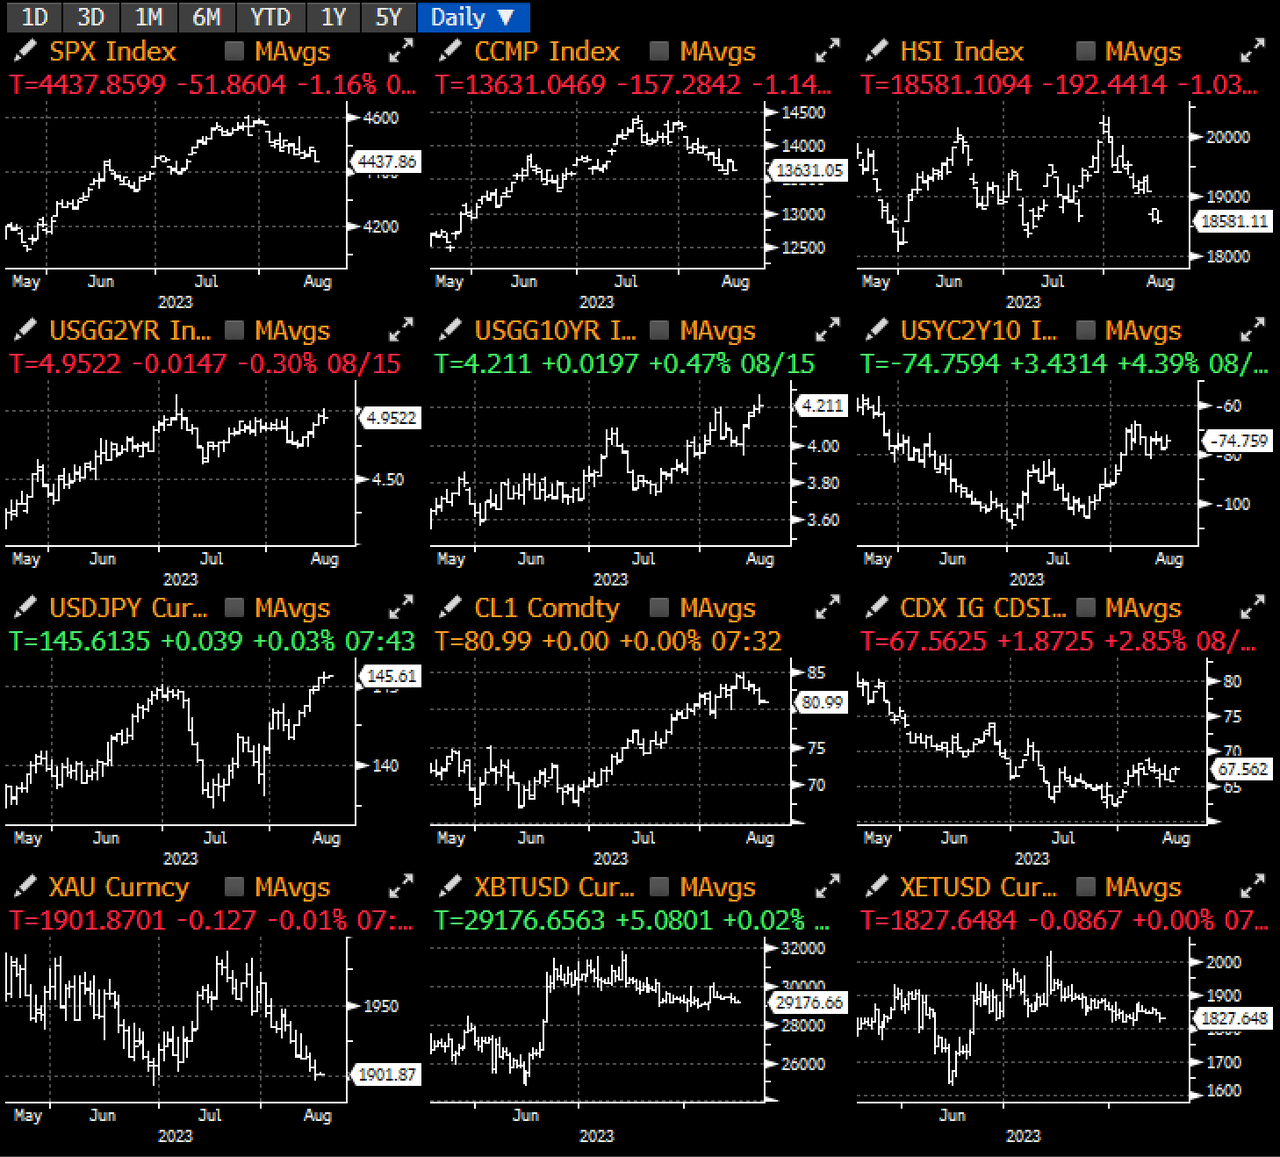
Weve been saying it over and over since last week,Risk markets are starting to feel the pressure, driven by a combination of higher real yields in the U.S. (rates are higher for longer) and continued weakness in the Chinese economy, two important economies are currently heading in diametrically opposite directions, with one trying to slow inflation and an overheating job market while the other is trying to salvage rapidly contracting economic activity,Stock markets fell in both economies, albeit for completely different reasons。
First in China,The excitement brought about by the unexpected cut in the lending facility rate (2.65% -> 2.50%) was quickly offset by weak retail sales and industrial production data, the National Bureau of Statistics also announced that due to the need to further sound and optimize the labor force survey statistics, it will stop publishing youth unemployment data, which naturally raises concerns about whether the local employment situation is already quite serious; was resolved, both A-shares and the Hang Seng Index failed to respond positively to the interest rate cut.The CNH exchange rate bears the brunt, the spot rose to a high of 7.3359, just one step away from the 10-year high.
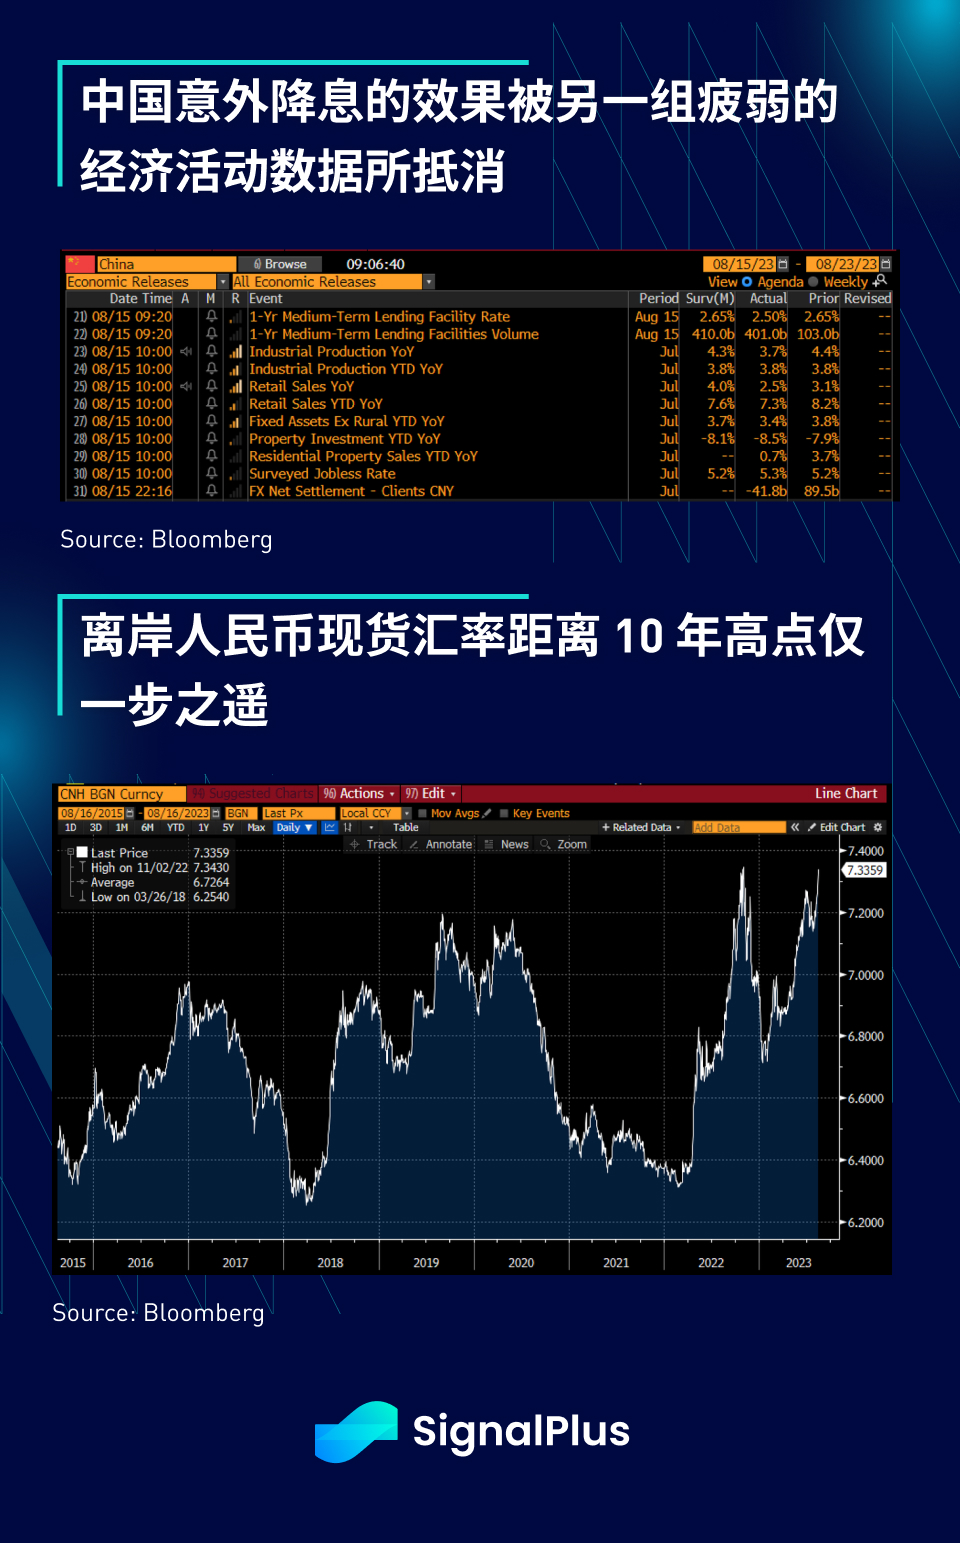
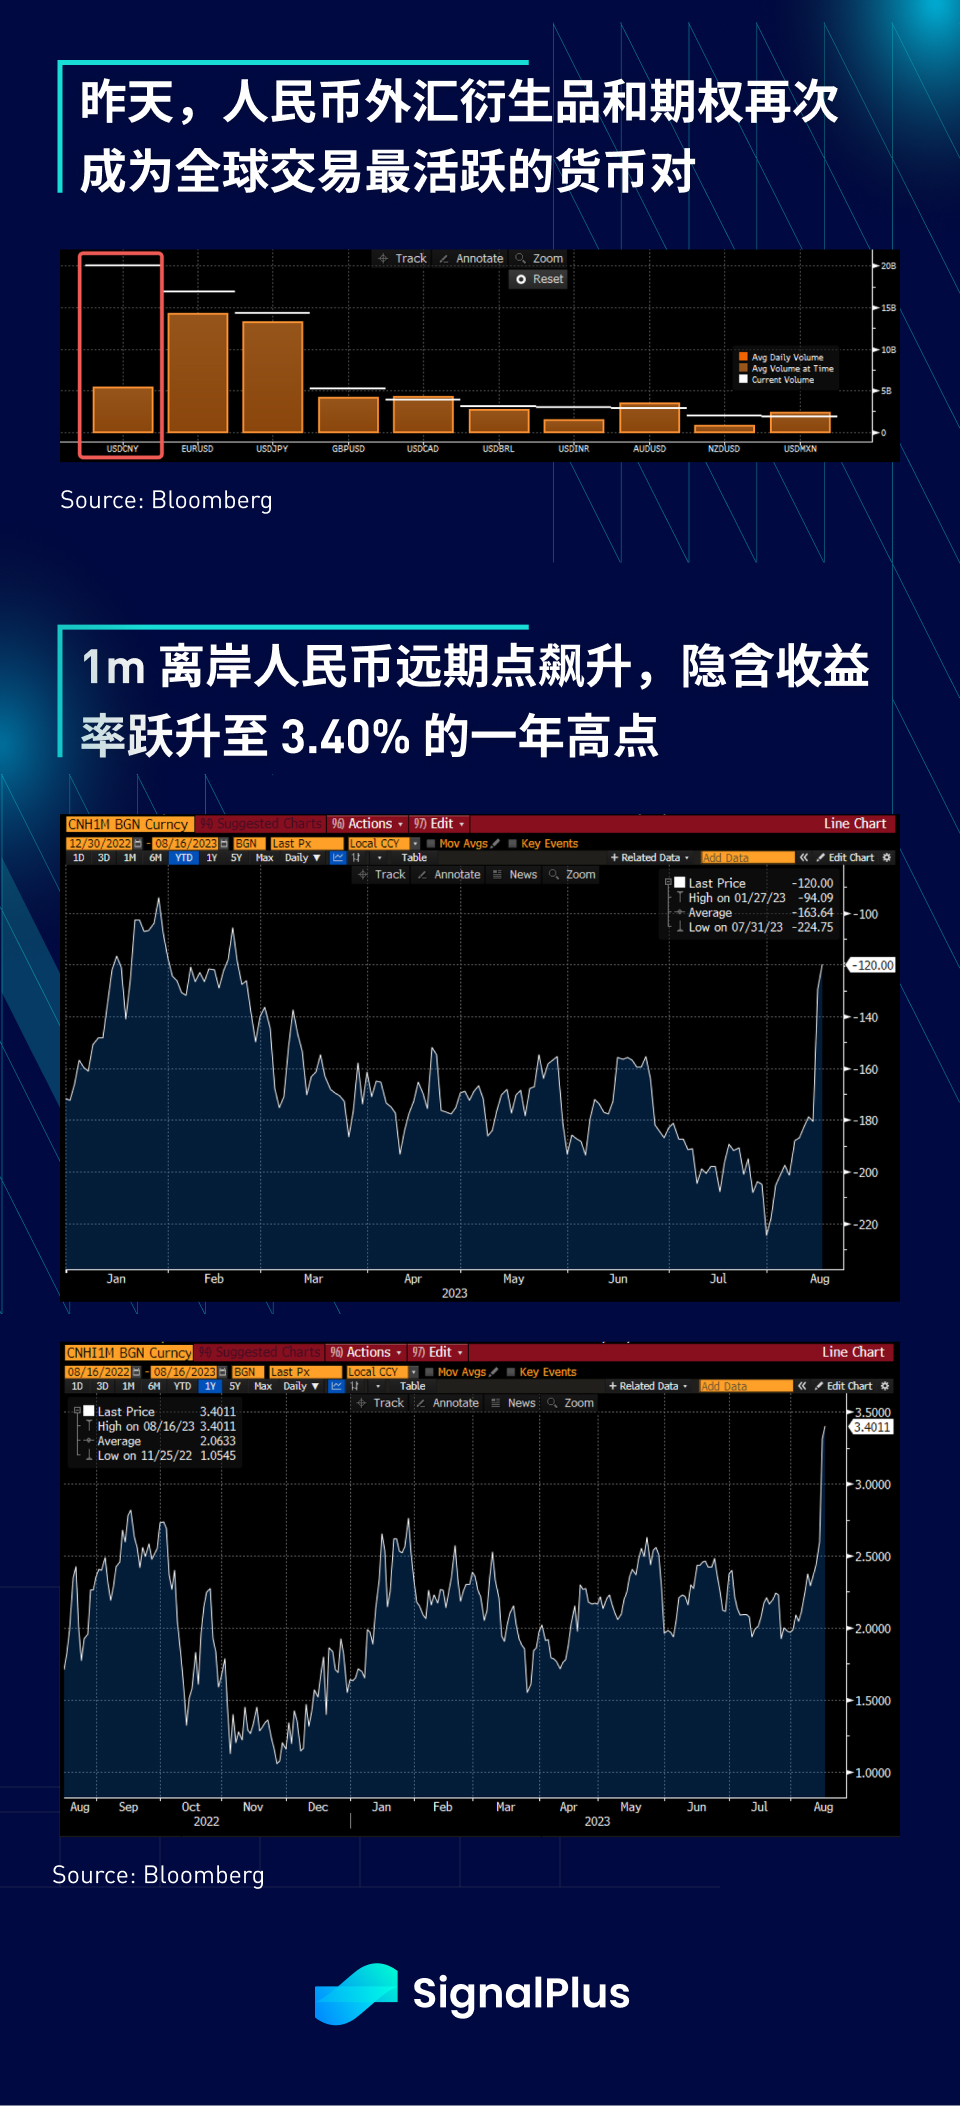
Unlike earlier this year, theThe current spot weakness is accompanied by a spike in FX forwards and an upward skew in options as hedge funds look for every possible way to increase their short positions in the yuan, yesterday, RMB foreign exchange derivatives and options became the most actively traded currency pair in the world again, the trading volume was again 3 times higher than the average Trading momentum increased, with the implied yield hitting a one-year high of 3.40%.
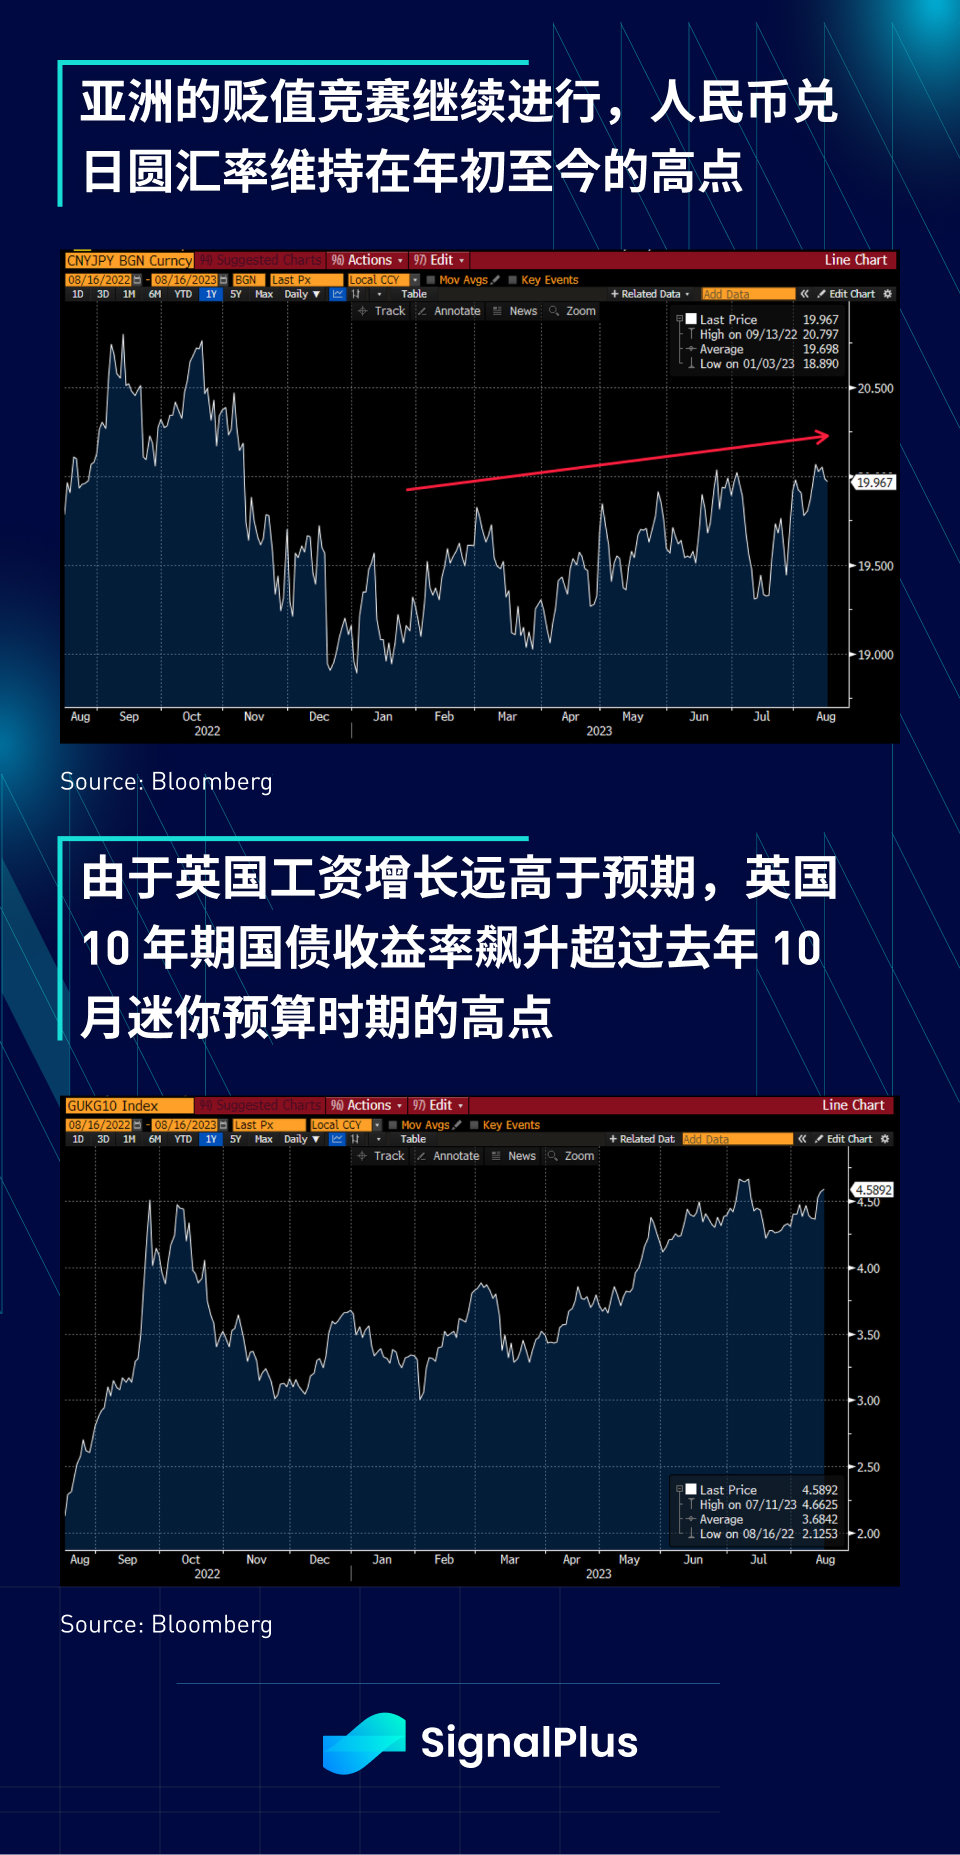
on the other hand,The situation in developed markets is completely different, with Japan reporting annualized GDP growth of up to 6%(vs 2.9% expected), resulting in USD/JPY breaking above 145, and CNY/JPY holding around this years high of around 20 as the devaluation race continues. On the other side of the Atlantic, the UKs three-month wage growth also reached 8.2% year-on-year, making the markets pricing for the Bank of Englands September meeting surged by 10 basis points, and the UK 10-year government bond yield rose again just before the UKs CPI was about to be announced. It is back near the highs of last Octobers mini-budget period.
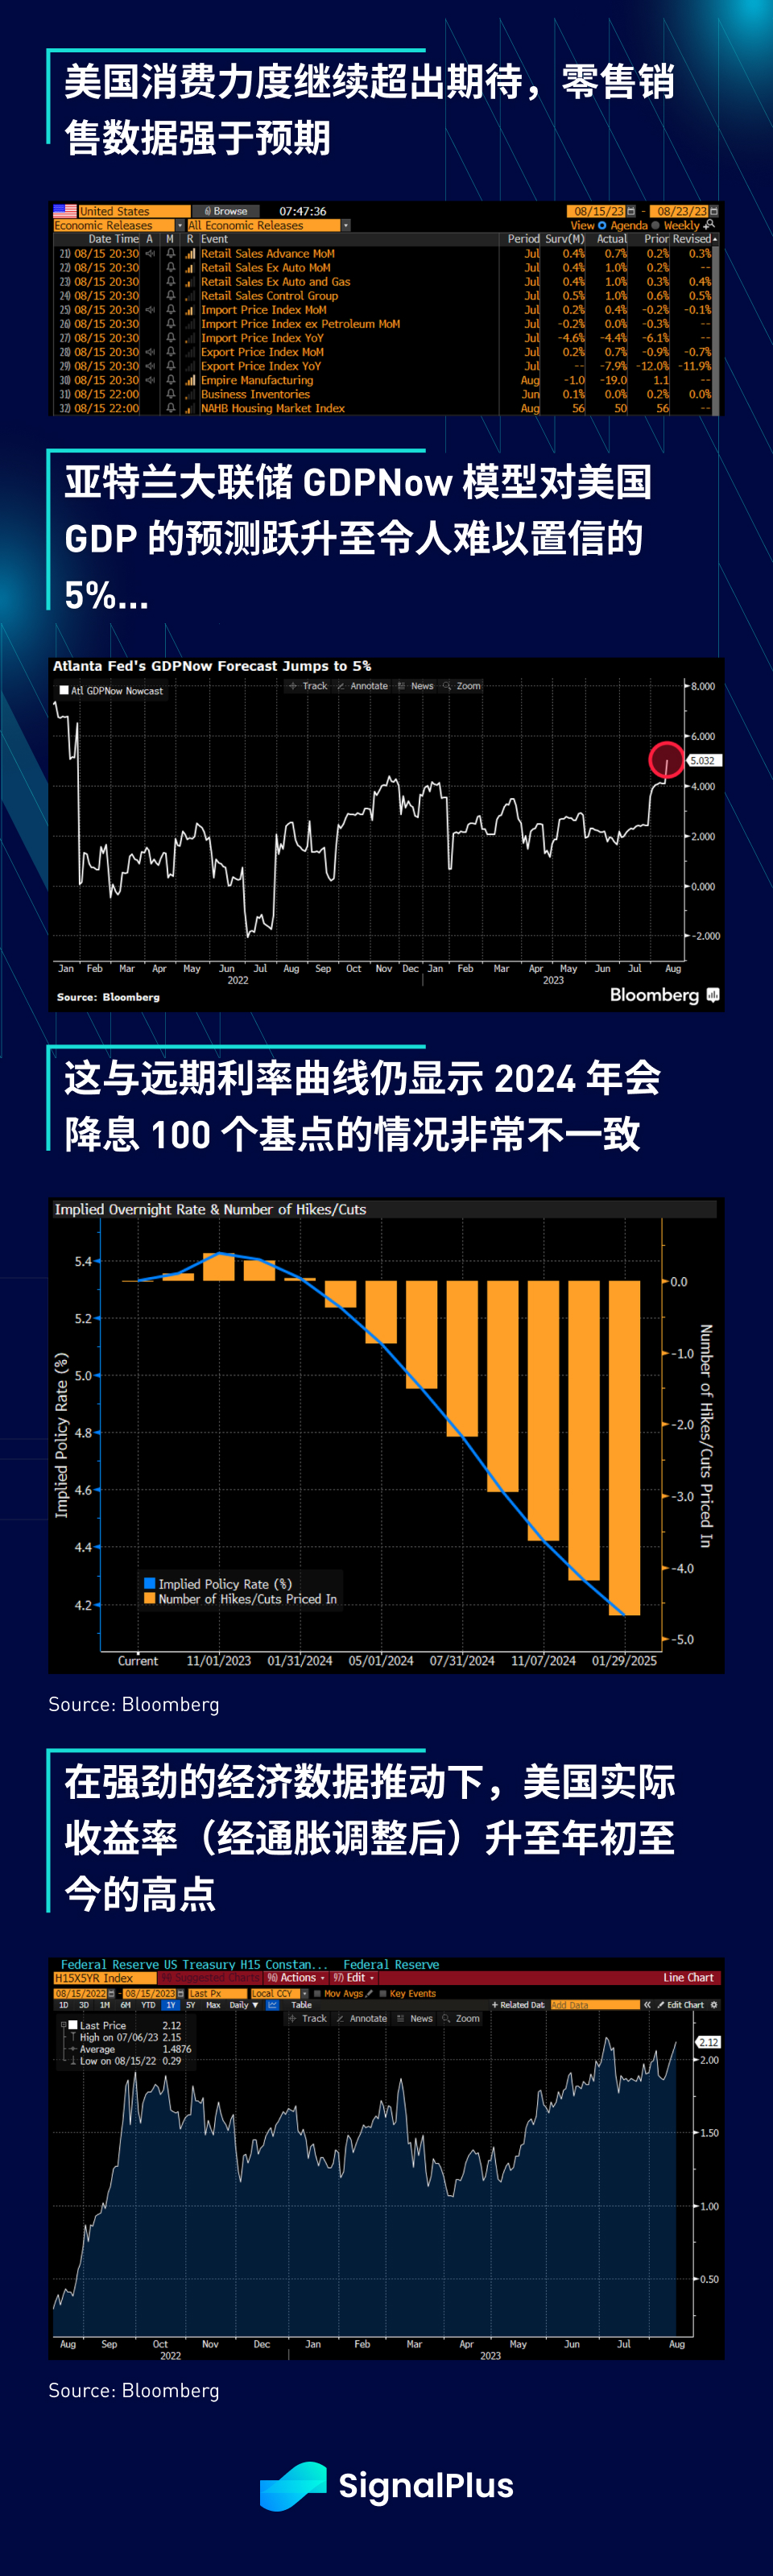
Strong economic momentum continues into the U.S., with retail sales data well above expectations(Overall data month-on-month + 0.7% vs. expected + 0.4%, control group month-on-month + 1.0% vs. expected + 0.5%), rekindledThe “higher for longer” narrative of interest rates,also,Atlanta Fed GDPNow model raises GDP forecast to 5%, which is highly out of line with the fed funds forward curve, which still expects about 100 basis points of rate cuts in 2024, in which case 5-year real yields (inflation-adjusted) climbed back to this years highs 2.12%, adding a bit of drama to the FOMC minutes that will be released today to see if the Fed will (or will not) try to send a message.
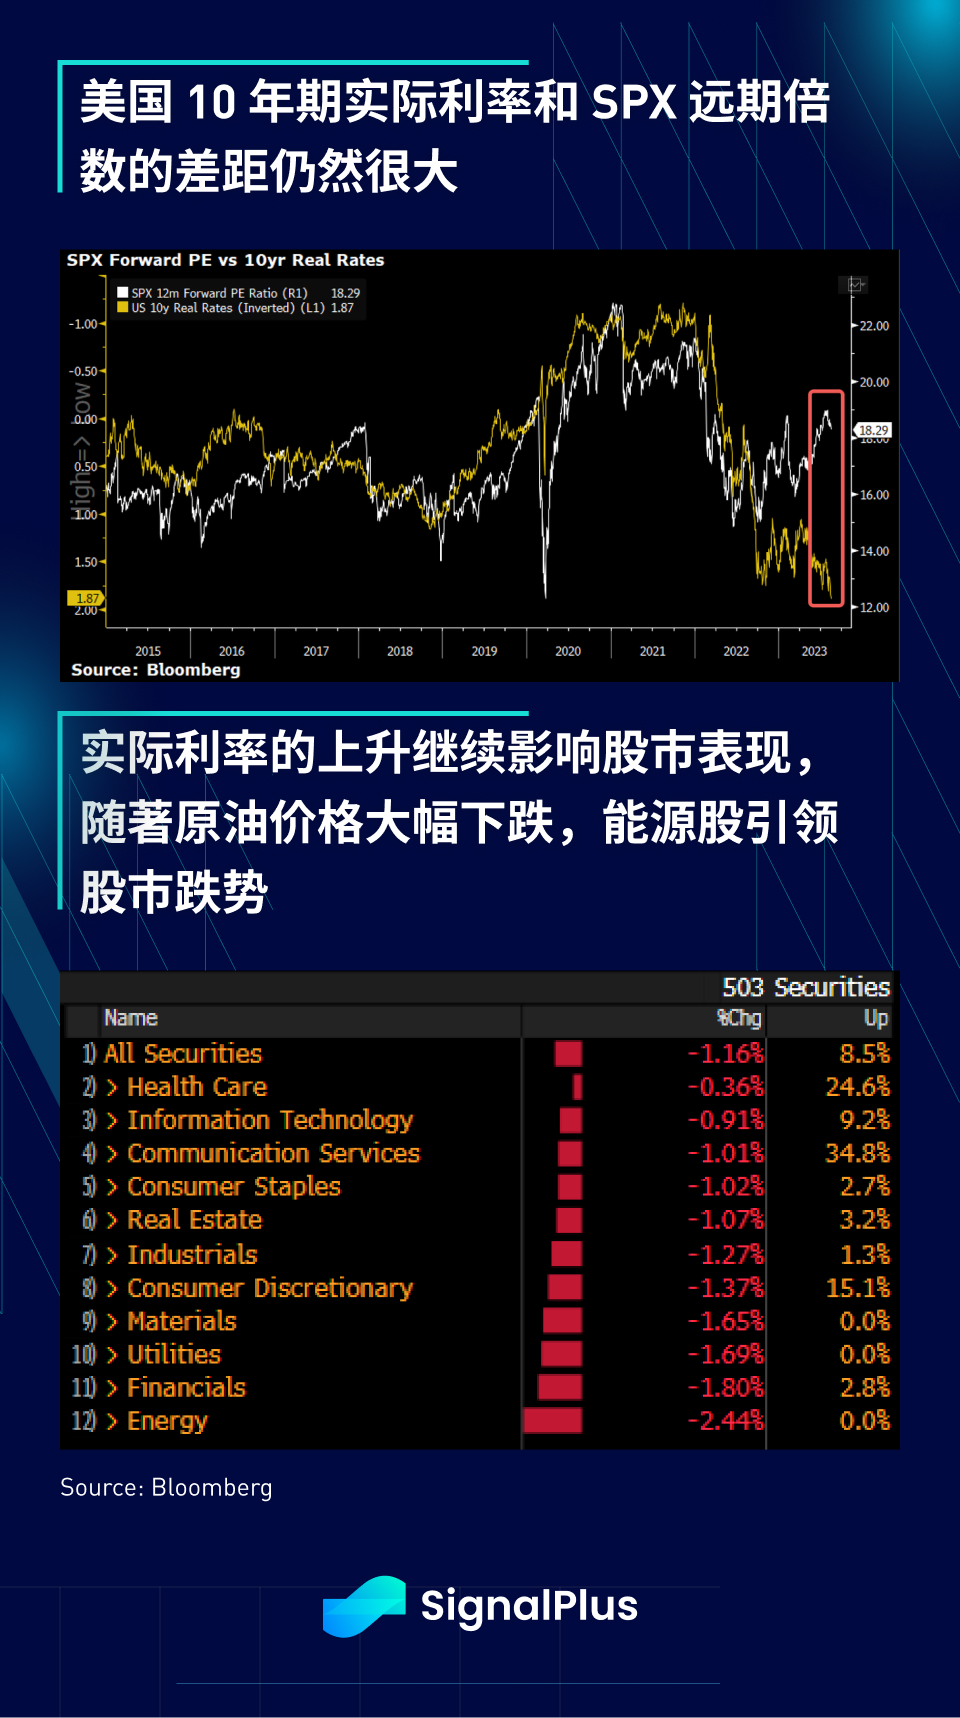
While Chinese stocks sold off on continued pessimism about the local economy, U.S. stocks also fell asRising interest rates are starting to worry equity investors again, especially given that the gap between the 10-year real rate (inflation-adjusted) and the SPXs 12-month forward price-to-earnings multiple remains very wide; SPX futures hit one-month lows yesterday, with regional banks (-3%) and energy (-2%) being hit particularly hard, should find support near 4450 on a technical basis, especially With the current bearish sentiment on China feeling a little overdone, however,Long-term trends may depend on how long-term bond yields move, and whether we will experience another special case of “mitigation panic” in the fall.
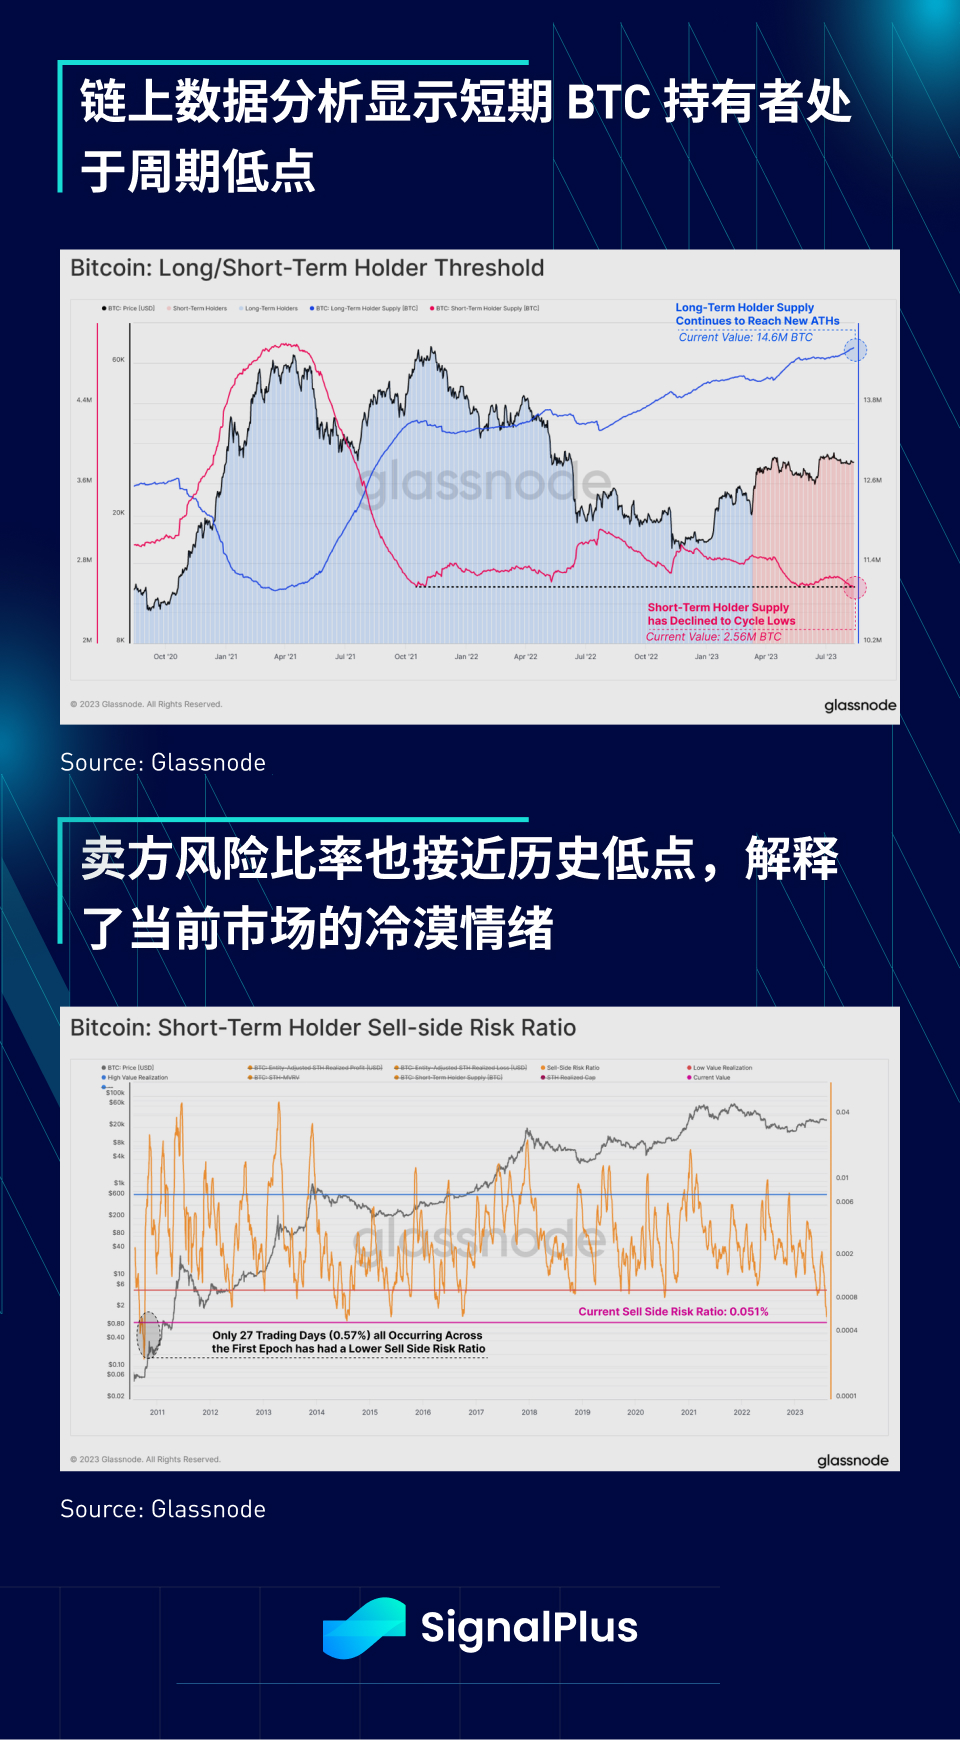
TradFi players are in high spirits this month, but crypto players are clearly not invited to the party, BTC/ETH volatility continues to be suppressed at levels similar to 3-month treasury bills, according to Glassnode’s on-chain analysis data,Currently, the amount of BTC held by short-term holders (i.e. hot money) has fallen to cycle lows, while long-term holders have reached an all-time high.,also,The current “sell-side risk ratio” (defined as the absolute value of the ratio of realized PL to realized market capitalization) is currently at an all-time low, which largely explains the current apathy in market sentiment, meaning that all investors who are willing to realize profits or losses at this moment have already done so. If traders are to be prompted to re-enter the market, the price may need to completely break through the current range (whether up or down). This is a typical The chicken-and-egg problem.
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption information. If you want to receive our updates immediately, please follow our Twitter account @SignalPlus_Web 3, or join our WeChat group (add assistant WeChat: chillywzq), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website:https://www.signalplus.com





