






ก่อนงบการเงินของ Micron ในวันพุธ: ความเห็นต่างระหว่างฝ่ายกระทิงและฝ่ายหมีไม่เคยมากขนาดนี้


- ประเด็นหลัก: Micron Technology กำลังจะประกาศงบการเงินไตรมาสที่สี่ของปีงบประมาณ 2026 ตลาดคาดหวังอย่างแข็งแกร่งแต่มีความเห็นต่างอย่างชัดเจน: นักวิเคราะห์ Luria ให้ราคาเป้าหมายที่ 2,000 ดอลลาร์ มองในแง่ดีว่าซูเปอร์ไซเคิลจะดำเนินต่อไป ขณะที่ "Big Short" Burry ใช้ options put ที่ 500 ดอลลาร์ เดิมพันว่าวัฏจักรจะกลับสู่ภาวะปกติ โดยข้อโต้แย้งหลักอยู่ที่ว่า Micron เป็นหุ้นวัฏจักรหรือหุ้นเติบโตกันแน่
- ปัจจัยสำคัญ:
- บริษัทให้คำแนะนำรายได้ 50,000 ล้านดอลลาร์ (±1,000 ล้าน) และ non-GAAP EPS 31 ดอลลาร์ (±1) โดยรายได้ในไตรมาสเดียวสูงกว่ารายได้ทั้งปีงบประมาณ 2025 ซึ่งอยู่ที่ประมาณ 37,100 ล้านดอลลาร์ ขณะที่ฉันทามติของ Wall Street คาดการณ์รายได้ประมาณ 51,070 ล้านดอลลาร์ และ EPS ประมาณ 31.52 ดอลลาร์ เพิ่มขึ้นเมื่อเทียบปีต่อปีประมาณ 351% และ 938% ตามลำดับ
- กำลังการผลิต HBM ยังคงกัดกร่อนอุปทาน DRAM แบบดั้งเดิม: Samsung คาดว่าในปี 2027 HBM จะคิดเป็นเกือบ 30% ของกำลังการผลิตเวเฟอร์ DRAM ทั้งหมด กำลังการผลิตเวเฟอร์ที่ HBM4 ต้องการนั้นมากกว่า DRAM ทั่วไปประมาณสามเท่า และกำลังการผลิตปี 2027 ของผู้ผลิตต้นทางทั้งสามรายถูกจองขายหมดแล้ว
- ความคืบหน้า HBM4 ของ Micron เร่งตัวขึ้น: HBM4 แบบ 12 ชั้นที่ออกแบบสำหรับแพลตฟอร์ม Vera Rubin ของ NVIDIA ได้เริ่มผลิตจำนวนมากและส่งมอบแล้ว โดยประสิทธิภาพการใช้พลังงานดีขึ้นกว่า HBM3E มากกว่า 20% รายได้จากการส่งมอบสะสมทะลุ 1,000 ล้านดอลลาร์ และกำลังการผลิตต่อเดือนมีโอกาสเพิ่มขึ้นเป็นสองเท่าภายในสิ้นปี สู่ระดับ 100,000 แผ่น
- ข้อโต้แย้งหลักของ Luria: HBM ถูกจำกัดด้วยอุปทานจึงทำให้ราคาแข็งแกร่ง คำสั่งซื้อถูกล็อกล่วงหน้ามากกว่าหนึ่งปี ทำให้มองเห็นความสามารถในการทำกำไรได้ยาวนานขึ้น อัตราส่วน P/E ของ Micron อยู่ที่เพียง 7 เท่า ต่ำกว่า AMD และ Intel ที่ 40—60 เท่าอย่างมาก
- ตรรกะแบบหมีของ Burry: มองว่าการขาดแคลนหน่วยความจำที่ขับเคลื่อนด้วย AI เป็นเพียงชั่วคราว เมื่อผลผลิตตามทันอุปสงค์ภายในสองปีข้างหน้า อุตสาหกรรมจะกลับสู่ภาวะขาลงตามวัฏจักรแบบดั้งเดิม Citi และ Bernstein ก็เตือนถึงความเสี่ยงจากการชะลอตัวของราคาและการกลับสู่ปกติของวัฏจักรเช่นกัน
- ความเสี่ยงสามประการ: อัตราผลได้ (yield) ของ HBM4 ไต่ระดับช้ากว่าคาด; ความยืดหยุ่นของราคา DRAM แบบดั้งเดิมและรายจ่ายด้านทุนในปีงบประมาณ 2027 (คาดอยู่ในช่วงกลางถึงสูงของระดับ 40,000 ล้านดอลลาร์ขึ้นไป); และสภาพแวดล้อมอัตราดอกเบี้ยมหภาคที่กดดันหุ้นเทคโนโลยีที่มูลค่าสูง
Micron Technology (MU) will release its fiscal year 2026 fourth-quarter earnings after the U.S. market close on September 30 (early morning October 1 Beijing time). The company previously guided revenue of $50 billion (±$1 billion) and non-GAAP earnings per share of $31 (±$1); the Wall Street consensus expects revenue of approximately $51.07 billion and adjusted EPS of approximately $31.52, representing year-over-year growth of approximately 351% and 938%, respectively.
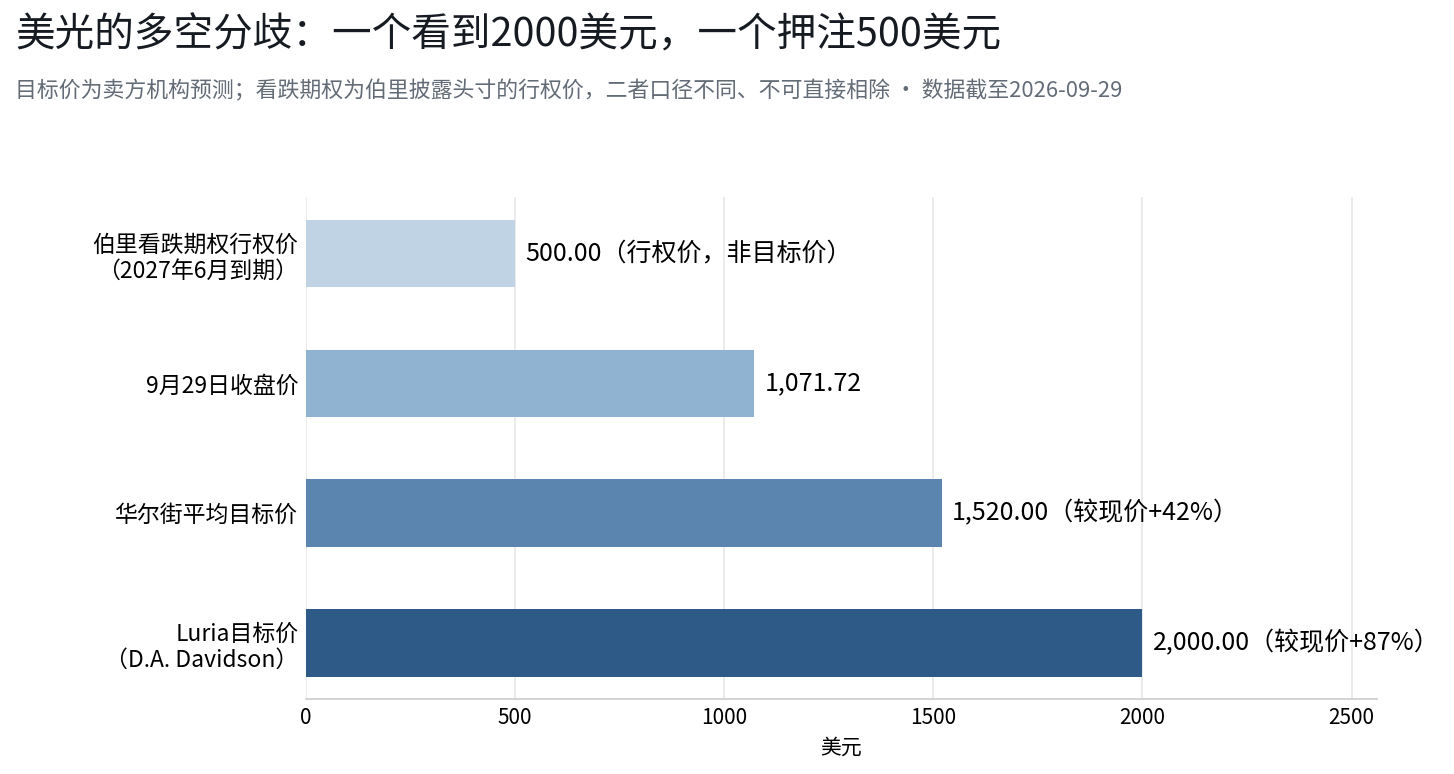
However, the market's focus for this earnings report is not solely on the quarterly figures themselves. Some market views hold that the earnings improvement has already been reflected in the stock price to some extent, and the market is also watching how much longer this memory cycle can last. D.A. Davidson analyst Gil Luria reiterated a $2,000 price target on the eve of the earnings report, implying approximately 87% upside from the September 29 closing price of $1,071.72; meanwhile, "Big Short" Michael Burry replaced his Micron short position with put options expiring next June with a strike price of $500. One side gives a $2,000 price target, while the other expresses a bearish view through put options with a strike price of around $500.
1. Quarterly Results: Market Expectations Are Generally Strong
Let's look at the numbers themselves first. The company guided revenue of $50 billion (±$1 billion) and non-GAAP EPS of $31 (±$1), but several institutions have offered more optimistic forecasts:
- Citi: revenue of $51 billion, EPS of $31.45;
- Goldman Sachs: revenue of $51.9 billion, EPS of $32.54;
- UBS: revenue of $52.4 billion, EPS of $32.50, the most aggressive;
- JPMorgan (Harlan Sur): revenue of $51.4 billion, gross margin of 86.2%, EPS of $31.73, all above the market consensus.
What does $50 billion in quarterly revenue mean? Micron's full-year revenue for fiscal year 2025 was approximately $37.1 billion—one quarter's revenue exceeds the total of the entire previous year.
From delivered results to structural variables, this earnings report has three layers of uncertainty: whether the guidance can exceed the already elevated market expectations, the timing of HBM4 mass production and revenue contribution, and how conventional DRAM price trends and capital expenditure plans will provide a basis for the industry outlook.
Morgan Stanley (Big Morgan) is relatively conservative in its forecast for the quarter: it expects revenue of $50.024 billion, up 342.1% year-over-year, gross margin of 86.4%, and earnings per share of $31.2, below the market expectation of $31.49. But Morgan Stanley also expects Micron to raise its earnings guidance, though by less than in previous quarters.
2. The Underlying Logic of the Supercycle: HBM Is "Draining" DRAM
From the perspective of industry supply and demand, a structural factor the market is currently focused on is that HBM capacity expansion may squeeze some conventional DRAM supply, while conventional DRAM still has market demand.
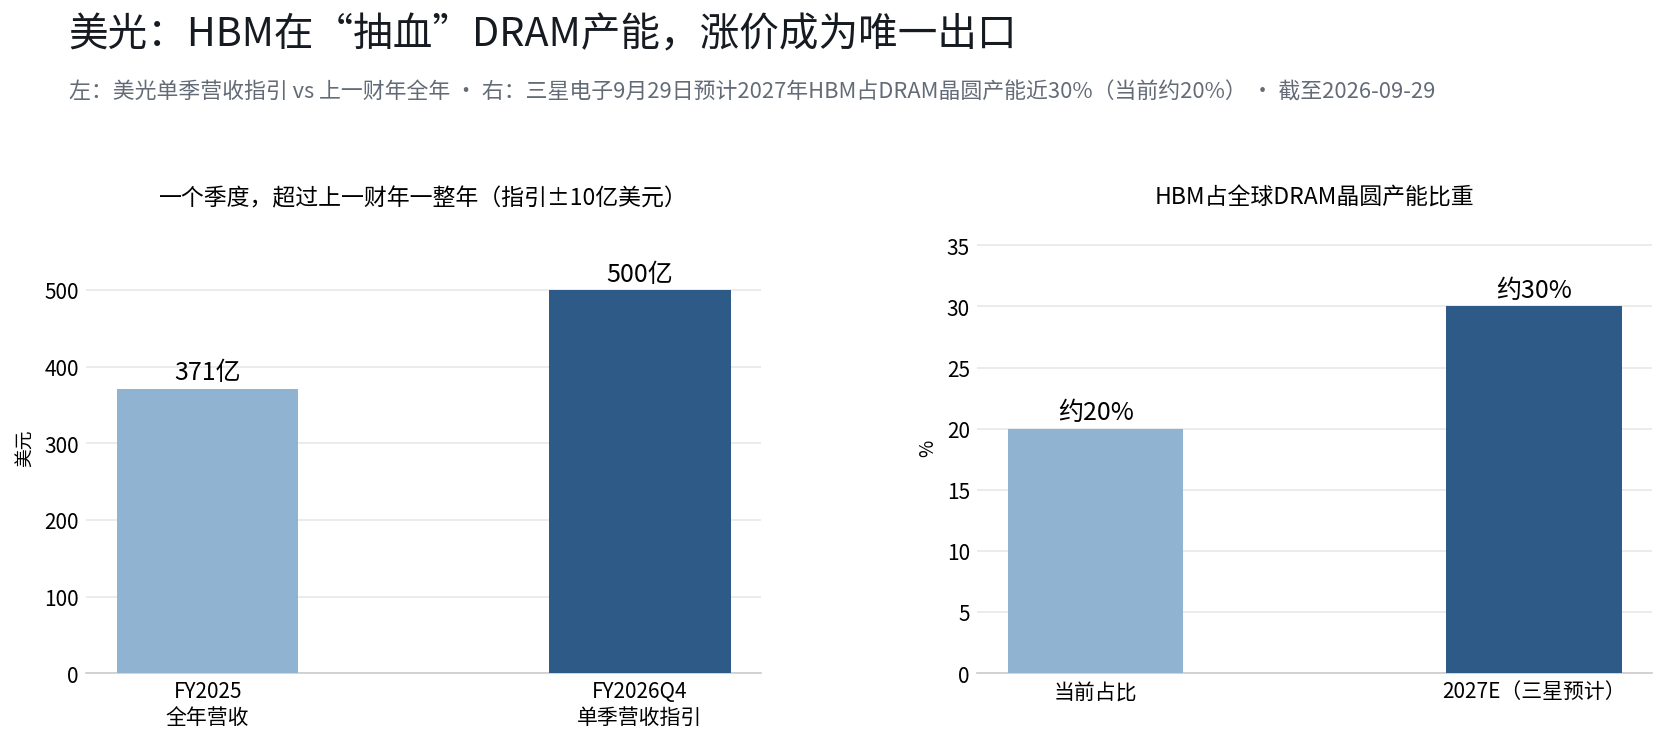
Samsung Electronics Executive Vice President Kim Taewoo gave a key figure in his latest statement on September 29: HBM is expected to account for nearly 30% of total global DRAM wafer capacity by 2027, compared with about 20% currently. Soochow Securities' calculation path is clearer—HBM capacity as a share of total DRAM capacity will rise from 12.3% in 2024 to 17.1% in 2025 and 20.8% in 2026, reaching 22.5% in 2027. The wafer capacity required for HBM4 is approximately three times that of general-purpose DRAM, and the full-scale increase in HBM4 production will inevitably reduce the available capacity for conventional DRAM. ADATA Technology Chairman Chen Li-Bai confirmed that the 2027 capacity of the three major manufacturers has already sold out, with HBM and AI server applications consuming about 70% of DRAM output.
What makes Micron special is that it is the only one of the three major memory manufacturers with significant exposure to both HBM and conventional DRAM. Samsung and SK Hynix have a higher share of HBM in revenue, but Micron's conventional DRAM and NAND businesses are larger in scale, so its profitability may also be significantly affected by changes in conventional DRAM prices. BMO channel research shows that the earnings surprise potential from server DDR5 price increases is greater than that from HBM; HBM3E and HBM4 prices are likely to rise quarter-over-quarter, while consumer memory demand is relatively weak.
Micron's own progress is also accelerating: the 12-layer HBM4 designed for Nvidia's Vera Rubin platform entered mass production and shipped in the first quarter of 2026, with energy efficiency improved by more than 20% compared with HBM3E, and cumulative shipment revenue has exceeded $1 billion. Micron CEO Mehrotra said at the June earnings call that the mass production ramp speed of 12-layer HBM4 is about twice that of 12-layer HBM3E. According to industry sources, Micron's monthly HBM capacity is expected to double to 100,000 wafers by the end of the year, and HBM4's share of its HBM output will rise from about 20%—30% at the beginning of the year to as high as 50% by the end of the year.
3. The $2,000 Price Target: Luria's Main Views and Basis
Luria, who reiterated his $2,000 price target on the eve of the earnings report, is close to the highest level on Wall Street. He raised his price target from $1,500 to $2,000 back in June, citing Micron's entry into a phase of "the best visibility in the semiconductor industry," with memory supply-demand tightness lasting at least through 2027.
His core argument has three layers:
- Luria believes that current HBM market pricing is significantly affected by supply constraints, demand remains strong, and new supply still needs time to be released.
- Micron's earnings visibility is lengthening. HBM orders are usually locked in more than a year in advance, and a considerable portion of 2027 revenue can already be reasonably predicted.
- The valuation method is shifting. He wrote in his report: "This memory cycle is a complete cycle of the GPU, CPU, and memory trinity. AMD and Intel maintain P/E ratios of 40—60 times, while Micron's P/E ratio is only 7 times."
Luria also mentioned a recent change: the successful launch of Meta's Muse has opened up entirely new application scenarios for consumers. "Just a few weeks ago, we were worried that memory demand from Meta would weaken, but now it appears that possibility is very low."
But the nearly $500 gap between Wall Street's average price target of $1,520 and $2,000 precisely shows that the market has no consensus on the question of "whether Micron is a cyclical stock or a growth stock." JPMorgan maintains an "overweight" rating and a $1,540 price target, expecting this quarter's revenue, gross margin, and EPS to beat market consensus, and says the slowdown in price increases is a matter of sales pace rather than weakening demand; UBS maintains a $1,625 price target, expecting DRAM to remain in undersupply at least through the second quarter of 2028, and expects Micron to begin stock buybacks starting in the second quarter of fiscal year 2027, with an initial scale of about $20 billion per quarter.
4. The Bears' Logic: Views and Risks of a Cyclical Return
In sharp contrast to Luria is "Big Short" Michael Burry.
According to China Securities Overseas Information, Burry revealed in his latest weekly briefing to investors that he has largely replaced his original short positions in major AI stocks with put options, among which his short position in Micron was replaced with put options expiring next June with a strike price in the $500 range. Burry's exact words were: "Because the timeline has shortened, I want greater leverage in my short positions."
He believes that the structural shortage of memory chips spawned by the current AI construction boom is temporary, and the industry will eventually return to the traditional model of alternating boom and bust: "Within the next two years, as production catches up with demand, this shortage will disappear, and memory chips will enter a downturn cycle again."
Citi analysts also warned before the earnings report that DRAM and NAND prices will slow in the coming quarters; Bernstein expects the memory cycle may begin to "normalize" in 2028. Historically, some memory stocks have still experienced significant price volatility or pullbacks during periods of strong performance, but historical performance does not represent future results.
5. Three Risks to Watch
- HBM4 yield ramp. HBM4 is still in the early stages of mass production, with yields lower than the previous generation HBM3E, and the manufacturing process consumes more DRAM capacity. If yield improvement is slower than expected, Micron's HBM shipment pace may be affected. The market is also watching whether the capacity ramp meets expectations, customer certification progress, and the timing of revenue contribution—since large-scale shipments of downstream platforms may be concentrated in 2027, HBM4's significant revenue contribution may mainly fall in the next fiscal year.
- Conventional DRAM price elasticity and capital expenditure. According to Bank of America analysts, the key data the market really cares about is Micron's outlook for fiscal year 2027 gross margin and capital expenditure: if gross margin can be maintained at around 85%, the forecast of $150—200 earnings per share for that fiscal year will be supported; capital expenditure is expected to be in the mid-to-high range of the $40 billion-plus level, with a considerable portion used for cleanroom construction, which may not immediately translate into additional output. But if the market's expectations for the memory cycle outlook change, Micron's stock price may still fluctuate even if actual results exceed market expectations.
- Suppression from the macro interest rate environment. On September 28, Micron closed down 2.61%, while the Philadelphia Semiconductor Index fell 1.61% that day, as soaring U.S. Treasury yields weighed on all high-valuation tech stocks. If the Federal Reserve continues to raise rates in October, high-beta memory stocks may face additional valuation pressure in an environment of tightening liquidity.
Final Thoughts
The market has high expectations for Micron's upcoming earnings report. Factors such as HBM prices, conventional DRAM supply and demand, and AI capital expenditure are all key market focus points, but actual results may still differ from market expectations. Beyond the earnings figures themselves, the market will also focus on management's outlook for 2027 and how investors view the cyclicality and growth potential of Micron's future business.
Luria's $2,000 price target and Burry's put options reflect differing market views on Micron's future performance. The earnings report and management outlook will provide the market with more information.
Let's interact: For this earnings report, which factors are you more focused on—HBM supply and demand, conventional DRAM prices, capital expenditure, or management's outlook for the future cycle?
Disclaimer: This article is for general informational and educational purposes only and does not constitute any investment advice, recommendation, offer, or solicitation, nor should it be regarded as a basis for buying, selling, or holding any securities or other financial products. The views, forecasts, price targets, and other forward-looking information (if any) expressed in this article come from relevant third parties or public sources and do not represent BIT's investment views or advice. Market conditions may change at any time, and actual results may differ materially from relevant forecasts or expectations. Investing involves risk, and investors should make independent investment decisions based on their own circumstances and seek professional advice when necessary.





