


Sky Founder Suspected of Draining His Own USDS Lending Pool


- Core Viewpoint: Sky's stUSDS pool has been drained of liquidity due to large-scale borrowing by a founder-linked address (rune.eth), with interest rates spiking to 19.75%. Although Sky proactively adjusted liquidation parameters to delay the risk, exit liquidity is severely insufficient. If SKY's price continues to fall, bad debt may be difficult to avoid, triggering disputes over governance and risk transfer.
- Key Elements:
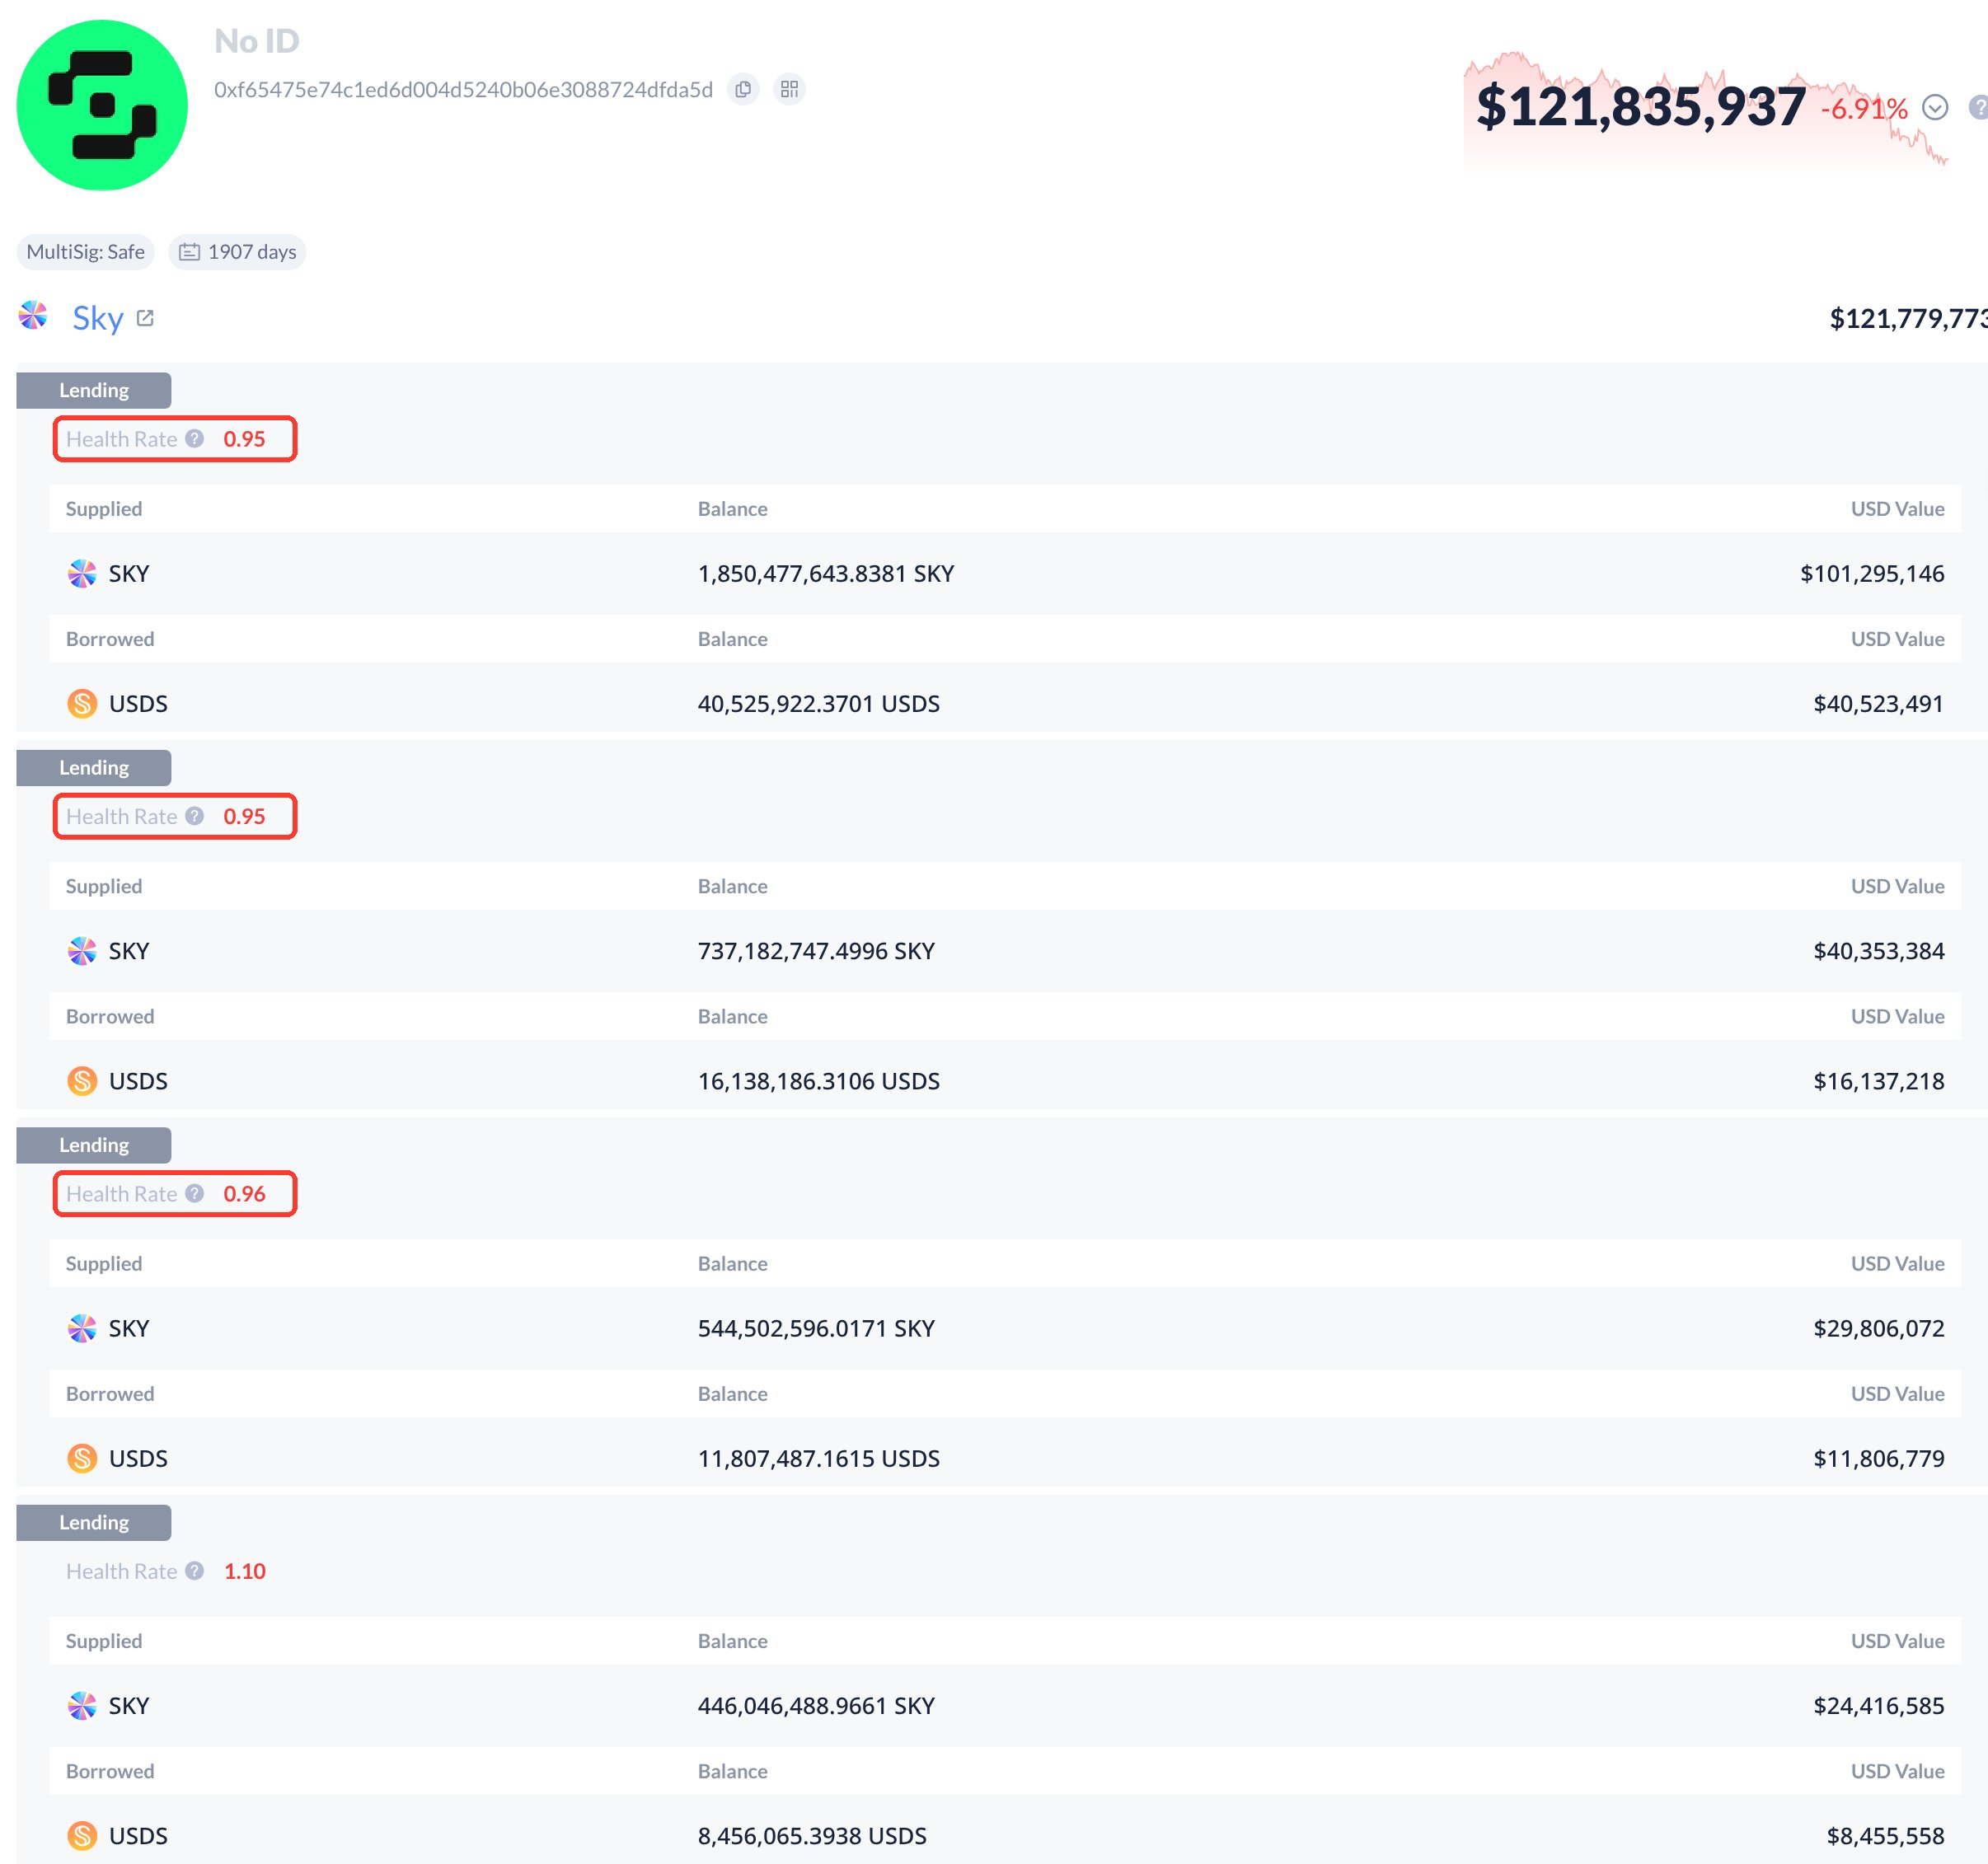
- The stUSDS pool has been borrowed dry, with 48% of debt (approximately $76.9 million) coming from rune.eth, which points to co-founder Rune Christensen. Four positions have gone six months without repayment, and three are already below the liquidation threshold.
- Since September 2025, Sky has switched from automatic liquidation to manual liquidation, and in November lowered the liquidation threshold to 120% and the hard cap price to $0.025, delaying some liquidation triggers.
- Exit liquidity is severely insufficient: stUSDS accounts for over 80% of the Curve pool, three Morpho pools have been drained, and available exit value is less than $9 million—less than 6% of the $150 million pool.
- SKY is approximately $0.04625, with Rune having pledged about 4 billion tokens; trading just 100 million tokens would cause slippage exceeding 20%, and if the price falls below $0.025, bad debt could exceed $100 million.
- USDS issuance exceeds $5.2 billion, making it the largest crypto-native stablecoin. Sky's TVL ranks 10th in DeFi, and the protocol remains influential in scale.
Author: Eric, Foresight News
On November 14, 2026, a user with the X handle punkquidity discovered that Sky's stUSDS annualized interest rate had risen to 13%, but no funds were available for withdrawal.
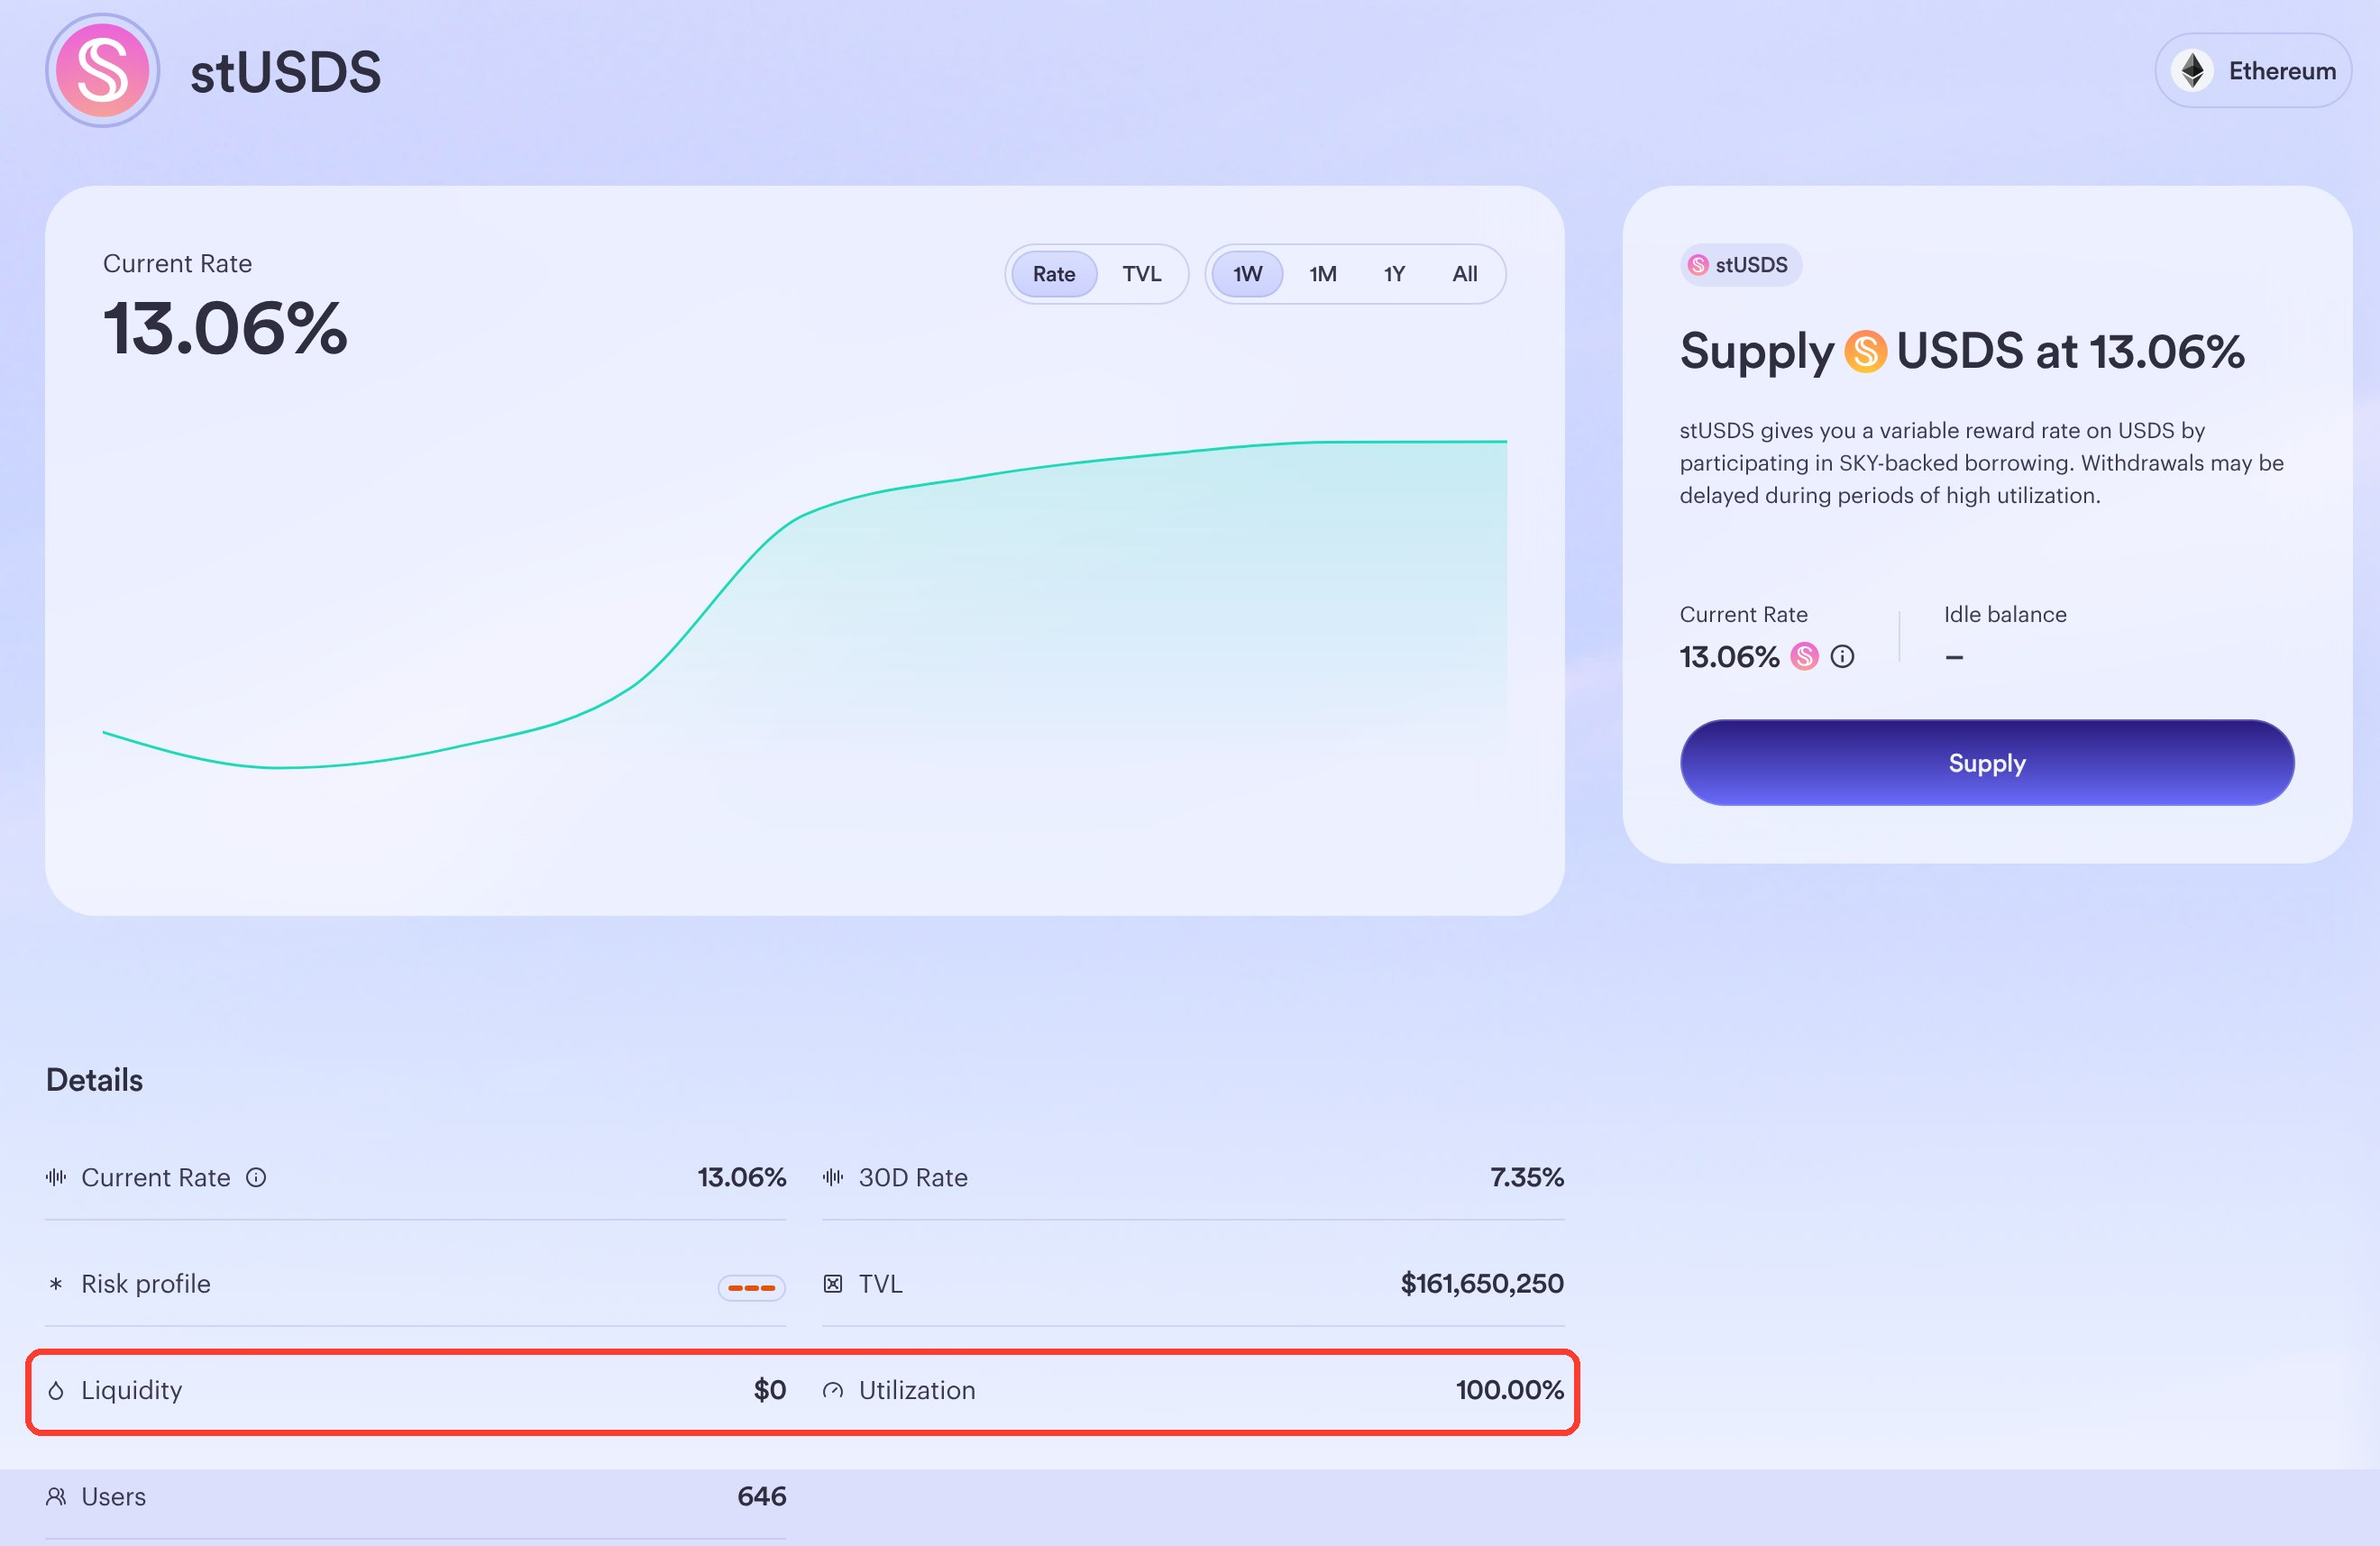
All stUSDS in Sky is designated for lending USDS against staked SKY. Users can supply USDS and receive stUSDS as a yield-bearing receipt, while others can collateralize SKY to borrow USDS. punkquidity further pointed out that on November 10, someone withdrew the last available USDS from the pool, and no one has deposited USDS into the pool since.
One day later, punkquidity posted again stating that of this drained USDS pool, 48% of the debt—approximately $76.9 million—originated from the rune.eth address, which points to Sky co-founder Rune Christensen. A total of 4 borrowing positions had made no repayment over 6 months, and 3 of them had already fallen below the liquidation threshold.
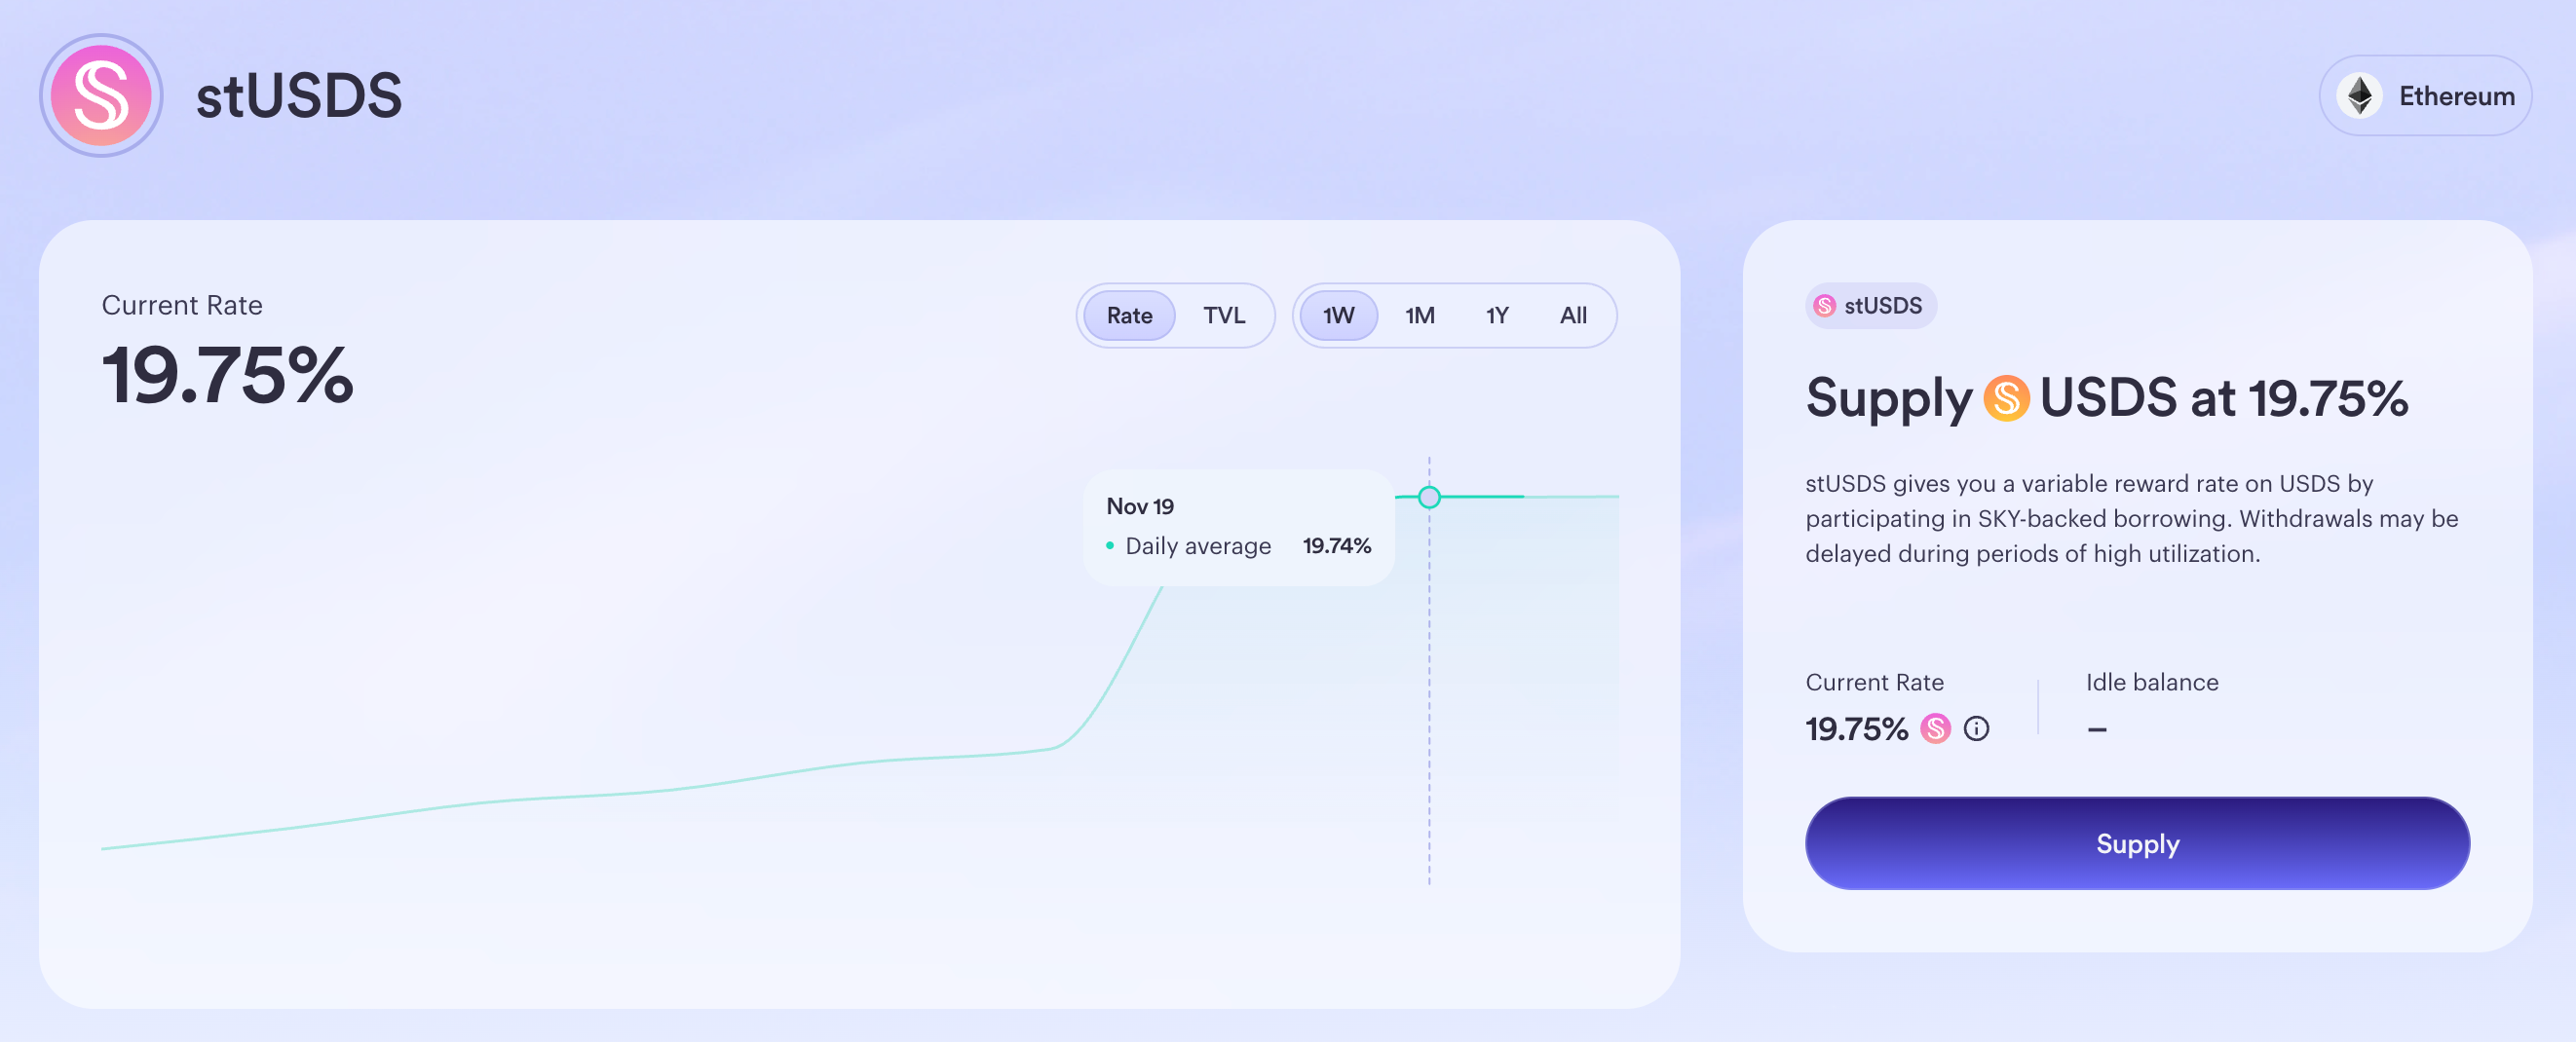
Upon verification by the author, as of the time of writing, the lending pool still has no liquidity available for exiting USDS, and the stUSDS interest rate has risen to 19.75%.
Discussion of this matter on X only began to gain traction on November 18, with many even suggesting that Sky's apparent failure to liquidate the founder's position was a backdoor operation. In reality, however, Sky had been preparing for this day since the second half of 2025.
In September 2025, Sky disabled automatic liquidation for the "collateralize SKY to borrow USDS" market, switching to manual liquidation. This action was taken at the time to prevent a short-term liquidity vacuum during the token migration from MKR to SKY, which could have led to price manipulation and unnecessary liquidations.
In October 2025, as Sky's price began to decline alongside the broader cryptocurrency market, Sky urgently carried out a series of operations.
In early October, Sky published the "Lockstake Capped OSM Wrapper," the core of which was to set Sky's oracle price to the lower of the market price and "a configured hard cap price." The purpose was to prevent anyone from borrowing heavily while the SKY price was still relatively high, thereby increasing future liquidation risk.
On November 26, less than a month after the market experienced extreme liquidations, Sky adjusted its risk parameters again: lowering the liquidation threshold from 145% to 120%, and reducing the previous "hard cap price" to $0.025. This meant that partial liquidations would only begin to be triggered if the SKY token price fell below $0.03.
At the same time, Sky planned to establish a Curve sUSDS/stUSDS pool to allow depositors to exit at a discount even at 100% utilization. Subsequently, Sky also planned to expand liquidity sources through Morpho.
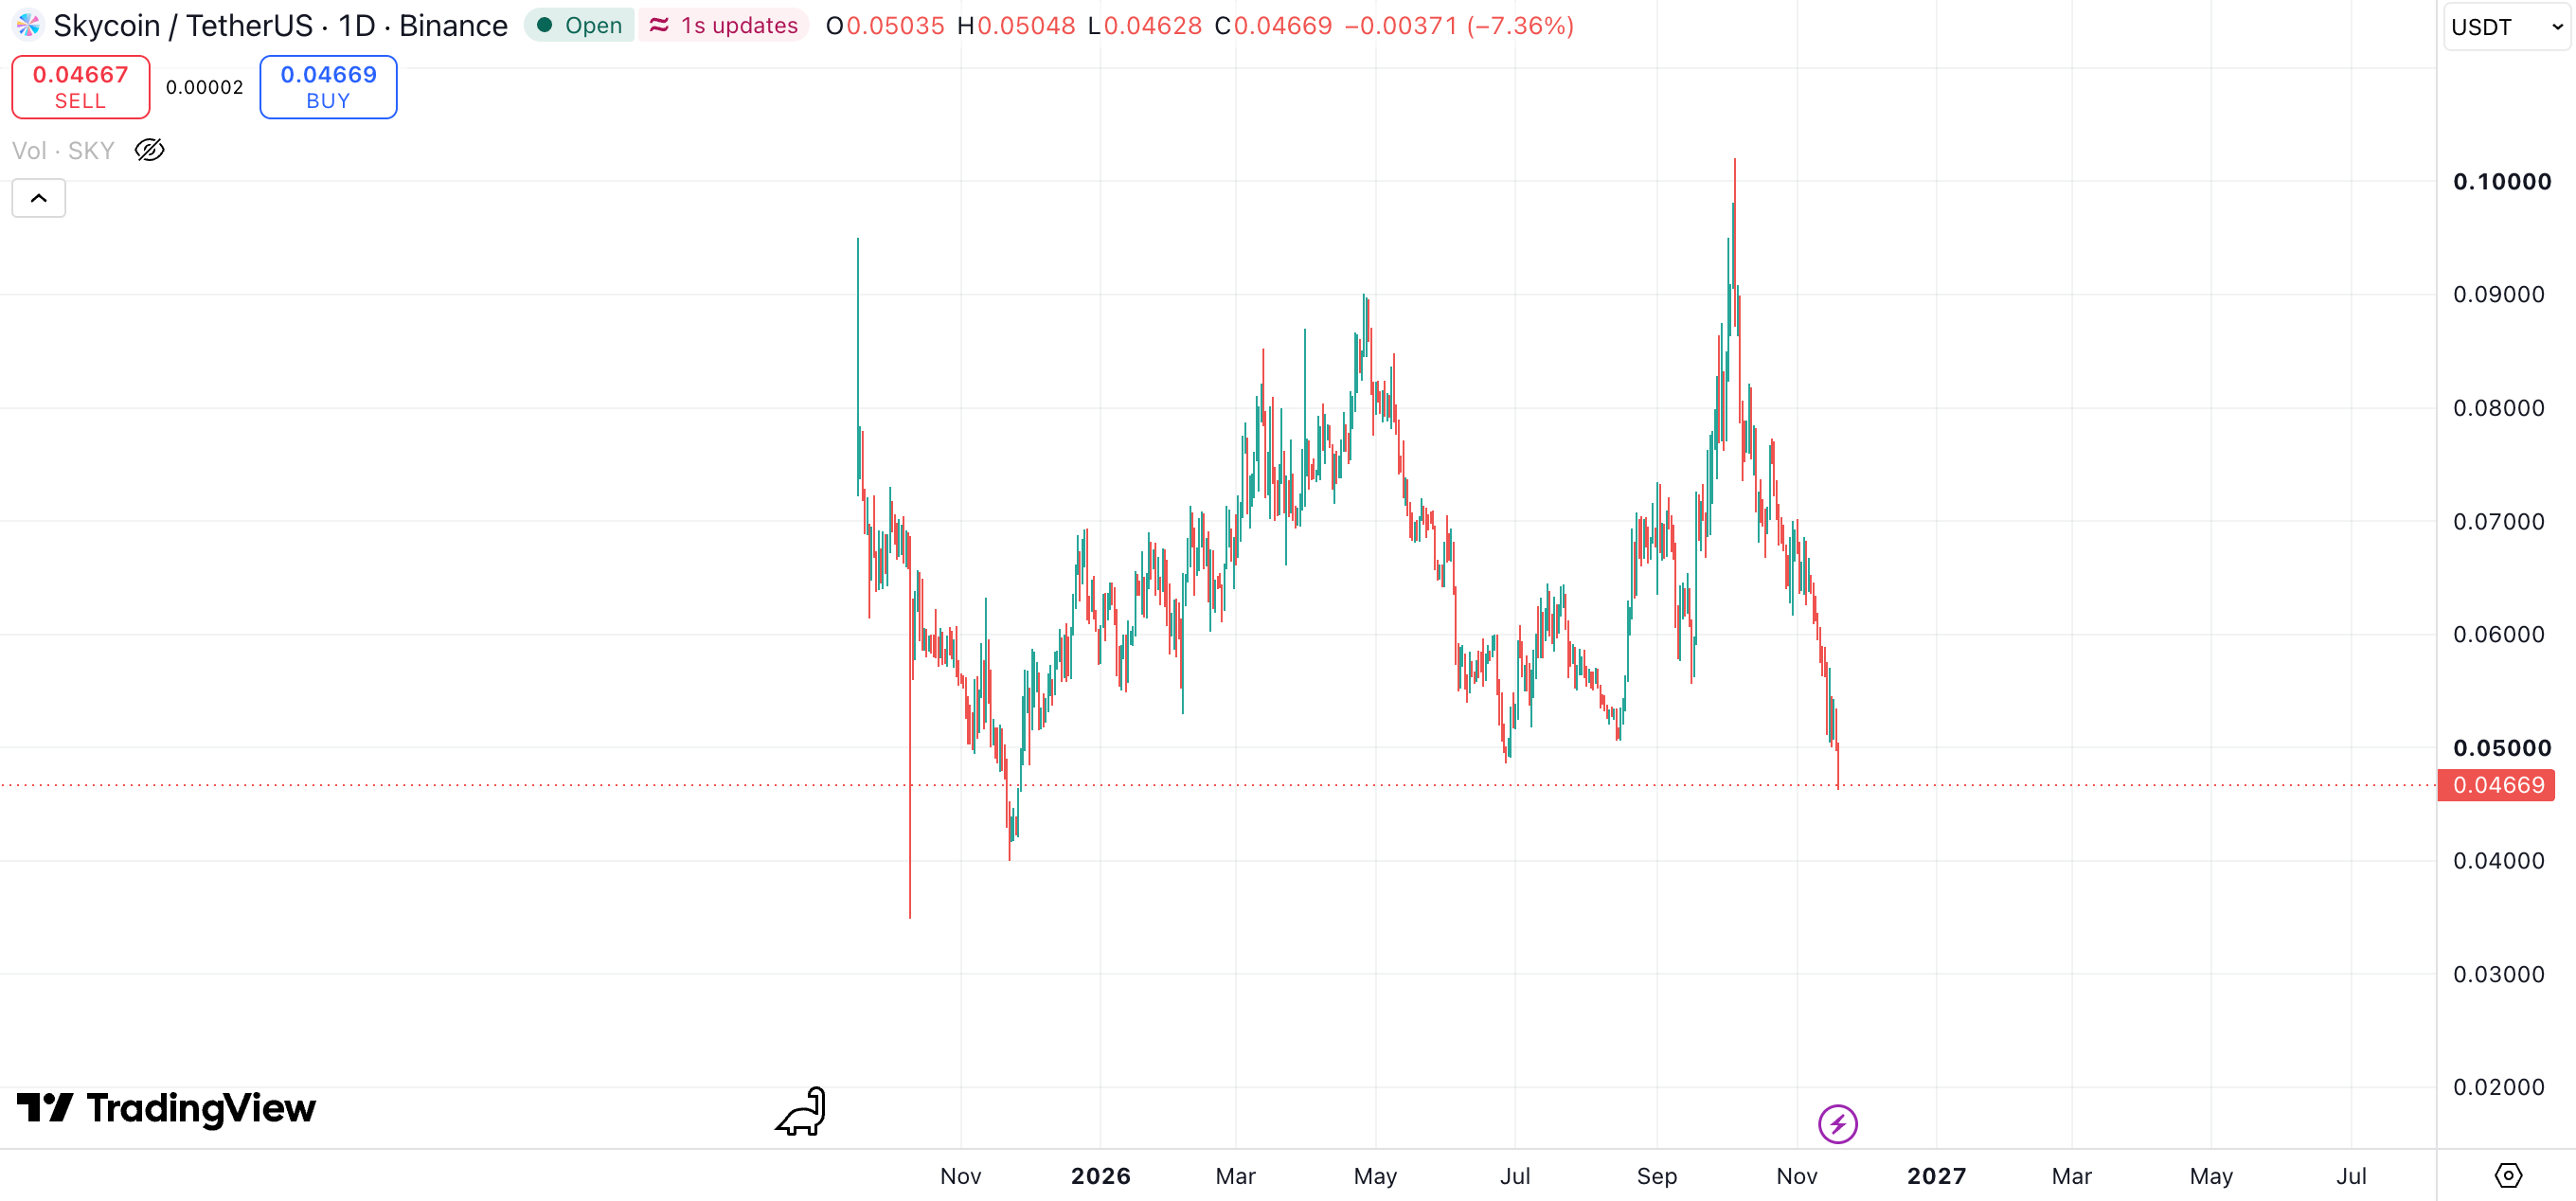
Sky's timing for converting the token from MKR to SKY coincided with the end of the bull market, which meant SKY's liquidity was never good from the start. Currently, Rune's position appears temporarily safe, but if the crypto market continues to weaken, liquidation will be inevitable.
DeBank may still be using the 145% liquidation threshold, causing some positions to display a health factor below 1. Overall, the series of operations in the second half of last year means that even though this SKY/USDS lending pool looks precarious, as long as SKY does not experience an extreme price decline, the pool is not at immediate risk of "blowing up."
But another question follows: does rune.eth's use of the rules to cash out such a large amount effectively shift the risk onto the protocol and retail users?
The USDS funds in the SKY/USDS lending pool exceed $150 million. Meanwhile, the Curve and Morpho exit channels mentioned in the governance forum late last year now appear to be a drop in the bucket.
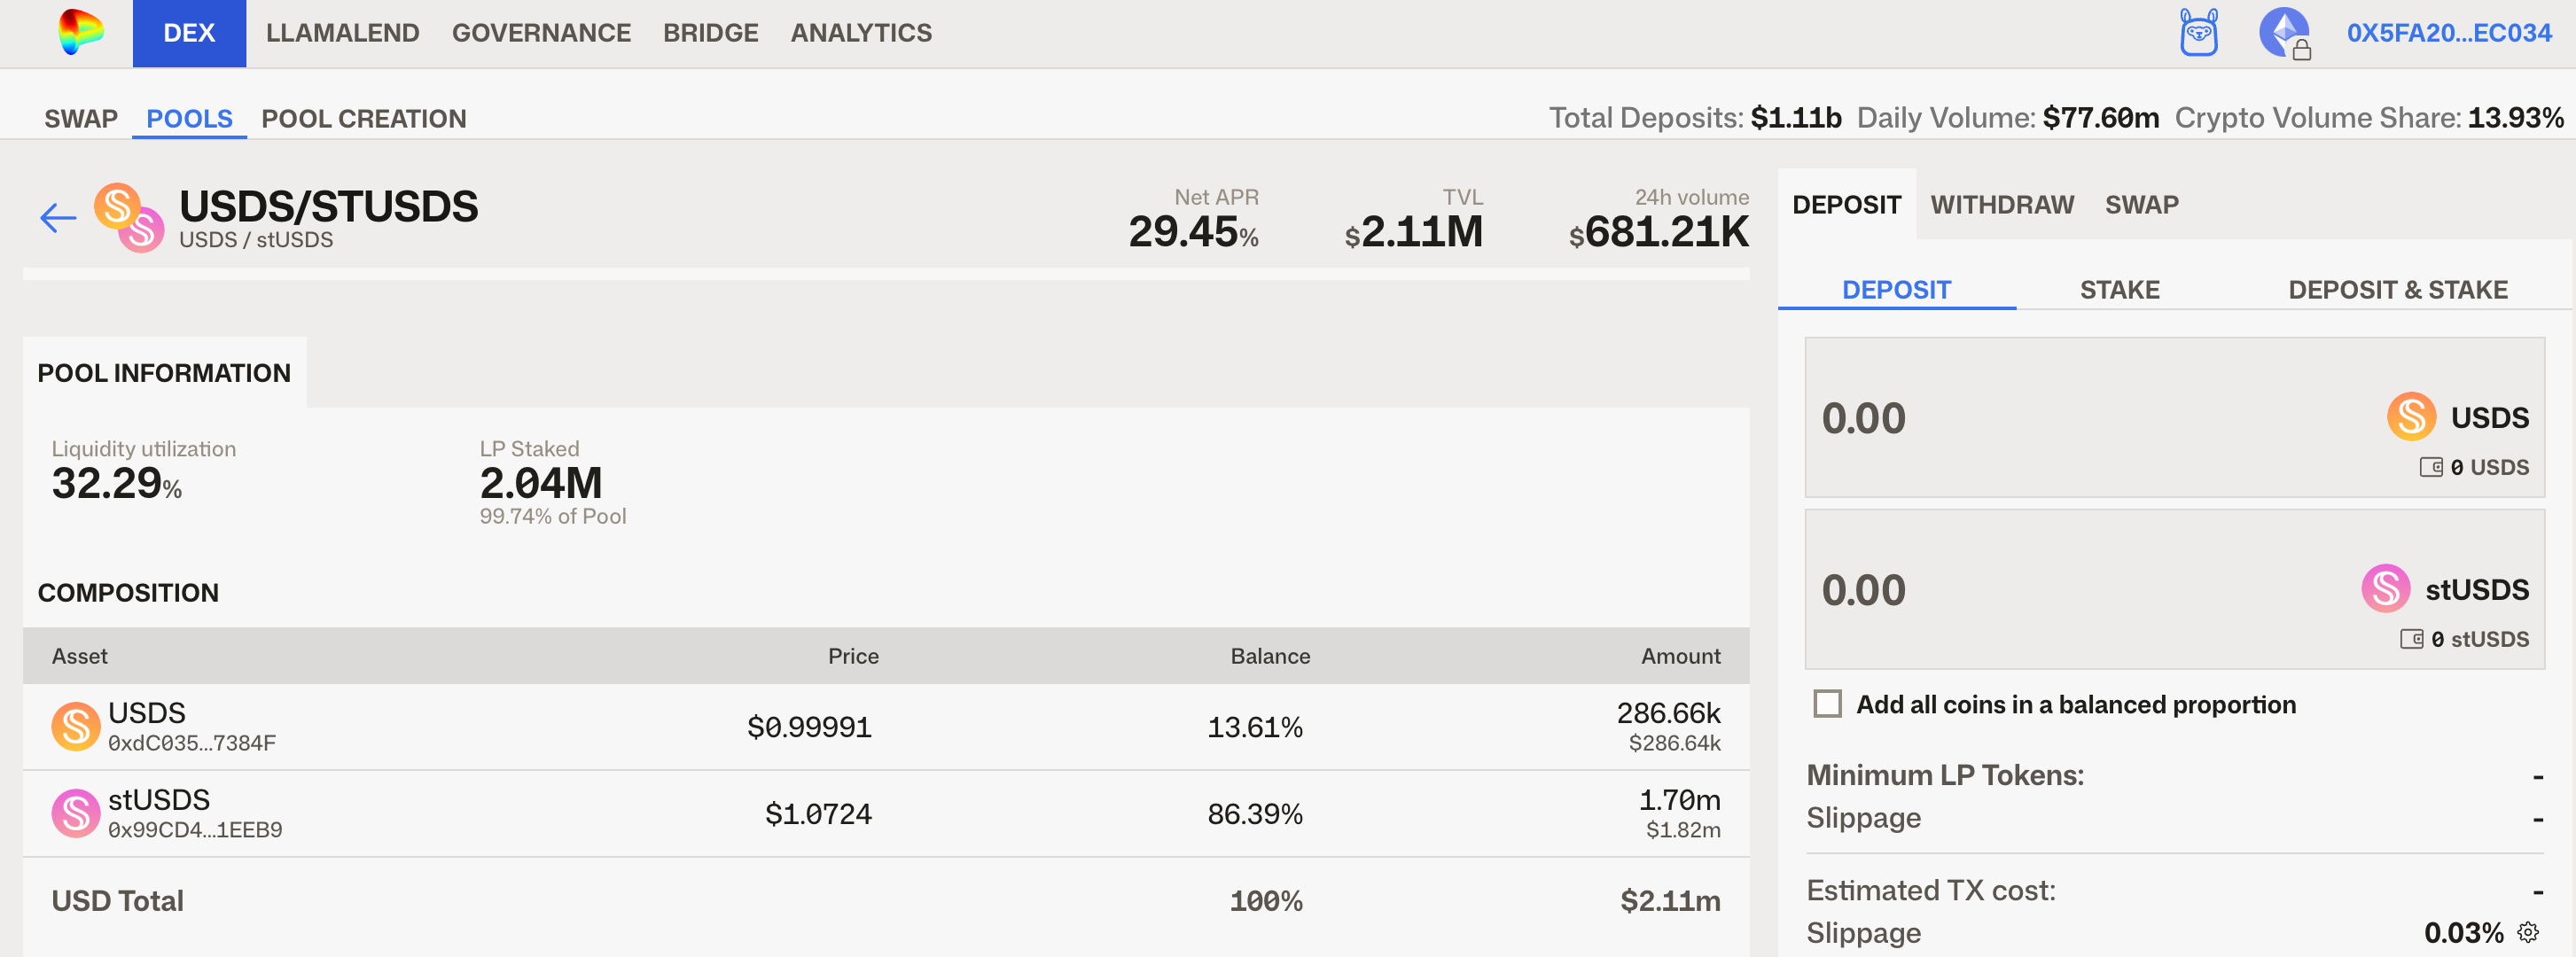
In the USDS/stUSDS liquidity pool on Curve, stUSDS now accounts for over 80%, clearly indicating that a large amount of USDS has been swapped out for stUSDS. On Morpho, the situation is even more evident: 3 stUSDS pools with over $6.5 million in liquidity each have been completely drained.
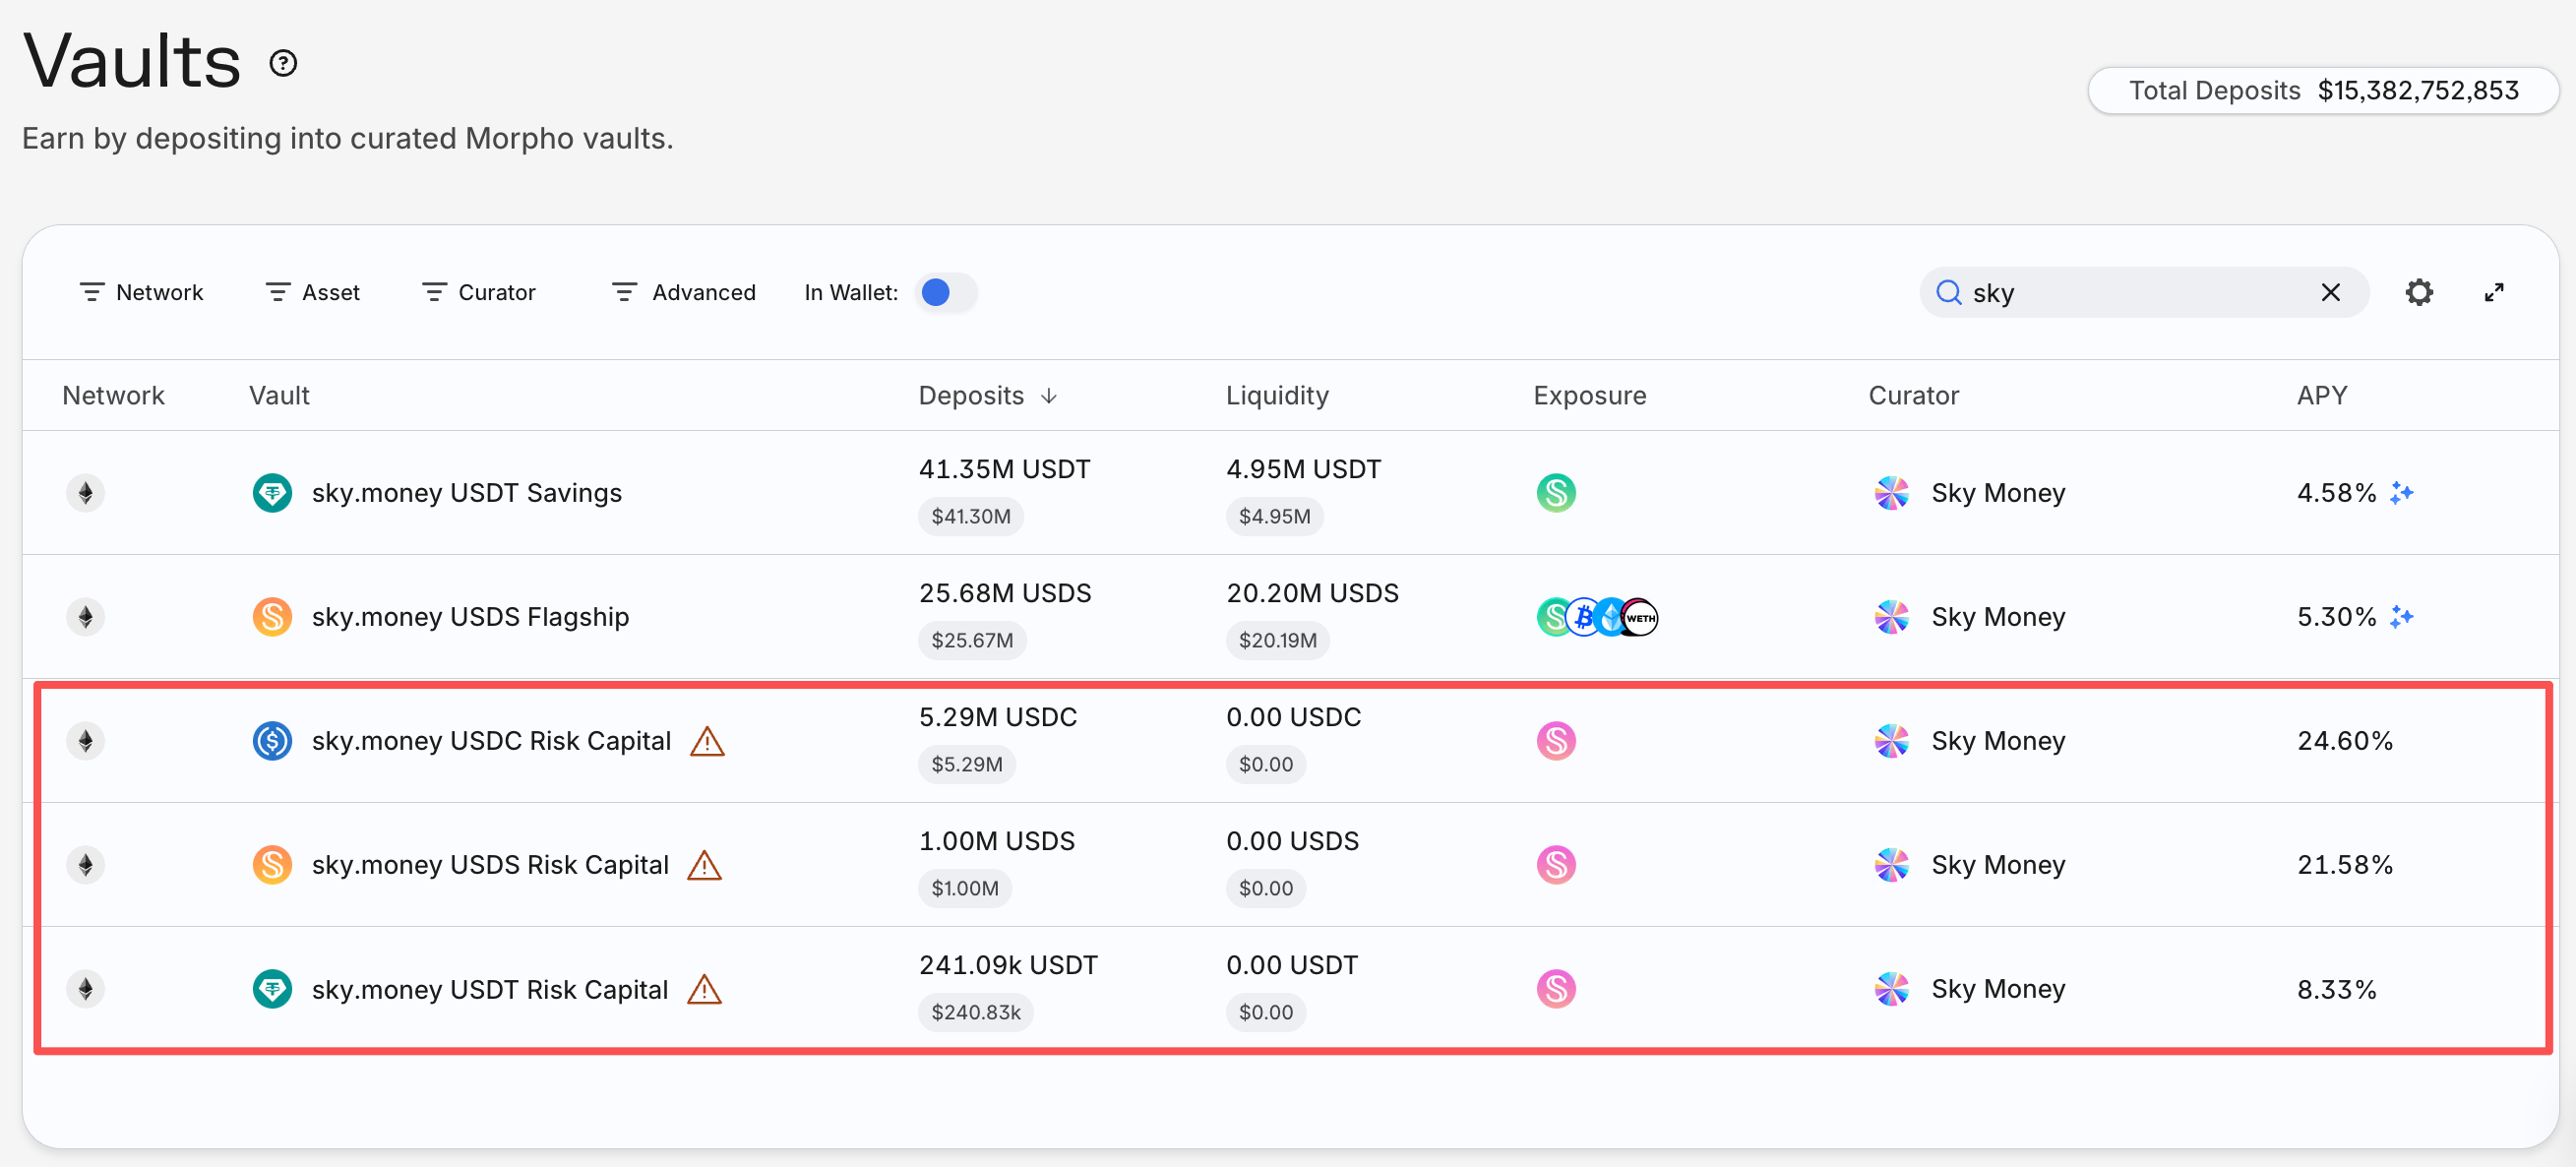
At most, the exit liquidity for these stUSDS positions is worth less than $9 million—less than 6% of the $150 million pool—and has already been drained by "smart money" ahead of everyone else.
Based on SKY's price of approximately $0.04625 at the time of writing, Rune's collateralized SKY amounts to roughly 4 billion tokens. According to 1inch data, even trading just 2.5% of that 4 billion—100 million tokens—would result in slippage exceeding 20%.
In other words, if SKY's price continues to decline and falls below $0.03 or even $0.025, even with gradual manual liquidations, bad debt in this pool will be unavoidable. And given the SKY liquidity on Ethereum, unless the Sky protocol itself steps in to absorb these SKY tokens, the scale of bad debt could well exceed $100 million.
A considerable number of Web3 practitioners on X have pointed out that this is likely a repeat of the incident where Curve's founder collateralized CRV to borrow stablecoins.
According to DefiLlama data, USDS is currently the third-largest stablecoin after USDT and USDC, and the largest among crypto-native stablecoins by issuance, exceeding $5.2 billion—surpassing USDe's approximately $4.9 billion. Sky ranks 10th by TVL among all DeFi protocols. The scale and position of the Sky protocol within DeFi remain unquestionable.
Additionally, Sky and its founder Rune had not responded to the matter as of the time of writing, and there is currently insufficient on-chain evidence to definitively establish that rune.eth is controlled by Rune Christensen. Nevertheless, given the behavior of a large token holder cashing out through a lending protocol during periods of poor liquidity and converting personal risk into systemic risk, this is still worth DeFi lending protocols' consideration and warrants targeted solutions.





