


SignalPlus Macro Research Report (20231012): Focus on today’s CPI data


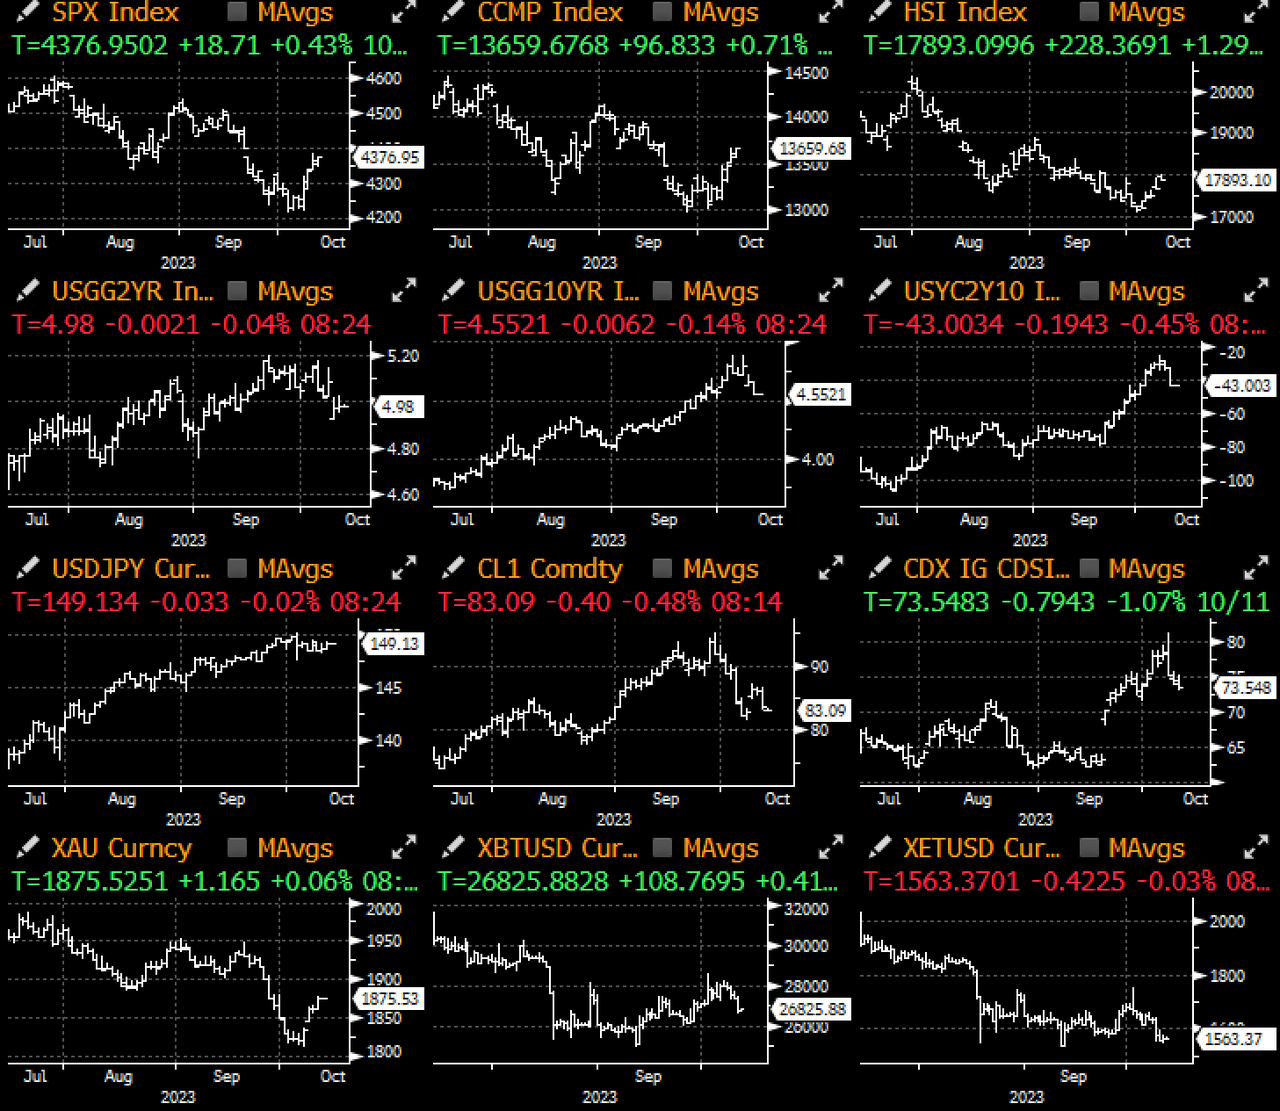
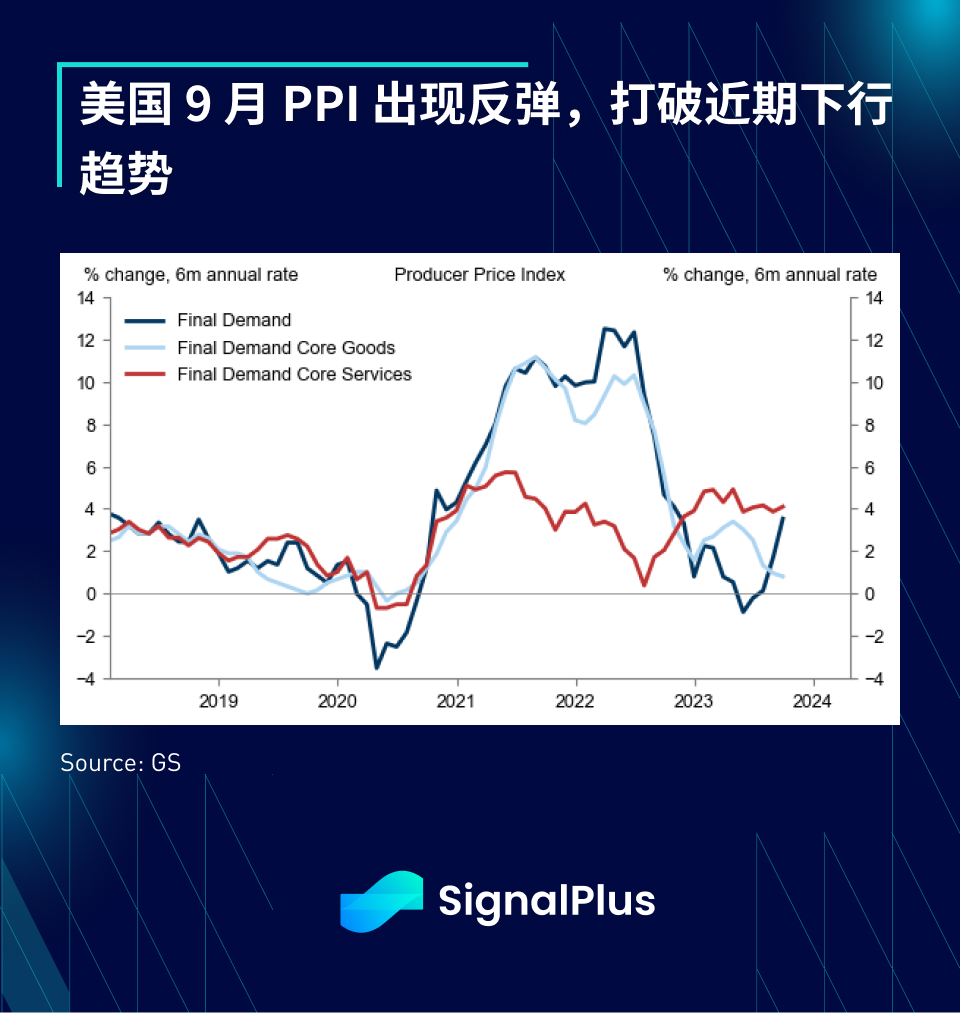
The U.S. PPI increased by 0.5% month-on-month in September, and the core PPI increased by 0.3%, both slightly higher than market expectations. The year-on-year growth also jumped to 2.7%, the highest level since April. The pressure mainly came from commodity prices (up 0.9%), energy prices (up 3.3%) and food prices (up 0.9%); both stock and fixed income markets fell immediately after the data was released, with the U.S. Treasury yield curve flattening 2.5 basis points and the SPX index falling 0.3% from its high.
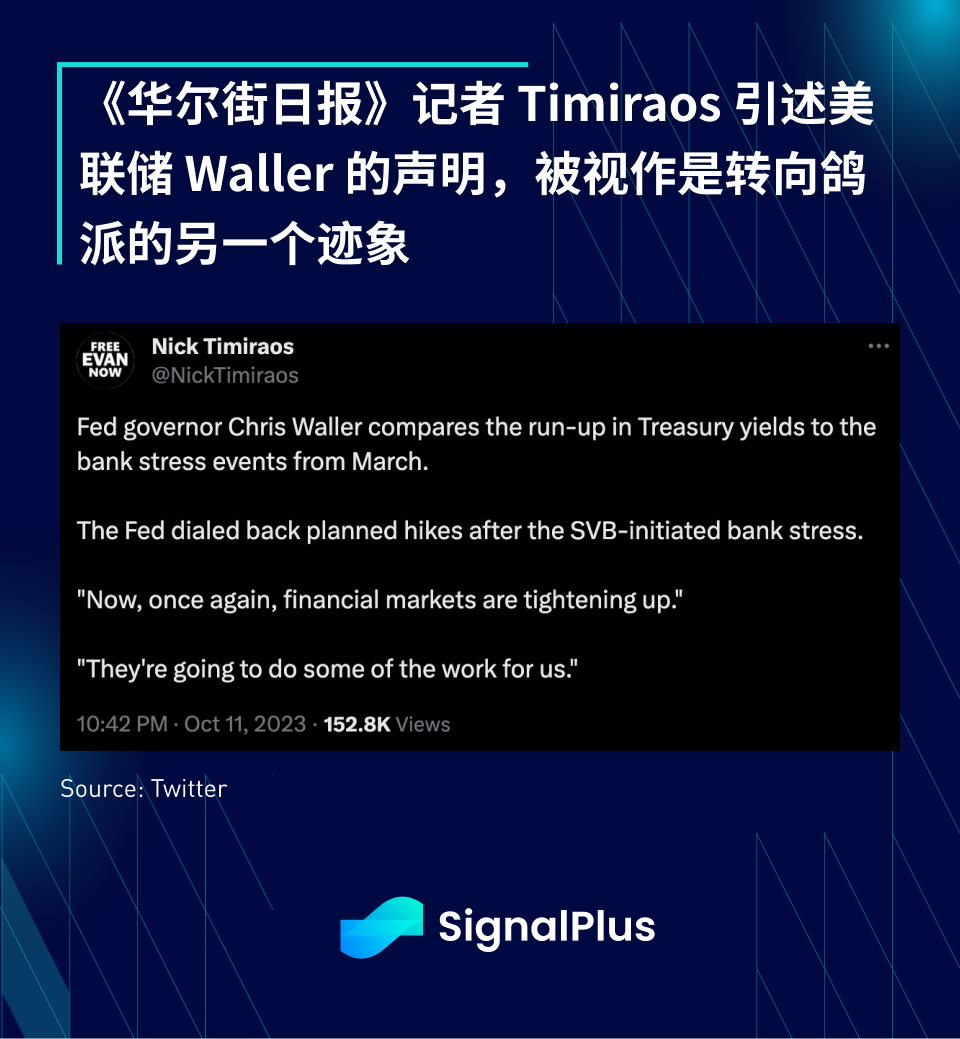
However, the upward trend in yields did not continue. The continued short squeeze in the global fixed income market caused a 15 basis point increase in British bonds. The bond auctions in the United Kingdom and Germany also received good responses; in addition, the dovish comments of Waller, the governor of the Federal Reserve, Noting that they finally got very good inflation [data] and that the Fed can now take a wait and see approach to raising interest rates; following a dovish article in the Wall Street Journal on Tuesday, Timiraos tweeted Wallers statement was quoted, suggesting that the current interest rate trend is similar to the SVB incident and has done most of the work for the Fed to tighten financial conditions.
The market originally expected a calm trading day, but the minutes of the FOMC meeting, which should have been outdated, showed unexpected dovish arguments, suggesting that the policy interest rate has reached sufficiently restrictive and that economic risks will be two-way; there are many minutes of the meeting Policy rate peaks were mentioned for the second time, and the focus of policy decisions and communications should shift from how high to raise rates to how long to keep them at restrictive levels. In addition, despite the current resilience of the economy, many officials are still optimistic that to downside risks to economic growth and a consensus that tighter credit could dampen economic activity; finally, Fed officials discussed the rise in term premiums for the first time in written comments, as the yield curve has steepened from July lows Against the background of about 60 basis points, their attention to this issue is also increasing.
Taken together, these comments further confirmed the Feds clear dovish bias after the weekend and also pushed the 30-year bond yield down 9 basis points, with the SPX index rising 1% from the session low.
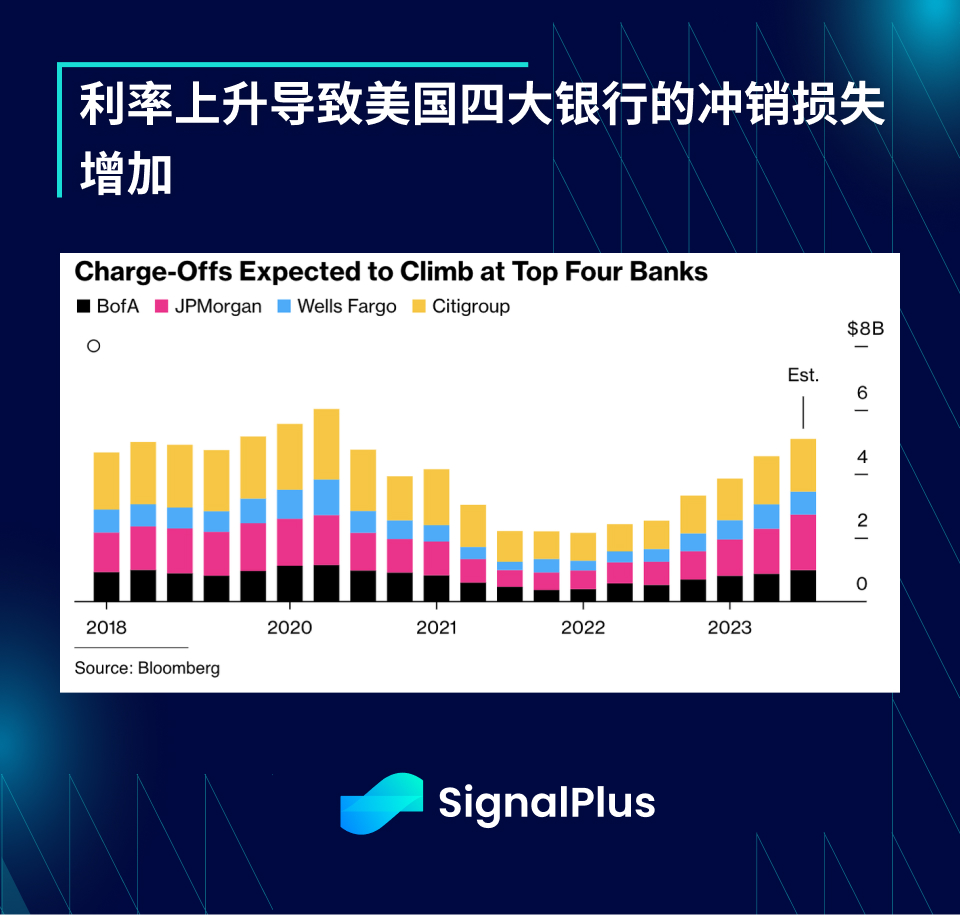
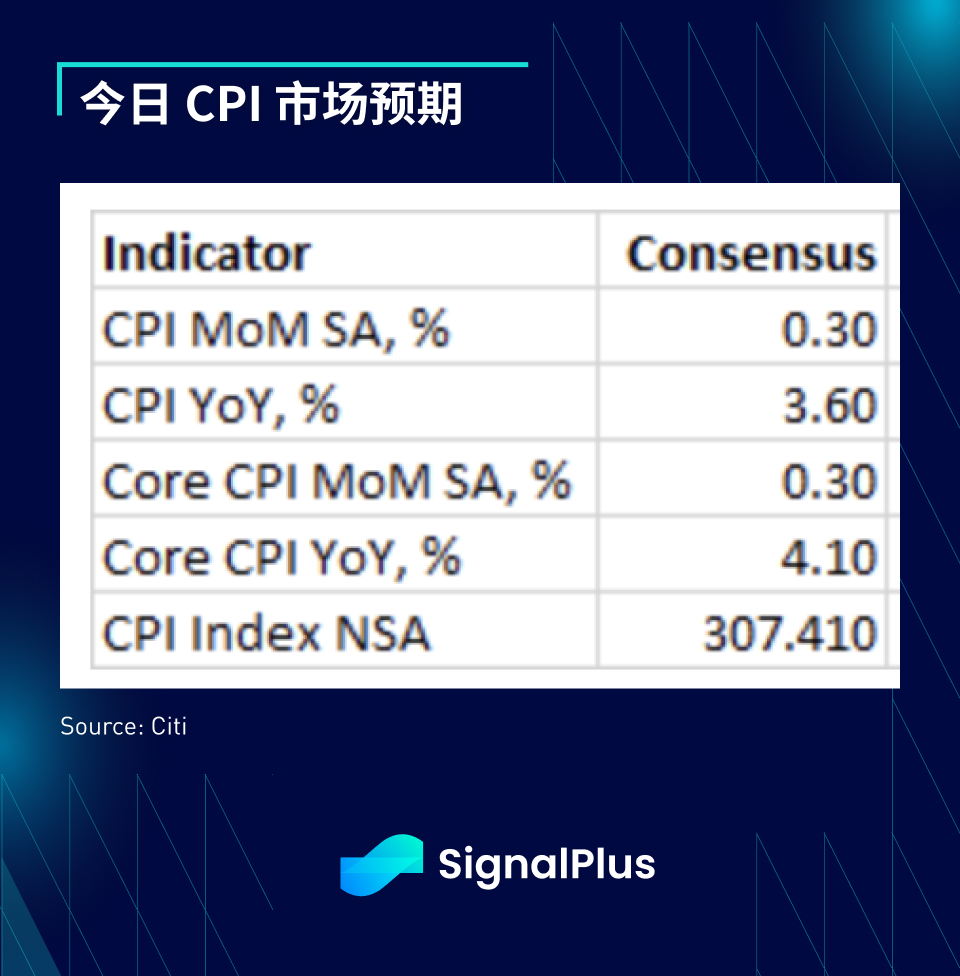
The focus this week will be todays CPI data, followed by the earnings season that starts on Friday; as risk markets seem to have fallen into a new round of FOMO after the Feds obvious turn, there is a higher chance of lower data today, again Pushing risk markets higher, CPI may need to reach 0.4% or above to halt the markets recent strength, while any data below 0.3% may be regarded as confirmation of a dovish turn, causing risk sentiment to further heat up and the dollar to fall. I wish you all smooth trading!
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption information. If you want to receive our updates immediately, please follow our Twitter account @SignalPlus_Web3, or join our WeChat group (add assistant WeChat: SignalPlus 123), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website:https://www.signalplus.com





