


SignalPlus Macro Research Report (20231009): The market focuses on this week’s CPI data


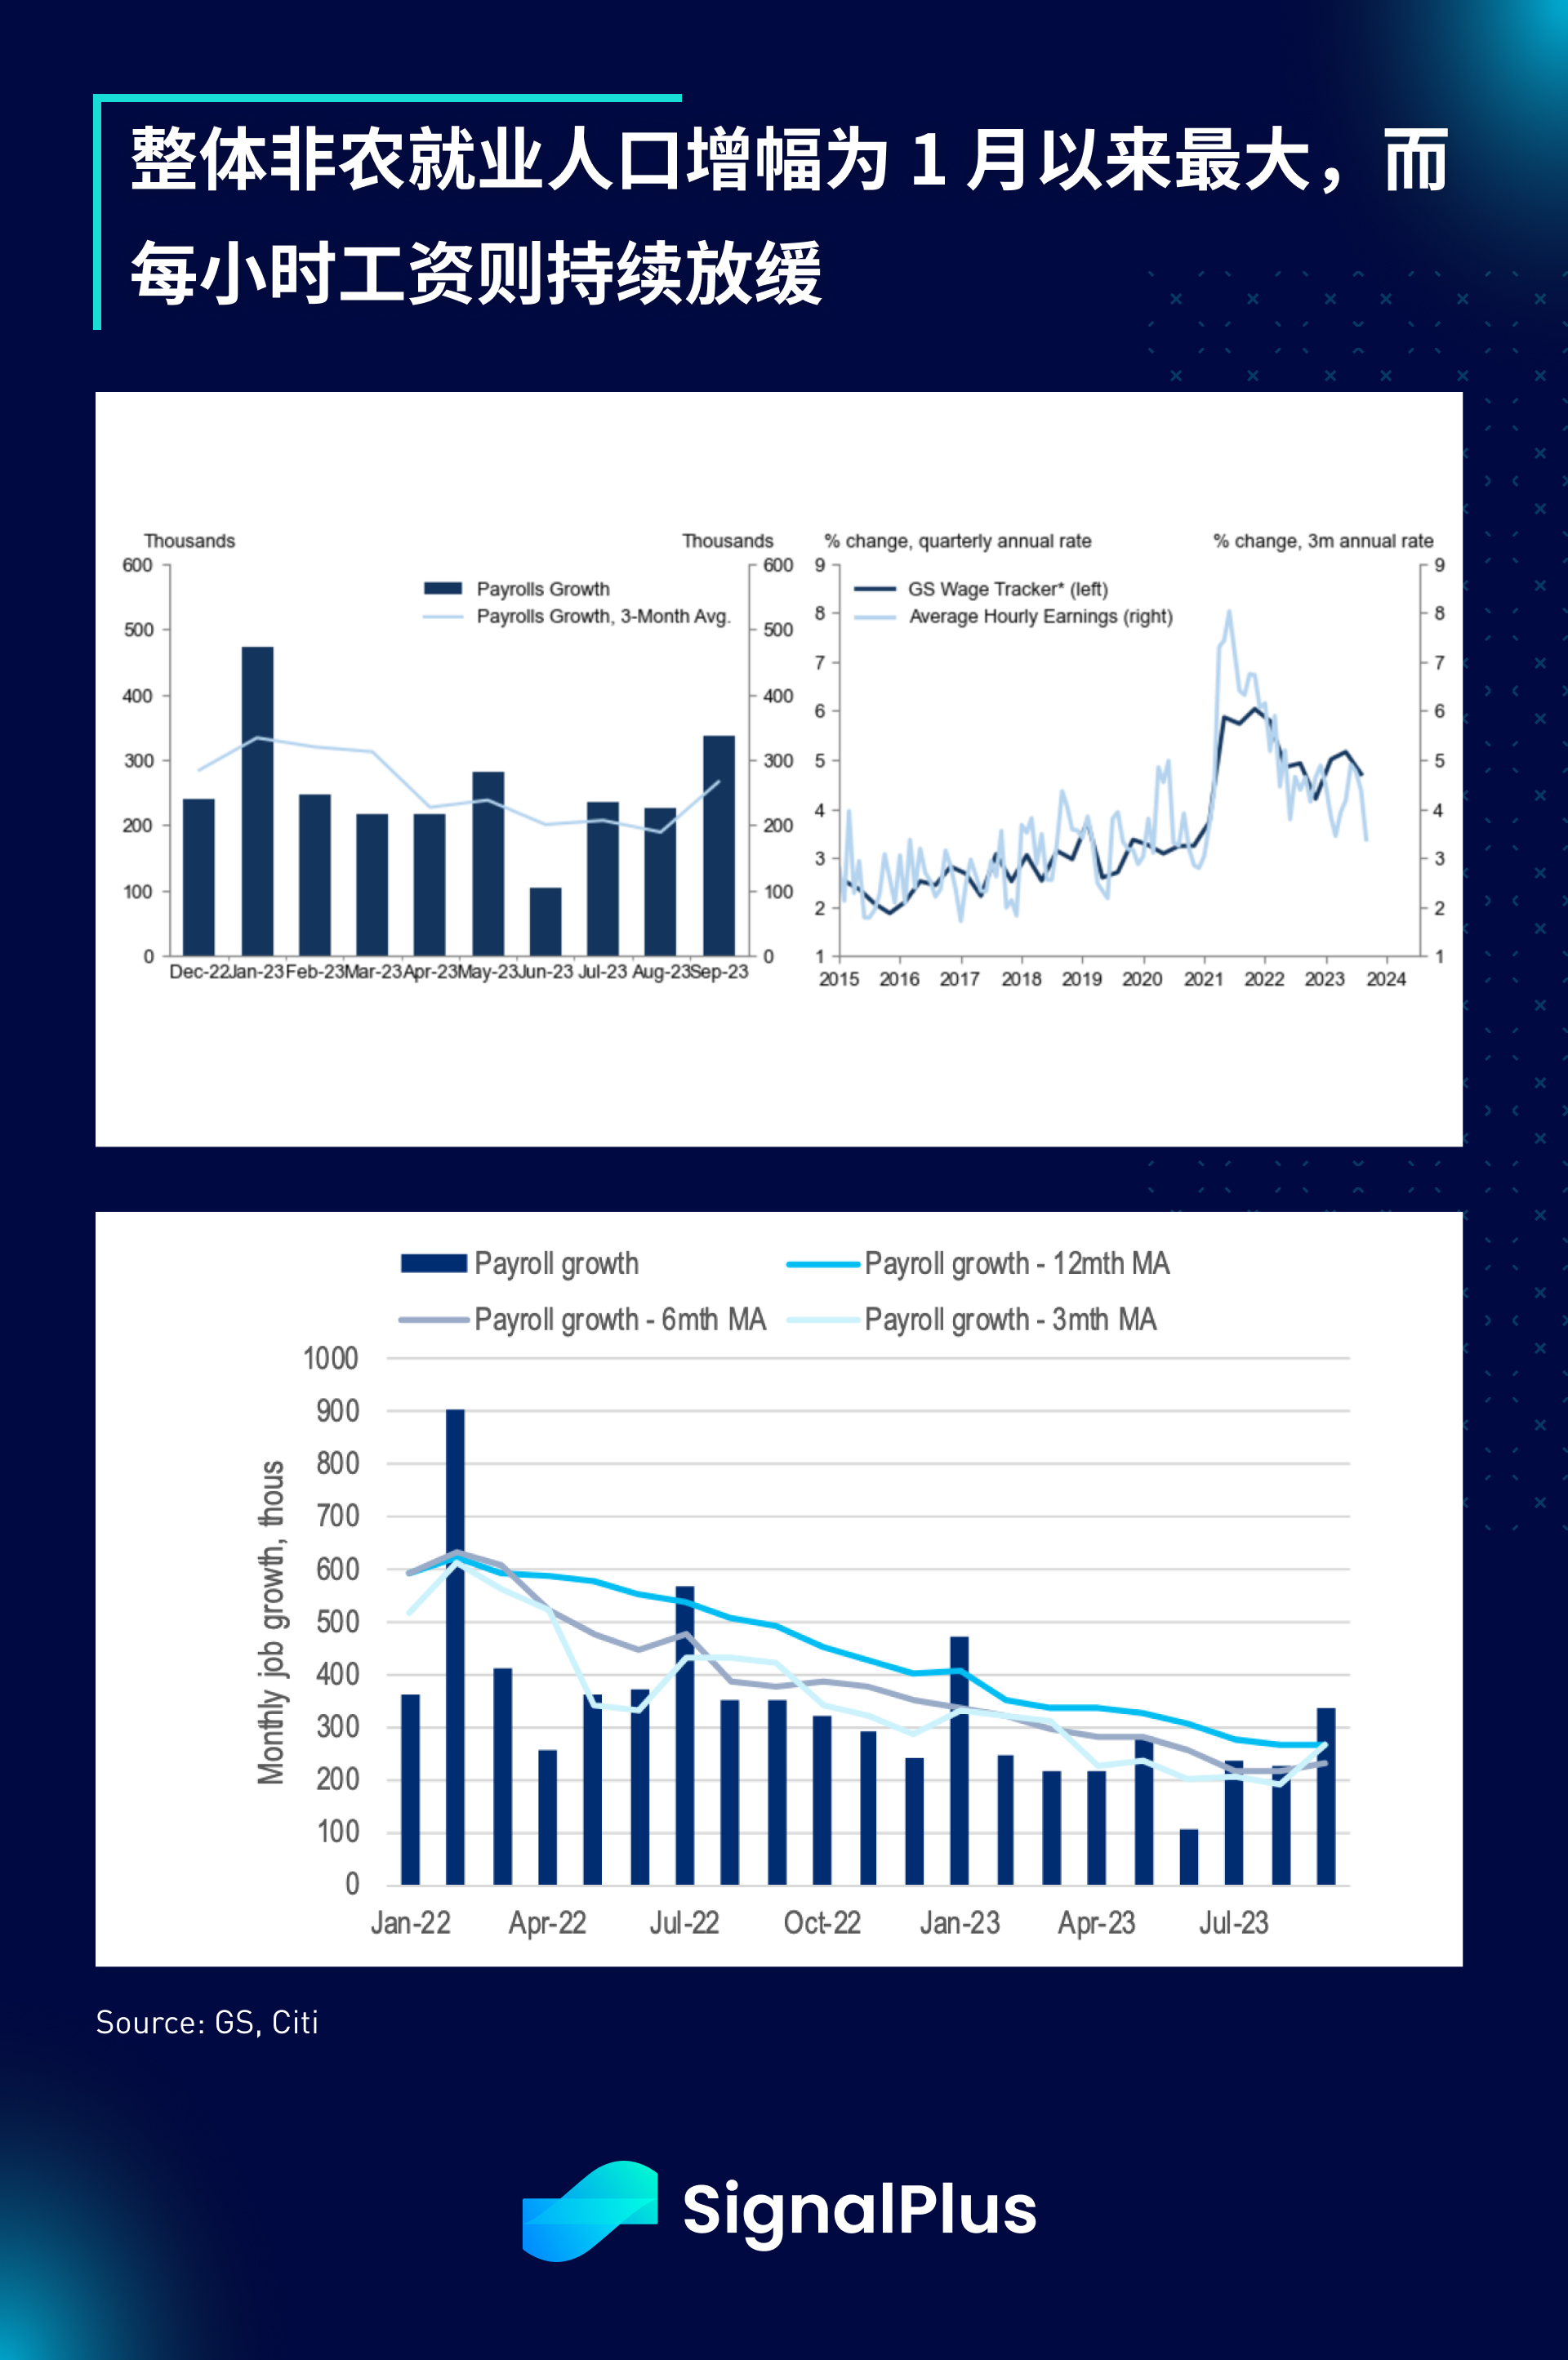
Non-farm employment data released last Friday showed that the number of employed people increased by 336,000 in September, almost twice the market expectation and the largest monthly increase since January. The previous value was also revised upward, with August and July was revised up to 227,000 (+40,000) and 236,000 (+79,000) respectively, showing a strong job market overall, with the service industry being the strongest, with an increase of 234,000, followed by leisure and The hotel industry increased by 96,000, and education and health care increased by 70,000. However, the overall unemployment rate also reached a seven-month high of 3.8%, and hourly wage growth slowed to 0.2% month-on-month (0.4% in July). %). Finally, as the economic situation slowed down, the labor force began to increase again. After the labor force surged by 736,000 people in August, it further increased by 90,000 people in September, and the labor force participation rate remained stable at 62.8%.
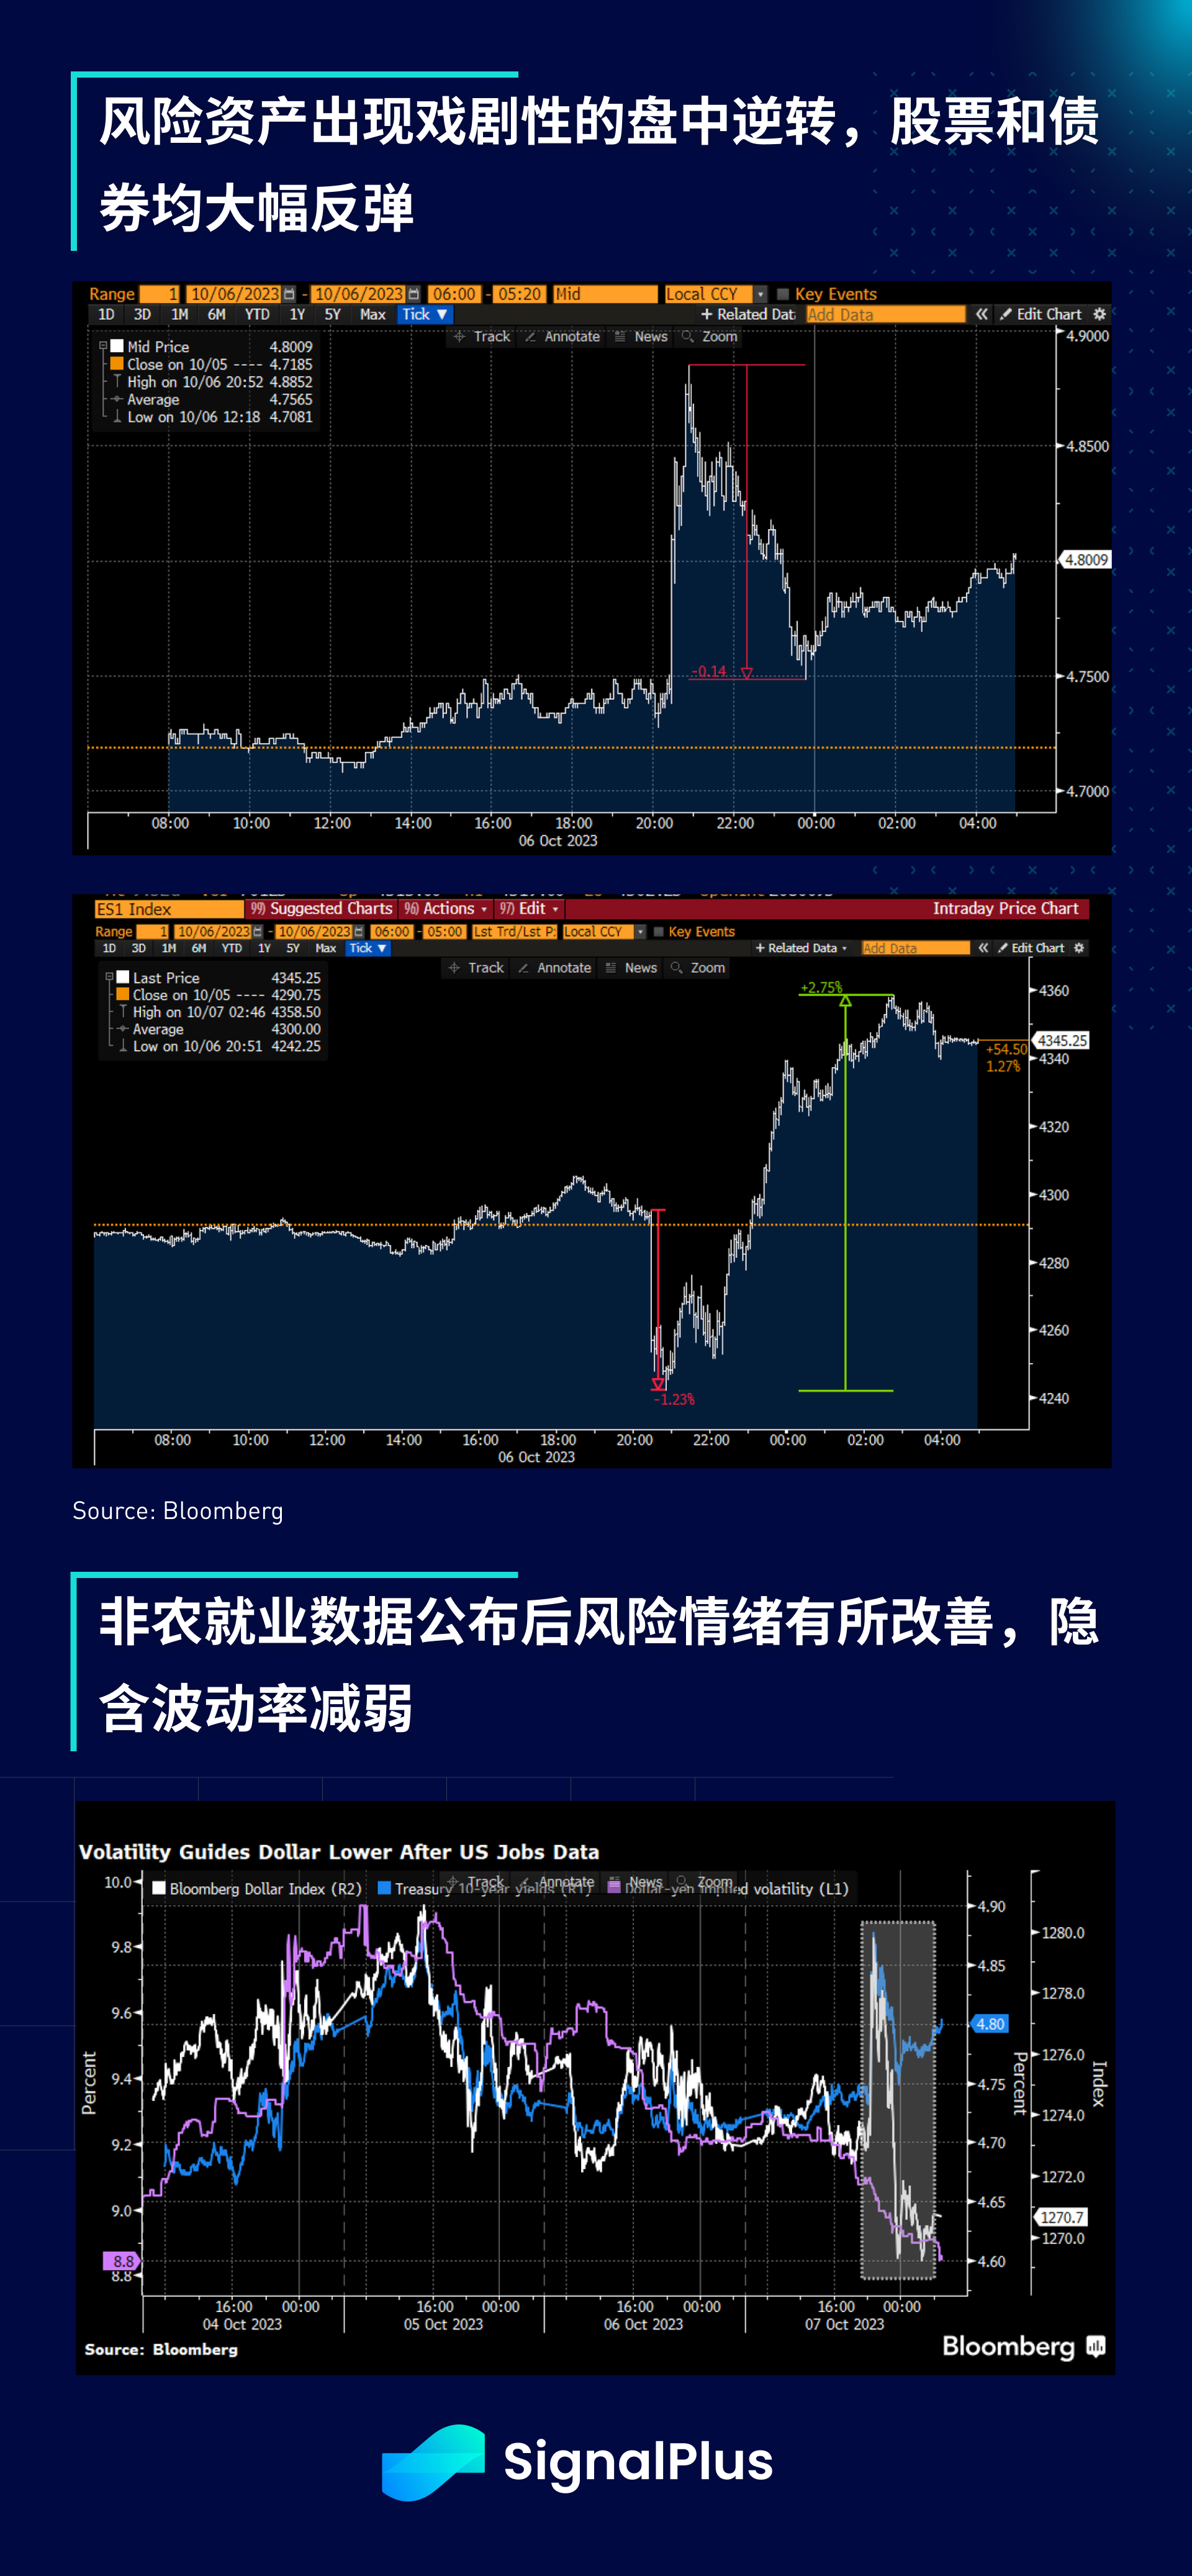
Shortly after the data was released, the 30-year U.S. Treasury yield first surged, hitting its highest level since 2007. The yield initially jumped 16 basis points, while SPX futures fell 1.3%. However, just when risk assets seemed to be going through Another tough session saw sentiment take a sharp turn late morning in New York, with yields retreating 14 basis points from peak to trough, while the SP Index moved more than 3 standard deviations intraday in a staggering rebound. At 2.8%, the U.S. dollar index broke a 12-week winning streak, implied volatility fell, gasoline and industrial commodities fell to their lowest levels in a month, and despite strong non-farm payrolls data, the possibility of a Fed rate hike in November Prices remain stable at just over 20%, and all in all, last week ended with a well-timed squeeze rally.
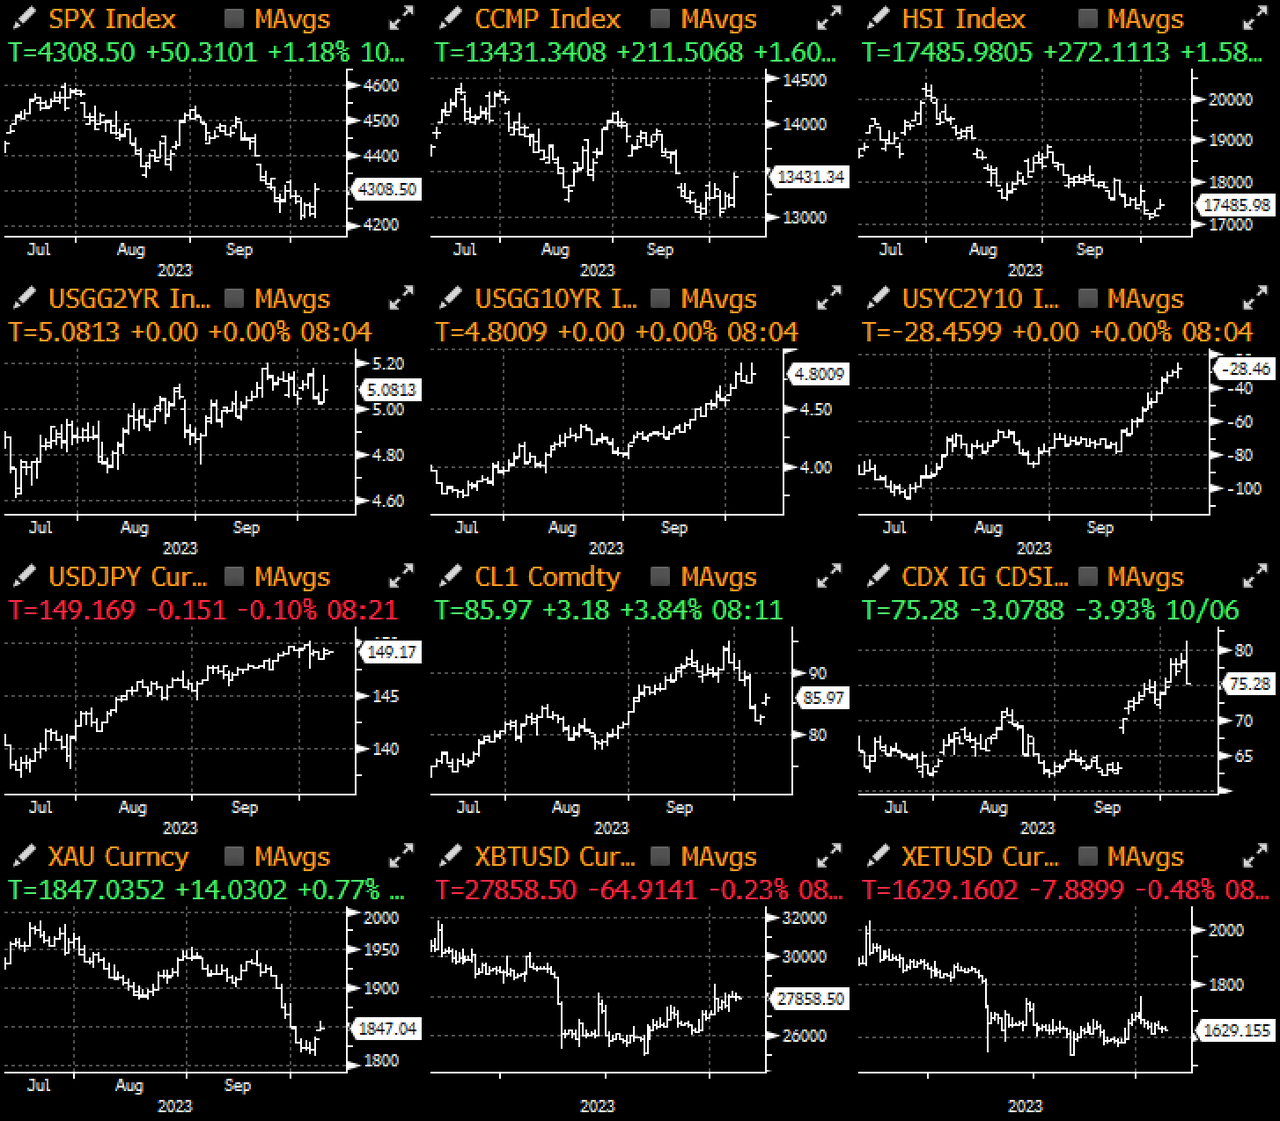
However, the calm in markets did not last long, as Hamas launched an unprecedented attack on Israel over the weekend, raising concerns about deepening conflict in the region and the risk of another war, the last time a similar situation occurred in 1973. The Yom Kippur War in 2006 caused crude oil (supply reduction) and gold (safe haven) prices to rise sharply, bond yields soared (inflation), and stocks sold off accordingly. This time, the market was relatively more conservative, opening on Monday morning. , crude oil/gold/bond prices rose slightly, and stocks fell only 0.6%; apart from the tragedy caused by the conflict, the markets main focus will be on crude oil supply and whether the current attack will significantly weaken the Middle East that the world has worked hard to achieve in recent years. To de-escalate the situation, we hope that the conflict can be de-escalated quickly to minimize casualties.
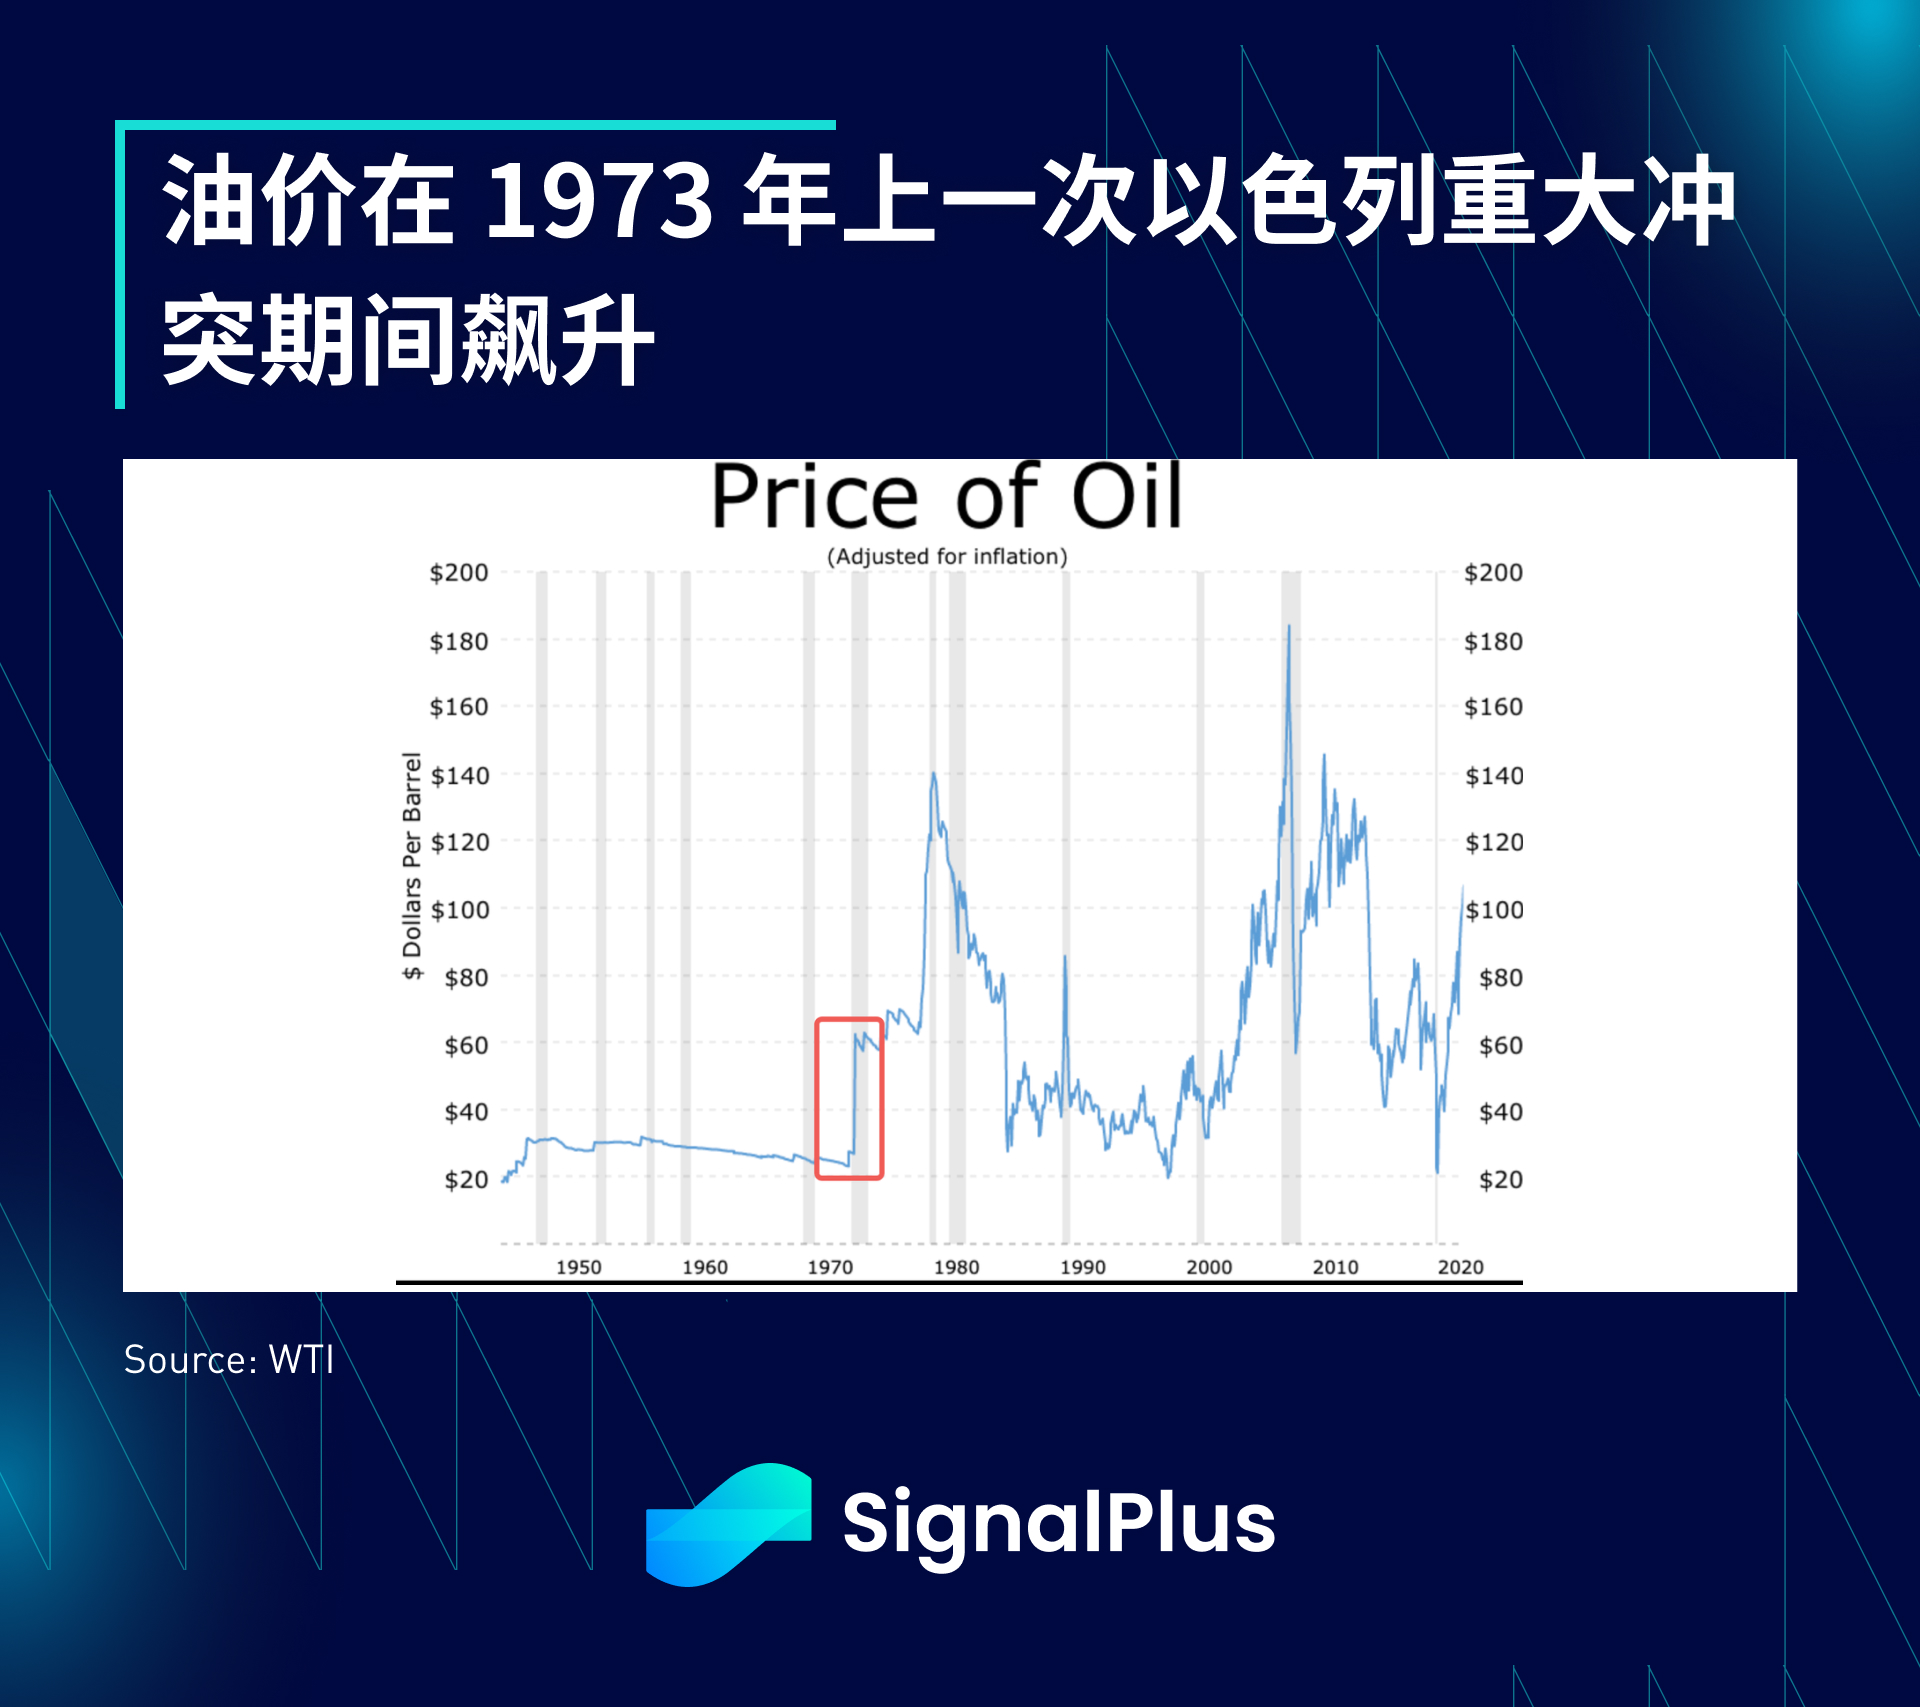
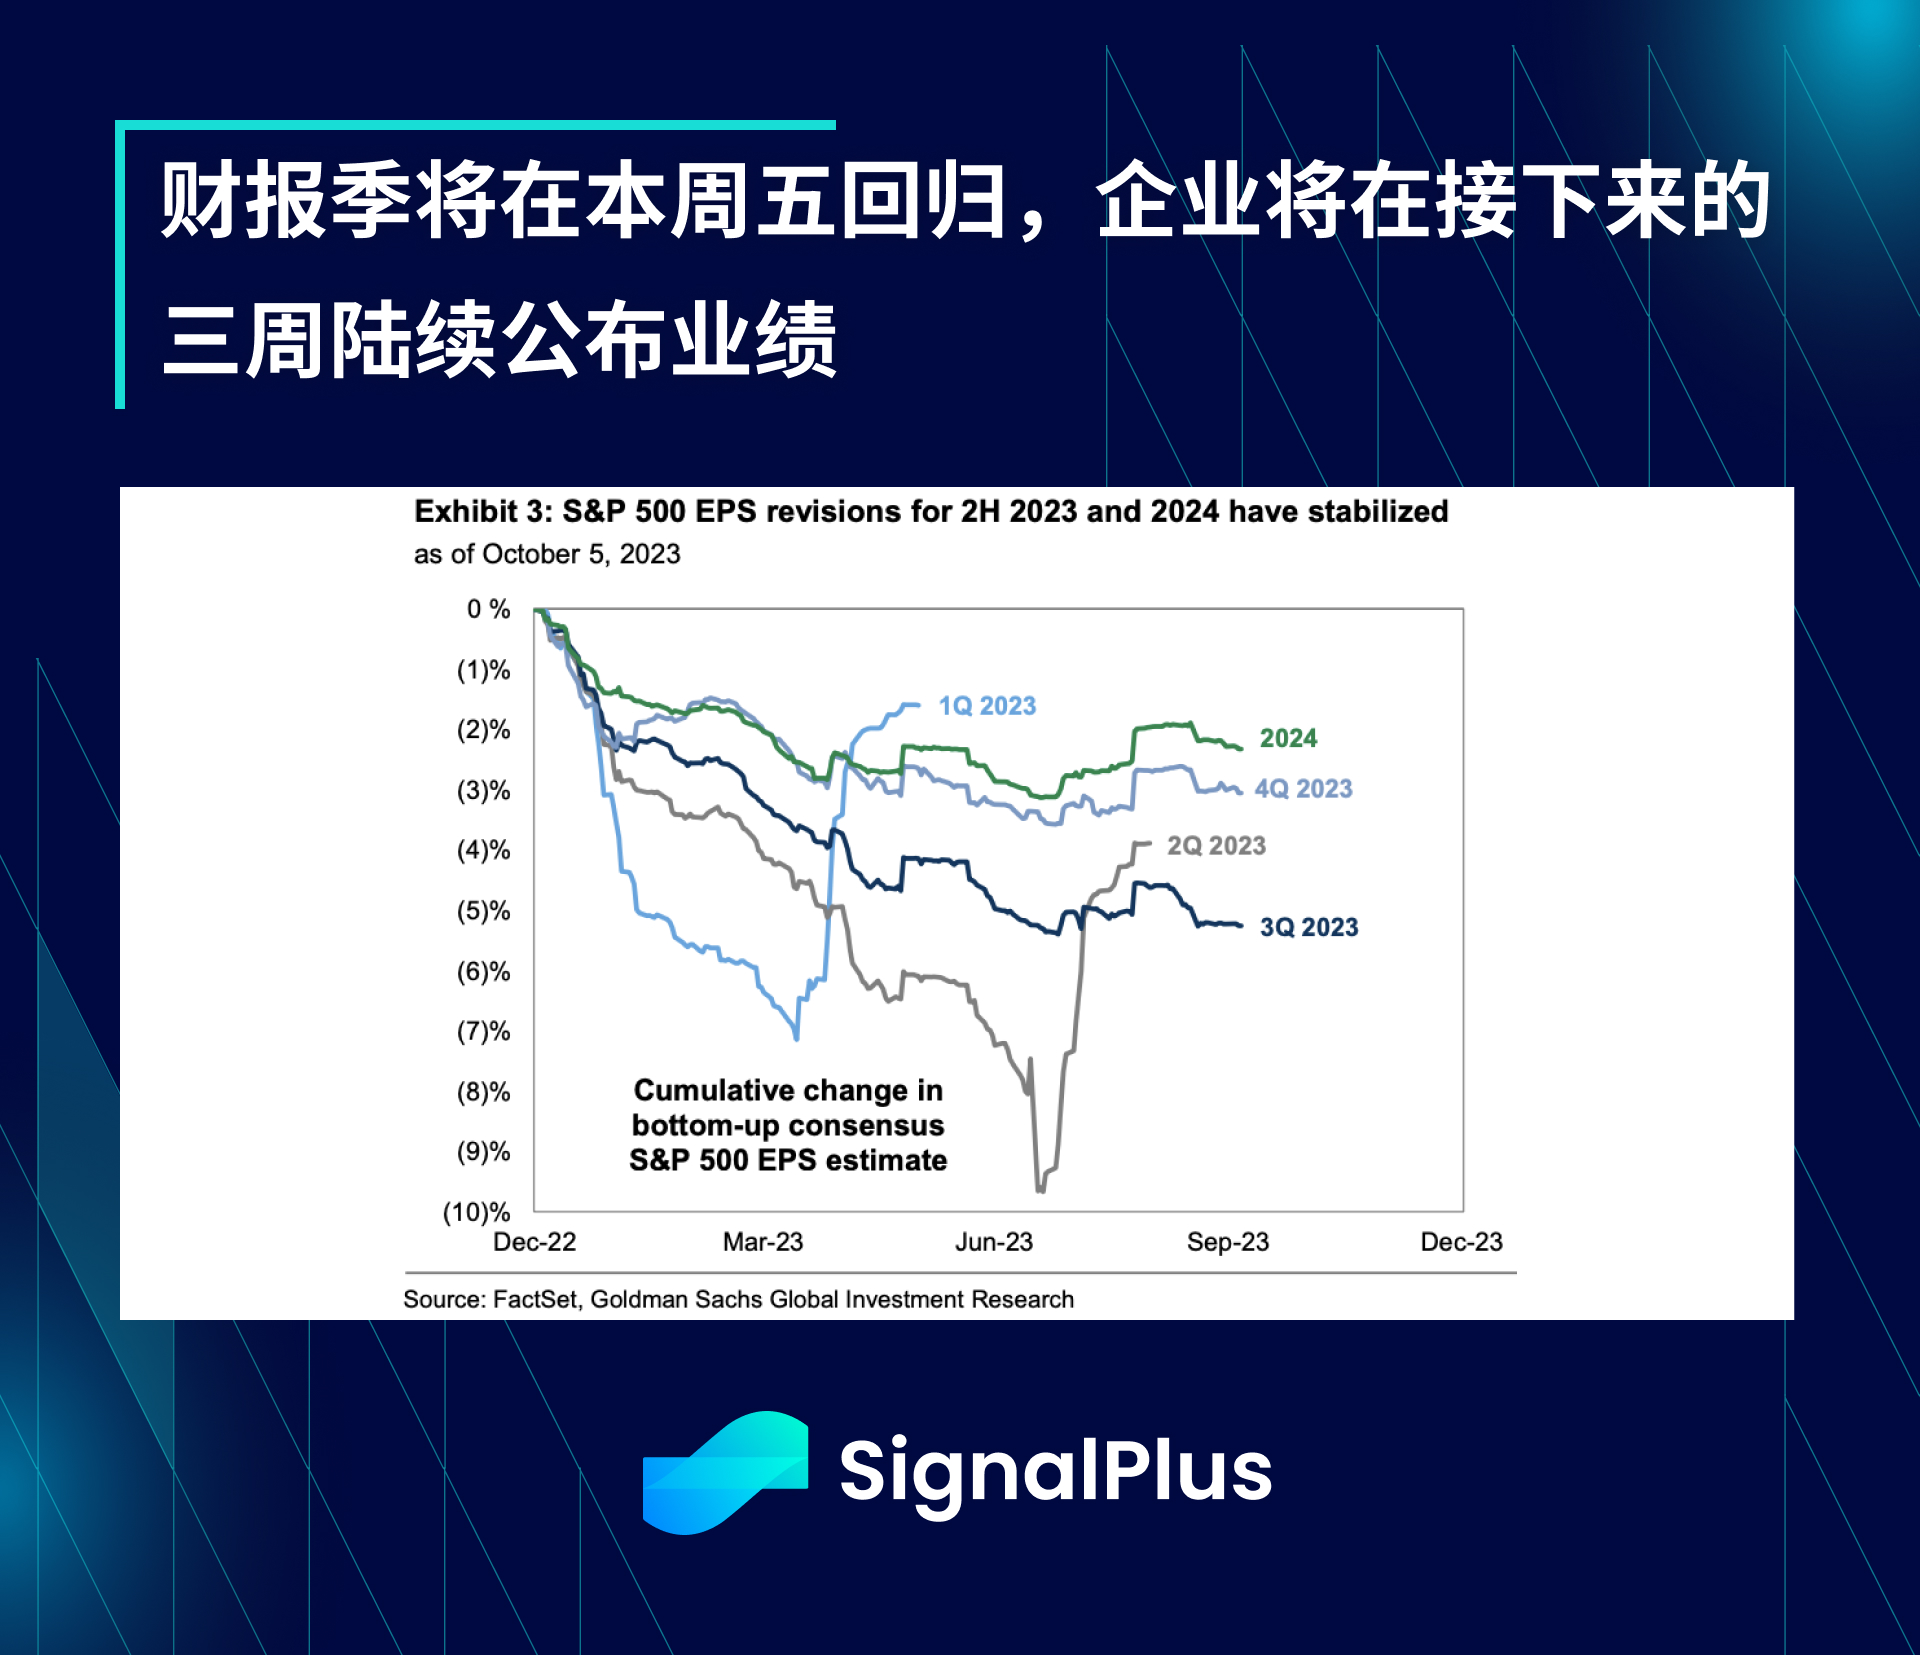
The market will next focus on the CPI data later this week. The market expects the CPI to increase by 0.3-0.4% month-on-month, with OER (owner equivalent rent) and tourism prices increasing. In addition, the financial reporting season will return in full force after this week. Citi, JPM and Wells Fargo will kick off their third-quarter financial reports on Friday. Nearly 80% of SP 500 companies will announce their results in the next three weeks, and profit forecasts have already been announced. Pretty stable and the EPS threshold will be slightly higher than the past two quarters.
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption information. If you want to receive our updates immediately, please follow our Twitter account @SignalPlus_Web3, or join our WeChat group (add assistant WeChat: SignalPlus 123), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website:https://www.signalplus.com





