


SignalPlus Macro Research Report Special Edition: Higher for Longer


As we mentioned in the FOMC preview article, we suspected that Powell would try to introduce a hawkish pause in interest rate hikes at last nights meeting through a more aggressive dot plot and related discussions. This was indeed the case, and this The submarket is finally getting the attention it deserves.
Earlier, the UK tried to seize the market focus. The annual CPI growth rate announced before the interest rate decision slowed to 6.7%, lower than the expected 7.0%. The market forecast for todays Bank of England interest rate decision was lowered to 50/50, which also gave Risk assets brought some early support, with SPX futures reaching an intraday high near 4505.
As widely expected by the market, the Federal Reserve decided to suspend interest rate hikes at 2 p.m. There were few changes in the FOMCs official statement, except for upgrading the growth assessment from moderate to sound.
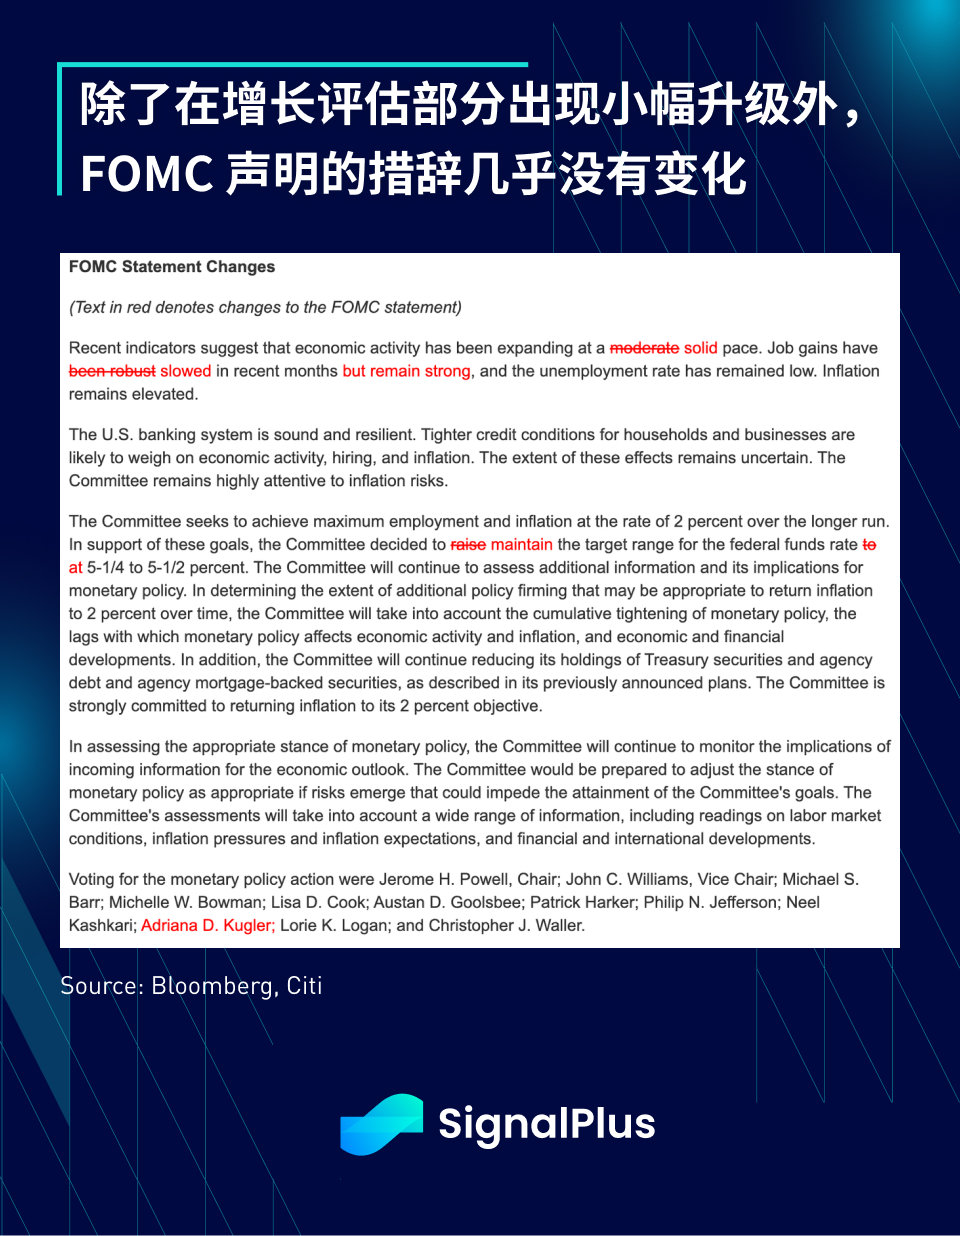
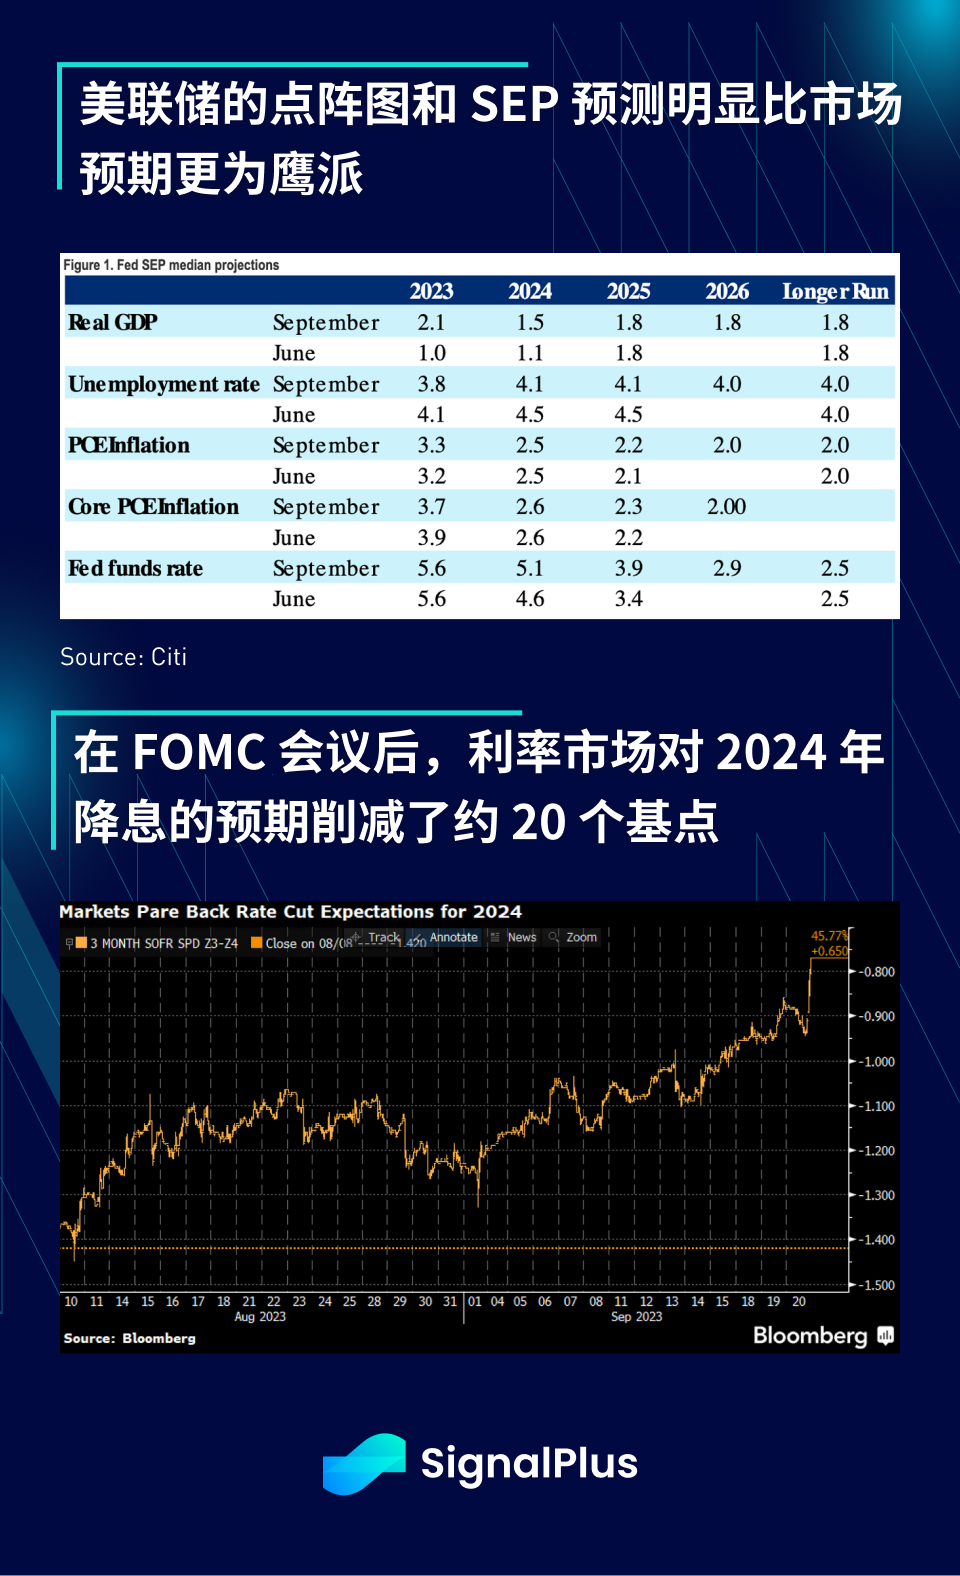
However, the focus of the meeting was ultimately the dot plot and the SEP (Summary of Economic Projections), both of which were clearly hawkish, far exceeding market expectations.
It is expected that there will be another rate increase in 2023. On 12/19, Fed members supported another rate increase, while the other 7 members supported no further rate increase.
The median interest rates in 2024 and 2025 both increased by 50 basis points (5.1% and 3.9% respectively), significantly higher than market expectations.
Real GDP is revised up from 1.0% to 2.1% in 2023, and from 1.1% to 1.5% in 2024.
The unemployment rate will be reduced from 4.1% to 3.8% in 2023, and the unemployment rate will be reduced from 4.5% to 4.1% in 2024.
However, Chairman Powell once again did his best to present a more balanced outlook at the follow-up press conference, with highlights including:
POWELL: Given the progress weve made, the FOMC decided to keep rates on hold
POWELL: FOMC ready to raise rates further if circumstances warrant
POWELL: We have to be confident that we can bring inflation back to 2%
POWELL: Were very close to where we think we need to be
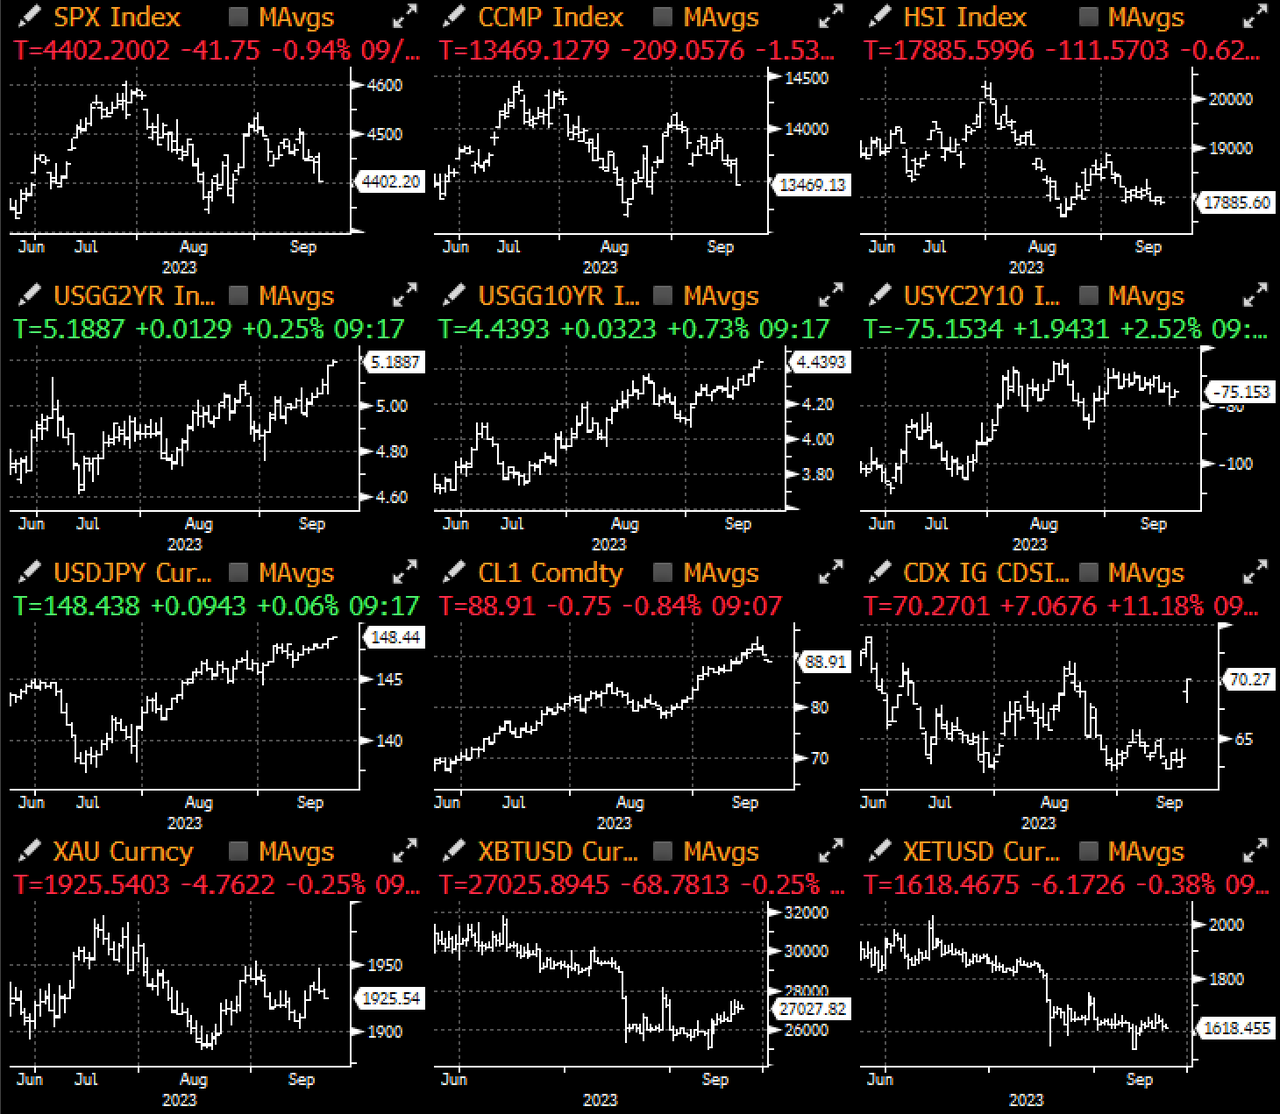
As for market reaction, initially when the dot plot was released, yields surged (2-year +10 basis points) and risk assets fell (SPX -0.5%), but after Powell expressed a more balanced view at the press conference, The market tries to rebound.
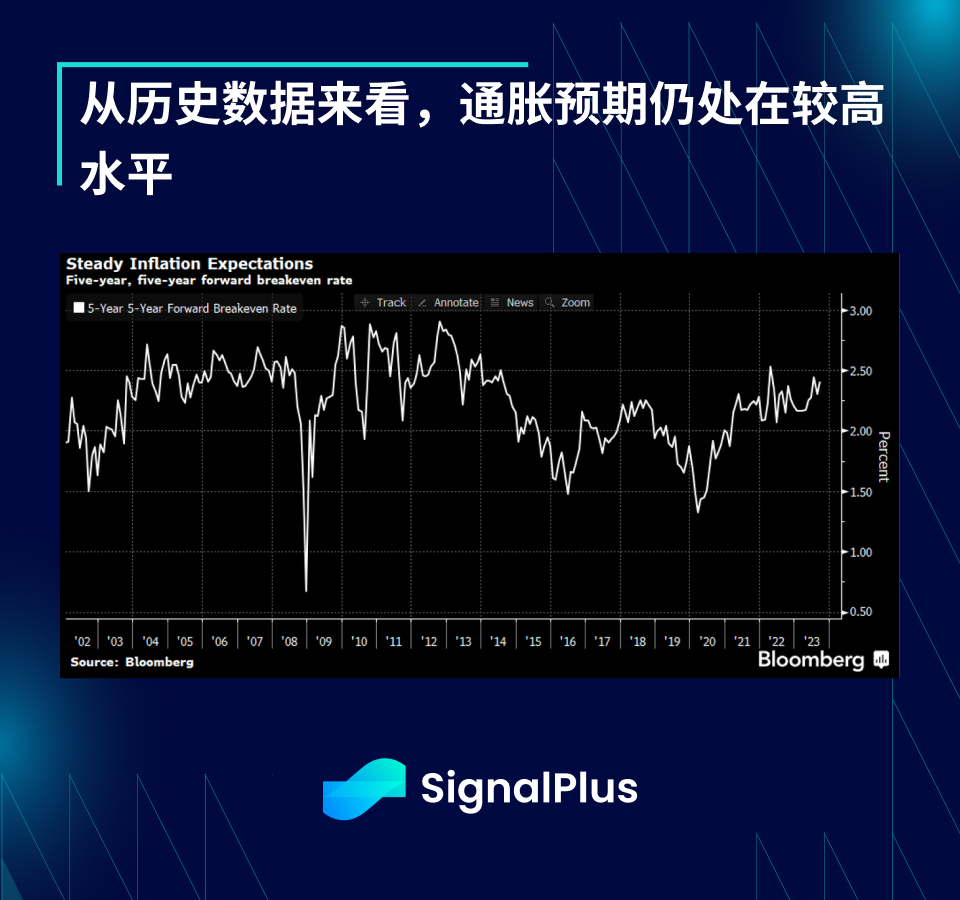
However, as the QA session progressed, it became clear that the Fed was serious about its message of keeping interest rates high for longer, especially as the economy is as strong as expected, U.S. household balance sheets are quite solid, and the unemployment rate remains near historic lows. And the upward revision of the growth trajectory also kept inflation expectations at a high level; finally, risk assets finally collapsed during the question and answer session, with the SPX index falling 1%, the Nasdaq index falling 1.5%, crude oil -3%, and the 2-year yield soaring 13 basis points higher against all major currencies.
POWELL: The neutral interest rate is likely to be higher than the long-term interest rate
POWELL: We wont know the true level of restriction until it emerges
POWELL: Overall, family finances are in good shape
POWELL: People hate inflation, they hate it very much
In addition, Powell made it clear that the FOMCs responsibility is to set nominal interest rates, not actual interest rates. The decline in inflation may be only part of the reason for the interest rate cut, clearly refuting the recent views of New York Fed William, who previously pointed out that nominal interest rates need to be adjusted downwards. , to keep the real interest rate unchanged.
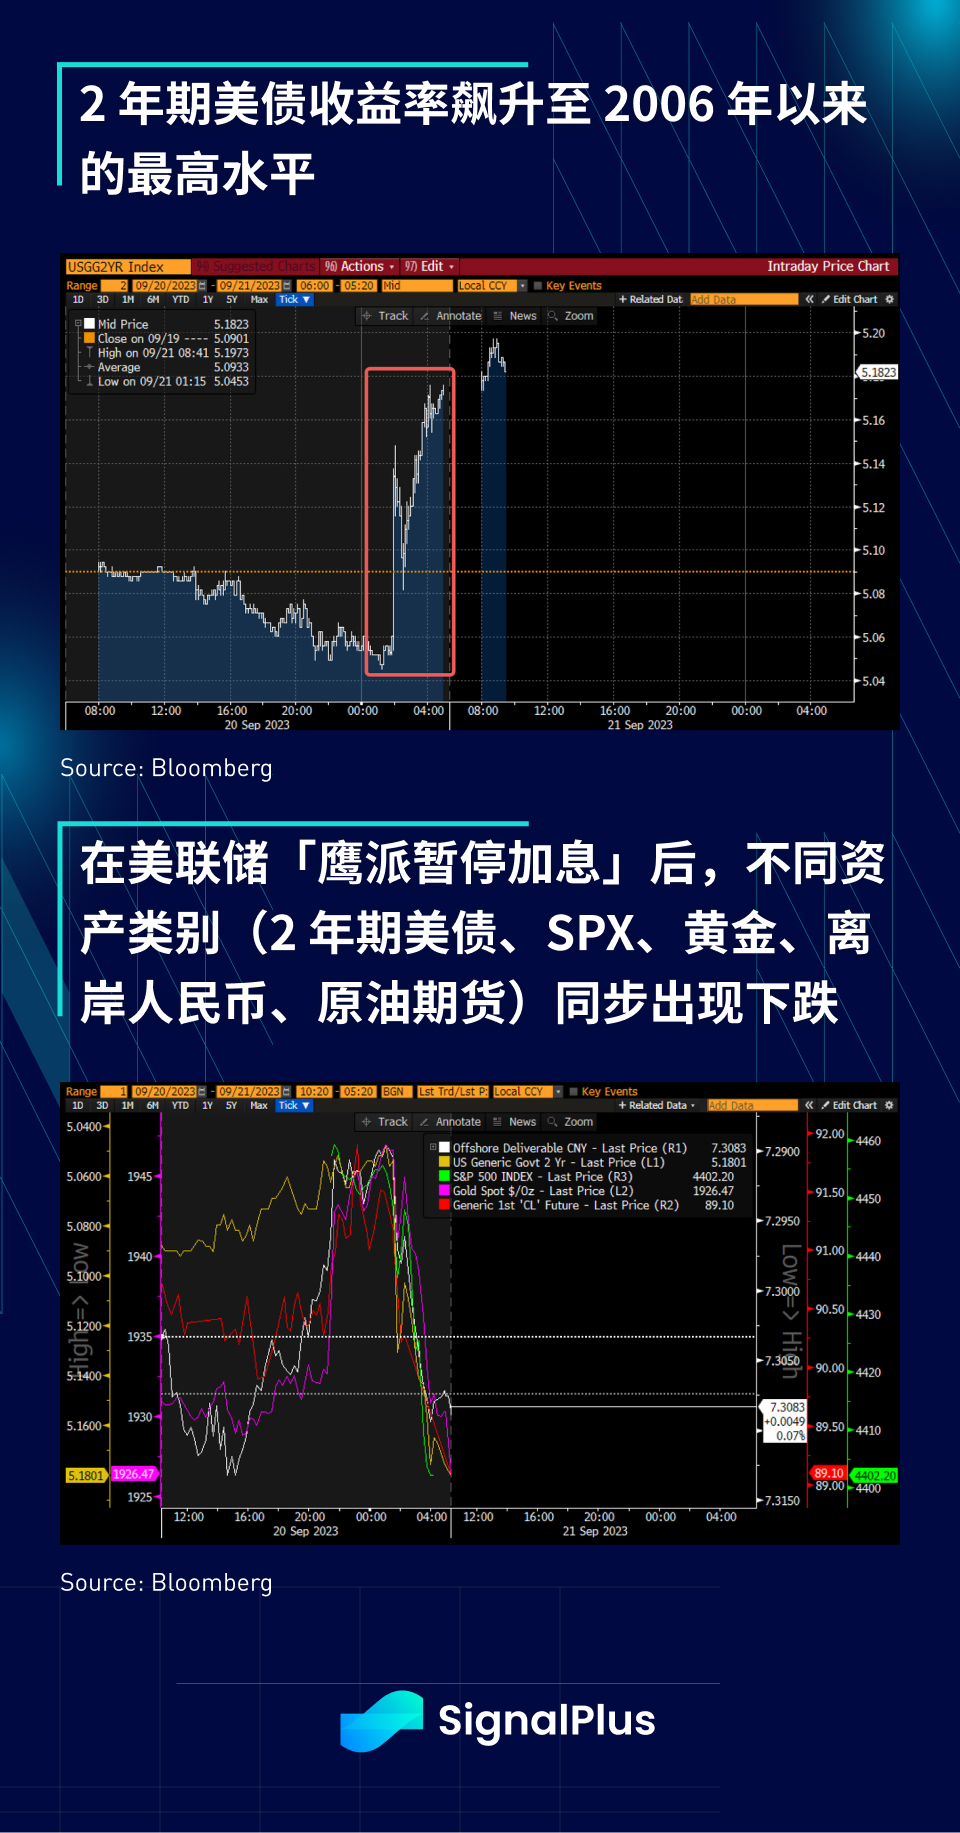
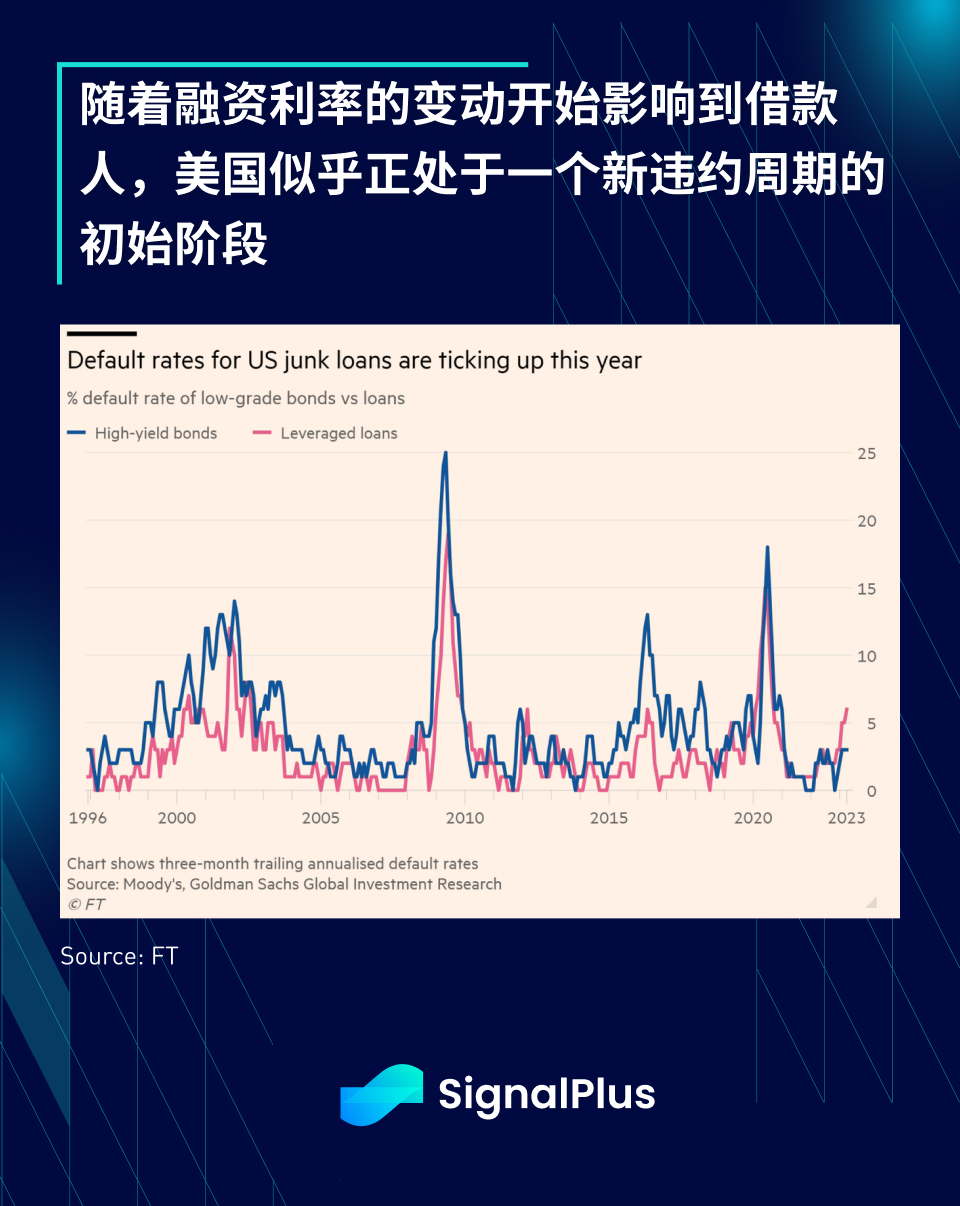
Looking ahead, while the Fed remains data-dependent, they are very direct about their intention to keep interest rates higher for longer, and their concerns and concerns about inflation are clearly more firm than the markets forecasts based on an economic slowdown, so despite growth An upgrade in assessments is theoretically good for risk assets, but the issue is always timing, with risk markets likely to struggle in the short term as low-rate stimulus fades, and the move in bond yields is also worrying, with 2-year yields approaching It is about a 14-year high of 5.20%, and the default rate has finally begun to rise this year; we expect that asset prices are still more likely to decline in the short term, but it is recommended that we still pay close attention to bond yields to prevent the situation in fixed income from getting out of control.
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption information. If you want to receive our updates immediately, please follow our Twitter account @SignalPlus_Web 3, or join our WeChat group (add assistant WeChat: SignalPlus 123), Telegram group and Discord community to communicate and interact with more friends .
SignalPlus Official Website:https://www.signalplus.com





