


SignalPlus Macro Research Report (20230726): Market calm, awaiting FOMC meeting news


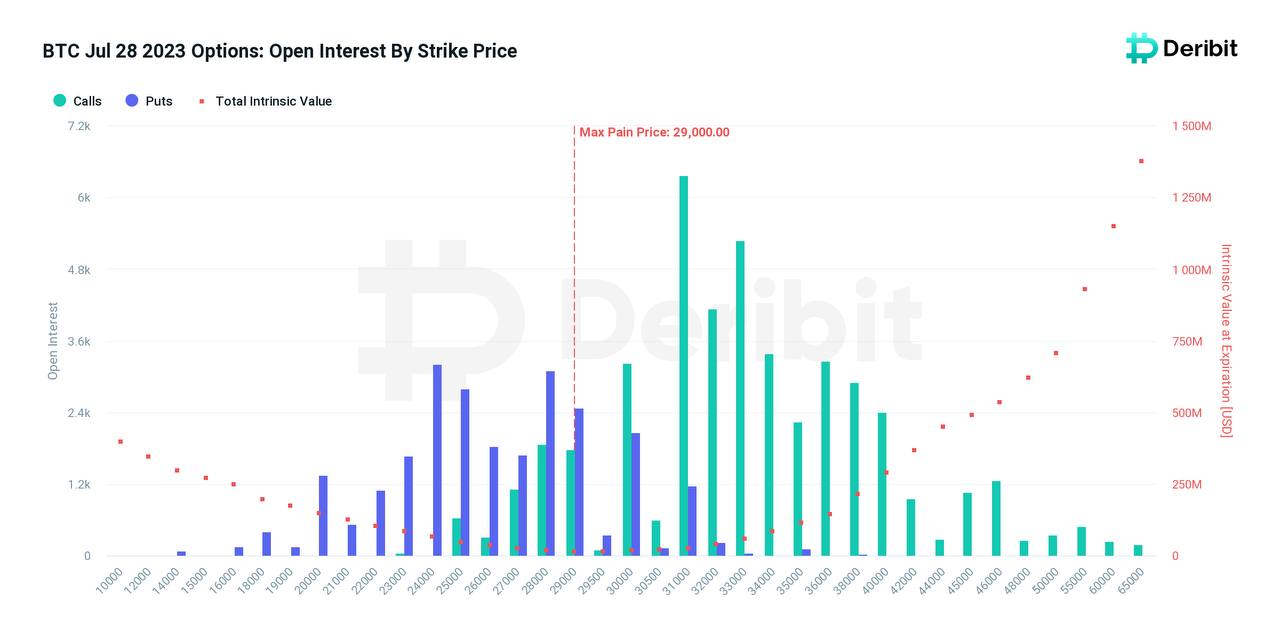
This Friday's maximum pain point for BTC options is 29000, accurately predicting the price drop in the middle of the month.
The volatility indexes DVOL for both BTC and ETH have hit historic lows, falling below 40, currently at 37 and 36 respectively.
In history, when the volatility reaches a new low, the price usually experiences significant fluctuations within a month.
The expected 25 bps rate hike from the FOMC meeting on the 27th is already priced in. The expectation for a soft landing of the US economy is getting stronger, which also means that once a recession sets in, US stocks will fall harder, and it will also negatively impact liquidity in the cryptocurrency market. As long as US stocks remain strong, the outlook for BTC prices in the near term is relatively optimistic and will not experience a sharp decline. However, if US stocks crash, BTC will certainly undergo a new round of price adjustment. It is recommended for traders to effectively use options to leverage in the low volatility range, to control risks and increase risk exposure wisely.

US Philadelphia Fed Non-Manufacturing Index Breaks Three-Month Decline, rebounding 18 points to the positive zone in July, with almost all components performing strongly, including a significant rebound of 26.3 points in the employment component, as well as decent growth in average workweek, profits, and new orders. The only concern in the positive data is the rise in prices paid, echoing the stubborn inflation seen in Monday's PMI data.
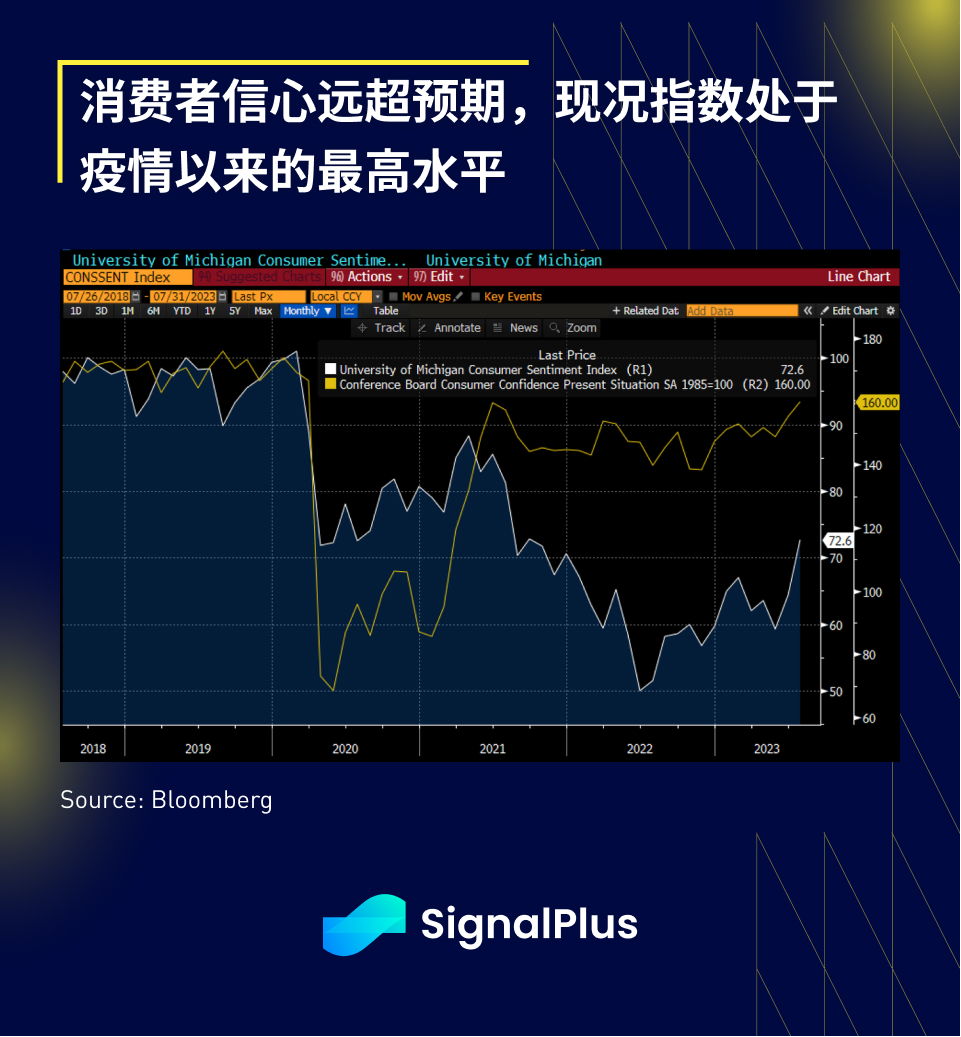
Consumer Confidence Index Soars 6.9 Points to 117.7 in July, well above expectations. It is worth noting that the Present Situation Index also skyrocketed to 160, reaching its highest level since the pandemic, and the rest of the consumer survey also showed broad-based strong growth.
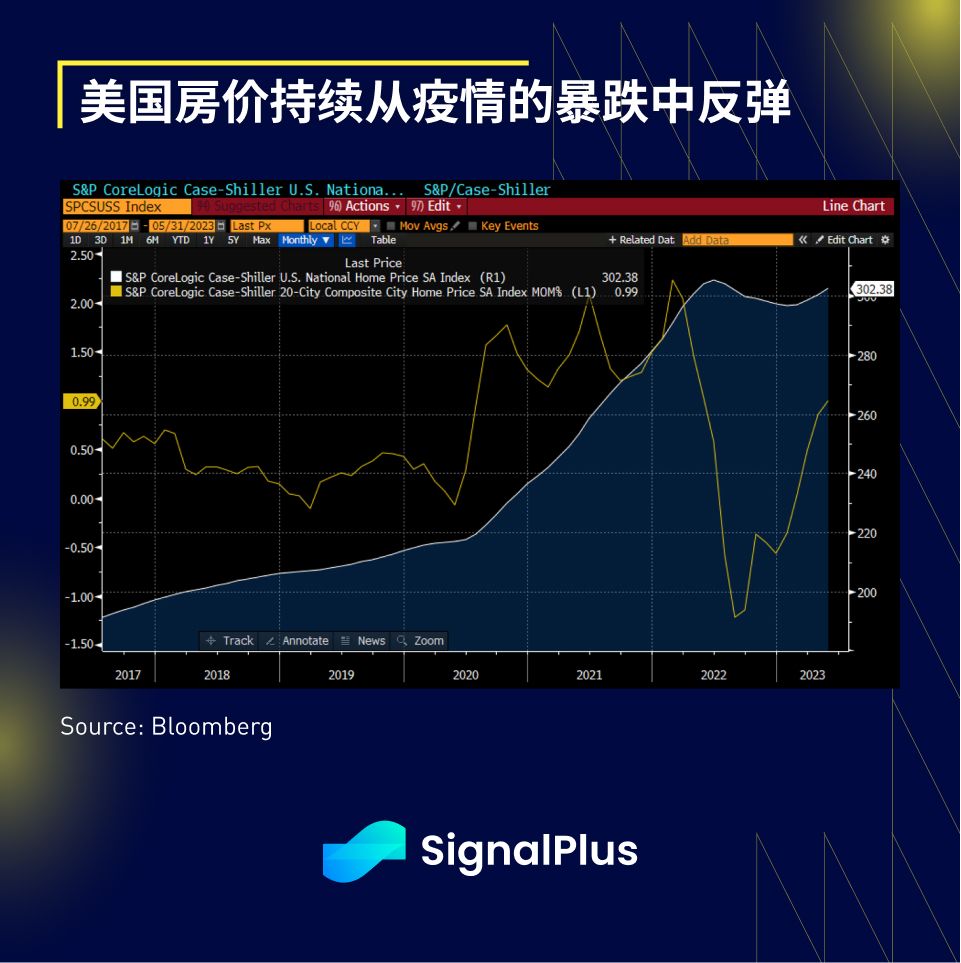
Similarly, US housing prices have continued to rebound significantly from the pandemic's plunge, rising 1% on a month-on-month basis, with overall house prices now only 1% below the historical peak in the summer of 2022.
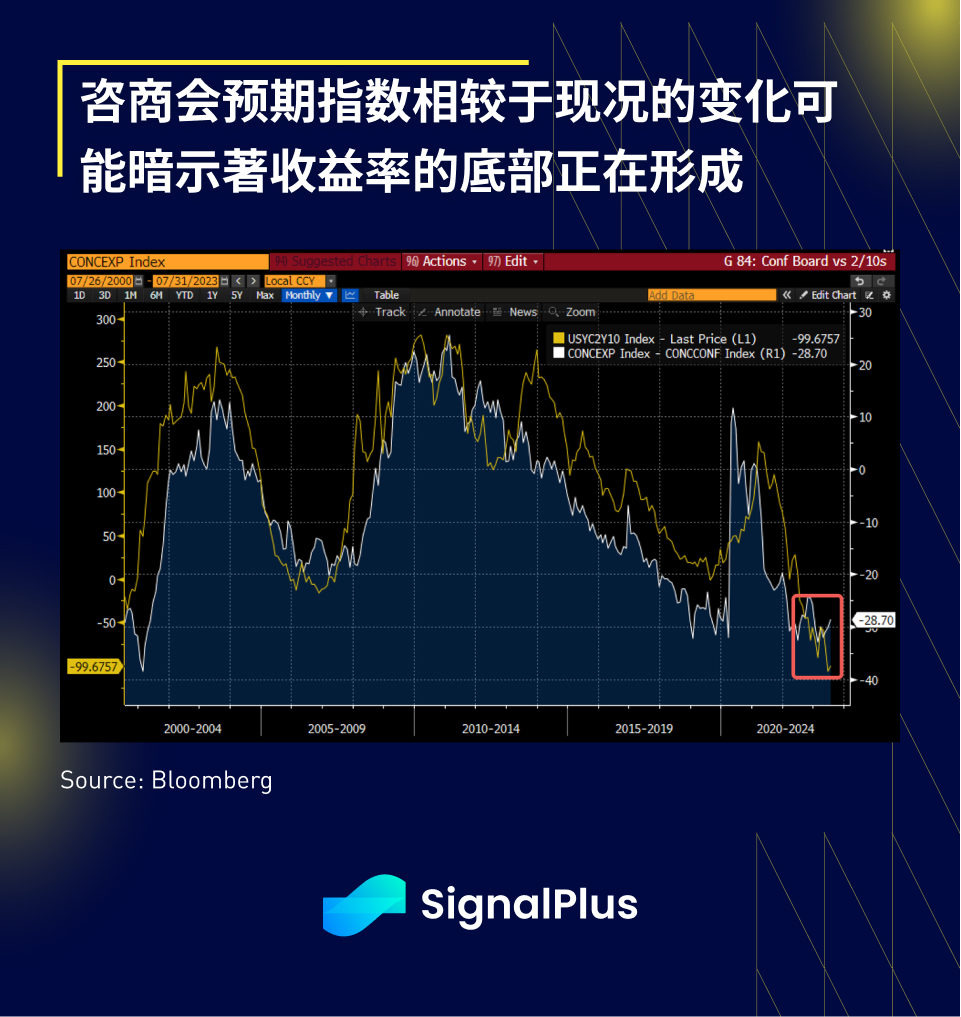
In addition, the business council's data shows that the job market remains relatively tight, and the expectations index's relative improvement to the current situation historically correlates with the yield curve, indicating that the bottom of the yield curve may be forming at the current level.
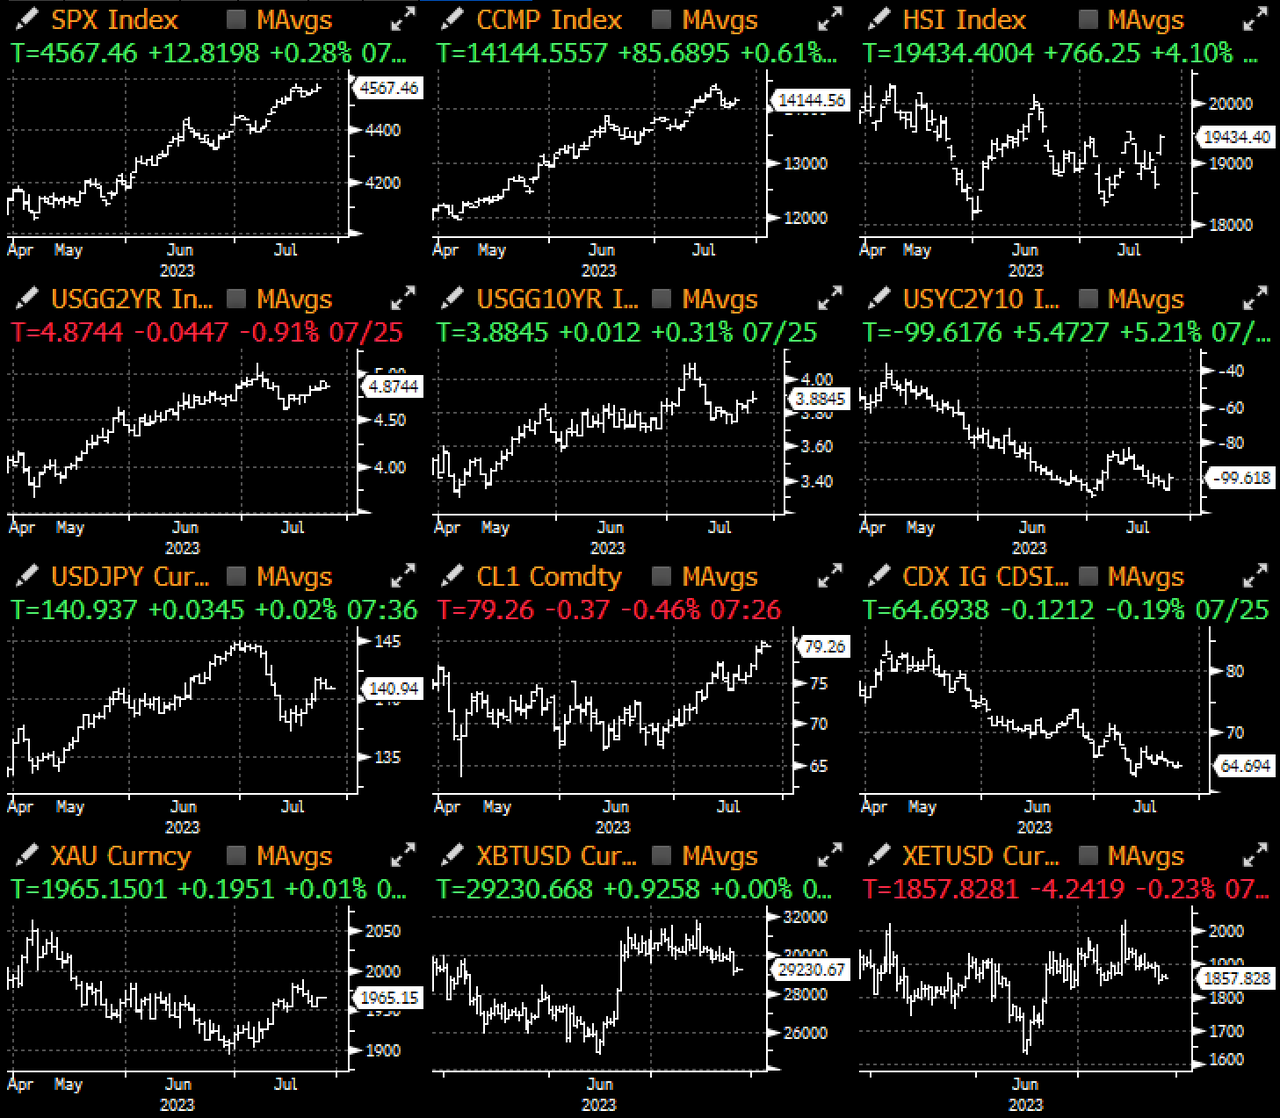
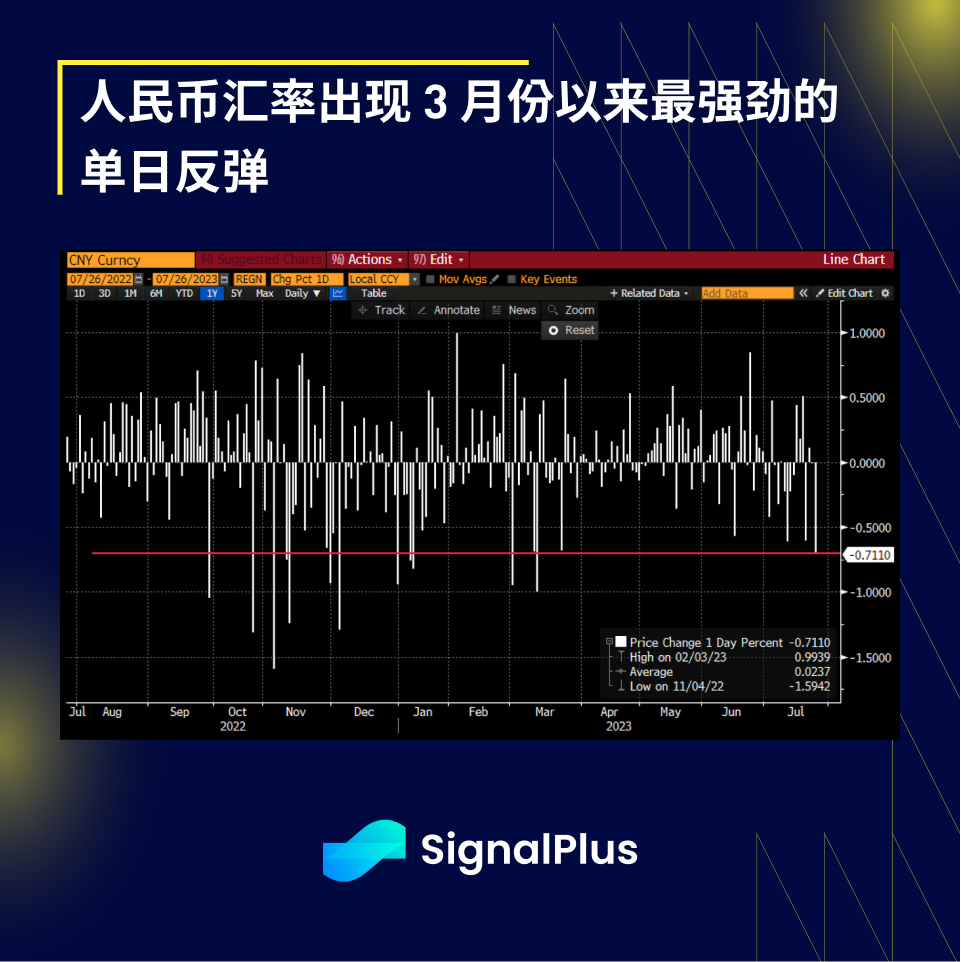
On other fronts, crude oil and copper futures prices have risen further, along with expectations of stimulus measures, leading to short-selling in Chinese-related stocks (Hang Seng Index + 4%, Shanghai Real Estate Index + 6%, Nasdaq Golden Dragon + 5%), resulting in the renminbi's strongest daily rebound since March.
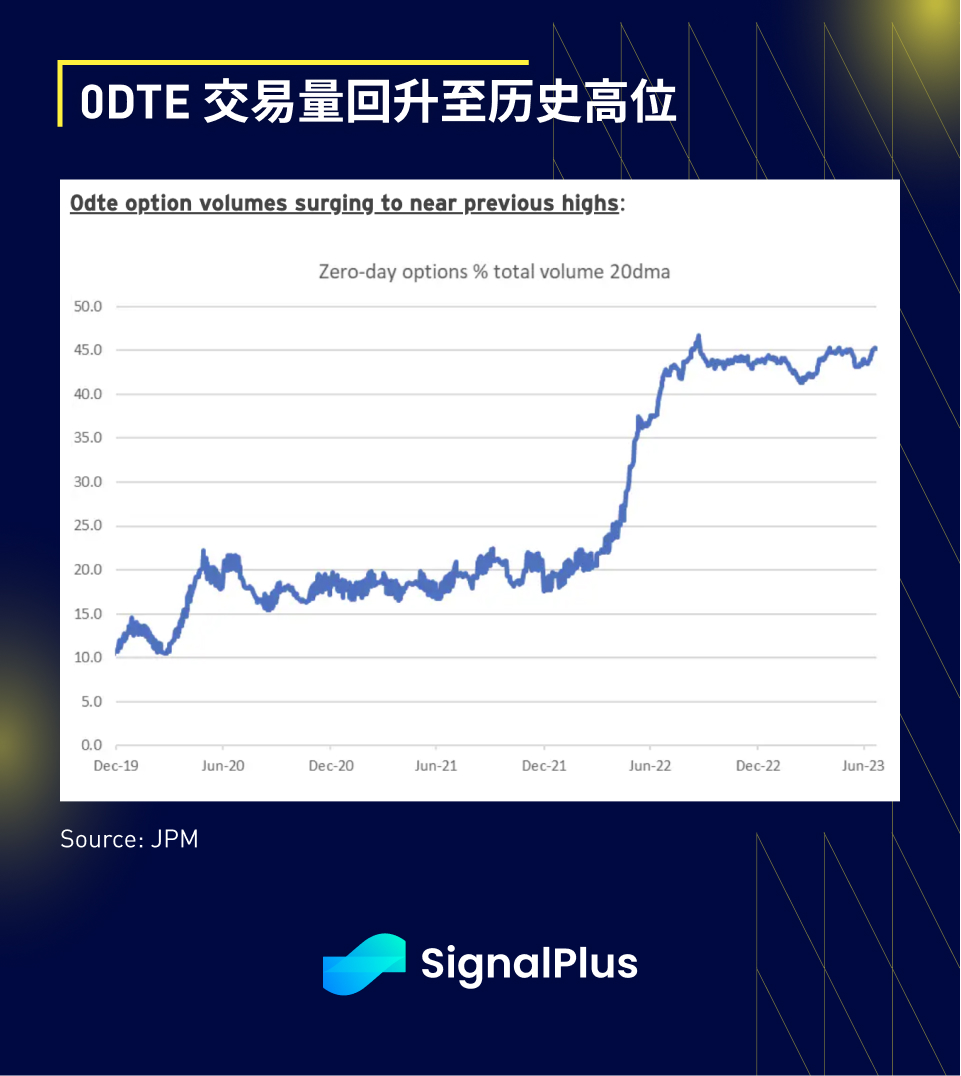
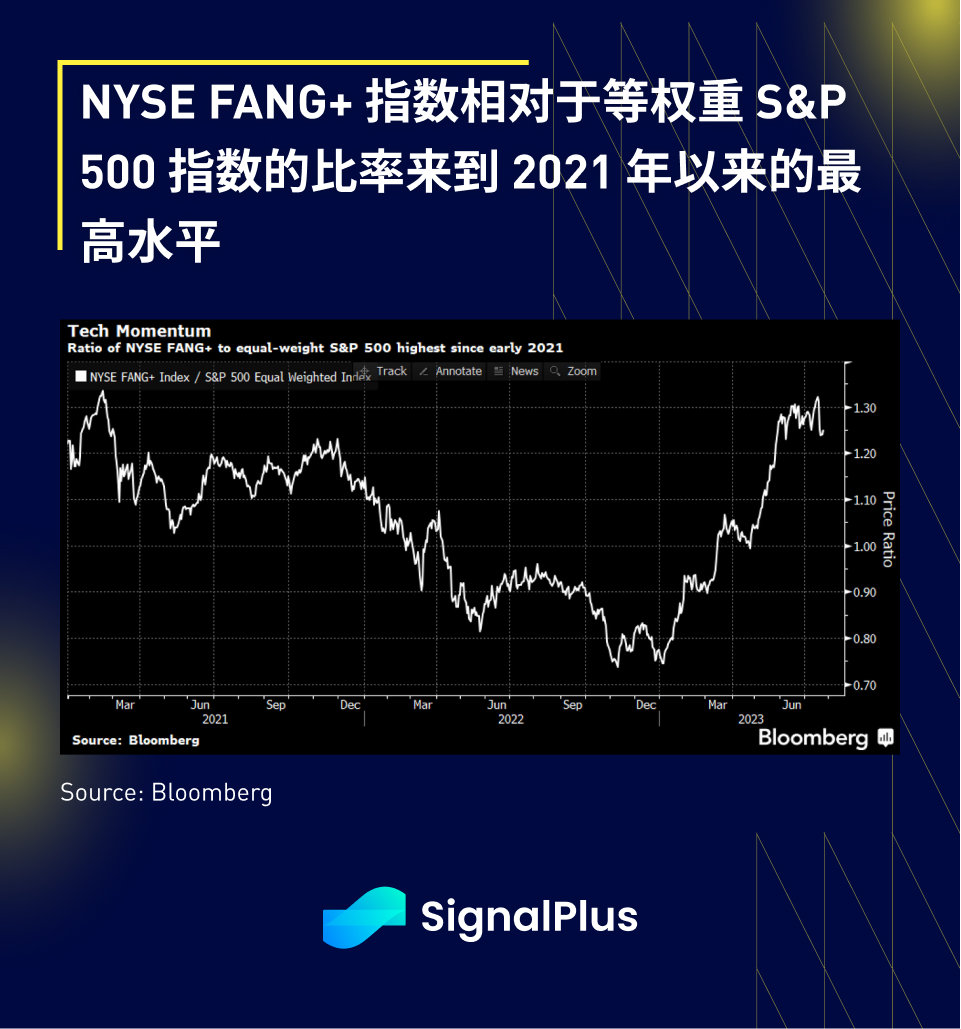
With the market sentiment becoming more optimistic everywhere, the trading volume of the 0-day expiration options for SPX has quietly rebounded to a historical high, and the ratio of FANG+ stocks to the equal-weighted S&P 500 index has also reached the highest level since 2021. It is indeed a good time.
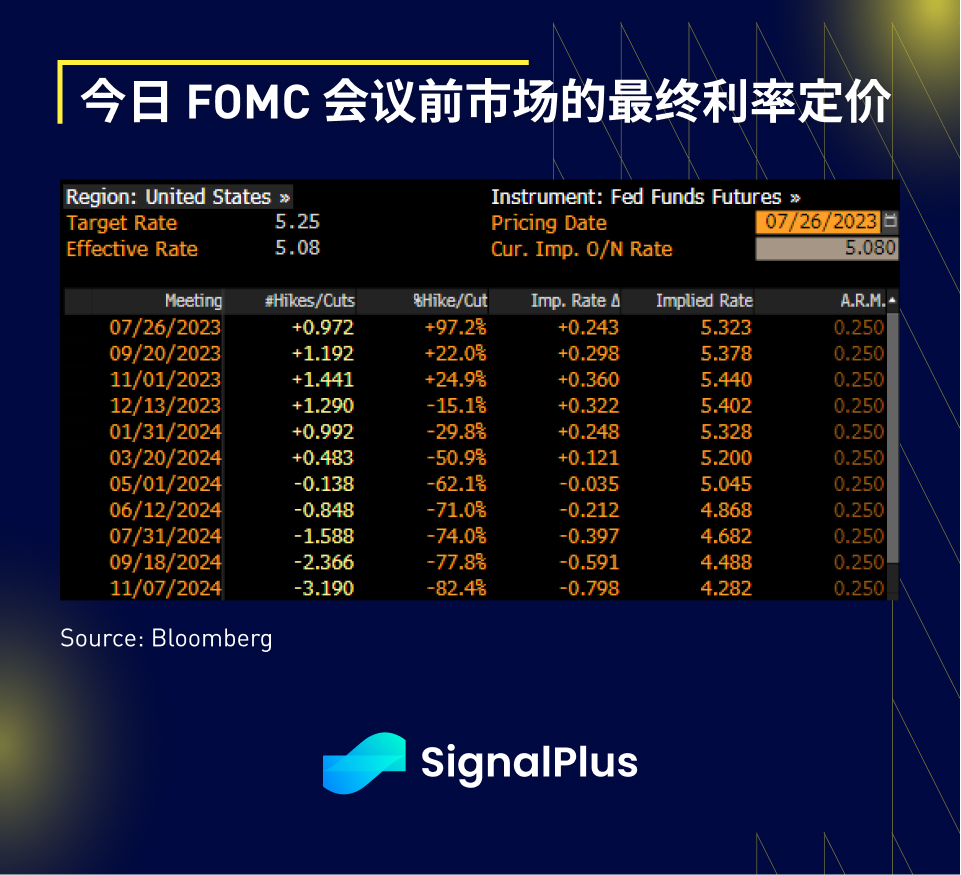
The current corporate earnings results have been mixed compared to high market expectations, but most of them still show growth (Alphabet exceeded expectations, while Microsoft was disappointing). The market will welcome the FOMC meeting tonight, and the current market expectations are generally dovish, expecting a "rate hike followed by a pause" message, which will validate the market's expectation of a rate cut in 2024. Traders are also expecting Powell to acknowledge the recent soft CPI and PCE data, which will have a positive impact on the stock market, and phrases like "inflation remains high" and "waiting for more information accumulation" may be removed or replaced with more dovish wording. Finally, regarding the Q&A session, we expect Powell to reiterate the standard discourse of remaining vigilant about inflation, but he may also guide the market to further move away from a rate hike in September (currently about 25% probability) and downplay the importance of the Fed's dot plot, being more dovish than market expectations. However, if he continues to emphasize the strong job market, resilience of consumer activity, or mentions the accommodative financial situation, it may be seen as more hawkish than market expectations.
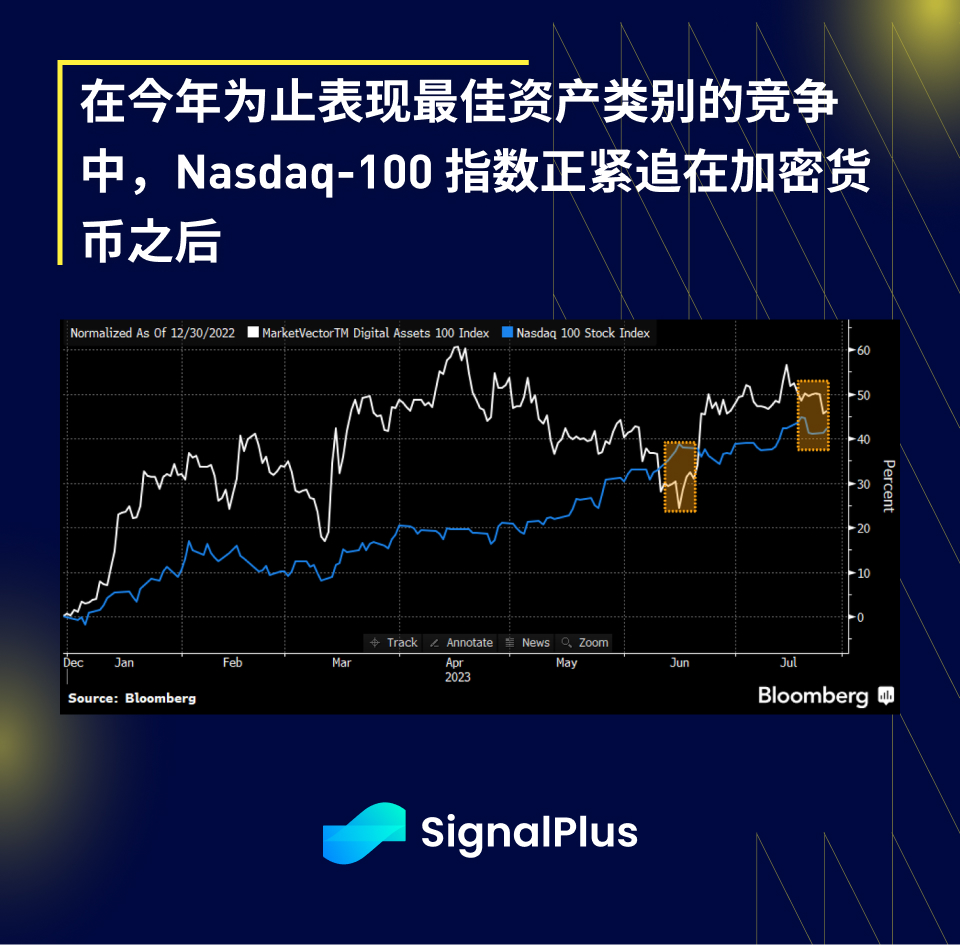
In terms of cryptocurrencies, there is still a lack of new catalysts to push prices higher, and a large amount of bad news has been largely digested. In addition, with the Federal Reserve's interest rate hiking cycle coming to an end, the downside potential is relatively limited. Basically, it is repeating the price trend of the past week. However, the recent decline has endangered the leading position of cryptocurrencies in this year's gains, as Nasdaq-100 is catching up due to the surge in Nvidia and other tech giants.
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encrypted information. If you want to receive our updates instantly, please follow our Twitter account @SignalPlus_Web 3, or join our WeChat group (add assistant's WeChat: chillywzq), Telegram group, and Discord community to interact and communicate with more friends.
SignalPlus Official Website: https://www.signalplus.com





