


SignalPlus Macro Research Report (20230713): Waiting for the Surrender of the "Bear Market"


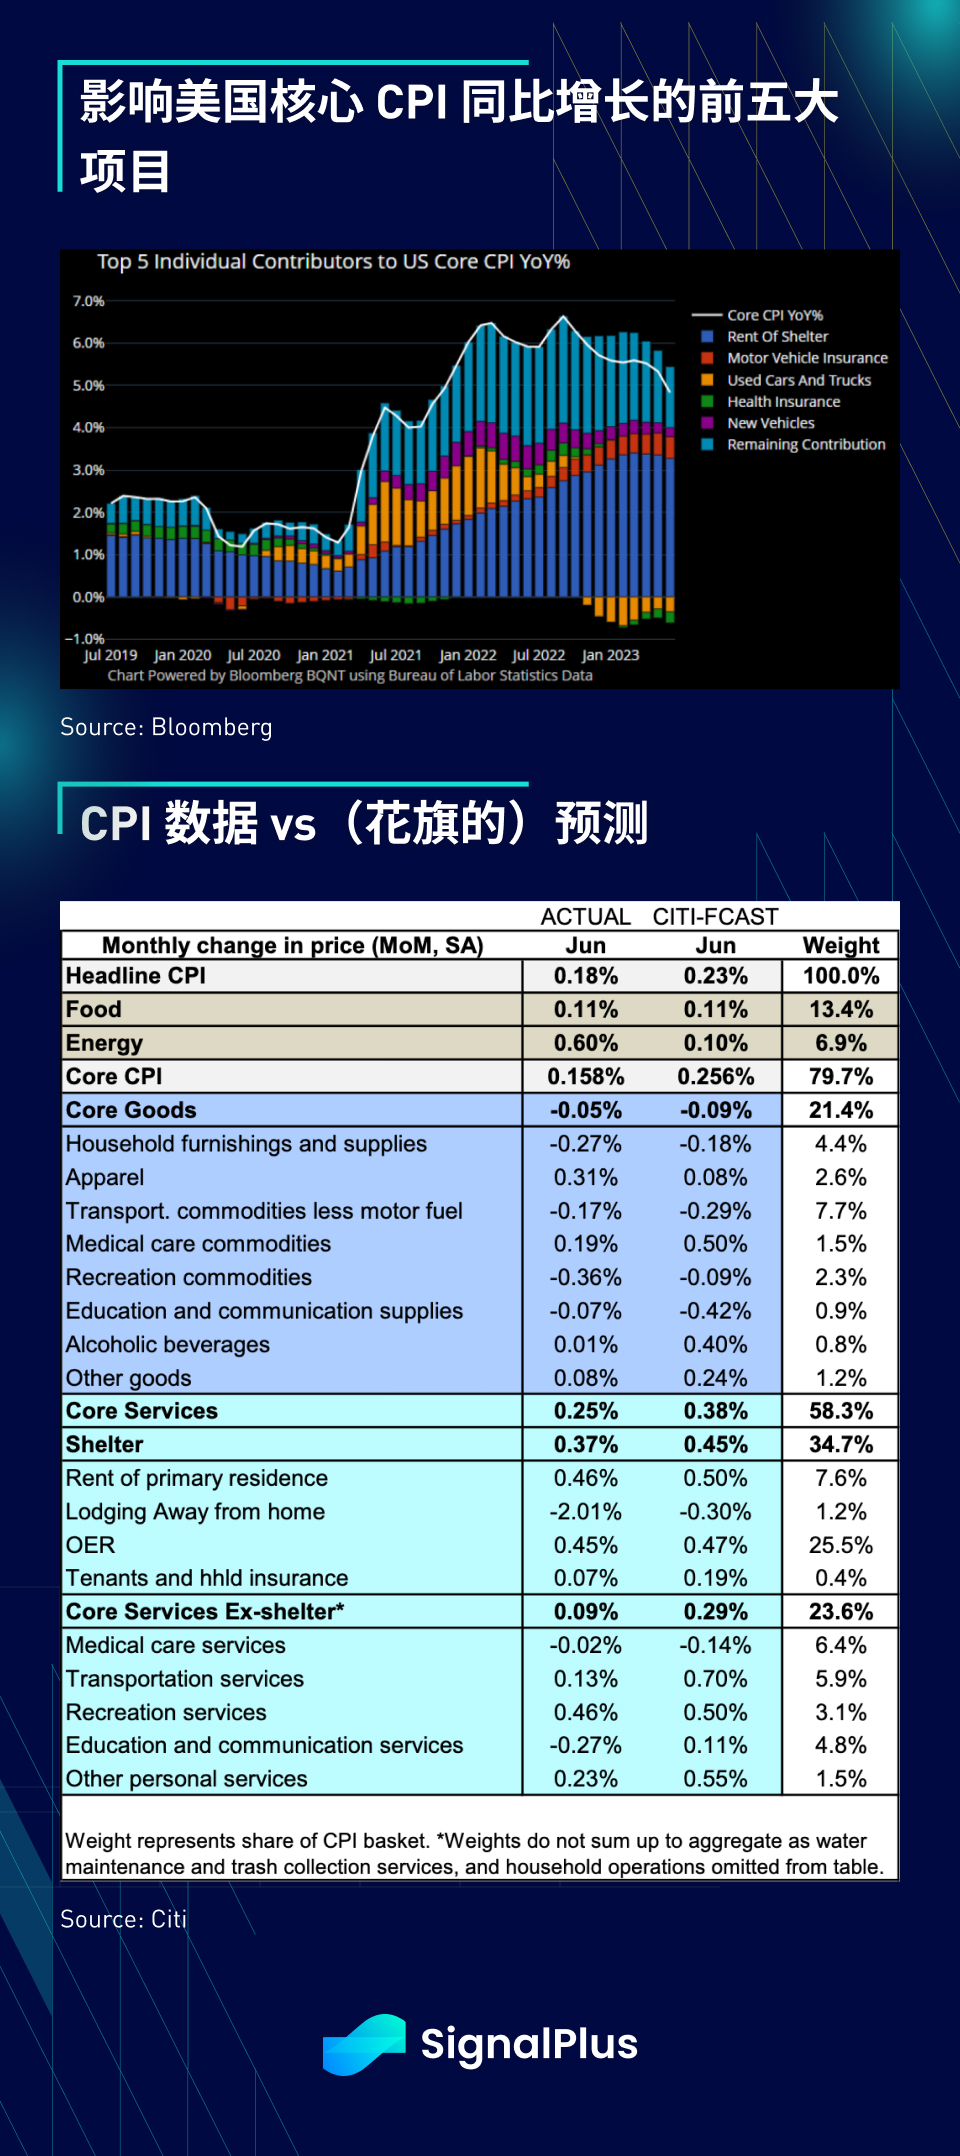
June core CPI increased by 0.157% MoM, lower than market expectations of 0.3%, and YoY growth decreased from 5.3% in May to 4.8%, core commodity prices rose by 0.1% MoM, used car prices fell by 0.5%, and housing prices continued to slow down, with both primary rents and equivalent rents lower than expected; the unexpected weakness in core CPI was mainly in non-housing services, which only increased by 0.06% MoM, while airfare prices dropped significantly by 8.1%.
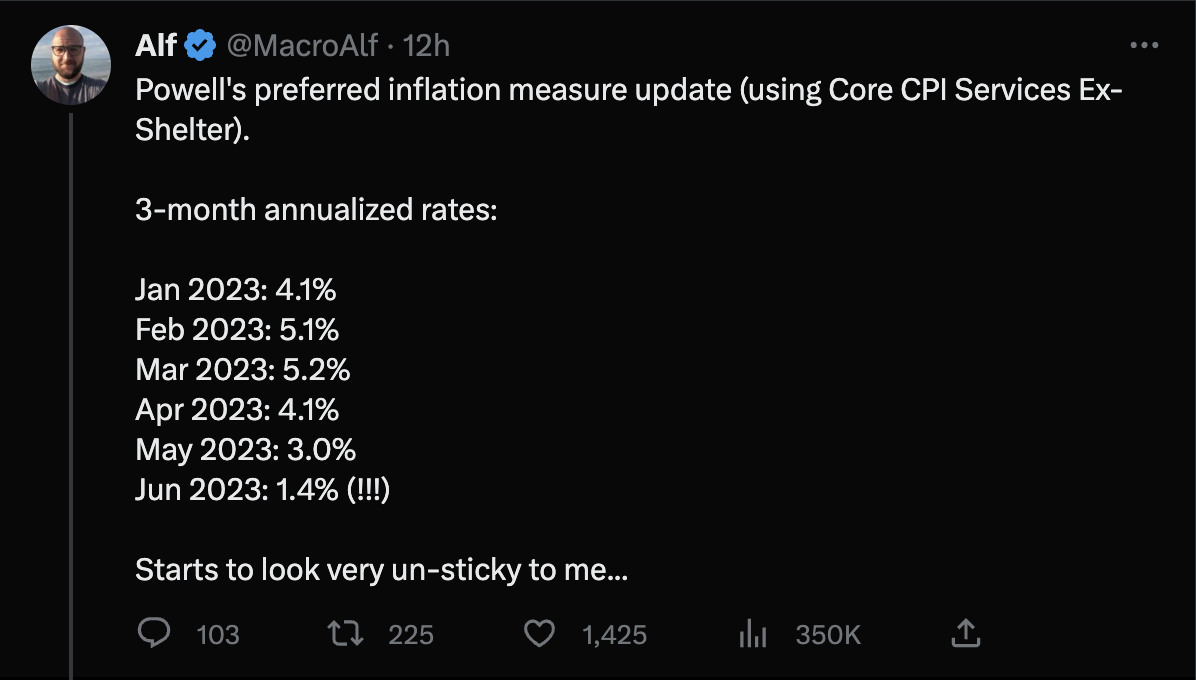
Even though market expectations have been revised downwards, the performance of CPI is still undoubtedly weak, causing Powell's preferred PCE index to sharply drop from 5.1% in February 2023 to 1.4% in June.
Source: Twitter
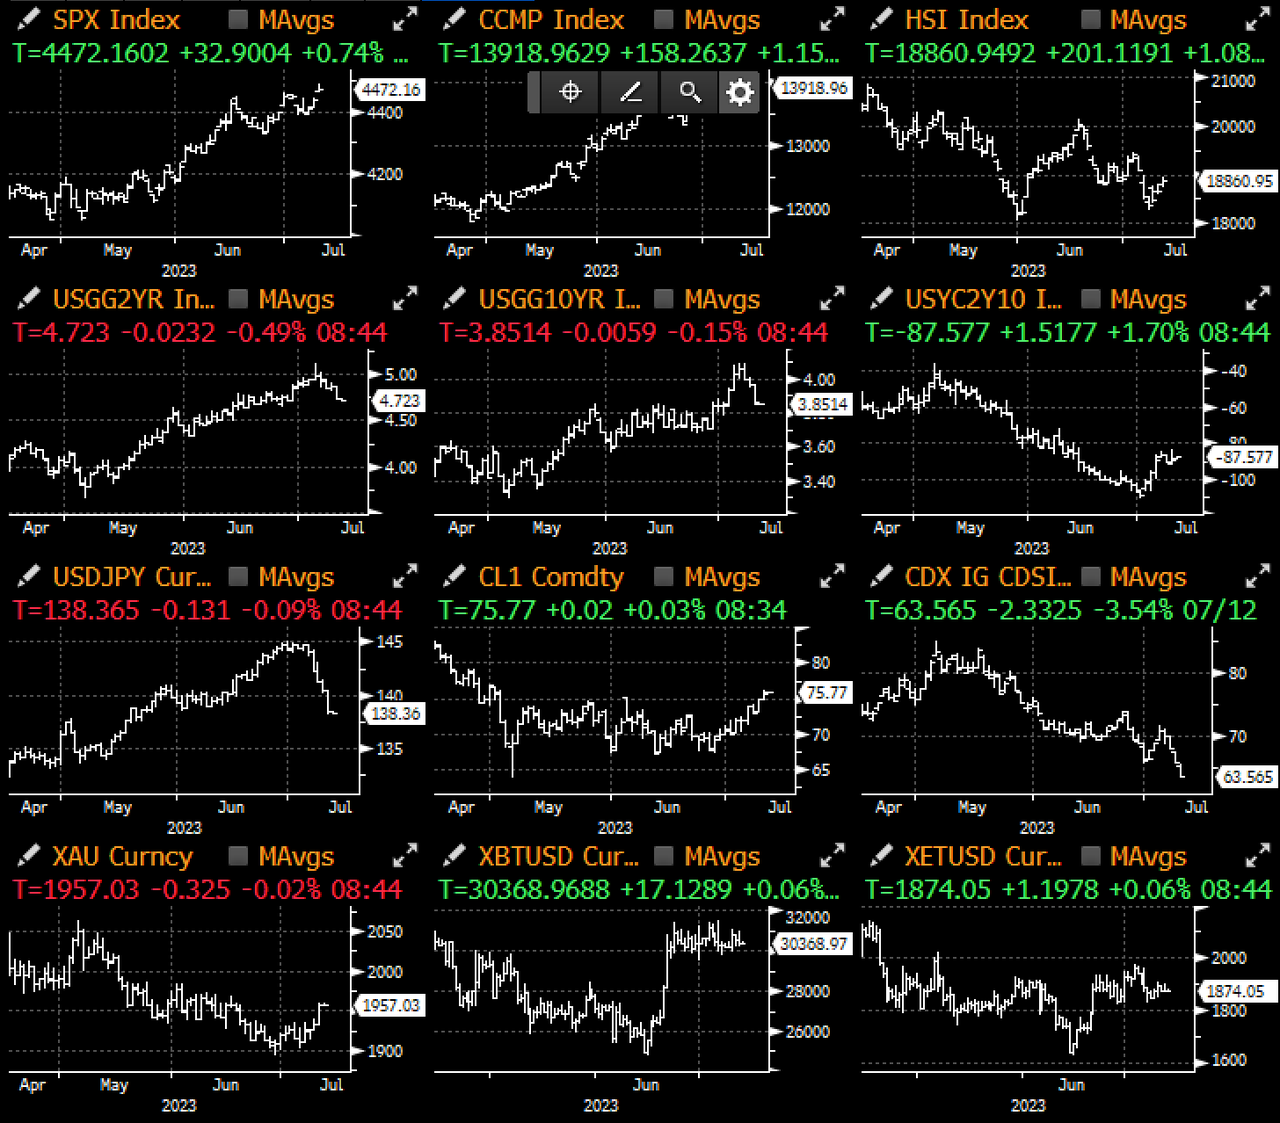
The risk market certainly welcomes the weak CPI, with bond yields falling 15 basis points that day, while the SPX rose 0.75% again, driven by technology stocks and rate-sensitive sectors, demonstrating a broad rebound in risk sentiment. Wall Street broker reports pointed out that after the data was released, investors showed strong interest in establishing long fixed-income positions (with lower interest rates) because as indicated by other indicators (such as rapid deceleration in M2 money growth and changes in the Case-Shiller house price index), the market expects CPI to continue to decline.
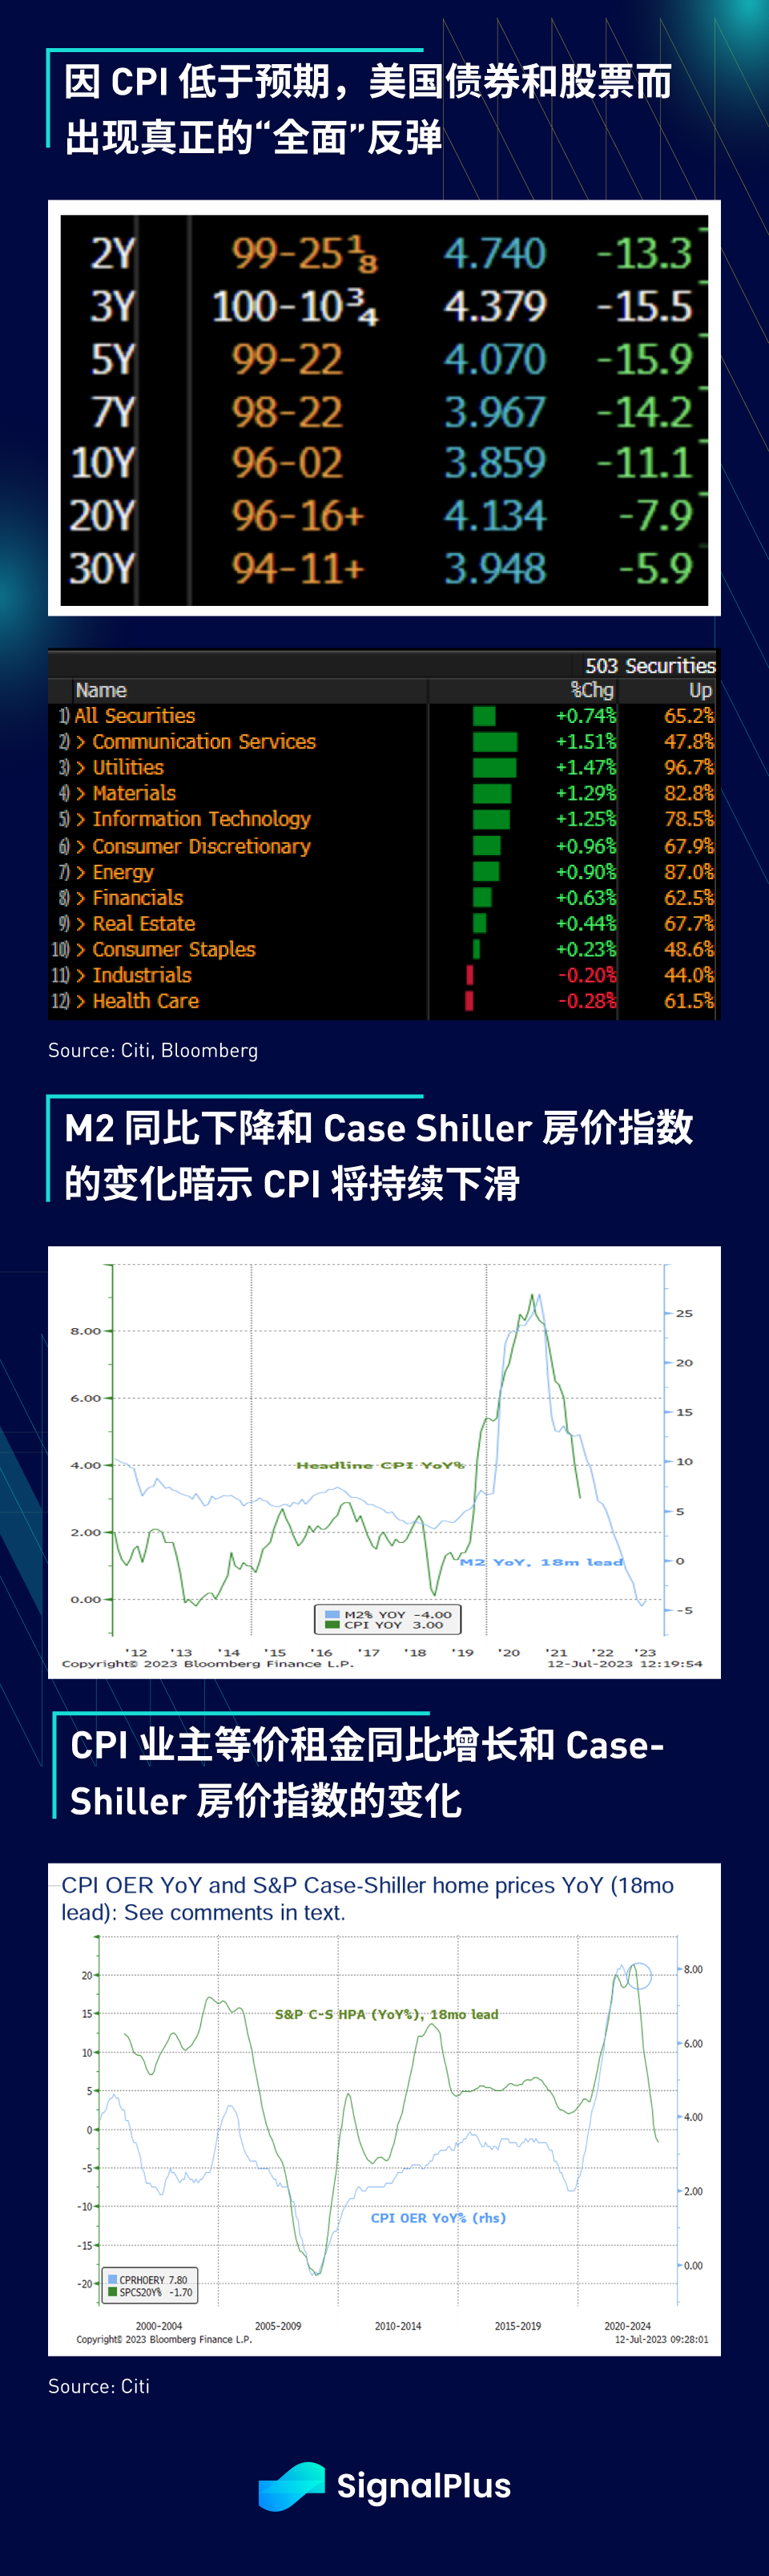
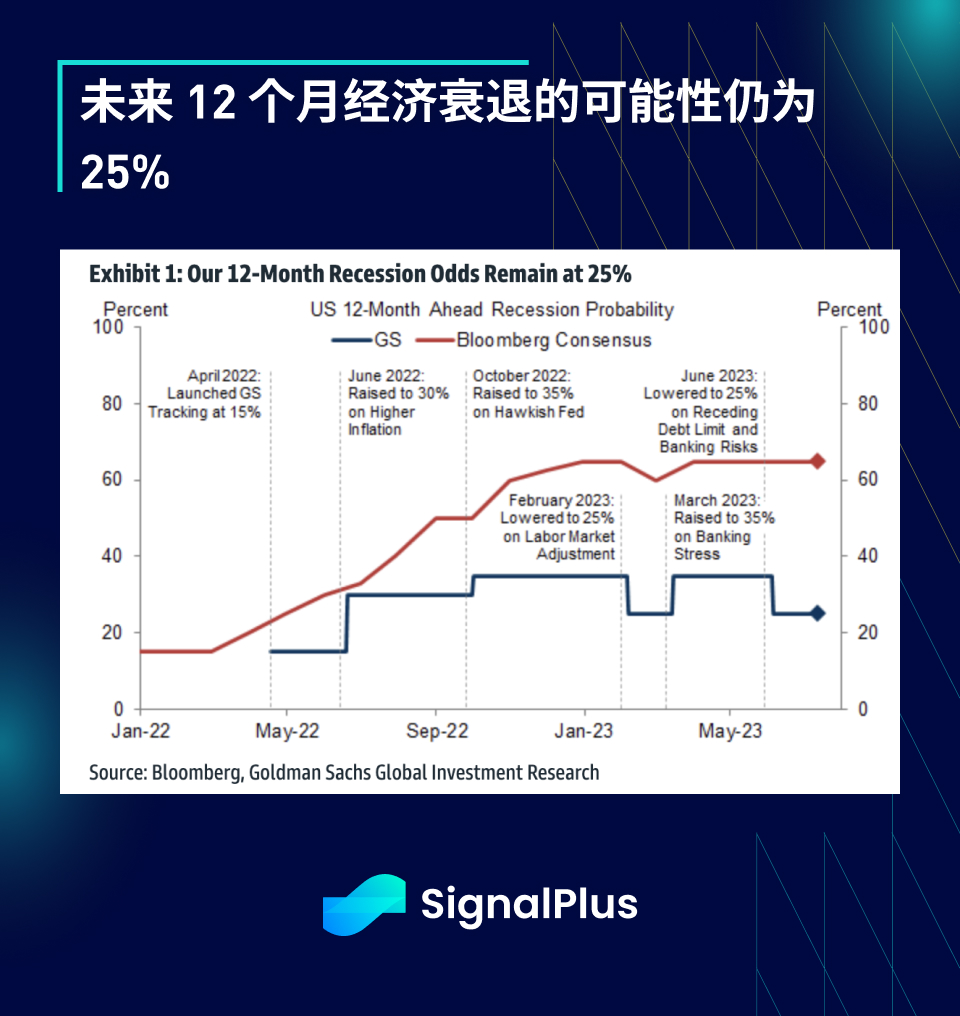
Due to exceptionally strong employment data last month, combined with a much larger-than-expected decline in CPI, the possibility of a US economic recession should continue to decline, and better-than-expected US corporate earnings may be the final straw that will make the bear market surrender (again).
It was not long ago that there was a large-scale regional banking crisis, yet the SPX index reached a high of around 4,500 points with terminal interest rates approaching 5.5%. Regardless of investors' inherent biases towards the Fed's rescue methods and economic philosophy, the current situation would not be possible without the Fed's efforts.
The focus in the coming weeks will be on corporate earnings, which will kick off this week with banks and financials, with the market focusing on adjustments to loan loss provisions and forward guidance on how rising interest rates and post-SVB regulatory costs will impact their investment portfolios.
Nevertheless, the current situation seems to have paved the way for a "comprehensive and clear" rebound, and the stock market is prone to short squeezes. However, some investors liken the current situation to the rebound in the late 1997-99 period, which was also in a similar Fed cycle, and there are clear similarities between today's AI investment narrative and the early internet boom of that time.
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption information. If you want to receive our updates instantly, please follow our Twitter account @SignalPlus_Web3, or join our WeChat group (add assistant WeChat: chillywzq), Telegram group, and Discord community to interact and communicate with more friends.
SignalPlus Official Website: https://www.signalplus.com/





