


SignalPlus Macro Research (20230710): Expectations of stock market correction increase, cryptocurrency market continuing to improve


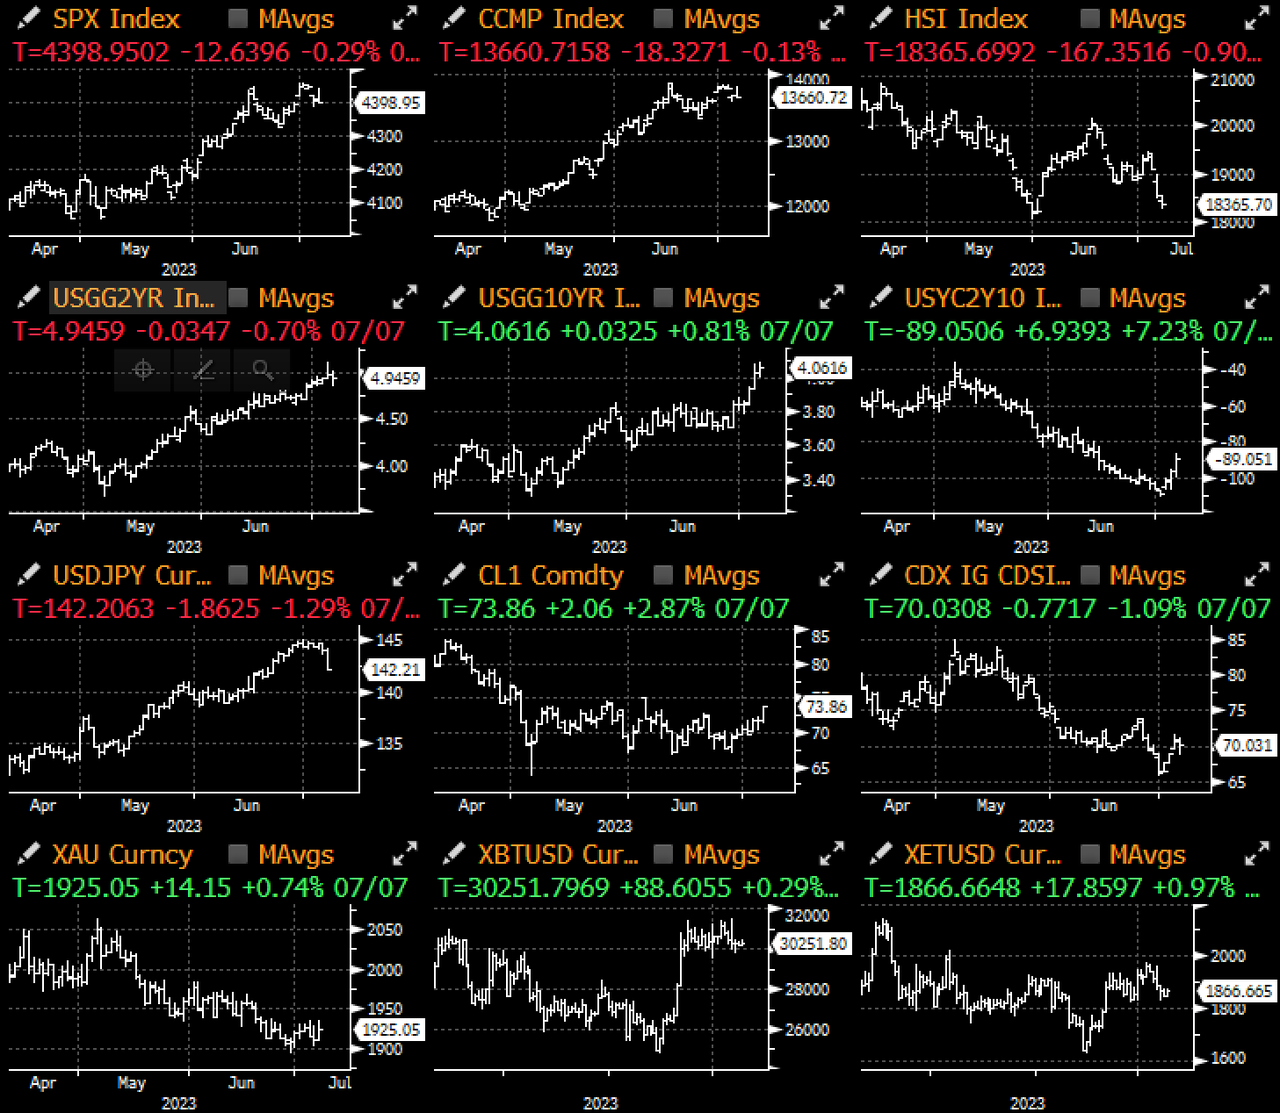
Friday's non-farm payrolls data fell short of expectations (209,000 vs an expected 230,000), ending the trend of exceeding expectations for 15 consecutive months, easing concerns in the struggling fixed income market. The 10-year yield immediately dropped 7 basis points after the data release. However, a deeper analysis of the data reveals that weekly work hours increased and average hourly wages grew by 0.4% for three consecutive times on a month-on-month basis, leading to a reversal in bond yields. The 2/10 spread increased by 7 basis points, marking the largest reversal since March at the closing of last week.
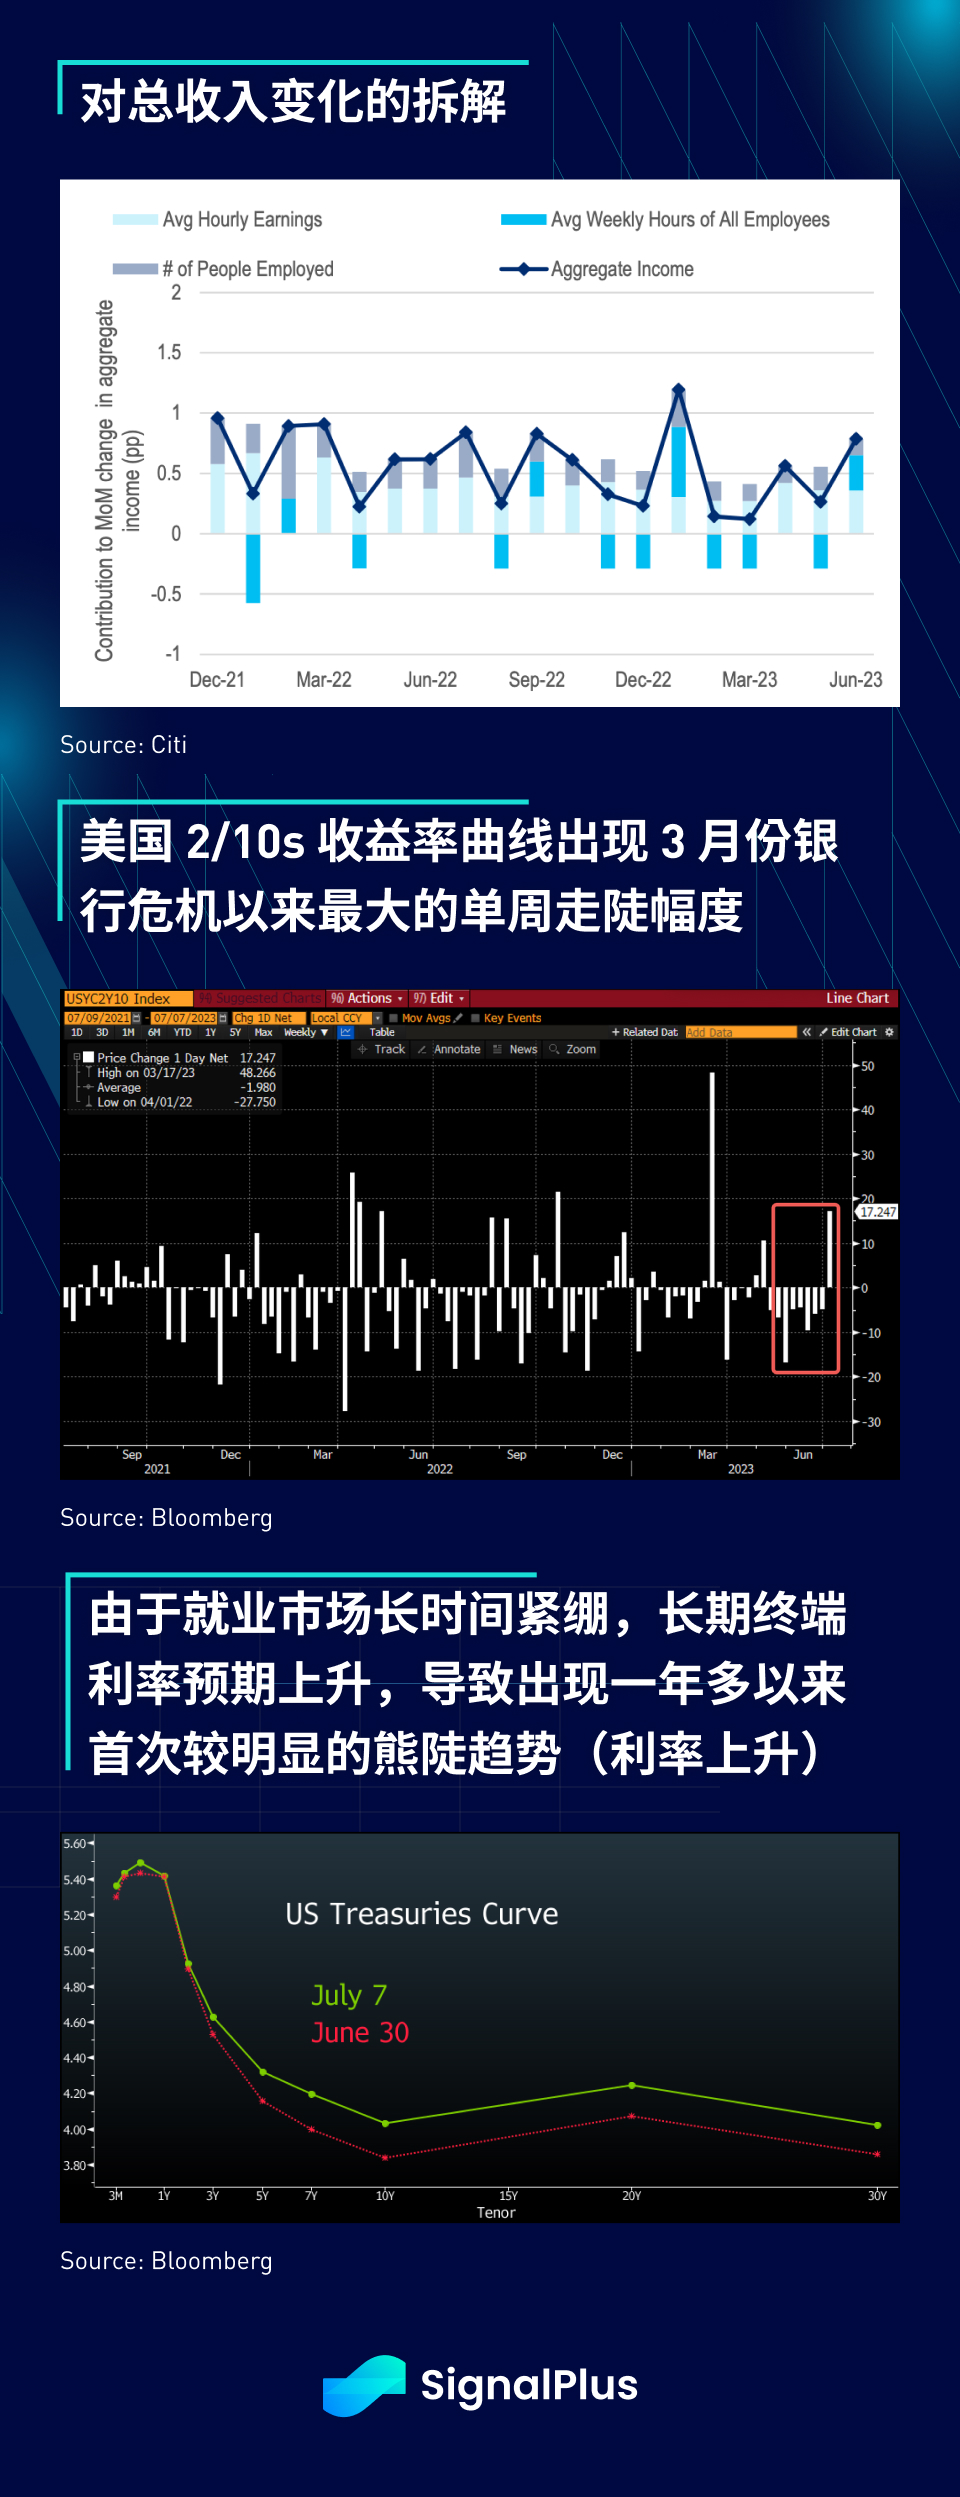
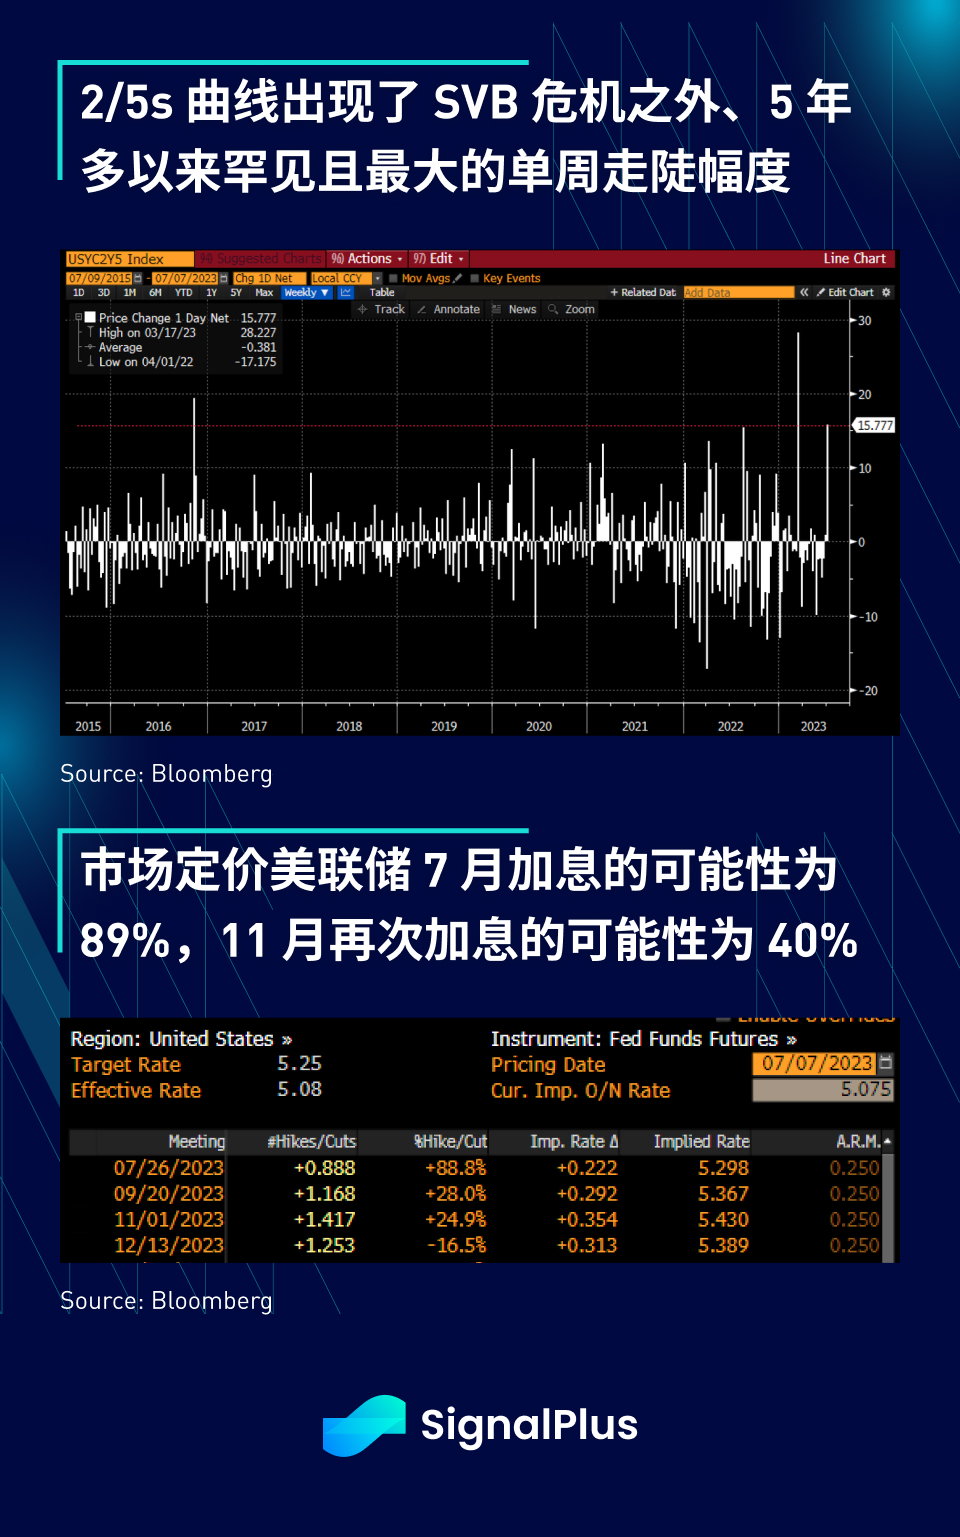
In addition, the yield curve experienced a sustained and significant steepening trend for the first time in over a year (i.e., long-term rates rising). The 2-year yield managed to hold the 5% resistance level, while the 10-year yield cleanly broke through the 4% level, closing at 4.06%. Moreover, the 2/5 spread saw a rare and significant steepening in a single week in 6 years (excluding the SVB crisis period), indicating the bond market's eagerness to eliminate any dovish sentiment resulting from the "skip rate hikes" in June. The probability of an interest rate hike in July stood at 89% at the end of last Friday, and the market expects a 40% probability of another rate hike before the November meeting.
In this week, the bond market will not have any breathing room. Important CPI data will be released on Wednesday, and traders will also have to deal with $90 billion of Treasury supply and $25 billion of US investment-grade corporate bond issuance this week. In addition, the ongoing TGA rebuild and quantitative tightening will continue to consume liquidity, and the pace of balance sheet reduction by the central bank in June is one of the fastest ever. Several Fed officials, including SF Fed's Daly, Cleveland Fed's Mester, Atlanta Fed's Bostic, Richmond Fed's Barkin, Minneapolis Fed's Kashkari, and Governor Chris Waller, will make speeches in the coming days. The market expects them to endorse the current rate trajectory.
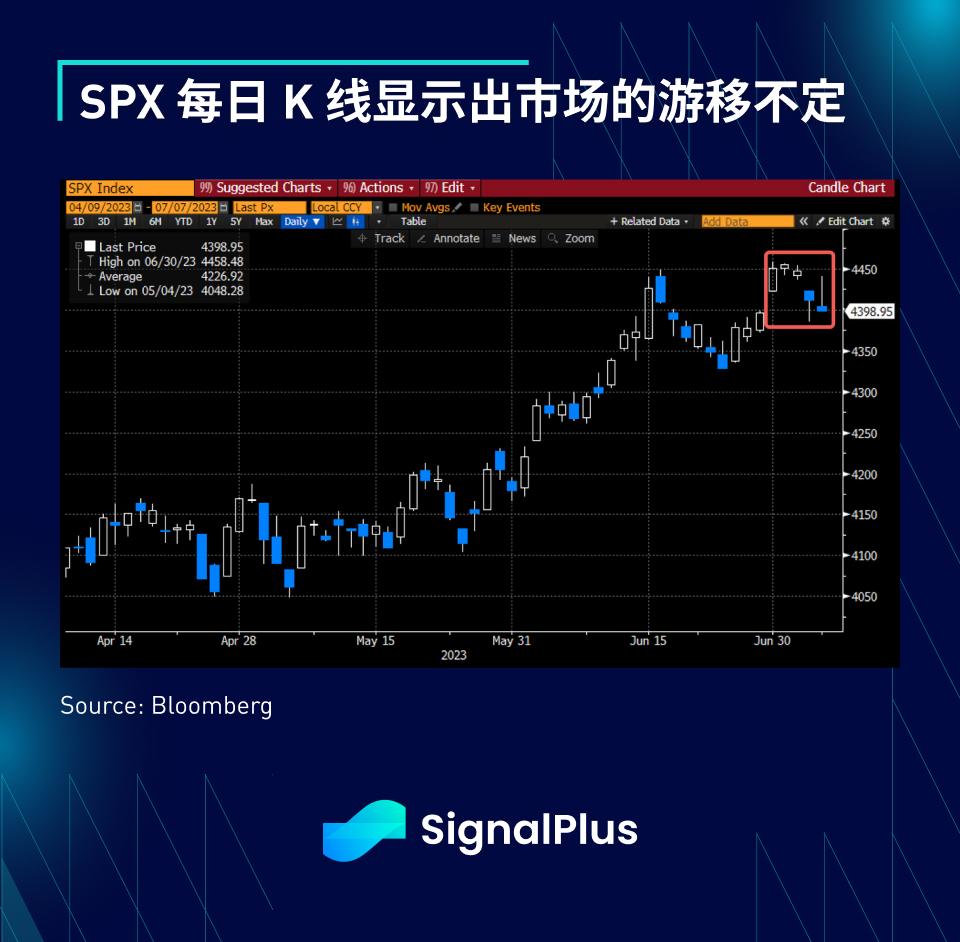
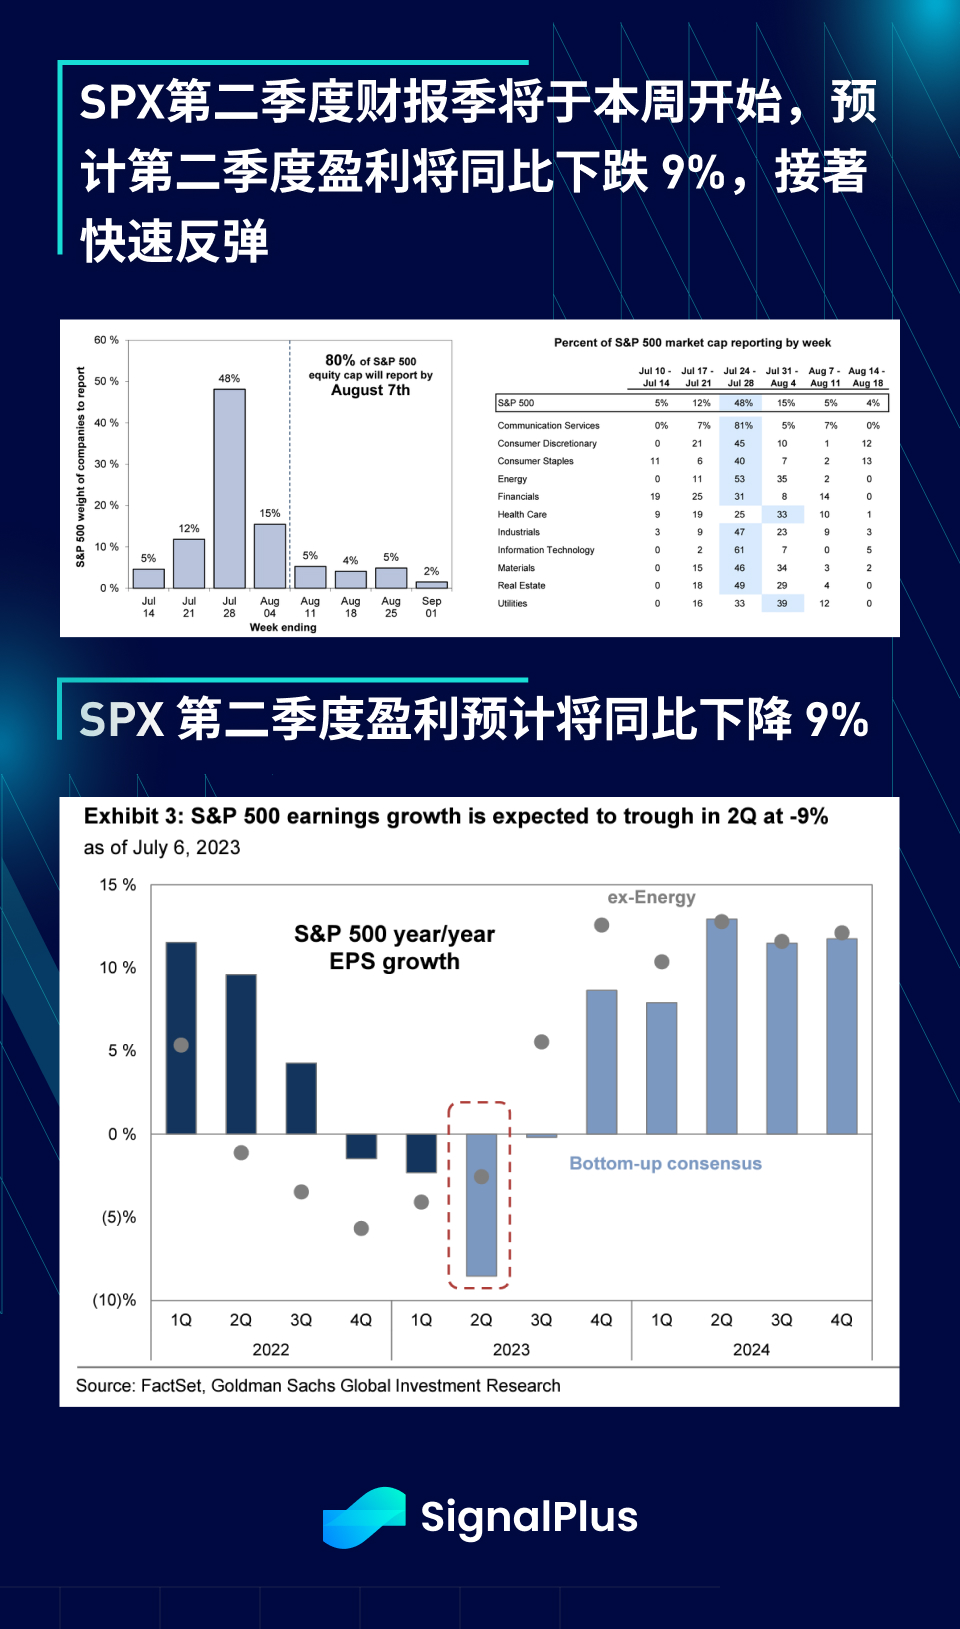
As for the stock market, it performed poorly in the closing hours, and there are potential downward trends in the daily chart. While the stock market is still contemplating how to deal with the rise in bond yields, the second-quarter earnings season will also kick off this week, starting with financial stocks. This week, the 28th, will be the busiest earnings week in terms of market capitalization, with 80% of SPX components expected to announce their results before August 7. Second-quarter earnings are expected to decline by 9% year-on-year, but a rapid improvement (+8%) is expected before the fourth quarter. It wouldn't be surprising to see some performances that exceed expectations, especially considering the recent strong economic momentum.
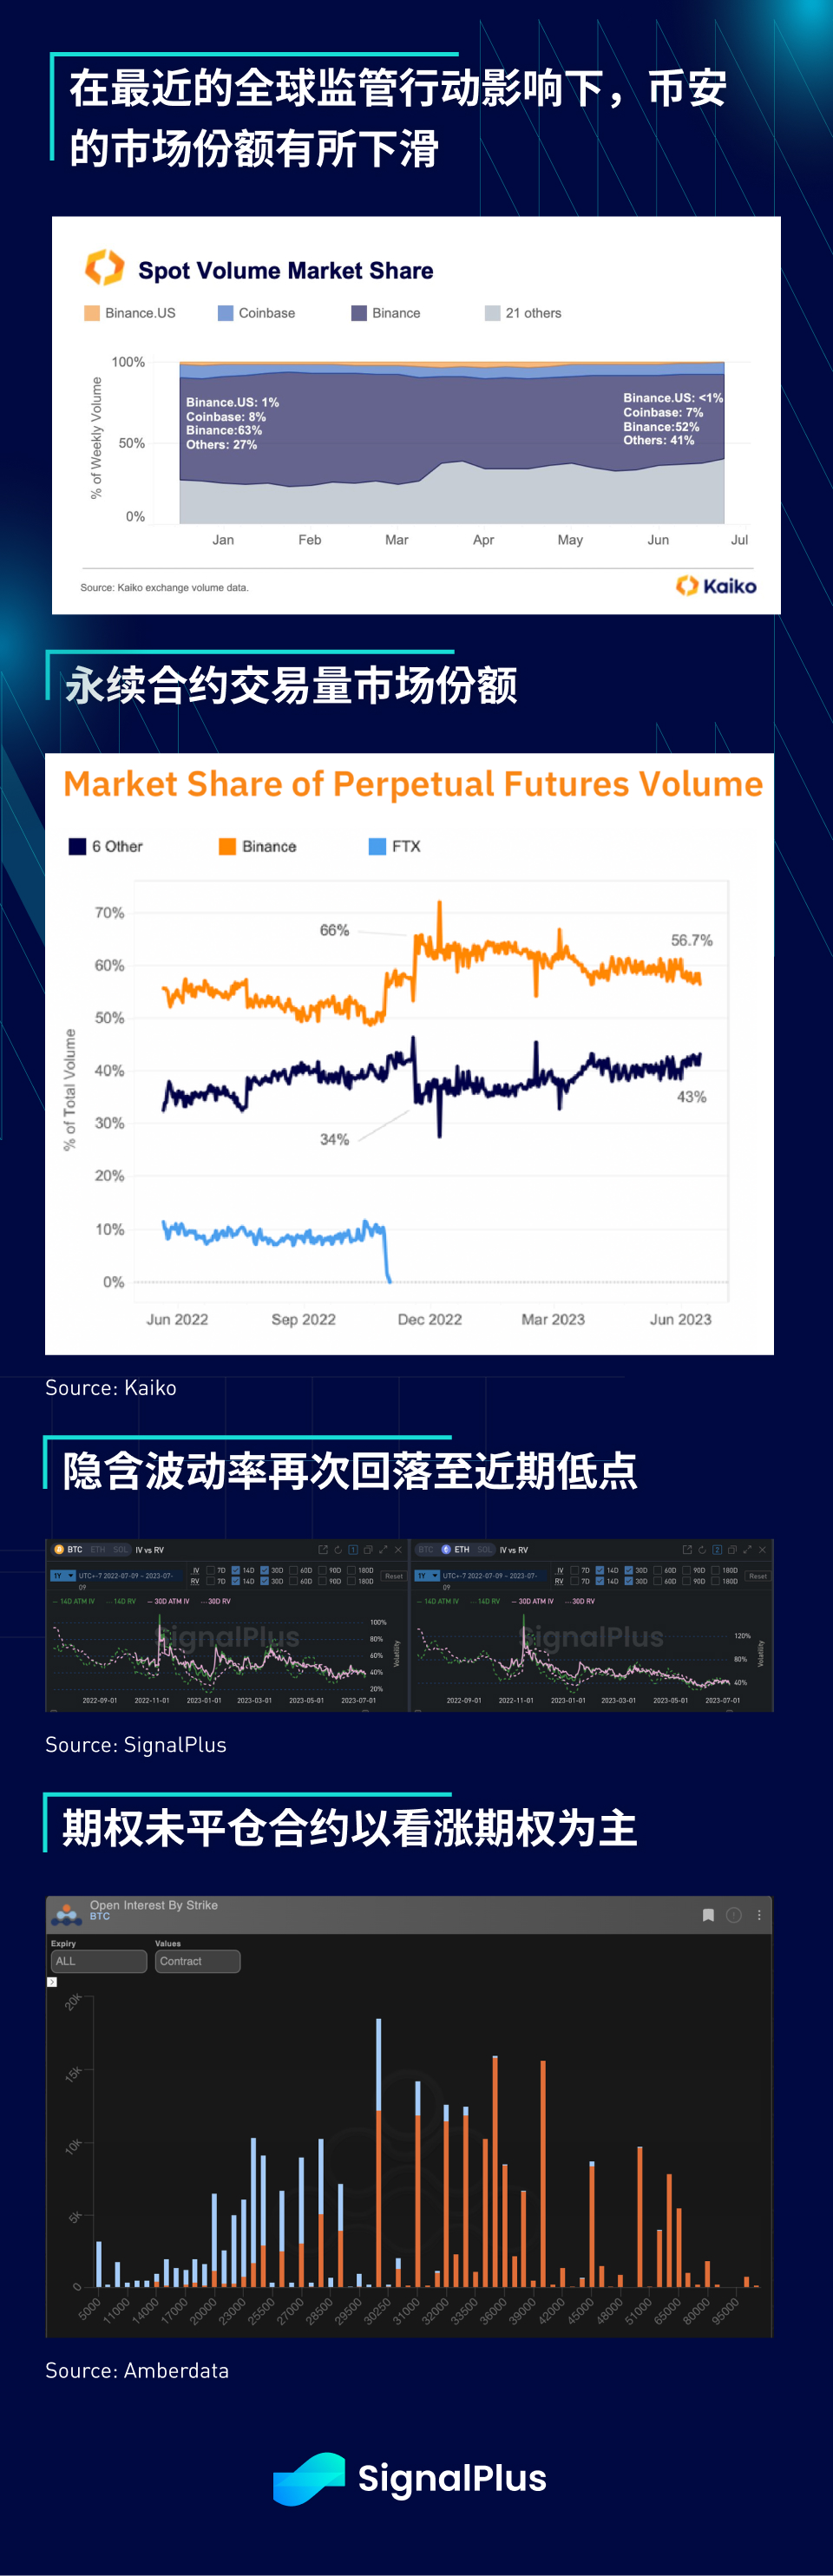
Cryptocurrency prices have been relatively stable, despite ongoing regulatory actions against Binance and recent reports of multiple executives resigning from the exchange. Due to regulatory activities, Binance's market share in spot trading volume has decreased from around 63% in January to around 52% at the end of June. Its leadership position in perpetual contract trading has also given back most of the gains seen this year. Implied volatility is once again trending downwards, and traders still favor strategies that generate returns, with open interest continuing to be dominated by call options.
If you want to receive our updates in real time, please follow our Twitter account @SignalPlus_Web 3, or join our WeChat group (add assistant WeChat: chillywzq), Telegram group, and Discord community to interact and communicate with more friends.
SignalPlus Official Website: https://www.signalplus.com/





