SignalPlus Macro Research (20230707): US economy rebounds better than expected, crypto market decoupled from Nasdaq


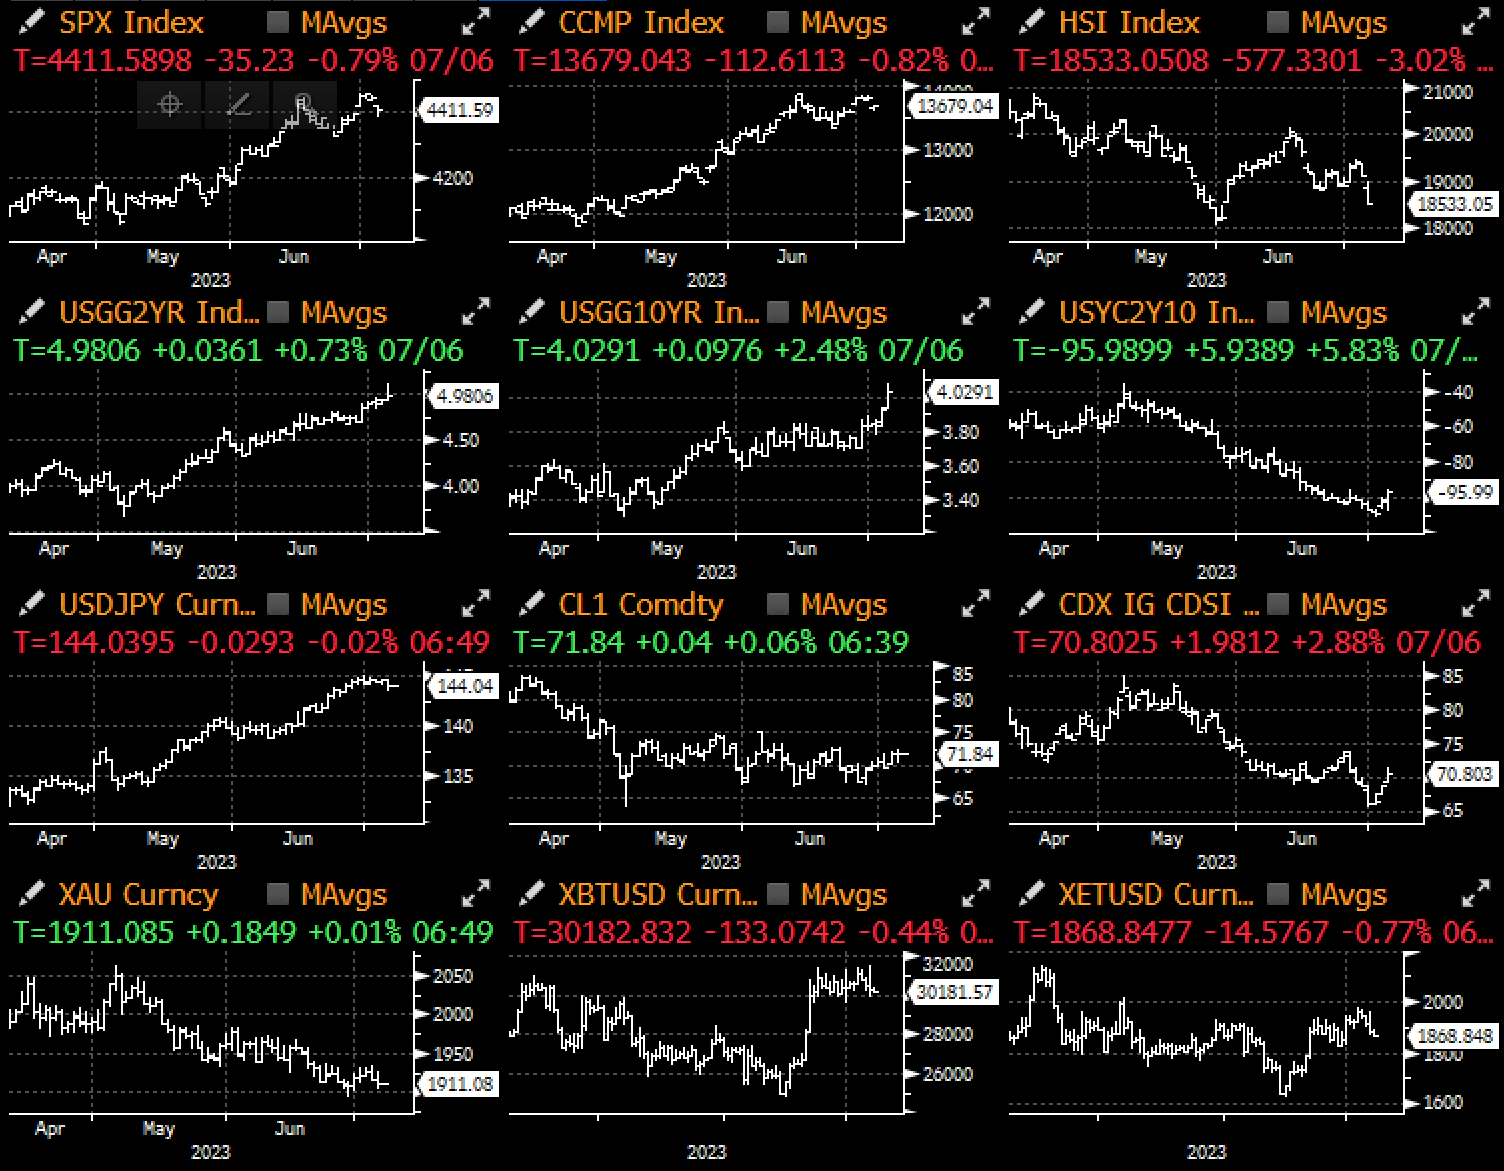
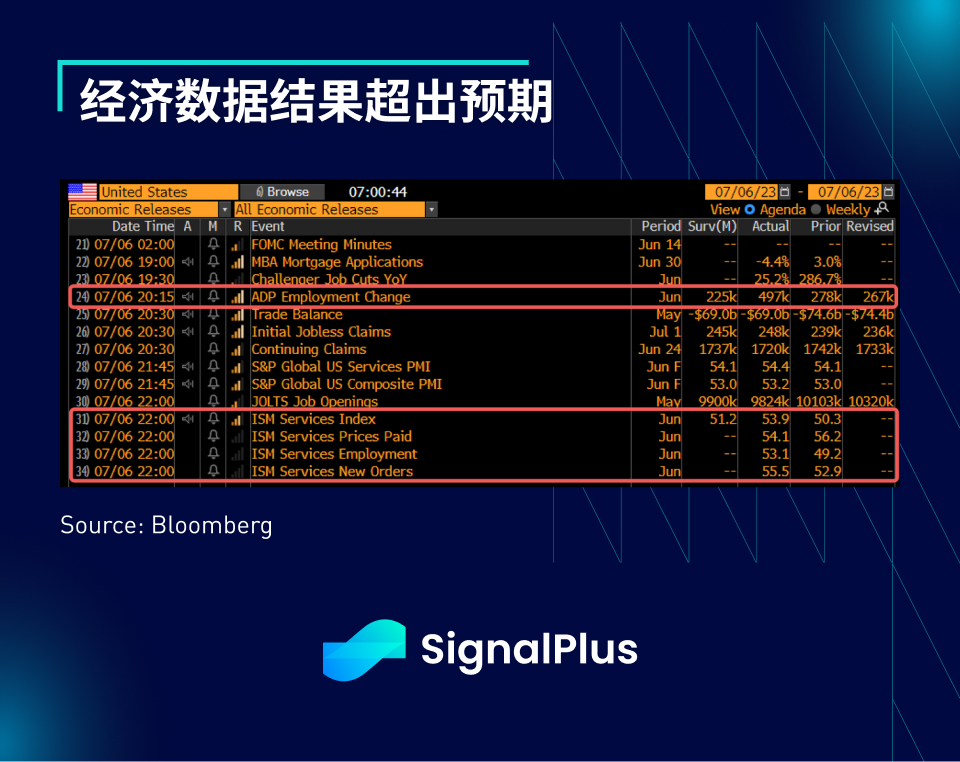
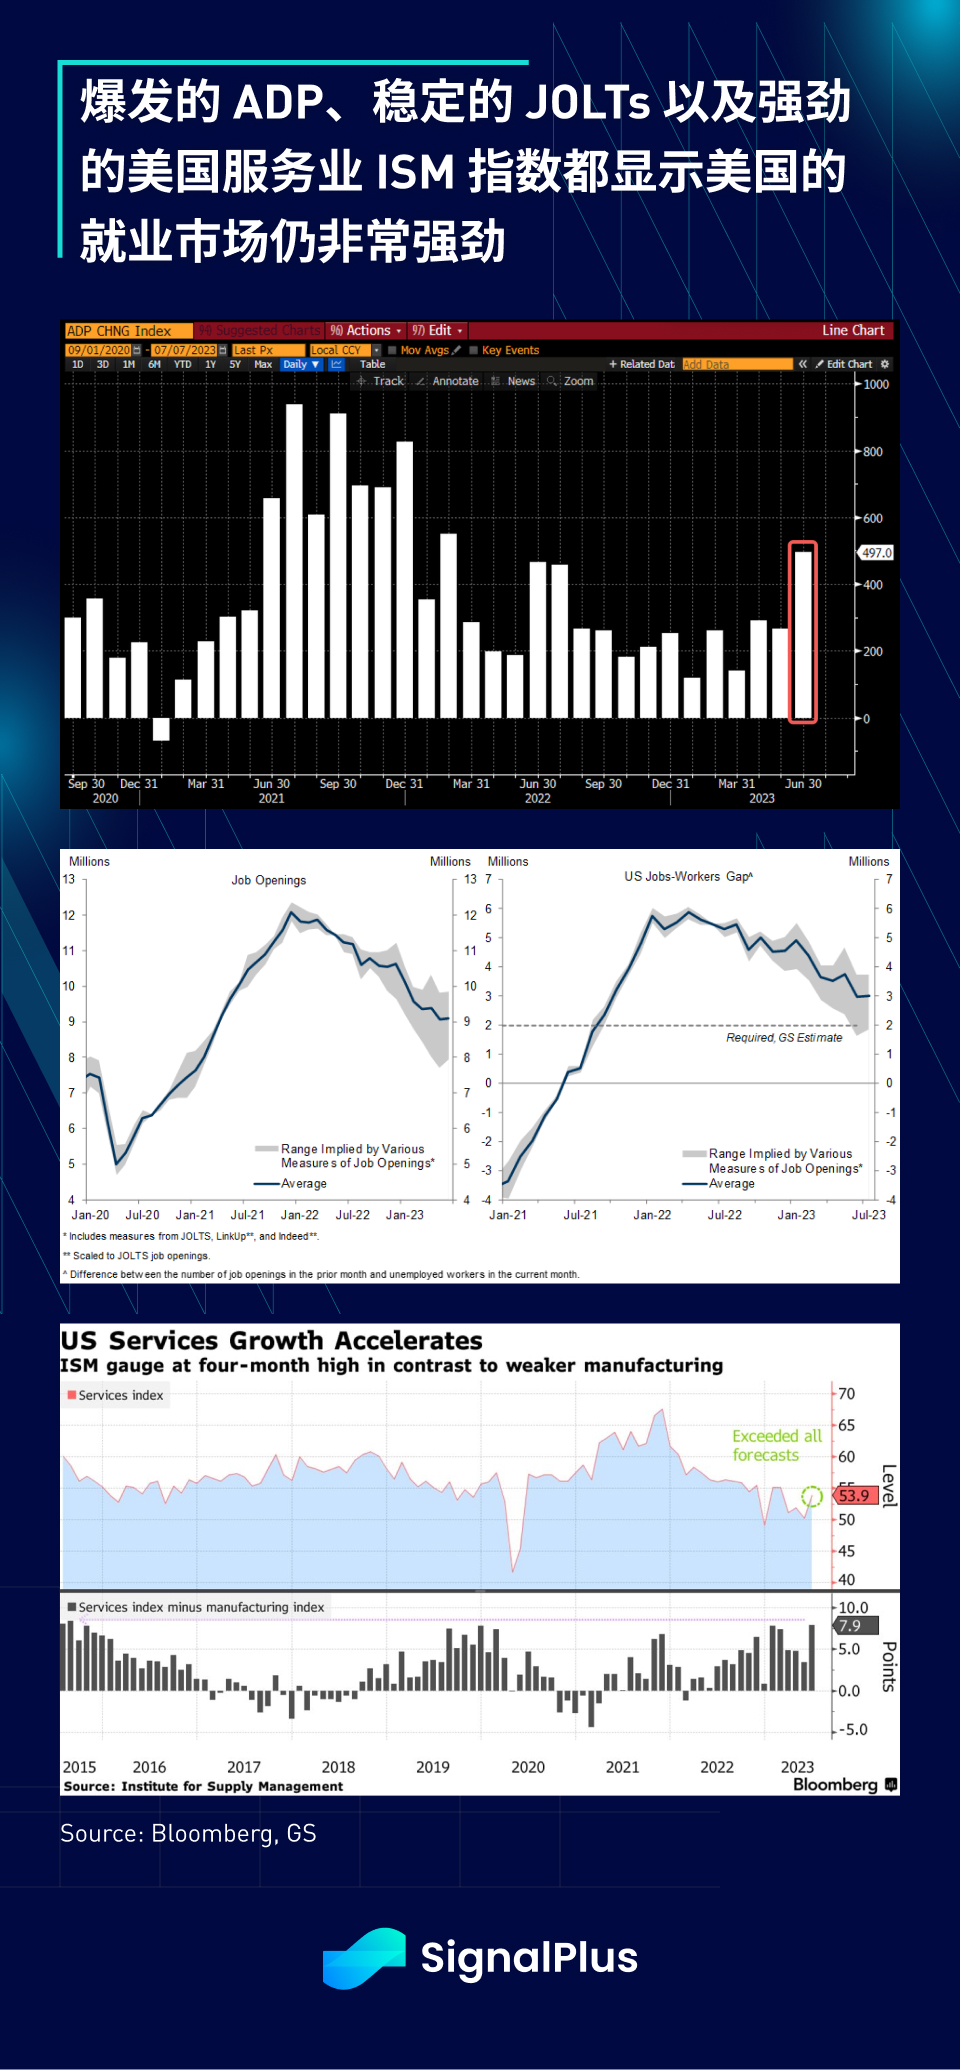
Yesterday welcomed a wave of intensive economic data releases, with results hotter than summer weather; Germany's factory orders data had a strong start, with a month-on-month growth of 6.4%, far exceeding the expected 1.2%, but what really got the market excited was the ADP data, which saw an incredible increase of 497,000 in employment, compared to the expected 225,000 (service sector + 373,000, manufacturing sector - 420,000), and the number of weekly initial jobless claims remained stable (248,000), while Challenger layoff announcements hit the lowest level since October last year, despite the slightly lackluster JOLTS data, the job openings-to-unemployed ratio fell to the lowest level since October 2021 (1.6 times), balancing out the rebound in the resignation rate (more voluntary resignations), however, the performance of the ISM services index is sufficient to make up for any disappointment, with both the overall index and new orders (55.5 vs 52.9) and employment (53.1 vs 49.2) indices exceeding expectations.
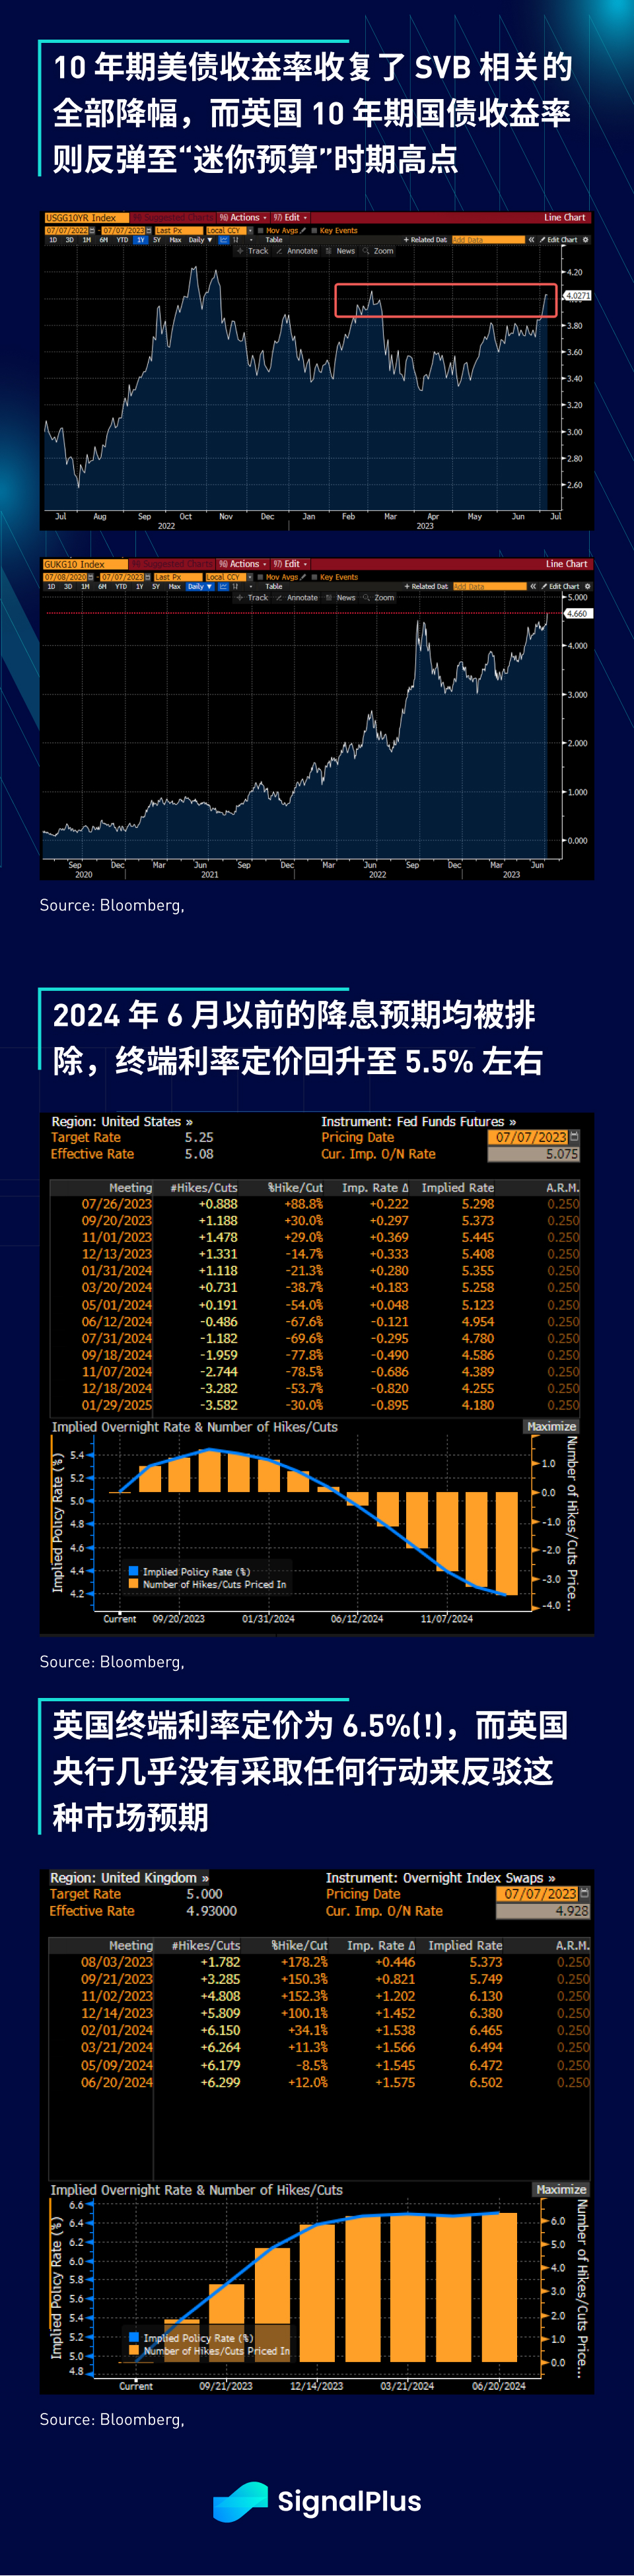
The bond market responded accordingly, with the U.S. 10-year yield erasing all SVB-related declines and closing above 4%, while the 2-year yield rebounded to above 5%, expectations of rate cuts before June 2024 have been removed (terminal rates are around 5.45%); on the other side of the Atlantic, the Bank of England's Bailey did not put up much of a fight against the market boldly pricing terminal rates at 6.5% (!), causing the UK 10-year bond yields to rebound above the high point during the Liz Truss mini budget period.
The trading volume reported by brokerage firms is about 180% of the normal level, and there is very active actual fund activity to reduce duration risk and sell short-term long positions. In addition, to make matters worse, Dallas Fed's Logan came forward to say that a rate hike in June would have been "completely appropriate," and that the Fed needs to adopt a more tightening policy to achieve its 2% inflation target, while still remaining skeptical about the so-called lagging effect of rate hikes.
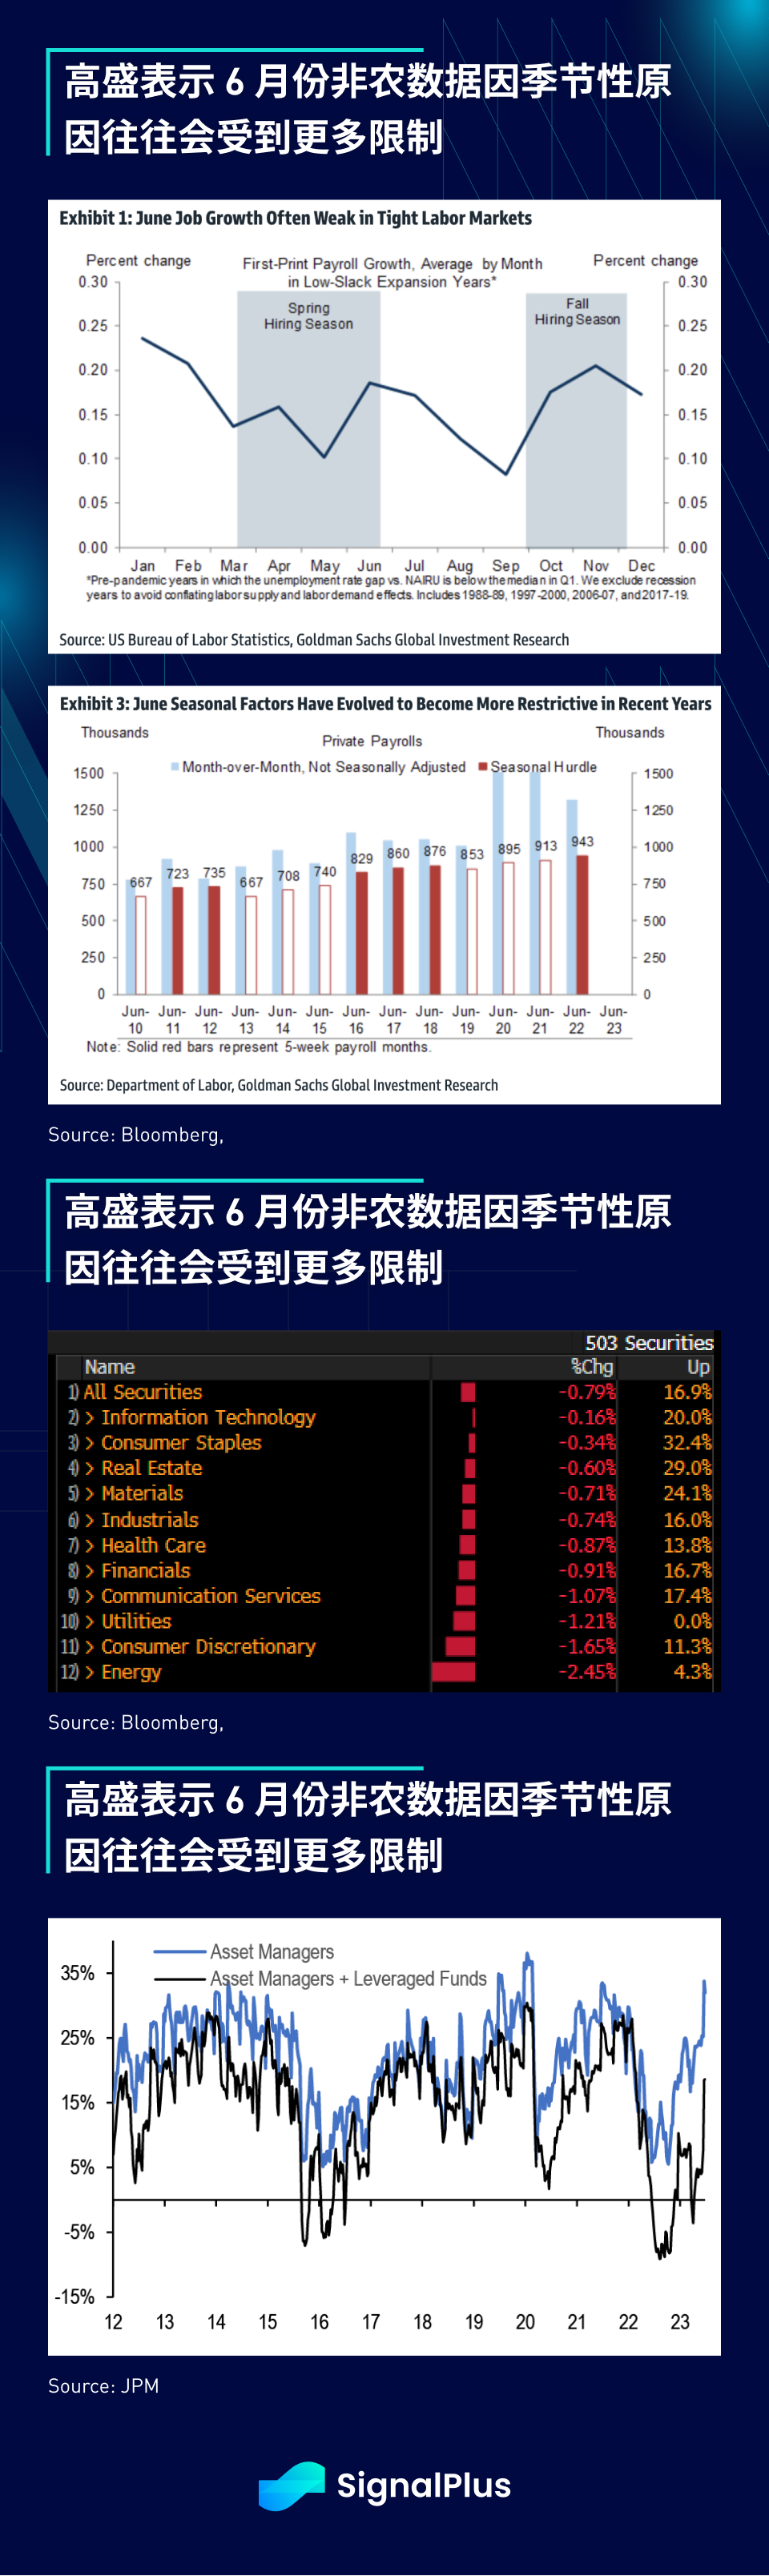
Due to the explosive ADP data, market expectations for non-farm data have undoubtedly increased today. However, Goldman Sachs warns that June data tends to be limited in terms of employment growth due to seasonal factors, so high expectations could lead to disappointment. In terms of stocks, all sectors of the SPX index showed declines yesterday as the market worried about the return of sustained rising yields. In addition, JPMorgan's survey data shows that institutional fund managers' risk exposures are approaching historical highs. If there is unexpected selling in the third quarter, the current market layout will be difficult to cope with.
In terms of cryptocurrency, prices have undergone a correction as gold prices have fallen and yields have risen, although the correlation between BTC and the overall stock market has almost returned to zero. In addition, quarterly spot trading volume for Bitcoin has dropped to the lowest level since 2020. In a low liquidity environment, it is expected that the price trend will continue to fluctuate and may experience some sharp fluctuations. This situation may continue until mainstream participation is further confirmed, such as the successful application of ETFs.