


Global Payments Weekly 2026W41


- ประเด็นหลัก: จุดสนใจด้านการชำระเงินด้วย crypto ในสัปดาห์นี้ได้เปลี่ยนจากตลาดซื้อขายไปสู่การเงินองค์กรและสถานการณ์ด้านการบริหารเงิน โดย stablecoin กำลังถูกนำมาใช้โดย SAP, PayPal และอื่น ๆ สำหรับการชำระบัญชีแบบ B2B ขณะเดียวกัน EU ได้ออกคำสั่งให้ถอน stablecoin ที่ไม่ผ่าน MiCA ส่งผลให้สภาพคล่องของ USDT กำลังเผชิญกับหน้าต่างการโยกย้าย
- ปัจจัยสำคัญ:
- ESMA ใช้คำสั่งถอนแทนระบบ whitelist โดย stablecoin ที่ไม่ผ่าน MiCA มีวันสิ้นสุดที่ชัดเจน และ PSP ในยุโรปต้องโยกย้าย USDT ไปยัง USDC/EURC หรือ EMT ของธนาคารภายในสามเดือน
- ค่าธรรมเนียม UPI ของอินเดียจากการประกาศในเดือนกันยายนเลื่อนออกไปเพียงสี่สัปดาห์ในเดือนตุลาคม แสดงให้เห็นว่าอำนาจกำหนดราคาของการชำระเงินแบบเรียลไทม์อยู่ที่การเมือง ไม่ใช่ NPCI โดยรางค่าธรรมเนียมเป็นศูนย์ได้กลายเป็นโครงสร้างพื้นฐานสาธารณะ
- ข้อกำหนดบังคับการชำระเงินแบบออฟไลน์ของ Mastercard และ RTGS 24/7 ของ BoE ตอกย้ำว่า "ใช้งานได้โดยไม่ต้องเชื่อมต่อ" เปลี่ยนจากทางเลือกเป็นข้อกำหนดด้านการปฏิบัติตามกฎเกณฑ์ โดยรอบการอัปเดต terminal ถูกเลื่อนขึ้นมาเป็นปี 2027
- ข่าวการชำระเงินด้วย crypto ที่สำคัญที่สุดในสัปดาห์นี้มาจาก SAP, ฝ่ายบริหารเงินของ PayPal, Anchorage และ Rain โดยความต้องการในสถานการณ์ AP องค์กรและฝ่ายบริหารเงินคือความแน่นอนในการชำระบัญชีและบัญชีที่กระทบยอดได้ ไม่ใช่ผลตอบแทน
- พันธมิตรด้านการจัดจำหน่ายเข้ามาแทนที่ผู้ออกเพียงรายเดียว: Fiserv เลิกใช้ Paxos/Circle, Rain ยื่นขอใบอนุญาตเอง, Arbitrum เข้าร่วมเครือข่าย Paxos USDG (มูลค่าหมุนเวียนเกิน 3 พันล้านดอลลาร์) การแบ่งปันรายได้จากทุนสำรองเป็นตัวกำหนดว่าช่องทางใดจะเป็นของผู้ใด
- Circle ร่วงลง 5.2% จากข่าวดีของ SAP Pay สะท้อนความกังวลของตลาดต่ออำนาจการจัดจำหน่ายของบริษัท; อุปทานรวมของ stablecoin ในสัปดาห์นี้อยู่ในช่วง 3.05–3.13 แสนล้านดอลลาร์
Period: 5–12 October 2026 (Week 41) · For traditional and crypto payments professionals · ~4-minute read
Note: All items are sourced from regulators, company announcements and mainstream financial/industry media, each with a publication date and link. [Forecast] and [Opinion] mark institutional or personal views; everything else is fact. No verifiable major public information was found this week for Southeast Asia (Singapore/Indonesia/Thailand) or Japan beyond the items listed; those cells are marked "no reliable public data this week".
1. This Week at a Glance

W38 watchlist follow-up: Sibos → Swift's blockchain ledger declared live, 19 banks expected by year-end (company expectation); FCA stablecoin gateway → opened in September, no new developments this week; October effective dates → UPI fee deferred; Brazil's Resolution 561 (barring eFX providers from settling remittances in stablecoins) took effect 1 Oct.
2. Industry Thermometer

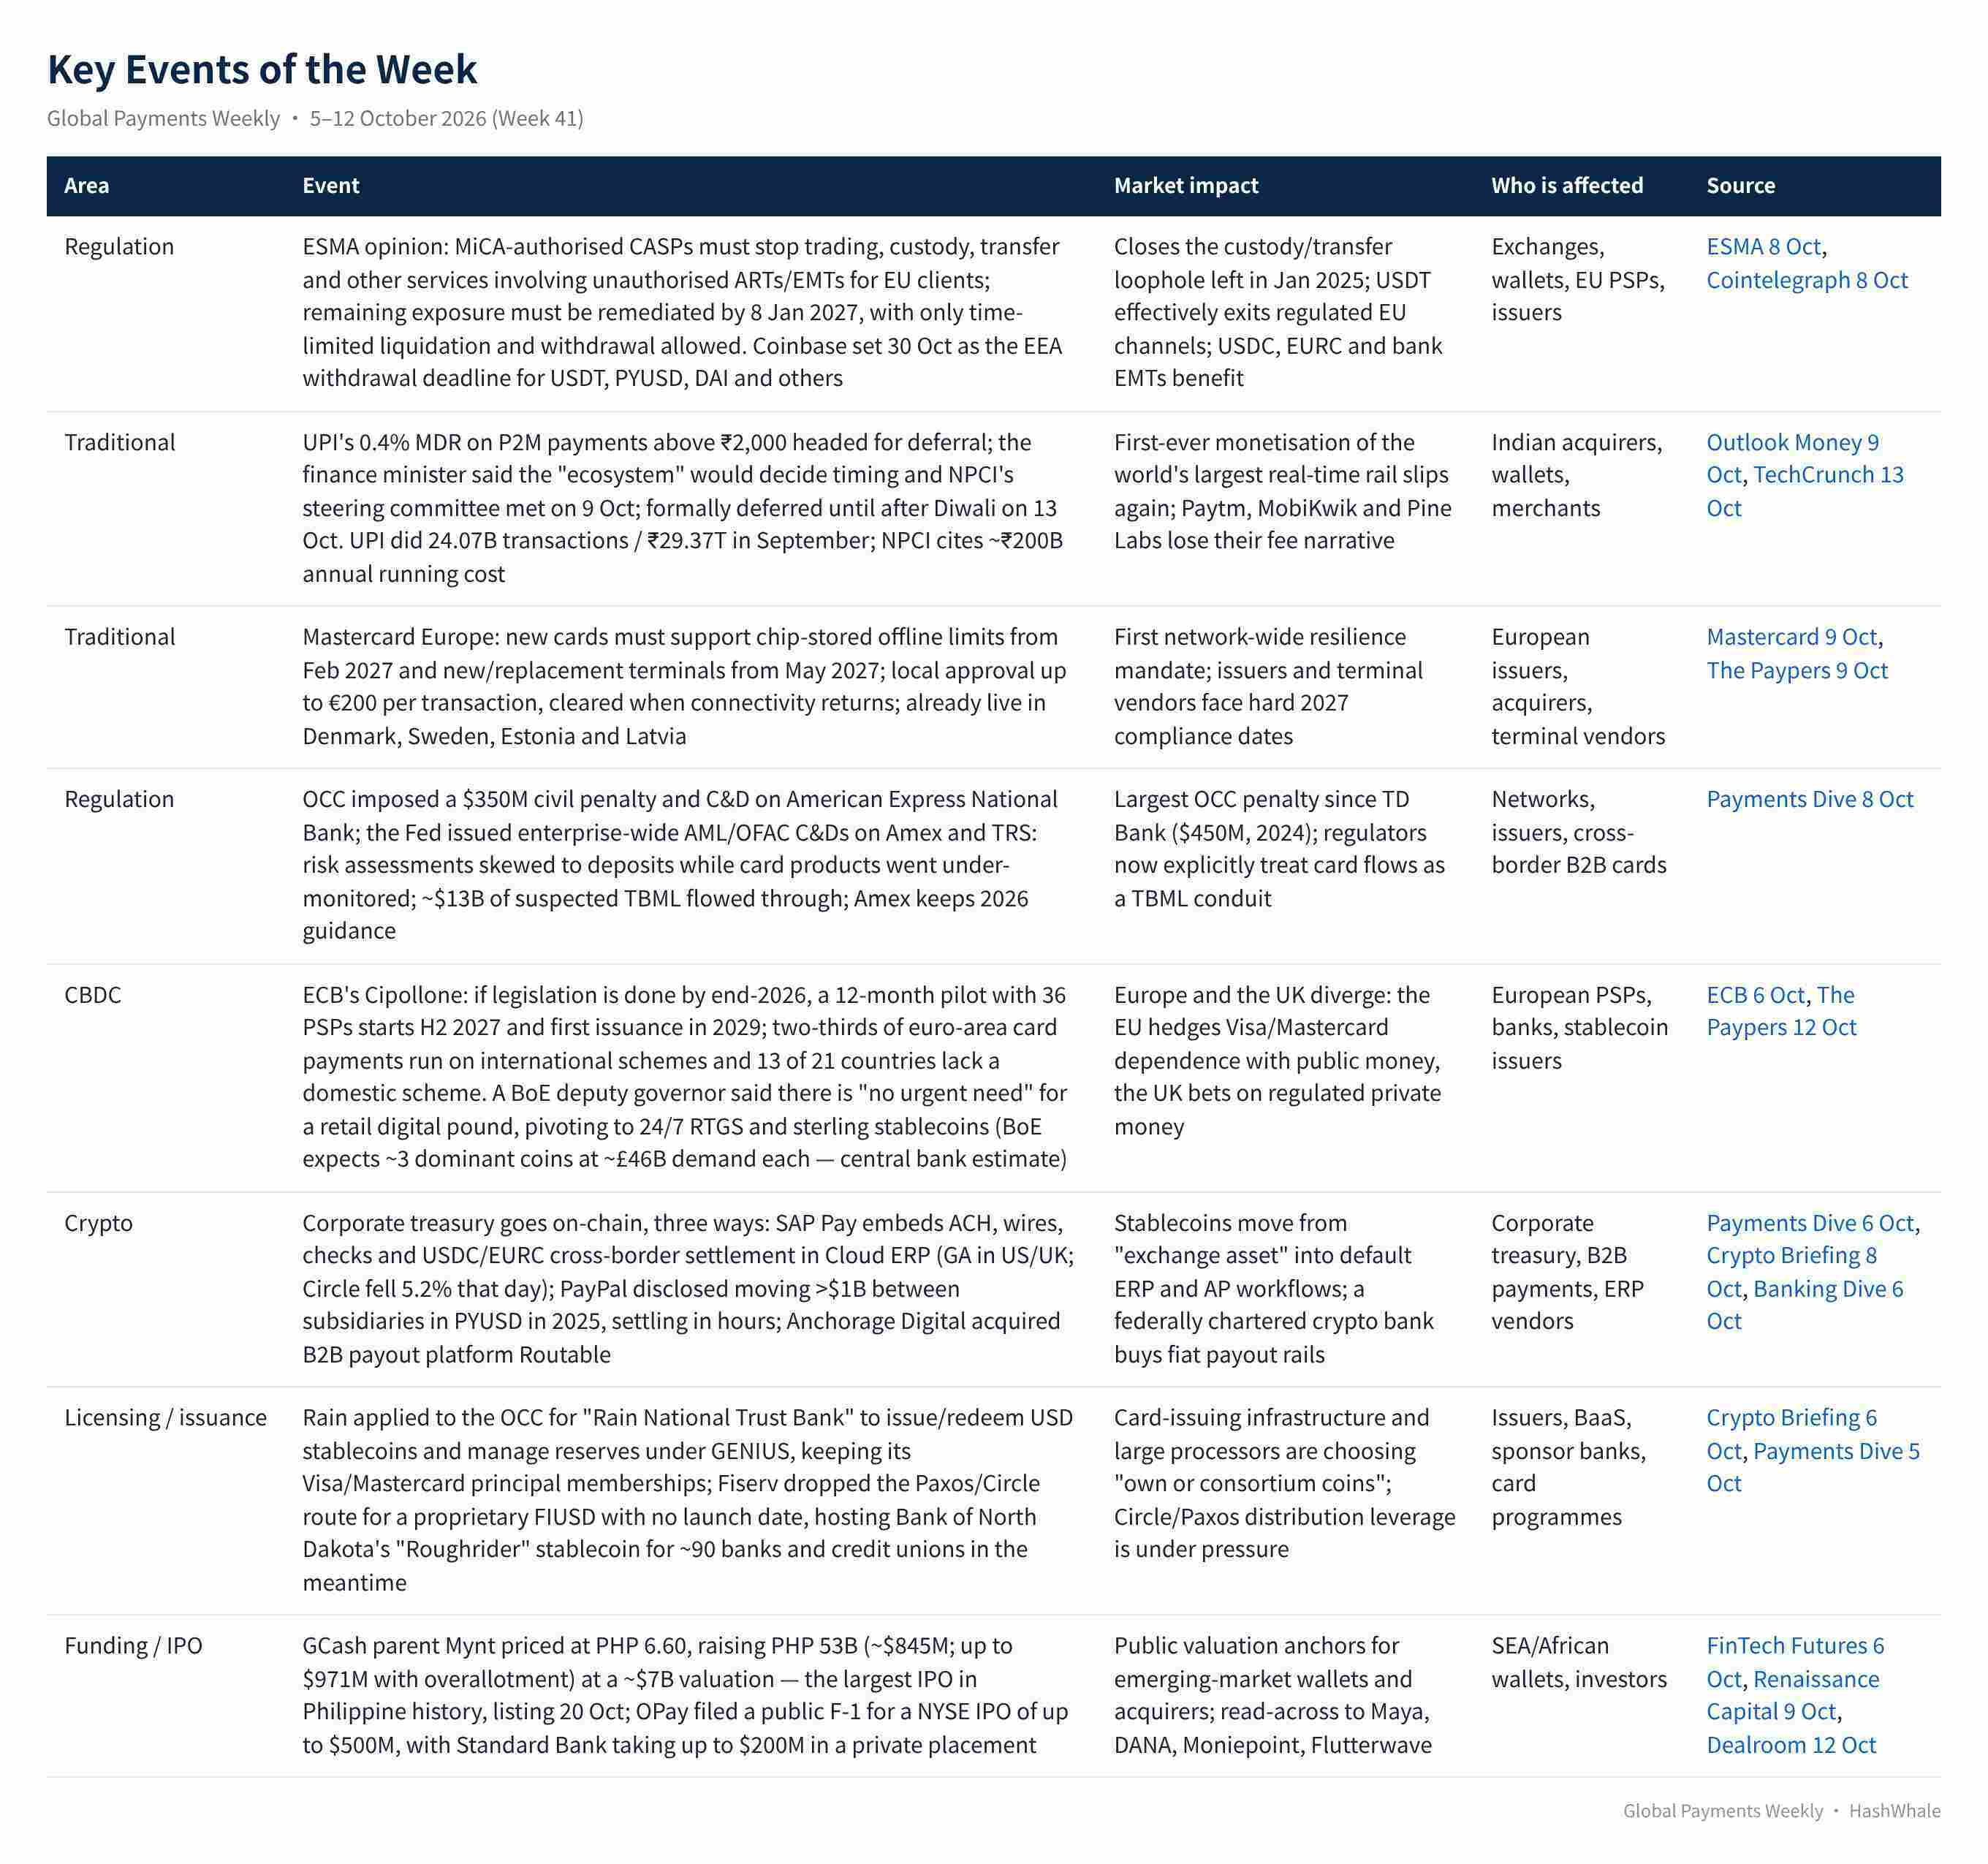
3. Key Events of the Week
 Why it matters (editorial analysis)
- The EU replaces a whitelist with a wind-down order. ESMA named no tokens, but by closing custody and transfers it gave non-MiCA stablecoins a definite end date. For PSPs operating in Europe, the next three months are a migration window for USDT liquidity into USDC/EURC or bank EMTs, not a wait-and-see period.
- Charging for real-time payments is harder than legislating. UPI went from announcement in September to deferral in October in four weeks: where zero-fee rails have become public infrastructure, pricing power sits with politics, not NPCI. Indian PSPs valued on a "fee switch" need to return to a value-added-services story.
- Resilience becomes a compliance item. Mastercard's offline mandate and the BoE's emphasis on 24/7 RTGS both turn "works without connectivity" from optional into required; terminal refresh cycles are pulled forward and acquirer hardware costs cluster in 2027.
- Stablecoins are changing customers. This week's heaviest crypto-payments news came from SAP, PayPal treasury, Anchorage and Rain, not exchanges. Corporate AP and treasury use cases do not need yield; they need certainty of settlement and reconcilable accounting — the use case least affected by GENIUS's interest ban.
- Distribution consortia displace single issuers. Fiserv dropping Paxos/Circle, Rain filing its own charter, Arbitrum joining Paxos's Global Dollar Network (USDG >$3B in circulation) and Open USD's late-September launch all say the same thing: who shares reserve income decides channel ownership. Circle fell 5.2% on what looked like good SAP Pay news — the market's worry about its distribution leverage is visible.
4. Deep Dive: Crypto & Web3 Data and Views
4.1 Stablecoin and On-chain Data Board

Trackers differ by several billion dollars; treat $305–313B as the band for this week's total supply.
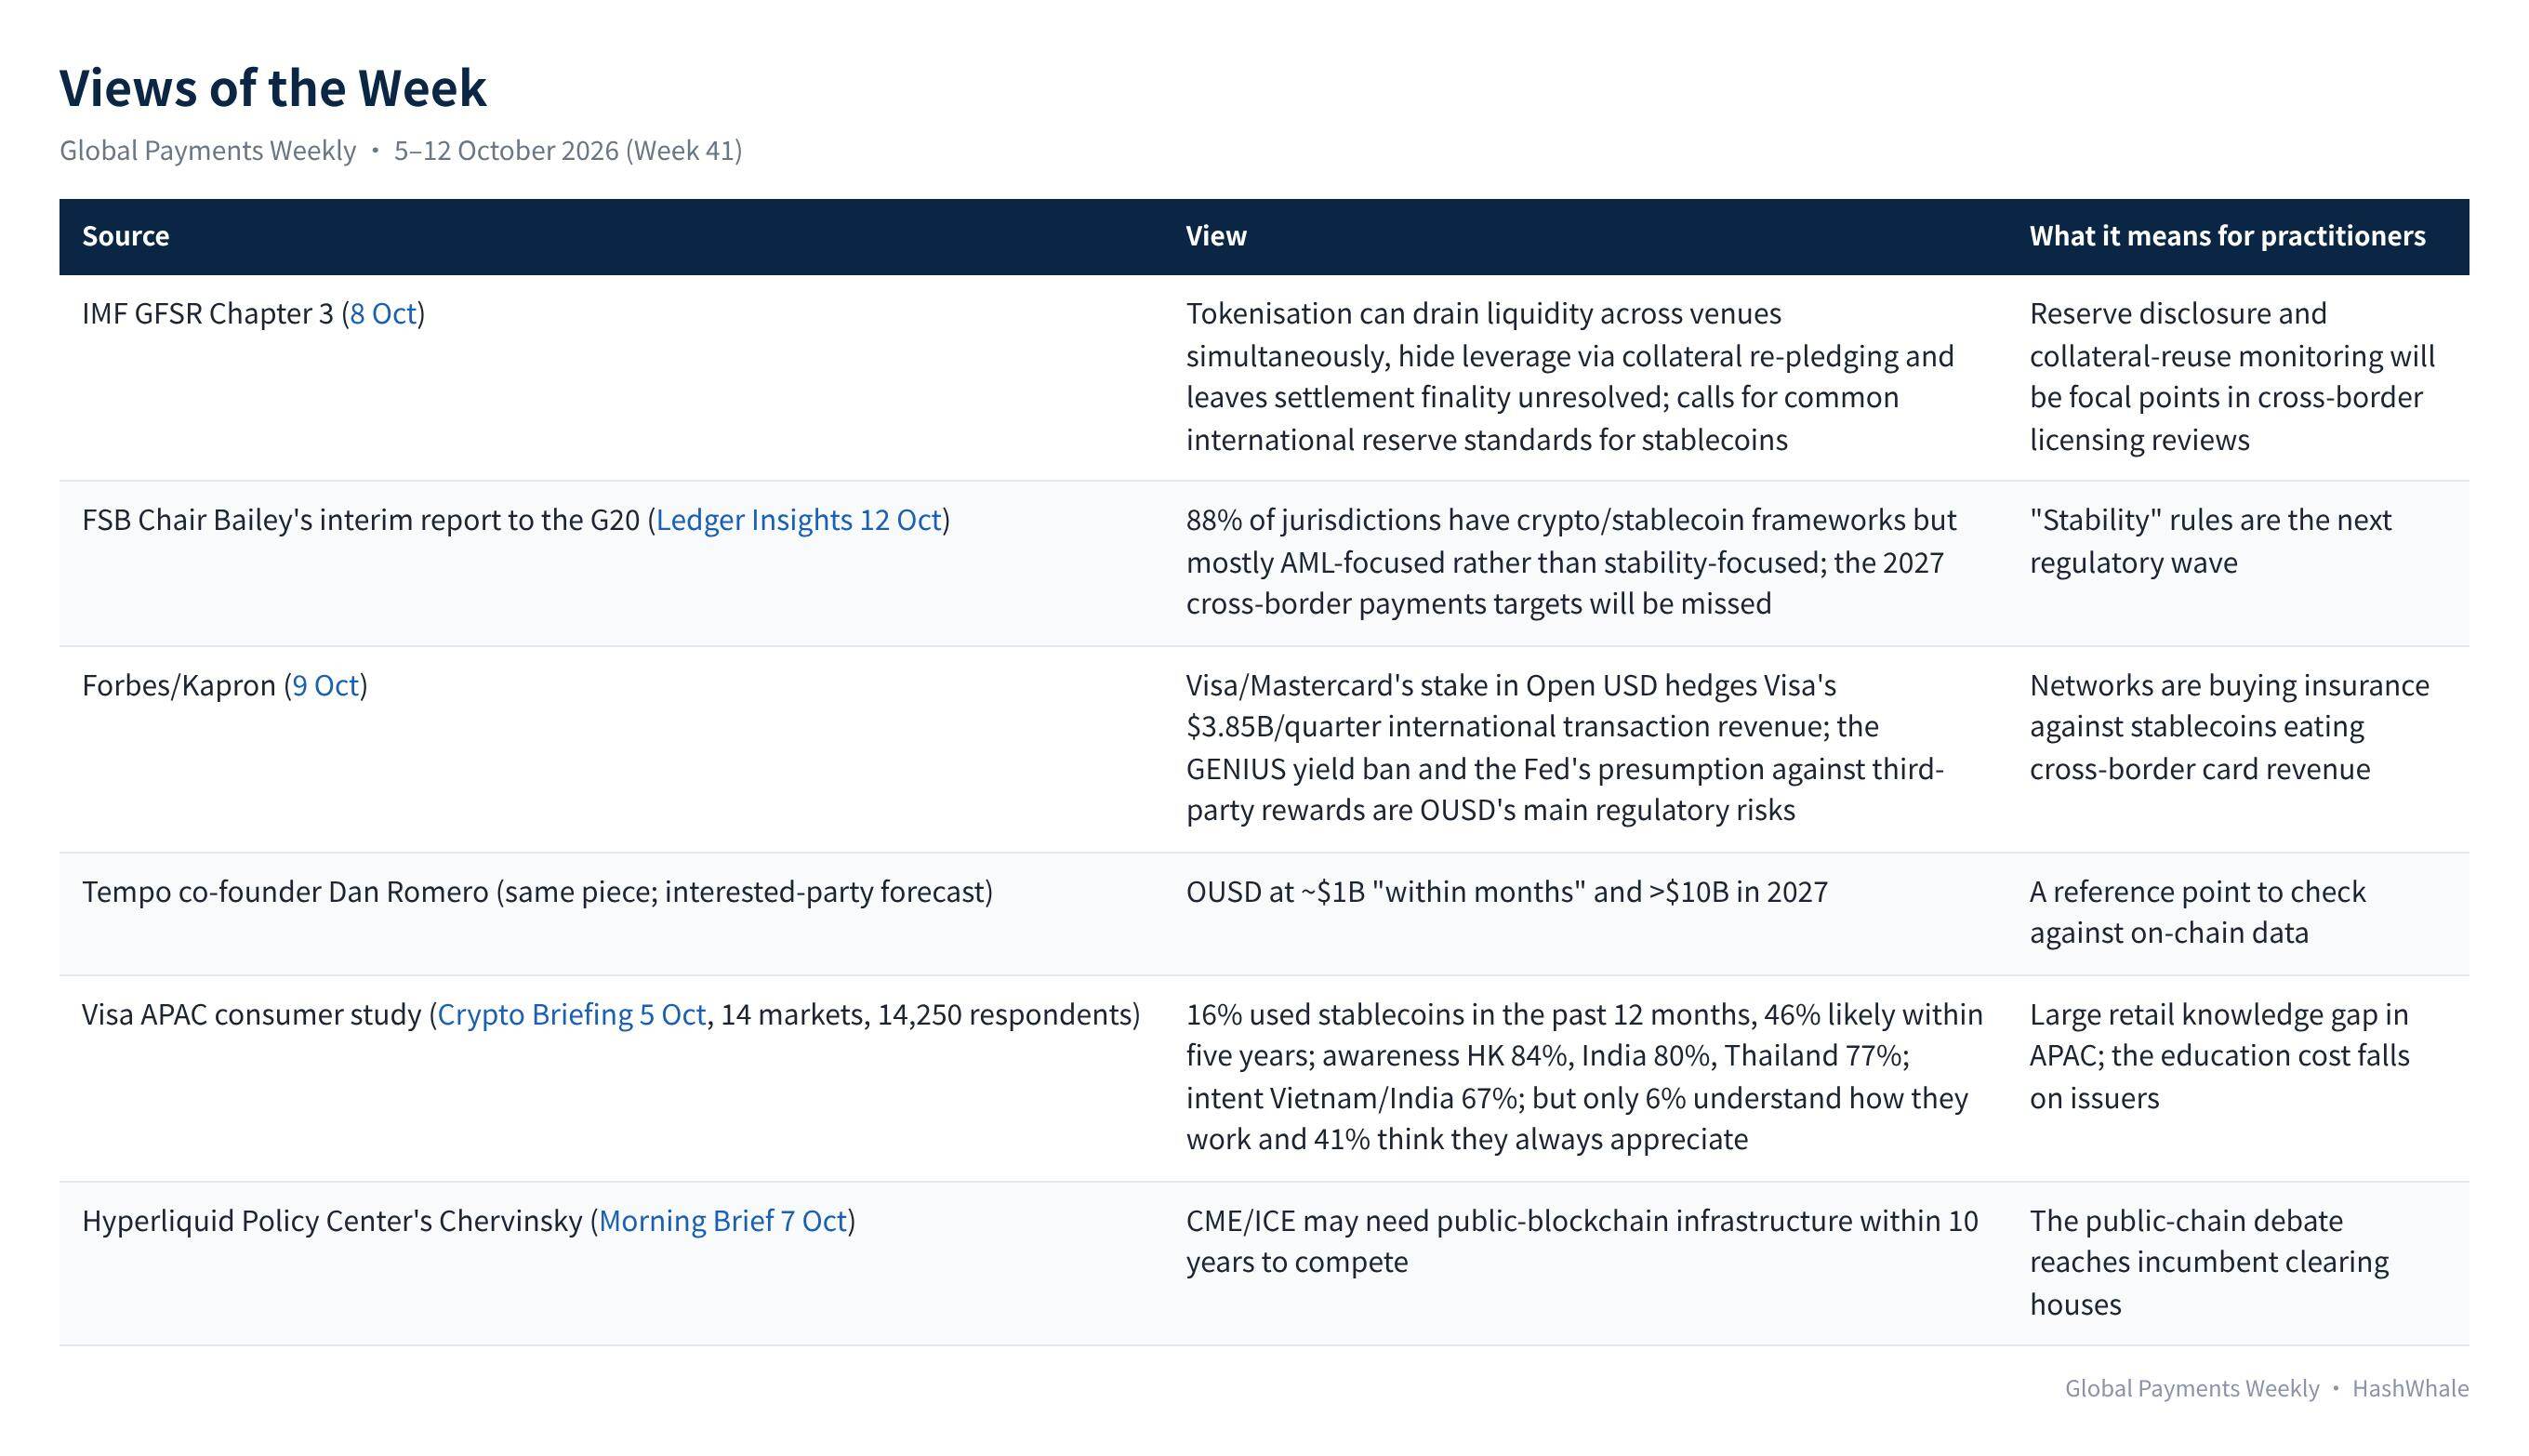
4.2 Views of the Week (institutional/personal opinions or forecasts, not facts)
4.3 Other Crypto Payments Items (one line each)
- Standard Chartered: institutional custody for Ripple's RLUSD via its DIFC branch, with an RLUSD-as-collateral plan with LMAX; separately, crypto/stablecoin/RWA custody to launch in Singapore by end-2026 (The Block 12 Oct, 8 Oct).
- Payward (Kraken) × Singapore Gulf Bank: 24/7 instant USD settlement for institutional clients in Asia and the Gulf via SGB Net (Cointelegraph 5 Oct); Payward also received VARA Full Market Approval in Dubai, with AED pairs going live within weeks (FXNG 12 Oct).
- Coinbase × Gennius: 1:1 USDC-backed ONED USD distributed through 85+ Latin American financial institutions, Argentina first, spendable via bank-issued Visa cards (Crypto Briefing 8 Oct).
- Mastercard × SoFi: BIN sponsorship, issuing and processing for Mexico's Orbi crypto-linked card, merchants settled in fiat; Bitso says stablecoins were 40% of LatAm crypto purchases in 2025 (PYMNTS 8 Oct).
- Securitize: 12 tokenised US stocks (Apple, Nvidia, Tesla, etc.) on Solana settling in USDC, Jump Trading market-making; SECZ +10% (Cointelegraph 8 Oct).
- Solana Foundation: open-source "Solana DvP" atomic delivery-versus-payment standard with JPMorgan input (Cointelegraph 6 Oct).
- Paxos USDG: live on Arbitrum; Arbitrum joins the Global Dollar Network with a DAO proposal for 100M ARB in incentives; USDG >$3B in circulation (CoinDesk 5 Oct).
- Tether, three items: Conduit sued Tether in SDNY over $2.76M of USDT frozen for more than a year (The Block 6 Oct); Sen. Blumenthal demanded Tether custody and reserve records from Cantor Fitzgerald, response due 23 Oct (Cryptonomist 9 Oct); Tether froze USDT linked to Ledger-device supply-chain thefts, with some funds moved into USDD to avoid freezes (Crypto Briefing 12 Oct).
- Block: 5% discount for Cash App bitcoin spent at Square sellers; Q2 bitcoin gross profit −31% y/y to $72M (Payments Dive 9 Oct).
- Funding: Noah (stablecoin cross-border infrastructure) closed a $38M seed (GlobeNewswire 7 Oct); Spiko (tokenised cash funds) raised a $90M Series B led by NEA (FinTech Global 6 Oct); IMMIX (non-USD stablecoin FX pricing) raised $3.5M (GlobeNewswire 8 Oct).
5. Traditional vs. Crypto Payments

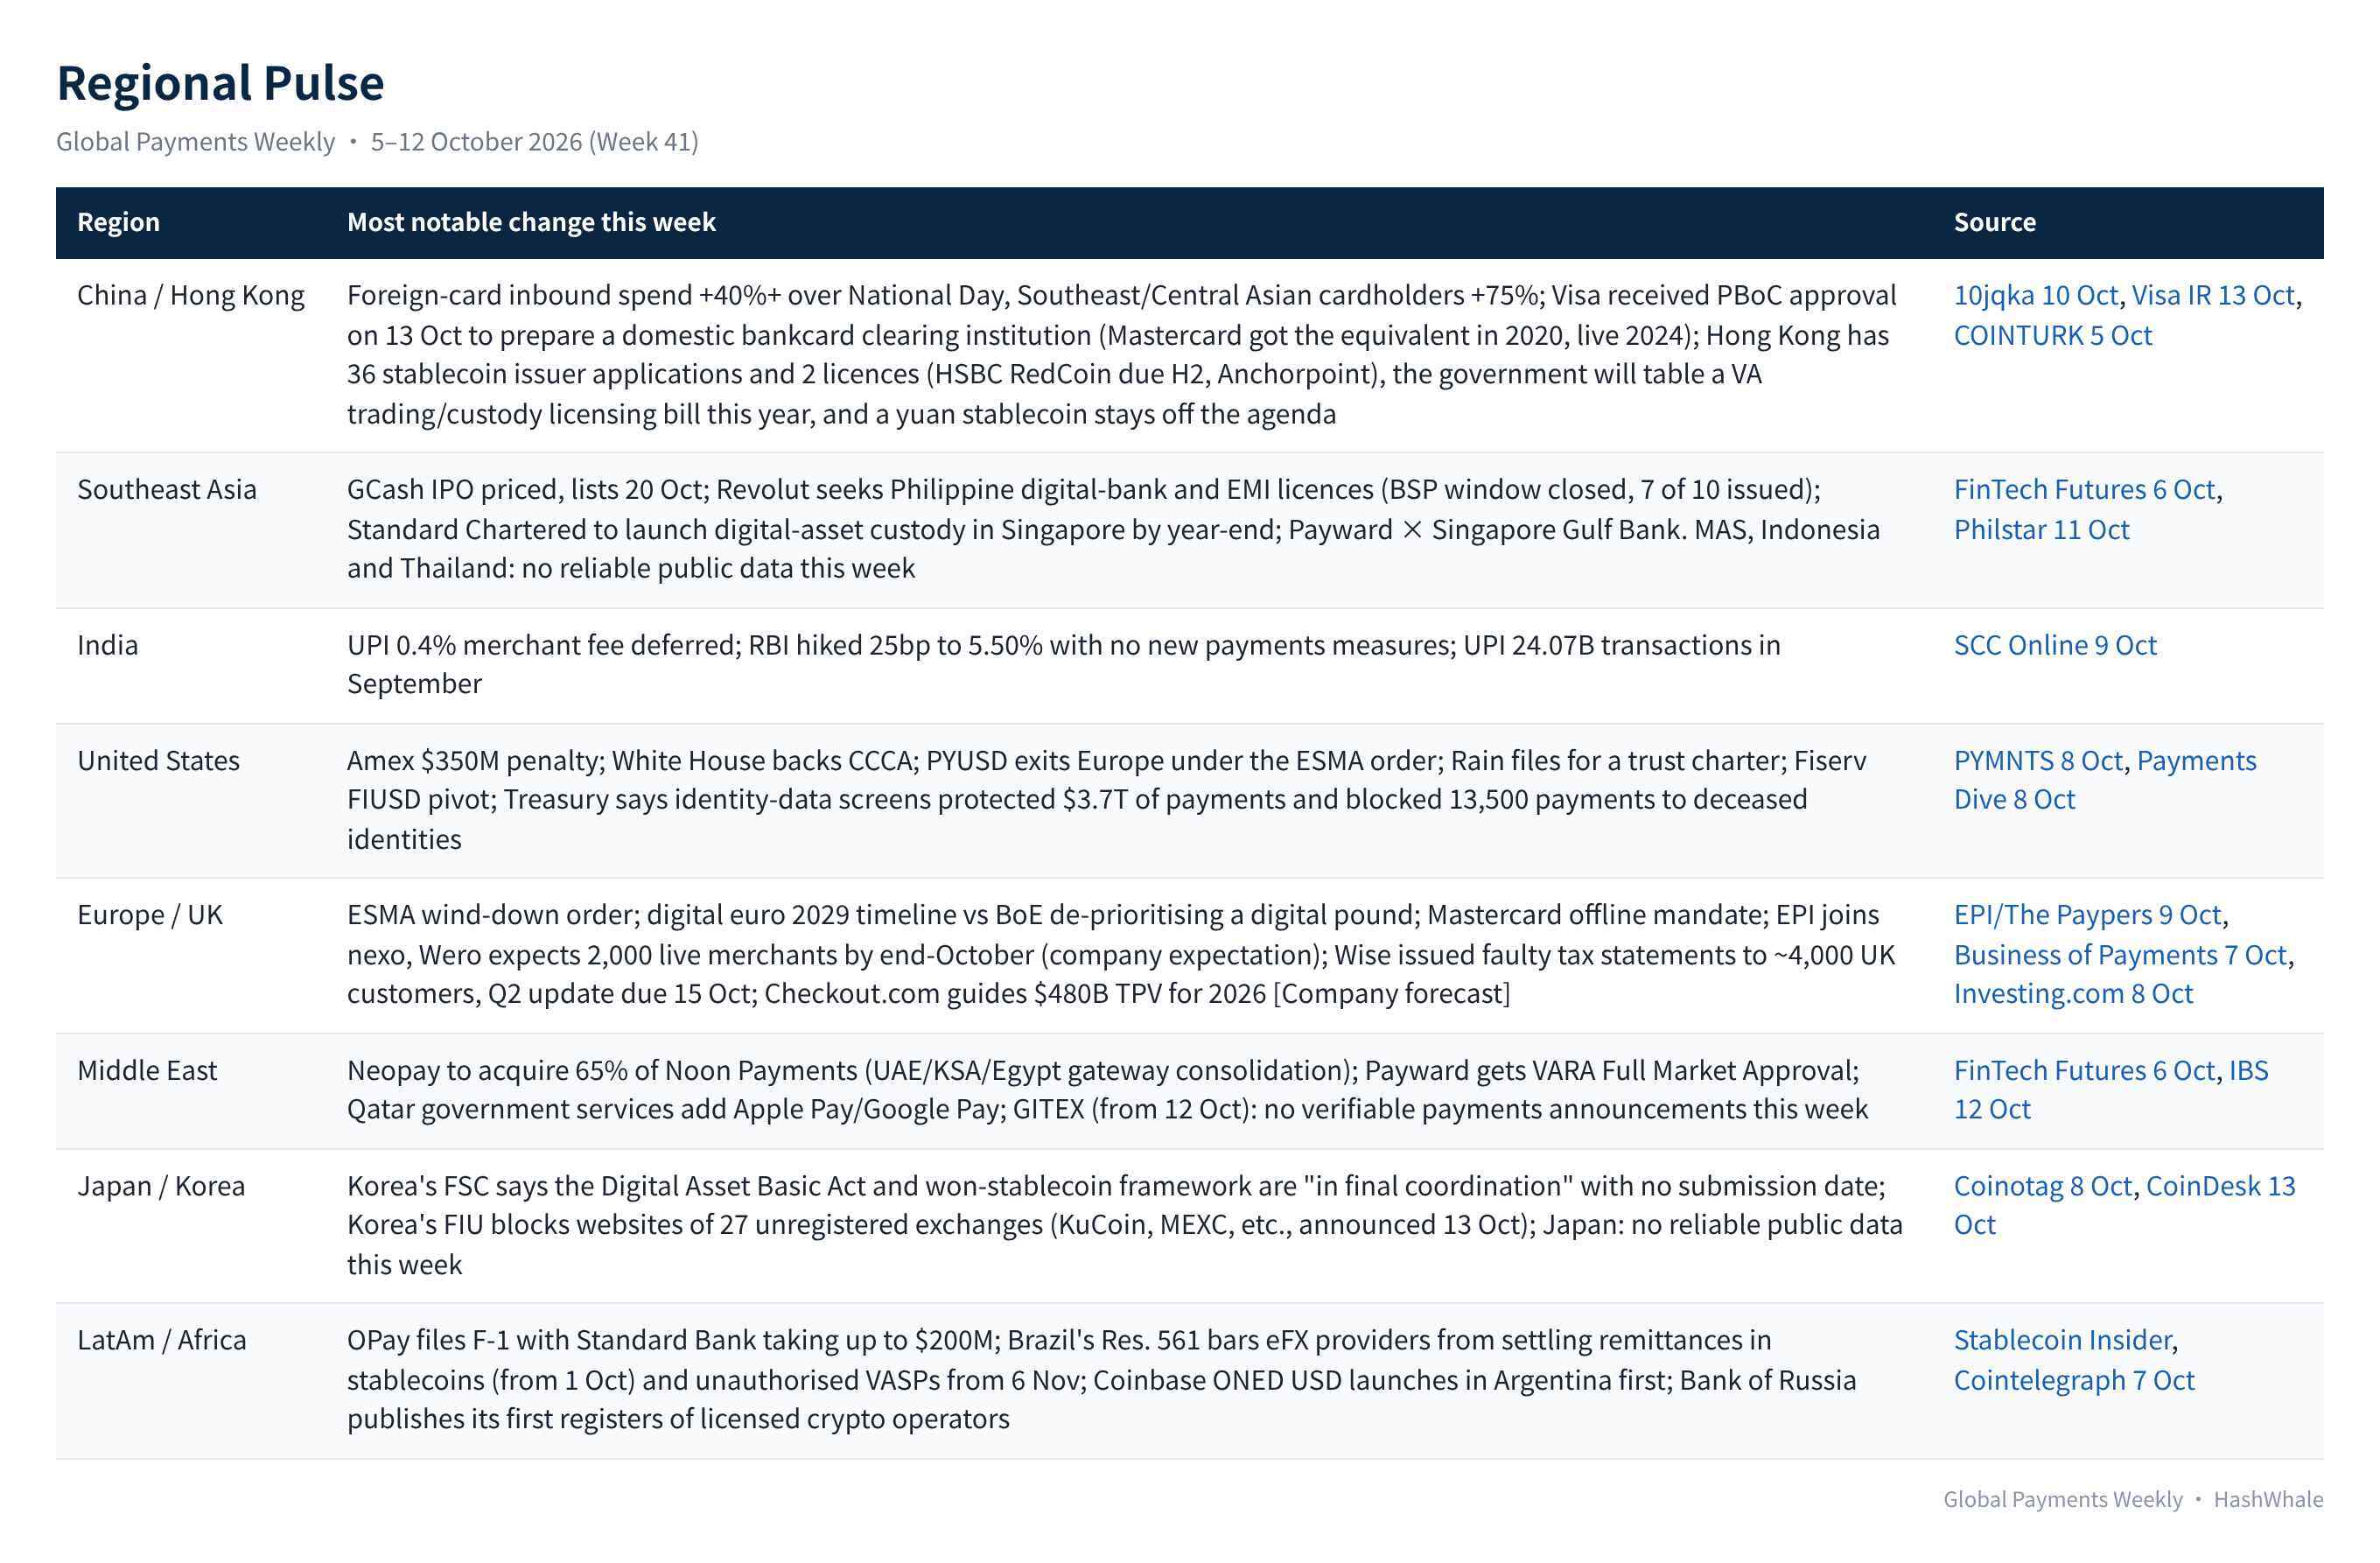
6. Regional Pulse
7. Action Items for Practitioners
Traditional payments
- Put "offline-capable" on the 2027 product roadmap. European issuers and acquirers should complete chip offline-limit parameter and terminal firmware assessments in Q4 to avoid crowded, pricier procurement at the February/May 2027 deadlines.
- Re-base fee assumptions for India and other emerging markets. The UPI deferral shows real-time payment pricing follows the political cycle; business plans should lean on value-added services (credit, SaaS, cross-border) rather than MDR.
- Benchmark card-product AML coverage against the Amex case. Transaction-monitoring thresholds and trade-background checks for cross-border B2B and commercial card flows need parity with deposit products; regulators now see card flows as a TBML channel.
Crypto payments
- Start the EU USDT migration countdown. Licensed firms serving EEA clients should finish client notifications before 30 Oct (the Coinbase marker) and move USDT exposure to USDC/EURC or bank EMTs before 8 Jan 2027, updating AML and settlement counterparties in parallel.
- Prioritise corporate treasury and AP use cases. SAP Pay, PYUSD intercompany transfers and the Routable deal show the interest ban does not touch B2B settlement demand; pitch embedded stablecoin settlement to ERP and AP-automation platforms.
- File GENIUS comments and re-assess issuance structure. Treasury's rule closes 19 Oct; weigh the Fed's 2% capital add-on, two-business-day redemption and parent deconsolidation requirements against the "own/consortium coin vs. licensed issuer" choice.
8. Watchlist for Next Week
- US rules and policy dates: Treasury GENIUS stablecoin rule comments close 19 Oct; Money20/20 USA 18–21 Oct (Mastercard previews an agentic-commerce "trust layer" and stablecoin sessions with BVNK); Cantor Fitzgerald's response to Sen. Blumenthal due 23 Oct.
- Asian capital markets and China access: GCash (GCASH) debut on the PSE on 20 Oct; progress and ownership structure of Visa's China clearing entity; NPCI's new UPI MDR date.
- European wind-down and tax: Coinbase EEA USDT withdrawal deadline 30 Oct; French National Assembly vote on the crypto-to-stablecoin tax amendment on 20 Oct; Wise Q2 trading update on 15 Oct.
Editor's note: all figures are as reported by the original sources; stablecoin supply differs by 1–3% across data providers; the Visa China approval, NPCI's formal deferral and Korea's exchange blocks occurred on 13 October, immediately after the period, and are dated accordingly.





