


Wall Street Interprets Jensen Huang's Resignation: The Consensus Is "No One Can Replace Him," and the Real Crisis Lies in the AI Ecosystem's Funding Chain


- Core Viewpoint: Jensen Huang's unexpected resignation as NVIDIA CEO triggered a single-day market cap wipeout of approximately $420 billion. The Wall Street consensus is "earnings unchanged, valuation revised down," with concerns shifting from short-term orders to organizational succession and the sustainability of the AI ecosystem's financing system.
- Key Elements:
- NVIDIA shares fell about 10% in premarket trading to $156, breaking below their 52-week low, with market cap having shrunk by roughly one-third over the past month.
- Of 14 investment bank research reports, only 3 downgraded the stock and 6 cut their target prices, while most maintained Buy ratings; the average target price from 13 firms stood at about $260, implying roughly 50% upside from premarket levels.
- The bull case rests on orders being sold out through 2028, with RBC estimating demand exceeds supply by about 50%, and product roadmaps including Vera Rubin already planned beyond 2028.
- Organizational risk stands out: about 60 executives report directly to Jensen Huang, and there is no clear internal successor; analysts describe the structure as "unsustainable and unreplicable."
- UBS estimates NVIDIA generates $50 billion to $60 billion in free cash flow per quarter, most of which flows back into the AI ecosystem; a leadership change could create a "pause period" that easily pulls out more than $50 billion in funding.
- Regulatory pressure has not eased with the resignation, with Department of Justice investigations and congressional subpoenas still proceeding; Goldman Sachs notes non-U.S. sales exposure of about 11%, while UBS estimates about 10% of revenue faces risk from tighter rules.
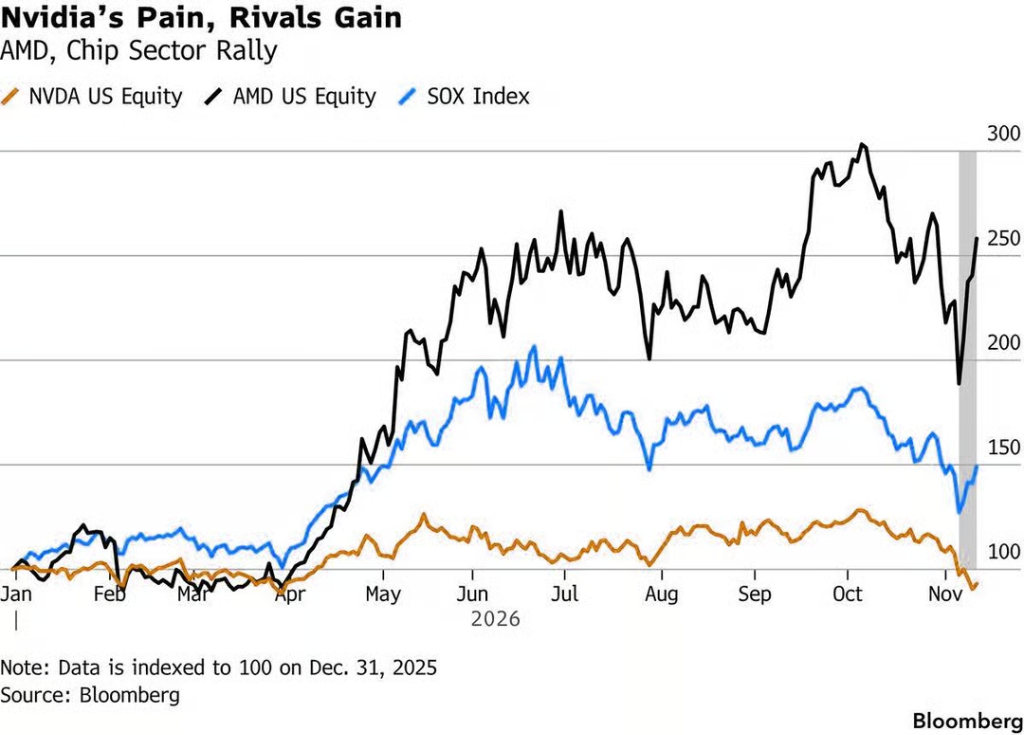
- Competitors are seen as beneficiaries, with AMD and Broadcom named by multiple institutions as direct beneficiaries; the Wall Street consensus floor is around $150, just 4% below the premarket price.
Original author: Long Yue
Original source: Wallstreetcn
Nvidia has announced that company co-founder and sole CEO Jensen Huang, who has led the company for 33 years, has resigned effective immediately and stepped down from the board of directors. CFO Colette Kress will serve as interim CEO concurrently, Synopsys veteran Harvey Jones will become the company's first board chairman, and the permanent CEO selection will consider both internal and external candidates.
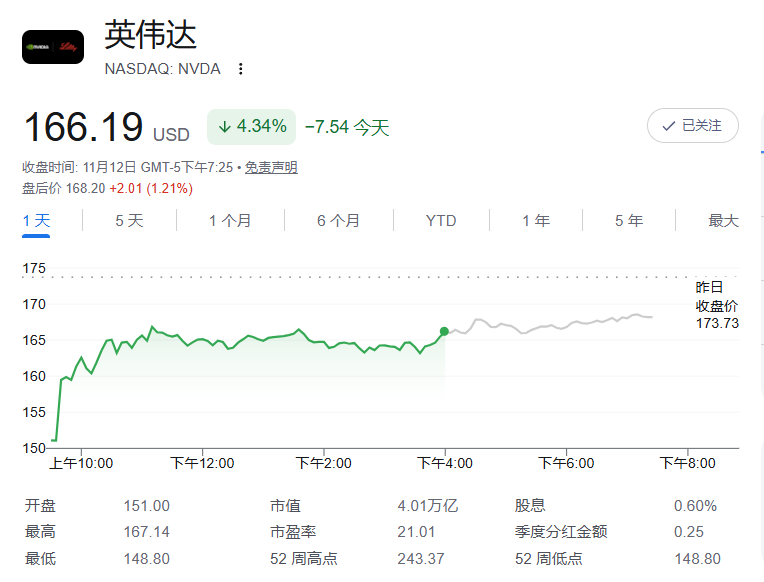
The news broke at 8:48 AM ET on the 12th. By the pre-market, Nvidia's stock had fallen about 10% to around $156, breaking below its 52-week low of $164.27. Roughly $420 billion in market value evaporated in a single day, and the company's market cap has shrunk by about one-third over the past month.
That evening, research notes from 14 Wall Street investment banks flooded into analysts' and fund managers' inboxes.
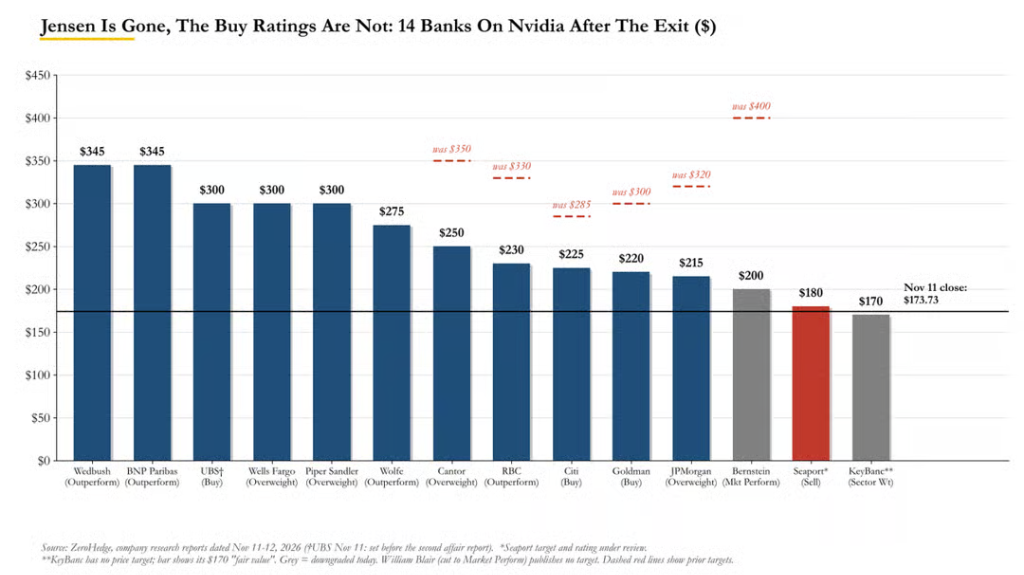
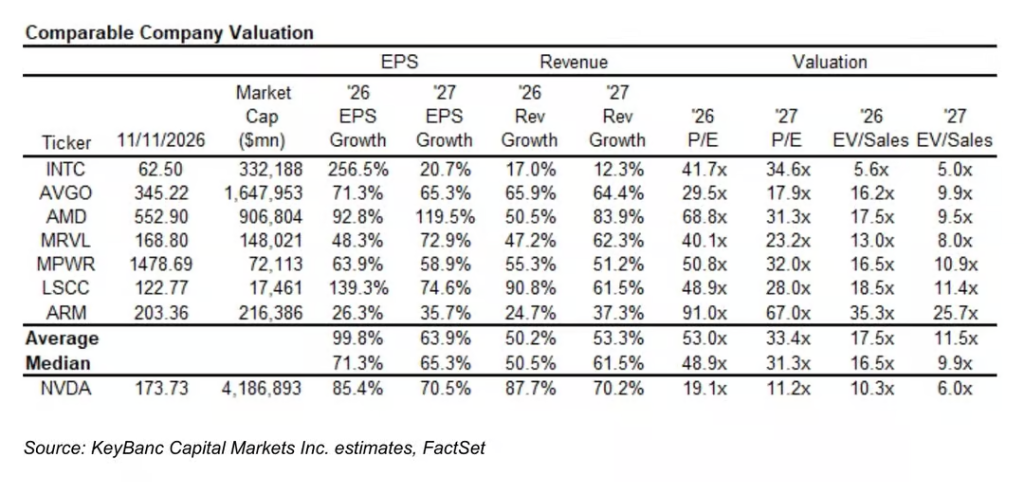
Three downgraded Nvidia's rating: Bernstein, KeyBanc, and William Blair. Six cut their price targets: Bernstein, JPMorgan, RBC, Cantor, Goldman Sachs, and Citi. But the vast majority maintained buy ratings — the core logic being that "orders are fully booked through 2028, and fundamentals are safe in the near term." The average price target across 13 banks is about $260, implying roughly 50% upside from the pre-market price.
On the question of who could succeed Jensen Huang. Seaport's Jay Goldberg wrote in his note — "Simply put, no one can fill Jensen's leather jacket. (No One Can Fill Jensen's Leather Jacket)." Sixty direct reports, and virtually zero successors. Bernstein analyst Stacy Rasgon lamented, "Where would he even find the time?"
The real concern is that the AI ecosystem financing system Jensen Huang built with his own hands will be thrown into sudden doubt with his departure.
Goldman Sachs: The Departure Is Meaningful but Manageable — Like Apple After Jobs
Goldman Sachs chose to wait until the press release was officially issued before putting pen to paper. Analyst James Schneider's characterization: Jensen Huang's departure is a "meaningful but manageable negative event."
He maintained his buy rating but cut his price target from $300 to $220. His valuation logic is clear at a glance: EPS forecasts are untouched, still at $10.00; but the valuation multiple was compressed from 30x to 22x, citing reduced visibility and heightened execution risk during the management transition.
In one sentence, the sell-side consensus: E (earnings) unchanged, P/E (valuation multiple) sharply cut.
Schneider compared the event to Apple losing Steve Jobs. Over roughly 18 months around 2011, Apple's forward P/E slid from about 17x to 12x, bottoming at 9x in 2013, until the market confirmed that the iPhone machine hadn't stopped turning because Jobs left — only then did the multiple gradually recover to about 15x.
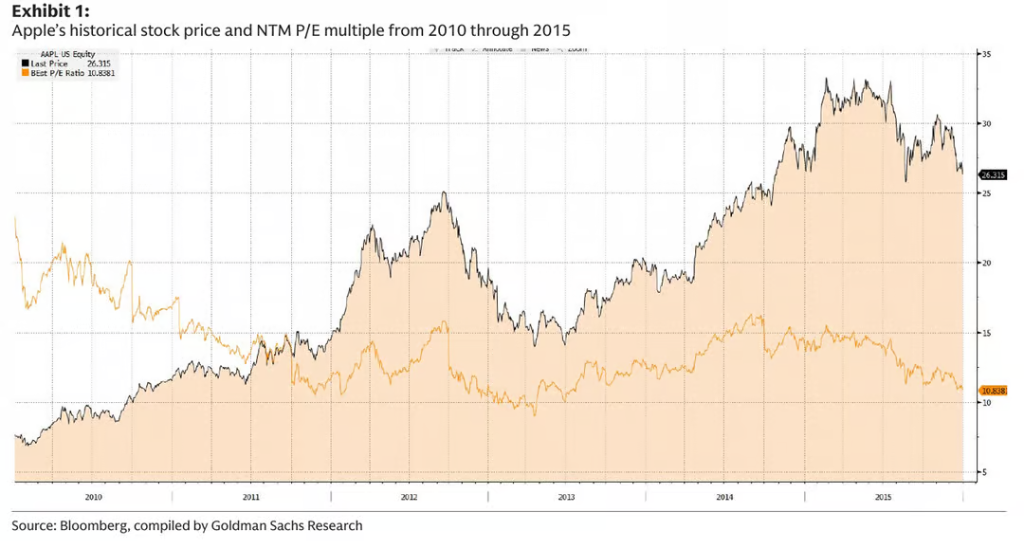
Schneider believes Nvidia's market will go through the same "search for a reasonable multiple" process until leadership and business momentum regain clarity.
But Schneider himself admits the analogy isn't perfect — Apple had a pre-selected successor, no DOJ investigation, and no threat of congressional subpoenas.
Bernstein's Longtime Bull Turns: "Where Would He Even Find the Time?"
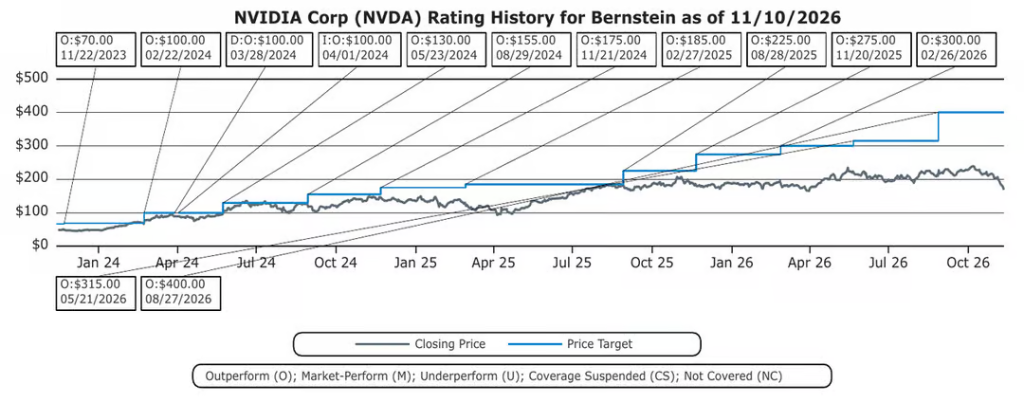
Bernstein's Stacy Rasgon has for years been one of Wall Street's most respected Nvidia bulls. This time, he downgraded the stock to market perform and slashed his price target from $400 to $200. The research note's title was a single sentence: "Where Would He Even Find the Time?"
He wrote:
The new allegations make us feel that the board can no longer possibly keep him in this position (we've seen other CEOs fired for far less...). If the board doesn't act now, the risk going forward will only grow, as more allegations seem likely to surface.
He also used a metaphor — perhaps the most memorable line for Nvidia holders this week:
If you find two ants in the kitchen, the best estimate of the total number of ants in the kitchen is absolutely not two...
The implication: more allegations, more investigations, and what a new leader might discover upon taking office — uncertainty is far from bottoming.
"Sold Out Through 2028" — The Bulls' Core Argument
Bernstein, KeyBanc, and William Blair chose to downgrade Nvidia; Bernstein, JPMorgan, Royal Bank of Canada (RBC), Cantor, Goldman Sachs, and Citi cut their price targets, by amounts ranging from $60 to $200.
But the average price target from 13 banks is still about $260 (median $250). Wedbush and BNP Paribas both have $345 targets — more than double the pre-market price.
Most firms are sticking with buy ratings. The only sell rating comes from Seaport's Jay Goldberg, with a $180 target — ironically, that price is still above the current market price.
So why is almost everyone still bullish?
The bull case boils down to one point: Jensen Huang is gone, but the order book stayed.
Piper Sandler's David O'Connor (overweight, $300 target) put it most bluntly:
The platform and architecture decisions for the next two generations of products are already made, the company's 2027 orders are completely sold out, and 2028 is basically the same. What's being discussed with customers now is 2029 and beyond.
Wolfe's Chris Caso (outperform, $275 target) was even more direct:
If the CEO is asked to step down, we believe fundamentals and earnings will be completely unaffected at least through 2028 — because Nvidia is essentially sold out during that period. The CEO transition will have no impact on orders or even the product roadmap, which is already clearly planned through 2028 and beyond.
RBC estimates that demand currently exceeds supply by about 50%. JPMorgan notes that the volume ramp paths for Vera Rubin, Rubin Ultra, and Feynman are already clear.
In other words, E is fine; the only thing moving is P/E. And there's not much multiple left to compress: at Wednesday's close, Nvidia's 2027 forward P/E was about 10x — Piper called it a 20-year low, William Blair called it an all-time low (just 7x 2028 consensus earnings).
"No One Can Fill Jensen's Leather Jacket": 60 Direct Reports, Zero Successors
If the next two years are safe, what is Wall Street really worried about?
A major concern is organizational structure. Seaport's Goldberg characterized it in one line:
Simply put, no one can fill Jensen's leather jacket. No one can fill Jensen's leather jacket.
He acknowledges that there are many executives capable of running Nvidia, but not one with the same stature across the industry. The problem is both personal and structural:
This siloed structure means any internal candidate will be deeply versed in their own area of expertise while knowing little about most of the rest of the business. This won't be a permanent obstacle, but it will take many quarters to reorganize the company around a new leader. Beyond that, it will be a different company — capable, but far less dynamic than it is today.
Wells Fargo put a number on it: about 60 executives report directly to Jensen Huang. Analyst Quatrochi said outright that this structure is "unsustainable and unreplicable," and could hit coordination speed and time-to-market.
As for the successor shortlist, the most-mentioned internal name is Ian Buck — a 22-year Nvidia veteran who oversees hyperscale and HPC business and is widely regarded as the architect of CUDA; Piper calls him "well regarded by investors." William Blair added Jonathan Ross (Groq founder, TPU architect, who only joined Nvidia last December). On the external side, according to media reports, Apple's Cook, AMD's Lisa Su, Arm's Rene Haas, and Micron's Sanjay Mehrotra have all been mentioned.
JPMorgan split the question into short-term and long-term dimensions:
We believe the most important near-term question for the stock is: whether Nvidia's board can successfully assemble an interim management team capable of maintaining the company's strong execution and continuing to advance the existing roadmap. However, beyond the next 2-3 years, the core focus will shift to: whether the management team has the forward vision to identify the next inflection point in accelerated computing and build a complete system not just of chips, but of ecosystem and platform.
In other words: an interim team can probably still ship the Rubin product line; but being able to foresee "the next CUDA" a decade before everyone else is the real reason this company became a $5 trillion market cap company.
Wedbush reviewed historical precedents: Marvell (ultimately thrived under an external CEO after the founding family exited), Apple (Cook excelled under an existing succession plan), HP and Intel (both lost their CEOs abruptly due to misconduct scandals, had no ready successors, and subsequently fell into what Bryson called "disastrous periods").
But Wedbush's conclusion: no case fully matches the current situation:
In this case, uncertainty could intensify further, because we can't think of any historical precedent that simultaneously satisfies all three elements: a founder CEO with comprehensive sway over the company's direction; a company (and its CEO) so pivotal to technology and tech policy; and virtually no obvious succession plan at the time of transition.
Nvidia Is AI's "Central Bank," and That Bank Has Only One Credit Officer
Wall Street has another major worry: what happens to the money?
Nvidia is not just a chip-selling company. For years, Jensen Huang has continuously channeled Nvidia's free cash flow — roughly $50-60 billion per quarter — into the entire AI ecosystem: equity investments in OpenAI, Anthropic, and xAI; asset backing for emerging cloud companies like CoreWeave; prepayments and equity stakes in optical component suppliers Lumentum, Coherent, and Corning.
UBS's Tim Arcuri ranked this as the top of three most impactful areas:
Nvidia has become a key source of funding for numerous AI industry participants, including emerging cloud service providers, large language model developers, ecosystem partners, and suppliers. We have always viewed Jensen Huang as the central force driving this effort. Even if a new leader ultimately maintains a similar approach, a "pause period" is likely... We estimate Nvidia generates about $50-60 billion in free cash flow per quarter, a large portion of which is recycled back into the entire system. This could easily withdraw $50 billion or more from the system — and precisely at a critical moment when rates are rising and liquidity is tightening in parts of the credit market.
William Blair's conclusion was more direct, and it's the core reason for its downgrade:
Existing contracts will continue to be executed after the CEO change, but what's truly at risk is the next round of deals — and Nvidia's ability to defend market share in 2027 and beyond. Without Jensen Huang, or with him severely constrained by investigations and scrutiny, we believe Nvidia could open a wider gap for competitors like Broadcom and AMD.
Seaport's Goldberg went further, noting that a $500 billion financing platform plan Jensen Huang announced two months ago, involving six private equity funds, has yet to be finalized. He believes that without Jensen Huang, the plan will likely dissipate.
On the day the news broke, CoreWeave fell more than 11% pre-market — on the very same day it was marketing an investment-grade loan of over $4 billion to the market.
Government Investigations Don't Disappear With the Resignation
Jensen Huang's resignation does not mean regulatory pressure is lifted.
The board's independent investigation led by Wachtell's Joon Kim is still ongoing, the DOJ's Megaspeed investigation continues, the House has requested a closed-door briefing on November 18, and Senators Warren and Coons have demanded the submission of relevant records.
Two banks put specific financial quantification on this:
Goldman Sachs notes that Nvidia's FY26 annual report shows total sales exposure to mainland China, Hong Kong, Taiwan, and non-U.S. regions at about 11%, and expects increased scrutiny of operations in jurisdictions such as Singapore.
UBS believes stricter rules could affect shipments to Singapore, Malaysia, and elsewhere, estimating about 10% of revenue at risk.
RBC notes that China accounted for about 1% of data center revenue last quarter and has already been excluded from guidance.
Wolfe takes a different view, arguing that export concerns are overstated, since AI chip shipments to China are already negligible.
Nvidia's Pain, Competitors' Opportunity
Almost all institutions agree on one thing: competitors benefit.
BNP Paribas, Seaport, and William Blair all named AMD and Broadcom as the most direct beneficiaries, as hyperscalers and AI labs now have more reason to diversify their chip sources. BNP Paribas expects custom chips could account for nearly three-quarters of AI accelerator shipments by 2030.
William Blair also pointed to a deeper logic: CUDA's moat is fundamentally built on the high cost of porting code to other chips. Now, AI coding assistants are rapidly driving that porting cost down. Anthropic mentioned in its IPO roadshow materials that it used to take 6 to 12 months to get a new accelerator up and running, while its Claude Mythos Preview model reportedly achieved prompt processing on AMD's MI355X in just about three days.
Analyst Naji cautiously notes that this case is rather limited. But the fact that such news circulated in the same week the founder resigned is itself telling.
Everyone Points to the Same Bottom
So where is the stock bottom?
Wall Street's answer is strikingly unanimous — and based on experience, that unanimity itself is not a good sign.
Cantor believes 9x 2027 expected EPS, corresponding to about $150, is a reasonable bottom. Piper sets $150 as support at





