Who Is Making Money from Digital Dollars? Profit Sharing Among Stablecoin Issuers, Distributors, and Payment Providers


- Key Insight: Stablecoin stock has nearly stagnated while estimated payment transfers have surged, and the truly critical question is how value is distributed among issuers, distributors, and payment processors—not the size of the market itself.
- Key Elements:
- As of the end of September 2026, stablecoin supply stood at $304.9 billion, up only 0.4% year-over-year; Allium estimates payment transfers for the first nine months at $482 billion, up 45.4% year-over-year, but that figure derives from wallet classification and behavioral rules rather than verified commercial payments.
- Tether and Circle together account for 84.7% of supply; USDT accounts for 84.2% of classified payment volume, with liquidity, counterparties, and user habits constituting its payment advantage.
- Circle reported Q2 reserve income of $667.7 million and distribution and other costs of $412.5 million, of which $324.6 million was paid to Coinbase; an RLDC margin of 41.2% shows that distributors capture a substantial share of reserve revenue.
- Payment value extends beyond on-chain transfers: local banking rails, FX conversion, reconciliation, compliance, and failure handling are difficult to replicate; sub-1-cent on-chain fees can coexist with expensive end-to-end payments.
- Tron accounts for roughly two-thirds of adjusted transfer value and 66.6% of classified payments, a position rooted in USDT availability and the provider network rather than low gas fees alone.
- On regulation, the U.S. GENIUS Act and the EU's MiCA affect issuance licensing, reserves, and yield restrictions; proposals must be strictly distinguished from final rules, and applications from approvals.
- Agent payments totaled 68.3 million transactions in Q3 worth just $3.7 million—transaction count doubled while total value fell, proving technical feasibility but lacking evidence of sustained payment demand.
Original article frominsights4vc
Compiled by Fast Courier @Odaily
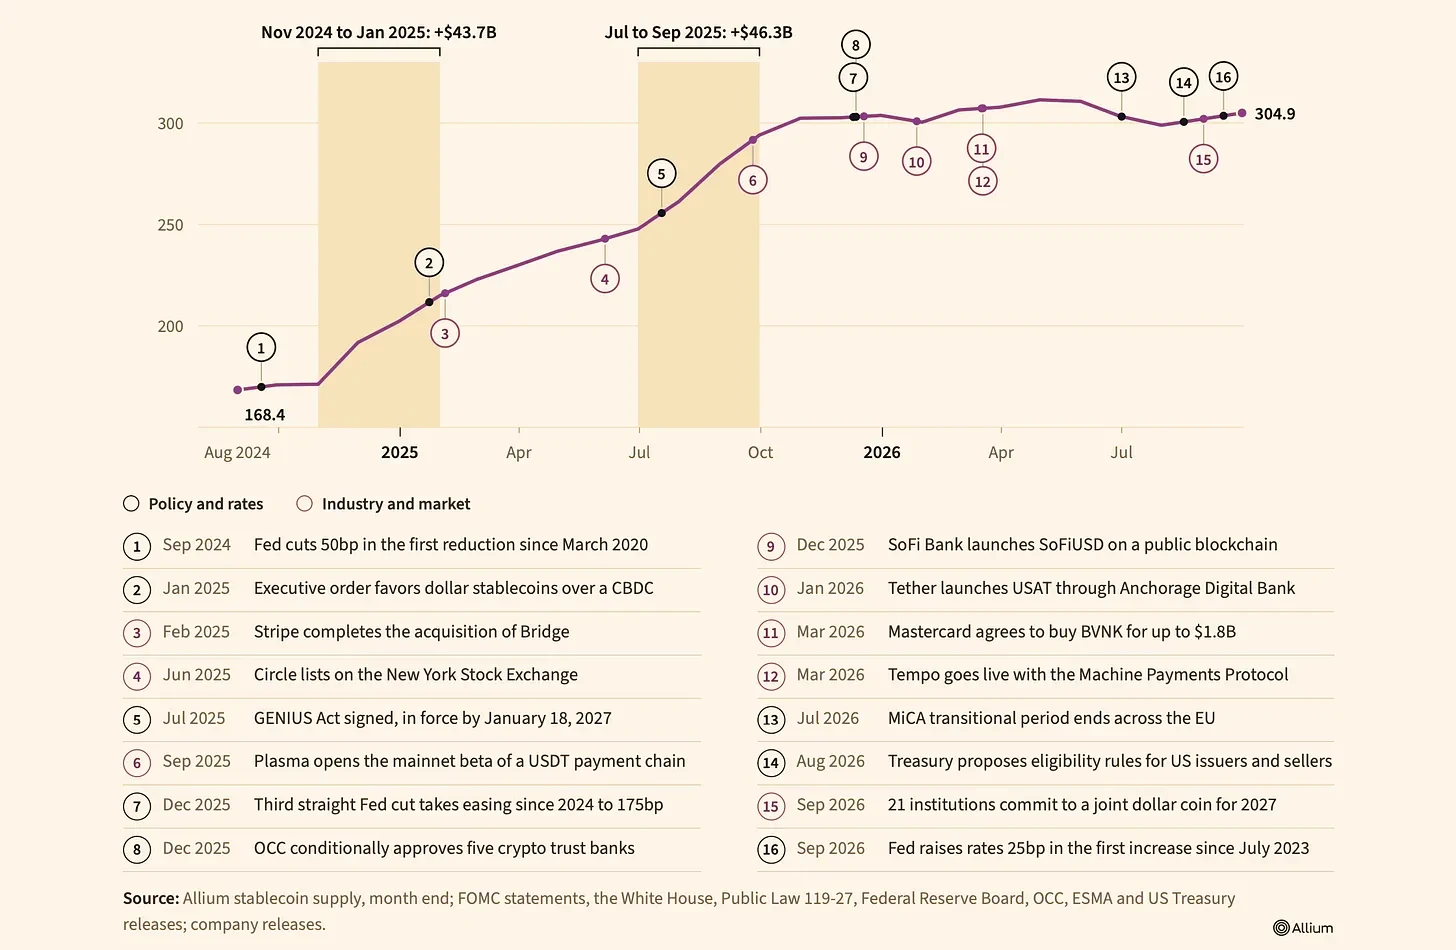
As of the end of September 2026, the circulating supply of stablecoins stood at $304.9 billion, only 0.4% higher than the level in December of the previous year. Yet Allium classified $482 billion in stablecoin transfers during the first nine months of the year as payments, up 45.4% year-over-year from 2025. The stock has barely changed, while the estimated volume used for payments has grown substantially.
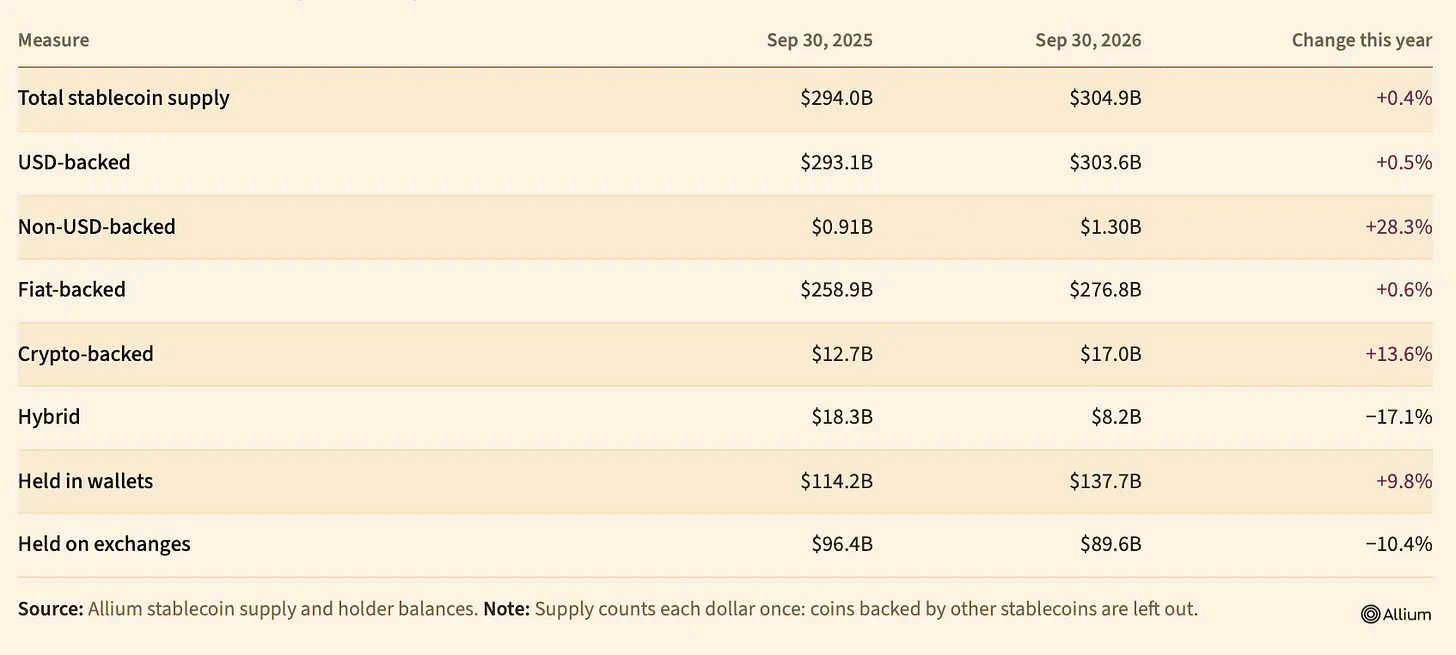
Stablecoin balances
For investors, a more worthwhile question than "how big can the stablecoin market become" is: when digital dollars move, who exactly is making money.
Imagine a customer who receives wages in stablecoins, keeps the balance in a payroll app, and eventually spends it through a card. The stablecoin issuer earns yield on reserve assets. The app owns the customer relationship. A payment service provider handles conversion and settlement. Multiple companies participate in the same transaction, but their economic models can be entirely different. The issuer with the largest supply is not necessarily the one capturing the most value.
There is a trap in the growth numbers. Allium's $482 billion payment estimate comes from wallet classification and transaction behavior, not verified invoices or merchant receipt records. Its methodology excludes a large amount of automated activity, but it cannot determine the commercial purpose of every transfer. When companies use transaction volume to support valuations or claim that their share of global payments is rising, this distinction matters. [1–3]
Economics explains more than transaction volume. Issuers earn a function of reserve balances and prevailing interest rates. Distributors negotiate their share of that revenue. Payment processors charge for moving funds, converting currencies, and connecting customers to banking infrastructure. The same dollar can generate revenue at multiple layers, making it easy to overestimate the size of the industry's total profit pool.
And the most valuable part of a payment may not be the on-chain transfer at all. Access to local banking rails, reliable currency conversion, reconciliation, compliance, and handling of failed transactions remain difficult to replicate.
This report aims to answer: where the money goes, which companies have the bargaining power to keep it, and whether their profitability can withstand lower interest rates, thinner margins, and intensifying competition.
1. The $98 Trillion Figure Cannot Describe a $98 Trillion Payments Market
Blockchains can reliably record the transfer of tokens, but they capture almost no evidence of the commercial obligations behind those transfers. A supplier payment and a market maker's inventory rebalancing may look identical at the event level. Automated paths through smart contracts multiply records; netting compresses several purchases into one. This distinction determines what the denominator should be in every debate about "stablecoin commerce."
Allium reports that gross stablecoin transfer volume in the first nine months of 2026 was $97.9 trillion. Of that, $59.3 trillion was classified as infrastructure activity, $36.2 trillion as trading venues, leaving about $2.4 trillion in adjusted activity. It then classified $482 billion—roughly one-fifth of the adjusted total and less than 0.5% of the gross figure—as payments. Each step is an analytical filter. The $482 billion is a payment estimate derived under Allium's coverage of assets, entities, and classification rules, not an independent tally of settled commercial obligations. [1]

Stablecoin activity
These filters are a substantial improvement over gross transfer volume. But their precision is unknown. Allium combines proprietary labels, wallet classification, and behavioral rules, with the first matching classification rule determining the outcome. A transfer between two identified businesses could be settling an invoice, rebalancing treasury accounts, or moving funds between affiliated entities. Allium has not published a value-weighted error study sufficient to estimate the false positive and false negative rates of its $482 billion payment series.
A working paper from the Bank for International Settlements (BIS) makes this problem more concrete. Researchers examined 593 million stablecoin transfer events across 141 million Ethereum transactions and found that nearly 60% of events were nested within complex multi-action transactions. The sample covered three dollar stablecoins on Ethereum in 2025. It demonstrated how dangerous it is to "count events as independent payments," but it did not provide any adjustment coefficient for Allium's much broader payment dataset. [2]
Historical comparison has a second complication. On September 18, 2026, Visa updated the classification methodology of its on-chain data dashboard, expanding the sample space of labeled addresses from approximately 15 million to 600 million and adding routing heuristics. More automated activity was identified and excluded. Visa's dashboard uses Allium's inputs, so agreement between the two series cannot be considered independent cross-validation. Growth rates need to be built on the same version of labels and exclusion rules. [3]
2. Two Issuers Dominate an Increasingly Crowded Market
As of the end of September, Allium attributed $184 billion in circulating supply to Tether and $74.2 billion to Circle. Together they account for approximately 84.7% of the $304.9 billion total. Tether's balance declined by $3.1 billion in the first nine months of 2026, while Circle's fell by about $864 million. Smaller issuers collectively offset the decline of the top two. The number of issuers with circulating supply exceeding $1 billion grew from 11 to 15. The market has become more crowded, but concentration has not noticeably decreased. [1]
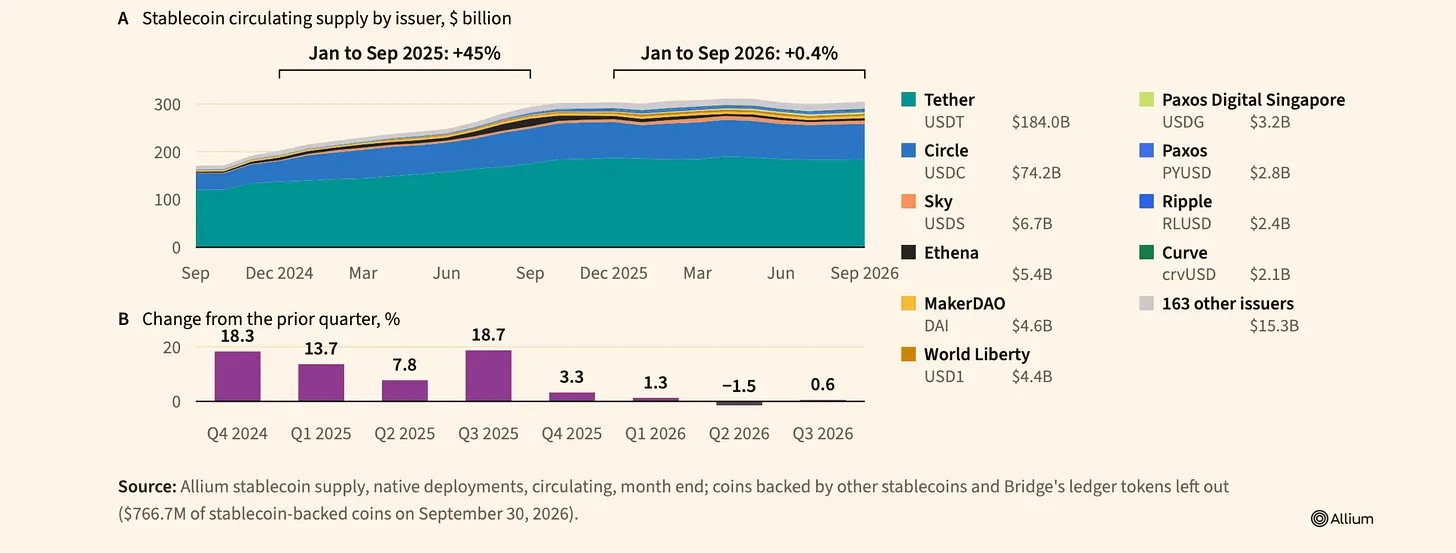
Stablecoin circulating supply by issuer
Beneath the flat total, expanding issuers collectively added $11.4 billion, almost exactly offsetting a $10.2 billion decline elsewhere. USDG, RLUSD, USD1, and newer products gained balances, partly at the expense of established tokens. Issuer-level data cannot determine how much of this flow represents new customer demand versus treasury migration, incentive subsidies, or switching from one dollar token to another. Several billion dollars in new issuance may simply be relabeling an existing dollar position. [1]
Similarly, not all branded tokens stack on top of their backing assets. Some corporate-branded stablecoins hold existing stablecoins as reserves. Counting both the wrapper layer and the underlying coin would create false market growth. Allium excluded such structures from its headline supply figure, but its report gives two different September values for this exclusion: $766.7 million in the issuer section and $872 million in the branded token section. The discrepancy may stem from scope or treatment differences that the provided report does not reconcile. We therefore use the published totals and do not recalculate branded supply. [1]
Idle balances deserve attention. A digital dollar may sit as collateral in an exchange account, may reflect a household's savings preference, or may support a yield-bearing reserve portfolio. An issuer's annual revenue depends more directly on the level and persistence of these balances than on how many transfers occur in a given week. There is a huge difference between a customer choosing to hold a token for six months and a partner stocking up for a marketing campaign.
Tether's lead has payment-dimension implications. Under Allium's classification, USDT accounted for $406 billion, or 84.2%, of January-to-September payment value. That is even higher than its concentration in the issuer supply market. It points to a powerful combination of liquidity, established counterparties, and customer habits. It does not reveal Tether's share of payment processing fees—the issuer, the network, and the company converting stablecoins into local currency may be different entities. [1]
3. After Distributors Take Their Cut, How Much Reserve Income Remains
For a conventional reserve-backed stablecoin, the starting point for profitability calculation is average eligible reserves and their realized yield, then subtracting what the issuer pays distributors and other service providers, and then operating costs. Period-end supply is an imperfect proxy for profitability, especially when interest rates or partner structures change. A one-percentage-point decline in reserve yield can have a larger impact on profitability than several quarters of moderate payment growth.
Circle discloses this split unusually clearly. In Q2 2026, the company reported $667.7 million in reserve income and $33.6 million in other revenue, for total revenue of $701.3 million. It spent $412.5 million on distribution, transaction, and other costs. The remaining $288.8 million represents a 41.2% "revenue less distribution costs" (RLDC) margin, which is before the company's operating expenses and is not net income. Of that quarter's distribution expenses, approximately $324.6 million was related to Coinbase alone. The conclusion is direct: an issuer can manage a large reserve book while a substantial portion of the resulting revenue flows to the company that brought in the balances. [4]
This arrangement is economically rational. Distributors who bring customers and persistent balances have bargaining power. For issuers, paying for that access may be cheaper than building consumer wallets, payment platforms, and regulatory relationships across multiple markets themselves. But distributors can also switch providers or bring issuance in-house. An issuer's moat therefore depends on the cost and friction of replacing it, its liquidity network, its security perception, and the brand of the token itself.
Consider a deliberately simplified sensitivity calculation. $1 billion in average reserves at a 3% realized return generates $30 million annually before costs. If the issuer retains half of reserve income after revenue sharing, it keeps $15 million before its own expenses. A one-percentage-point decline in realized yield reduces this retained amount by $5 million, assuming balances and sharing ratios remain unchanged. Raising the partner's share by ten percentage points at the original yield reduces retained revenue by another $3 million. These are arithmetic examples, not estimates of any company's contracted margins.
Tether's disclosure profile is different. It reported approximately $1.5 billion in net operating profit for Q2 2026, and its BDO-attested reserve materials showed a reserve surplus of $4.11 billion. In August, Tether announced that KPMG had issued an unqualified opinion on Tether International's 2025 financial statements. This reported annual audit should not be conflated with quarterly reserve attestations; this publication has not independently reviewed the signed audit opinion. Similarly, continuing to claim that "Tether has never undergone a financial statement audit" while ignoring the above announcement would be an outdated statement. These figures and attestation scope are not directly comparable to Circle's publicly filed quarterly financial reports. [5–6]
4. Distribution Contracts Determine Who Keeps the Spread
Much of the current competition is happening inside familiar software. Wallets choose default dollar balances, exchanges direct liquidity, and treasury platforms integrate specific tokens into payment flows. These decisions determine which reserves get funded and where customers build habits.
Global Dollar Network describes rewards for partners based on USDG minting, custody, and acceptance. Open USD (OUSD) offers another structure: Open Standard created the product, Bridge is its issuer, and Stripe integrates OUSD into its payment and financial infrastructure. Eligible Open Standard partners can receive rewards tied to their OUSD activity. Stripe is one of Open Standard's founding companies, not the sole owner of the program. These arrangements illustrate how distribution access can claim a portion of reserve income, but public descriptions cannot determine actual realized margins or partner retention. [7–8]
Branding creates another accounting problem. A partner can present its own dollar product while another entity issues the underlying liability, manages reserves, and handles redemptions. The product's visible name reveals almost nothing about these contractual roles. When analyzing supply, look through the wrapper layer to the backing assets; when analyzing profitability, follow the agreements that allocate investment income, rewards, and service fees.
Consolidation can improve an operator's position, but ownership does not guarantee attractive margins. Mastercard said in August that it had completed its acquisition of stablecoin infrastructure provider BVNK. Its strategic logic is to gain orchestration capabilities spanning traditional payment systems and digital assets. The announcement establishes a completed transaction, not realized cost advantages, integration results, or a new revenue run rate. Similarly, Stripe's ownership of Bridge gives it the ability to combine issuance infrastructure with products used by merchants and developers. Whether these combinations can defend pricing depends on service reliability and the value of customer workflows. [8–9]
5. Enterprise Payments: A Large Estimate with Limited Verification
Allium attributed $134 billion in classified payment value during the first nine months of 2026 to business-to-business (B2B) transfers. Consumer-to-business transfers were $112 billion, and business-to-consumer was $63 billion. The remaining $173 billion was consumer-to-consumer. Adding the three categories involving at least one business party gives $309 billion, or about 64% of reported payment value. The amount actually received by enterprise-labeled wallets is narrower: B2B plus C2B equals $246 billion, or about 51%. Allium's enterprise labels also include institutions, meaning neither figure can prove equivalent trade invoicing. [1]
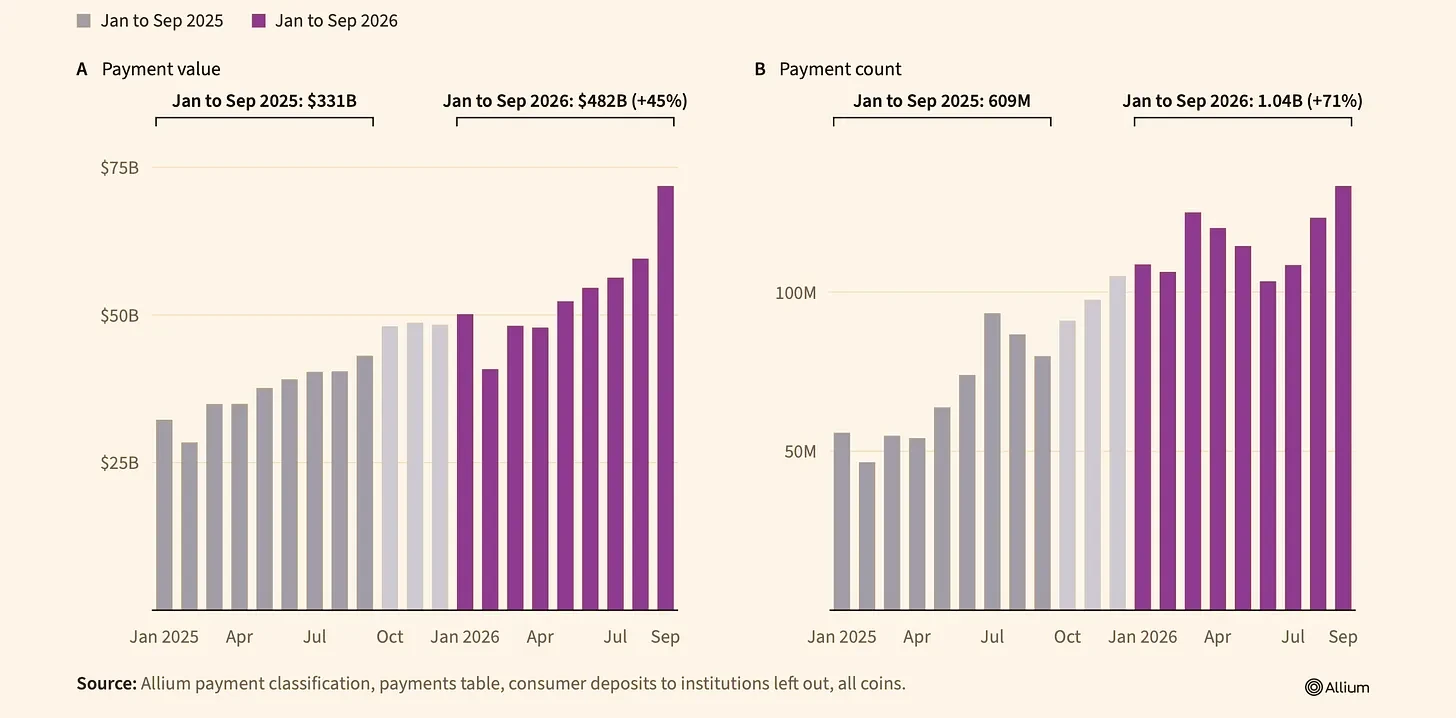
Monthly stablecoin payment value and count
Allium also tags transfers with purpose: procurement $111.8 billion, business operations $116 billion, payroll and disbursements $29.3 billion, peer-to-peer activity $172.5 billion, and another $52.3 billion unlabeled. These amounts provide useful guidance on transaction patterns. But determining what proportion of the model's interpretation corresponds to a completed commercial obligation requires verified invoices, payroll records, and payment receipts. [1]
The most promising near-term payment applications are likely to appear where existing financial infrastructure is expensive or difficult to use. An importer may need to pay a supplier in dollars when its local bank cannot provide foreign exchange in time. A multinational may want its subsidiaries to be able to reallocate cash outside local business hours. A platform may need to distribute earnings to contractors across multiple markets. Such needs vary enormously by corridor, payment amount, recipient requirements, and local licensing. Stablecoins may solve one part of the task while leaving other frictions in place.
The most commercially interesting benchmark is repeat usage by the same verified businesses after incentives and promotional pricing end. A supplier payment product should be evaluated by matched invoices, funded customers, completed settlements, repeat months, and contribution after compliance and payment costs. A treasury platform can be valuable even with relatively few transactions because it reduces idle balances and operational delays. Counting addresses or counting transfers would obscure both types of economic return.
6. The Payment Fee That the Blockchain Cannot Show
Low network fees are a genuine technical achievement. Allium's September comparison shows that among the eight networks listed, seven had transfer fees below 1 cent, with Ethereum higher at 13.52 cents. These are network execution costs under the study's selected methodology, excluding local currency conversion, bank charges, prefunding, sanctions screening, fraud, failed payments, and customer service. Tron is not included in that chart because its resource and fee mechanism is not directly comparable. [1]
Businesses buying payment services care about how much money ultimately reaches the recipient usable, and when. Relevant costs include explicit fees, realized FX spreads, the time value of funds tied up with intermediaries, handling of exceptions, and the expected cost of failures. The World Bank's remittance price methodology similarly treats exchange rates and speed as core comparison items alongside transfer fees. Therefore, an on-chain transaction costing less than 1 cent can perfectly well coexist with an expensive end-to-end payment. [10]
Consider a $100,000 cross-border supplier invoice. If the stablecoin leg costs only $0.01 but the service provider charges 40 basis points for conversion and disbursement, the quoted variable cost is $400. If a bank quotes $250 under comparable delivery conditions, then on this basis the on-chain path is not cheaper. But if the bank requires two days of prefunded cash while the stablecoin path can disburse same-day, the conclusion may reverse. A proper comparison should price the days of funds tied up at the customer's actual cost of capital, verify availability in the receiving market, and hold service levels constant. None of the above amounts are market-wide cost estimates.
Working capital may matter more than the quoted payment fee. A multinational paying daily may have to preposition cash with multiple local intermediaries. A reliable stablecoin corridor can release some of those balances and improve capital efficiency. But in markets with thin liquidity, service providers may have to hold extra inventory for poor offshore liquidity and settlement delays. These savings should be incorporated into the treasury model, measured against actual funding needs and transaction volumes.
Processors face a harsher calculation. Suppose a processor earns 10 basis points in gross service revenue on $10 billion in eligible annual flow, or $10 million. Counterparty and variable expenses consume 6 basis points, or $6 million, leaving $4 million in contribution before fixed overhead and losses. If competition compresses the gross take rate to 8 basis points while costs remain at 6, contribution at the same flow falls to $2 million. The processor would need to double comparable flow to preserve the original $4 million contribution. This example assumes constant unit costs and excludes any additional operating leverage; it is not a quoted industry take