


When the market is down, how do crypto VCs view the current market?


Original author: IGNAS - DEFI RESEARCH
Original compilation: Deep Chao TechFlow
Take a look at the chart below. The correlation between the price of Bitcoin and the amount of funds raised in the crypto market is truly amazing. As the price of Bitcoin has fallen, so has the amount of money raised.
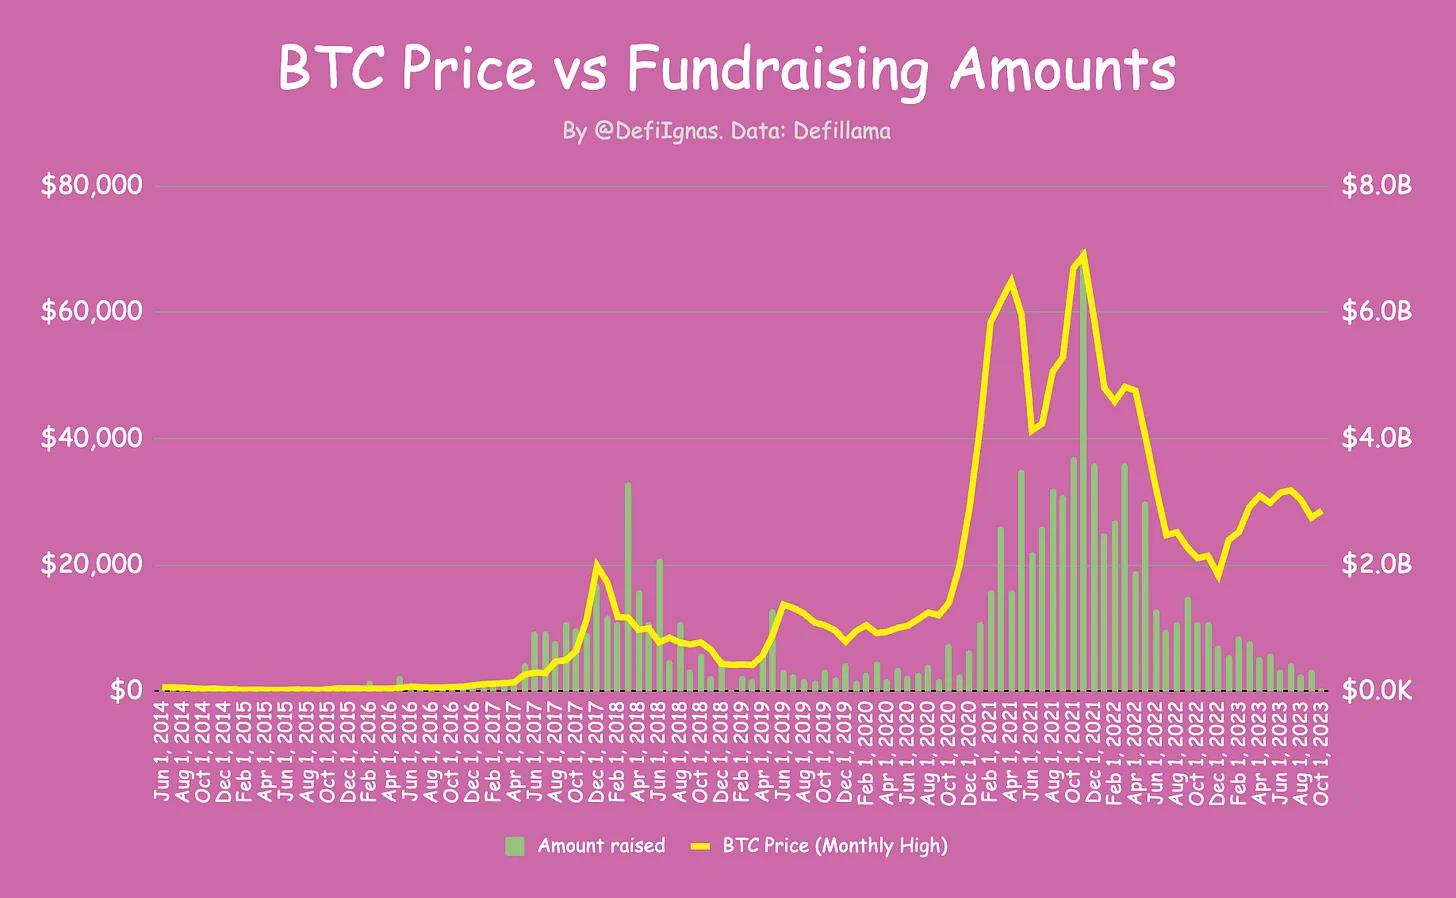
Interestingly, while Bitcoin and Ethereum prices are above their 2018 bull market peaks, funding has fallen back to pre-2020 levels. Bitcoin has actually rebounded from its 2022 lows, but funding continues to decline.
Venture capital is often considered the market leader, making smart, forward-looking decisions. So why does venture capital seem to be following the general trend of the market, rather than leading it?
When the market recovered slightly, the amount of funds raised had fallen to the level of 2018-2019. Do they know something that we ordinary retail investors don’t?Isn’t it time to “buy the dip” now that valuations are depressed?
To find out, I reached out to several crypto VC firms and DeFi project founders who have recently received funding. They are Sachi Kamiya from Polygon Ventures, Etiënne from TRGC and an anonymous angel investor (hereinafter referred to as Mr.Anon) who agreed to provide their views.
Jaimin, founder of Caddi, also provided valuable insights from the perspective of a DeFi builder. Caddi is a browser extension for saving money in DeFi Swaps and protecting you from scams. He recently raised $650,000 in funding from venture capital firms including Outlier Ventures, OrangeDAO and Psalion VC, as well as angel investors including Layer Zeros Bryan Pellegrino, Nansens Alex Svanevik and Pentoshi.
How bad is it?
The image below provided by CoinCarp provides a different perspective. With a total of $18.6 billion and 1,053 deals, the fundraising situation looks much better than in 2020.
However, the chart includes Web2 deals, such as the $6.5 billion raised for Stripe, which are not relevant to us.
In terms of my beloved DeFi, there have been 175 DeFi funding rounds raising a total of $779 million, with an average of $4.4 million per round. Thats a significant drop from last year, when 341 rounds were raised totaling $3.56 billion, with an average of $10 million per round.
As a result, funding is tighter and the average amount of funding per round has dropped by more than 55%.
Unfortunately, the performance of the DeFi field is actually the second worst industry after NFT. In the past 365 days, DeFi protocols raised only $1.14 billion, while CeFi startups raised $2 billion. Where is our decentralized future?
Looking closer, exchanges dominate DeFi financing. They accounted for 38% of all financing in Q3 2023.
Overall, several crypto companies are laying off employees due to a lack of funds, with Yuga Labs, Ledger, and Chainalysis announcing large-scale layoffs last week.
Despite the bear market, a handful of protocols have managed to raise significant amounts of capital. This gives investors hope that they haven’t given up on crypto and DeFi entirely. In fact, Blockchain Capital recently raised $580 million to invest in DeFi, gaming, and infrastructure projects.
When asked about the current funding market from the perspective of DeFi builders, Jaimin commented that “just as the macro conditions have not changed, this market is also in the worst state in the past few years.” Polygon Ventures’ Sachi expressed a similar sentiment, saying:
The overall sentiment in crypto venture capital is bearish. Due to negative sentiment, fewer early-stage projects receive capital.
Mr. Anon Angel investors use figures to express that maybe only 10% of the trading volume during the bull market.
Compared to past bear markets, Etiënne noted that unlike 2019, there is real money sitting on the sidelines. What about 2019? Absolutely zero.
This is why the market still offers huge opportunities. Mr. Anon, Etiënne, and Sachi all agree that now is a great time to find deals without crazy valuations, with Sachi noting that investors “can take the time to do due diligence on each project, but venture capital is more focused on user metrics and real adoption.”
Interestingly, this is the hardest thing for startups to do. Jaimin said, “Investors want to see exponential growth, whether it’s revenue, users, TVL or in our case, transaction volume.
Achieving sustainable growth in this market is very difficult, there is little influx of new people, volatility is low, prices are depressed, and overall sentiment is bad. Vision alone is not enough.
Sachi concluded optimistically, “It makes sense to invest now because some of these projects will do well in the next round.”
Why do we need crypto venture capital?
There is a lot of distrust, hostility, and negativity toward crypto ventures in the crypto community. The main reason is obvious: to use retail investors as an exit for liquidity.
Algod believes that the best projects will be those that do fair issuance without venture capital because people realize they don’t want to be exiting liquidity. In another post, he also shared that venture capital funding will be a bearish catalyst compared to 2021, “Prioritizing the community will be key and projects start to realize that deal volume is not driven by venture capital, but Driven by ordinary investors.”
This view is shared by some non-crypto investors.
For example, in an interview with Bloomberg, Jason Calacanis, an angel investor in Robinhood, Uber, and Superhuman, warned that “scam” VCs in cryptocurrencies will have serious consequences if they sell crypto tokens to retail investors.
Calacanis believes many of these tokens are securities that venture capital firms are reselling to unsuspecting retail investors. He predicted that companies and venture capital firms that knowingly sell “worthless” tokens will face major lawsuits and even criminal charges.
So…can we skip crypto ventures altogether? The biggest concern is how fair these fair issuances are.
According to Mr. Anon, “A fair issuance is not fair because the team and insiders know about them before the actual issuance and can snatch liquidity.” Jaimin is skeptical, saying that the issuance now is unlikely to be a real fair because people can manipulate it in various ways, and mutual dumping will always exist.
Etiënne from TRGC agrees: “Fair start or not, the motivation to make money remains the same. Retail traders are not innocent. Retail traders are market gamblers with smaller funds.”
That said, Sachi said that for founders who already have experience running crypto companies, a fair offering could be effective. All respondents seemed to agree that fair launch is a tough game for first-time founders and those without initial resources.
Personally, I like fair distribution. The birth of YFI and INV is still my best memory of the 2020 DeFi Summer. I hope well see some truly fair issuance in the next bull run.
But I would venture to say that venture capital plays an important role in crypto, providing initial infusions of capital, mentoring, providing networking opportunities, and even boosting the credibility of projects across the industry.
What can we learn from crypto venture capital?
This is the main question that prompted me to write this article.
As you can see from the Bitcoin vs. Funding Amount chart, the amount raised seems to be following the Bitcoin price trend rather than leading the trend, which is a bit disappointing. Savvy VCs are expected to predict market movements and increase the amount of money they raise at the end of a bear market, allowing them to cash out in a bull market.
Sachi provides valuable insights:
Not all venture capital follows market trends. Some VCs, especially in the United States, tend to invest based on market trends. But thats not the case for many Asian VCs - in fact, they become more active during bear markets because good opportunities exist.
Mr. Anon, the angel investor, added that the project raised funds during the bear market but will make announcements when it makes more sense for them.
Then venture capital also has a token lock-up period, which makes the cash-out strategy even more complicated. I think investing during a bear market would allow VCs to sell their tokens at a profit when the lock-up period expires. On the other hand, if VCs invest during a bull market, they may need to sell during a bear market, further depressing already depressed altcoin prices.
The timing seems elusive. Mr. Anon shared:
There is uncertainty about TGE. I think at least big projects will wait for the best time to start, and with a good lock-in structure, it will still be possible to make a profit after the cliff allocation ends.
Sachi from Polygon Ventures told me that when considering unlocking, they will consider the quality of the project differently and prefer a shorter lock-up period. But they will consider how native the team is to cryptocurrency.
Managing tokens requires skills (e.g. listing on an exchange, market maker, etc.). The more native a team is, the more likely the project is to be successful in the long term.
So, what lessons can we learn from venture capital?
Etiennes answer is quite straightforward:
Haha, no.
Don’t blindly trust venture capital. I mute 95% of my ventures on all platforms. I highly recommend old foxes like Howard Marks, Nassim Taleb, Warren Buffett, Stan Druckenmiller, Ed Thorp, Jim Simons, Mark Spitznagel and others.
There is an exception here. I would only listen to venture capitalists like Mike Moritz or Doug Leone who have a 30-year track record. Instead of I made money with token XYZ, now let me teach investing people, they are the worst. We cannot learn anything from them.
Mr. Anon’s advice is simple. Dont put all your eggs in one basket. “Even some VCs have made this mistake and lost a lot of money.” And as crypto users, “we should strive to educate people about the project, share feedback and suggestions, etc. This is very valuable to authoritative users.”
Sachi offers practical advice. Its important to ask the right questions and do your own research. For example: Are these real user metrics? Can the founders be trusted?
Retail investors should understand that when a project makes an announcement (for example: a partnership with a large company or project), there is more than meets the eye. Completing transactions and incentives involves many moving parts that may not be part of the announcement (e.g.: token swaps, grants, incentives, etc.). Retail investors should always consider whether a protocol is truly being adopted organically and invest accordingly.
— Sachi Kamia of Polygon Ventures
Jaimin also emphasized risk management:
I recommend people to learn new knowledge, read and keep learning, DeFi is developing very quickly and gaining knowledge in an area of interest can bring many benefits: you can reason and create value for the project.
These are not investment advice, but it seems like us retail investors could do better in crypto. Of course, like retail investors, venture capital investors also experience FOMO and investment hot spots. My advice is to do your own research and understand the narrative rather than just following orders.





