


LD Capital: Bubble Mart's performance has rebounded significantly, optimistic about the growth contributed by IP+ and the outbound strategy.


Original author: Lisa, LD Capital
1. Company Overview
Beijing POP MART Cultural Creative Co., Ltd. was established in 2010 and is a leading trend culture and entertainment company in China. Over the past ten years, POP MART has built a comprehensive operation platform covering the entire industry chain of trendy toys in five areas: global artist exploration, IP incubation and operation, consumer reach, trendy culture promotion, and innovative business incubation and investment. On December 11th, 2020, POP MART International Group Limited was listed on the Main Board of the Stock Exchange of Hong Kong.
On August 22nd of this year, POP MART (09992.HK) released its mid-term performance for 2023, with significant recovery in core business indicators, and a net profit of 477 million yuan, surpassing the total for the entire previous year. Overseas business continued to grow rapidly, with a year-on-year revenue increase of 140%. According to historical performance data, POP MART's performance in 2022 ended the previous trend of continuous growth, with revenue increasing by only 2.67% and net profit decreasing by 44.32%. POP MART's stock price also plummeted from a peak of over 100 Hong Kong dollars, dropping by 70%. As the COVID-19 pandemic recedes and the socio-economy begins to recover, the financial report data provided by POP MART seems to indicate that it has emerged from its "darkest moment." POP MART Chairman and CEO Wang Ning stated at the performance conference, "We are confident that our overseas business will reach 1 billion yuan this year, and we are confident that next year's overseas revenue will exceed the pre-IPO revenue of the entire group in 2019, equivalent to creating another POP MART overseas," which has brought strong expectations to investors.
2. Business Data
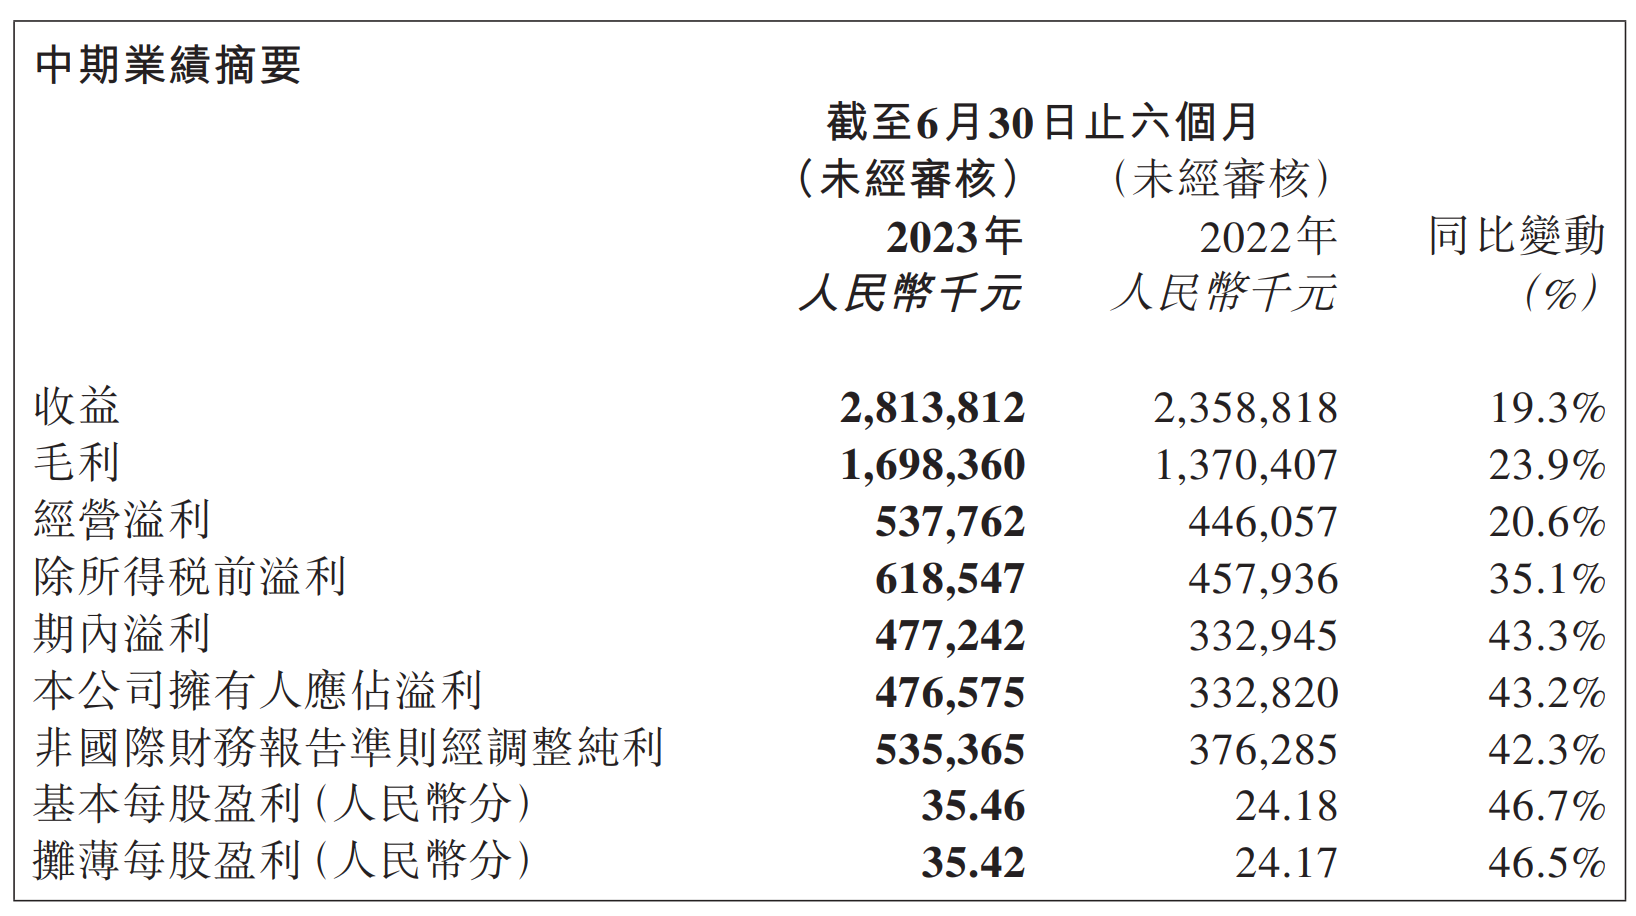
23 H 1 Bubbles Mart achieved revenue of 2.814 billion RMB, a year-on-year growth of 19.3%, with adjusted net profit of 535 million RMB, a year-on-year increase of 42.3%. Net profit attributable to shareholders was 477 million RMB, a year-on-year increase of 43.2%.
Significant recovery in the domestic offline market, with skyrocketing sales through the online Douyin channel.
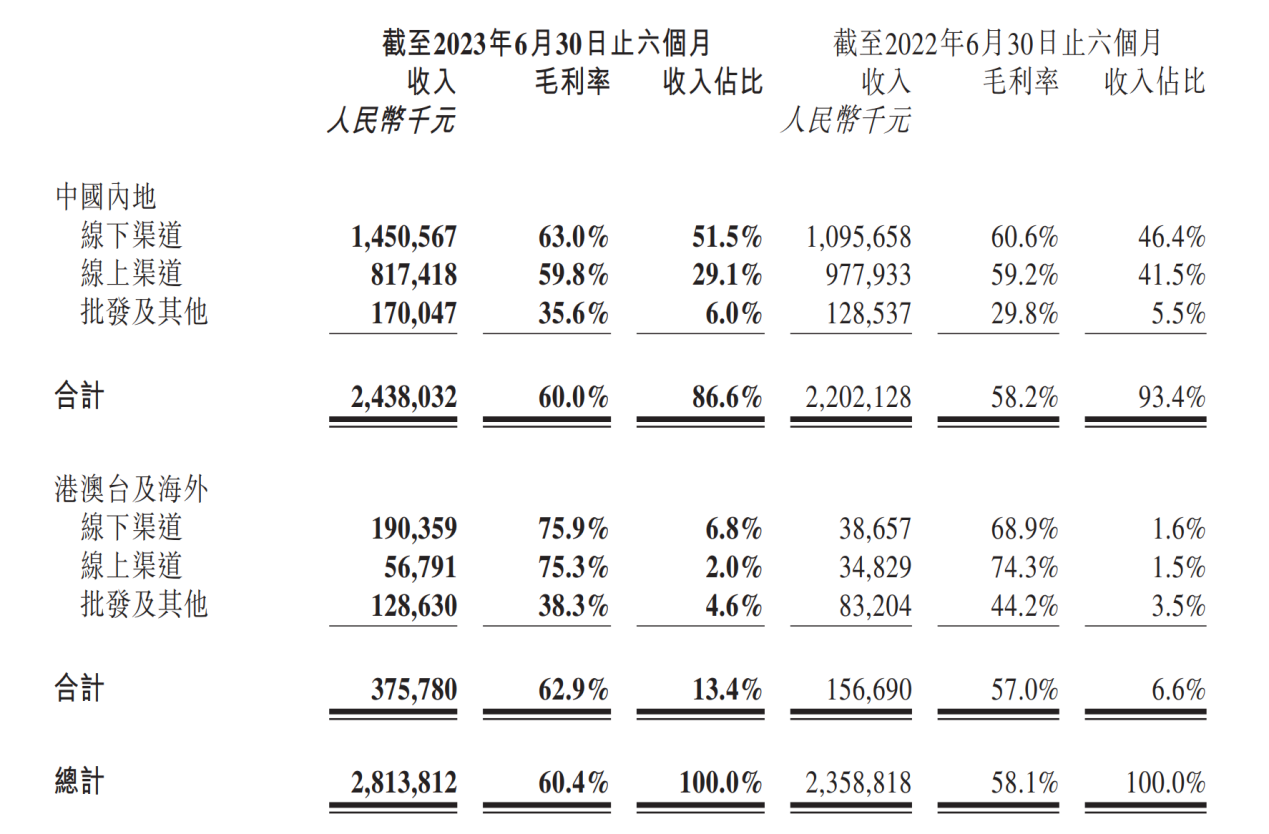
Mainland China's H1 revenue was 24.38 billion yuan, a YoY growth of 10.71%. The domestic user base has grown steadily, with an increase of 4.384 million users in H1 2023, bringing the total number of members to over 30 million at 30.388 million. Membership contributed to 92.2% of sales, with a repeat purchase rate of 44.5%.
By sales channels:
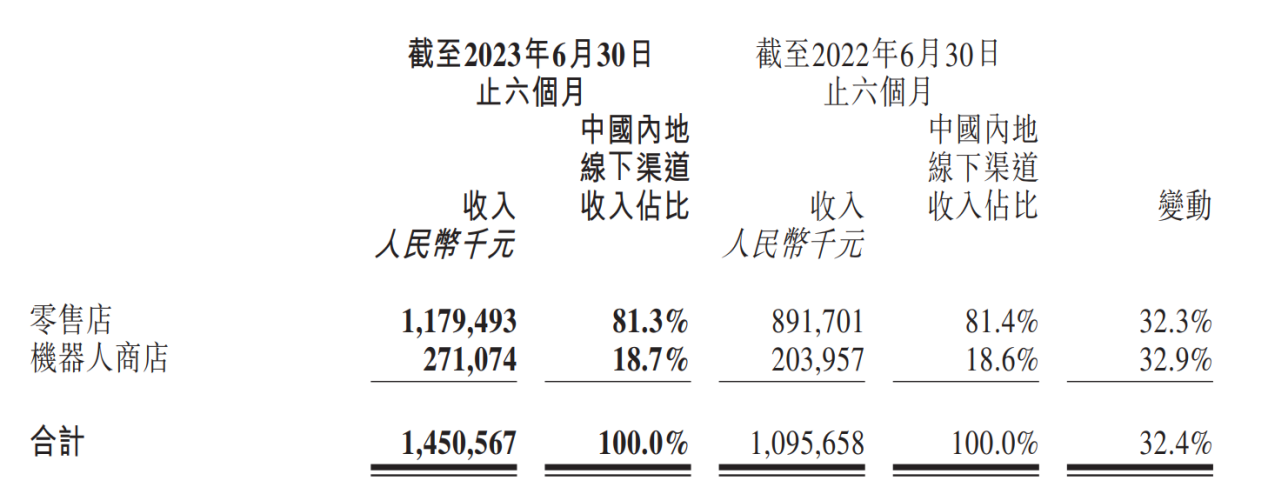
(1) Offline revenue was 14.51 billion yuan, accounting for an increased share of 51.5% of total revenue, with retail stores and robot shops generating revenue of 11.79 billion yuan and 2.71 billion yuan, respectively, a YoY growth of 32.3% and 32.9%. The number of retail stores and robot shops increased by 11 and 118 to 340 and 2185, respectively, by the end of 2022. Growth was mainly driven by the recovery of offline consumption after the pandemic and improvements in store decoration and display effects. Sales of machines in scenarios such as high-speed rail, airports, and cinemas have grown rapidly.
(2) Online revenue is 8.17 billion yuan, which is lower than offline revenue, and the proportion of total revenue has decreased by 12.4% to 29.1%. In the first half of 2023, Pao Pao Mart/ Tmall flagship store/Douyin platform/others achieved revenues of 3.73/1.55/1.10/1.80 billion yuan, with changes of -31.4%/-36.6%/+569%/+3.7% respectively. Traditional e-commerce platforms such as Tmall have been affected by the recovery of offline channels and diversion to Douyin. Douyin channel's revenue has soared and it is the channel with the highest ARPU (Average Revenue Per User) value. The high-end series MEGA also sells very well on Douyin.
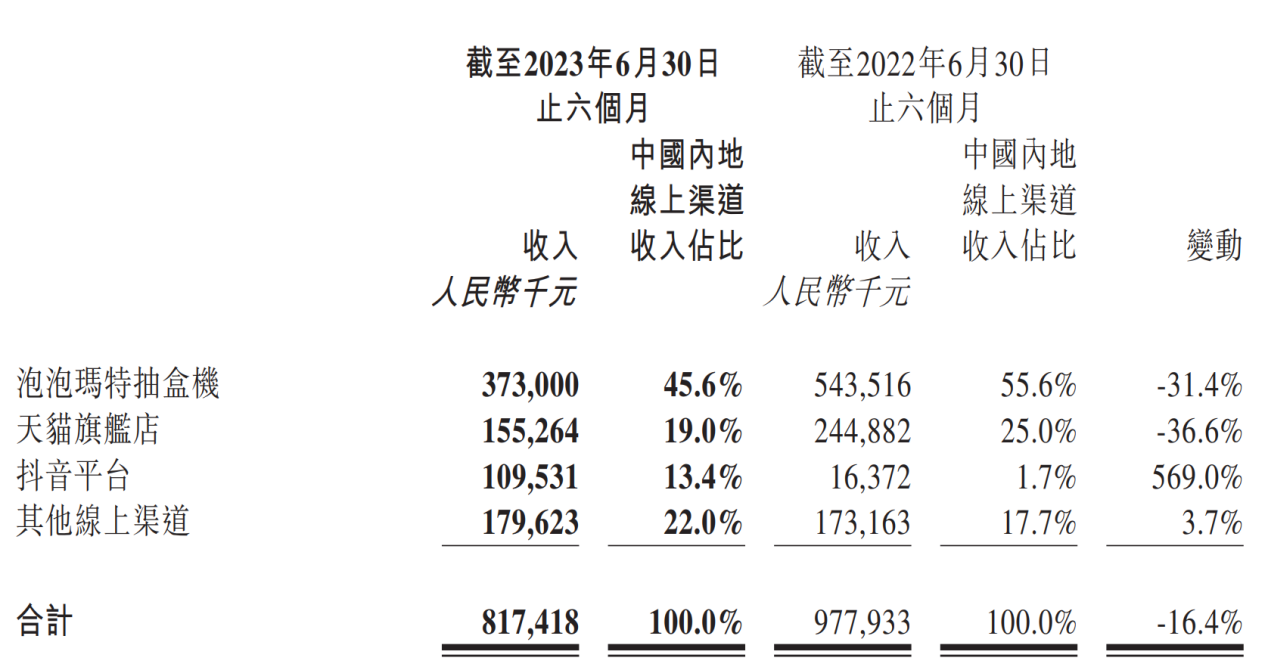
(3) Wholesale revenue: 170 million yuan, accounting for 6.0% of total revenue, a year-on-year increase of 32.3%, mainly due to the growth in sales at the Nanjing Bubble Mart store.
Overseas markets continue to see high growth and have a promising future
In H1 2023, revenue from China, Hong Kong, Macau, Taiwan and other overseas markets reached 376 million yuan, with a year-on-year growth rate of 139.8%, and the revenue share increased from 6.6% in the same period last year to 13.4%. Offline/online/wholesale revenues were 190/57/129 million yuan, with year-on-year growth rates of 392.4%/63.1%/54.6% respectively. Wang Ning, the CEO of Bubble Mart, stated that all overseas stores are currently profitable, and he is confident that the overseas business will achieve 1 billion yuan in revenue this year.
(1) Offline channels
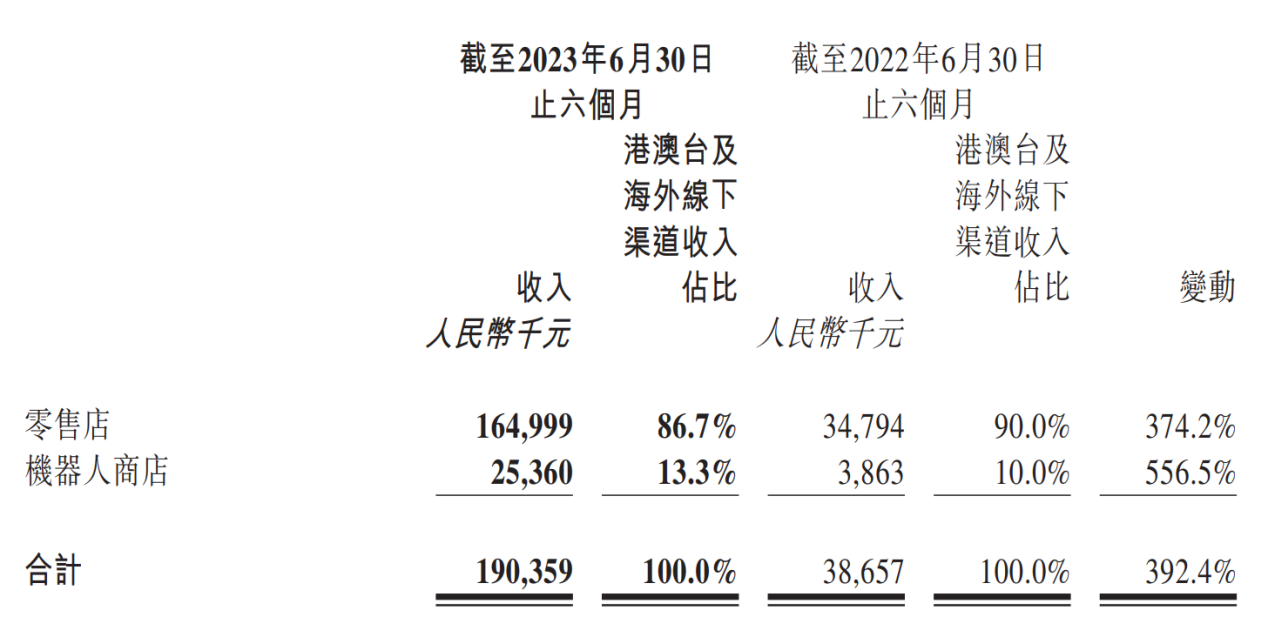
Retail stores/robot stores achieved revenues of 165/25 million yuan respectively, with an increase of 374.2%/556.5% compared to the same period last year; the number of retail stores/robot stores increased by 27/81 to 38/106. In the first half of 2023, Pao Pao Ma continued to promote the DTC (Direct To Customer) strategy, opening its first offline stores in France and Malaysia, and jointly establishing a joint venture company with Minor International, one of the world's largest hotel, restaurant, and retail industry groups, to develop the Thai market. At the same time, actively participate in overseas exhibitions such as the UK MCM Anime Expo, Melbourne OZ Anime Expo, Jakarta Anime Expo, Malaysia IOICITY Mall War, and continue to promote the globalization of the brand, and increase overseas brand recognition.
(2) Online Channels
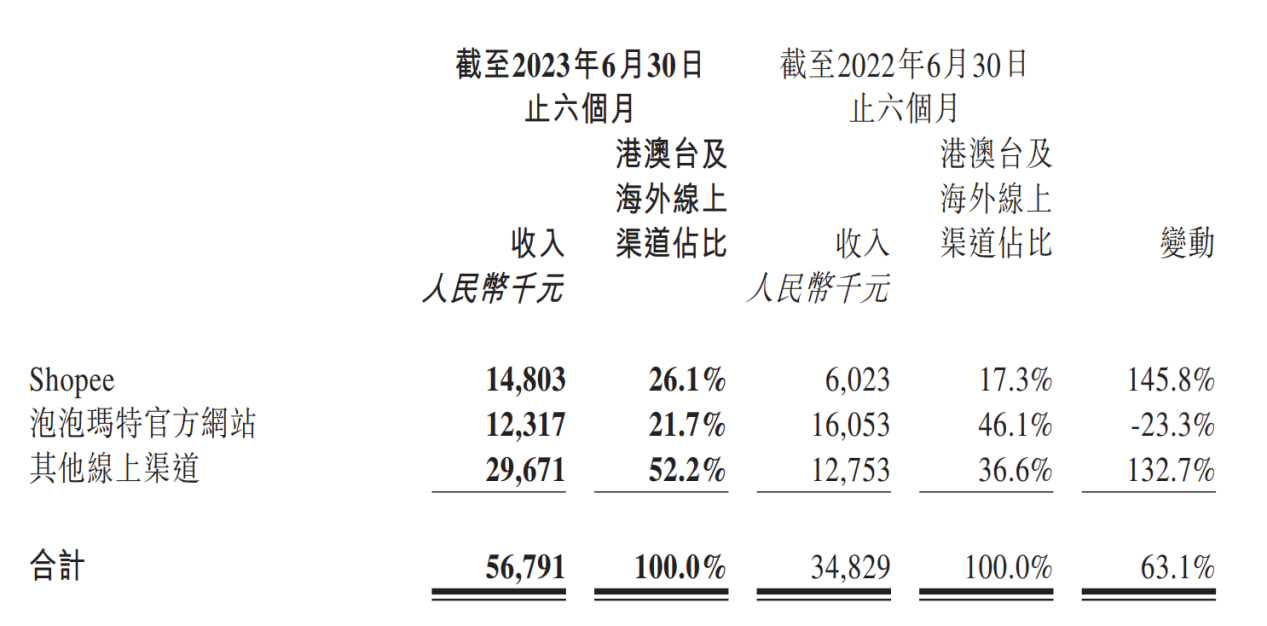
Shopee/Paopao Mart official website/Other income 0.15/0.12/0.30 billion yuan, with year-on-year changes of 145.8%/-23.3%/132.7%, the decrease in income from the Paopao Mart official website is due to the company reducing advertising investment on the official website and increasing promotion on platforms with higher sales conversion rates.
Classic IP steady growth, new product series continue to exert force
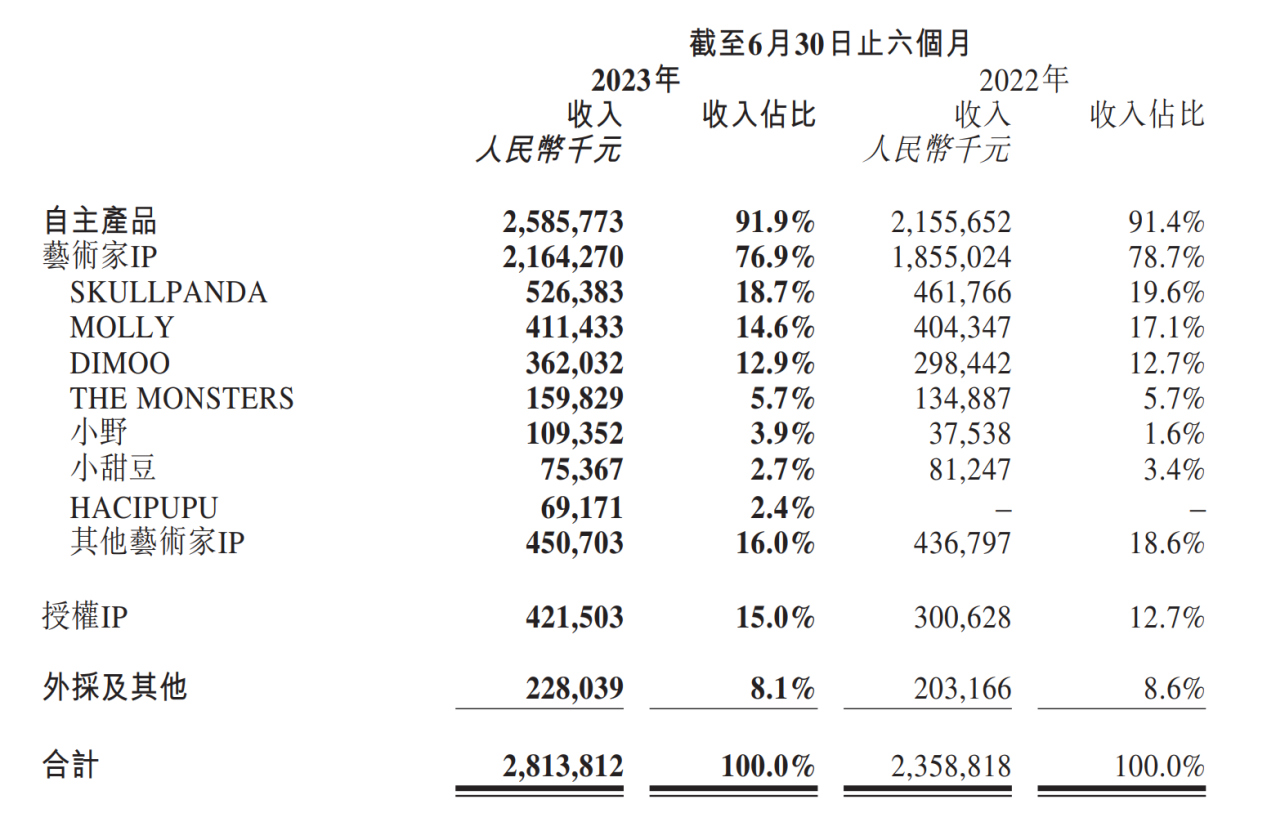
The head IP has maintained strong vitality, and the three major self-owned IPs SKULLPANDA, MOLLY, and DIMOO have achieved revenues of 526 million yuan, 411 million yuan, and 362 million yuan, respectively, with year-on-year growth of 14.0%, 1.8%, and 21.3% respectively. Among them, SKULLPANDA's eighth series "temperature" launched in November 2022 has been well received by fans for its warm colors and imitation ceramic texture, with sales revenue of 254 million yuan as of 23H1. The high-end product line "MEGA COLLECTION" launched for 3 years has gradually entered a mature stage of operation. MEGA COLLECTION is divided into five series: Grand, Art, Lifestyle, Joy, and Original, with MOLLY and DIMOO as the main products. The customer unit price is relatively high, and it achieved revenue of 242 million yuan in the first half of the year.
The innovative IP launched by Pop Mart, the "socially anxious little boy" HACIPUPU, earned 69.20 million yuan in the first half of the year. The Yesh series launched by the company's in-house design team PDC (Pop Design Center) achieved revenue of 109 million yuan, a year-on-year growth of 191.3%.
Theme park and game landing, continuous expansion of new businesses After more than 2 years of polishing, Baoma City Park will officially open in September. This immersive IP-themed park is located in Chaoyang Park, Chaoyang District, Beijing, covering an area of about 40,000 square meters, divided into four major areas: Bubble Street, Forest Area, Lakeside Area, and the main Molly Castle. At the same time, the first game "Dream Home" will start exclusive testing in Q4 2023. The game business is expected to be combined with the city park and play a supporting role. As a long-term strategic layout, the park may not bring significant benefits to the company in the short term, but the lack of content extension of the image IP itself can provide consumers with online and offline IP interactive scenes, further enhancing the influence of IP and deepening membership stickiness, maximizing the value of IP, and to a certain extent reducing the willingness of players to "quit". In comparison with Disney's IP empire, the continuous expansion of Baoma's business map also brings greater imagination to the capital market.
III. Profit Forecast and Investment Advice
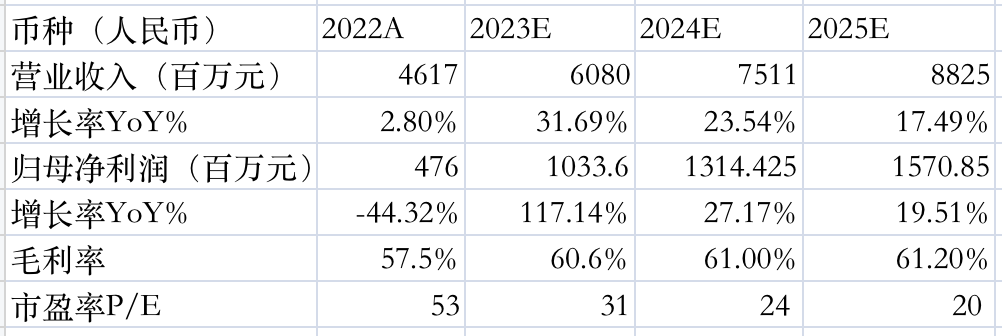
After experiencing the wild growth of "blind box fever", the entire industry has gradually transitioned from early disorderly competition to a stage of diversified competition and long-term development. As a leading player in the trendy toy industry, Pop Mart has formed certain barriers through years of deep cultivation, with high-quality IP as its core. After the pandemic, both revenue and profit have improved. The domestic offline scene has recovered, and there is vast potential for overseas expansion. Meanwhile, a complete and diverse operation landscape has been built, including games and amusement parks. We estimate that the company's revenue for FY 2023E to FY 2025E will be 6.08/7.51/8.825 billion yuan, with a year-on-year growth of 31.69%/23.54%/17.49%. The net mother profit will be 1.033/1.314/1.571 billion yuan, with a year-on-year growth of 117%/27.17%/19.51%. Based on the closing price on September 7, 2023, the corresponding P/E ratios are 31/24/20X, and we recommend a hold rating.
Risk Warning: Consumption recovery is lower than expected; new product promotion is lower than expected, overseas expansion is lower than expected; market competition intensifies.
This report does not constitute an investment advice to anyone.





