


When AI Agents Begin to Pay Autonomously: Cobo's Lucas on Stablecoin Payments and Security Infrastructure


AI agents are moving from information processing to autonomous execution, and payments are beginning to become part of that process.
When AI can autonomously call APIs, purchase computing resources, or complete on-chain transactions, the initiators of payments, transaction frequency, and amount structures may all change accordingly. In particular, high-frequency, small-value machine-to-machine payments are placing new demands on the cost structure of traditional payment channels, as well as on fund security and permission management.
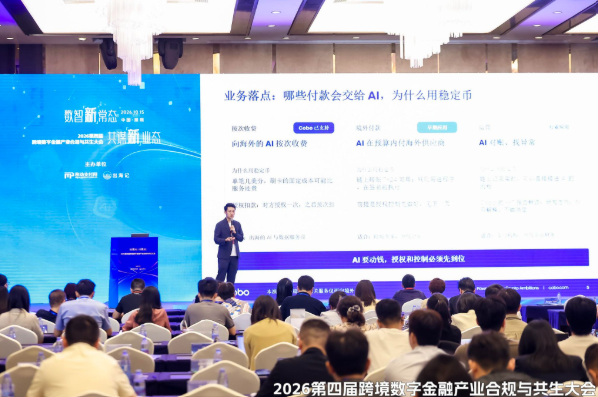
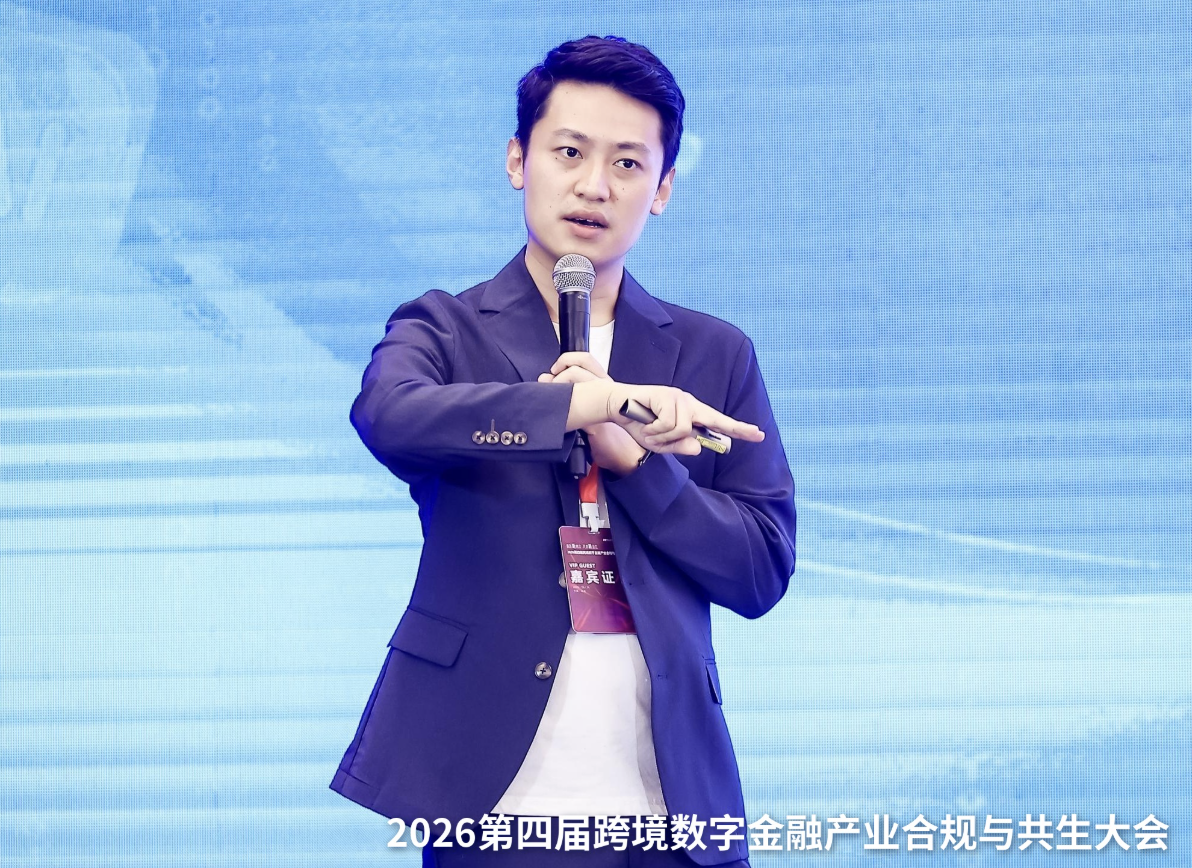
On October 15, at the Fourth Cross-Border Digital Finance Compliance Conference hosted by Mobile Payment Network, Lucas, Head of Sales and Solutions at Cobo, delivered a keynote speech on "Integration Practices and Security Risk Control of AI Agent and Web3 Stablecoin Payments," sharing Cobo's observations and practices regarding this trend.
Drawing on prior industry exchanges during TOKEN2049 in Singapore, Lucas began with the rise of AI Agent payments and further discussed the security boundaries of agentic wallets, the key components of stablecoin payment infrastructure, and how traditional payment institutions can leverage modular infrastructure to enter the Web3 payments market.
1. The Rise of On-Chain AI Payments: From Subscriptions to Pay-Per-Use
As AI agents begin to autonomously call APIs and purchase data and computing resources, payment demand is changing accordingly: transactions may become more frequent, but individual amounts are getting smaller.
Traditional payment systems struggle to handle such transactions economically. Payment channels such as credit cards typically carry fixed fees; for an API call worth only a few cents or even less than 1 cent, the payment cost may exceed the price of the service itself. Low-cost blockchain networks and stablecoins offer new settlement options for these high-frequency, small-value transactions.
This shift is already beginning to appear on-chain. According to a sampling study of the Base and Solana networks covering more than 6 million transactions over 35 days, over 90% of AI-related payment transactions in the sample were worth only a few cents or even less than 1 cent. This means machine payments are showing an amount distribution that is markedly different from traditional consumer payments.
The most direct applications come from APIs and online services. On Solana, there are already weather query APIs charging less than 1 cent per call, as well as token security screening services charging a few cents per use. Services that previously required subscriptions or prepaid balances are now beginning to experiment with reducing billing units to individual calls, enabling AI agents to purchase the resources they need on demand.
Similar explorations have extended to internet content access. Companies such as Cloudflare are promoting pay-per-use mechanisms based on the x402 protocol, providing new charging methods for scenarios such as AI crawlers accessing website content and automated service calls.
For enterprises, the potential value of this mechanism goes beyond API micropayments. In scenarios such as overseas supplier settlement, advertising placement, and channel commission distribution, AI agents are expected to initiate batch payments within preset budgets and permission scopes, combined with automated reconciliation, anomalous transaction identification, and on-chain anti-money laundering (AML/KYT) screening, reducing manual operations.
Judging from these early practices, AI agents are driving payments to extend from human-centric proactive operations to transactions automatically initiated by software based on business needs. As transaction frequency rises and amounts continue to be broken down into smaller units, payment infrastructure must not only provide low-cost settlement capabilities but also support automated execution and corresponding risk controls.
2. The Security Boundaries of Agentic Wallets: From Protecting Private Keys to Controlling Transaction Permissions
As AI agents begin to operate wallets autonomously, security issues also become more complex.
Unlike traditional wallets, AI agent operations may be affected by factors such as model hallucinations and malicious prompt injection. Even if the private key itself is not leaked, the agent may still initiate transactions beyond the user's true intent under erroneous instructions or external manipulation.
This means that the security of AI wallets requires not only protecting private keys but also setting clear permission boundaries for the agent's autonomous behavior.
To address this issue, Cobo Agentic Wallet controls the agent's transaction behavior at different stages through MPC (multi-party computation) private key management, Pact policy constraints, and pre-signature verification.
MPC private key management: preventing AI from independently controlling funds. Through MPC technology, transaction signing is completed collaboratively by multiple independent parties, and the AI agent does not need to hold the complete private key. Even if the agent's runtime environment is compromised, attackers would find it difficult to independently complete transaction signing using only the key material in that environment.
Pact policy constraints: predefining the scope of AI actions. Enterprises or wallet owners can pre-authorize the agent's transaction rules, including permitted payment recipients, per-transaction and cumulative limits, validity periods, and trigger conditions. The agent can execute autonomously within the authorized scope, but transactions beyond the rules cannot directly obtain signing authorization.
Pre-signature verification: setting a final checkpoint before funds are transferred out. The system can set tiered approvals based on transaction amount, recipient address, and business rules. For example, small transactions that comply with established policies can be executed automatically, while transactions exceeding specified limits or triggering risk conditions require manual confirmation. By independently verifying transaction permissions at the signing stage, the risks posed by tampered front-end instructions or anomalous agent behavior are reduced.
The core of this mechanism is to separate AI's autonomous execution capability from control over funds, allowing the agent to complete authorized payment tasks while enforcing critical transaction restrictions within the signing process.
3. Stablecoin Payment Infrastructure: From System Integration to Transaction Risk Control
Agentic wallets solve the question of within what permission scope AI can use funds, but for stablecoin payments to truly enter enterprise business processes, infrastructure capable of handling collection, fund screening, bookkeeping, payment, and settlement is also needed.
For traditional payment institutions, the challenges are mainly concentrated in three areas: how to integrate stablecoins under existing technology and licensing frameworks, how to identify on-chain fund risks, and how to ensure that every transaction is executed as expected.
The first is the choice of integration architecture.
Lucas summarized stablecoin payment integration approaches into a 2×2 matrix: at the asset management level, enterprises can choose third-party custody or self-custody; at the system integration level, they can choose standardized payment pages or embed into existing payment systems via API/SDK.
These two sets of choices can be combined according to an enterprise's own business needs, technical capabilities, and compliance requirements. For institutions that wish to retain their existing payment gateways, modular integration means they do not need to build an entire on-chain infrastructure from scratch.
The second is compliance screening of on-chain funds.
Unlike traditional card payments, once a stablecoin on-chain transfer is confirmed, it usually cannot be reversed through the chargeback mechanisms of card networks. Therefore, enterprises need to identify high-risk addresses, anomalous fund flows, and potential anti-money laundering risks during the collection and payment process.
Cobo's approach combines data from on-chain transaction monitoring (KYT) partners with AI-assisted analysis to provide compliance personnel with transaction risk alerts and fund flow information, supporting subsequent review and handling decisions.
Finally, and this is the part that is easily underestimated, is the security of transaction execution itself.
Looking at digital asset security incidents in recent years, attackers do not necessarily need to directly steal private keys. Compromise of front-end pages, business systems, or third-party services can likewise lead to transaction instructions being tampered with, causing an otherwise legitimate signing process to execute incorrect payments.
To address such risks, Cobo employs a layered protection mechanism covering three stages: controlling access and invocation permissions at the service request layer; constraining transactions through order creation, review, and multi-level approval at the business process layer; and independently verifying transaction intent and authorization rules at the final signing layer.
The significance of this design is that even if the upstream business system is compromised, anomalous transactions still have a chance to be identified and intercepted before final signing, rather than relying entirely on the security of the front-end system.
For enterprises entering the stablecoin payments market, low-cost on-chain transfers are only a basic capability. What truly determines whether they can enter production environments is a complete control system spanning system integration, fund compliance, and transaction execution.
4. The "Middle Path" for Traditional Payment Institutions Entering Web3
For traditional payment institutions looking to expand their stablecoin business, how to enter Web3 is first and foremost a trade-off between technology investment and business control.
At one end is relying on third-party service providers to deliver complete payment and asset management capabilities, which is relatively simple to integrate but may limit autonomous control over underlying systems and fund flows; at the other end is building on-chain acquiring, fund collection, address management, and Gas fee management infrastructure from scratch, which offers greater autonomy but also means ongoing R&D and maintenance investment.
In its collaboration with licensed payment institutions in Hong Kong, Cobo explored a third path between the two: through modular payment middleware, enterprises can directly integrate existing on-chain payment capabilities while choosing asset management and system integration methods according to their own business and compliance requirements.
Under this model, payment institutions do not need to repeatedly develop common blockchain underlying functions and can devote more resources to customer service, business expansion, and compliance operations, while retaining control over assets and key business processes under appropriate architectural arrangements.
For traditional payment institutions, modular infrastructure offers a more flexible way to enter: combining underlying technical capabilities with their own business systems, without having to choose between fully relying on external service providers and building a full stack in-house.
Conclusion
AI agents are bringing entirely new use cases to on-chain payments, but current applications are still mainly concentrated in small-value, pay-per-call, and automated transactions under preset rules.
From agentic wallets to stablecoin payment infrastructure, one direction is gradually becoming clear: as payment execution becomes increasingly automated, enterprises need to build fund control, transaction authorization, and risk management on more independent and verifiable mechanisms.
This will also be a direction Cobo continues to explore: through modular asset security and payment infrastructure, providing composable underlying capabilities for AI agents, traditional payment institutions, and Web3 developers.





