Asian "Black Thursday": Same AI, Four Different Prices, the Market Went Wild


- Core View: On October 15, Asian markets fell in sync on concerns over "AI financing constraints," but the difference in declines reached sevenfold. The root cause lies in differences in the form of AI assets and the nature of buying capital across markets, leading the same narrative to be priced differently.
- Key Elements:
- South Korea's KOSPI200 has fallen 22.4% cumulatively since October 2, with the two major stock indices triggering circuit breakers on the same day; foreign capital withdrew more than $130 billion during the year, and about $41 billion of buybacks by Samsung and SK Hynix were nearing completion, as three types of buying flows ebbed simultaneously.
- Japan's Nikkei 225 fell 4.90%, triggered by weakness in CoreWeave bonds, while SoftBank's balance sheet came under pressure from rising AI financing costs, and semiconductor equipment makers were sold off in a concentrated manner.
- Taiwan's weighted index fell 1,655.96 points, with TSMC alone dragging it down by nearly 396 points, while small and mid-cap stocks and margin positions amplified volatility.
- Hong Kong's Hang Seng Index fell only 1.03%, with AI hardware accounting for about 15%-20% of the Hang Seng Tech Index; southbound capital recorded net selling of HK$5.08 billion but showed structural rebalancing of "switching from hardware to platforms."
- The Shanghai Composite fell 1.59%, with 5,108 stocks declining, as crowded trades such as optical modules and PCBs unwound in a concentrated way, while liquor and brokerage stocks bucked the trend, signaling a defensive rotation.
- The nature of buying flows determines the buffering mechanism: foreign capital is trend-following money, buybacks are time-limited mechanical buying, southbound capital is allocation-type money, and A-share margin positions are leveraged money.
On October 15, Asian markets experienced a rare synchronized deep selloff, but the declines differed by a factor of seven. If it were simply "Asian markets falling together," the declines should have been similar; behind the four tiers of declines is the same AI narrative being repriced separately across four different market structures. This article breaks down five markets—South Korea, Japan, Taiwan, Hong Kong stocks, and A-shares—to examine what AI assets look like in each market and where the shock enters from.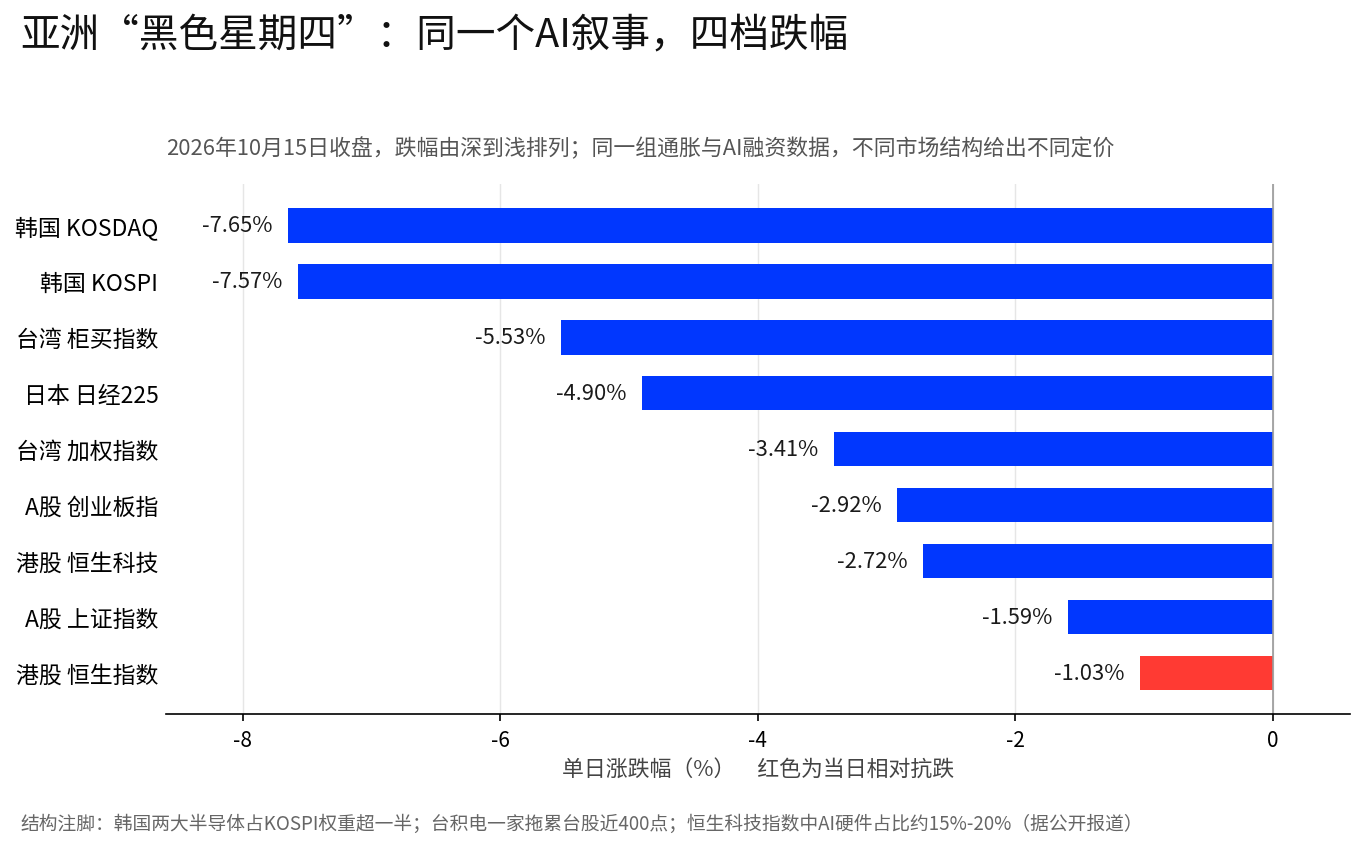
South Korea: The Epicenter—the Disappearance of Buyers Matters More Than the Change in Earnings
KOSPI and KOSDAQ both triggered Level 1 circuit breakers intraday, halting trading for 20 minutes. This was the 10th circuit breaker for the Korean stock market this year, and the second time both major indices triggered circuit breakers on the same day since July 29. SK Hynix closed down 11.06%, and Samsung Electronics closed down 9.48%; since October 6, KOSPI has fallen for a seventh consecutive trading day, with a cumulative decline of approximately 21%.
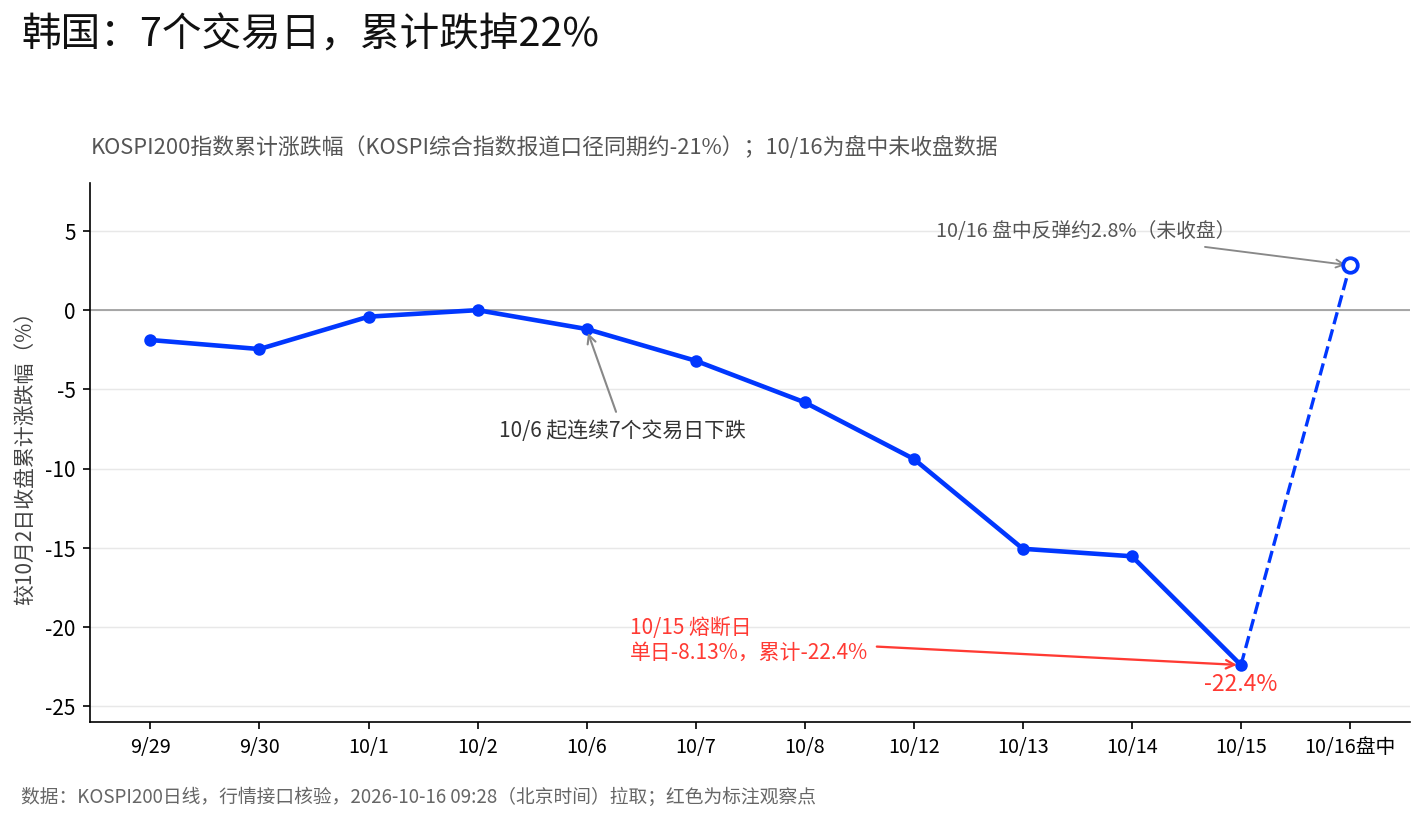 The KOSPI200 data is more granular than media reports: based on the October 2 close, the cumulative decline through the October 15 close was 22.4%, with a single-day drop of 6.25% on October 13 and 8.13% on October 15 (the KOSPI Composite Index was -7.57% that day). According to reports, both major indices triggered Level 1 circuit breakers after rapid intraday declines, halting trading for 20 minutes. What the circuit breaker mechanism provides is a cooling-off period; it cannot change the chip structure—foreign investors who want to sell, and buybacks that have already concluded, mean selling pressure remains in place after the pause ends. Notably, as of 9:28 AM Beijing time on October 16, KOSPI200 rebounded about 2.8% intraday (unclosed data): an oversold bounce may occur, but the problem of a buyer vacuum ultimately requires new capital to resolve.
The most notable contradiction is that earnings are still hitting record highs. Samsung Electronics' preliminary results show third-quarter operating profit is expected to be 107.4 trillion won, nearly nine times the year-ago figure (according to reports), yet the stock has fallen nearly 20% since the earnings guidance was released. According to KB Securities analysts (as reported), market doubts about the sustainability of AI investment are driving investors to price semiconductors using the logic of cyclical stocks. This is not a story of "earnings missing expectations," but rather a story of "whether the market is willing to pay a growth-stock premium for cyclical peak earnings."
Changes in the chip structure may be more critical than earnings. According to reports, foreign investors have withdrawn over $130 billion from the Korean stock market this year, the largest amount among major Asian markets; on October 15 alone, net selling was approximately 2.9 trillion won (KOSPI; combined with KOSDAQ, reports total approximately 3.6 trillion won), marking the eighth consecutive trading day of net selling. The more important variable is buybacks: the combined buyback plans of Samsung Electronics and SK Hynix totaling approximately 55 trillion won (about $41 billion) are nearing completion, and JPMorgan estimates that most of the approximately $23 billion in buying in the Korean stock market last month came from buybacks by these two companies (according to reports). After this important source of buying fades, the market's capacity to absorb selling pressure becomes noticeably thinner.
South Korea's Financial Services Commission said after its meeting that it will closely monitor the market and promptly implement contingency plans if necessary; officials and experts at the meeting believed that given multiple overlapping factors, the decline and pace of capital outflow may have shown a degree of overreaction.
Japan: The Trigger and the Balance Sheet
The Nikkei 225 closed down 4.90% at 64,425.95, with a point drop of 3,318.34—the third-largest in history. According to reports, the trigger that day was a sharp decline in the bond price of U.S. cloud computing company CoreWeave—AI-related stocks had been rising continuously, and concerns about the scale of industry investment, financing costs, and balance sheet conditions were already accumulating; volatility in related bonds amplified risk-aversion sentiment.
Selling was concentrated in the semiconductor supply chain. According to reports, semiconductor automated test equipment leader Advantest fell over 14%, Tokyo Electron fell nearly 8% at its intraday low, and SoftBank Group fell 9.33%. What makes the Japanese market unique is that SoftBank is one of Asia's largest AI investors, having paid a record financing yield late last month to support its AI investment plans. When AI financing costs rise, SoftBank's balance sheet pressure is quickly reflected in its stock price; and semiconductor equipment makers are concentrated in the Nikkei's weighting, making valuations more sensitive to interest rates and AI capital expenditure.
Connecting three things into a chain makes it clearer: CoreWeave bond weakness is the financing end of U.S. AI infrastructure, SoftBank paying record yields for AI investment is the investment end, and concentrated selling of equipment makers and semiconductor heavyweight stocks is the production end—three links in the same financing chain, priced separately by the market on the same day. Whether this chain continues to tighten explains more about where the constraints on the next phase of the AI rally lie than looking at any single market's decline in isolation.
Taiwan: One Company Drags the Market Down Nearly 400 Points; Small and Mid-Caps Fall Deeper
Taiwan's weighted index closed down 1,655.96 points at 46,969.87, the sixth-largest closing point drop in history; the OTC index (dominated by small and mid-caps) fell 5.53%, with a total of 1,898 declining stocks across listed and OTC markets (according to reports).
TSMC's ADR closed down 3.4% the previous night; on the day, Taipei opened down NT$70, closing at NT$2,440, down 2.01%, with the single company dragging the broader market down nearly 396 points (according to reports). According to Taiwanese media, MediaTek fell 6.93%, Delta Electronics fell 8.68%, and ASE Technology Holding hit the daily limit down. The interpretation from local investment advisory analysts points to the chip structure: inflation above expectations, rising probability of further Fed rate hikes, AI players relying on debt to fund construction spending, combined with high margin balances, leading to simultaneous release of profit-taking at highs and margin liquidation selling pressure (according to reports; this view represents only the judgment of the relevant individuals).
Hong Kong Stocks: The Smallest Decline—Southbound Capital Is Doing Structural Rebalancing
The Hang Seng Index closed down 1.03% at 24,062.72, the smallest decline among major Asian markets. The structural reason: AI hardware accounts for only about 15% to 20% of the Hang Seng Tech Index, which is essentially an internet platform-dominated index; when AI hardware valuations are repriced, structural diversification provides a buffer.
Southbound capital behavior is worth examining closely. On October 15, southbound capital recorded a full-day net sell of HK$5.08 billion, a new single-day high in nearly two weeks (according to reports). There was a clear structural pattern in flows: net buying of Tencent at HK$852 million and CNOOC at HK$331 million; net selling of Yangtze Optical Fibre and Cable at HK$931 million, Hua Hong Semiconductor at HK$800 million, and SMIC (the 13th consecutive day of reduction). Southbound capital appears to be rotating within Hong Kong stocks from AI hardware manufacturing toward platforms and defensive assets—a different type of action from foreign investors' overall withdrawal from Korean semiconductors.
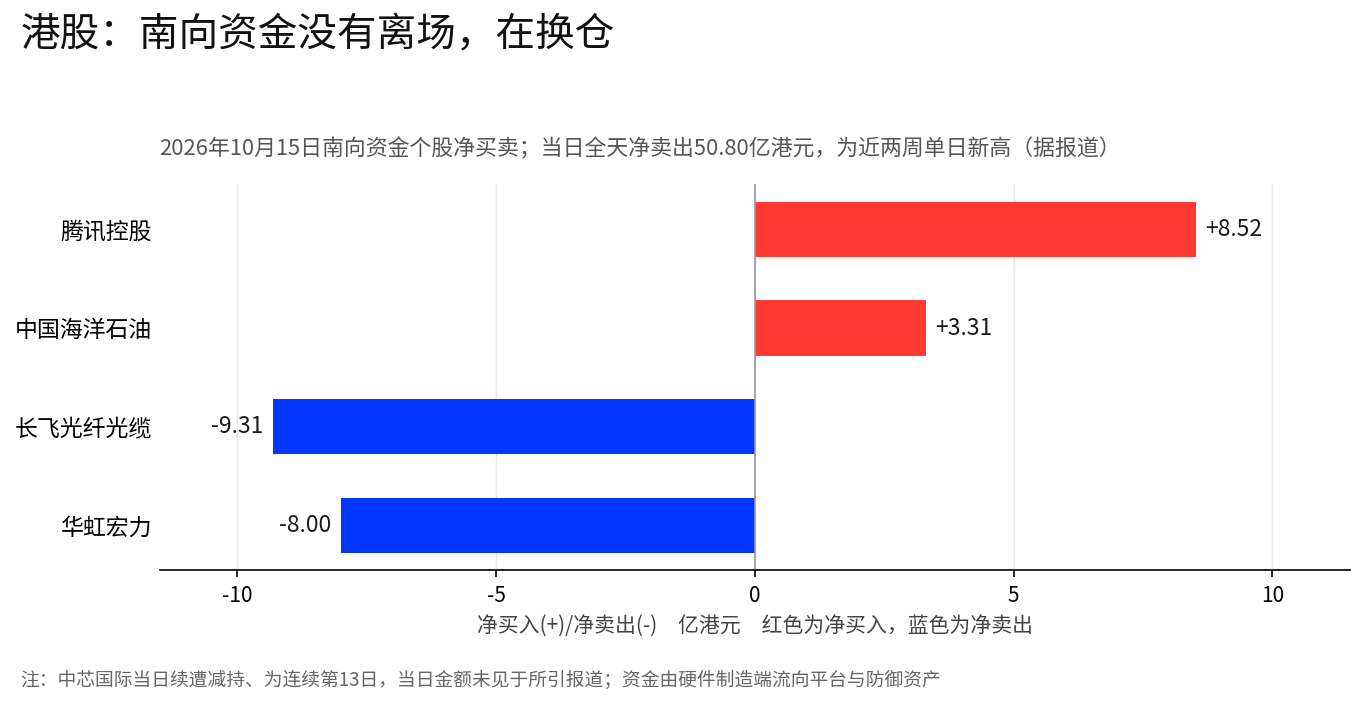 If this rebalancing continues, pressure on Hong Kong's hardware segment remains, while platforms may show relatively stronger resilience; this is an observational perspective, not a pricing conclusion.
A-Shares: Sentiment, Technicals, and External Shocks Converging
The Shanghai Composite Index closed down 1.59% at 3,707.48, barely holding above 3,700, and the ChiNext Index fell 2.92%; 5,108 stocks declined across the market, with total market capitalization evaporating approximately 2.25 trillion yuan in a single day (according to reports). Mainland fund managers interviewed believe the adjustment is a convergence of internal and external factors: the Nasdaq fell 1.88% overnight and the Philadelphia Semiconductor Index fell 4.3%, transmitting AI hardware valuation digestion pressure to domestic markets, while insufficient incremental capital remains the core contradiction (according to reports; this view represents only the judgment of the relevant institutions); investment advisory strategists stated that the market decline was not a resistance-free fall, but a concentrated release after sentiment, technicals, and external shocks converged, with external factors being an important trigger (according to reports).
A-shares' uniqueness lies in optical modules and PCBs being crowded trading directions over the past two years. When interest rate expectations shift and external tech stock valuations come under pressure, margin positions and quantitative funds in these sectors withdraw in a concentrated manner. Baijiu and brokerage stocks rising against the trend shows that capital is not withdrawing across the board, but making a structural defensive rotation.
The Same AI, Four Pricing Methods
Putting the five markets together, the root of the differences lies in the different forms AI assets take within each market structure:
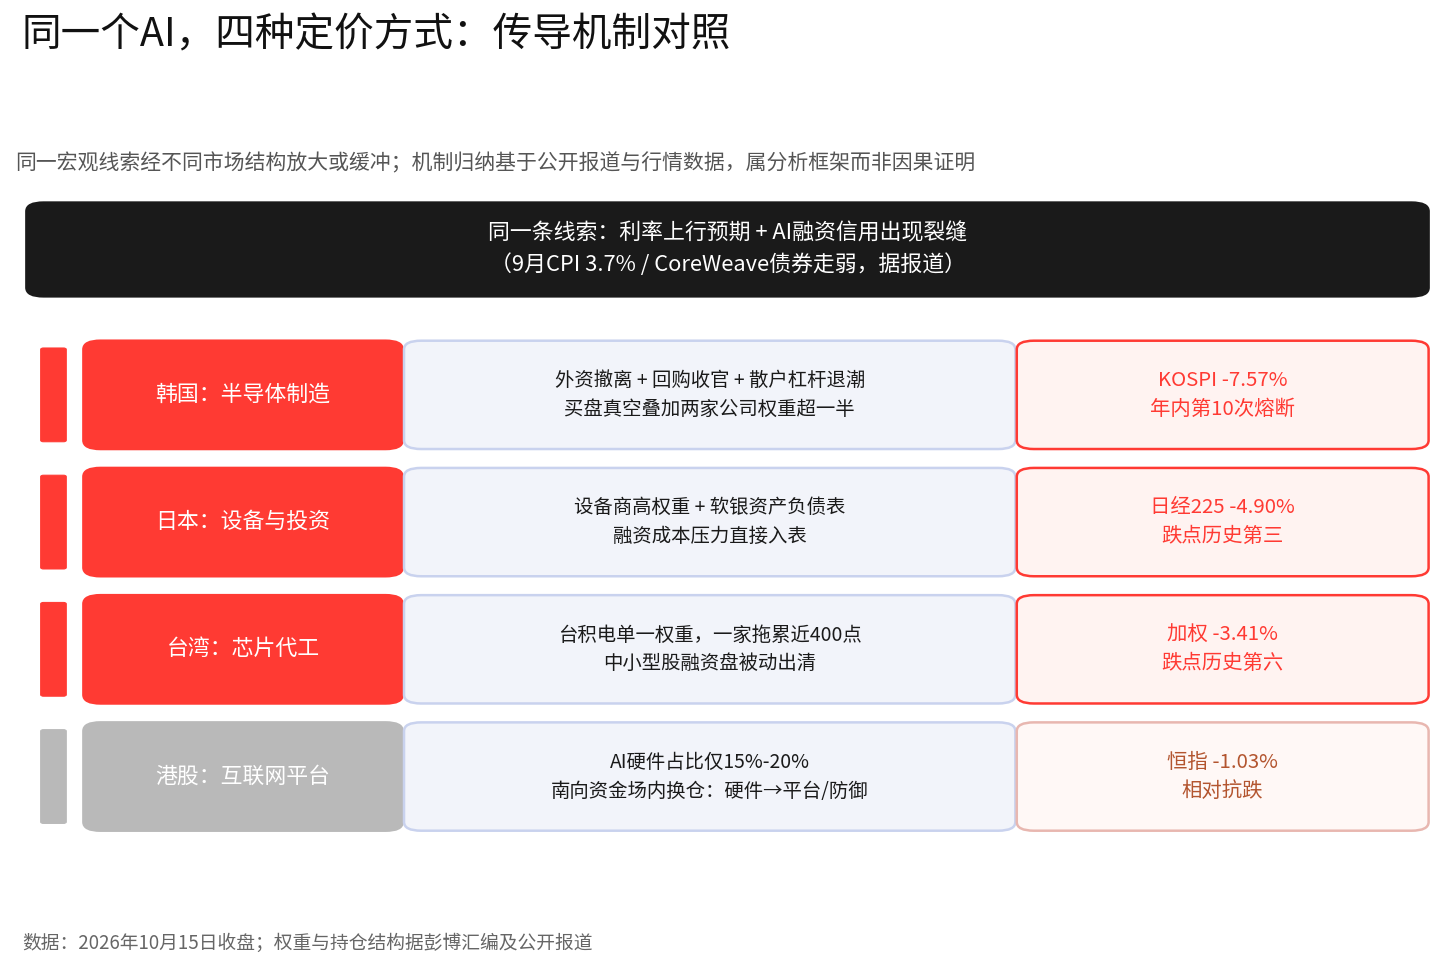
- South Korea's AI is semiconductor manufacturing: two companies account for more than half of KOSPI's weighting (Bloomberg compilation), foreign ownership is high, and buybacks are an important source of buying. When foreign outflows and the conclusion of buybacks occur simultaneously, concentration amplifies the decline.
- Japan's AI is semiconductor equipment and investment: equipment makers are core weightings, and SoftBank is the largest AI investor. When financing costs rise, balance sheet pressure is transmitted directly.
- Taiwan's AI is chip foundry: TSMC alone contributed nearly 400 points of decline, and the index can hardly hedge against a single weight; margin positions in small and mid-caps further amplify volatility.
- Hong Kong's AI is internet platforms: hardware accounts for a low proportion, and southbound capital completes a "hardware-to-platform" structural hedge internally.
- A-shares' AI leans toward manufacturing and the computing power chain: highly crowded optical modules and PCBs face deeper pressure, defensive sectors rise against the trend, and the market is rotating internally.
The same AI narrative corresponds to completely different asset structures across the four markets. When the macro variable of "AI financing constraints" hits all markets, the way each market absorbs the shock depends on what its AI assets look like. Historical comparisons are for reference only; past performance does not represent future results.
Why the Buffering Methods Differ: The Nature of Three Types of Buyers
The differences among the four markets stem not only from the form of AI assets but also from the capital nature of the buyers.
Foreign capital is trend-following money. It is most sensitive to interest rates and credit events; once a direction forms, selling is continuous and unidirectional—a single-day net sell of approximately 2.9 trillion won for eight consecutive days is this nature.
Buybacks are time-limited mechanical buying. They continue buying regardless of valuation during the announcement period; the 55 trillion won scale is enough to provide support in a slow decline, but it disappears the moment the announcement period ends and provides no continuity. This is the most easily underestimated change in Korean stocks this round.
Southbound capital is allocation-type money. It recorded a net sell of HK$5.08 billion on the day, but it sold hardware and bought platforms and defensive assets—the money did not leave, it merely changed positions within the market.
A-shares' margin positions are leveraged money. They amplify gains in normal times, and during declines they are forced to liquidate, turning crowded trades into concentrated releases; baijiu and brokerage stocks rising against the trend shows that on-market capital is rotating rather than fully retreating.
Facing the same thread of "AI financing constraints": South Korea encountered a simultaneous ebb of three types of buyers, with the shock amplified by high concentration; Hong Kong encountered in-market rotation by allocation-type capital, with the shock absorbed by structural diversification. A sevenfold difference in declines—half can be explained by asset structure, and the other half depends on the nature of the buyers. This framework is inductive rather than causal proof; whether it holds can be verified item by item using the observation points below.
Market Focus Going Forward
First, whether foreign selling of Korean stocks slows after regulatory statements, and whether there are specific arrangements for stabilization measures; whether the approximately 2.8% intraday rebound in KOSPI200 on the morning of October 16 (as of 9:28 AM Beijing time) can continue is the first observation window for the nature of supporting capital. Second, CoreWeave bond prices and credit spreads. It is one of the important triggers for this round of Asian AI hardware selling; if bonds continue to weaken, pressure from AI companies' financing costs will continue to transmit to Asian hardware stocks. Third, whether southbound capital's "hardware-to-platform" rebalancing continues, which can serve as one of the observational indicators for structural divergence in Hong Kong stocks. Fourth, the progress of margin balance clearing in A-share technology sectors, and the sustainability of baijiu and brokerage stocks' counter-trend performance.
BIT supports real-time Hong Kong and U.S. stock quotes and direct trading: users can track southbound capital flows into Hong Kong internet platforms and U.S. AI chip sector movements and trade within the same BIT account. Stablecoin direct deposits, 7×24 second-level settlement. During the public beta, Hong Kong stocks have zero commission and zero interest on margin subscriptions. During periods of increased Asian market volatility, please consider position sizing and leverage in light of your own risk tolerance.
Data Notes
- Index quotes: KOSPI/KOSDAQ, Nikkei 225, Taiwan Weighted, Hang Seng Index, Shanghai Composite Index, etc., as of the October 15, 2026 close; some verified through market data interfaces, some from public market reports.
- KOSPI200 daily chart: verified through market data interface, retrieved at 09:28 (Beijing time) on October 16, 2026; October 16 data is intraday and unclosed.
- Korean foreign capital flows and regulatory statements: The Paper, China News Service, etc., October 15, 2026; foreign single-day net selling has two reported figures—KOSPI only and including KOSDAQ—both noted separately in this article.
- Japanese sectors and SoftBank financing: Xinhua Finance, Kyodo News, etc., October 15, 2026.
- Taiwan market data and chip structure: Taiwanese media reports, October 15, 2026.
- Southbound capital: Securities Times DataBao, Cailian Press, October 15, 2026.
- A-share market data and institutional views: East Money, Huaxia Times, etc., October 15, 2026; CoreWeave bond-related information relayed by Cailian Press, etc.
Disclaimer:
This article is intended for general information and market commentary purposes only, based on public materials available as of the time stated herein; relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or other persons cited herein represent only the views of the relevant third parties at specific times and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation of any securities, investment products, or trading strategies, and should not be relied upon as a basis for any investment decision. Financial markets carry risks; securities prices and market performance may fluctuate, and historical performance and past market trends do not represent or guarantee future results. Investors should independently assess relevant risks based on their own circumstances and seek professional advice when necessary. BIT's Hong Kong stock trading services are not provided to Hong Kong residents or users in other restricted jurisdictions.