


DID: Improvements to on-chain credit business and DAO identity


AAVE recently launched the stable currency GHO and mentioned the credit scoring system in the route, which brought the credit on the chain back into people's sight: will the unsecured credit loan mentioned a long time ago become popular? Not so, the credit scoring system as the basis of credit is still facing many problems, the infrastructure of DID is advancing slowly, and DAO, as an independent economic entity, does not have an identity paradigm that is different from retail investors, and the credit business on the chain is still facing identity problems. Problems such as identification and recovery cannot be solved at present.
first level title
Three characteristics of DID: the root of the difference from the existing identity system
secondary title
low consensus cost
Fast speed and high verification efficiency
Composability
Composability
Mutual calls between protocols
secondary title
native globalization
Nature has no borders and naturally meets the needs of transnational credit value transfer
The global division of labor knows no borders and naturally covers a wider group
The consensus of DID itself is formed by the underlying public chain. A sufficiently decentralized public chain has already solved the consensus problem. The DID system built on it does not need to consider consensus, and key behavioral data are directly recorded on the chain. Form a consensus. DID protocols and between DID protocols and other protocols can be called each other, and the control authority is all determined by the user, which gives the DID protocol a very large composability, and the DID protocol can be easily connected to other applications. , Information transmission without barriers. This gives users ownership of their own data, users can authorize protocols to call any type of data, and protocols can be combined with each other.
DID can operate without a trusted entity, so it is naturally borderless, and users can naturally access their credit on the chain to various applications, regardless of where the application is registeredfirst level title
DID perfects DeFi
DID solves the identity problem of DeFi, which is the pain point of DeFi. If it is impossible to judge and measure the credit level of users, the mortgage rate of all users can only be increased and over-collateralized.Combining DID with the launch of a credit scoring system to achieve low-mortgage or even unsecured credit loans is generally considered to be the next development direction of DeFi. As an economically independent individual, DAO also needs an identity paradigm. If DID creates this paradigm, it will also bring a new range of customers to DeFi. Various financial operations on the chain will be easily realized. DeFi A base point for rapid expansion will be found.
The large-scale expansion of DeFi is bound to compete with traditional financial services for market share, and a class of financial services that cannot access the credit system cannot complete the reduction of mortgage rates.Without access to the credit system, DeFi cannot reduce the mortgage rate and improve its own capital utilization efficiency, This will be a huge obstacle for DeFi to achieve large-scale expansion. Judging from the lending business with a high proportion of DeFi, the large-scale unsecured credit business at this stage only exists in the institutional business, and its scale is very small. At this stage,The development of credit on the chain is still early, and there is still a certain distance from the ideal credit businesssecondary title
Idealized credit business and financial identity of DAO
The operation of an idealized credit business includes three dimensions, before, during and after.
beforehand
Collect information such as repayment history, proof of income, guarantees, etc.
Investigation and risk assessment, verification of information.
According to the credit model, evaluate the probability of default, determine the applicable interest rate, mortgage rate and credit limit, etc., plus subjective judgment, determine whether to issue credit.
in progress
The scope of use of funds is stipulated, and the operation of traditional financial service providers is to set up special accounts.
Risk Management.
Fund monitoring.
afterwards
Recovery, liquidation of collateral.
Credit history, limiting the scope of services for customers.
Backtesting the tuning model.
A DAO's idealized identity paradigm in finance should be similar to a corporate legal person in the real world, with independent property rights and independent exercise of commercial rights.
independent property rights
The control right is public, no independent entity can control the DAO's financial treasury, but the operation of funds is determined by a definite governance method.
Most assets and liabilities are on-chain and can be chosen to be public or not.
The business is sustainable, members can flow, and it is an independent brand that does not depend on an individual to exist.
Independent exercise of commercial rights
Independently exercise commercial rights and have commercial credit.
secondary title
The dilemma of on-chain credit business at this stage
The scope of credit business can be roughly divided into retail users and institutions according to the scale.For the credit business of institutions, the scale is large and the profit is high, and financial service providers have the incentive to spend more cost to collect information, while for retail customers, the cost of collecting information for financial service providers is relatively high, and the time and energy spent on collecting information are too high. limited.TrueFi is the first unsecured credit platform with decentralized operation, and it is also the largest one at present. It currently only conducts institutional business, and its customers only have more than a dozen institutions.
Its business model is that the user puts TUSD into the fund pool of the TrueFi platform, and the borrower in need submits an application, and after the TRU pledger reviews the credit, the TRU fund pool approves the loan. In this process, TrueFi's whitelist review and the votes of TRU pledgers play a decisive role, but the judgment of TRU pledgers is largely based on the TrueFi credit score given by TrueFi's credit model. Therefore,image description。
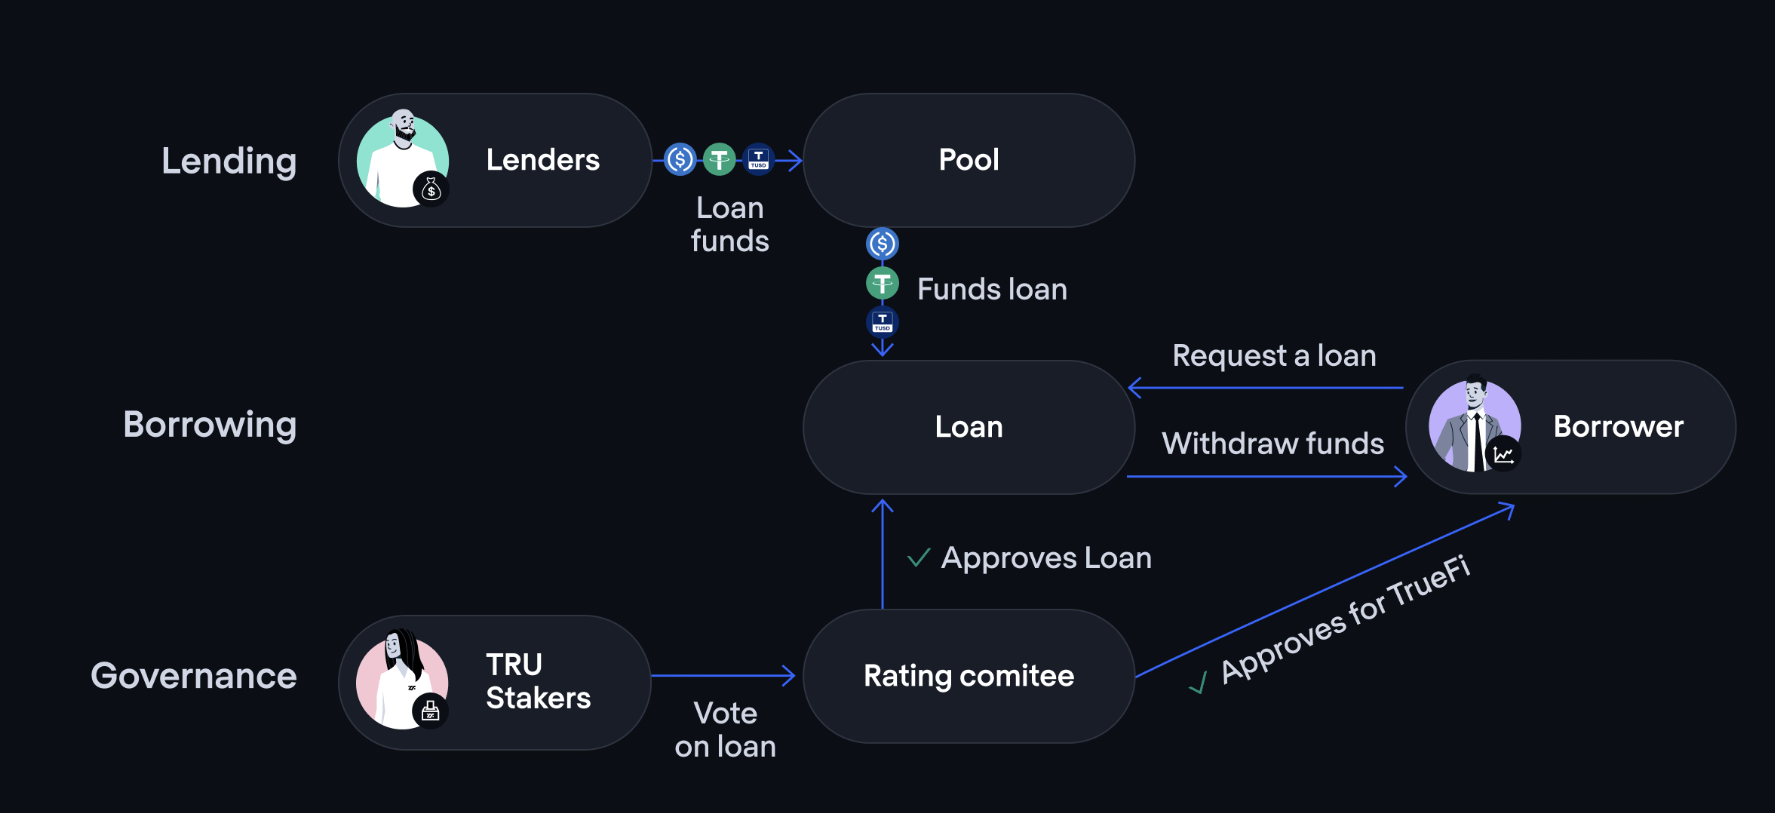
TrueFi business flow chart (data source: TrueFi official website)
Since it is impossible to collect and judge customer information on a large scale, the solution chosen by TrueFi is a strict whitelist review system to screen out institutional users with a low probability of default and who can recover off-chain. TrueFi is also participating in the construction of on-chain credit scoring by building its own credit model. When we consider the conditions for TrueFi's large-scale expansion, we can clearly perceive the bottleneck of the development of the credit business on the chain at this stage, that is,Large-scale user identification issues and recovery issues。
Although many DID projects intend to solve the problem of user identification in the financial field, it is still at a very early stage. Various protocols have some problems, and there is currently no protocol that has been applied on a large scale. Recovery issues include whether DID should be included in off-chain identities and data, as well as practical issues.LTO Network is a hybrid blockchain platform. He designed the identity certificate system on the chain at the bottom layer, and chose to link real-world data to strengthen the commercial availability of identity on the chain. This is a pathsecondary title
Improvements to DIDs
DID can improve many aspects of credit business through credit scoring system and basic information.
Preliminary Information Collection and Subjective Judgment
DID is mainly used to complete the pre-information collection link of the credit business. In the chain environment, the user's information is read through the voucher and data recorded by the DID to initially evaluate the user. For example, the user's historical repayment records, on-chain activity records, social connections, etc. can be used as initial information for DeFi protocol evaluation.
Through the behavioral data recorded by DID (interaction with certain agreements, participating DAO, etc.), the DeFi protocol can also allow salesmen or certain Token pledgers to make subjective judgments and assist decision-making.
Fund lock and fund monitoring in the event
Combined with DeFi, DID can specify the purpose of funds, and ensure the whereabouts of funds through customized on-chain contracts.
On the chain, the flow of funds can be monitored from time to time, and the behavior in the event can be recorded, reflected on the DID, and metadata can be provided to the DID in the event.
post credit history
Once a breach of contract occurs, the information is recorded on the chain. In a DID-perfect ecosystem, it will affect the subsequent benefits that it can enjoy and directly affect the next credit application. It is a means of dealing with breaches of contract afterwards. If the impact and consequences of default records are strong enough, it can form a constraint on borrowers, but this depends on the construction of the entire ecology.
Scenarios that cannot be improved
Off-chain recovery and accountability: DID alone cannot solve the problem of recovery. This involves off-chain collection, legal affairs and many other problems that are difficult to achieve on the chain, and it is not the key that DID wants to solve.
Collection of off-chain data: Accessing off-chain data means trusting an entity, and this is where DID is weak. How to interact with off-chain data is still the current difficulty.
Collection on the chain: collection on the chain is difficult to achieve, and it is difficult to recover after the loss occurs. DID's credit scoring system only reduces its motivation for default, but it cannot solve the collection problem.
The DAO financial identity determined by DID can improve many problems of DeFi. This new range of customers also requires DeFi to provide financial services for it, because this kind of DID is naturally unable to integrate into the financial system of the real world, and it is difficult for traditional financial institutions to provide financial services in a short period of time. The framework for serving DAOs has been developed within a short period of time, which means that only DeFi can provide these DAOs with the on-chain financial services they need.
user identification problem
A properly functioning DAO should have abundant on-chain data, which is the foundation of credit.
DAO's economic activities can provide support for its credit, similar to how companies in the real world use future cash flow as a repayment support, DAO's economic activities will also be continuous in theory and predictable to a certain extent.
financial recovery issues
The credit record of DAO is very important. It directly affects its own brand value and the credit of all members, which is a constraint for DAO.
first level title
secondary title
credit scoring system
There are many DIDs exploring the mining of financial data and exploring a universally applicable credit scoring system. At present, such DIDs that provide financial services mainly rely on a certain protocol, such as TrueFi and Maple Finance’s credit scoring system. Models rely on their own lending operations and are kept whitelisted for review. Other DID protocols that focus on credit scoring will be connected to mainstream lending protocols, and credit scores on the chain will be given through the repayment records of mainstream lending protocols. For example, ARCx will give credit scores based on the interaction between users and DeFi protocols.
secondary title
DAO's Financial Identity
Currently there is no DID protocol that specifically provides financial identities for DAOs, and this paper argues that there will be a huge demand for standardizing financial identities for DAOs.A DID identity system that adapts to the characteristics of DAO will determine the assets and claims of DAO in a certain paradigm, so as to realize the various financial operations mentioned above. From this point of view, the identity system will also be financial. In general, the organizational form of DAO requires a financial paradigm, which is determined by DID.
At the same time, during the development of DAO, its members will also face problems similar to DAO.The response speed in the real world is very slow, and there are various difficulties for a full-time DAO member to obtain financial services in the real world.secondary title
Reference
https://medium.com/amber-group/decentralized-identity-passport-to-web3-d3373479268a
https://mp.weixin.qq.com/s/DlQXjQq8mIUpllANXZ-lbw
https://mirror.xyz/shreyjain.eth/TyBzMOegl3rMNxpAFoJ36MjE0pGfdLcrVCBgy-x3qS8
https://www.ltonetwork.com/documents/LTO Network - Identities Paper.pdf
disclaimer
More information
Copyright Notice
Without the authorization of DODO Research Institute, no one may use without authorization (including but not limited to copy, disseminate, display, mirror, upload, download, reprint, excerpt, etc.) or allow others to use the above intellectual property rights. If the work has been authorized to be used, it shall be used within the scope of authorization, and the source of the author shall be indicated. Otherwise, its legal responsibility will be investigated according to law.
about Us
"DODO Research Institute" led by the dean "Dr.DODO" led a group of DODO researchers to dive into the Web 3.0 world, doing reliable and in-depth research, aiming at decoding the encrypted world, outputting clear opinions, and discovering the future value of the encrypted world. "DODO" is a decentralized trading platform driven by the Proactive Market Maker (PMM) algorithm, which aims to provide efficient on-chain liquidity for Web3 assets, allowing everyone to issue and trade easily.
More information
Official Website: https://dodoex.io/
GitHub: https://github.com/DODOEX
Telegram: t.me/dodoex_official
Discord: https://discord.gg/tyKReUK
Twitter: https://twitter.com/DodoResearch
Notion: https://dodotopia.notion.site/Dr-DODO-is-Researching-6c18bbca8ea0465ab94a61ff5d2d7682
Mirror:https://mirror.xyz/0x70562F91075eea0f87728733b4bbe00F7e779788





