


At 9:30 PM tonight, the US will release the CPI report: with year-over-year data absent, what should investors watch?


- Key Viewpoint: The October CPI report is the last inflation data before the Federal Reserve's December policy meeting. The market is closely watching whether prices can cool as expected. Core CPI month-over-month is expected to slow to 0.2%, which will become a key basis for judging whether the Federal Reserve will raise rates further.
- Key Elements:
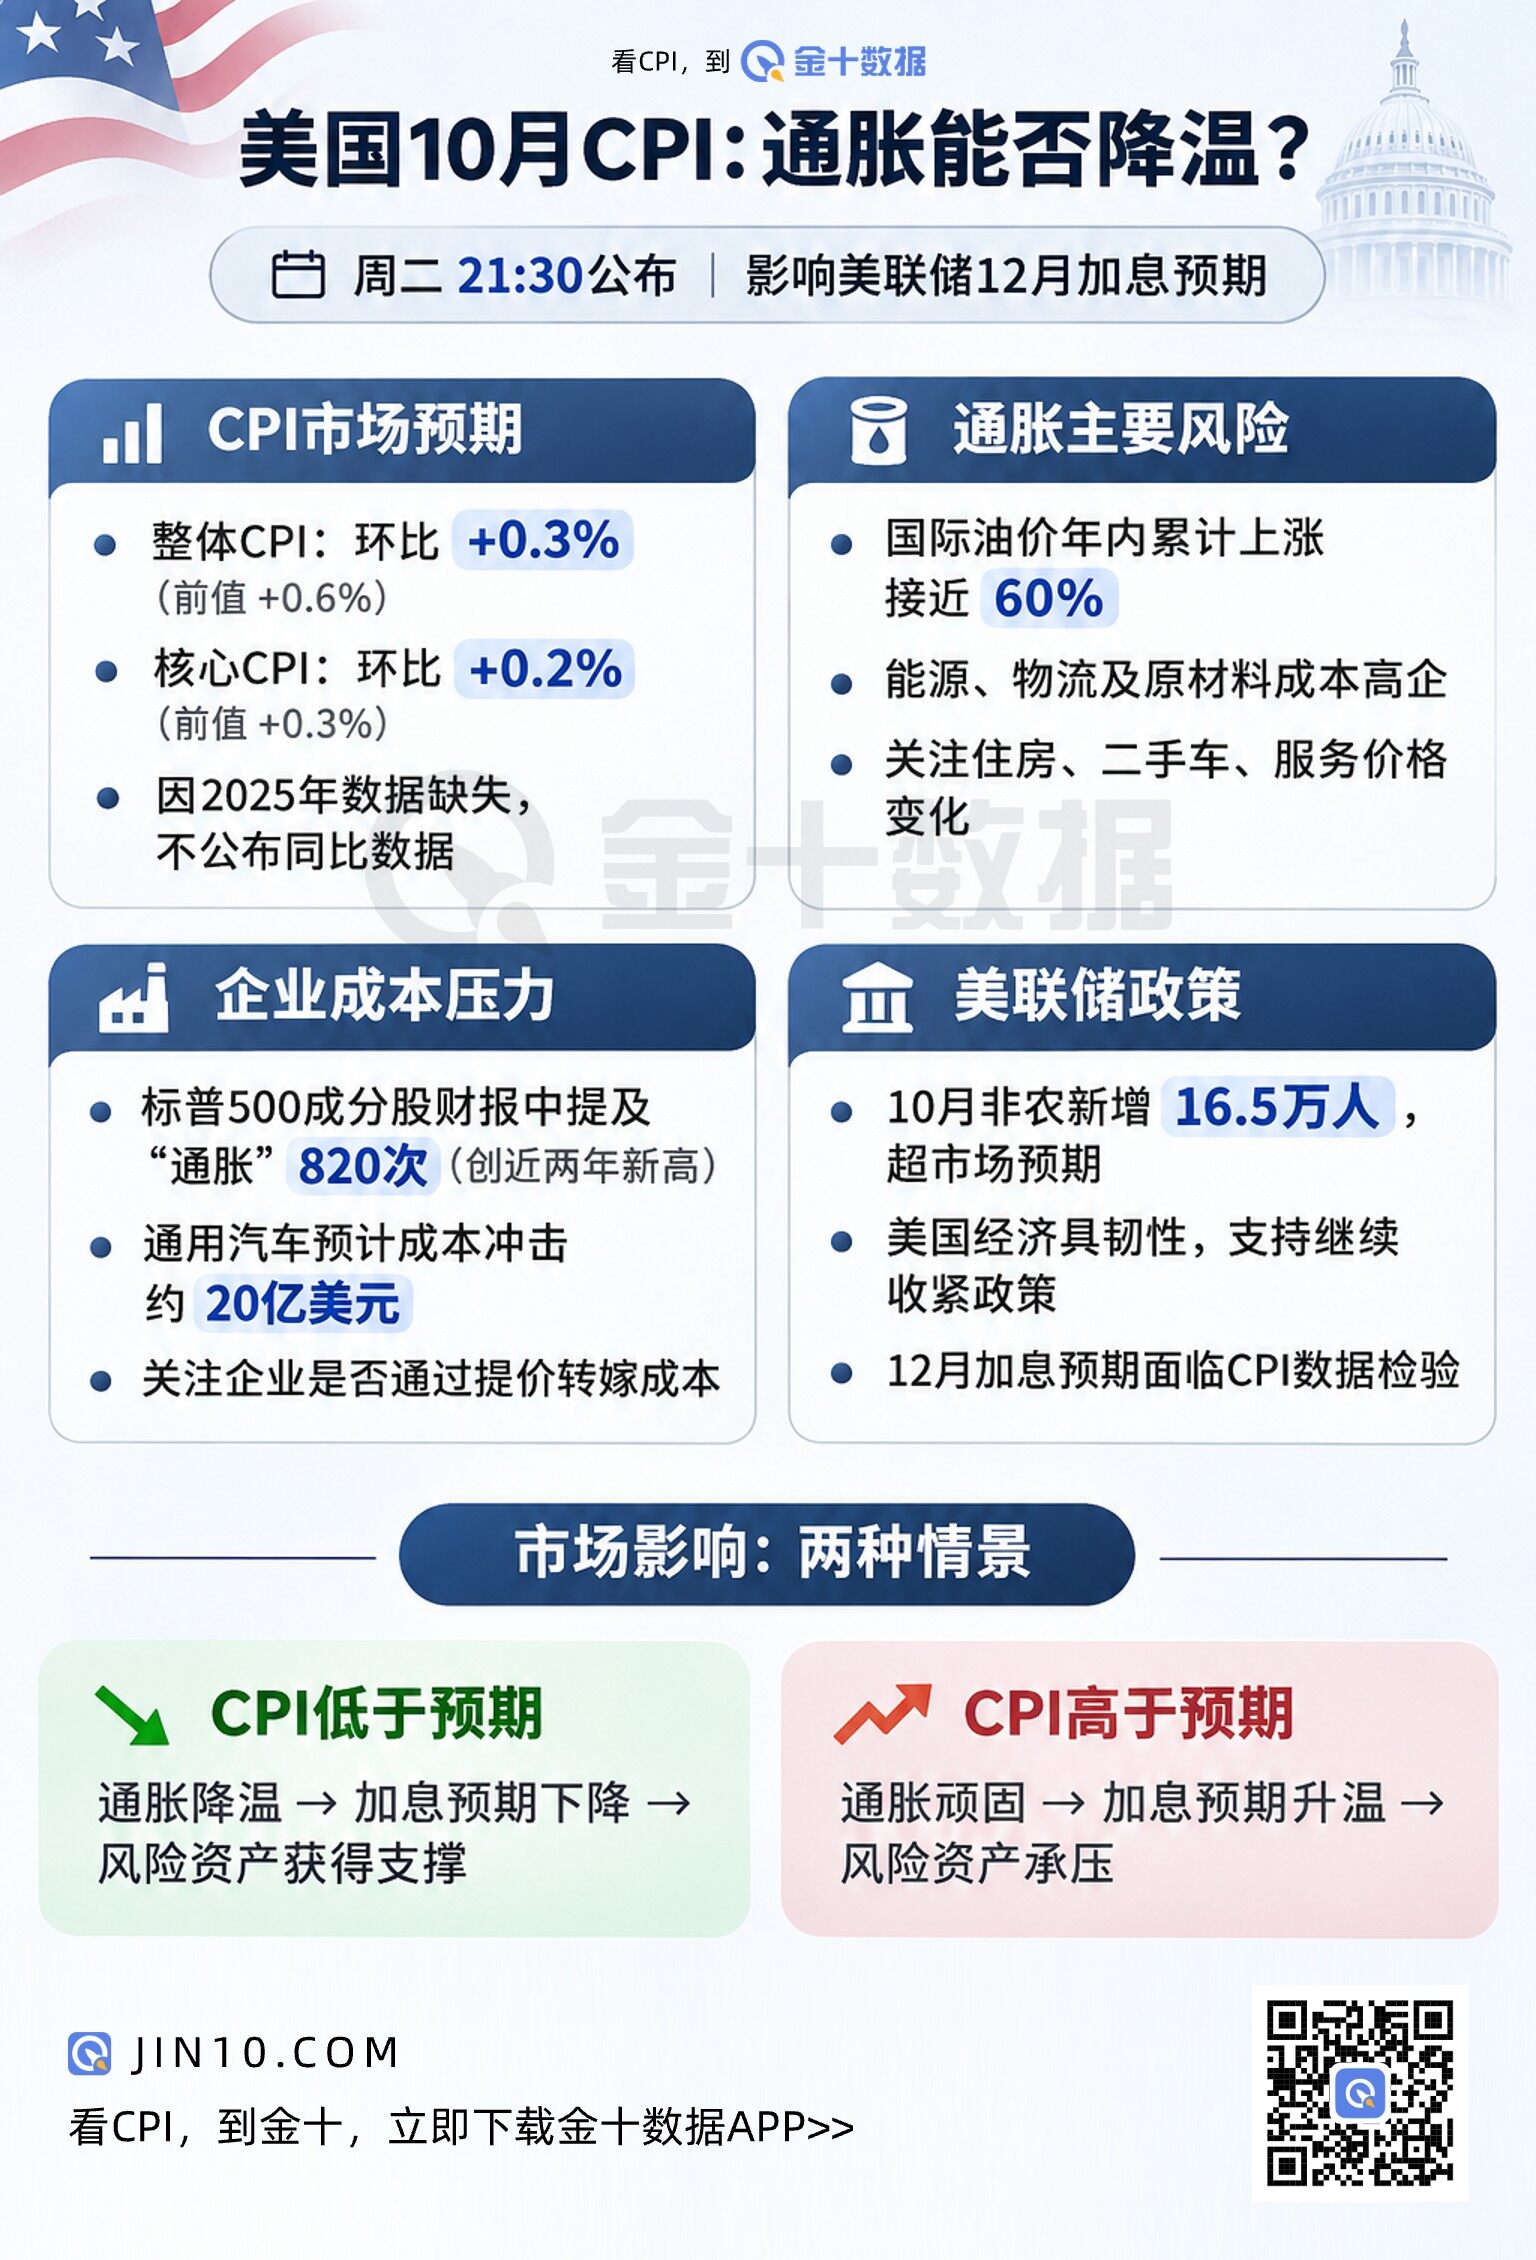
- Economists expect October overall CPI to rise 0.3% month-over-month (previous value 0.6%), and core CPI to rise 0.2% month-over-month, potentially the smallest increase in three months.
- Because the October 2025 government shutdown led to missing data, this release cannot publish the year-over-year annual rate, and the market will rely more on month-over-month data and price components to judge the trend.
- Although energy prices have fallen from highs, their cumulative increase since the start of the year is still nearly 60%, continuing to push up transportation, manufacturing, and household spending costs. Companies passing on pressure may affect future inflation.
- In October earnings calls of S&P 500 constituent companies, "inflation" was mentioned 820 times, a new high since February 2024, with industrial companies accounting for about a quarter.
- General Motors expects rising commodity and logistics costs to bring about $2 billion in adverse impact, and companies such as PPG are considering raising prices to pass on costs.
- October nonfarm payrolls added 165,000 jobs, exceeding expectations. Economic resilience gives the Federal Reserve room to continue focusing on controlling inflation.
- October PPI will be released on Friday and is expected to accelerate to 6.6% year-over-year, the highest in nearly four years, further reflecting price pressure on the production side.
Original source: Jin10 Data
At 21:30 on Tuesday evening, the U.S. Bureau of Labor Statistics will release the October Consumer Price Index (CPI). Investors will focus on whether prices, which have risen significantly for two consecutive months, are beginning to cool, and whether the latest data can change the market's judgment on further Federal Reserve rate hikes.
A Reuters survey shows that economists expect October headline CPI to rise 0.3% month-over-month, down from 0.6% in September; core CPI, excluding food and energy prices, is expected to rise 0.2% month-over-month, potentially marking the smallest increase in three months.
There is a special aspect to note in this CPI report. Due to the U.S. federal government shutdown in October 2025, the CPI report for that month was missing, so the U.S. Bureau of Labor Statistics will lack a reference point this time and will be unable to publish annual (year-over-year) inflation data. The monthly (month-over-month) rate will be released as normal. Therefore, the market will rely more heavily on overall and core CPI month-over-month changes, as well as specific price components, to judge inflation trends.
Additionally, this report will be the last CPI data before the Federal Reserve's December policy meeting (the next CPI will be released later on the same day as the Fed's rate decision). The previously released October nonfarm payrolls report came in stronger than market expectations, further reinforcing the judgment that the U.S. economy remains resilient. For Wall Street, which is reassessing the interest rate outlook, whether inflation can decline as expected has become an important variable determining the next stage of asset price movements.
Inflation Expected to Cool, but Price Pressures Have Not Yet Subsided
Previously, U.S. September CPI rose 0.6% month-over-month, the largest single-month increase since April of this year, and two consecutive months of significant increases have deepened market concerns about inflation persistence.
The latest economist forecasts show that the overall U.S. price increase in October may slow markedly. Core CPI is expected to rise 0.2% month-over-month, down from 0.3% in September. If the forecast holds, it will provide some buffer against the previously strengthening inflation data.
Citigroup economists expect that the pass-through of high energy costs to other goods prices may be relatively limited, and service sector price increases will also remain moderate.
Bloomberg Economics expects that October headline CPI may actually rise about 0.25% month-over-month, with core CPI at about 0.24%. The research team believes that price increases for both goods and services may slow, with changes in prices for used cars, consumer electronics, and housing-related services worth watching.
However, falling energy prices do not mean inflation pressures have been resolved. Although international oil prices fell sharply last week to below $100 per barrel, they are still up nearly 60% since the beginning of the year, and natural gas prices remain far above year-start levels.
Persistently high energy prices are driving up costs in transportation, manufacturing, agriculture, and household spending. Whether companies can continue to absorb these costs, and whether they pass on the pressure by raising prices for goods and services, will affect inflation trends in the coming months.
Corporate Inflation Concerns Rise, Market Also Needs to Watch Price Pass-Through
Recent corporate earnings reports reflect that U.S. inflation pressures have broadly affected different industries.
Bloomberg statistics show that during October earnings calls of S&P 500 constituent companies, "inflation" and related terms were mentioned 820 times, the highest level since February 2024. Industrial companies accounted for about a quarter of the mentions, reflecting pressure from rising energy and logistics costs.
General Motors expects that rising prices for commodities, logistics, and memory chips will bring about $2 billion in adverse impact this year. Coatings manufacturer PPG Industries said it is considering raising product prices to ease raw material cost pressures.
Consumer goods companies are facing similar problems. Seasoning manufacturer McCormick warned that high freight costs and weak consumer spending are simultaneously affecting operations, and the company still needs to assess the inflation and cost outlook for 2027.
These corporate statements make the specific components of October CPI more valuable for reference. If the energy price shock remains mainly concentrated in a few categories such as gasoline, while core goods and services prices begin to slow, the market may believe that the risk of further inflation broadening has eased somewhat. If housing, transportation, and other services prices continue to grow rapidly, inflation persistence will remain the main problem facing the Federal Reserve.
This Friday, the U.S. will also release the October Producer Price Index (PPI). Economists expect that PPI may accelerate to 6.6% year-over-year, reaching the highest level in nearly four years. This data will further reflect price pressures at the corporate production stage and provide supplementary evidence for judging whether costs continue to pass through to consumers.
Whether the Fed Hikes in December: CPI Will Provide Key Evidence
October CPI is drawing high attention directly because the Federal Reserve's monetary policy stance is being tested by persistent inflation.
The Federal Reserve kept the benchmark interest rate unchanged at its late-October policy meeting, but some officials have advocated further monetary tightening. The market currently expects that the Federal Reserve may raise rates in December and continue to raise rates in March next year.
Last Thursday, Cleveland Fed President Hammack said that in order to bring inflation back to the 2% target in a timely manner, the Federal Reserve needs to adopt a restrictive monetary policy stance. She prefers more frequent, smaller rate adjustments to reduce the risk of monetary policy falling behind economic conditions.
Hammack had previously voted against the Fed's rate decision last month. She believes that persistent supply shocks may gradually lead businesses and consumers to form stronger inflation expectations, increasing the difficulty for the central bank to stabilize prices.
The latest employment data also puts the Federal Reserve before a more direct policy choice. U.S. October nonfarm payrolls released last Friday increased by 165,000, exceeding all market forecasts. Resilient job growth shows that the economy can still withstand higher borrowing costs and also gives the Federal Reserve room to continue focusing policy on controlling inflation.
If October core CPI is significantly below market expectations, investors may lower their judgment on the magnitude or frequency of future rate hikes. Conversely, if inflation once again exceeds expectations, the market may reassess how long rates will remain elevated, or even raise expectations for a more tightening policy path.





