


How far is the U.S. from the next financial crisis?


- Core View: Deutsche Bank, based on the Minsky theoretical framework, points out that under the AI boom, U.S. asset prices have already crossed the warning threshold, but corporate leverage remains moderate and has not yet entered the crisis "red zone"; if the trend continues, it will clearly approach the warning boundary around 2028, and the manner of credit expansion may become a key variable.
- Key Elements:
- The Deutsche Bank GHSS framework uses a three-year increase in corporate debt/GDP of more than 9 percentage points and a three-year gain in real stock prices of more than 26% as the dual thresholds for the "red zone." Once both lines are crossed simultaneously, the probability of a crisis within three years reaches 45%.
- Current U.S. equity gains have easily surpassed the asset price threshold, but the rise in corporate leverage remains moderate. This round of the AI rally looks more like a technology boom driven by equities and physical investment rather than a large-scale debt-fueled bubble.
- Historical validation: Japan in 1989 and Thailand in 1994 both significantly exceeded the red zone boundaries; in the 2000 internet bubble, stock prices soared but leverage was limited, so it did not evolve into a full-scale financial crisis.
- Under the baseline assumption (extrapolating credit growth in 2027 and an annualized 12.5% stock price growth rate), the U.S. will move clearly closer to the red zone in 2028 but is expected to remain outside the boundary.
- Structural shift: the financing source for AI-related capital expenditure is shifting from operating cash flow to external debt financing. How credit responds will become the core of risk assessment in the next stage.
- Other potential risk points: the rapidly expanding private credit market in lightly regulated areas, and global sovereign balance sheets that have continued to rise after multiple rounds of fiscal expansion.
Author: Zhao Ying
Source: Wallstreetcn
Economic prosperity breeds the seeds of the next crisis—this is the most profound warning that economist Hyman Minsky left to the world. Today, the AI boom has driven US stocks to highs, borrowing costs remain loose, and beneath the calm surface, key indicators measuring financial fragility are quietly shifting. Deutsche Bank believes that the US has not yet reached the "red alert zone" that preceded historical crises, but if current trends continue, this distance could narrow significantly around 2028.
According to Trading Desk, Deutsche Bank noted in its latest report, using its latest financial crisis prediction framework, that the "double-high" combination of rapid asset price increases and strong credit expansion has historically been the most dangerous precursor to a crisis. Under this framework, once both indicators simultaneously cross the threshold into the "red zone," the probability of a financial crisis occurring in the corporate sector within the next three years is as high as 45%.
At present, US stock gains have easily crossed the asset price threshold, but the rise in corporate leverage has so far remained moderate. This means the current AI rally is more like a technology-driven boom led by equities and real investment, rather than a traditional bubble reliant on large-scale borrowing.
However, Deutsche Bank also warns that the funding sources for AI-related investment are shifting from operating cash flow to external financing (including debt financing). The US will move noticeably closer to the "red alert zone" by 2028, but is expected to remain outside the boundary.
Minsky Moment: Stability Itself Is Destabilizing
Minsky's most famous assertion is that "stability is destabilizing"—the longer good times last, the more both borrowers and lenders dare to take risks, until the conditions for the next crisis quietly mature.
Deutsche Bank's report raises its core question precisely within this theoretical framework: since the 2008 global financial crisis, despite experiencing the COVID-19 shock, geopolitical conflicts, surging inflation, and the most aggressive global monetary tightening cycle in decades, the world has not experienced a major financial crisis with lasting macroeconomic impact. Even the 2023 US regional banking turmoil was brought under control relatively quickly.
This apparent stability is precisely the potential breeding ground for Minsky's logic. For this reason, Deutsche Bank's research team believes that the most pressing question today is not "why no crisis has occurred," but "where the next vulnerability is accumulating."
The US Remains Outside the "Red Zone," with 2028 Potentially a Key Observation Point
According to Deutsche Bank's report, the GHSS framework it employs uses the three-year change in corporate debt/GDP and the three-year gain in real stock prices as its two core axes, with a rise in corporate debt/GDP exceeding 9 percentage points and a real stock price increase exceeding 26% as the dual thresholds for entering the "red zone."
Historical comparisons reveal the predictive power of this framework. Before the collapse of Japan's bubble economy in 1989, and around Thailand in 1994, both indicators significantly exceeded the "red zone" boundary. Before the 2008 financial crisis, the euro area, driven by a handful of peripheral countries, also entered the danger zone. By contrast, during the 2000 dot-com bubble, US stock prices rose sharply, but leverage accumulation was relatively moderate, keeping the overall position outside the "red zone"—which partly explains why the subsequent deep stock market bear market did not evolve into a full-blown financial crisis.
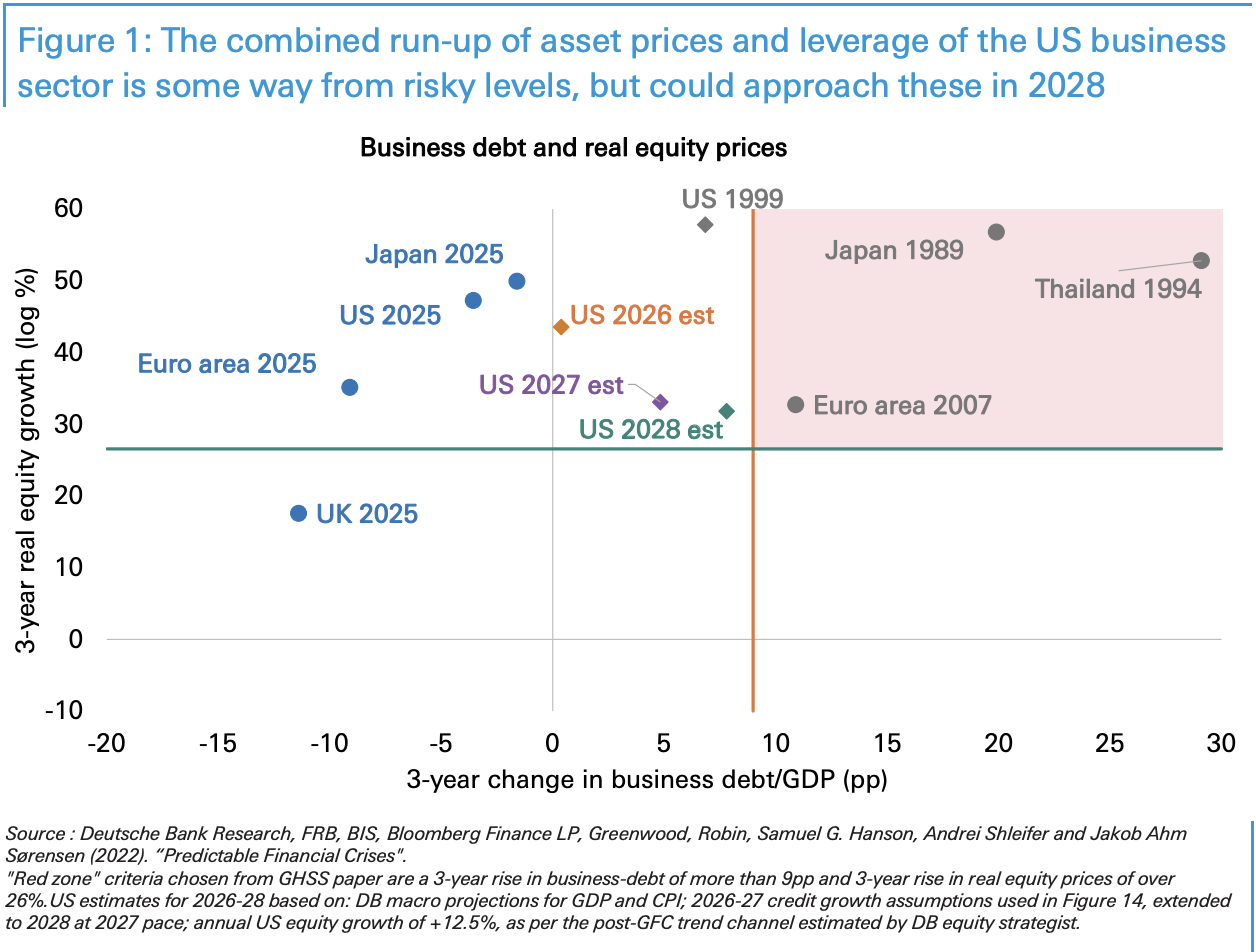
Deutsche Bank's calculations show that the US is currently in a relatively safe position on the chart, with corporate leverage growth in 2025 still restrained. According to the bank's estimates, under baseline assumptions—including its macroeconomic GDP and inflation forecasts, extrapolation of 2027 credit growth to 2028, and an annualized 12.5% stock price growth rate referencing post-financial-crisis trends—the US will move noticeably closer to the "red zone" by 2028, but is expected to remain outside the boundary.
The AI Boom: Investment-Driven or a Debt Bubble?
The core debate in the current market is whether this AI wave is a rational technology investment cycle or another credit expansion bubble manifesting in a different form.
Deutsche Bank's analysis offers a relatively cautious judgment: to date, the AI boom has been driven more by rising stock prices and real capital expenditure than by systemic leverage. This bears some similarity to the dot-com bubble period—which was also characterized primarily by surging stock prices with limited debt accumulation, and ultimately triggered a severe stock market correction but not a full-blown financial crisis.
However, the report also flags a structural shift: the funding sources for AI-related capital expenditure are migrating, gradually moving from companies' own operating cash flow toward external debt financing. If this trend continues, whether credit growth and stock price gains can maintain their current state will become a key variable in determining the direction of risk in the next phase. As the report states, "how credit responds in this new phase of AI buildout may prove to be the crux."
Other Potential Risks: Private Credit and Sovereign Balance Sheets
Beyond AI-related risks, Deutsche Bank's report also points to two other potential crisis candidates: the rapid expansion of the private credit market and the widespread stretching of global sovereign balance sheets.
The report notes that post-2008 regulatory reforms and faster policy intervention mechanisms have made the transmission and contagion of crises more difficult—an important institutional reason why the world has successfully avoided major financial crises over the past decade and more. However, the private credit market has expanded rapidly in grey areas with relatively weak regulatory coverage, and sovereign debt levels have continued to climb after multiple rounds of fiscal expansion. Both constitute potential accumulation points of systemic risk that warrant sustained investor attention.
Overall, Deutsche Bank's conclusion is not an alarm but a forward-looking stress test based on a quantitative framework. By its estimates, 2028 is an observation point worth flagging. Before then, plenty of variables still have ample time to change, but the key point is this: Minsky's logic has never failed—the calmer things are, the more vigilant one must be.





