


MSX US Stock Daily Watch: AMD Q3 Earnings: Data Center Revenue Up 97%, MI450 and Helios Propel Performance into an Acceleration Phase


- Key Takeaways: AMD is accelerating its transformation from a CPU and gaming chip vendor into an AI infrastructure platform spanning CPUs, GPUs, networking, rack-scale systems, and software, with the data center business becoming its core growth engine—though the surge in revenue and profit has yet to translate into free cash flow in tandem.
- Key Points:
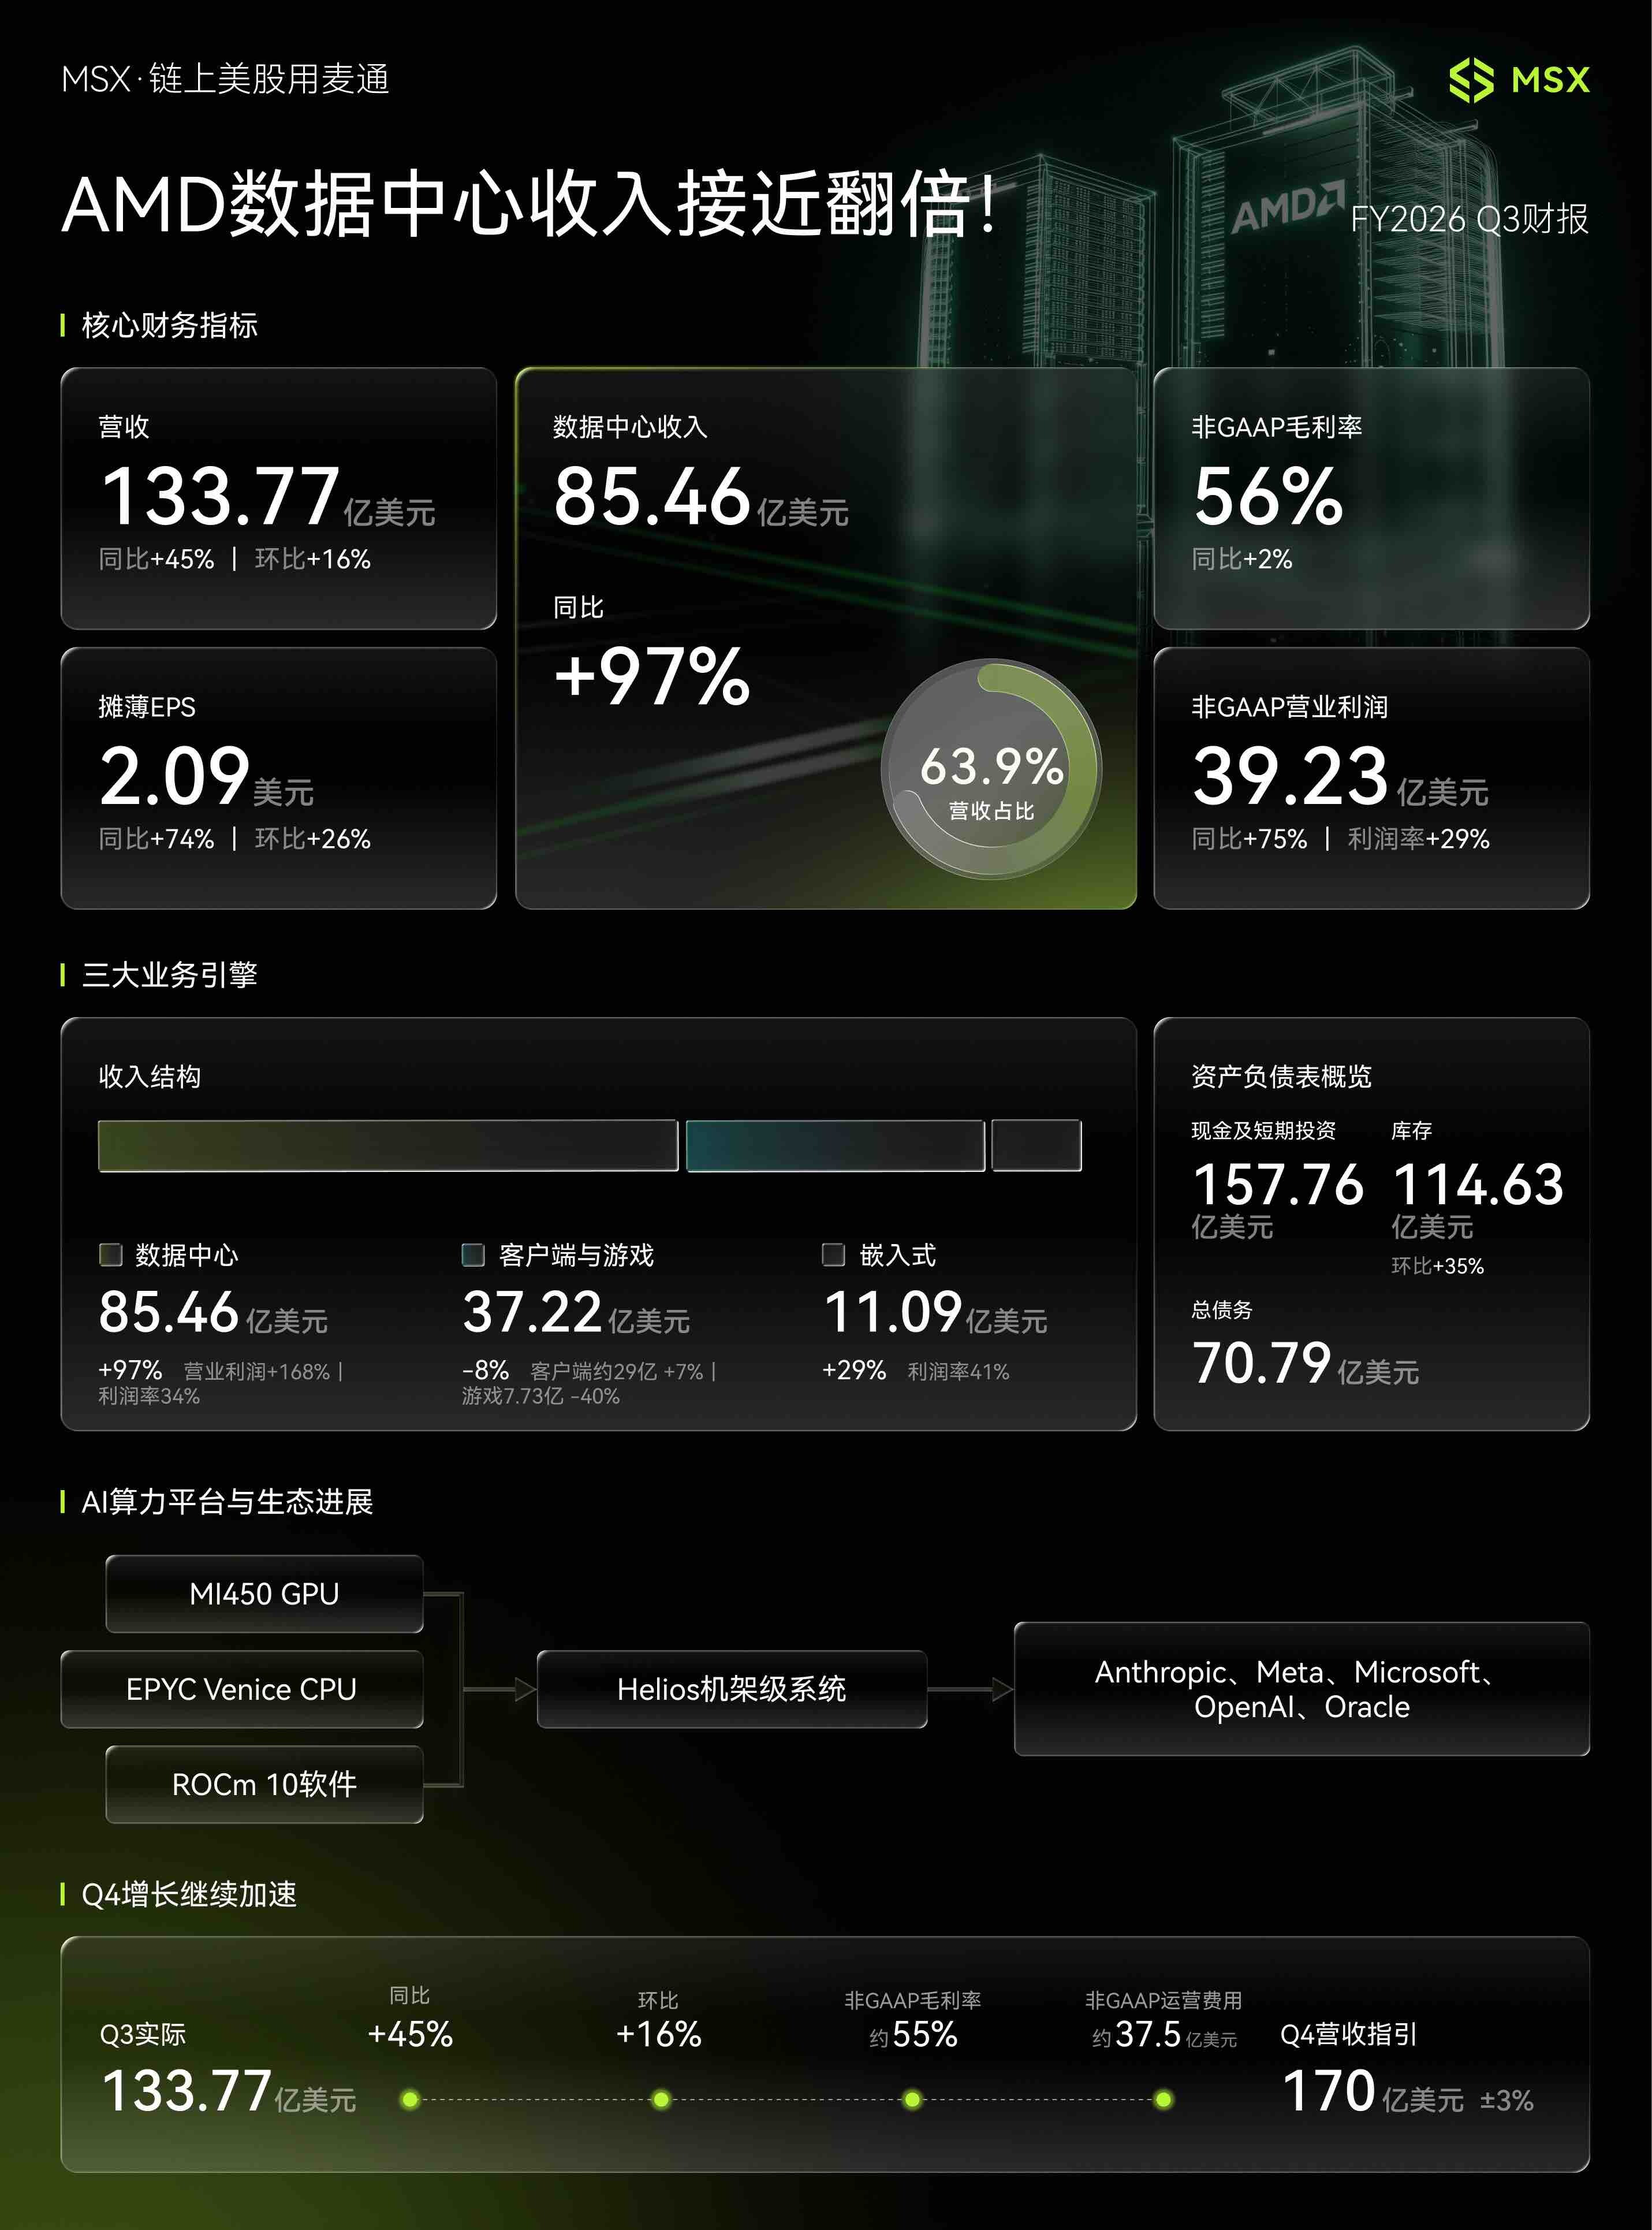
- FY2026 Q3 revenue was $13.377 billion, up 45% year-over-year, with adjusted EPS of $2.09, up 74% year-over-year, both beating market expectations.
- Data center revenue was $8.546 billion, up 97% year-over-year, accounting for approximately 64% of total revenue; the segment's operating margin rose from about 25% to about 34%.
- The MI450 GPU and Helios rack-scale system have secured first-wave deployments with Anthropic, Meta, Microsoft, OpenAI, and Oracle Cloud Infrastructure.
- Q4 revenue guidance is approximately $17 billion, with management expecting data center revenue to grow about 50% quarter-over-quarter and AI GPU scale to surpass server CPUs for the first time.
- Management expects total revenue growth of over 80% in 2027, with the data center business contributing more than 80% of company revenue.
- Q3 free cash flow was only $554 million, while inventory grew 35% quarter-over-quarter to $11.463 billion as the company stocked up ahead of ramp-up—a key risk indicator to watch.
- Approximately $1.097 billion in non-cash customer warrant expenses widened the gap between GAAP and adjusted profit, raising potential equity dilution concerns.
[MSX Research Institute · Daily US Stock RWA Watch] is a signature daily report produced by MSX Maitong, a leading RWA trading platform. Leveraging our strong macro research capabilities, we help you capture the core pulse of global traditional US stocks, liquidity changes, and the RWA tokenization market, so you can position ahead of the curve in quality assets.
Today's Watch
AMD is accelerating its transformation from a semiconductor company focused on CPUs and gaming chips into an AI infrastructure platform spanning CPUs, GPUs, networking, rack-scale systems, and software.
In Q3 FY2026, AMD's revenue reached $13.377 billion, up 45% year-over-year and 16% quarter-over-quarter, beating market expectations of approximately $13.06 billion; adjusted EPS was $2.09, up 74% year-over-year, beating market expectations of approximately $1.94. GAAP operating income reached $2.832 billion, up 123% year-over-year; adjusted operating income reached $3.923 billion, up 75% year-over-year. Adjusted operating margin rose to 29% from 24% in the prior-year period, indicating that the expansion of the data center business is not only driving revenue growth but also beginning to unlock operating leverage.
What makes this earnings report more meaningful is the data center business. Q3 data center revenue reached $8.546 billion, up 97% year-over-year and 27% quarter-over-quarter, accounting for approximately 64% of total company revenue. The segment's operating income reached $2.882 billion, up 168% year-over-year, with operating margin rising to approximately 34% from approximately 25% in the prior-year period.
Growth came from both EPYC server CPUs and Instinct AI GPUs. AMD has begun ramping the MI450 series GPUs and Helios rack-scale systems, with Anthropic, Meta, Microsoft, OpenAI, and Oracle Cloud Infrastructure already running models or workloads on the first batch of Helios systems. The next-generation "Venice" EPYC server CPU has also entered the volume ramp phase.
AMD expects Q4 revenue of approximately $17 billion, plus or minus 3%, corresponding to a range of approximately $16.49 billion to $17.51 billion, with the midpoint above market expectations of approximately $16.23 billion. At the midpoint, Q4 revenue is expected to grow approximately 66% year-over-year and approximately 27% quarter-over-quarter.
Management expects Q4 data center revenue to grow approximately 50% quarter-over-quarter, with the AI GPU business also surpassing the server CPU business in scale for the first time. The company also expects total revenue growth of more than 80% in 2027, with server CPU revenue nearly doubling and the data center business contributing more than 80% of company revenue. Following the earnings release, AMD's stock rose as much as approximately 7.5% in after-hours trading.
Data in a Minute
• Q3 FY2026 revenue of $13.377 billion, up 45% year-over-year and 16% quarter-over-quarter;
• Market expected revenue of approximately $13.06 billion;
• Data center revenue accounted for approximately 63.9% of total revenue;
• Data center operating income of $2.882 billion, up 168% year-over-year;
• Data center operating margin of approximately 33.7%, versus approximately 24.7% in the prior-year period;
• Client and gaming segment revenue of $3.722 billion, down 8% year-over-year and 3% quarter-over-quarter;
• Of which client revenue was $2.949 billion, up 7% year-over-year;
• Gaming revenue was $773 million, down 40% year-over-year;
• Client and gaming segment operating income of $573 million, down 34% year-over-year;
• Embedded segment revenue of $1.109 billion, up 29% year-over-year and 14% quarter-over-quarter;
• Embedded segment operating income of $453 million, up 60% year-over-year;
• Embedded segment operating margin of approximately 40.8%;
• Q3 operating cash flow of $1.202 billion;
• Capital expenditures of $648 million;
• Free cash flow of $554 million, down from $1.530 billion in the prior-year period;
• Free cash flow margin of approximately 4%;
• Cash, cash equivalents, and short-term investments totaled $15.776 billion at quarter-end;
• Total debt of $7.079 billion, including $4.75 billion in senior notes financing completed in August;
• Market previously expected Q4 revenue of approximately $16.23 billion;
• Q4 adjusted gross margin guidance of approximately 55%;
• Management expects the data center business to account for more than 80% of company revenue in 2027;
• Following the earnings release, AMD's stock rose as much as approximately 7.5% in after-hours trading.
MSX View
AMD currently has three growth curves. The first is EPYC. Although AI data centers rely primarily on GPUs as the main compute resource, every GPU system still requires CPUs to handle system scheduling, network management, storage access, data preprocessing, and a large number of general-purpose computing tasks. The larger the AI cluster, the higher the demand for high-performance server CPUs.
AMD's EPYC business therefore benefits from two trends simultaneously: first, continued share gains in the traditional server CPU market; second, growth in total server demand driven by AI data center expansion. The next-generation "Venice" processor will adopt the Zen 6 architecture, and AMD expects the product to begin ramping production in Q4. Management expects server CPU revenue to nearly double in 2027, indicating that the company believes the AI infrastructure pull on CPUs is not a short-term phenomenon.
The second growth curve is Instinct GPUs. The MI450 series is AMD's key product in its attempt to narrow the gap with Nvidia. Compared with earlier sales of individual accelerator cards, MI450 and Helios are now delivered as complete rack systems, integrating GPUs, EPYC CPUs, networking chips, interconnects, cooling systems, and ROCm software into a single platform.
This shift is significant. Large AI customers are no longer buying just chips, but a complete computing system that can be installed, networked, and run models directly. Rack-scale products involve larger individual contracts and place higher demands on supply chain coordination, networking technology, software compatibility, and delivery capability. AMD stated that Anthropic, Meta, Microsoft, OpenAI, and Oracle Cloud Infrastructure are already running models or workloads on the first batch of Helios systems. This indicates that Helios has moved beyond the pure product demonstration stage and entered customer validation and initial deployment.
The third growth curve is a complete AI platform. AMD previously relied mainly on customers purchasing CPUs, GPUs, and other components themselves, with server vendors completing integration. Now the company is expanding upward into Helios rack systems while filling in networking, software, and dedicated inference chips downstream. The company has released ROCm 10 and launched the Helion reference architecture for agentic systems. AMD also plans to acquire World Labs and Taalas: World Labs can supplement spatial intelligence and world model research capabilities, while Taalas focuses on custom inference chips. These investments show that AMD aims to participate not just in the GPU market, but in a complete AI infrastructure system spanning models, software, chips, and rack systems.
This strategy also brings new risks. First, AMD needs to invest simultaneously in GPU architecture, CPUs, networking, software, rack design, and customer support, significantly increasing R&D and operational complexity. Adjusted operating expenses grew 29% year-over-year to $3.560 billion this quarter, still a relatively fast pace.
Second, some large AI agreements include customer warrants. AMD recognized approximately $1.097 billion in non-cash charges this quarter related to changes in the fair value of customer warrants, widening the gap between GAAP and adjusted profit.
Warrants can help AMD lock in large customers, but may also create potential equity dilution. Judging whether these agreements create value for shareholders requires comparing the revenue, profit, and cash flow ultimately generated by customers against the cost of warrants and related investments.
Third, revenue and profit growth have not yet translated into free cash flow in sync. AMD's Q3 adjusted net income reached $3.471 billion, but free cash flow was only $554 million. The main reason is not business losses but the company preparing inventory and expanding working capital for rapid ramping. Inventory increased by approximately $2.995 billion this quarter, accounts receivable increased by approximately $1.928 billion; accounts payable increased by approximately $2.313 billion, partially offsetting the cash usage. Inventory reached $11.463 billion at quarter-end, up 35% quarter-over-quarter.
Preparing chips, packaging, memory, and system components ahead of the large-scale ramp of MI450, Helios, and Venice is commercially reasonable. If Q4 and 2027 orders are delivered as planned, this inventory will convert into revenue and cash flow. However, if customer data centers delay going live, supply chain mismatches occur, or product demand changes, high inventory could also lead to slower turnover and impairment risk. Therefore, inventory growth is both a leading signal of future revenue acceleration and a risk indicator that must be continuously monitored.
The main question the market has had about AMD in the past is whether Instinct products can move from small-scale trials to large-scale procurement. Now, data center revenue is nearly doubling, MI450 and Helios are beginning to contribute revenue, multiple leading customers have entered system validation and deployment, and Q4 data center revenue is expected to grow approximately 50% quarter-over-quarter.
About MSX Maitong:
MSX is a leading RWA trading platform dedicated to providing secure, efficient, and transparent access to global financial markets. As one of the world's earliest on-chain US stock trading platforms, MSX has always been at the forefront of the industry, leading market transformation through continuous innovation.
The platform deeply integrates blockchain technology with compliance frameworks, comprehensively offering spot and derivatives trading for nearly 400 tokenized stocks and Pre-IPO assets, perfectly bridging the gap between traditional finance and the digital asset industry.
Centered on the core mission of "enabling free circulation of quality assets," MSX has now built a diversified digital financial services system covering US stock spot and perpetual contracts, crypto trading, Pre-IPO, and Maitong Research Institute, aiming to provide global investors with all-hours, high-performance access to quality assets.
Official Website: https://msx.com/
Chinese TG:https://t.me/MSXOfficial
Global TG:https://t.me/MSXGlobal
Risk Disclaimer: Macroeconomic conditions and US stock markets are highly volatile. This content is for academic and research observation reference by Maitong Research Institute only and does not constitute any investment advice.





