


Global Payments Weekly 2026W41


- Key Takeaways: This week, the focus of crypto payments shifted from exchanges to corporate finance and treasury scenarios, with stablecoins being used by SAP, PayPal, and others for B2B settlement; meanwhile, the EU issued a wind-down order for non-MiCA stablecoins, and USDT liquidity faces a migration window.
- Key Elements:
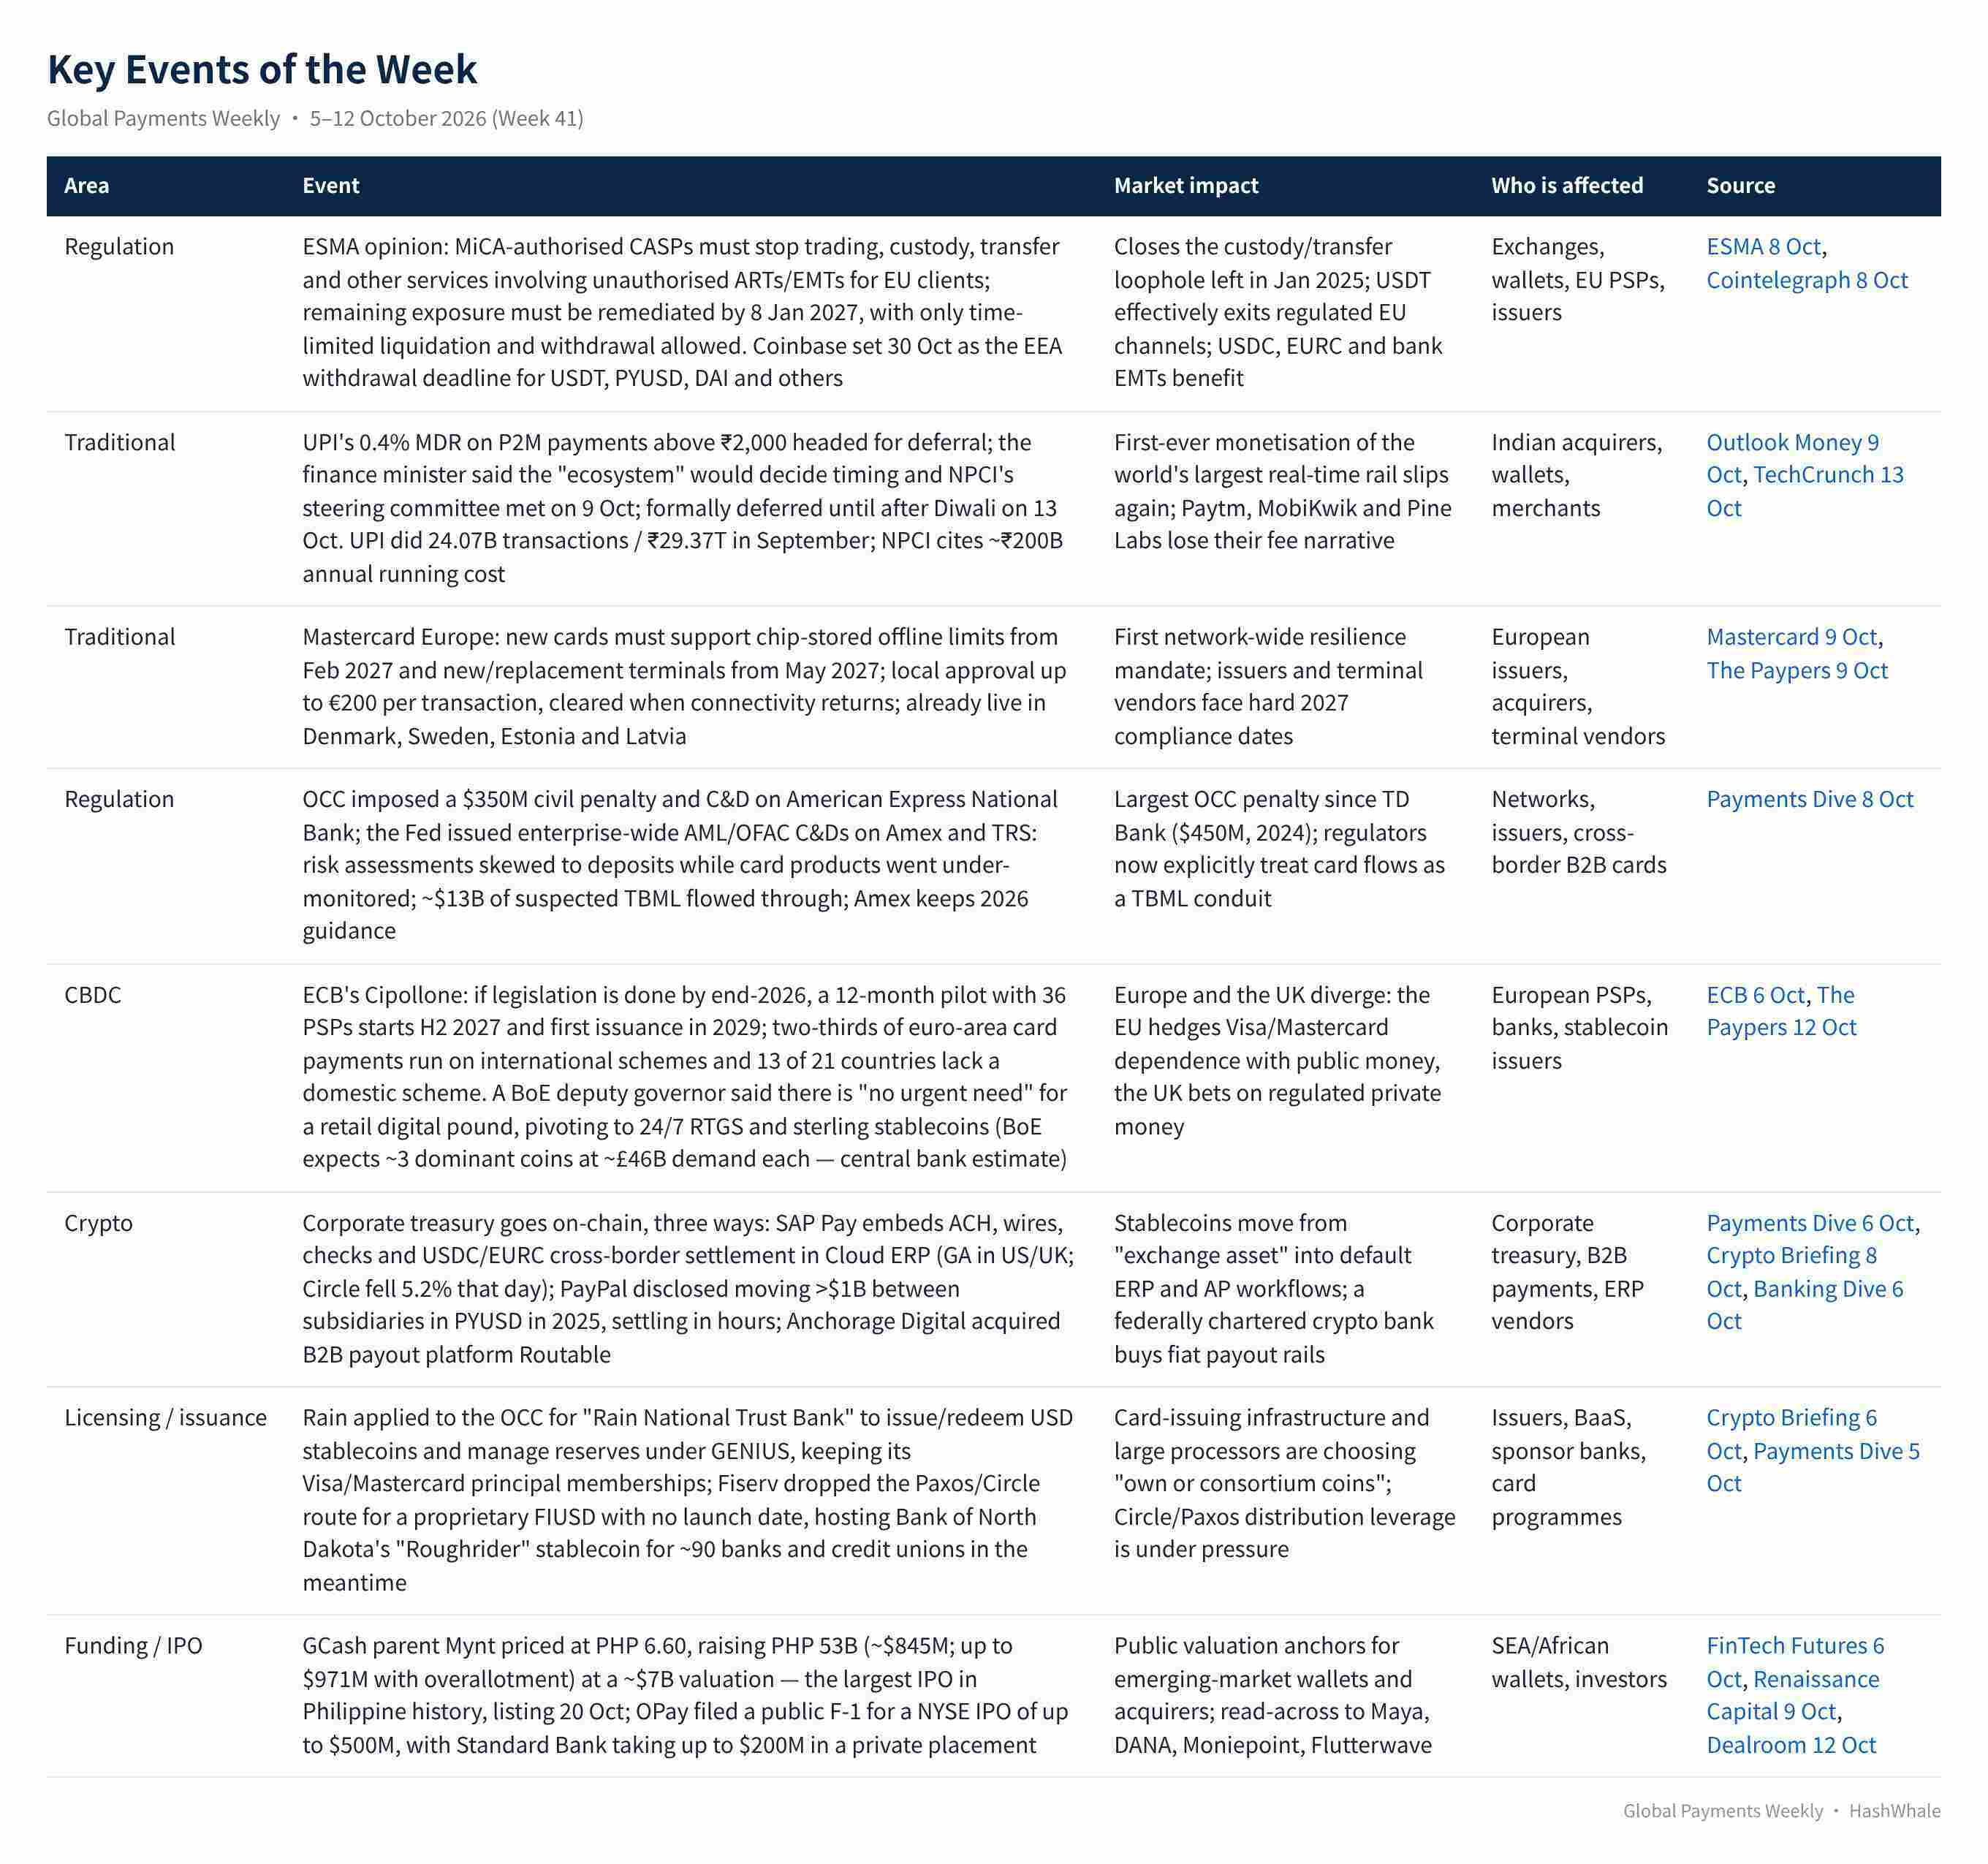
- ESMA replaced its whitelist with a wind-down order, setting explicit termination dates for non-MiCA stablecoins. European PSPs must migrate USDT to USDC/EURC or bank-issued EMTs within three months.
- India's UPI fee reversal—from a September announcement to an October postponement in just four weeks—demonstrates that pricing power for real-time payments rests with politics rather than NPCI, and that zero-fee rails have become public infrastructure.
- Mastercard's mandatory offline payment requirement and the BoE's 24/7 RTGS emphasize that "usable without connectivity" has shifted from optional to a compliance requirement, pulling terminal upgrade cycles forward to 2027.
- The week's most significant crypto payment news came from SAP, PayPal treasury, Anchorage, and Rain. Demand in enterprise AP and treasury scenarios centers on settlement finality and reconcilable accounting, not yield.
- Distribution alliances are replacing single issuers: Fiserv dropped Paxos/Circle, Rain applied for its own license, and Arbitrum joined the Paxos USDG network (circulating supply exceeding $3 billion). Reserve income distribution determines channel allegiance.
- Circle fell 5.2% despite the SAP Pay news, reflecting market concerns about its distribution leverage; total stablecoin supply this week ranged from $305 billion to $313 billion.
Period: 5–12 October 2026 (Week 41) · For traditional and crypto payments professionals · ~4-minute read
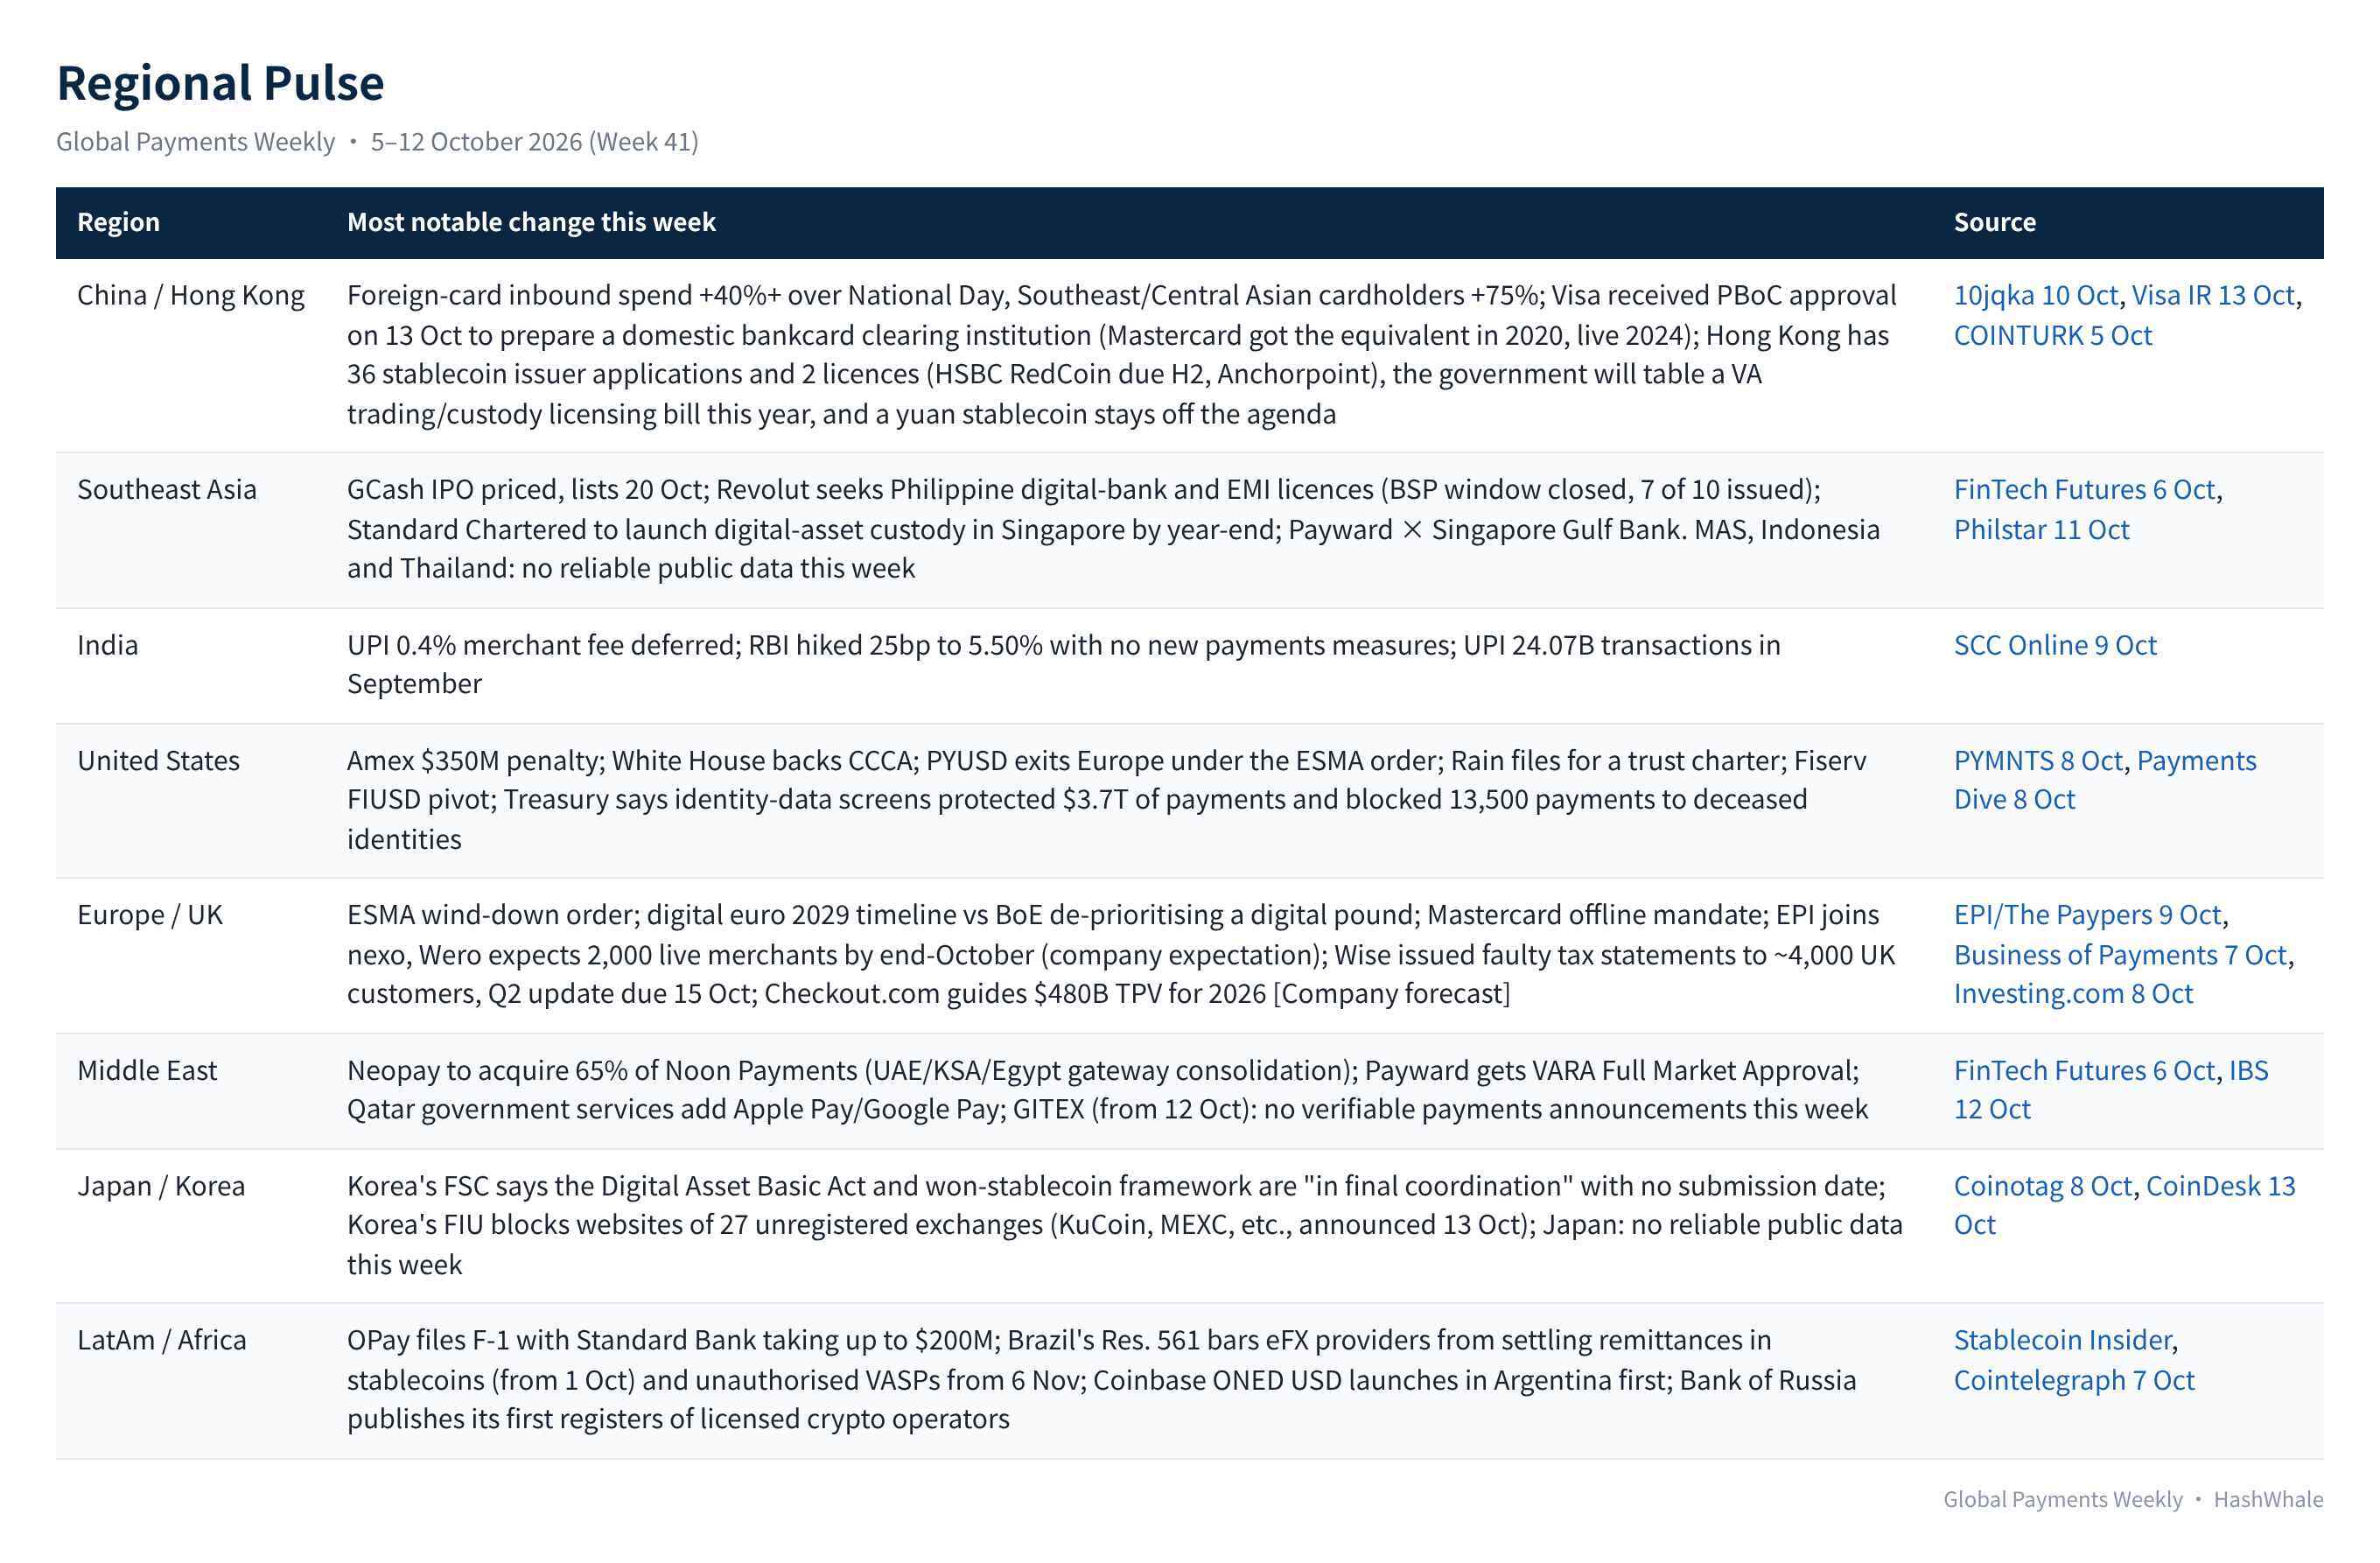
Note: All items are sourced from regulators, company announcements and mainstream financial/industry media, each with a publication date and link. [Forecast] and [Opinion] mark institutional or personal views; everything else is fact. No verifiable major public information was found this week for Southeast Asia (Singapore/Indonesia/Thailand) or Japan beyond the items listed; those cells are marked "no reliable public data this week".
1. This Week at a Glance

W38 watchlist follow-up: Sibos → Swift's blockchain ledger declared live, 19 banks expected by year-end (company expectation); FCA stablecoin gateway → opened in September, no new developments this week; October effective dates → UPI fee deferred; Brazil's Resolution 561 (barring eFX providers from settling remittances in stablecoins) took effect 1 Oct.
2. Industry Thermometer

3. Key Events of the Week
 Why it matters (editorial analysis)
- The EU replaces a whitelist with a wind-down order. ESMA named no tokens, but by closing custody and transfers it gave non-MiCA stablecoins a definite end date. For PSPs operating in Europe, the next three months are a migration window for USDT liquidity into USDC/EURC or bank EMTs, not a wait-and-see period.
- Charging for real-time payments is harder than legislating. UPI went from announcement in September to deferral in October in four weeks: where zero-fee rails have become public infrastructure, pricing power sits with politics, not NPCI. Indian PSPs valued on a "fee switch" need to return to a value-added-services story.
- Resilience becomes a compliance item. Mastercard's offline mandate and the BoE's emphasis on 24/7 RTGS both turn "works without connectivity" from optional into required; terminal refresh cycles are pulled forward and acquirer hardware costs cluster in 2027.
- Stablecoins are changing customers. This week's heaviest crypto-payments news came from SAP, PayPal treasury, Anchorage and Rain, not exchanges. Corporate AP and treasury use cases do not need yield; they need certainty of settlement and reconcilable accounting — the use case least affected by GENIUS's interest ban.
- Distribution consortia displace single issuers. Fiserv dropping Paxos/Circle, Rain filing its own charter, Arbitrum joining Paxos's Global Dollar Network (USDG >$3B in circulation) and Open USD's late-September launch all say the same thing: who shares reserve income decides channel ownership. Circle fell 5.2% on what looked like good SAP Pay news — the market's worry about its distribution leverage is visible.
4. Deep Dive: Crypto & Web3 Data and Views
4.1 Stablecoin and On-chain Data Board

Trackers differ by several billion dollars; treat $305–313B as the band for this week's total supply.
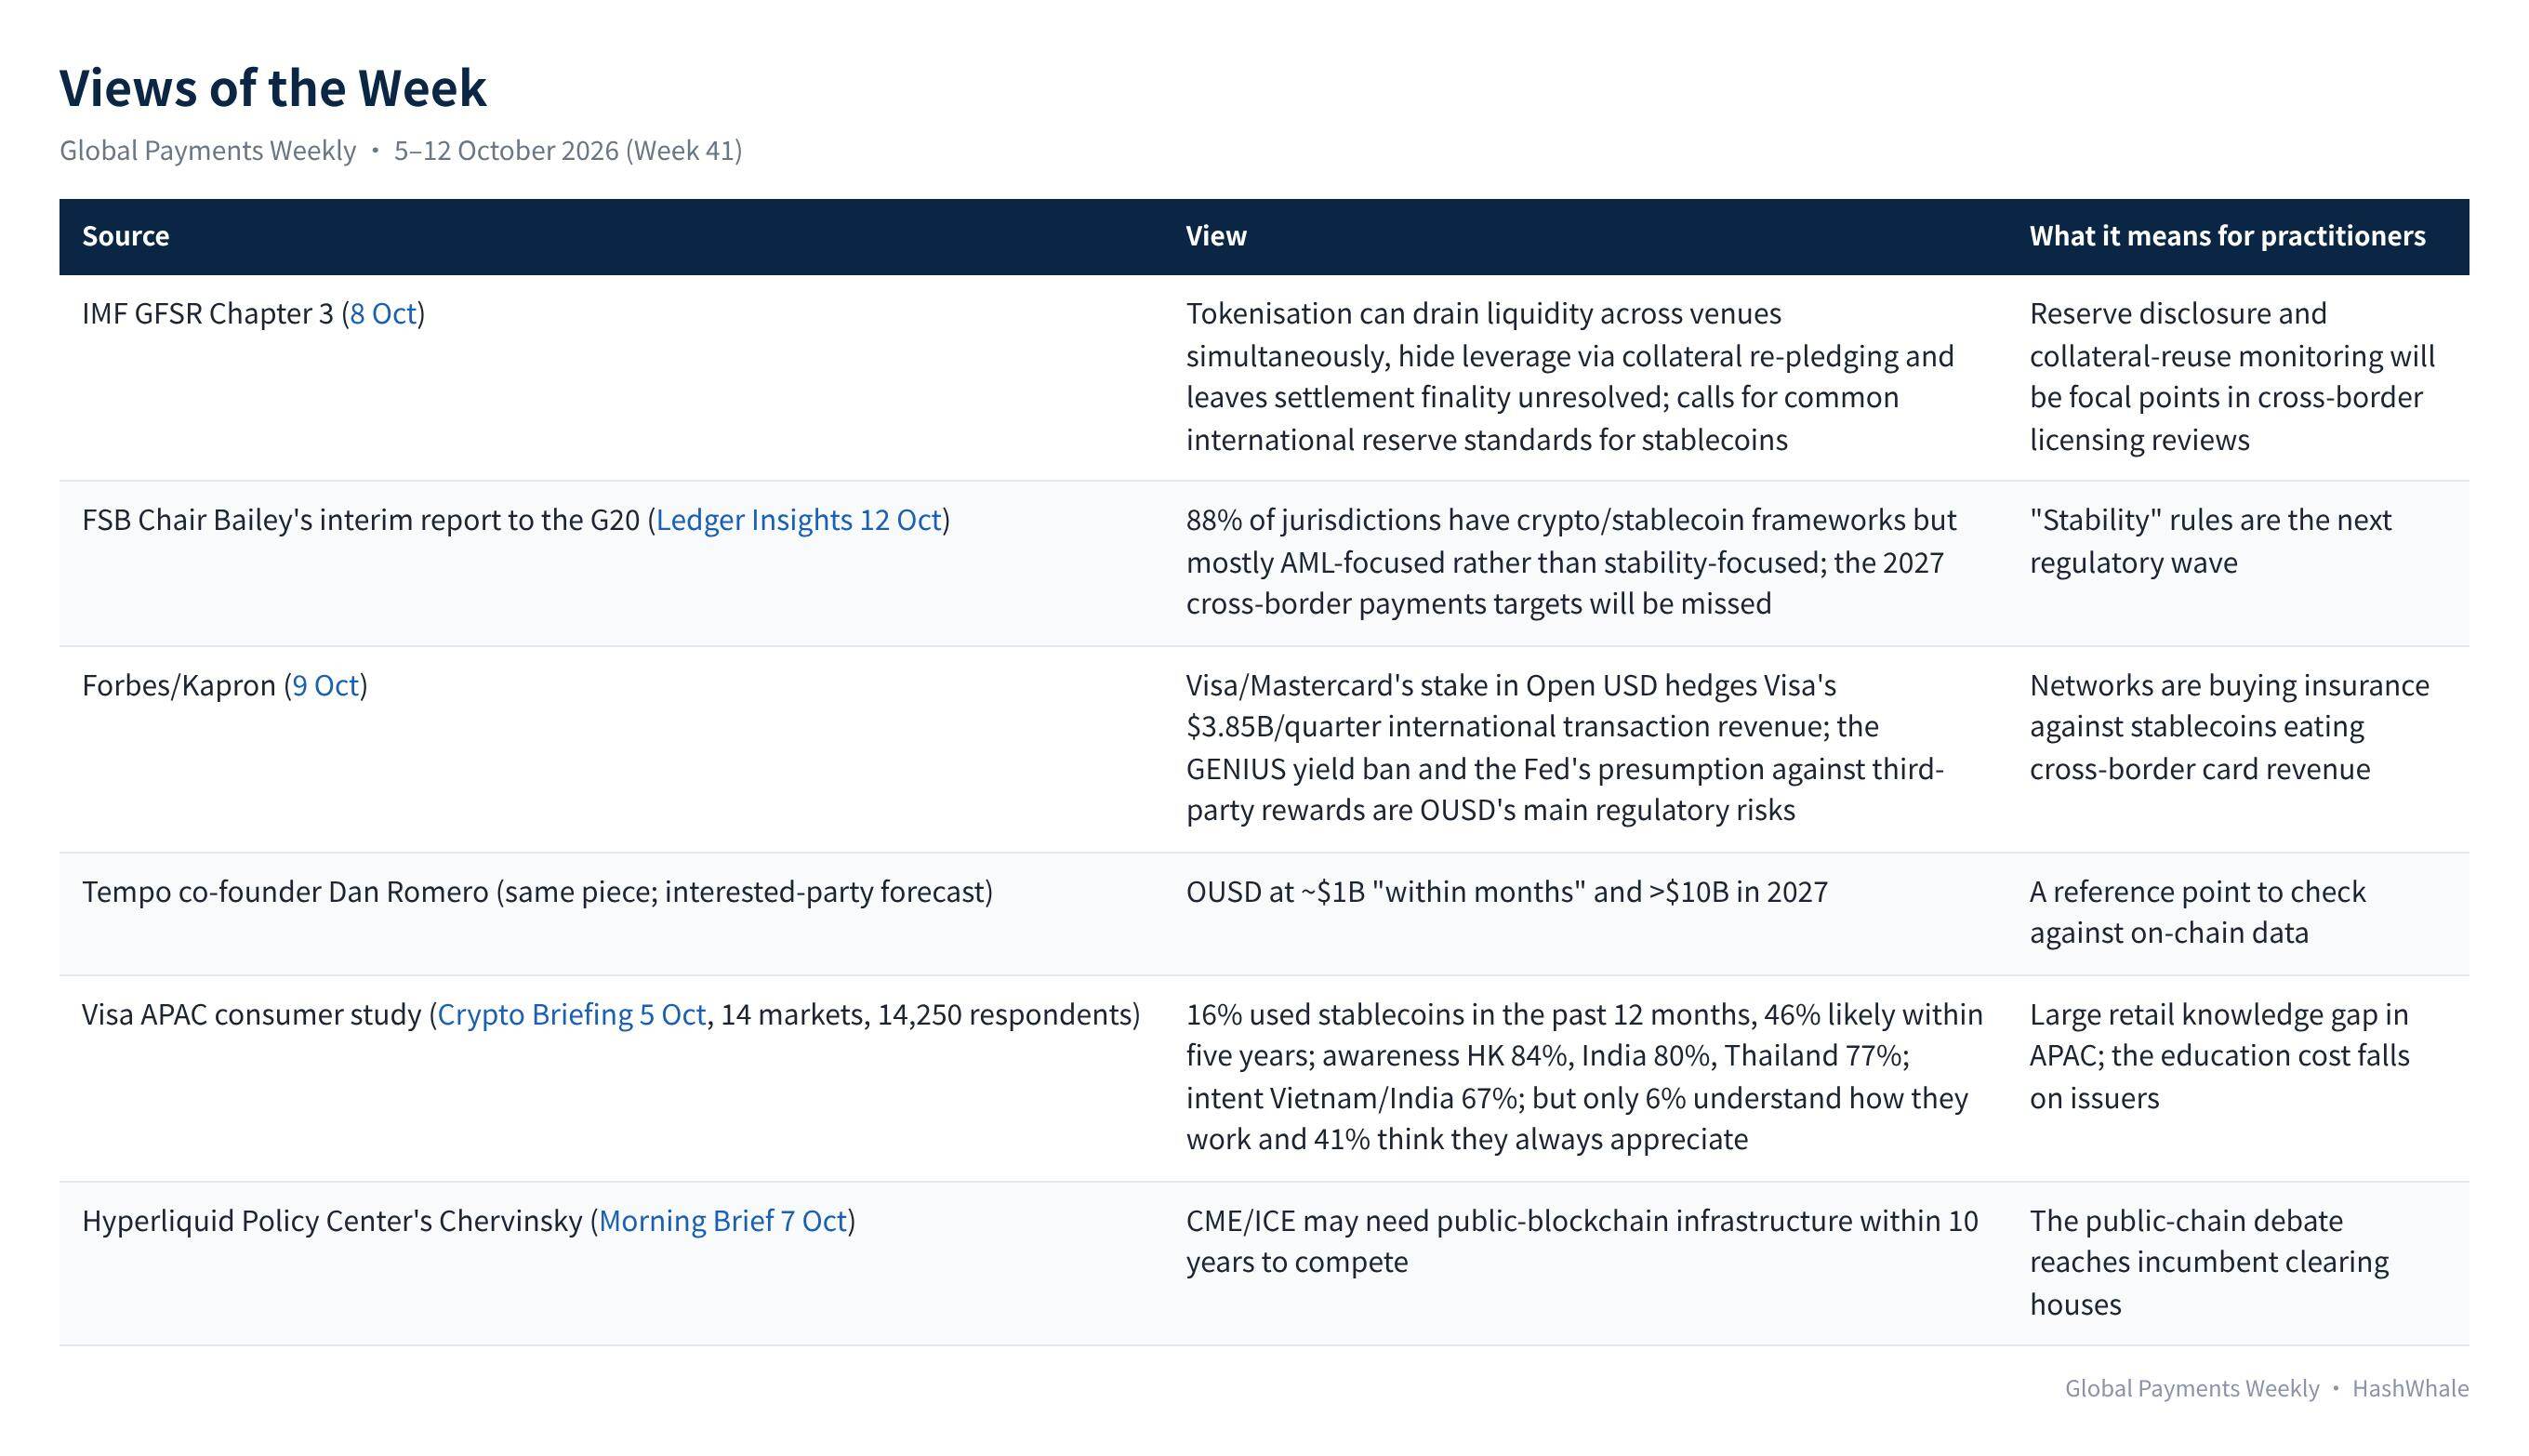
4.2 Views of the Week (institutional/personal opinions or forecasts, not facts)
4.3 Other Crypto Payments Items (one line each)
- Standard Chartered: institutional custody for Ripple's RLUSD via its DIFC branch, with an RLUSD-as-collateral plan with LMAX; separately, crypto/stablecoin/RWA custody to launch in Singapore by end-2026 (The Block 12 Oct, 8 Oct).
- Payward (Kraken) × Singapore Gulf Bank: 24/7 instant USD settlement for institutional clients in Asia and the Gulf via SGB Net (Cointelegraph 5 Oct); Payward also received VARA Full Market Approval in Dubai, with AED pairs going live within weeks (FXNG 12 Oct).
- Coinbase × Gennius: 1:1 USDC-backed ONED USD distributed through 85+ Latin American financial institutions, Argentina first, spendable via bank-issued Visa cards (Crypto Briefing 8 Oct).
- Mastercard × SoFi: BIN sponsorship, issuing and processing for Mexico's Orbi crypto-linked card, merchants settled in fiat; Bitso says stablecoins were 40% of LatAm crypto purchases in 2025 (PYMNTS 8 Oct).
- Securitize: 12 tokenised US stocks (Apple, Nvidia, Tesla, etc.) on Solana settling in USDC, Jump Trading market-making; SECZ +10% (Cointelegraph 8 Oct).
- Solana Foundation: open-source "Solana DvP" atomic delivery-versus-payment standard with JPMorgan input (Cointelegraph 6 Oct).
- Paxos USDG: live on Arbitrum; Arbitrum joins the Global Dollar Network with a DAO proposal for 100M ARB in incentives; USDG >$3B in circulation (CoinDesk 5 Oct).
- Tether, three items: Conduit sued Tether in SDNY over $2.76M of USDT frozen for more than a year (The Block 6 Oct); Sen. Blumenthal demanded Tether custody and reserve records from Cantor Fitzgerald, response due 23 Oct (Cryptonomist 9 Oct); Tether froze USDT linked to Ledger-device supply-chain thefts, with some funds moved into USDD to avoid freezes (Crypto Briefing 12 Oct).
- Block: 5% discount for Cash App bitcoin spent at Square sellers; Q2 bitcoin gross profit −31% y/y to $72M (Payments Dive 9 Oct).
- Funding: Noah (stablecoin cross-border infrastructure) closed a $38M seed (GlobeNewswire 7 Oct); Spiko (tokenised cash funds) raised a $90M Series B led by NEA (FinTech Global 6 Oct); IMMIX (non-USD stablecoin FX pricing) raised $3.5M (GlobeNewswire 8 Oct).
5. Traditional vs. Crypto Payments

6. Regional Pulse
7. Action Items for Practitioners
Traditional payments
- Put "offline-capable" on the 2027 product roadmap. European issuers and acquirers should complete chip offline-limit parameter and terminal firmware assessments in Q4 to avoid crowded, pricier procurement at the February/May 2027 deadlines.
- Re-base fee assumptions for India and other emerging markets. The UPI deferral shows real-time payment pricing follows the political cycle; business plans should lean on value-added services (credit, SaaS, cross-border) rather than MDR.
- Benchmark card-product AML coverage against the Amex case. Transaction-monitoring thresholds and trade-background checks for cross-border B2B and commercial card flows need parity with deposit products; regulators now see card flows as a TBML channel.
Crypto payments
- Start the EU USDT migration countdown. Licensed firms serving EEA clients should finish client notifications before 30 Oct (the Coinbase marker) and move USDT exposure to USDC/EURC or bank EMTs before 8 Jan 2027, updating AML and settlement counterparties in parallel.
- Prioritise corporate treasury and AP use cases. SAP Pay, PYUSD intercompany transfers and the Routable deal show the interest ban does not touch B2B settlement demand; pitch embedded stablecoin settlement to ERP and AP-automation platforms.
- File GENIUS comments and re-assess issuance structure. Treasury's rule closes 19 Oct; weigh the Fed's 2% capital add-on, two-business-day redemption and parent deconsolidation requirements against the "own/consortium coin vs. licensed issuer" choice.
8. Watchlist for Next Week
- US rules and policy dates: Treasury GENIUS stablecoin rule comments close 19 Oct; Money20/20 USA 18–21 Oct (Mastercard previews an agentic-commerce "trust layer" and stablecoin sessions with BVNK); Cantor Fitzgerald's response to Sen. Blumenthal due 23 Oct.
- Asian capital markets and China access: GCash (GCASH) debut on the PSE on 20 Oct; progress and ownership structure of Visa's China clearing entity; NPCI's new UPI MDR date.
- European wind-down and tax: Coinbase EEA USDT withdrawal deadline 30 Oct; French National Assembly vote on the crypto-to-stablecoin tax amendment on 20 Oct; Wise Q2 trading update on 15 Oct.
Editor's note: all figures are as reported by the original sources; stablecoin supply differs by 1–3% across data providers; the Visa China approval, NPCI's formal deferral and Korea's exchange blocks occurred on 13 October, immediately after the period, and are dated accordingly.





