






SignalPlus Macro Analysis (20240318): Economic data is weak and the crypto market starts to pull back


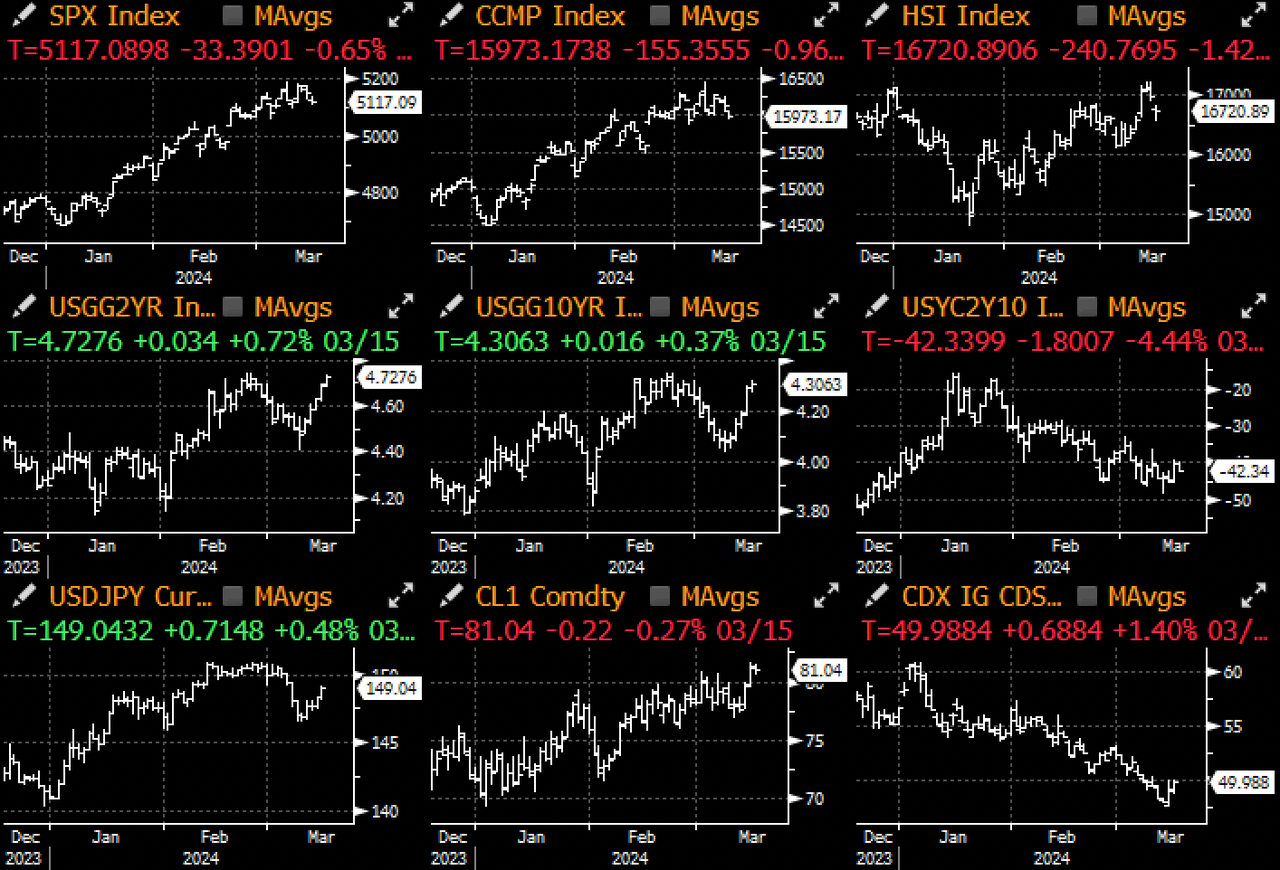
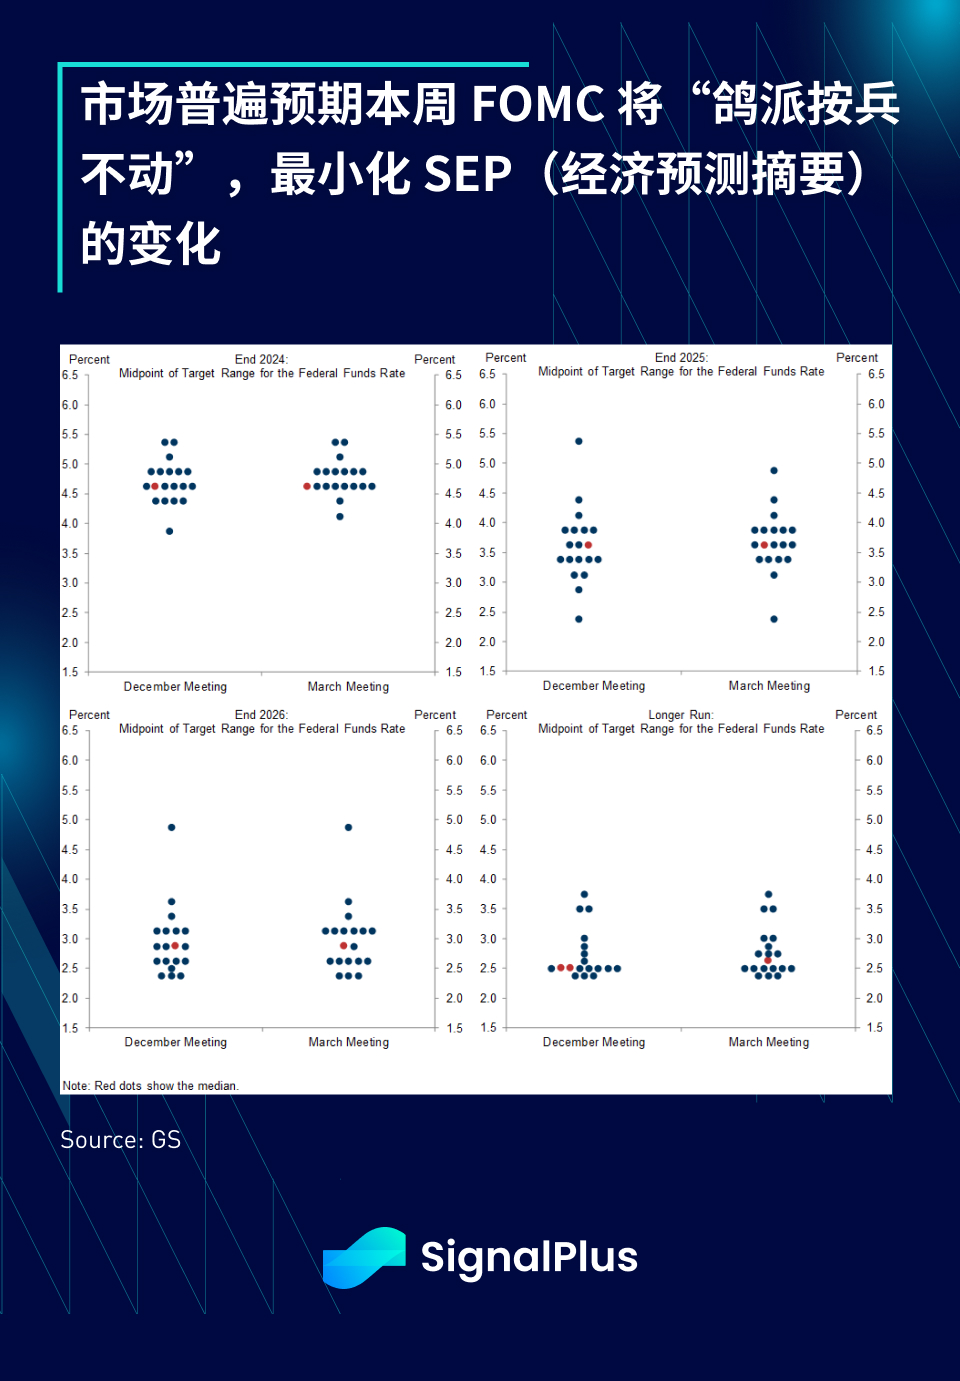
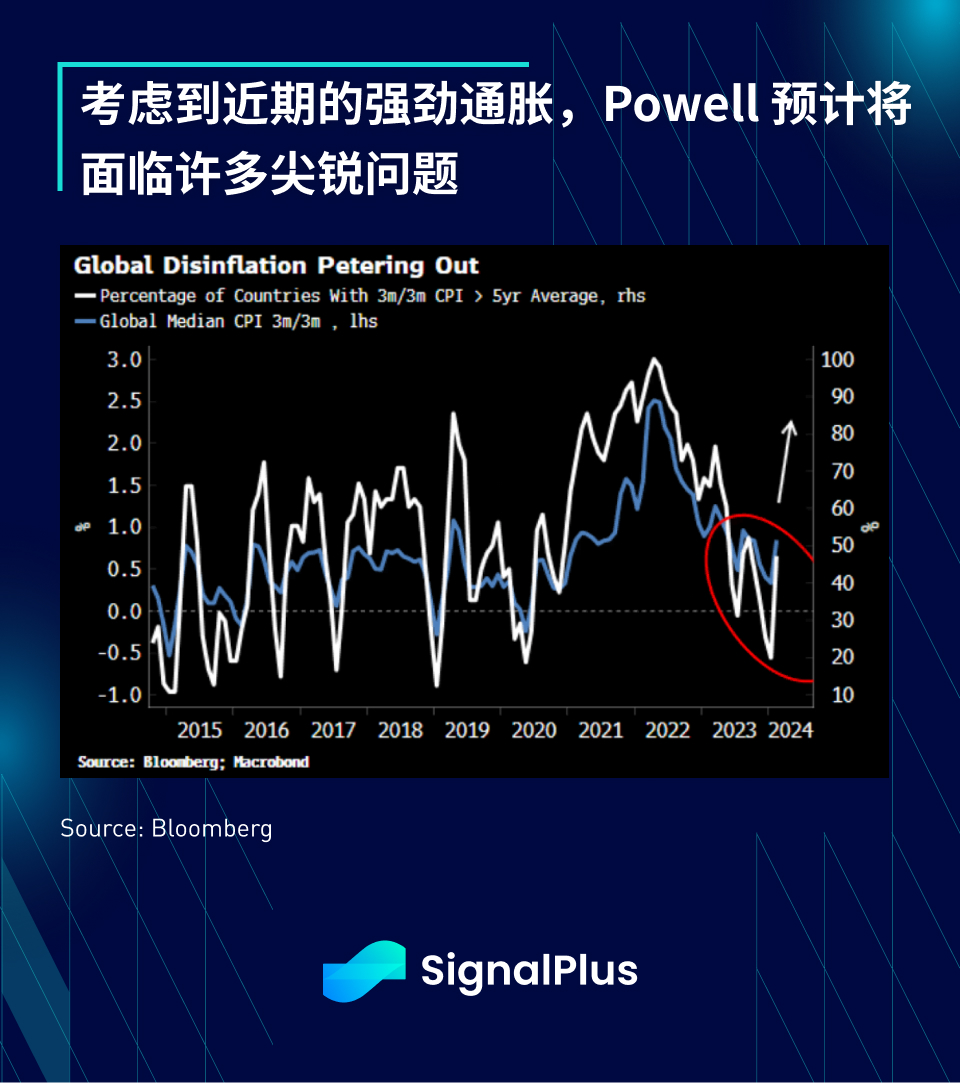
The market ended last week with the divergence between asset performance and inflationary pressures continuing to intensify. This week is about to usher in the FOMC meeting, although most Wall Street expects the Fed to be dovish and on hold even though there are still 3 interest rate cuts in the middle of the dot chart. ”, but the question-and-answer session is expected to be filled with questions about higher-than-expected inflation and loose financial conditions, putting some pressure on the chairman.
In addition to the FOMC, there will be many other central bank meetings this week, led by the Bank of Japan/Federal Reserve/Bank of England/Australia, and more than 10 central banks will make monetary policy decisions. The general consensus is that most central banks will remain dovish regardless of their actions, with the Bank of Japans decision likely to be the most differentiated given the possibility of exiting its long-term negative interest rate/yield curve control policy.
This week’s central bank meeting schedule is extremely busy (Credit: Citi)
Bank of Japan - Cancellation of negative interest rate policy is possible, but risks are tilted to the dovish side
FOMC - On hold, risk lies in dot plot forecasts
SNB - 25 basis points rate cut more likely than pricing reflects
Risks to Norges Bank-MPR forecast tilt slightly to the dovish side
BoE - Dovish risks in vote and guidance
Reserve Bank of Australia - Risks of dovish guidance
Brazils central bank - cuts interest rates by 50 basis points, forecasts and forward guidance shift to hawkish
Czech Central Bank - Cut interest rates by 50 basis points vs. 75 basis points, we prefer the former
Mexico’s central bank cuts interest rates by 25 basis points, starting an easing cycle
Colombia’s central bank – rate cut accelerates to 50 basis points
Turkish Central Bank - There is a risk of interest rate hike, but we think it is unlikely
Bank of Canada - Risk of slight hawkishness in central bank comments
Peoples Bank of China - 1-year/5-year LPR interest rates unchanged
Source: Citi
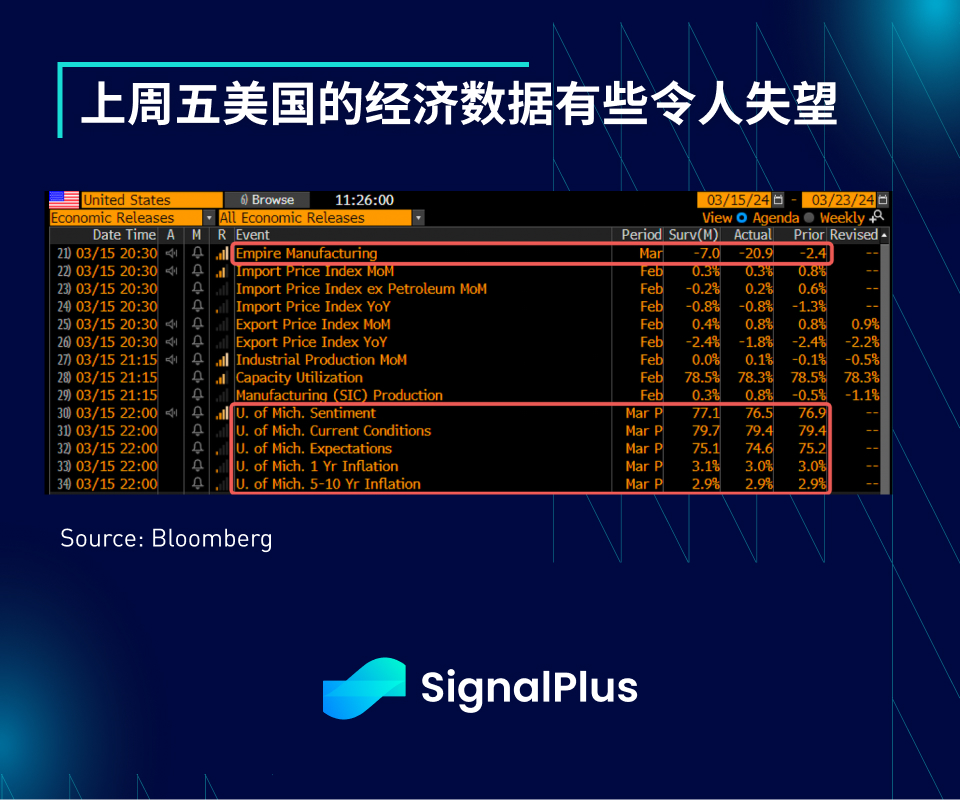
Last Friday, U.S. economic data was weak. The New York Fed manufacturing index was significantly lower than expected (-20.9 vs. the previous value of -2.4). Both employment and prices paid were significantly weaker than expected. The University of Michigans consumer confidence index has also declined slightly from previous months, and inflation expectations have remained stable at around 3%, which is still well above the Feds long-term goal.
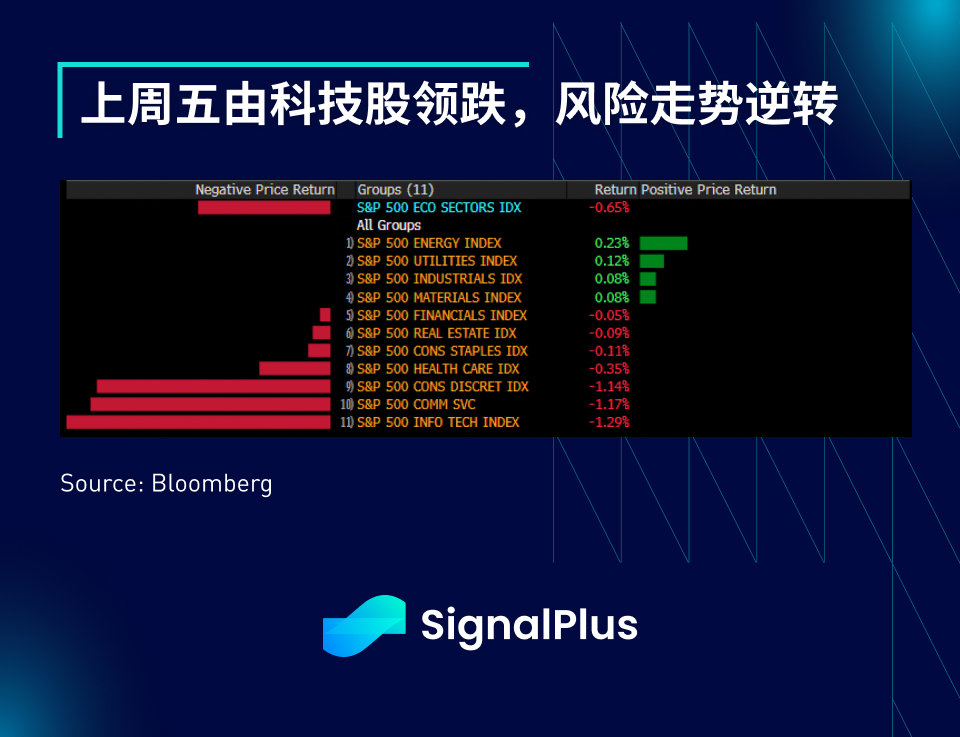
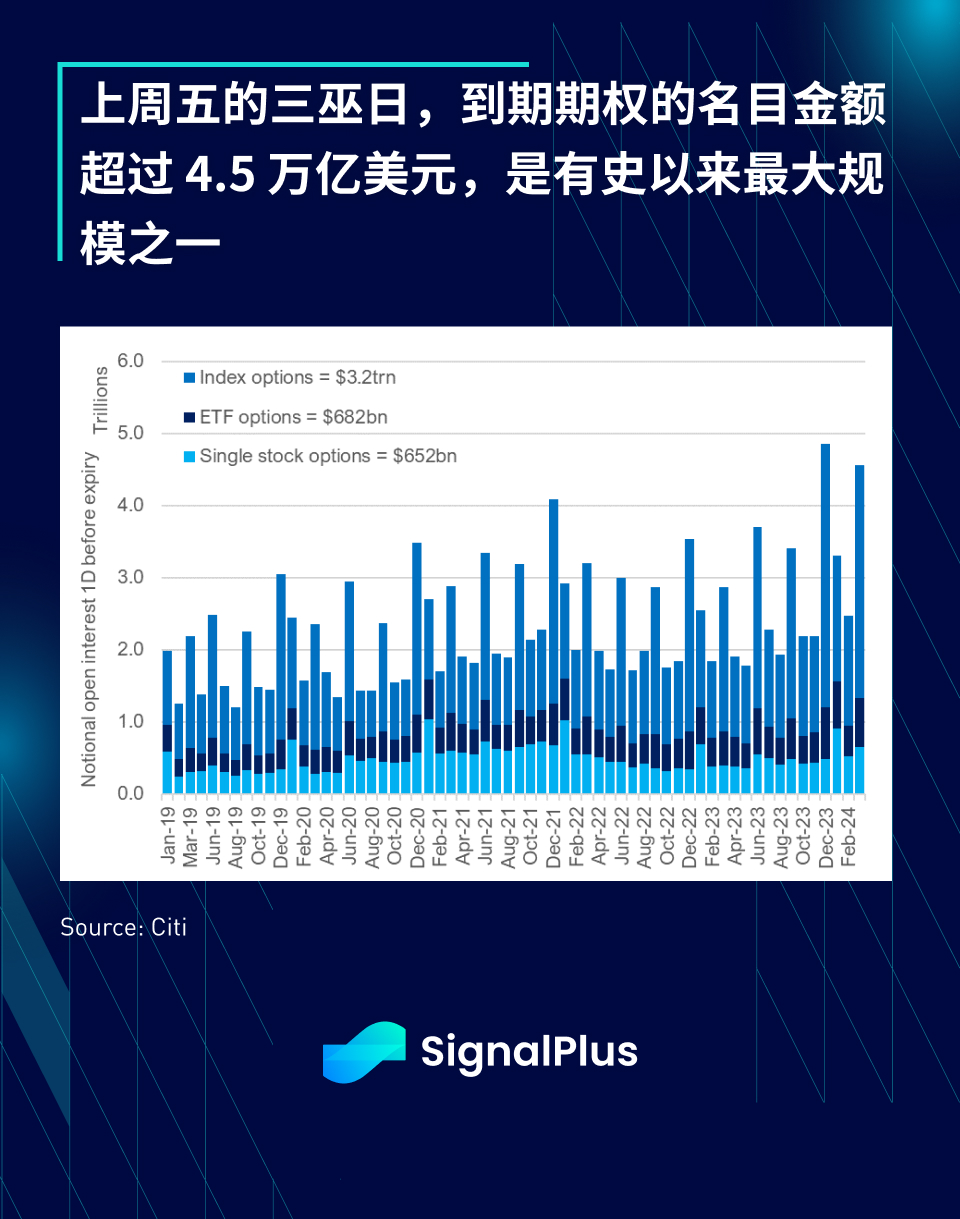
Stocks ended lower on Friday, led by technology stocks, as traders took some profits after a wild year-to-date rally. In addition, there was also a large-scale option expiration last Friday, with more than 4.5 trillion in stock index, ETF and single stock options rolling positions. Before the end of the Three Witching Days, the market was basically dominated by risk reallocation and delta hedging.
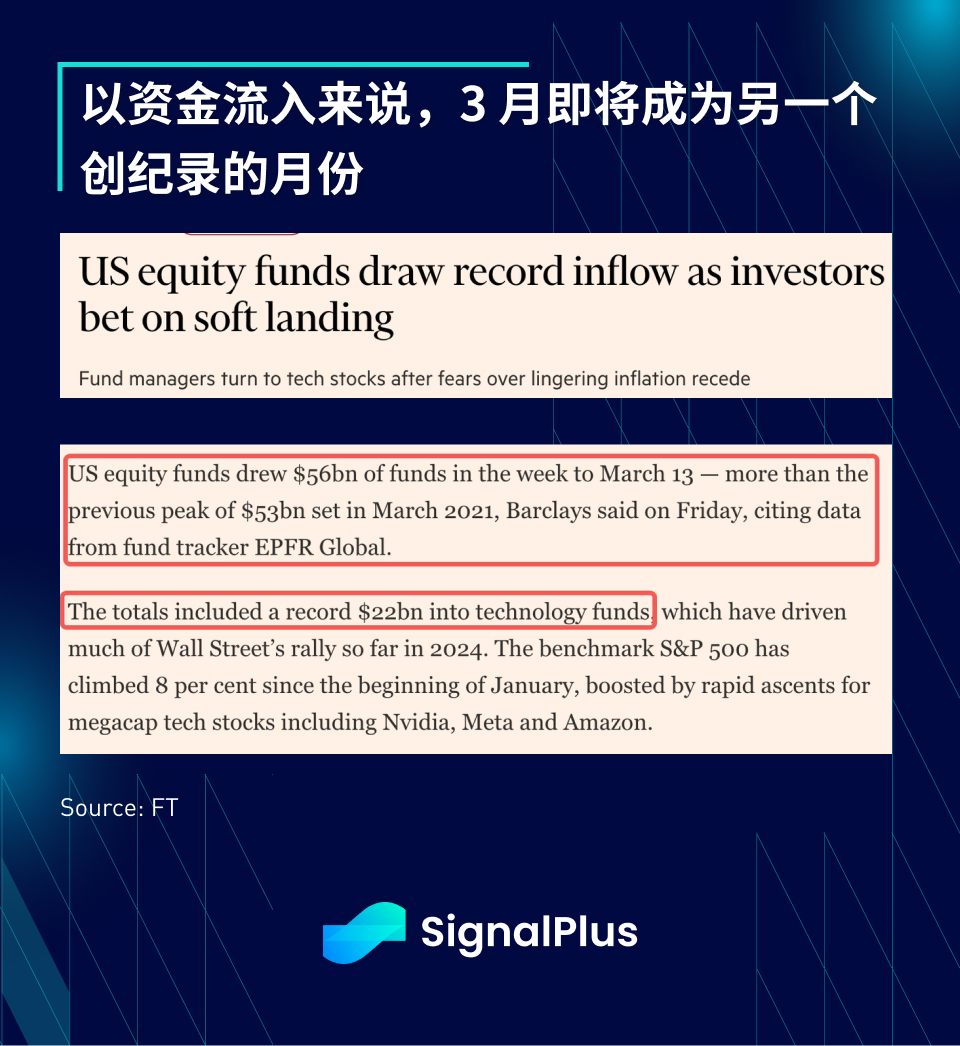
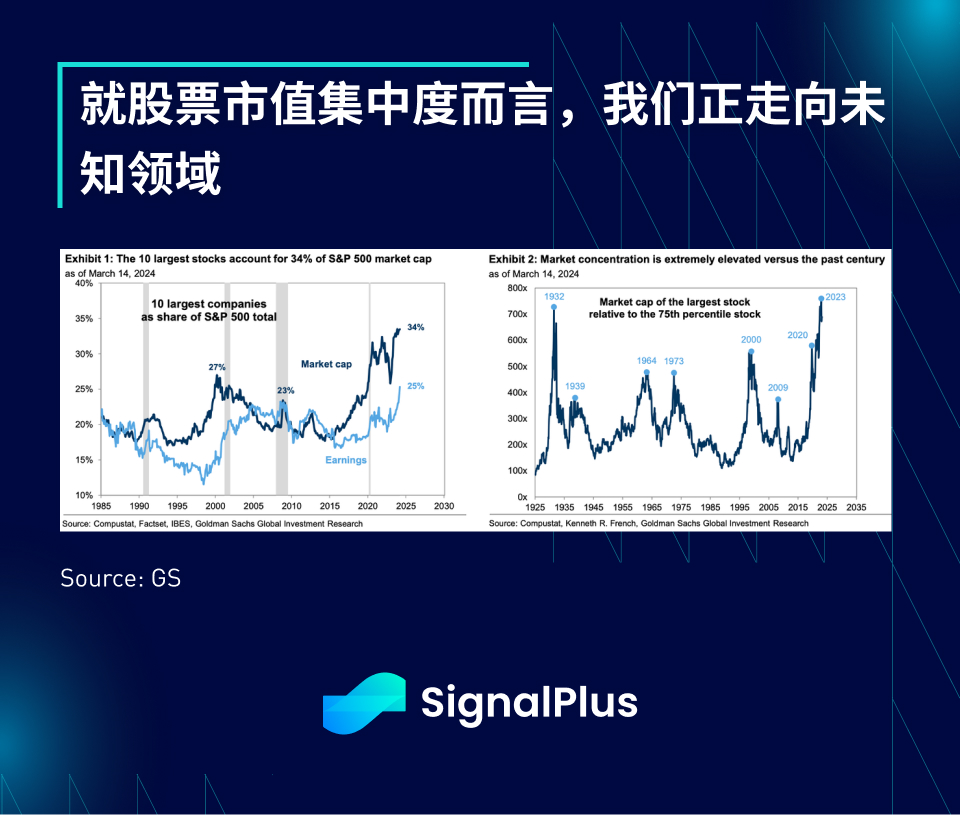
However, despite the slight pullback, March is still shaping up to be a record month, with investors pouring a record $56 billion into stocks in the first two weeks of March (including $22 billion in technology stocks), and market concentration (with market capitalization) are heading toward extreme levels not seen since 1932.
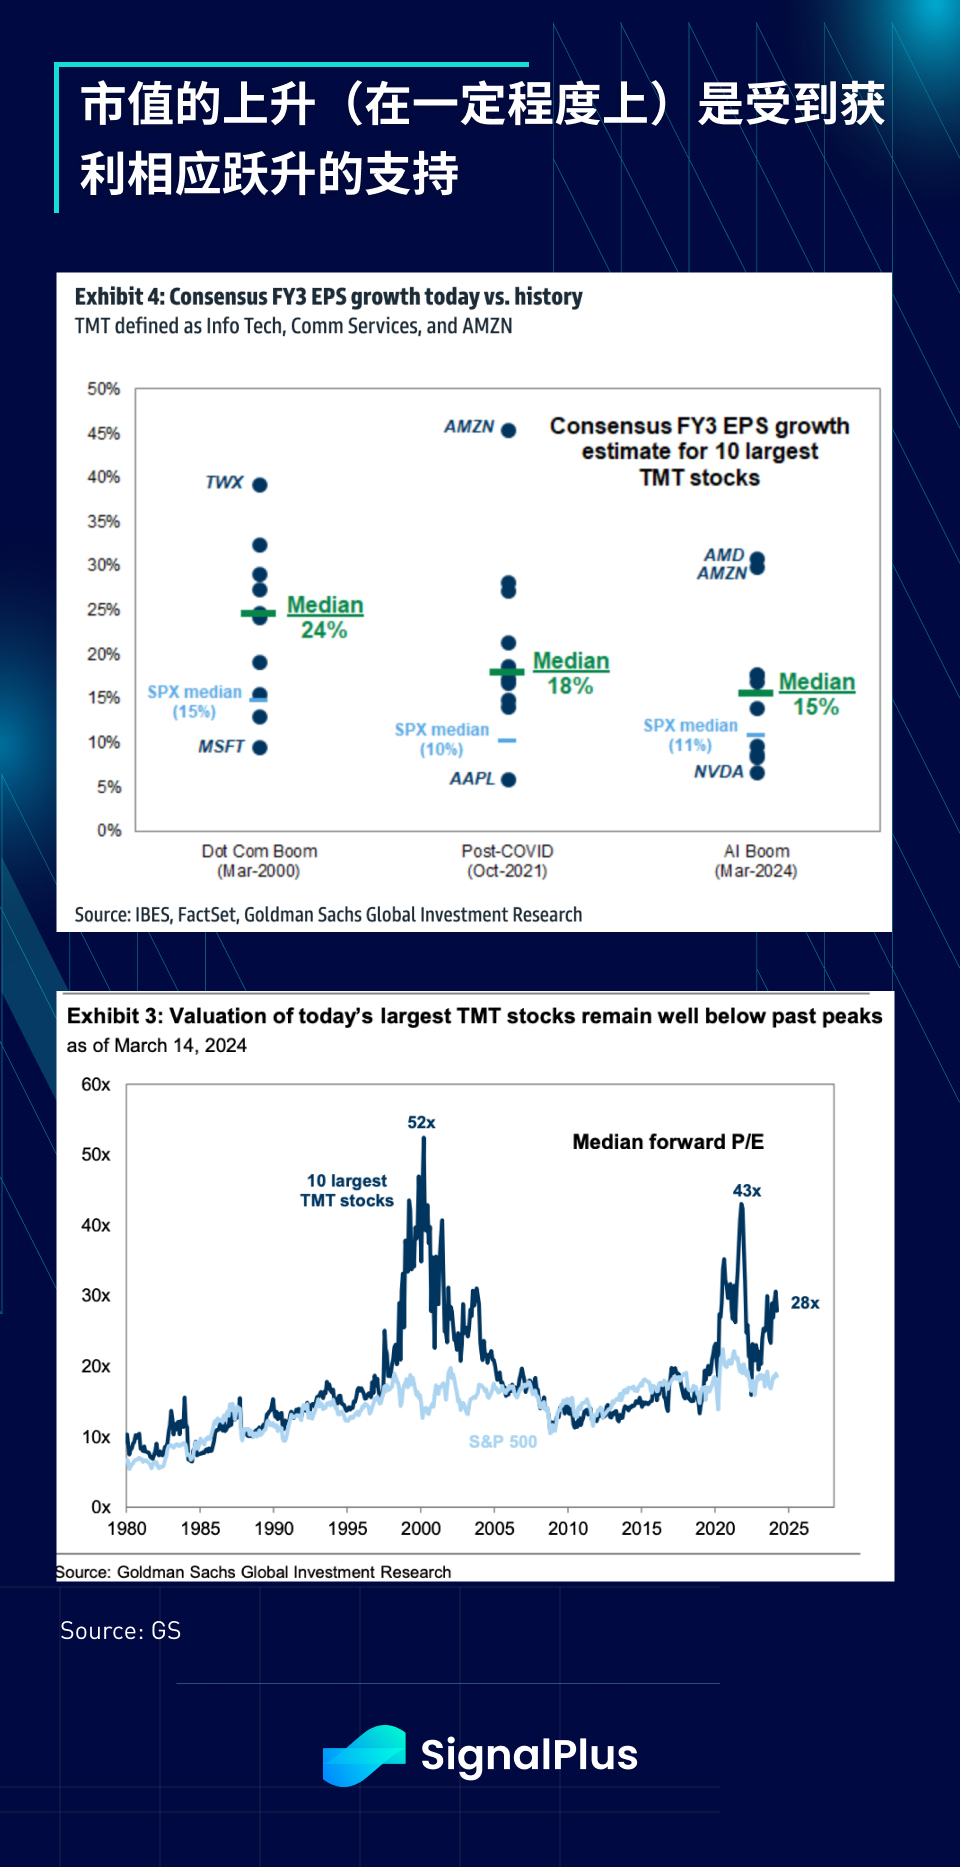
However, investors (and strategists) remain fairly calm about concentration risk, as rising concentrations are accompanied by large jumps in profits relative to the average stock. With technology stocks accounting for the lions share of SPX EPS, the rise in share prices only lifted the forward P/E ratio to 28x, which is still below the bubble highs of 52x and 43x in 1999 and 2021, respectively. While undoubtedly expensive in absolute terms, given the sheer ubiquitous impact of AI, investors feel they have no choice but to pay a premium to gain exposure to AI large-cap stocks.
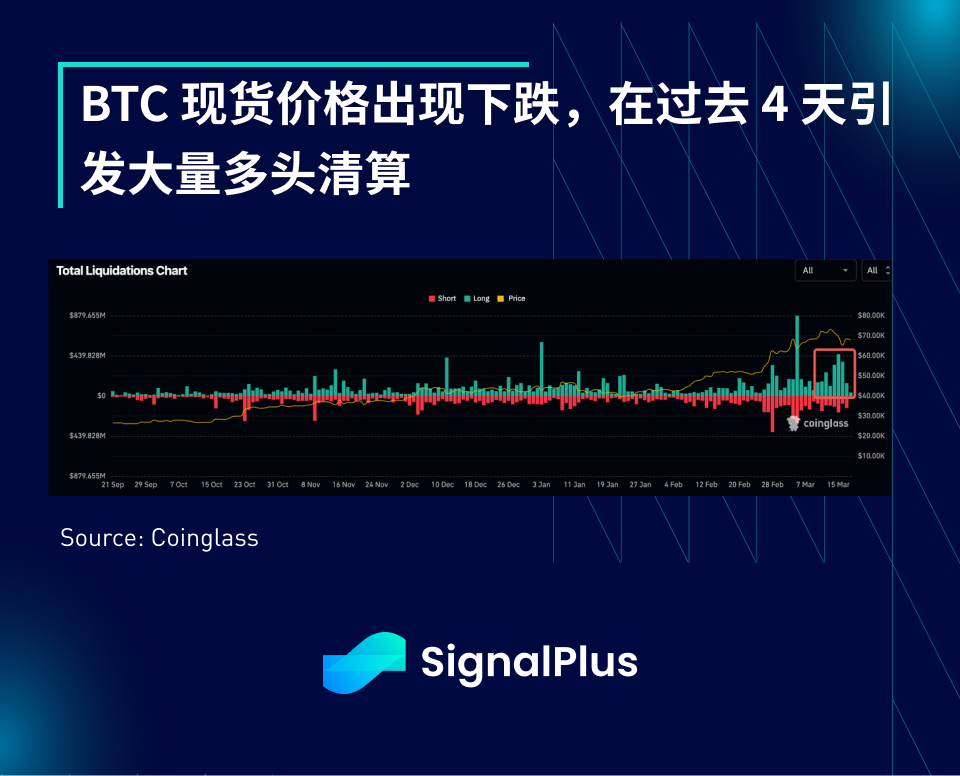
On the cryptocurrency side, prices have undergone a painful correction over the past 72 hours, with BTC spot falling from approximately $73,000 to approximately $65,000 over the weekend, forcing a significant number of bulls and bargain hunters out of the market. As we mentioned before, the recent craze seems to have been excessive, and altcoin/memecoin are showing signs of exceeding their limits.
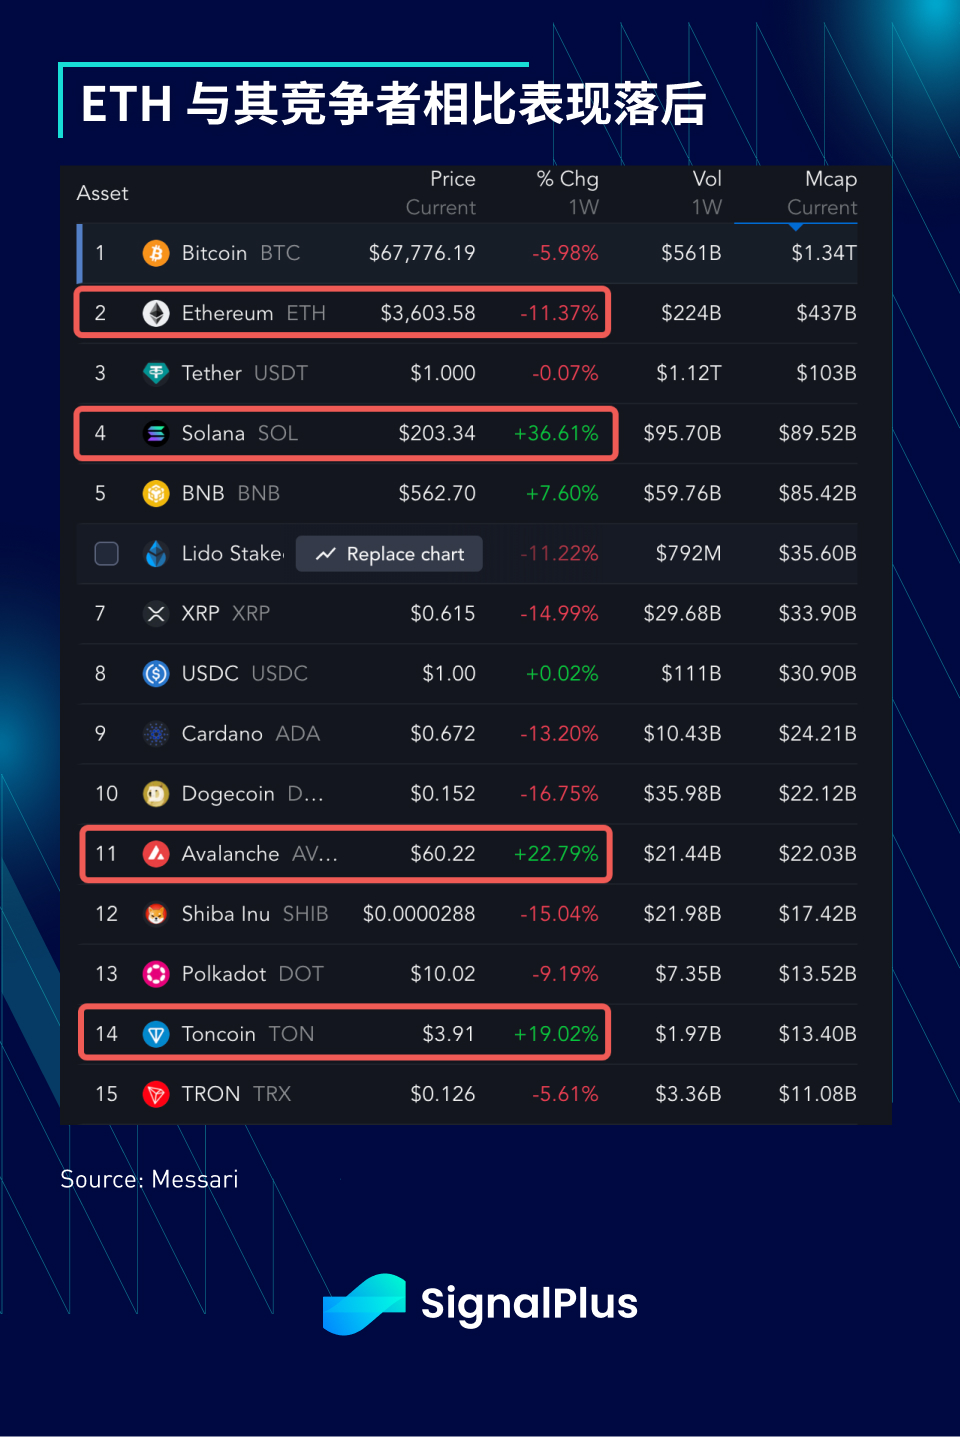
Outside of BTC, ETH still struggles in comparison to other major EVM and L1 chains, especially Solana/Avalanche/TON. As the ETH foundational narrative gets squeezed under various L2 spotlights, attention is also being diverted to the burgeoning network activity of EVM competitors (reflected in memecoins and non-ETH ETSs) and the upcoming Telegram stock IPO (supporting TON Token). The US SECs disapproval of ETH ETF is another risk that cannot be ignored. For this former darling of TradFi, we still recommend remaining cautious in the short term.
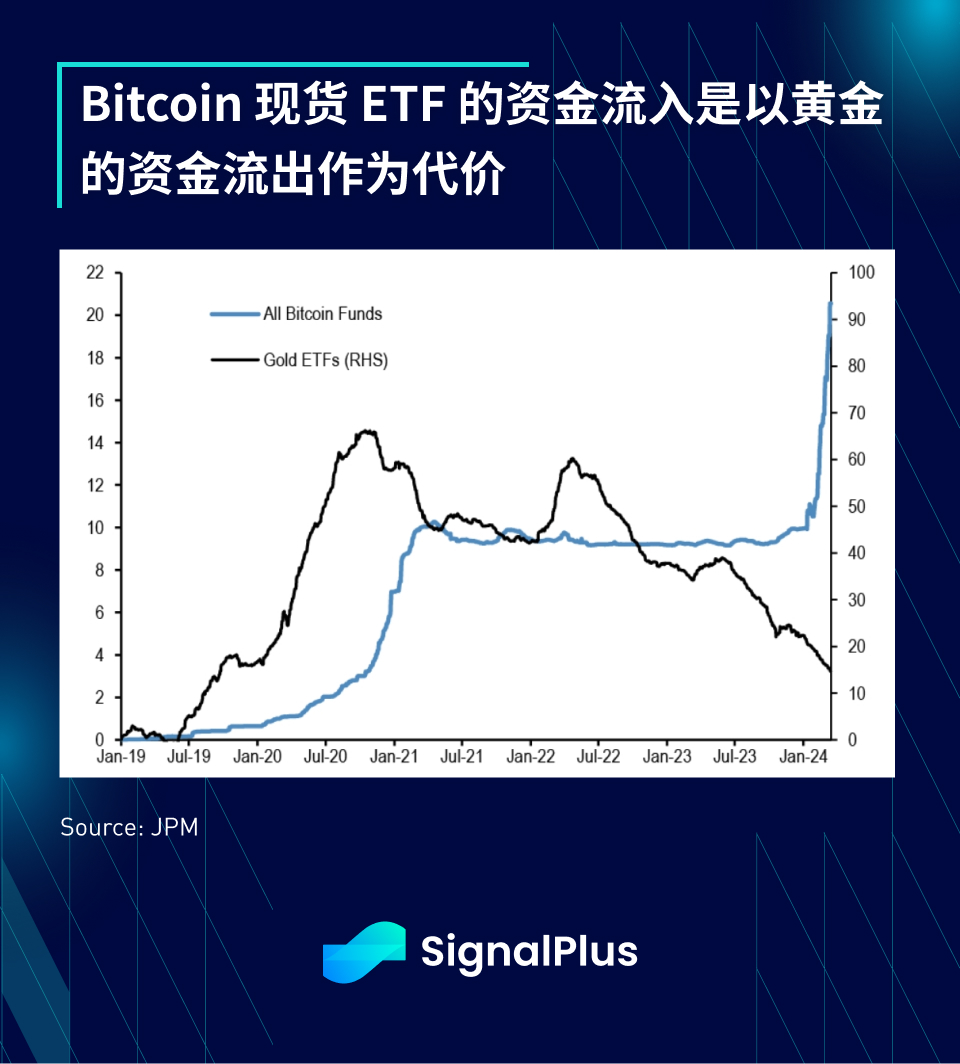
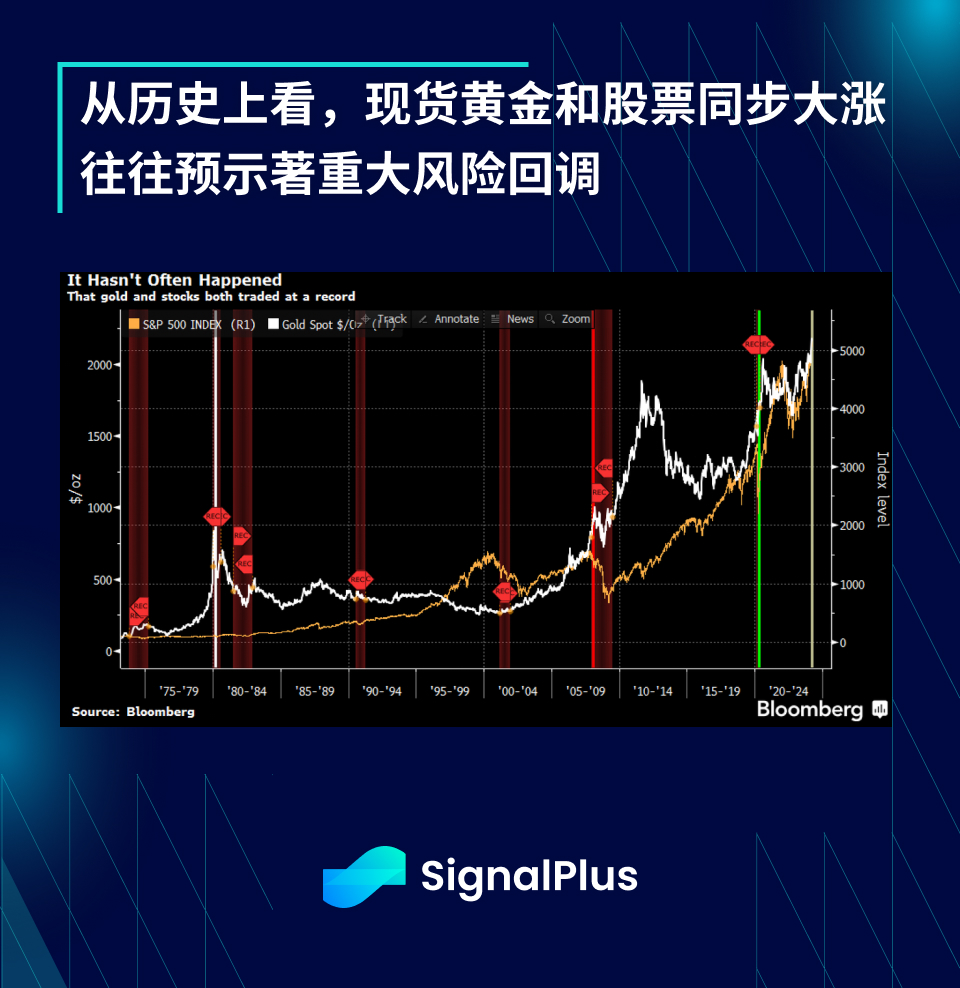
Finally, JPM made the interesting observation that inflows into BTC ETFs have come at the expense of outflows into gold ETFs, consistent with Bitcoin’s long-standing reputation as “digital gold.” Despite this, gold spot prices remain consistent with cryptocurrencies and stocks. They hit new highs together, although the returns are not that amazing. If stocks and cryptocurrencies risk a correction over the remainder of the year, will spot gold prove to be a safe haven? In addition, as early as the early 1980s, 2007 and 2020, gold and the stock market hit cycle highs at the same time, and then the markets faced major risk correction events. Will history repeat itself again? Definitely worth our continued attention...
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption information. If you want to receive our updates immediately, please follow our Twitter account @SignalPlus_Web3, or join our WeChat group (add assistant WeChat: xdengalin), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website:https://www.signalplus.com





