


Global Payments Weekly 2026W35


- 핵심 요점: 이번 주 전통 결제 및 암호화폐 결제 업계의 주요 동향은 대형 결제 기업의 자산 가격 결정 규율, 소매 대기업의 NFC 결제 개방에 따른 시장 구도 재평가, 그리고 규제와 상업 은행의 추진 속에서 스테이블코인이 규제 적합성과 토큰화된 달러의 다중 경로 경쟁 단계로 가속화되고 있는 점에 집중되었습니다.
- 핵심 요소:
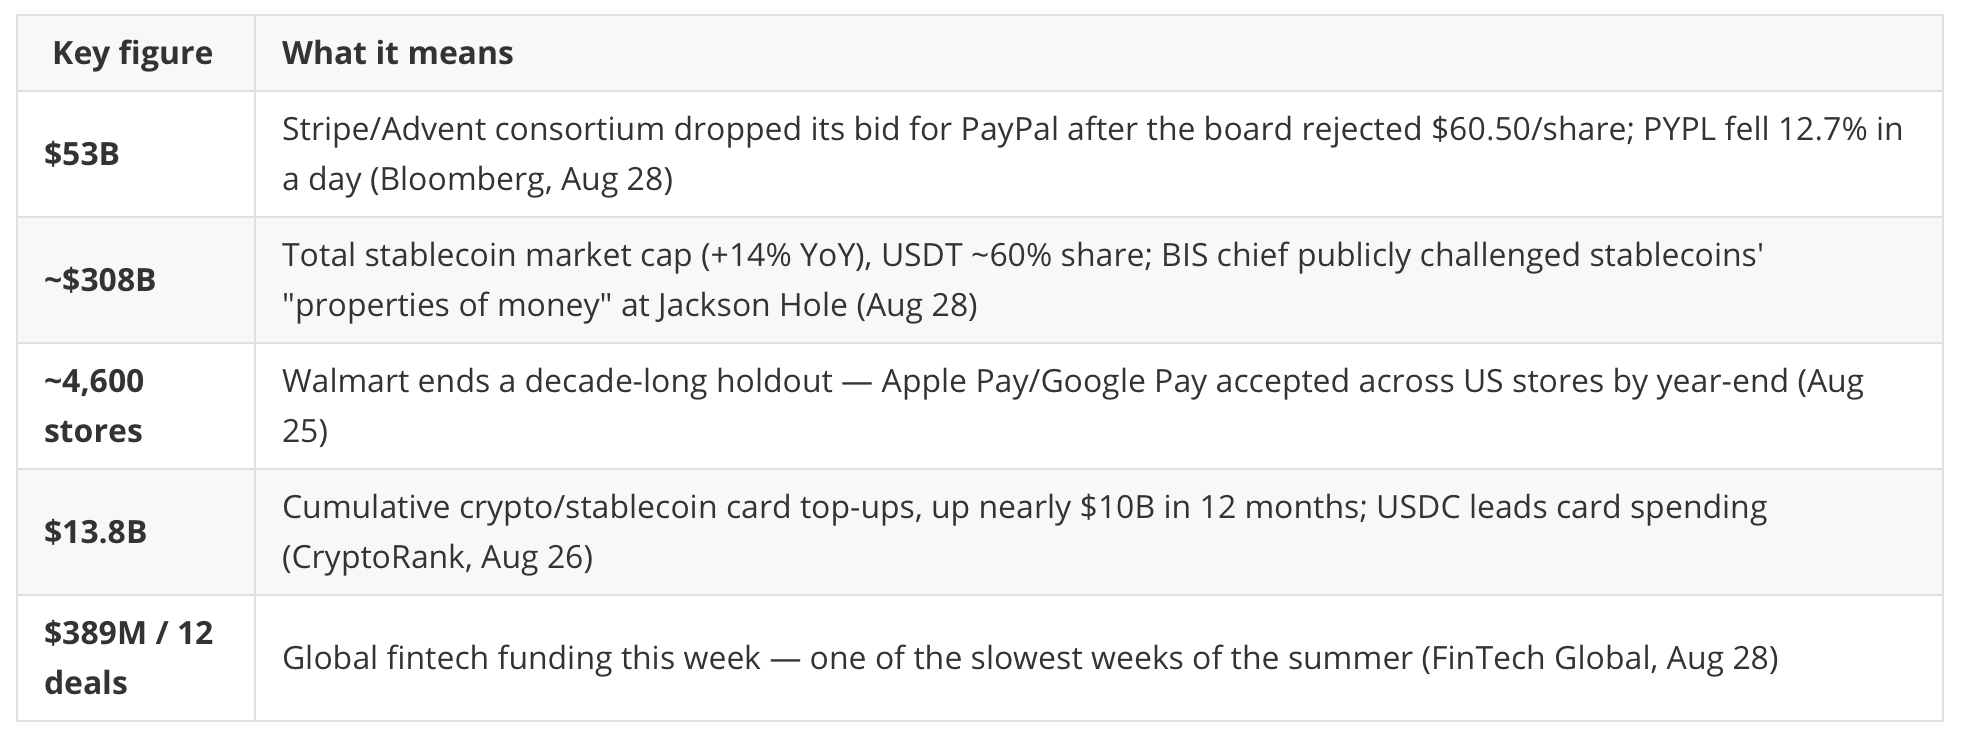
- PayPal 인수 건은 주당 60.50달러가 거절되면서 무산되었고, 컨소시엄은 가격 인상 대신 포기하기로 결정했습니다. 이는 매수 측이 결제 자산에 대해 예상보다 강한 가격 결정 규율을 보였음을 의미하며, PYPL 주가는 약 30%의 상승분을 반납했습니다. 대형 M&A 서사는 당분간 주춤할 수 있습니다.
- Walmart가 NFC 결제를 개방함과 동시에 자체 OnePay 및 BNPL 사업을 추진하면서, 발행사와 네트워크 입장에서는 실물 카드의 비접촉 결제 거래량에 구조적 호재가 될 전망입니다. 결제 단계에서의 경쟁 반응을 주목할 필요가 있습니다.
- Revolut은 MiCA 발효에 따라 USDT를 상장 폐지하고 규제를 준수하는 유로 스테이블코인 EURR을 발행했으며, 발행 주체는 Stripe의 Bridge입니다. 결제 대기업들이 스테이블코인의 '컨트랙트 제조사'가 되고 있으며, 이는 MiCA의 축출과 육성이라는 이중 효과를 부각시킵니다.
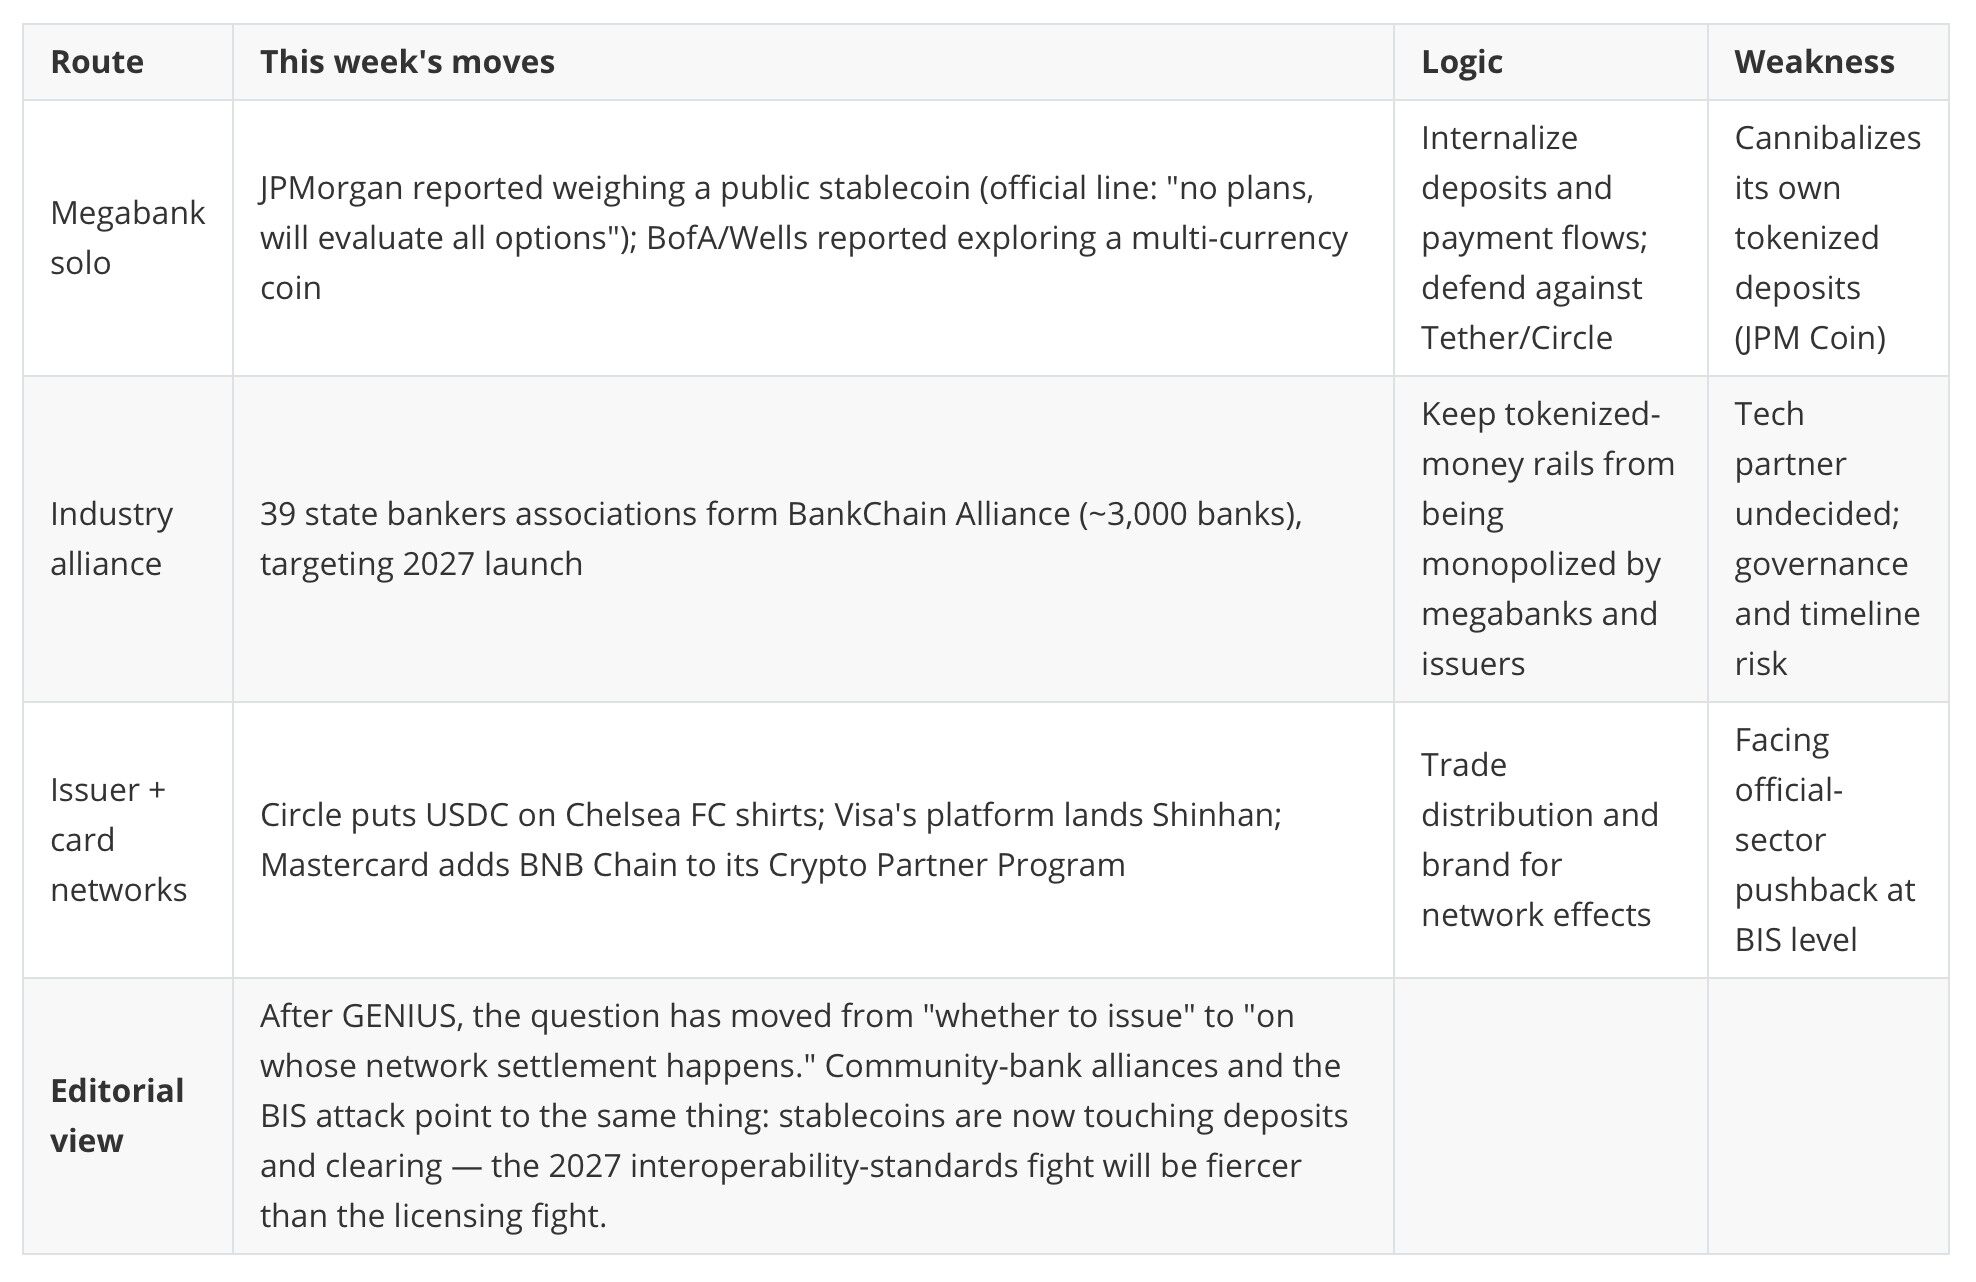
- JP모건(단독), 커뮤니티 은행 연합, 그리고 TCH(독자 노선)가 병행하여 토큰화된 달러를 추진하고 있습니다. 최소 세 가지 경로가 공존하며, 상호운용성이 아닌 발행이 인프라 제공업체의 다음 경쟁 초점이 되고 있습니다.
- Swift가 ISO 20022 마이그레이션을 연기한 반면, TCH RTP는 2027년 상반기跨境(국경 간) 파일럿을 발표했고 온체인 결제도 성숙해지고 있습니다. 전통적인 메시지 마이그레이션의 지연은 대체 솔루션의 시간적 여유를 넓혀주고 있습니다.
Author / Editor: WANG TAI
Coverage period: Aug 24 – Aug 30, 2026 (Week 35) · For traditional & crypto payments practitioners · ~4-min read
1. The Week at a Glance
2. Industry Thermometer
3. Key Events of the Week

Why these matter (editorial analysis)
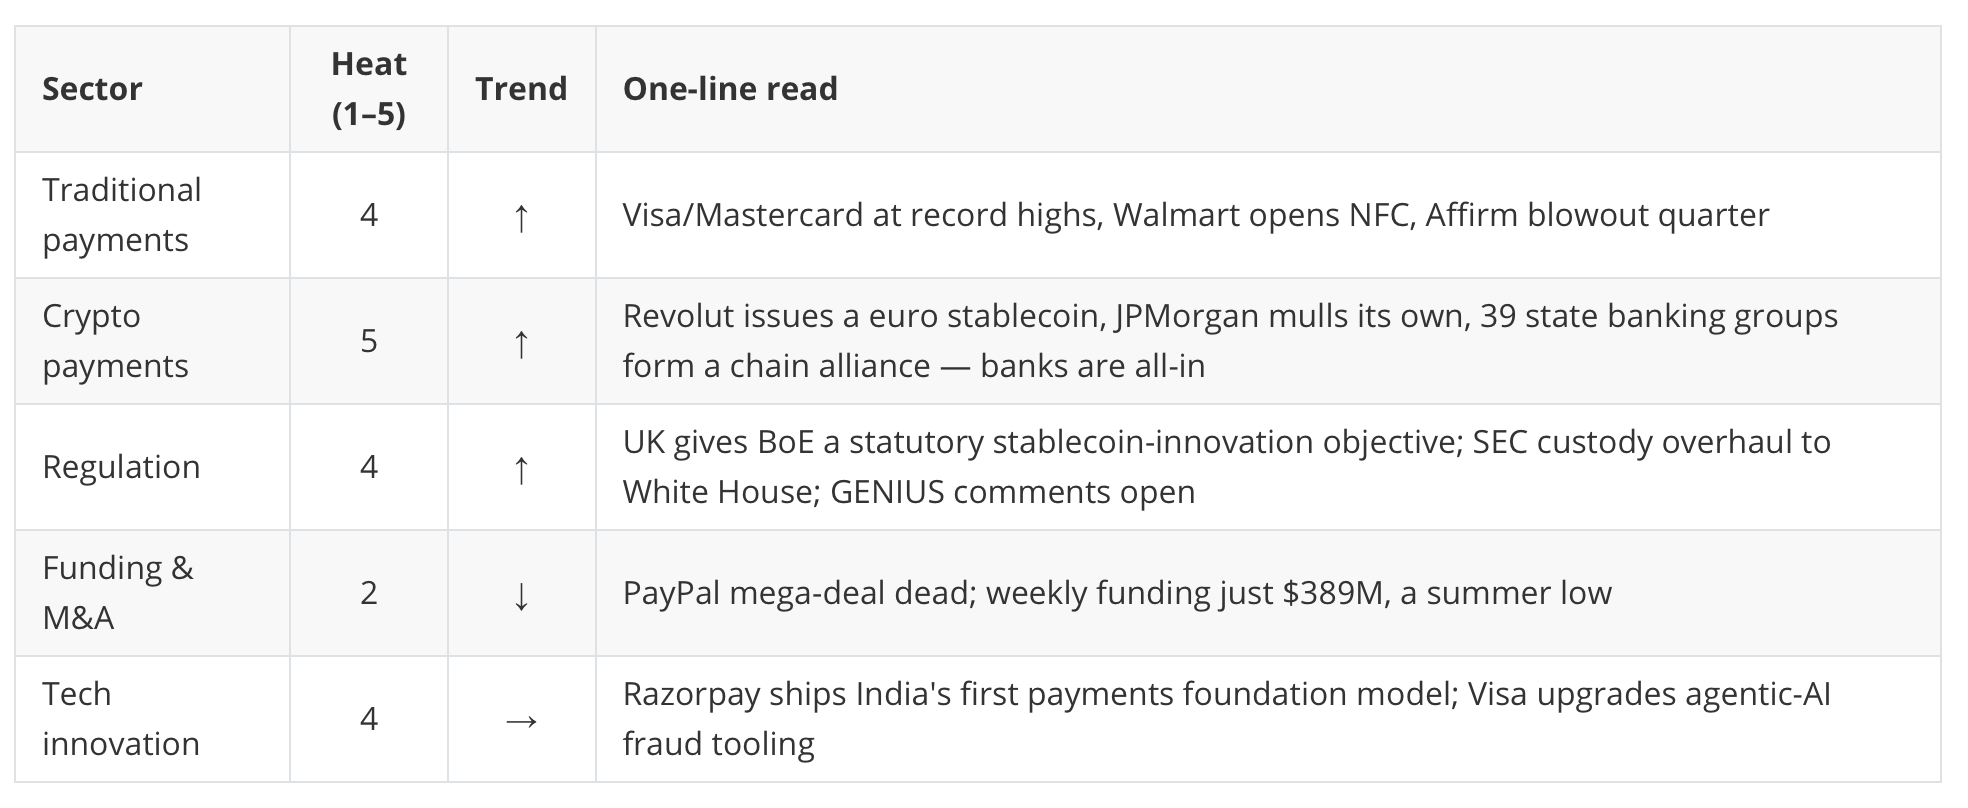
- PayPal deal collapse: the consortium walked rather than raised after a $60.50/share rejection — buy-side price discipline on payments assets is stronger than the market assumed. PYPL gave back the ~30% gained since talks surfaced; expect the large-cap consolidation narrative to cool near-term.
- Walmart opens NFC: this is repositioning, not surrender — Walmart is simultaneously pushing its own OnePay and BNPL. For issuers and networks it is a genuine card-present contactless volume windfall; watch how aggressively OnePay counters at checkout.
- Revolut EURR: MiCA's expulsion effect (USDT delisting) and incubation effect (a compliant euro stablecoin) landed at the same company in the same week — and the issuer is Stripe's Bridge. Payment giants are becoming the stablecoin "contract manufacturers."
- JPMorgan & BankChain: megabanks solo, community banks in alliance, TCH on its own track — at least three parallel routes to tokenized dollars. For infrastructure providers, interoperability, not issuance, becomes the next competitive interface.
- Swift's ISO 20022 delay: with TCH's RTP announcing a cross-border pilot for H1 2027 and on-chain settlement maturing, every slip in legacy messaging migration hands the alternatives a wider time window.
4. Crypto / Web3 Deep Dive
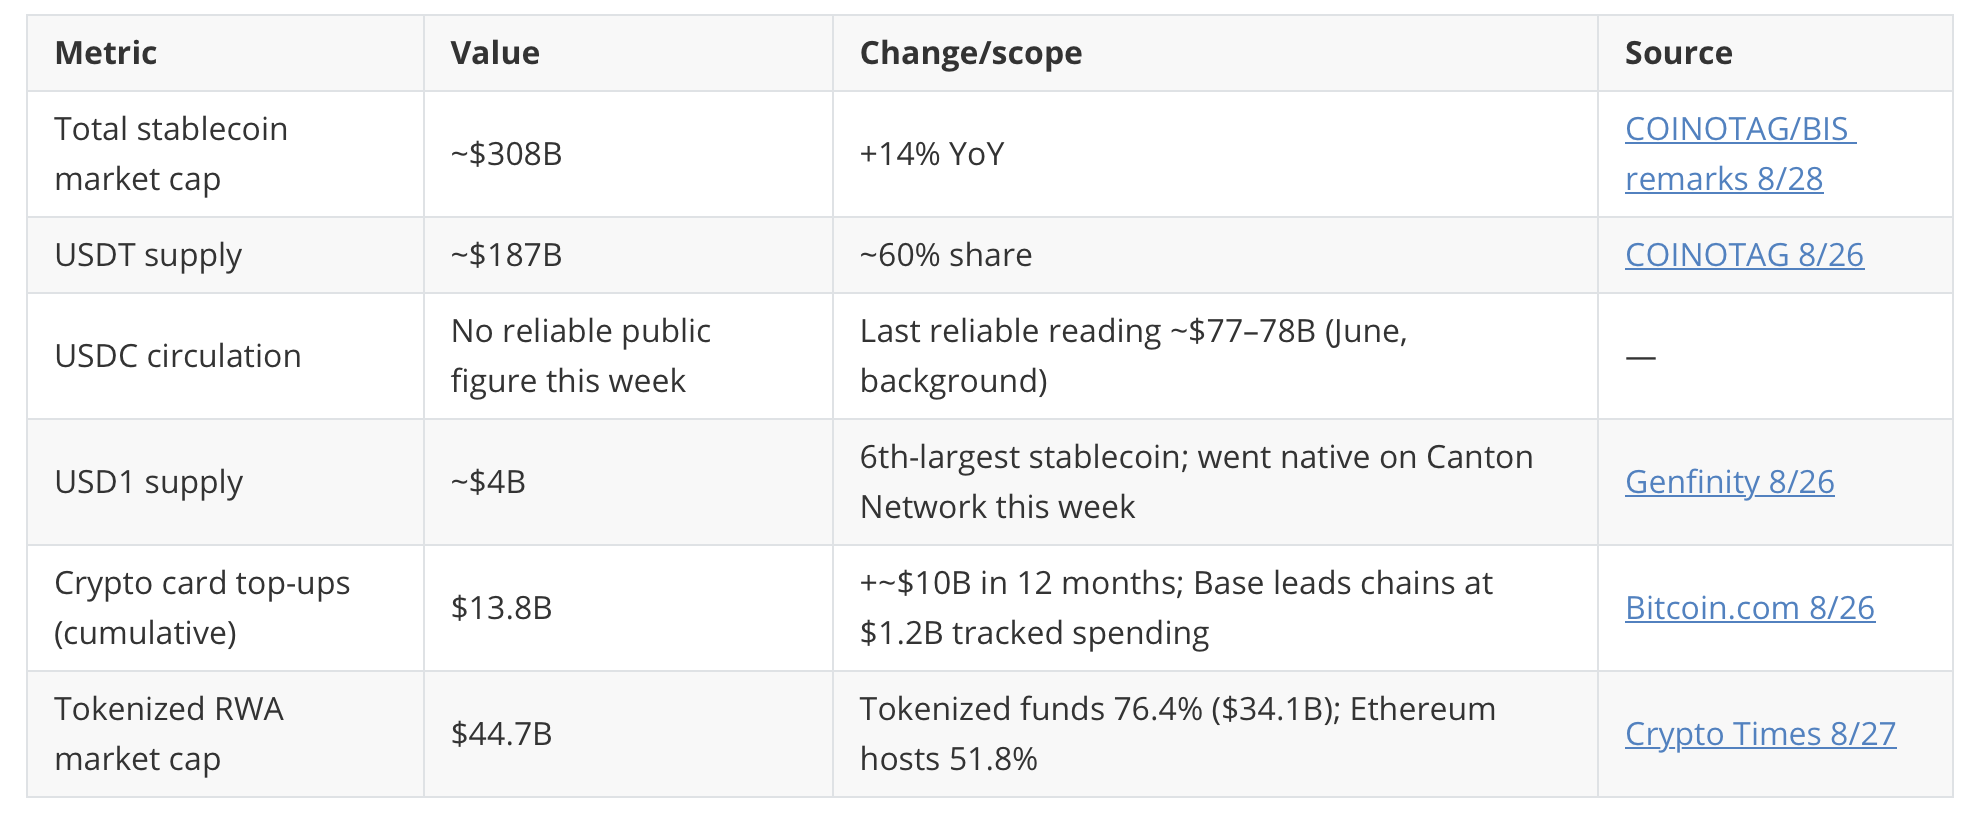
4.1 Stablecoin data dashboard
4.2 Theme of the week: banks pile in — three parallel routes to tokenized dollars
4.3 Voices of the week

4.4 Regulatory week in brief
US: SEC sent its crypto-custody rule overhaul for advisers/funds to the White House (OIRA) (The Block 8/26); the Blockchain Association backed Treasury's GENIUS Section 3 proposed rules — comments due Oct 19 (The Block 8/25). UK: BoE gets a statutory stablecoin-innovation objective (see Key Events). EU: MiCA enforcement effects turn visible — Revolut delists USDT and issues compliant EURR. No major new policy from Mainland China or Hong Kong this week (background: PBOC expanded e-CNY operators to 30 banks mid-August; Hong Kong's HKDAP advancing in institutional use).
5. Traditional vs. Crypto Payments

6. Regional Watch

7. Action Items for Practitioners
For traditional payments practitioners
- Re-price your wallet channel strategy: Walmart's NFC opening delivers structural card-present contactless volume in the US — issuers and acquirers should model the tap-to-pay share shift now, and watch OnePay's counter-moves at checkout.
- Don't slow ISO 20022: Swift's deferral is a buffer, not an exemption — keep structured-address work on schedule, and add TCH RTP's cross-border pilot (H1 2027) to your cross-border product roadmap review.
- Pick BNPL partners on credit quality: the Affirm/Klarna divergence shows underwriting, not GMV growth, determines partner durability — build performance triggers into co-brand and distribution deals.
For crypto payments practitioners
- Align EEA products with MiCA now: Revolut's USDT delisting is the signal — plan compliant-stablecoin substitution (EURC/EURR-class) and liquidity migration for European flows within the year.
- File GENIUS comments (due Oct 19): the foreign-issuer prohibition bites July 2028 — lock in your structural path (US entity, agency issuance, or exit) during the comment window.
- Position at the bank-interoperability layer: with megabanks, state-bank alliances and card networks building in parallel, the "connector" role (compliant settlement, cross-network clearing) is scarcer than issuance — the Shinhan × Visa template is replicable with regional banks.
8. Watchlist for Next Week
- Aug 31: Revolut's USDT delisting across the EEA — watch where European USDT liquidity migrates (EURC/EURR/USDC) and whether other platforms follow.
- Sept 1: Wero launches in Luxembourg; TCH RTP's new rules take effect in September — two bellwethers for legacy rails' self-renewal in Europe and the US.
- The announcement window ahead of Money20/20 Middle East (Sept 14–16, Riyadh) — expect concentrated Saudi/UAE licensing and product news; also track large banks' and issuers' position papers in the GENIUS comment docket (closes Oct 19).
All data and events are drawn from public reporting; links point to original sources. Editorial analysis reflects judgment based on public information and is not investment advice.





