


Anthropic's Q3 revenue grew nearly 50%—why did pre-IPO contracts decline?


- Key Takeaways: Anthropic's Q3 revenue grew 46.7% quarter-over-quarter to $16.956 billion, but compute costs grew faster and profit margins declined. Pre-IPO perpetual contract prices fell following the earnings disclosure, as market pricing focus shifted from growth rate to the cost of growth.
- Key Details:
- Q3 revenue reached $16.956 billion, up 46.7% quarter-over-quarter, but growth slowed significantly from approximately 144% in Q2.
- Compute and infrastructure expenses rose 77.5% quarter-over-quarter to $9.863 billion, with their share of revenue increasing from about 48% to 58%.
- Adjusted operating margin fell from 19% to 15%; at the operating level, the company swung from a profit of $974 million in Q2 to a loss of $567 million.
- As of September 30, 2026, total purchase and lease commitments amounted to approximately $895.4 billion, of which about $69.8 billion will come due within 12 months.
- Following the earnings disclosure, related contracts on Binance, Trade.xyz, and OKX fell 4.86%, 4.82%, and 4.20% respectively, with average hourly trading volume increasing by 60.6% to 142.3%.
- Open interest increased in contract count but slightly declined in USD-denominated terms, as price declines offset the growth in position count.
Author: SoSoValue Research
Anthropic's Q3 revenue grew 46.7% quarter-over-quarter to $16.956 billion, but after the financial data was disclosed, the price of its pre-IPO perpetual contracts fell.
After the prospectus was disclosed, the prices of multiple Anthropic perpetual contracts dropped and trading volume expanded. Among them, the xyz:ANT contract deployed by Trade.xyz on Hyperliquid fell 4.81%, with average hourly trading volume increasing 142.4% compared to the 24 hours before disclosure; related contracts on OKX and Gate also fell 4.18% and 4.85%, respectively.
The price pullback occurred as the AI sector came under overall pressure. Anthropic's revenue growth remains strong, but rising short-term compute costs, declining profit margins, and massive long-term spending commitments are prompting the market to reassess the capital requirements behind this AI company's growth.
Revenue Up Nearly 50% QoQ, but Compute Costs Growing Faster
Anthropic's updated S-1/A filing shows that in Q3 2026, the company's revenue reached $16.956 billion, up 46.7% from $11.555 billion in Q2 and far above the $1.382 billion in the same period last year.
However, while revenue expanded rapidly, compute costs grew even faster. Q3 compute and infrastructure expenses rose from $5.558 billion in Q2 to $9.863 billion, up 77.5% quarter-over-quarter; as a share of revenue, this rose from approximately 48% to approximately 58%.
The company said it delivered approximately $5 billion worth of short-term committed compute in Q3, at costs significantly higher than comparable multi-year compute purchases. As model development and user demand expand, whether compute supply can keep pace with business growth, and at what price additional compute can be secured, is directly affecting profit margins.
In terms of growth rate, the 46.7% QoQ increase in Q3 remains elevated but has slowed from approximately 144% QoQ growth in Q2. For Anthropic, which has already commanded high valuation expectations, investors need to assess both the sustainability of revenue expansion and the ability to convert revenue growth into profit.
Losses Narrow, but Margins Face Pressure
In Q3, Anthropic recorded a net loss of $23.291 billion, wider than the $12.138 billion in the same period last year but significantly narrower than the $66.309 billion in Q2.
The net loss includes substantial fair value changes related to financing instruments. In Q3, fair value changes on convertible notes, derivative liabilities, SAFE and other instruments resulted in a $21.936 billion loss, a major component of the net loss that does not equate to total operating cash expenditure for the quarter.
Operating-level changes better reflect the quarter's cost pressures. Anthropic recorded an operating loss of $567 million in Q3, compared with operating income of $974 million in Q2. The company primarily attributed the swing to a loss to short-term compute costs and approximately $2 billion in non-cash expenses related to a donation matching program.
Adjusted operating income increased from approximately $2.2 billion in Q2 to approximately $2.5 billion in Q3, but the adjusted operating margin fell from 19% to 15%. This indicates that under the company's adjusted metrics, the business is still generating more operating income and adjusted operating income is still growing, but at a slower pace than revenue, causing the adjusted operating margin to decline from 19% to 15%.
A longer-term constraint comes from procurement and lease commitments already signed. Anthropic disclosed that as of September 30, 2026, and commitments entered into thereafter total approximately $895.4 billion, the vast majority related to compute and infrastructure, of which approximately $69.8 billion will come due within 12 months after September 30. These amounts span multiple years and are not current-period expenses already incurred, but they reflect future expansion's dependence on capital and compute delivery.
Contract Prices Pull Back, Trading Volume Expands Notably
Anthropic has not yet officially listed, but its perpetual contracts trading on Binance, Hyperliquid/Trade.xyz, and OKX provide a reference for observing pre-IPO market expectations. After the Q3 financial data was disclosed, related contracts across all three platforms saw price declines, while trading volume expanded notably.
From after the earnings disclosure to 14:00 on November 3, related contracts on Binance, Trade.xyz, and OKX fell 4.86%, 4.82%, and 4.20%, respectively. Details are as follows:
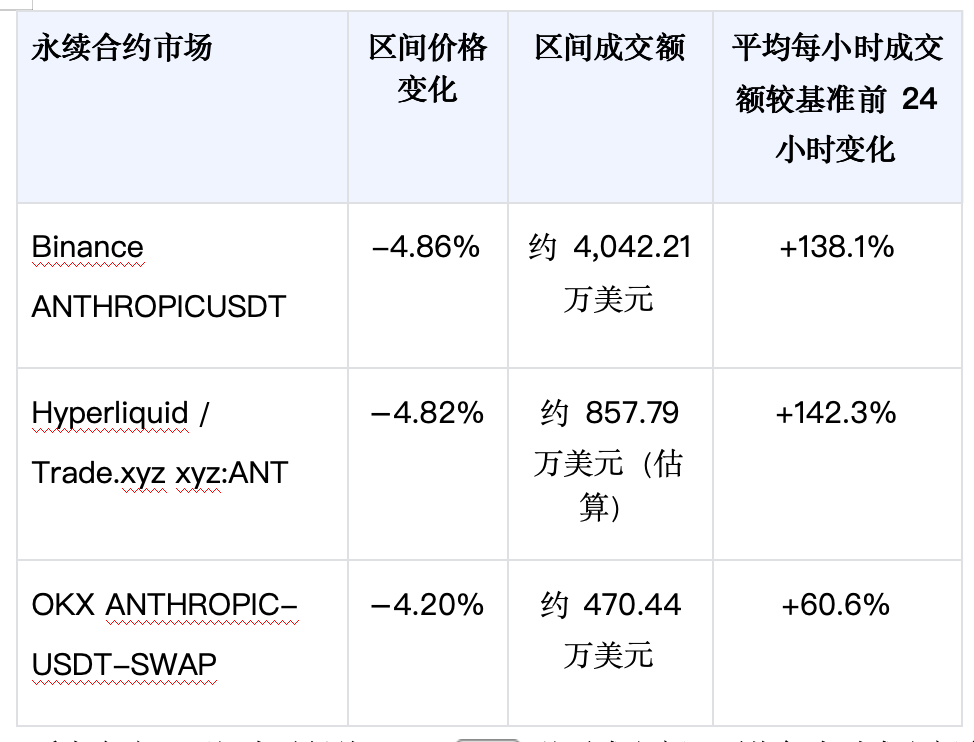
Binance recorded approximately $40.4221 million in trading volume during this period, with average hourly trading volume rising from $1.0895 million in the baseline period to $2.5939 million, an increase of 138.1%. Trade.xyz's average hourly trading volume was estimated to grow 142.3%, and OKX grew 60.6%. Price declines and trading volume expansion occurred simultaneously, indicating that after the financial information update, contract prices pulled back alongside increased trading activity, while the other side of the financial data shows: compute expenses growing faster than revenue and profit margins declining.
This change contrasts with Anthropic's rapid revenue growth. For pre-IPO valuation, the market is focused not only on growth speed but also on whether new revenue can cover rising compute costs. At the same time, overall tech stock performance, IPO expectations, and liquidity across platforms may also jointly affect contract prices, and this pullback cannot be entirely attributed to the financial disclosure.
Open Interest Increases in Quantity, but USD-Denominated Size Edges Lower
Lower prices do not necessarily mean the number of outstanding contracts decreased in tandem. Open interest (OI) data shows that during the above statistical period, open interest quantity on both Binance and OKX increased, but USD-denominated open interest size edged lower.
Among them, Binance's open interest quantity increased 3.07%, while USD OI fell from $73.7382 million to $72.3995 million, down 1.82%; OKX's open interest quantity increased 3.44%, while USD OI fell from $7.3602 million to $7.3476 million, down 0.17%. Open interest quantity increased on both platforms, but price declines offset the quantity growth, causing USD-denominated open interest size to edge lower.
For Anthropic, revenue growth and cost pressures are manifesting simultaneously. Q3 results demonstrated the pace of business expansion, but declining profit margins also raise new questions: as scale continues to expand, can the company secure compute at lower costs and convert more revenue into profit?
Pre-IPO Pricing Focuses More on the Cost of Growth
Anthropic's Q3 financial data presents a picture of coexisting growth and cost pressures: revenue grew 46.7% QoQ, yet compute and infrastructure expenses grew 77.5%, and the adjusted operating margin fell from 19% to 15%. Business expansion remains rapid, but whether revenue growth can sustainably translate into better profitability still depends on compute procurement costs and subsequent capacity delivery.
As the IPO approaches, whether the share of short-term high-priced compute can decline, whether long-term capacity can be delivered as planned, and whether profit margins can improve will become important bases for evaluating its valuation. This contract price pullback is just one stage in the pre-IPO pricing process; subsequent financial disclosures and IPO progress may still shift market expectations.
This round of price decline is just one stage in the pre-IPO pricing process. As more financial information and IPO progress are disclosed, the market's valuation assessment of Anthropic will continue to adjust. These changes can also be continuously tracked on SoSoValue's Anthropic (ANT) dashboard: by observing the company's financial data and announcements alongside changes in contract prices and implied valuations, one can more clearly understand how operating progress is reflected in market pricing.
Additionally, the October ARR that the market is watching is expected to be updated before next week's roadshow, with optimistic expectations that October ARR will reach $78 billion or above, which would be an important indicator for assessing growth potential.





