


DogPay Founder Interview: Slow Is Fast—From U-Cards to a Global Payment Network


- Key Takeaways: Stablecoin payments are shifting from trading scenarios to cross-border trade settlement and corporate payments. By holding licenses, connecting to banking networks, and building its own compliance system, DogPay provides traditional foreign trade and going-global enterprises with integrated infrastructure including stablecoin acquiring, accounts, and card issuance, processing approximately $500 million in funds per month.
- Key Elements:
- DogPay's business covers more than 140 countries, connects to settlement networks such as SWIFT, ACH, and SEPA, serves over 1,000 enterprise clients, and processes approximately $500 million in funds per month.
- Its clients are mainly traditional foreign trade and service-sector going-global enterprises, not Web3 companies; stablecoin collection can shorten the repayment cycle from over a week via SWIFT to same-day or even a few hours, while avoiding foreign exchange losses.
- It already holds Hong Kong MSO, TCSP, and money lending licenses, as well as US and Canada MSB licenses, is applying for a European license, and plans to apply for a Singapore MPI license.
- The core barrier lies in its position in the industry chain: it operates at the issuing bank level, can issue independent BINs rather than shared BINs, and can continuously secure banking account resources from JPMorgan, OCBC, DBS, and others.
- Visa and Mastercard are actively integrating stablecoin settlement; the industry landscape is one of joint building rather than disruption, and stablecoins have expanded the service coverage of USD cards.
- It has added AI router capabilities, unifying large-model routing access into enterprise accounts and, together with employee spending cards, enabling control of spending limits, thereby extending enterprise treasury management scenarios.
Original | Odaily (@OdailyChina)
Author | jk
Over the past two years, as the TGE narrative has drawn to a close, crypto has gradually shifted toward compliance, and stablecoin payments have clearly gained significant momentum.
Before 2023, when people talked about stablecoins, it was mostly about trading, on/off-ramps, and on-chain assets; but now, they are increasingly entering more concrete scenarios such as cross-border collections and payments, corporate settlements, and everyday payments. At the same time, a group of companies built around stablecoin payments has begun to expand from single-purpose U-cards or on/off-ramp tools toward more complete payment systems encompassing accounts, acquiring, settlement, and card issuance.
DogPay is one of them.
If you don't know DogPay, it is a leading player in Asia's stablecoin payment sector: it provides Web3 businesses and cross-border merchants with stablecoin acquiring, corporate accounts, Cards, and CaaS/BaaS services, with a business network covering more than 140 countries and regions, connected to mainstream settlement networks such as SWIFT, ACH, SEPA, and FPS, and serving over a thousand enterprise clients. From accounts and acquiring to card issuance and settlement, DogPay is building a global payment infrastructure that connects stablecoins with the traditional financial system.
But beneath the licenses and the data, why do clients need a payment service provider? How exactly does money flow through this system? And compared with traditional solutions, what exactly does a crypto payment solution save?
Odaily had the opportunity to sit down with DogPay Co-founder Peter for a one-on-one conversation about the compliant payments sector.
Below is the full transcript of the interview:
Odaily: I believe most readers have a general concept of stablecoin payments. Could you share some real client cases to explain why clients need your solution?
Peter: There is one example that is relatively easy to share, called MUFY. It is a product company of the AI era, running an AI emotional companionship platform: the platform sets up a story background for each character, and users can converse with these characters.
In the process of going global and acquiring users worldwide, this team faced a very high barrier to collecting payments, and building the corresponding product themselves would have been very difficult. We provided them with a stablecoin acquiring product, so platform users can pay directly using Dogpay's stablecoin payment—whether for subscriptions or for topping up to purchase credits, this product handles it all.
In addition, our acquiring product has a built-in KYT (Know Your Transaction) system, so the funds enterprises receive are clean: funds that fail KYT cannot be credited, which effectively provides a layer of risk isolation for enterprises.
Odaily: So MUFY is a traditional AI company, not a Web3 company, correct?
Peter: Correct. Most of our clients are not Web3 companies, but enterprises engaged in real goods trade or service trade.
For example, some clients in goods trade receive payment directly in stablecoins from South America or Africa. They can convert the stablecoins into fiat currency on Dogpay and then deposit them into their own corporate accounts. This is because we directly provide enterprises with corporate bank accounts, so collection, conversion, and crediting can all be completed on the same platform.
Dogpay's Web2+Web3 solution, source: official website
Odaily: How does a sum of money go from a fiat account to a stablecoin, and then to funds an enterprise can use? For example, when a user in some small country makes a payment, how does the money enter the enterprise's account step by step?
Peter: First of all, conducting this kind of financial service requires a license. We currently hold licenses in Hong Kong, the United States, and Canada, and are also applying for a European license. With licenses, we can cooperate with banks and open large-scale bank accounts.
You can think of it this way: after obtaining the license, the bank grants us account-opening capability, so we are essentially a digital bank, and clients' account openings are all completed through us. Specifically, under this large account, we open an independent VA (virtual) account for each client. At the same time, the platform also provides clients with an entry point for opening corporate bank accounts, as well as crypto wallets.
After an enterprise completes KYB and KYC and opens an account on Dogpay, it can directly use this system. For example: a mainland enterprise exports a batch of motorcycles to Nigeria and receives payment in stablecoins. This trade genuinely took place, so the enterprise can, on the basis of the trade contract, transfer the stablecoins into its corporate crypto account with us, and the platform then directly converts them into US dollars, which enter the corporate account it opened on Dogpay.
Our account capabilities currently cover a JP Morgan account in the United States, as well as accounts with banks such as OCBC and DBS. After a client opens an account and the payment arrives and is converted into US dollars—this step is what we call off-ramp. Once the funds are exchanged into the bank account, they are fully compliant income and can be directly used for the enterprise's daily operations. That is the general flow of this chain.
The on-ramp from fiat to crypto works in reverse. Because what we provide is a fully compliant bank account—take the JP Morgan account as an example—once a client has this account, they can handle domestic US transfers as well as cross-border remittances via SWIFT, so the channels for funds coming in and going out are all open.
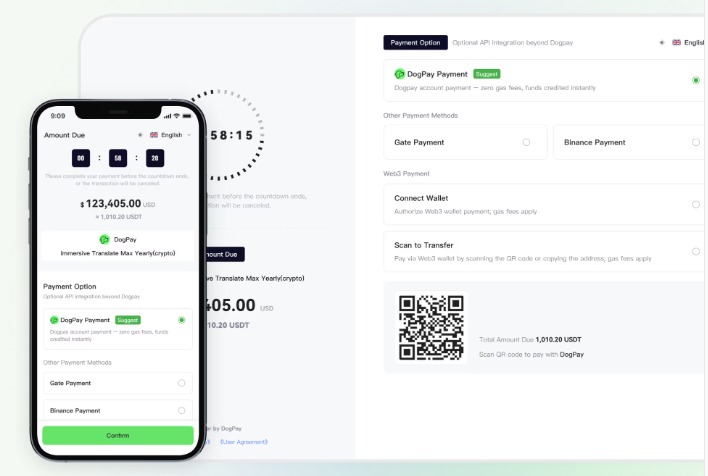
Dogpay's enterprise-side collections, source: official website
Odaily: Compared with traditional finance, at which stages does this process reduce losses and improve efficiency?
Peter: Traditional goods trade has an inherent risk: apart from a few major fiat currencies, the exchange rates of most countries' currencies fluctuate significantly. So when clients collect fiat locally, they face exchange rate risk, and the settlement cycle is also too long—these are the main pain points. If you go through traditional SWIFT remittance, it takes at least a week.
With stablecoin collection, funds go directly into the enterprise's crypto account and are then converted into US dollars, which can basically be completed the same day, or even within a few hours. For enterprises, the collection cycle is shortened and efficiency is greatly improved, while exchange losses and other costs are also avoided.
In addition, the volume of stablecoins in trade settlement is growing. When we chose to start a business in this sector, it was precisely because we expected the settlement scale of goods trade and service trade to grow very quickly.
Odaily: Which of Dogpay's products is currently the most used? Is it the U-card, bank accounts, or services like Card as a Service and Bank as a Service?
Peter: These are different types of products. Card as a Service and Bank as a Service open up our underlying capabilities to other companies that want to offer stablecoin payments.
Two examples. We have a client in Vietnam that runs a foreign-trade-related payment business locally but does not have the ability to open US dollar accounts itself, so we provided that capability to them. We also have a client in Brazil that runs payments locally but cannot issue U-cards—they wanted to issue cards, so we provided them with Card as a Service capability, enabling them to issue US dollar cards locally.
Both types of services are seeing significant client growth. But in terms of amount, the largest is still OTC—Dogpay processes roughly $500 million in funds each month.
Odaily: With such a large volume, what does Dogpay specifically handle behind the scenes?
Peter: It mainly falls into two parts. Let's start with the crypto part.
First, the vast majority of enterprises do not have the ability to manage funds, nor the ability to do KYT—that is, to ensure funds are clean. So they need a platform-based product to help them avoid the risk of receiving tainted cryptocurrencies.
Second is the acquiring business. Acquiring requires generating a separate one-time QR code for each user for a specified amount to make a payment, and it also involves a series of tasks such as fund consolidation. We have already fully developed this entire system, so clients can use it upon integration, without having to learn everything about crypto all over again. Risk control, fund consolidation, and other aspects are all included in this system.
Now for the fiat bank account part. If clients had to go to JP Morgan, Standard Chartered, or banks in Korea individually to open accounts, the cycle would be very long, and the qualification requirements are extremely high. We have already completed filings in these licensed regions, so when helping clients open accounts, they are usually opened within two days. KYC and KYB are also completed with us.
Odaily: In other words, you complete the compliance part on behalf of your clients.
Peter: Correct. We handle compliance and build the infrastructure, so for clients it's simply plug-and-play.
Odaily: Where do you think the real competitiveness of the crypto card, or U-card, market comes from? How is it different from a traditional Visa card?
Peter: Outsiders might think we are a challenger, taking on Visa or Mastercard. But that is not actually the case. Over the past six months, both Visa and Mastercard have been actively integrating stablecoins.
This process can be divided into two stages. For a period before, card networks adopted a model where stablecoins were pegged to the US dollar: issuing banks still settled with Visa in US dollars, but cards were allowed to accept USD top-ups. More recently, some cards already support topping up directly with stablecoins, and when settlement is completed on Visa's side, stablecoins are used as well.
So whether it is traditional card networks or the fintech service companies that came later, their attitude toward stablecoin U-cards is essentially one of co-building. Because with stablecoins, more people can open different US dollar cards instead of being excluded from the service.
For example: there are issuing banks in the US, in Hong Kong, and in Singapore. In the past, limited by business scope, it was very difficult for a South American user to open a card issued in Singapore. Now with stablecoins, users can more freely choose cards from different issuing regions according to their actual needs. So overall, this is a process of co-building and expanding service coverage.
For Visa, it has built a very mature global settlement network over the years—whether it is offline POS machines or online subscription services, these standards were set by Visa, and this part does not need to be disrupted. The emergence of stablecoins is about enabling these products to be used by more people.
Therefore, no one is trying to overturn the Visa system. Users' habits—whether physical cards, virtual cards, or Apple Pay and Google Pay—do not need to change, nor do they need to relearn anything; it's just that stablecoins have been added as an option at the settlement stage.
Odaily: Compared with other competitors in payments and U-cards, what is Dogpay's greatest competitive advantage and moat?
Peter: I think the biggest advantage is channel capability. All businesses can be seen as supply chain businesses—the key is where you sit in the supply chain.
Take cards as an example. From top to bottom, the chain is: card networks, members of card networks, issuing banks; below issuing banks there are card platforms, and below card platforms are various white-label distributors. Over the past two years, we have seen many branded cards gradually disappear, because they used shared BINs and sat downstream in the industry chain, with relatively weak bargaining power and risk resilience.
Dogpay, by contrast, sits at the issuing bank level and can issue independent BINs, helping clients issue the cards they want. We do not use shared BINs; instead, we can apply for a separate BIN for each client.
The same logic applies to bank account capabilities: as our fund volume continues to grow and our licensing capabilities continue to improve, we can consistently gain support from more banks. Currently, we have secured banks in Hong Kong, Singapore, the US, and Korea, and once the European license is approved, European banks are expected to be brought on board as well. We continually obtain better licenses, thereby gaining access to higher-quality bank resources, and then open these capabilities to our clients. Where a company sits in the supply chain determines how high it can go.
This position is not easy to attain. Licenses themselves are costly, applications require a long cycle, and some licenses are difficult to maintain over the long term.
Dogpay's enterprise-side KYB, source: official website
The second advantage is that we understand our clients' real needs better. Most of Dogpay's clients are not Web3 companies as outsiders assume, but traditional enterprises, including those in foreign trade, those taking services and applications global, and companies doing overseas marketing. The business processes and product needs of these clients are quite complex, and through long-term service we have developed a standardized set of solutions.
By contrast, Web3 companies' needs are usually relatively simple—either fundraising or card issuance, such as white-label cards. Different client groups mean different depths of client understanding, and this depth of understanding determines a company's product structure and pace of development.
Odaily: You mentioned licenses earlier. Could you elaborate on which jurisdictions you currently hold licenses in? What is the value and application threshold of these licenses?
Peter: We currently hold an MSO license and a TCSP license in Hong Kong (TCSP is a trust-type license), plus a money lending license; we hold MSB licenses in the US and Canada; the European license is still being applied for, and this year we also plan to apply for Singapore's MPI license.
Odaily: Are these licenses difficult to apply for? Everyone says they are highly valuable—where is the main threshold?
Peter: The difficulty lies in the fact that licensed institutions must be extremely protective of their reputation, so regulators impose correspondingly higher requirements on applicants. During the application stage, regulators conduct stricter reviews of the company's past operating history, including all the clients it has served.
After obtaining the license and entering the regulatory system, the requirements do not loosen. You need to meet higher anti-money laundering standards and regulatory requirements, and your service to every client must be carried out strictly in accordance with these standards.
So companies operating with licenses tend to move at a relatively slower pace. But there are benefits to being slow: every piece of business can withstand scrutiny, and the company's foundation is built more solidly.
Odaily: Are there any figures you can disclose at this point, such as client numbers, revenue data, or even a range?
Peter: We currently process roughly $500 million in funds each month. On the enterprise client side, we crossed 1,000 not long ago, and now have over a thousand enterprise clients.
Odaily: Do you offer different solutions for clients in different regions and of different types (high-frequency, low-frequency, large-amount, small-amount)?
Peter: We have many products: card issuance, bank account capabilities, OTC, and cards for direct enterprise use, among others—what we call "flexible combinations."
Clients can choose just one of these services, such as only opening an account, only doing collections, or only doing remittances; or they can freely mix and match according to their business needs, such as layering acquiring, card issuance, or card usage on top of an account. You can think of us as providing enterprises with a complete infrastructure for fund flows.
Recently, we also added an AI router capability. We found that in addition to collections and payments, enterprises have a large amount of expenditure to manage, and the cost of using AI is one of them. And our judgment is that starting this year, not many companies will still emphasize "I've integrated AI," just as today no company specifically emphasizes "I'm connected to the internet"—AI has become a kind of infrastructure. So we launched the router product, which routes and centrally connects mainstream large models and then provides them to clients.
In terms of usage, clients can create an enterprise account on the platform and then allocate quotas to different employees. Each employee's usage is controllable, and the enterprise manages it centrally through the backend account, making all expenditures clear at a glance.
The logic of this product is actually quite similar to our corporate cards. After an enterprise opens an account with us, it can issue employee spending cards for all employees. In the past, employee travel and daily expenses often went through reimbursement processes, which were cumbersome; now our design is to directly allocate a quota to each employee, who then spends with the card, and it can be pre-configured as to which products the card can and





