Expert interpretation: Under the background of global water release, why do central banks of various countries issue CBDCs one after another?


Central bank digital currency (CBDC) has officially entered the international financial market, and many experts have regarded CBDC as one of the most important trends shaping currency in the next decade. According to the survey data released by the Bank for International Settlements, 80% of the 66 central banks in the world said they were researching digital currency technology, and about 20% of the central banks said they might issue digital currency in the next six years.
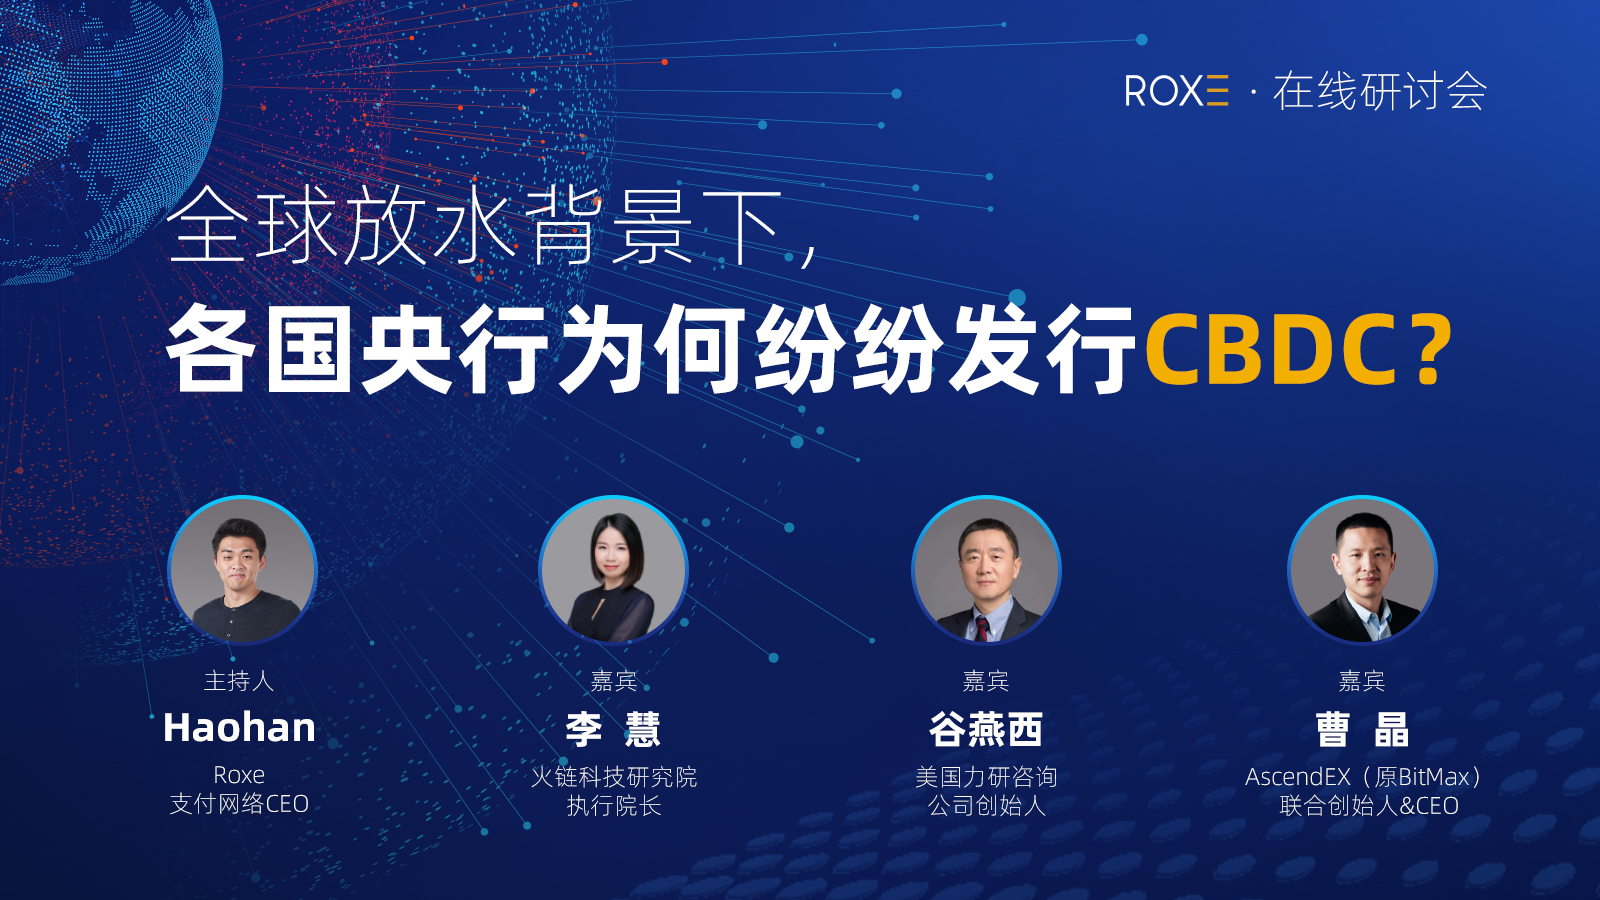
At present, the Bahamas, Uruguay, Ecuador, Venezuela, Thailand, and Cambodia have issued CBDCs. The digital currencies of central banks in emerging market countries such as China have entered the actual testing stage. The development of CBDCs in the world has entered the fast track. What impact will it bring, whether it can effectively deal with inflation, and what opportunities and challenges will it face? To this end, on April 21, the Roxe payment network invited Li Hui, the executive director of the Huolian Technology Research Institute, Gu Yanxi, the founder of the American Liyan Consulting Company, and Cao Jing, the co-founder and CEO of AscendEX (formerly BitMax), to discuss CBDC. The development trend of the conference was discussed in depth, and Haohan, CEO of Roxe payment network, served as the moderator of the meeting.
The impact of CBDC on central banks
CBDC generally refers to digital currencies issued directly by central banks of various countries. "Although it is still unclear what underlying technical basis central banks will use to support the issuance of CBDC, the development of encrypted digital currency and Libra (now renamed Diem) is an important reason for the fire of CBDC." American Liyan Consulting Company Founder Gu Yanxi said.
Initially, the Libra Association’s plan to issue a single stablecoin based on a basket of fiat currencies caused a global stir and spurred central banks to create their own CBDC solutions. However, the central banks of various countries are currently in the exploratory stage, and the research on CBDC mainly depends on what problems it can solve. Gu Yanxi believes that CBDC is mainly to solve two problems: first, how to improve the efficiency of cross-border transactions? At present, the high cost and low efficiency of cross-border payment have seriously hindered the development of cross-border trade. This is the primary problem that CBDC should solve at the moment. Advantages of Libra. Second, how to deal with the opportunities brought about by the emergence of digital assets? At present, digital assets are all generated on the blockchain. If you want to circulate globally, you need a native digital currency that can support the docking with digital assets in terms of programming. The familiar Ethereum uses smart contracts for transactions. Especially with the development of DeFi, many problems can be solved based on stablecoins.
"I don't think a single central bank can solve these two main problems by issuing CBDC alone. If the major central banks cooperate to issue CBDC under the premise of maintaining the independence of their respective monetary policies and agreeing on technology and issuance mechanism, it can effectively solve the above problems. problems, especially in terms of the performance of cross-border payments," Gu Yanxi added.
In this regard, AscendEX (formerly BitMax) co-founder & CEO Cao Jing and Gu Yanxi hold different views. He believes that the real problem to be solved by digital currency is not necessarily cross-border payment, but the unbanked population in remote areas. question. "At the same time, I don't think central banks of various countries will adopt unified measures to issue digital currencies. Just like the European Union, if the same currency is adopted, it will cause great problems. Therefore, in the initial pilot implementation, the central banks of various countries should issue their own digital currencies independently. CBDC, this will help big countries observe the effects of CBDC issuance, and then decide whether to follow up." Cao Jing added.
Cao Jing analyzed that CBDC is not necessarily an encrypted currency. The core of the blockchain is distributed bookkeeping. Judging from the current development situation, there is no clear regulation that the digital currency issued by the central bank is an encrypted currency based on the blockchain. It could also be electronic money in the form of centrally designed storage. Whether CBDC is a blockchain cryptocurrency, including whether Libra is a digital currency, and what form central banks will take are still inconclusive.
"I think that the main pain point that central banks want to solve by launching digital currencies is the problem of most people in developing countries without bank accounts, rather than cross-border payments." Cao Jing further analyzed that due to the high maintenance costs of outlets , in many countries, especially remote rural areas in developing countries, there are no bank outlets, and it is very inconvenient for people to deposit and withdraw money. Digital currency can solve the problem of unbanked accounts to a large extent, and many services can be solved online. . In addition, if the U.S. dollar is replaced by a digital currency, it will have a major impact on the world. Therefore, large economies including the U.S. dollar and the euro are unlikely to start pilot projects from the initial stage, but some small countries with relatively simple economic structures It has developed rapidly on the digital currency track, and of course there are major countries like Japan, but most of the pioneers of CBDC are small countries such as Iran and Venezuela, because for countries that cannot freely convert foreign exchange, digital currency has Help it break through some practical barriers.
"It is true that the cost of replacing the original system with digital currency in small countries is relatively low, just like China's mobile payment instead of cash payment, and if the United States replaces credit card payment, it will not bring much benefit, and it will replace the original system. The cost of education is also very high.” Roxe payment network CEO Haohan also said.
Li Hui, executive director of Firelink Technology Research Institute, believes that CBDC is a historical development trend. In the digital world of the future, whether to build a financial infrastructure that is more suitable for the digital world on the existing system is the key consideration for many central banks in designing CBDC. The purpose is to better control the flow of funds, and then better Carry out macro-control and implement some fiscal and monetary policies, including increasing the flexibility of currency payments and reducing many unnecessary intermediate links. The U.S. economic stimulus package in March last year is a good example. The reason why the digital dollar plan was proposed at that time is because digital currency payments are more efficient. Through the digital dollar, the U.S. government can distribute relief funds directly to the American people more efficiently without going through banks or payment companies. Not only the United States, but many countries have this demand.
CBDC is a new thing, and central banks of various countries are in the exploratory stage. Regarding whether the underlying technology will adopt blockchain technology, whether it is a retail CBDC or a wholesale CBDC, countries have different approaches. Although some countries have launched CBDC, they have not actually implemented it. The reason is that the CBDC system has not been fully utilized. The development of CBDC will have a certain impact on the existing banking system. A successful CBDC design will not undermine the stability of the existing financial system, otherwise it will bring financial risks.
"As Dr. Cao said, the countries that tried CBDC before were actually countries with underdeveloped economies or very serious inflation, because they were worried that if China's DCEP or the US digital dollar were implemented, they might replace them. The domestic legal currency has caused their own sovereign currency to be severely impacted and affected. In addition, CBDC is a digital system based on technology, and there will be some technical risks, and it needs to be continuously tested and iterated." Li Hui added.
Can CBDCs Ease Inflation Dilemmas?
"If CBDC is not designed properly, it may bring certain risks. In a financial crisis, depositors may transfer their deposits to CBDC. Originally reliable deposit insurance can continue to prevent runs, but it is easier for CBDC to transfer money away. , thus causing the risk of a run.” Haohan said: “In the digital world, legal currency cannot be circulated better, because almost every country’s legal currency needs to pass through its own clearing and settlement system, such as the United States for local clearing and settlement through FED-WIRE, and China’s There are two sets of clearing and settlement systems, domestic and international, which are isolated from each other and have great friction. For some countries with severe domestic inflation and international sanctions, the issuance of CBDC may be a possible solution for currency substitution to alleviate inflation, such as Turkey."
Li Hui believes that CBDC is a payment method and cannot directly solve the economic problem of domestic inflation. The United States has watermarked a lot of money before, and mentioned in the report that these funds can be distributed to the people and businesses by means of CBDC or digital dollars, which will accelerate everyone's expectations for inflation.
Regarding the relationship between CBDC and inflation, Cao Jing and Li Hui have the same views. He said that digital currency itself will not solve the problem of inflation, but if digital currency is adopted on a large scale, it can help policy makers of governments of various countries formulate more refined monetary policies. Inflation has helped somewhat.
"Whether it is CBDC or the existing economic system, the key to curbing inflation lies in monetary policy, that is, whether it can truly control the amount of money issued to be consistent with the amount of GDP issued. If the total amount of money is constant, a deflationary economy will not lead to inflation. "Gu Yanxi said: "The carrier of CBDC itself will not have an impact on inflation. The key still depends on the monetary policy of the central bank. Under the current situation, I think Bitcoin is the best tool to curb inflation on a global scale. "
Can the CBDCs of various countries be interconnected?
"Currently, the development of CBDC is still in the early stage. Whether it is technical or political, it is difficult to truly unify the global digital currency. There is a high probability that there will be a public interface formulated by the main currencies of several major countries. The future of CBDC Development is not so much a technical issue as a political and commercial issue, and it is still too early to talk about whether or how to integrate in the experimental stage.” Cao Jing said.
Gu Yanxi believes that it is very possible to reach a unified standard in terms of technology, and then countries can achieve interoperability after issuing according to their own monetary policies. Specifically, whether the central bank will adopt a "distributed" or "centralized" system and standard mainly depends on what kind of agreement the central bank will reach. Although the input cost is high, unified technical standards must be feasible, and operability can also be realized.
"I very much agree with Mr. Gu's point of view. In the future, we will definitely establish a set of global common unified standards to realize the interconnection between CBDCs in various countries." Li Hui said: "This standard is not only technical, but also includes many business aspects. Yes, on the basis of unified standards, currency exchanges between each other can be carried out more smoothly, including the realization of payment and other functions." In fact, the G7 Group, G20, Bank for International Settlements, Financial Stability Board FSB and the Financial Action Task Force on Anti-Money Laundering International organizations such as the FATF have been discussing very intensively about the future standards of CBDC. Just like the current cross-border payment is based on the SWIFT standard, there will be such an institution or organization specifying a set of standards for digital currency in the future. In addition, the current cross-border remittance is a bank-to-bank transaction. There are many banks in each country, which is an N-to-N relationship. In the future, if each country has its own CBDC central bank digital currency system, it will become a one-to-one relationship. Therefore, for future cross-border payments, CBDC can reduce many intermediate redundant links in business and improve remittance. efficiency.
The positive effect of China's issuance of DCEP
At present, the proportion of China in the world economy is not proportional to the proportion of RMB in the foreign exchange reserves of various countries. Now, although great progress has been made in the internationalization of the renminbi, as a non-convertible currency, it still restricts many countries from adopting the renminbi. The development of digital currency can improve the international status of the renminbi. In addition, the promotion of RMB digital currency is also good for people without bank accounts in many parts of China, allowing more people to enjoy financial services.
"For the defense of the U.S. dollar, China, as the second largest economy in the world, has a GDP of about 75% of that of the United States. It has a very strong ability to resist the inflation output of the U.S. dollar, so the launch of the digital renminbi is China's international The economic influence of China and the popularization of RMB have laid a good foundation." Cao Jing added.
"I very much agree with Dr. Cao's views on monetary policy." Gu Yanxi said: "DCEP, as a new RMB carrier, will definitely touch more users and application scenarios that cannot be touched by the existing RMB circulation system, such as Dr. Cao The unbanked people mentioned are indeed good for them. As for whether DCEP can fight against the expansion of the US dollar, in addition to monetary policy, it also depends on the degree of promotion of DCEP and the degree of market acceptance on a global scale. factor."
"The international status of the renminbi mainly depends on monetary policy and economic strength. Of course, it is also inseparable from some foreign policies. DCEP based on payment, circulation efficiency and diversity can speed up this process, but at present DCEP is only a trial in China. It will take a long time for large-scale use and international investment. Therefore, in the short term, DCEP may not have any substantial resistance to the current situation, but can only play a mitigating role. But in the long run, it can indeed accelerate the increase of RMB. international status." Li Hui said.
At present, countries are rushing to promote CBDC. Under the trend of digitalization, CBDC, as an important supplement to the current underdeveloped payment and settlement system, can not only solve the existing cash management cost problem, but also promote the realization of inclusive finance, allowing more people to enjoy more convenient, Safe, low-cost financial services.