Analyst: Variational's $1.5B FDV valuation is overly optimistic, conservative scenario could put it at just $167M
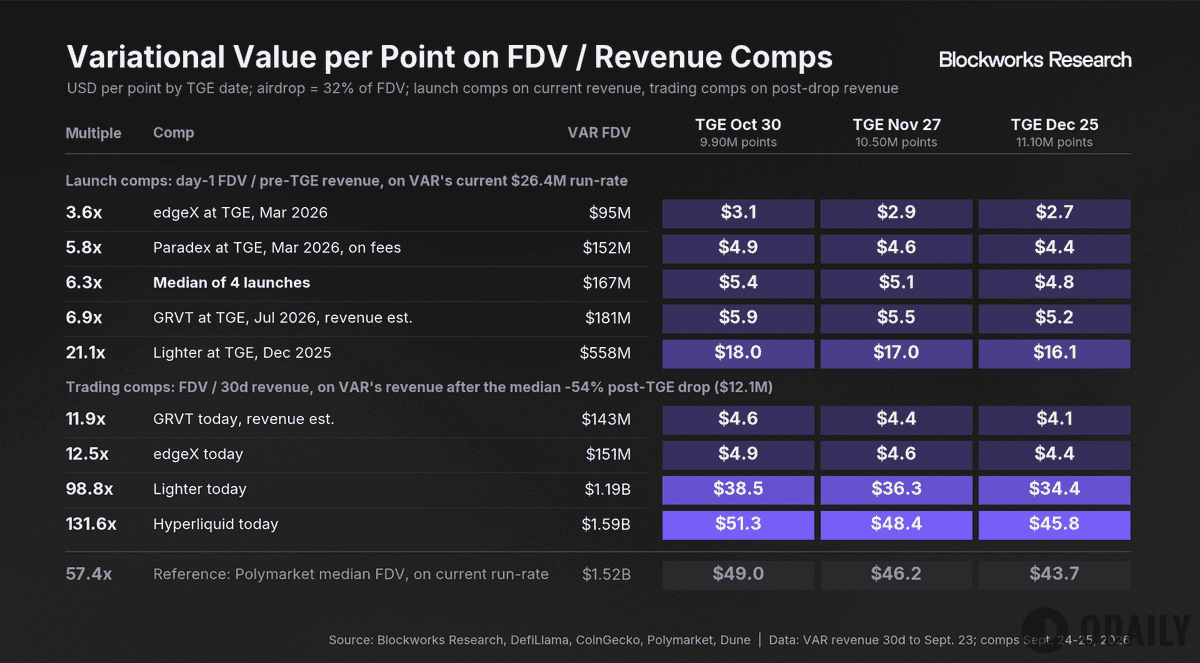
Odaily News: Blockworks analyst Shaunda Devens posted on X that Polymarket's current FDV valuation of approximately $1.5 billion for Variational is somewhat overly optimistic. This pricing directly applies Hyperliquid and Lighter-level valuation-to-revenue multiples to a platform that still relies on points subsidies. By comparison, the median first-day "FDV / annualized revenue" ratio for recently launched Perp DEX tokens is only 6.3x (Variational is currently around 57x), and within the first month after TGE, trading volume typically drops sharply by a median of 54%.
Shaunda added that if conservative assumptions based on historical precedents are adopted (using the median first-day "FDV/annualized revenue" ratio of 6.3x), Variational's fair valuation would be only $167 million, corresponding to a points price of $4.8–$5.4. Even using the highest recent ratio precedent (Lighter's approximately 21.1x), its valuation would still only be about $558 million, corresponding to a points price of $16–$18.
However, Shaunda also explained: "To be clear, given that current market risk appetite is clearly in a Risk-on state, we do not believe Variational's valuation at TGE will fall to the extremely conservative range mentioned above. These historical multiples are listed to illustrate that current pre-market OTC pricing may be overly optimistic."