






Shorting the New Cloud Providers: Musk's Masterful Power Play


- Core Viewpoint: Musk is shorting more than 200 emerging compute cloud providers, predicting they will die en masse as debt markets tighten and power delivery lags. This is essentially a commercial snipe launched on the back of SpaceX's own cash flow and its ability to have "power waiting for chips." Compute infrastructure is shifting from a leverage-fueled land grab to a new cycle defined by balance sheet strength and engineering delivery.
- Key Elements:
- Musk says vast amounts of compute will be "stranded" in half-built data centers, and that the 200-plus Neoclouds will face "guppy-level" death and consolidation, with most unlikely to survive.
- Neoclouds rely on a high-leverage flywheel of "long-term contracts as collateral—borrow to buy chips—collect rent to pay interest." The bottleneck has shifted from chip shortages to power shortages, and cash flow is severely mismatched with debt duration.
- Leader CoreWeave carries over $35.6 billion in debt and $640 million in single-quarter net interest expense. Its bond yields have spiked to 15%–16%, CDS-implied default probability exceeds 60%, and its stock fell more than 20% in a single week.
- SpaceX posted Q3 revenue of $14.575 billion, with its AI division accounting for $7.56 billion. Its nameplate compute capacity stands at 1.7 gigawatts, and it has locked in $40 billion in GPU financing, backstopped by investment-grade credit and Starlink cash flow.
- Industry evaluation standards are shifting toward debt service capacity and delivery certainty. Providers lacking independent cash flow will face punitive financing costs of 12%–15% and become prey for mergers or liquidation.
Original | Odaily (@OdailyChina)
Author | Azuma (@azuma_eth)
This past weekend, Elon Musk dropped a series of predictions on X, tossing a depth charge into an AI compute infrastructure market already seething with undercurrents.
Faced with Silicon Valley's still-beloved "hoard GPUs and get rich" myth, Musk first coldly predicted that massive amounts of compute would be "stranded in half-built data centers," then handed down a death sentence to the world's 200-plus emerging compute cloud providers (Neoclouds) — with the debt markets slamming shut, these companies are about to face a "guppy-level death and consolidation."
Tellingly, just days before unleashing this "compute bear thesis," Musk had been boasting on SpaceX's Q3 earnings call about how its own compute was oversubscribed, with major cloud providers and dozens of startups endlessly queuing up to rent.
On one side, his own compute is bustling and he claims to have just finalized a $40 billion loan for buying GPUs; on the other, he is loudly pronouncing that his peers are about to be wiped out. Were Musk's weekend broadsides the good-faith whistleblowing of an industry pioneer? Or a precisely targeted hunt?
Death Prophecy: From Stranded Compute to Industry Annihilation
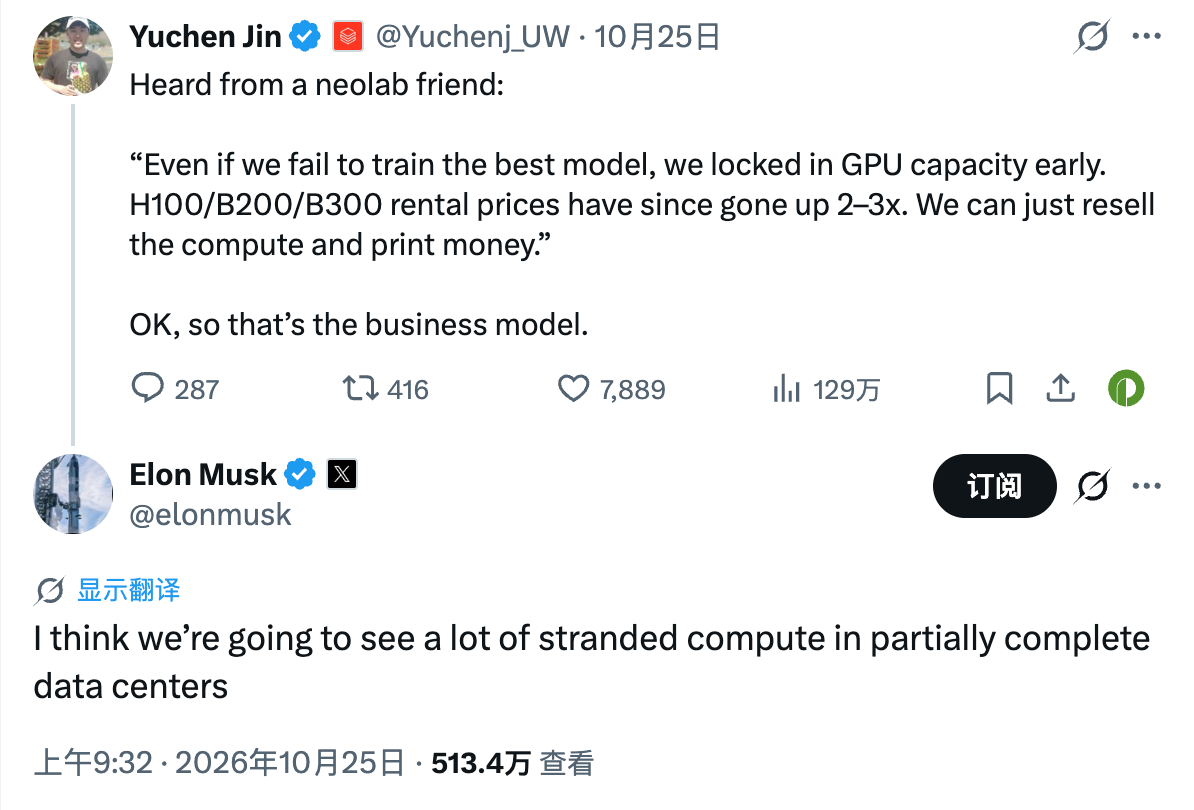
The storm began on October 25, when Silicon Valley blogger Yuchen Jin shared an anecdote from inside the industry. A friend at an AI lab revealed the current absurd ecosystem: "It doesn't matter if we can't train the best models. We locked in GPU capacity early. H100, B200, and B300 rental prices have tripled or doubled — just reselling compute is a money printer."
Under that tweet, which treated "compute middlemen" as a business model, Musk poured the first bucket of cold water: "I think we'll soon see a lot of stranded compute, stuck in data centers that are only half built."
Then Chamath Palihapitiya, a Silicon Valley VC sitting on a large portfolio of "powered land assets," stepped in on Musk's side (in hindsight, the two always felt like they were coordinating), publishing a long post that dissected Musk's view frame by frame and predicted that 2027 would be a "year of brutal clearing" for AI compute infrastructure.
Chamath noted that Neoclouds now face four major problems.
- Organizational and capital mismatch: Most Neoclouds are poorly managed and thinly capitalized, while traditional hyperscalers are extremely bureaucratic — signing a single NDA takes three months, and hosting periods run 18 months.
- 2027 pipeline delays and compute hoarding: Delays in the existing infrastructure pipeline will erupt in 2027. By then, the traditional giants will inevitably prioritize internal demand and force margin extraction externally through "model routers." Large volumes of paid-for GPUs will sit gathering dust in warehouses, with returns far below the cost of capital — "except for one company (an apparent nod to SpaceX), everyone will face this problem."
- The physical deadlock of land and power: In West Texas, the compute heartland, securing mineral rights exemptions is slower than ever; East Texas is riddled with legal risk; local grids are completely overloaded, and utilities, in order to clear out "placeholders," will inevitably raise the upfront capital commitment thresholds sharply.
- The fatal weakness — liquidated damages (LD) clauses: This is the last straw. Neoclouds lacking high-availability compute operations experience, once hit by construction delays or outages, cannot meet uptime commitments, and the strict liquidated damages clauses in customer contracts will trigger penalties directly, causing them to lose investment-grade packaging or even be abandoned by major customers.
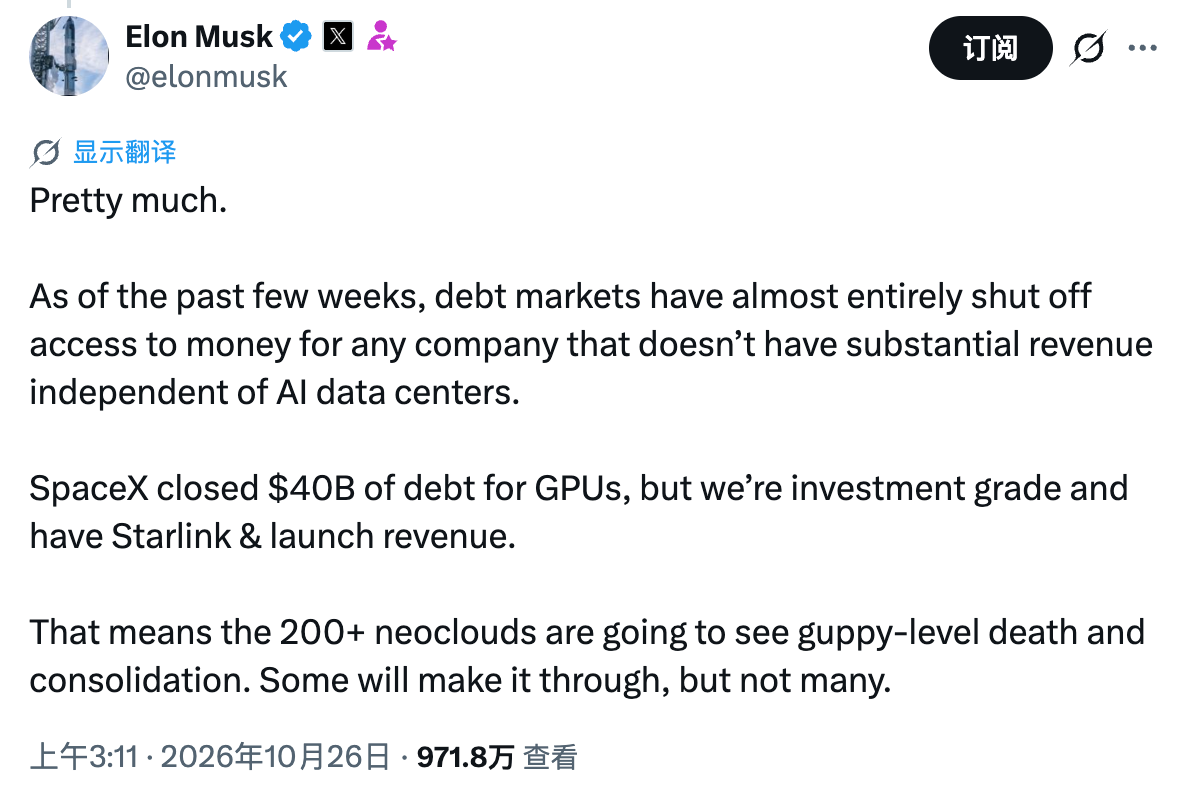
Facing Chamath's precisely delivered knife, Musk then added the most lethal follow-up: "Pretty much. Over the past few weeks, for any company without a revenue stream independent of AI data centers, the debt market has essentially slammed shut. SpaceX just finalized $40 billion in debt to buy GPUs, but we are investment grade and backstopped by Starlink and rocket launch revenue. That means 200-plus Neoclouds will face guppy-level death and consolidation. A few will survive, but not many."
Musk then specifically emphasized: "SpaceX will absolutely not acquire any Neocloud, because that would make no sense."
Eve of the Storm: Why Did the "Borrow to Buy GPUs" Flywheel Suddenly Seize Up?
Harsh as Musk's words were, he hit the most fragile pressure point of the current Neocloud industry — the physical delivery trap of "GPUs waiting for power" colliding with a "credit pullback wave" in financial markets.
Over the past two years, Neocloud players represented by CoreWeave, Nebius, and Crusoe ran a highly leveraged capital flywheel — first signing 3-to-5-year long-term compute offtake contracts with major customers; then using those contracts and the GPUs being purchased as collateral to borrow tens of billions in private credit or high-yield debt from Wall Street; finally buying cards, renting data center space, and collecting rent to service principal and interest.
But by October 2026, this flywheel built on the assumption of "infinite expansion" hit the brakes simultaneously on both the physical and funding sides:
The first blow came from the shift in the physical bottleneck — the market went from "short on chips" to "short on sockets." As Musk warned back in 2024, the AI bottleneck transmits along the path of "chips → transformers → power." Nvidia's GPUs are now shipping continuously, but supporting substations, grid interconnection permits, cooling systems, and powered data center shells are severely lagging. Once the astronomically expensive GPUs get stuck at half-finished construction sites and cannot be plugged in, they generate not a cent of rental cash flow.
The second blow came from creditor panic and duration mismatch. GPUs gather dust in warehouses, but creditors' interest clocks never stop for a second. Just ten days before this war of words erupted (October 13-16), industry leader CoreWeave had just suffered a brutal "double kill" in stocks and bonds:
- Although CoreWeave held a contract backlog of up to $104.2 billion, its total on-book debt had snowballed to $35.6 billion (including $16.3 billion in lease liabilities, broad debt commitments exceeded $51 billion); net interest expense in Q2 alone reached $640 million, far exceeding its operating cash generation, directly dragging the company to a massive net loss of $626 million.
- In mid-October, the bond market struck first. Yields on CoreWeave's 2032 and 2031 bonds soared, successively touching crisis levels of 15%-16% for junk debt (bond prices fell below 80 cents on the dollar), five-year credit default swaps spiked to 1000-1200 basis points (implying a default probability of over 60% over the next five years), and the stock plunged more than 20% in a single week.
- Notably, on October 13, the day CoreWeave bond yields spiked, Chamath posted the chart on X with a "👀" emoji, and Musk commented below with "Yikes" — the next day CoreWeave's stock plunged 15% — and with this past weekend, that marks the second time in half a month the two have teamed up in tandem to short peer sentiment.
This is the truth of the "doom loop" Musk described. Neoclouds need to pay for GPUs immediately, while the $100-billion-plus backlog will take years to convert into cash; once data center energization is delayed and financing rates spike to 15%, the liquidity gap in between instantly becomes a black hole that devours the company.
Whistleblower or Hunter? Musk's Open Conspiracy
Once you understand the industry's fragility, looking back at Musk's sudden bearish turn makes it clear this was no simple "industry risk warning," but a commercial snipe timed to perfection. Because in this crisis, Musk is precisely the biggest potential beneficiary.
First, look at SpaceX's real hand today. With its AI business deeply integrated into its "Super Intelligence" (SI) division, SpaceX is no longer just an aerospace and satellite communications company — it is now the world's most ferocious AI compute giant.
On October 21, SpaceX said in its just-disclosed Q3 2026 earnings report:
- SpaceX's Q3 total revenue surged 161% to $14.575 billion, with net profit of $4.4 billion;
- Among that, the Super Intelligence division posted quarterly revenue of $7.56 billion (up about 830% year over year), historically surpassing the connectivity business where Starlink sits ($5.248 billion) and the space launch business ($1.767 billion), accounting for more than half of total company revenue;
- As of the end of September, SpaceX's nameplate compute scale had reached 1.7 gigawatts, with quarterly capital expenditure of $19.59 billion (of which $16.44 billion went to the SI business), and it had just completed $40 billion in off-market chip financing through private debt to purchase Nvidia GPUs arriving in Q1 and Q2 next year.
Put that earnings report on the table, and Musk's three-layer motive for repeatedly shelling Neoclouds becomes obvious.
First, a dimensional strike on business model — "power waiting for GPUs" beating "GPUs waiting for power," and "high spot premiums" beating "cheap long-term contracts."
Most Neoclouds rely on third-party commercial real estate developers to build data centers; to get bank loans, they have to sign 3-to-5-year fixed-price long-term contracts with customers; and in today's compute-scarce environment, those early long-term contracts instead lock in thin margins.
SpaceX, by contrast, leveraging the industrial-grade vertical integration it has demonstrated in places like Memphis, takes the "power waiting for GPUs" route — planning to prepare 20 gigawatts of power and cooling capacity next year to match 10 gigawatts of compute. More critically, SpaceX relies on Starlink and rocket launches to generate tens of billions of dollars in stable cash flow and investment-grade credit each year, so it has no need to sign cheap long-term contracts to beg banks for loans. So when SpaceX tells peers who have GPUs but cannot plug them in that "your compute will be stranded," it is essentially declaring to the whole market: "Only here do we have ready power and sockets."
Second, psychological warfare and pulling the rug out — scaring off peers' customers and creditors.
As market observers have noted, despite Neoclouds' heavy debt, as long as customers keep placing orders and operating cash flow maintains high growth, most leading players still have a chance to trade time for space and ride out the storm.
Musk's ruthlessness lies in this: on the surface he is talking down Neoclouds' funding chains, but in reality he is intimidating Neoclouds' downstream customers and upstream creditors. When the world's most influential tech giant publicly asserts that "200-plus neoclouds will die like guppies" and "the bond market has closed," which large model company or enterprise customer would still dare hand mission-critical compute business to a neocloud that "could blow up at any moment"? Once customers panic and turn to SpaceX, or banks further tighten refinancing, Neoclouds that could have survived will also see their funding chains snap and make the prediction come true.
Third, a positioning battle at the industry chain level — Jensen Huang certainly wants all buyers alive, but Musk only wants peers dead sooner.
Comparing Musk's remarks with Nvidia CEO Jensen Huang's comments a few days earlier highlights the subtlety of the commercial game. Just as CoreWeave was crashing in mid-October, Nvidia — which holds about 10% of its shares — immediately had Jensen Huang step up to defend it, stressing that Neocloud demand was off the charts and funding problems would eventually be resolved.
The reason for the different attitudes is simple. Jensen Huang sells shovels — he needs every Neocloud buying GPUs to survive in order to maintain Nvidia's premium and a diversified buyer ecosystem; Musk is both a super-buyer of chips and a dealer selling compute directly. If peers go bankrupt, not only will the freed-up Nvidia high-end chip allocations be absorbed by SpaceX, but overflow high-end compute renters will also be forced to flow to SpaceX.
As for Chamath, who has been playing the "good cop" with Musk, he also said publicly in August that he and his partners had acquired nearly 6 gigawatts of grid power and behind-the-meter generation capacity, which will ramp up and interconnect in batches from now through 2029. In other words, Chamath is sitting on nearly 6 gigawatts of powered data center land waiting to sell — the more he hypes the 2027 "GPUs waiting for power" panic, the higher the price his "powered dirt" can fetch.
AI May Not Face a Winter, but Compute Infrastructure Is Due for a Shakeout
It should be noted objectively that Musk's claim that "the bond market has completely closed" is still somewhat exaggerated. Shortly before he spoke, Nebius had just secured a $3.5 billion loan led by Citigroup, and Lambda had obtained $1 billion in investment-grade financing earlier in the month. Capital has not fled AI infrastructure, but the wild era of indiscriminate spending is indeed over.
Still, it must be acknowledged that the public opinion tsunami Musk triggered is accelerating the structural turn of the AI compute market from late 2026 to 2027.
In this shakeout, the capital market's evaluation criteria for compute companies have quietly shifted — from simply valuing backlog growth to a brutal focus on debt-servicing capacity and cash flow duration matching. All-around giants with non-AI independent cash flow and investment-grade ratings can still borrow tens of billions at extremely low cost, while "one-legged" Neoclouds that rely purely on debt to buy GPUs and lack self-generated cash flow will be forced to bear punitive financing costs of 12%-15% or more, ultimately becoming prey for giant M&A or asset liquidation.
At the same time, the industry's competitive moat has thoroughly shifted from the early "grabbing GPUs" to "grabbing power and delivery certainty." 2027 will ruthlessly test the engineering delivery fundamentals of every compute giant: whoever can secure land and mineral rights, overcome grid interconnection queues, and quickly deliver high-availability, powered, liquid-cooled data centers will capture the high-premium spot windfall; conversely, no matter how many high-end chips are hoarded, in the face of strict liquidated damages clauses they will only become depreciating liabilities.
Under this pressure, the downstream buyer base is also fragmenting — leading closed-source large model companies are sparing no expense to snap up high-certainty spot compute from SpaceX, while more traditional enterprises are starting to bypass middlemen and build their own small and mid-sized data centers to run open-source models, pursuing data security and controllable costs.
Ultimately, Musk's "stranded compute thesis" is not sounding the winter horn for the AI industry; on the contrary, it declares that AI compute has moved from "PPT land-grabbing plus leverage" into a new cycle of "competing on balance sheets and heavy-industry delivery capability." In this shakeout set to fully erupt in 2027, demand remains scorching, but most of the "guppy" chips on the table are destined to be swept into the pockets of the great sharks at the top of the pyramid.





