Macro Weekly (8.21): Institutions are buying on dips


Market Overview
The worlds major stock indexes have experienced three consecutive weeks of declines, with the SP and Nasdaq recording record highs in March, as worries about higher Treasury yields and inflation are heating up, as well as concerns about an unexpected slowdown in Chinas economy compounded by a debt crisis. industry crisis and the biggest decline since the end of last year. After an extremely optimistic July, market sentiment appears to have fallen back into neutral territory, with data showing some institutions are buying on dips in the last two weeks.
stock market
The SP 500 Index fell by more than 5% from the end of July, the Nasdaq 100 Index and the Russell 2000 Index fell by nearly 7%, the CSI 300 Index fell by 5.7%, the Hang Seng Index fell by nearly 11%, and the Nikkei 225 Index fell by 5.5%. The decline in the Dow Jones Industrial Average was relatively muted. However, since the stock market has gained about 20% since the beginning of the year, the correction so far is still within a healthy range and has not yet caused a significant deterioration in market sentiment.
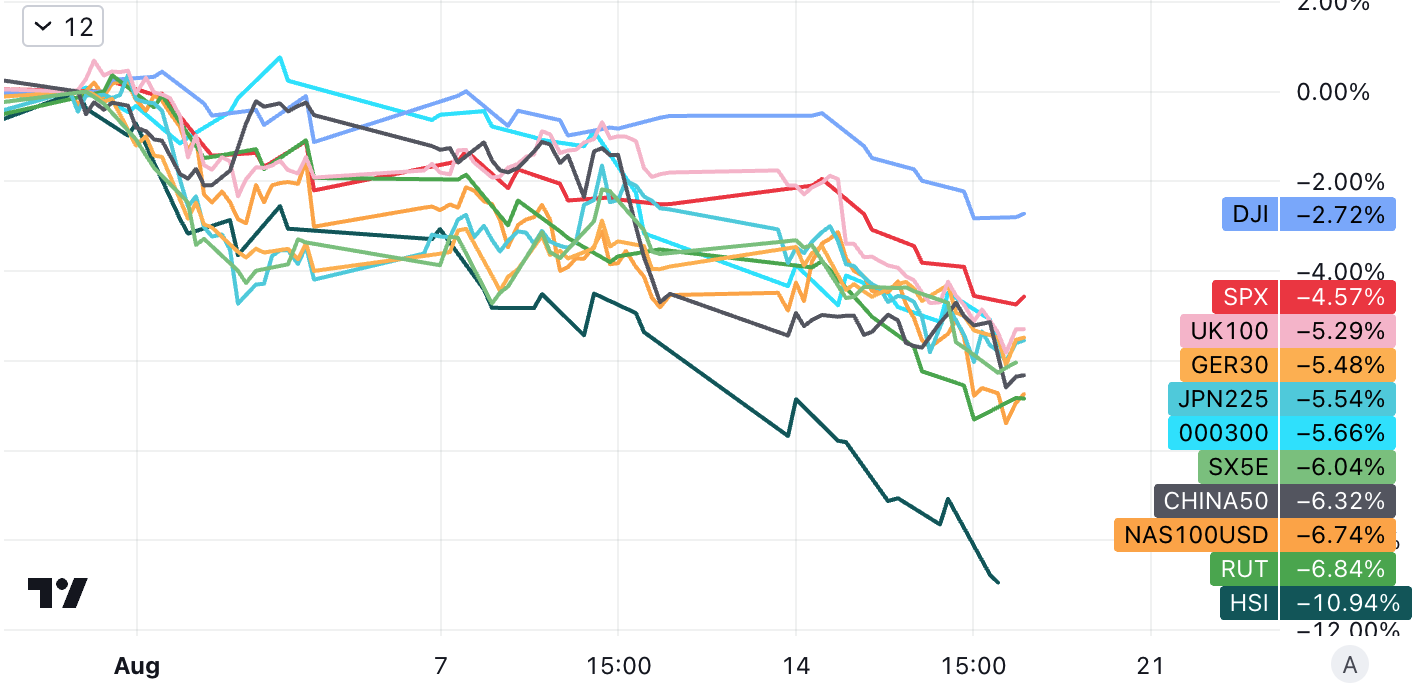
The difference in decline is mainly due to the comprehensive reflection of changes in investment styles, changes in the interest rate and inflation environment, and profit prospects.
The Dow Jones Industrial Average consists primarily of large, stable, and long-established companies. In an environment of rising inflation and interest rates, investors may be more inclined to invest in these companies with defensive qualities. Meanwhile, the Nasdaq is mostly made up of technology and growth stocks, while the Russell 2000 is mostly made up of small-cap stocks, which may appear riskier in the current environment. Highly valued growth stocks, such as many Nasdaq components, may come under greater pressure as rising funding costs threaten to erode future earnings prospects. By contrast, many of Dow Jones companies may fare better in an inflationary environment because they may be able to more easily pass on cost increases to consumers.
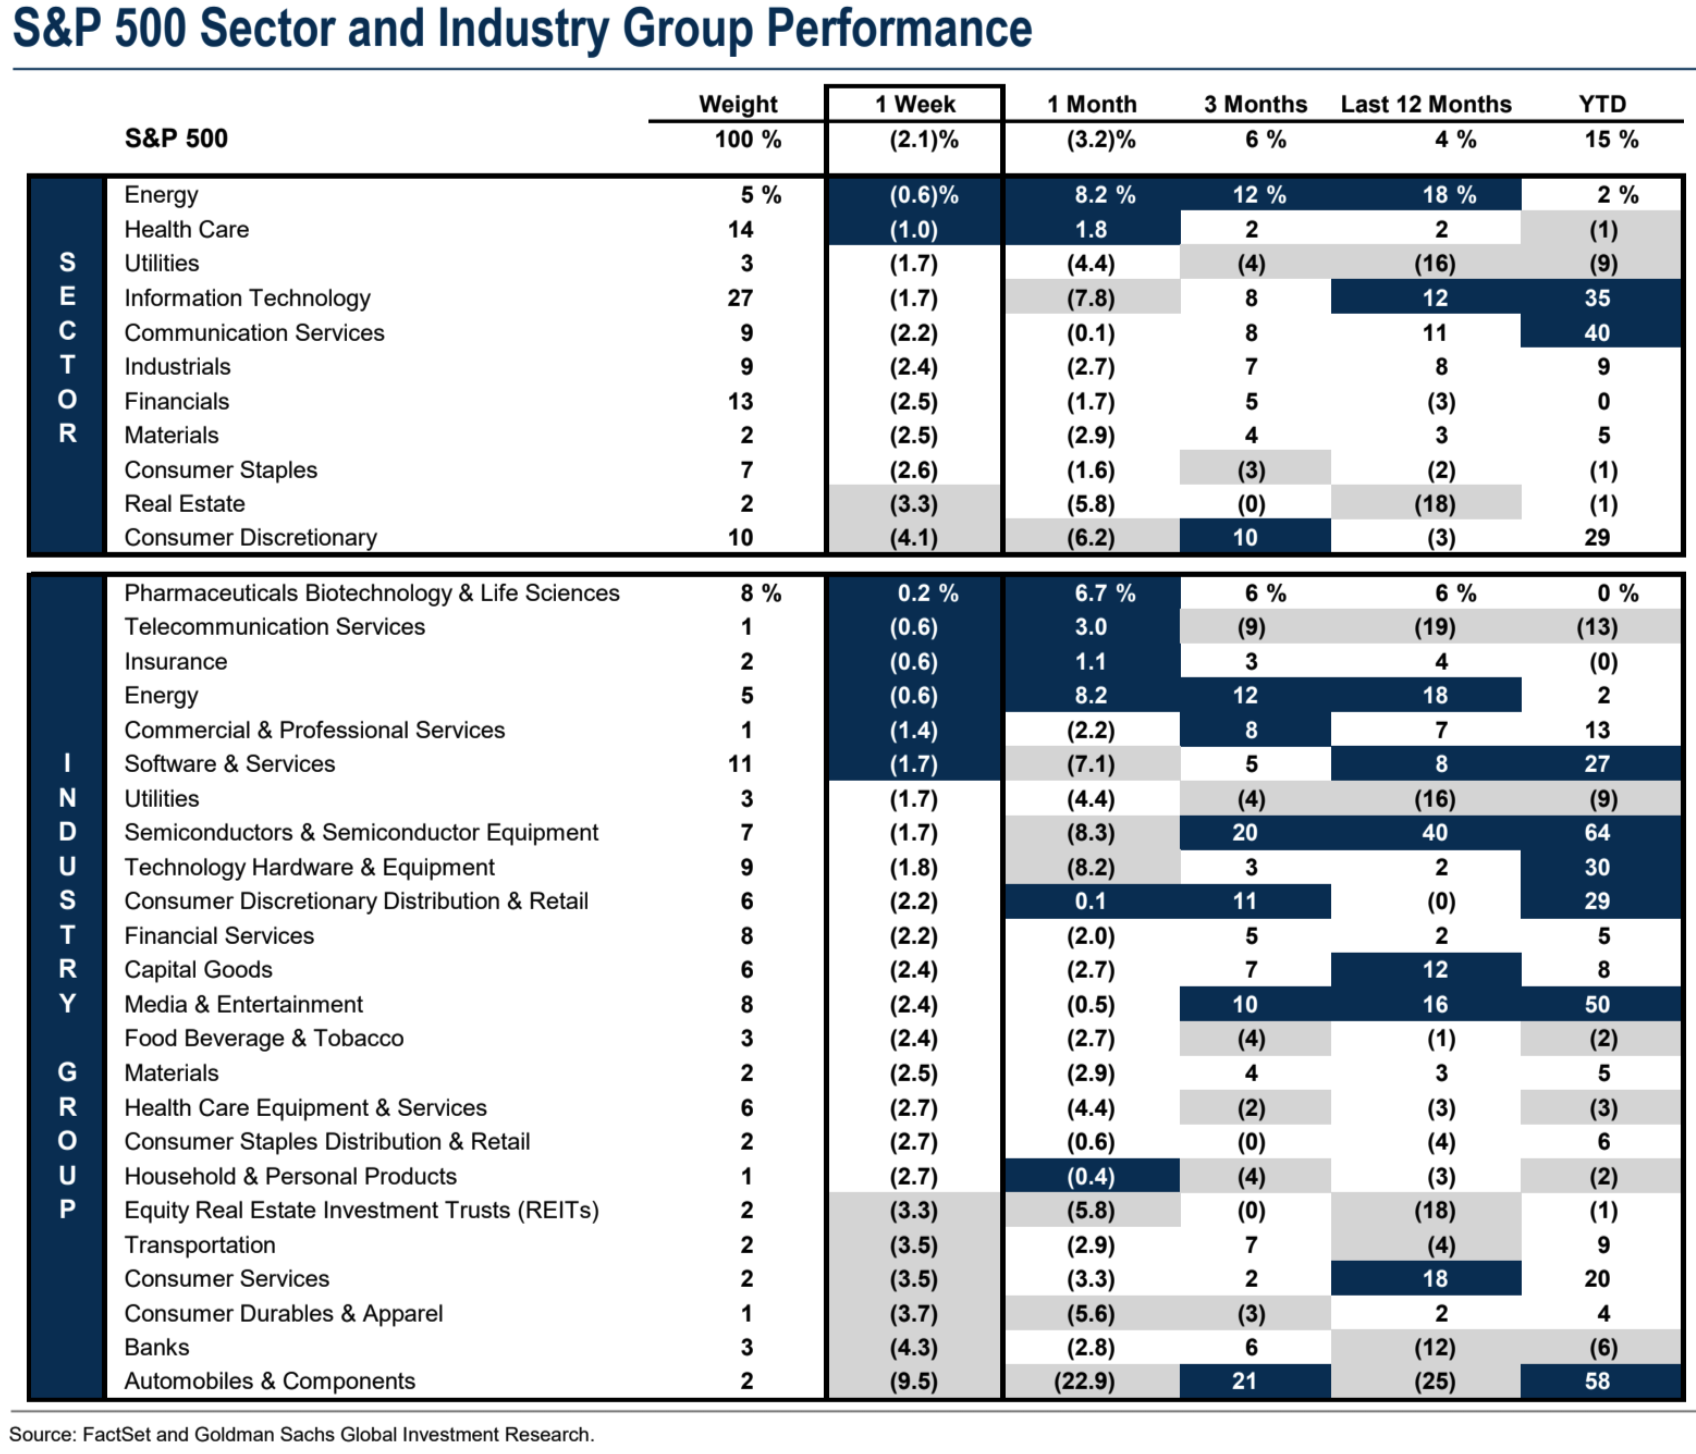
In terms of industries, biomedicine, communication services, and energy sectors performed well last week, while discretionary consumer goods such as automobiles, durable goods, and transportation and tourism sectors lagged behind.
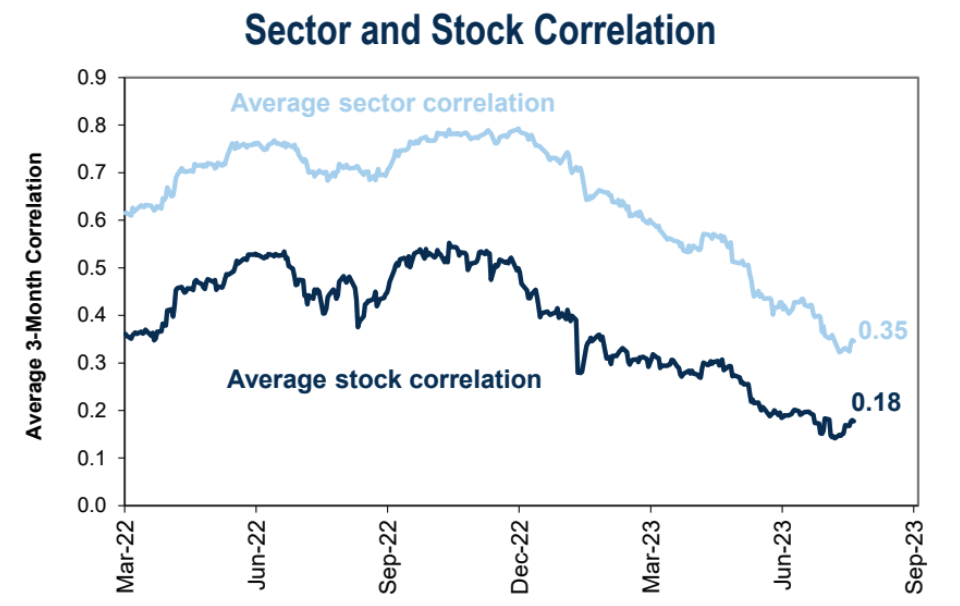
Because of the overall decline, the correlation between stocks (0.15 – 0.18) and sectors (0.33 – 0.35) rebounded slightly:
interest rate market
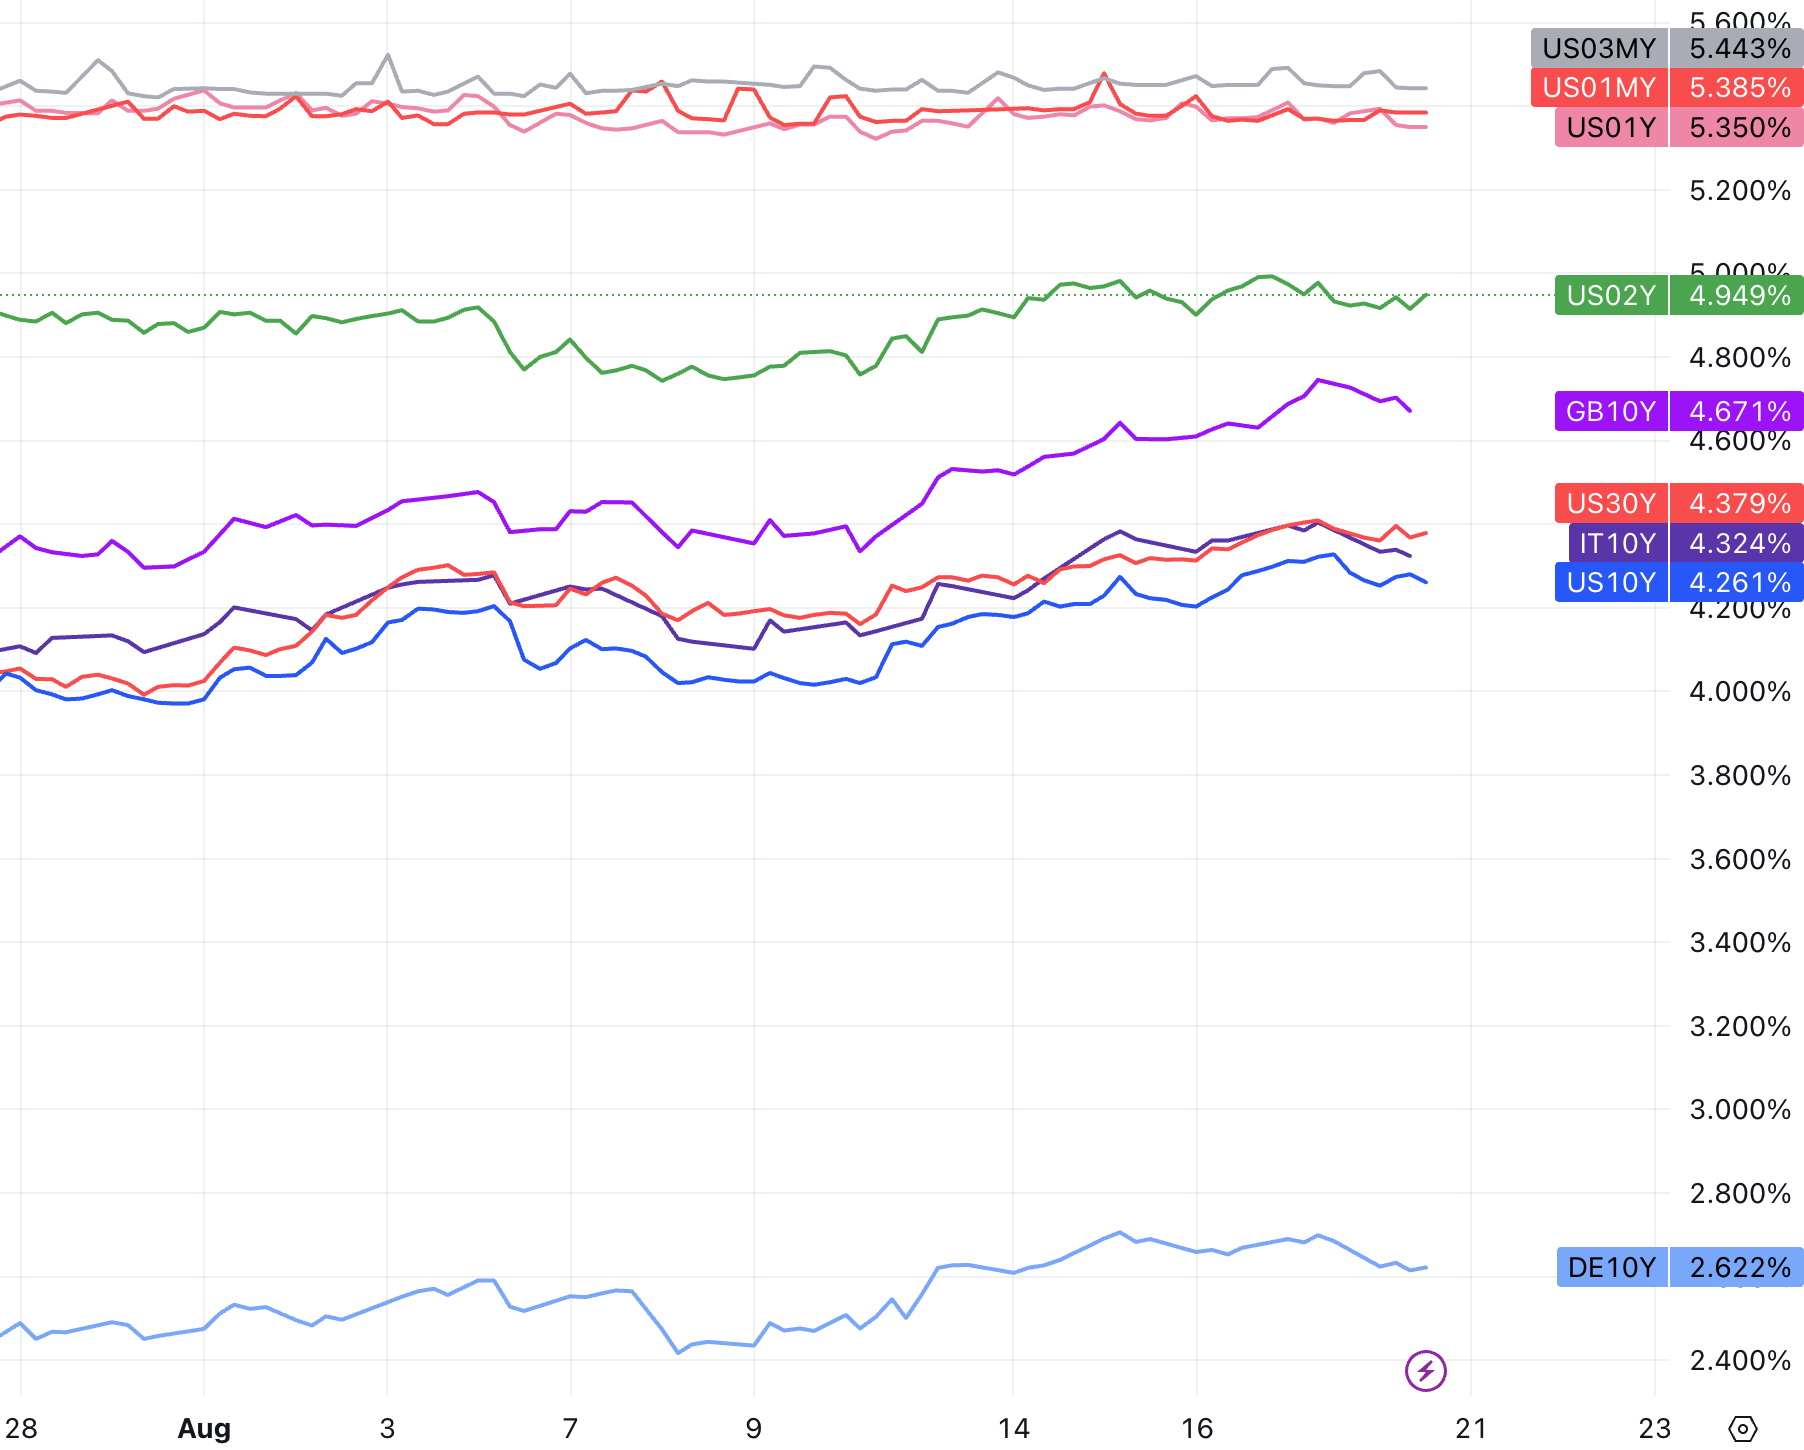
Supported by supply-side pressure and hot economic data, the U.S. 10-year Treasury yield hit its highest level since October at 4.33% last Thursday, while the 1-12-month bond yield was almost unchanged; in the United Kingdom, due to inflation indicators Still strong, wages are growing faster than expected, and the UK 10-year government bond yield jumped to 4.75% last week, the highest level since October 2008:
Concerns about Chinas worsening real estate crisis and its impact on the countrys sluggish economy also added to the negative sentiment.
Chinese real estate giant Evergrande Group filed for bankruptcy in New York late Thursday. Real estate woes are a major drag on Chinas struggling economy. News of Evergrande comes after another Chinese property giant, Country Garden, recently warned it would lose billions of dollars in the first six months of this year. Moodys downgraded the companys rating, citing increased liquidity and refinancing risks.
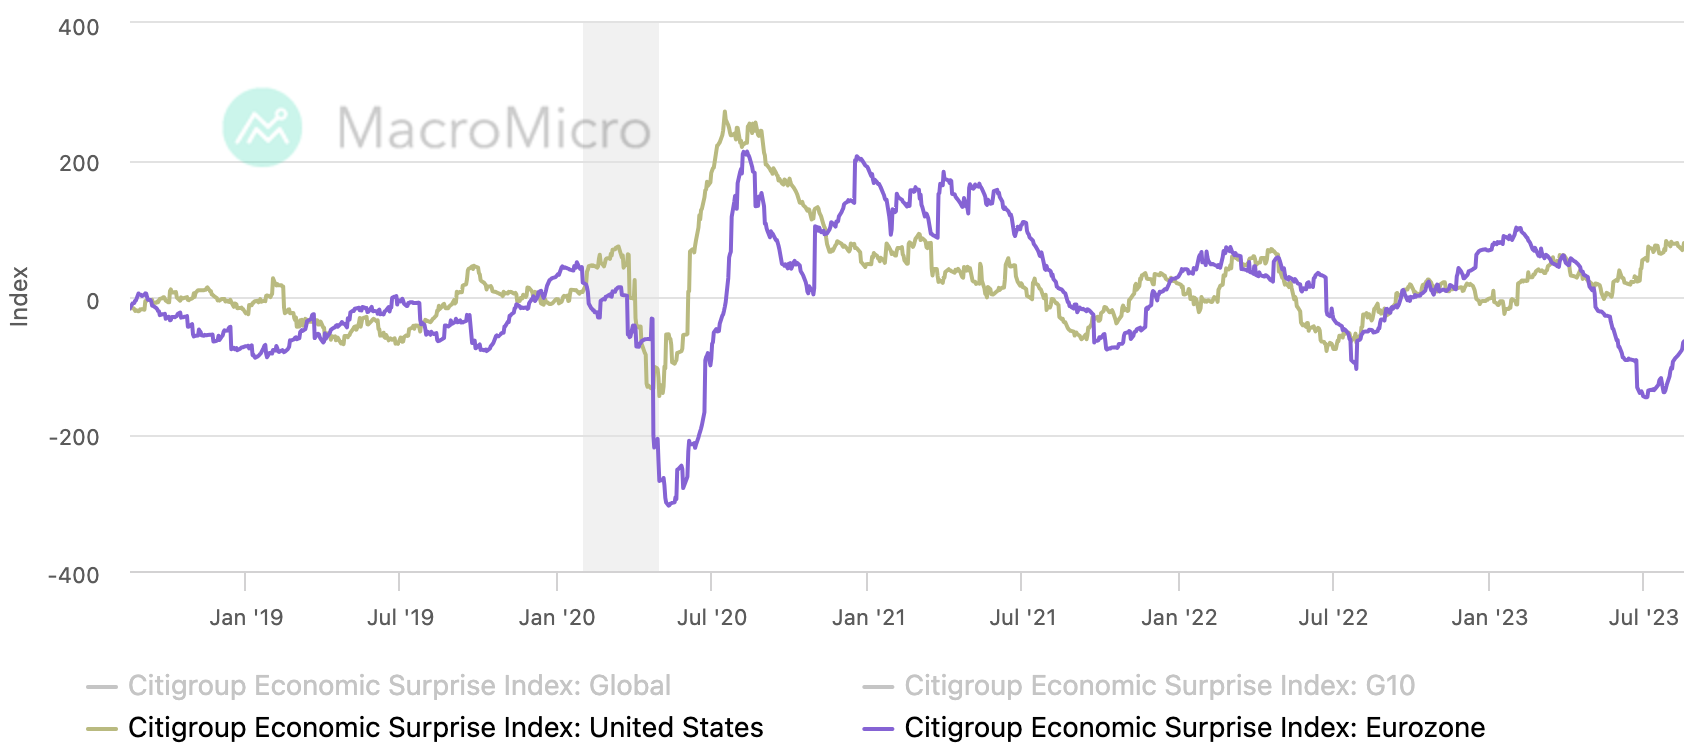
Generally speaking, the stock markets retracement reflects more of a re-pricing of interest rate and price expectations rather than a signal that the economy has completely lost momentum. In the past few months, the market had been overly optimistic in assessing the economic prospects in a rising interest rate environment. The European and American economic surprise index, as measured by the Citi Economic Surprise Index, has rebounded this summer, and the macroeconomic momentum is still:
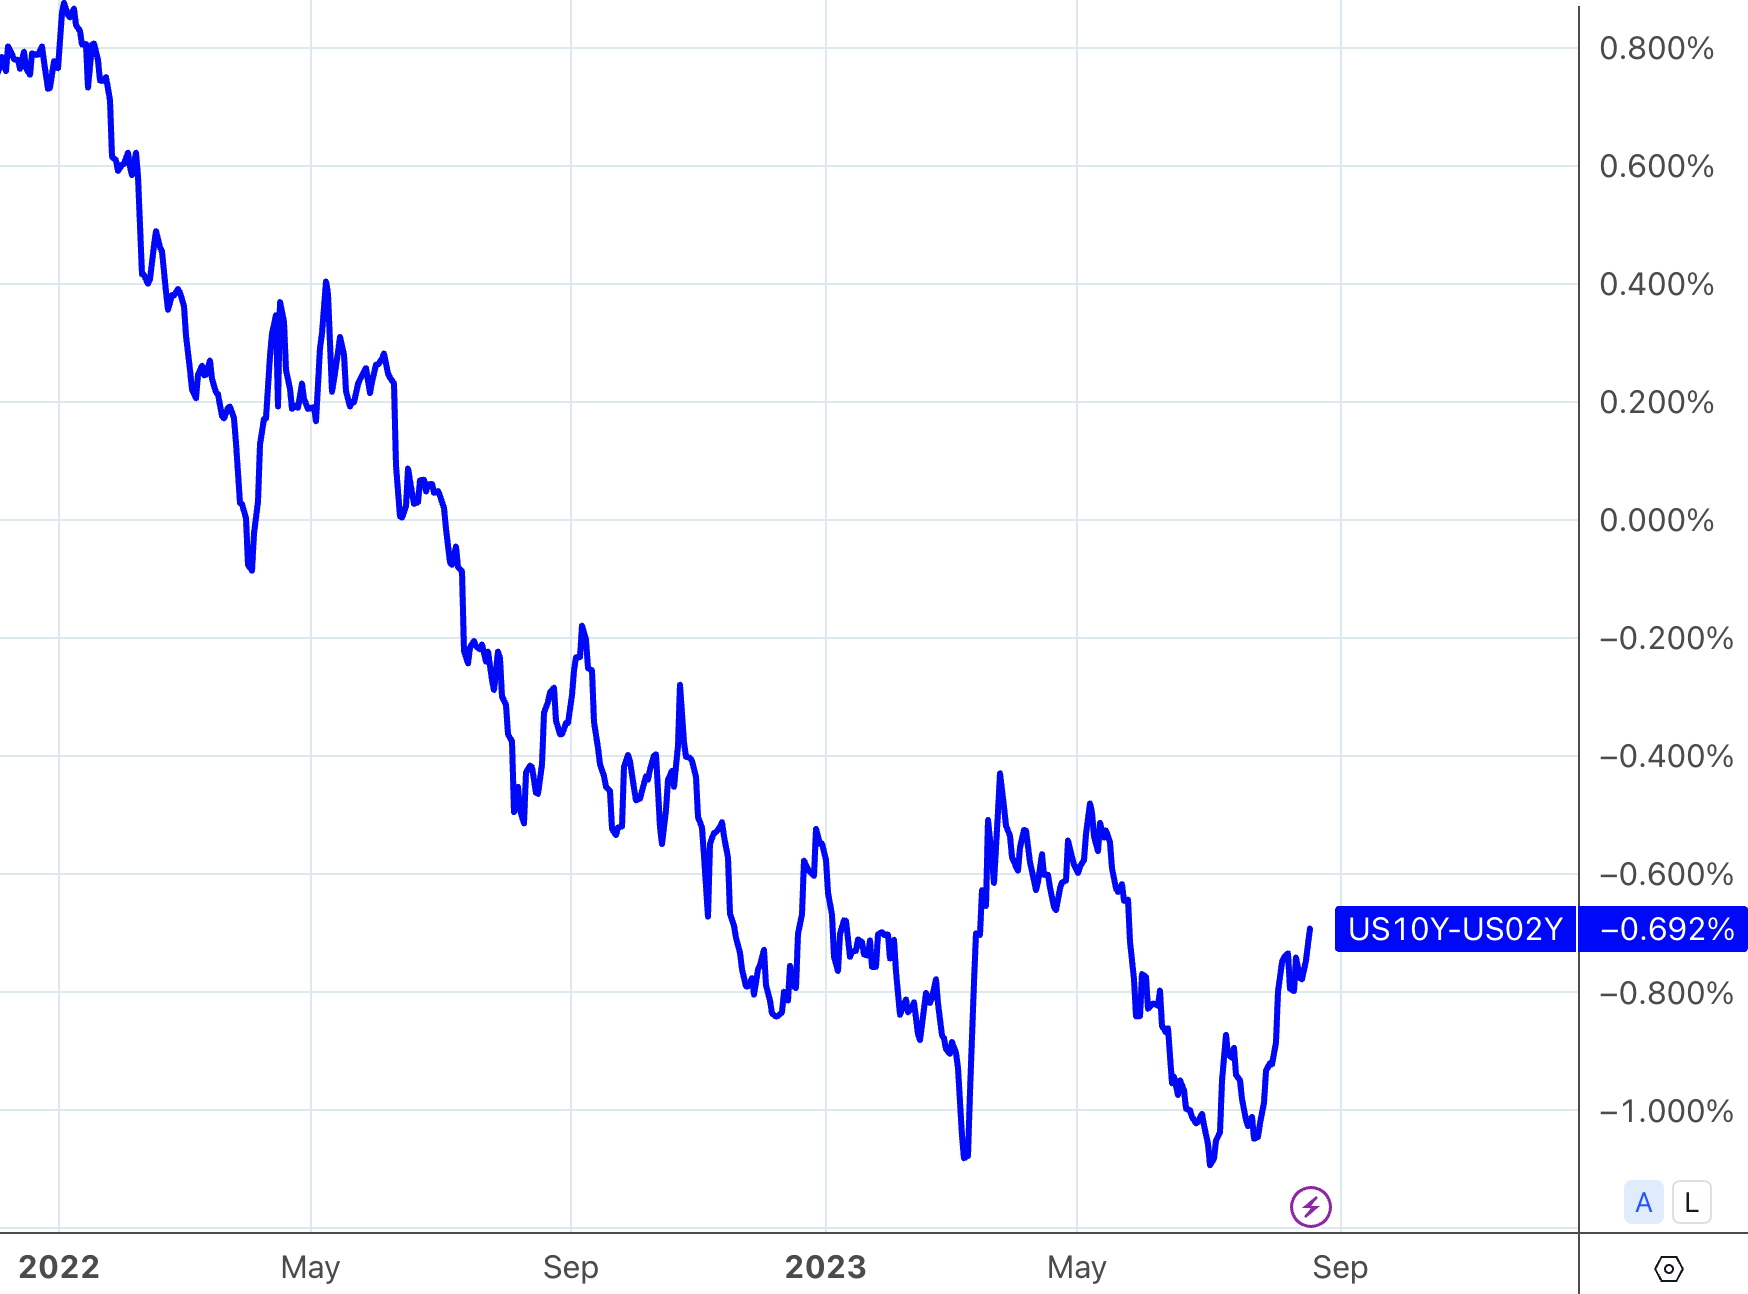
Regarding the interest rate market, the rise in the 10-year Treasury bond yield is not a signal that the Federal Reserve will further raise interest rates significantly in the future. The main reason is that the previous increase in long-term interest rates has not matched the increase in short-term interest rates. The recent adjustment is not unexpected, because Either short-term yields will fall or long-term yields will rise. The bond market structure should not maintain long-term distortions. The Feds interest rate hike expectations have come to an end, and marginal changes will have limited impact on the interest rate market. In addition, we can see that the inversion in long-term and short-term bond yields has narrowed significantly since August, which can actually be regarded as a signal of a rebound in long-term economic growth expectations:
exchange rate market
The dollar followed yields higher, with DXY hitting a two-month high last week. USD/JPY briefly rose to 146.2, the yens lowest level since November last year, exceeding the area that triggered intervention by Japanese authorities in September and October last year. But Japanese Finance Minister Shunichi Suzuki said last week that authorities were not intervening against absolute currency levels.
The yuan fell below 7.3 last week, refreshing its lowest level since October last year. However, on Thursday and Friday, the Peoples Bank of Chinas statement to defend the yuan exchange rate and the sharp increase in the central parity rate led to a sharp rebound in the exchange rate, and USDCNY finally stayed at 7.28.
In the last three days of last week, the Peoples Bank of China set the central parity rate of the onshore yuan against the U.S. dollar at around 7.2, about 1,000 basis points higher than the market price. This is the largest defense of the yuan on record through its midpoint guidance. The central parity rate of RMB is the reference point for transactions, and its range is limited between +2% and -2%, and the Chinese central bank will nominally accept unlimited orders within this price range. In addition to raising the central parity rate, another source said that a large state-owned bank directly sold dollars to buy renminbi in the foreign exchange market last week.
The Peoples Bank of China just cut interest rates last Monday, and more monetary and fiscal stimulus measures are on the way. The pressure on the yuan to depreciate due to the widening of interest rate differentials may continue. But at present, mainstream institutions do not expect that the non-renminbi will continue to depreciate sharply at the current position.
For years, China has been highly sensitive to any sharp movements in the yuan, as the speculative attacks that accompanied the yuans devaluation eight years ago are still fresh in its mind (the 811 Exchange Rate Reform). The risk of a vicious cycle of rising market pessimism and China facing capital outflows, which may lead to more severe devaluation, highlights the need for appropriate intervention.
Trending
[Fed survey: U.S. consumers short-term inflation expectations hit a new low since 2021]
A survey released by the New York Federal Reserve on Monday showed that the countrys consumers one-year short-term inflation expectations fell from 3.8% to 3.5% in July, hitting a new low since April 2021 and marking the fourth consecutive month of decline. Consumer inflation expectations for the three-year and five-year periods also fell, both falling to 2.9 percent from 3 percent.
[Bank of Japans service sector inflation hits 2% for the first time in 30 years in July]
CPI rose 3.3% year-on-year in line with expectations, but the core core CPI, which excludes energy and food, rose 4.3% year-on-year, still the fastest since 1981.
[The minutes of the Federal Reserve meeting are hawkish: warn of major inflationary upside risks, and be wary of rising stock markets]
The minutes show that most policymakers still believe that inflation has significant upward risks, which may require further interest rate hikes; many believe that balance sheet reduction may not stop even when interest rates are cut; almost all policymakers believe that July is appropriate to raise interest rates by 25 basis points. support keeping interest rates unchanged. Fed staff no longer expects mild recession this year, sees PCE inflation falling to 2.2% in 2025
At the July FOMC policy meeting, Federal Reserve staff pointed out that stock prices have generally risen, corporate bond spreads have narrowed, asset valuation pressures have been significant, and the risk assessment in May was moderate; they also named residential and Commercial real estate prices, saying they are elevated relative to fundamentals. Fed policymakers also cited the danger that commercial real estate valuations could fall significantly, which could have adverse effects on some banks and other financial institutions, such as insurance companies.
[After energy and food, signs of stagnant inflation in the United States reappeared, and used car prices rose for the first time in four months]
U.S. used car wholesale data rose for the first time in four months in the first half of August, raising concerns that this is another sign that inflation may be sticky for a long time after a rebound in energy and food prices.
[U.S. retail sales in July rose 0.7% month-on-month, exceeding expectations, the largest increase since January]
At $696.4 billion, it topped the previous reading by 0.3% (revised 0.2%) and beat market expectations by 0.4%, the biggest gain in six months. Retail sales account for about one-third of all consumer spending and are often seen as one of the bellwethers of the U.S. economy. Benefiting from continued growth in real wages, U.S. retail sales growth exceeded expectations across the board in July, indicating a solid performance of the U.S. economy.
[Chinas U.S. bond holdings fell to a 14-year low]
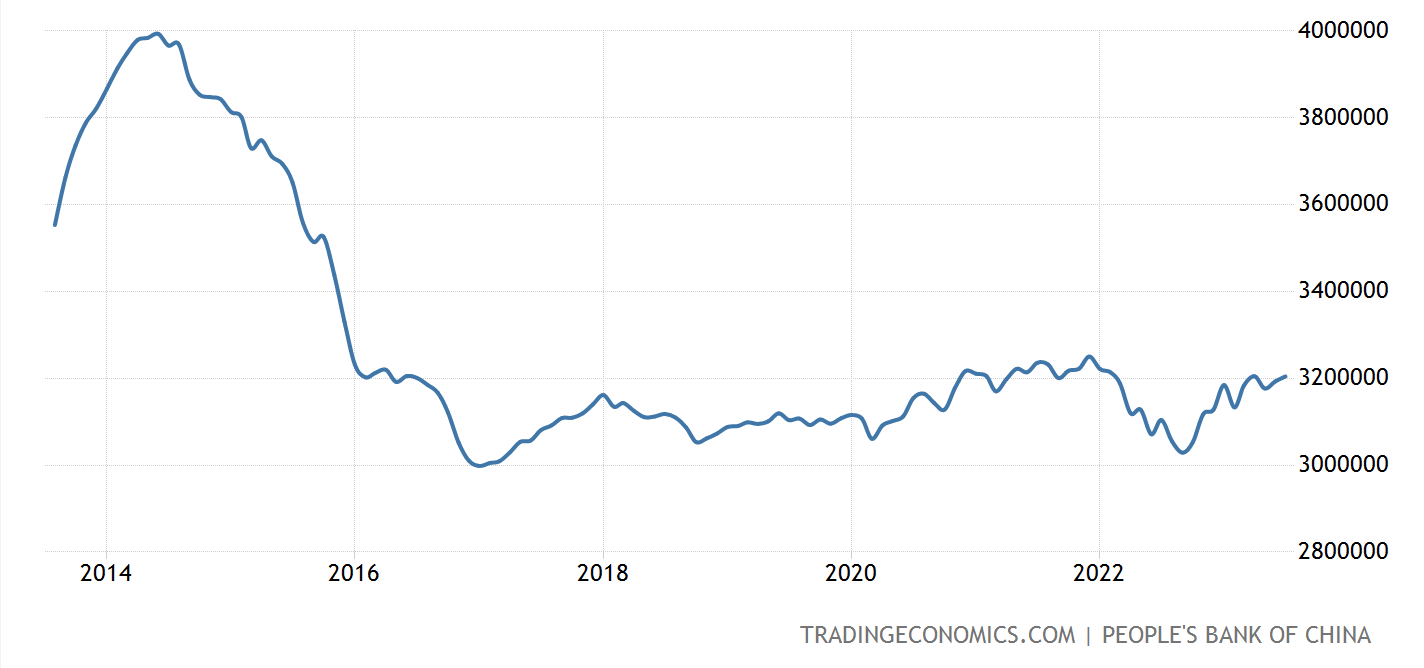
On Tuesday, August 15th, Eastern Time, the U.S. Treasury Department released the International Capital Flows Report (TIC), which showed that by June this year, China’s U.S. debt holdings had declined for the third consecutive month, with U.S. debt holdings in that month decreasing by $11.3 billion month-on-month. Total holdings fell to US$835.4 billion, the lowest since June 2009.
China’s U.S. Treasury holdings have been below $1 trillion since April last year. As of February this year, China has reduced its holdings of U.S. Treasuries for seven consecutive months, and its total holdings have hit a new low in more than 12 years for seven consecutive months. After increasing its holdings in March and April, in May it hit a new low since May 2010. .
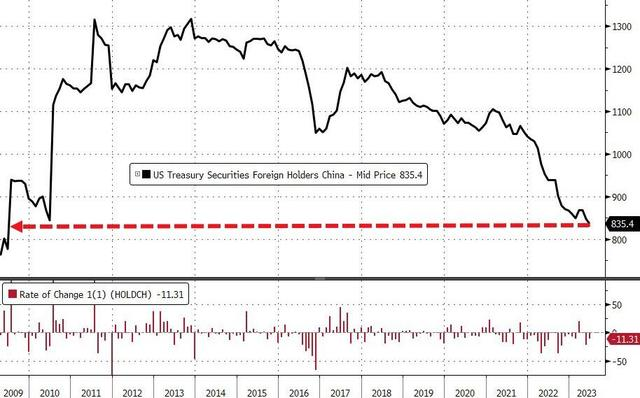
However, China’s foreign exchange reserves rose to US$3.193 trillion at the end of June, and are generally on the rise this year:
[Google’s “humanity’s most powerful model” Gemini is first revealed and may be released in the fall]
The media broke the news that Gemini, Google’s “new big killer”, combines the capabilities of the three major models of GPT-4, Midjourney, and Stable Diffusion. It can also provide analysis charts, create graphics with text descriptions, and control software using text or voice commands.
[Bridgewater flagship fund was short on U.S. stocks and U.S. bonds in late July]
Bridgewater released a report to investors stating that in late July, Bridgewater’s flagship fund Pure Alpha was “moderately” short on U.S. stocks and U.S. bonds. Among the 28 assets analyzed by the fund, 15 held a bearish stance, including the U.S. dollar, Metals and global stocks. The two most bullish positions are the Singapore dollar and the euro. The latest 13 F report shows that Bridgewater increased its holdings in Pinduoduo and China ETFs in the second quarter of this year, heavily invested in U.S. stocks and emerging market ETFs, and cleared Netflix and gold ETFs.
market sentiment
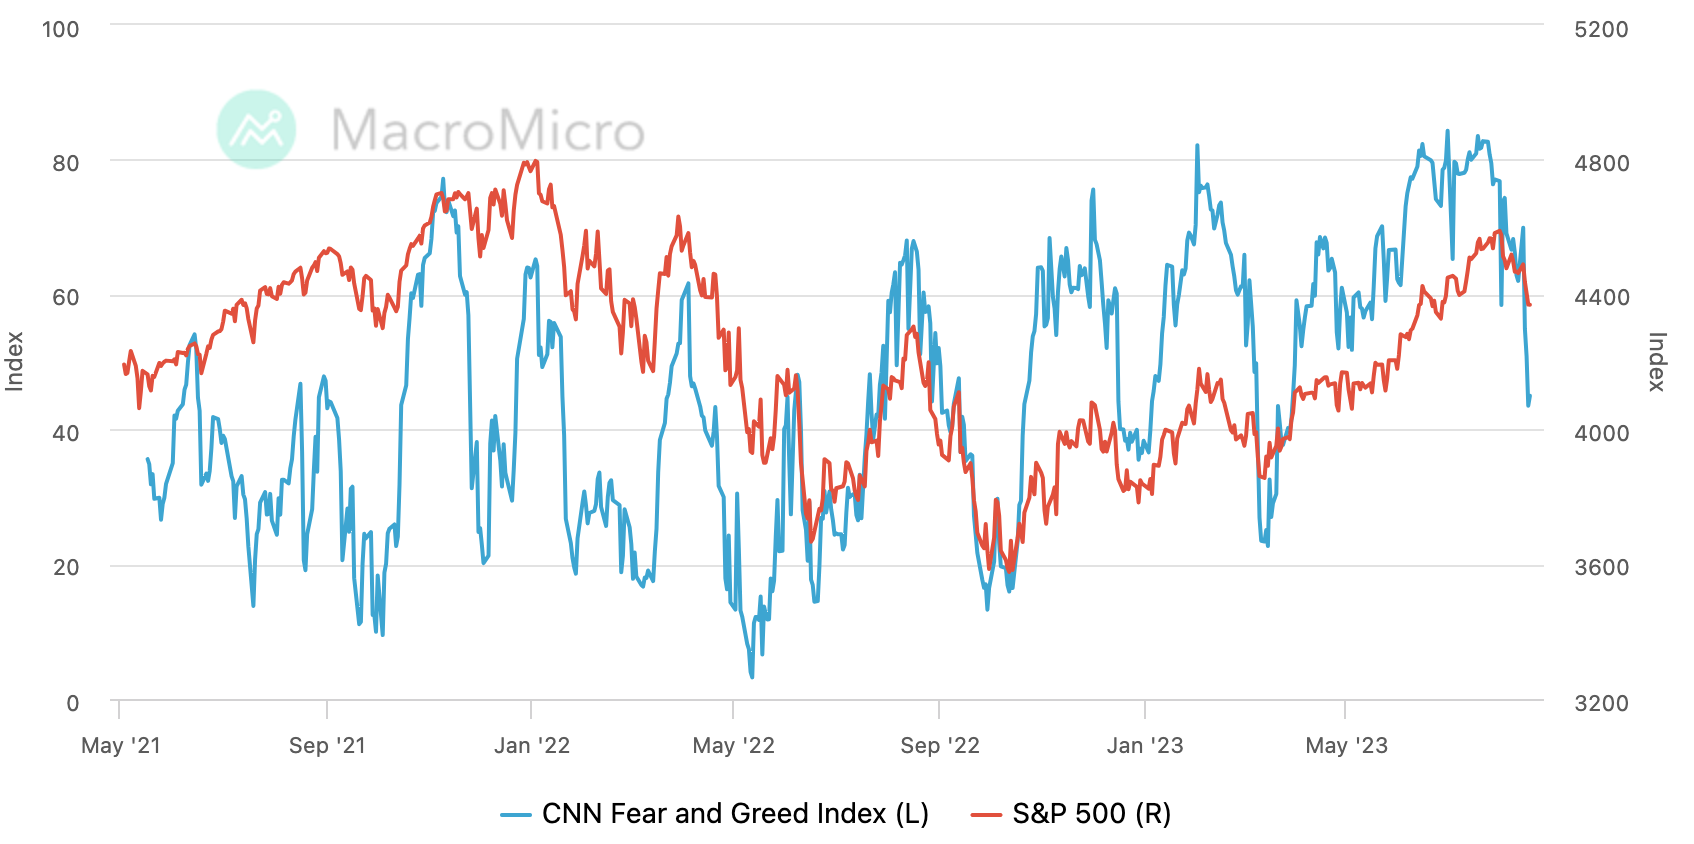
There was a lot of pessimism in the market earlier this year, and the shift from pessimism to optimism was the fuel for the stock market rally. We saw it go from overly pessimistic to overly optimistic very quickly, and now were starting to see that reverse.
The CNN Fear and Greed Index has retreated sharply to late-March levels, with a current reading of 45 in neutral territory:
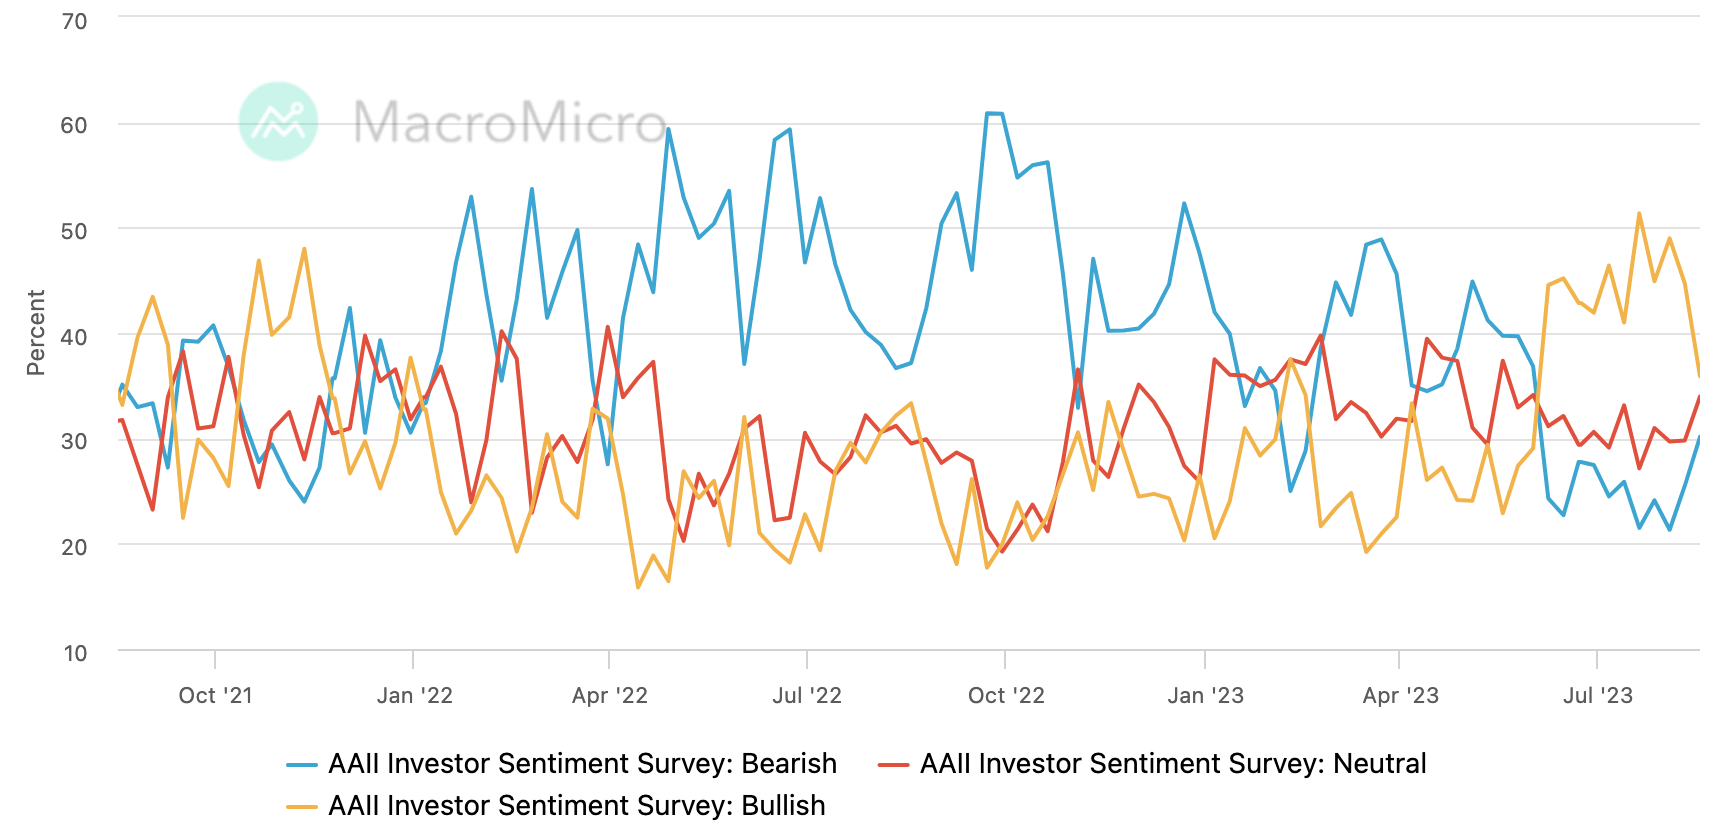
In the AAII investor survey, the bullish proportion fell sharply from 44.7% to 35.9%, while the shortish proportion rebounded for two consecutive weeks and is currently 30.1%:
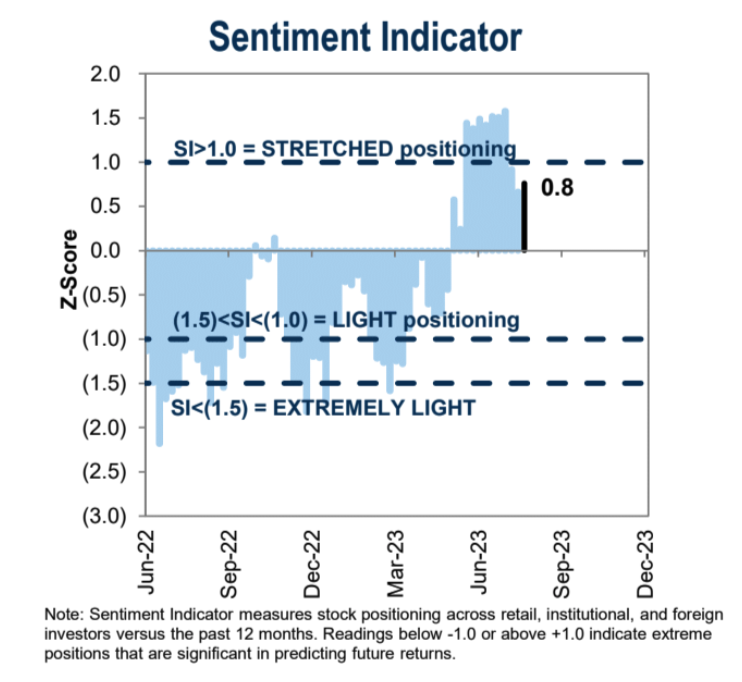
Goldman Sachs’ institutional position sentiment indicator rebounded from the previous week (0.7 – 0.8):
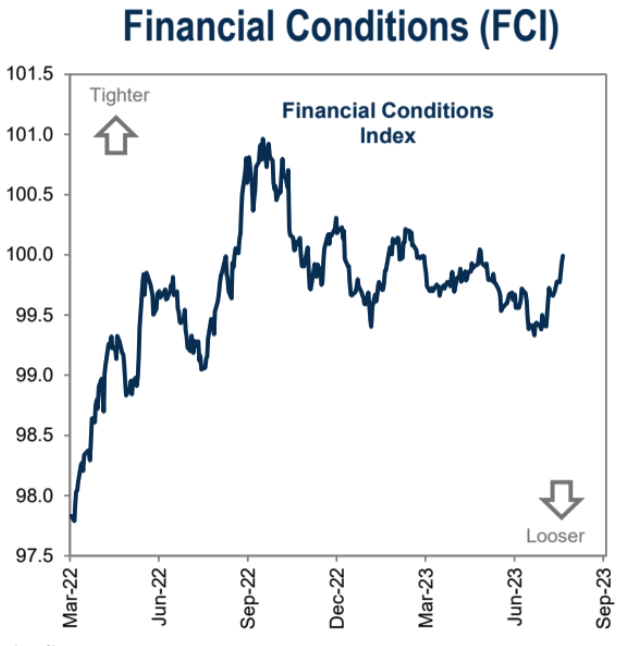
Financial tensions surge to highest levels since March:
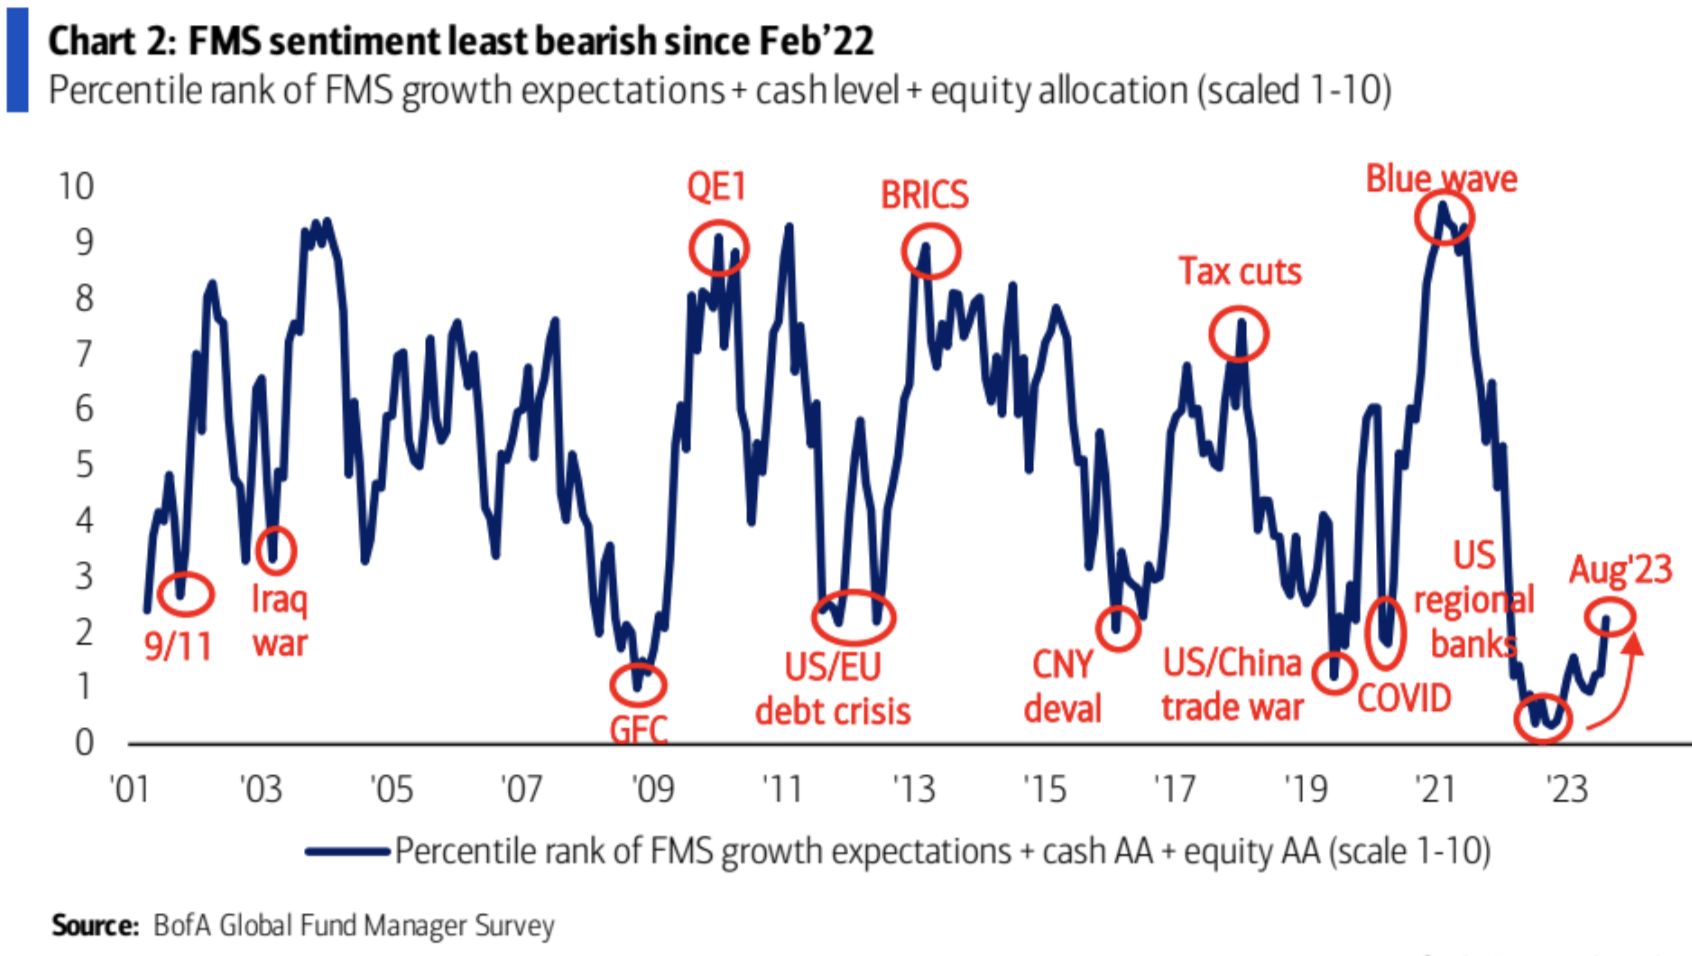
Bank of America survey: Investor pessimism is the lowest since February last year. Investors still expect global growth to weaken over the next 12 months, but believe central banks can achieve a soft landing in the interim.
Investors are now at the least underweighted stocks in 16 months and the most overweighted tech stocks in more than two and a half years:
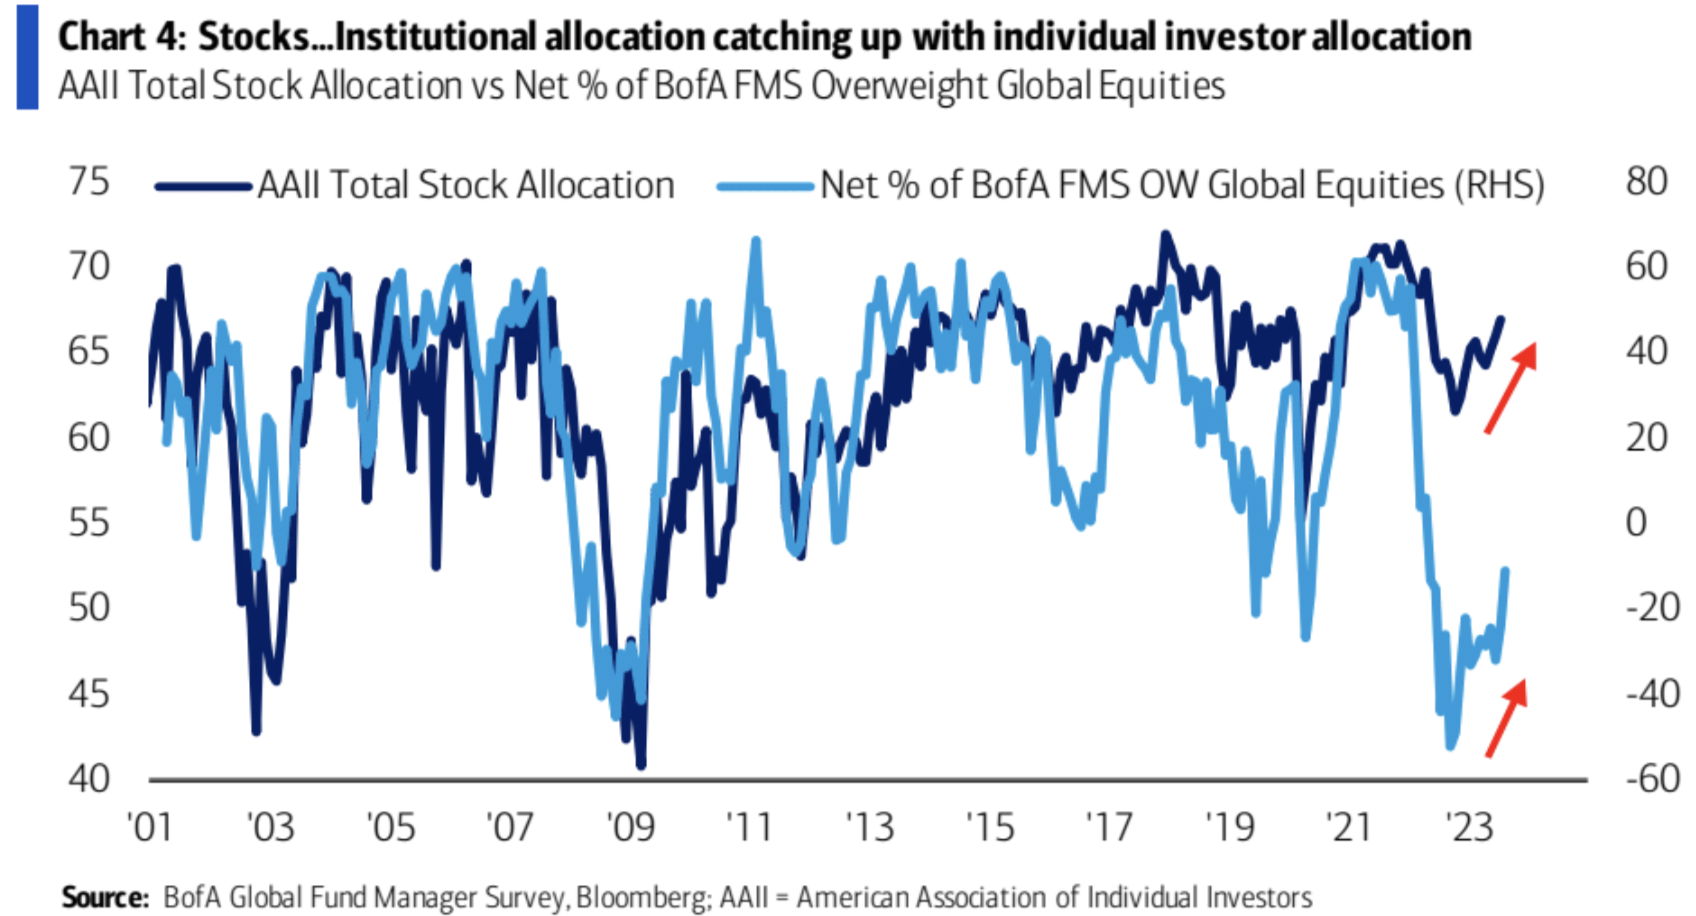
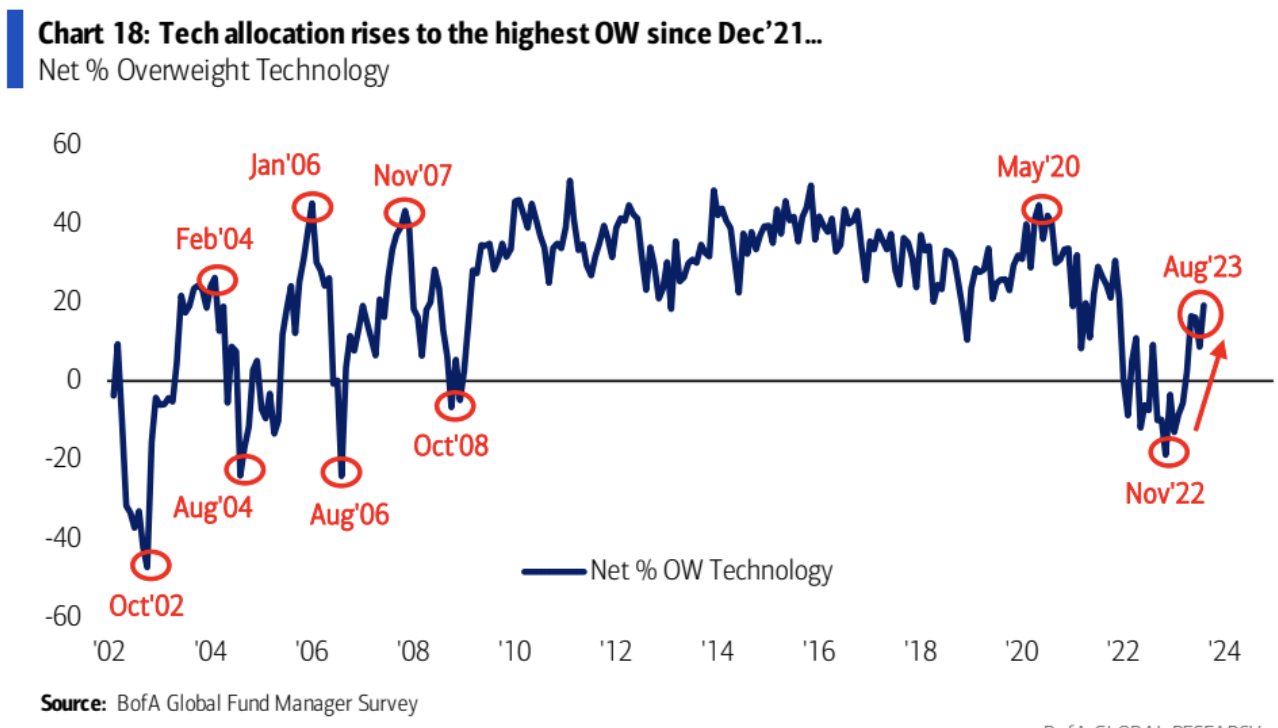
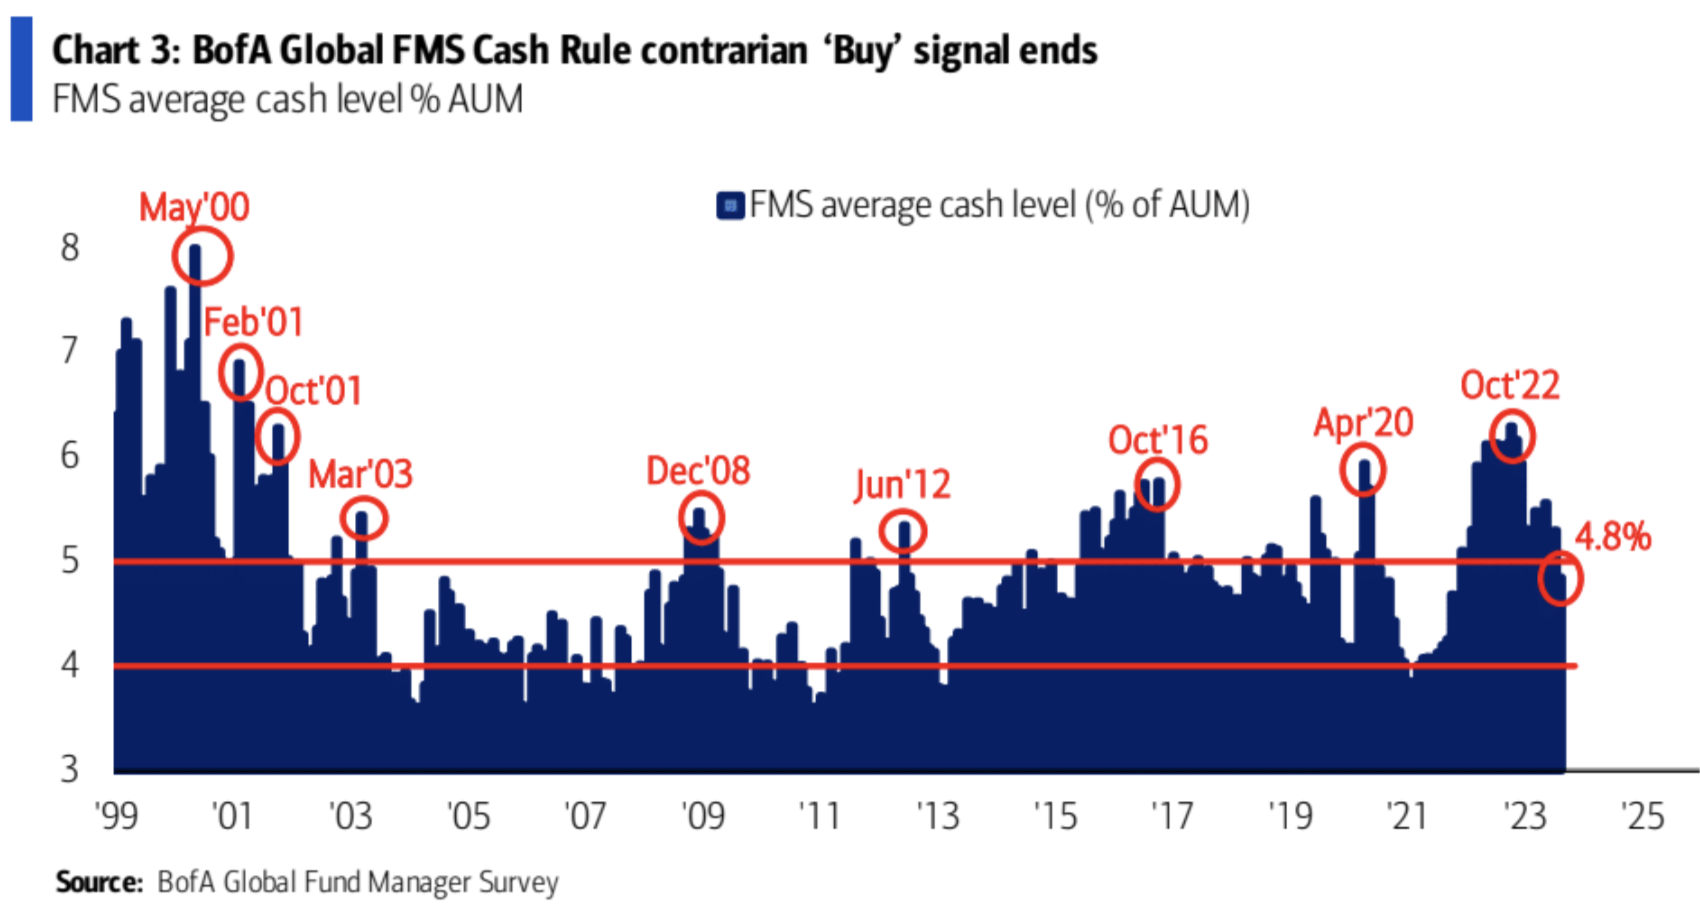
The cash allocation ratio dropped to 4.8% from 5.3% in the previous month, the lowest level since November 2021:
Funds and positions
Overall position
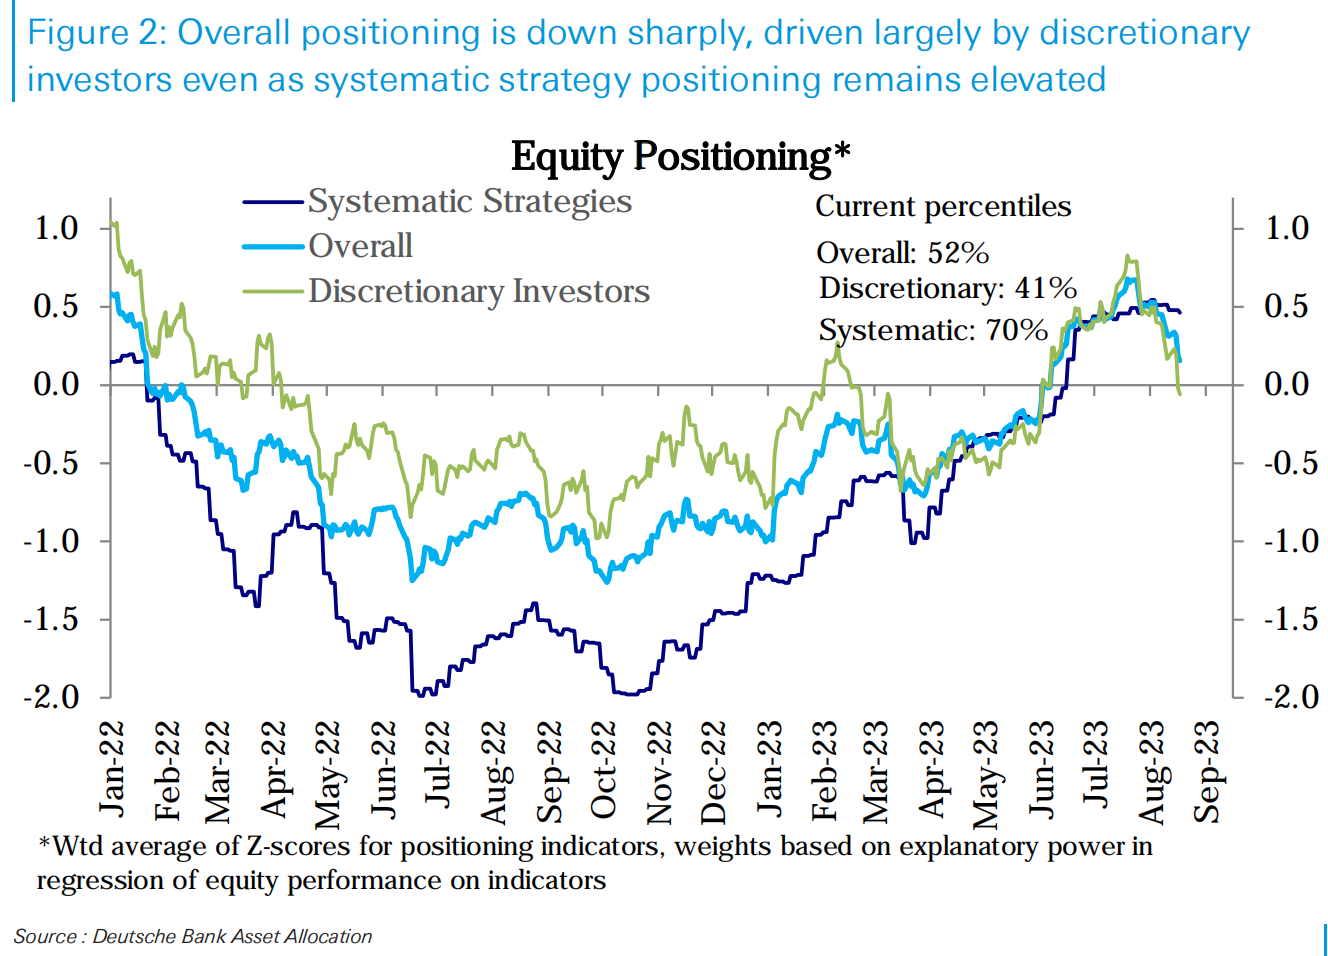
The level of U.S. stock positioning aggregated by Deutsche Bank has fallen for the fourth week in a row to a two-month low (the 52nd percentile of history). Most of the decline is driven by subjective strategies, and the position level of this part has slipped to slightly below neutral (41st percentile); the positions of systematic strategy funds have not changed much in the past week, and the overall position remains at the same level as at the end of 2021. Highest level (historical 70th percentile).
Industry positions
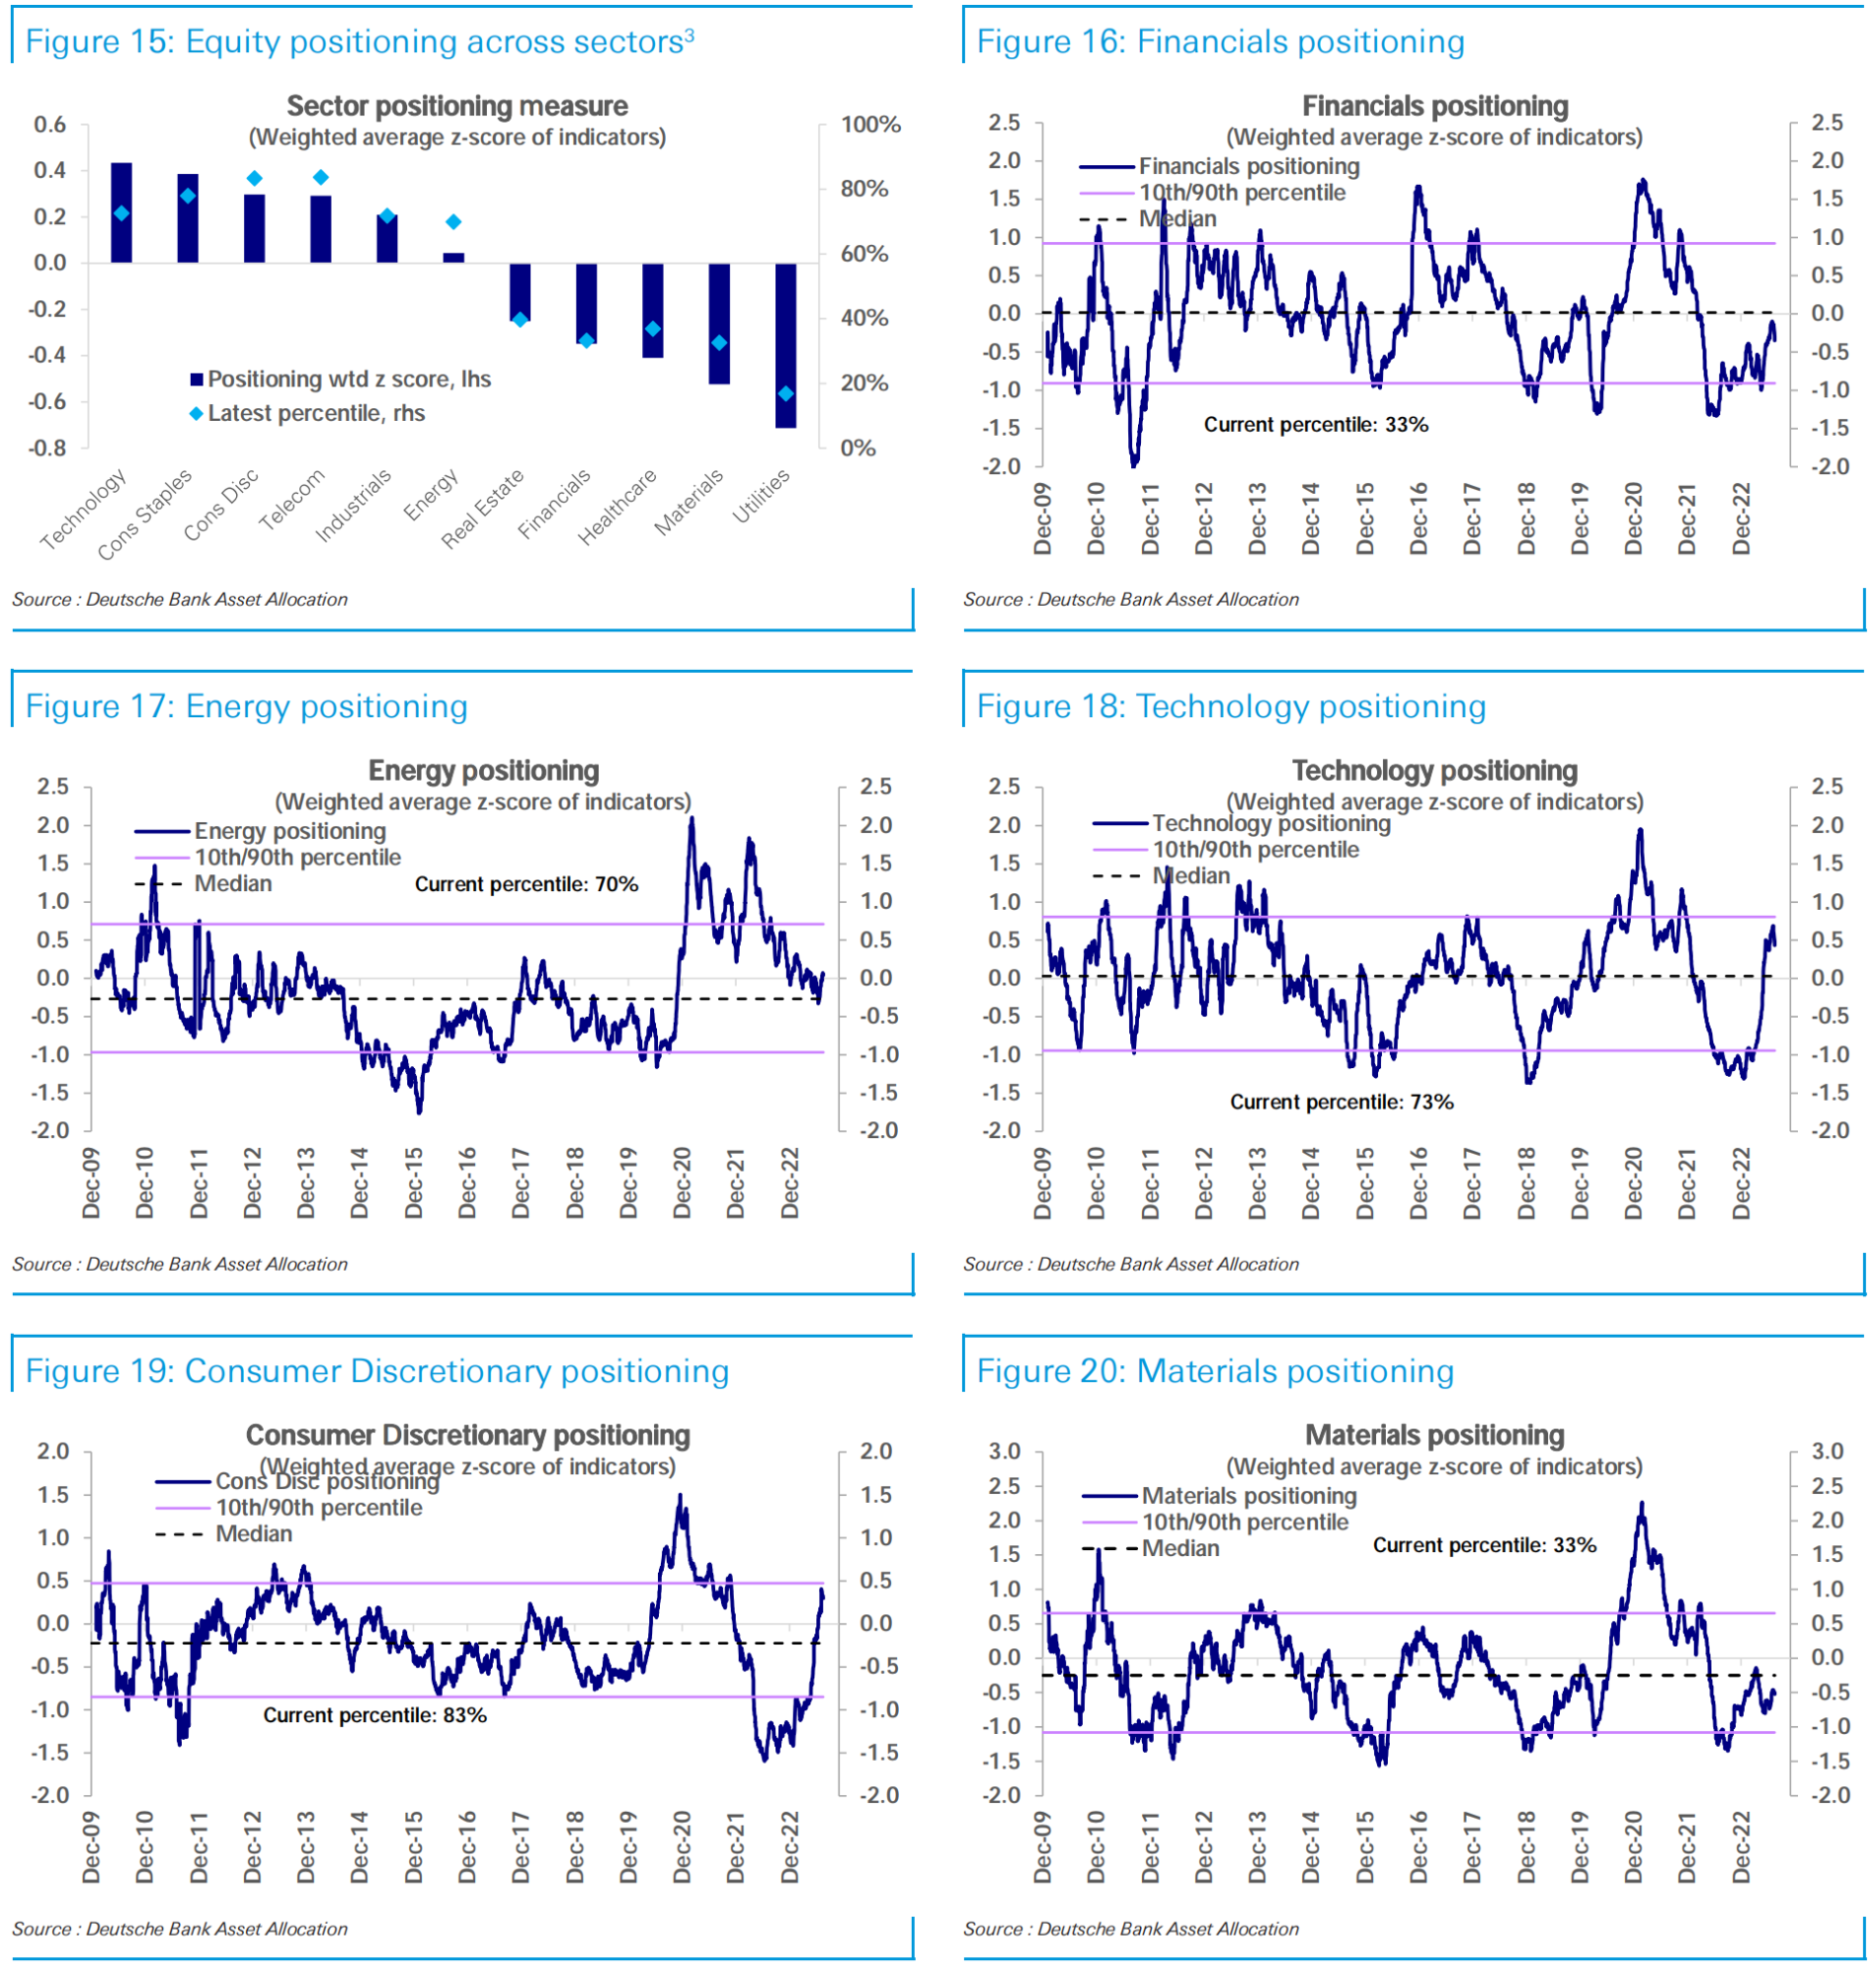
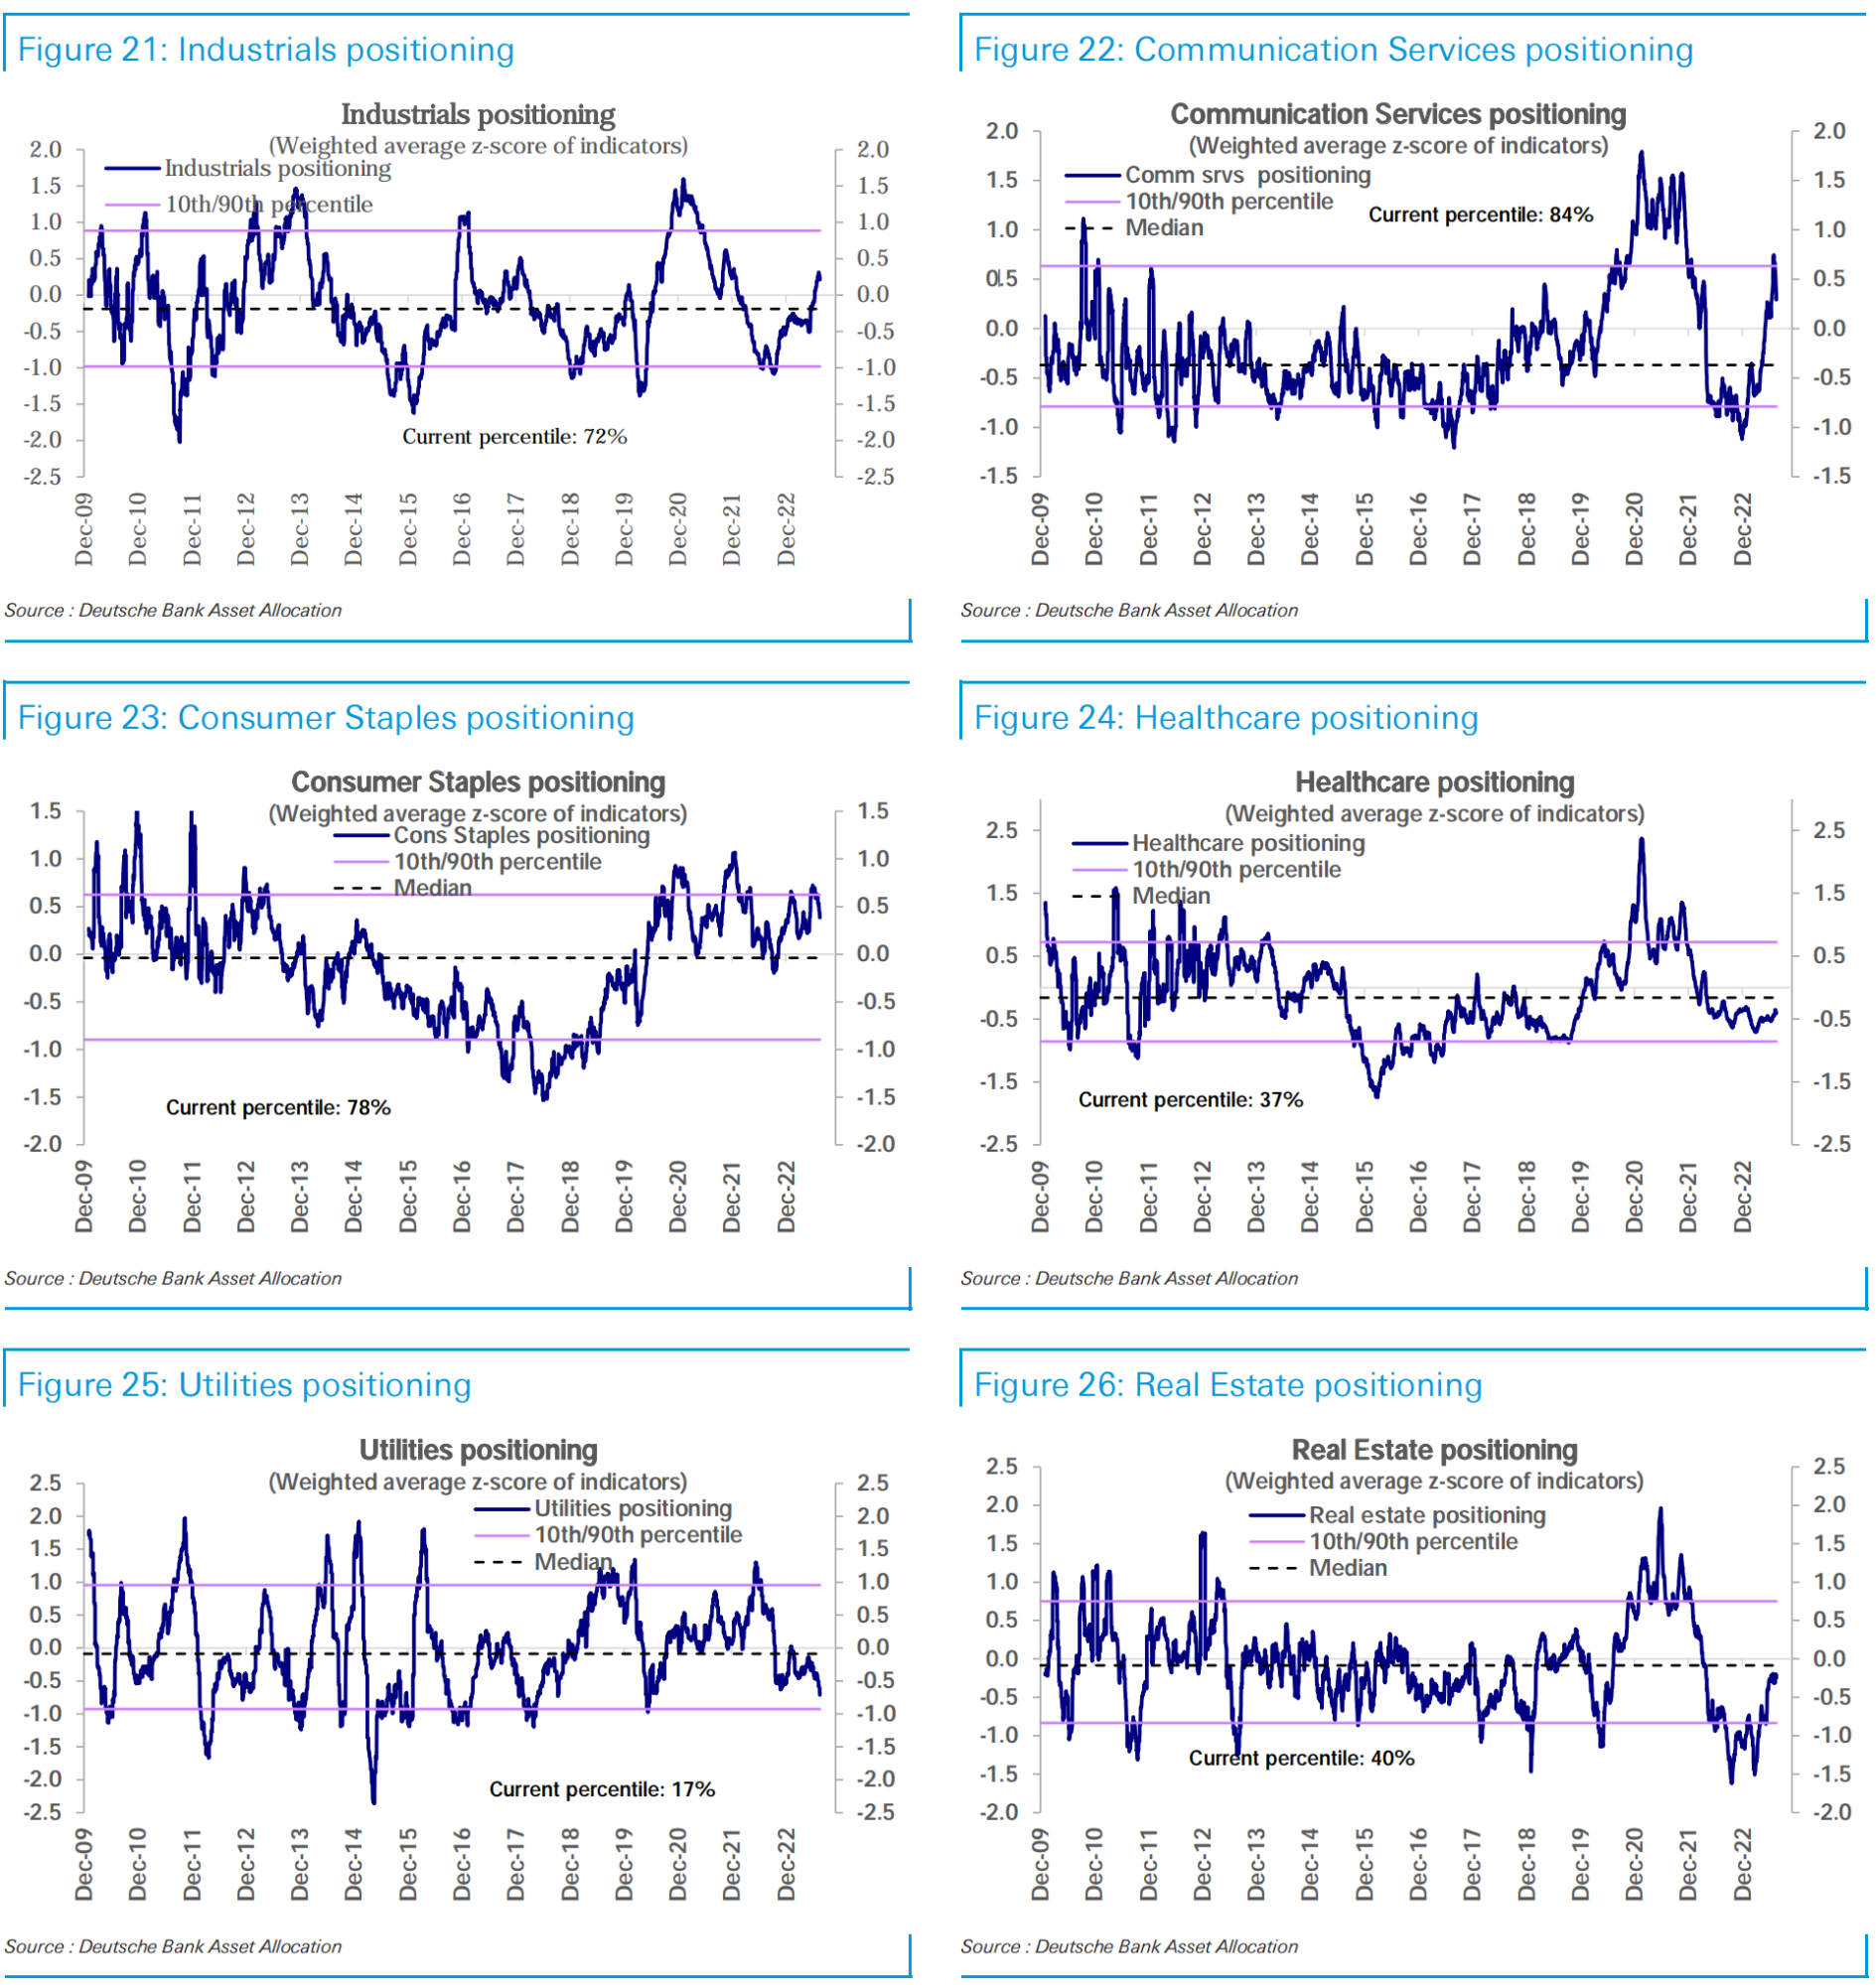
Positions in Technology (73rd percentile), Consumer Staples (78th percentile), Consumer Discretionary (83rd percentile), and Communication Services (84th percentile) remain oversubscribed, but have improved this week decline.
Holdings in Industrials (72nd percentile) also fell and remain moderately overweight, as did Energy (70th percentile).
Real estate (40th percentile) was moderately underweight and largely flat, and financials (33rd percentile) were also underweight and fell this week.
Healthcare (37th percentile) and Materials (33rd percentile) are underweight and essentially flat, while Utilities (17th percentile) are underweight and in a downtrend.
Fund flow
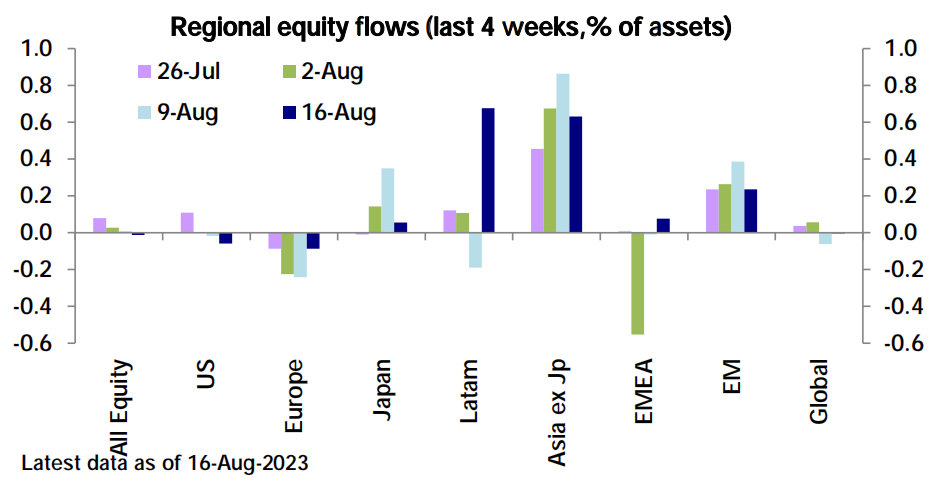
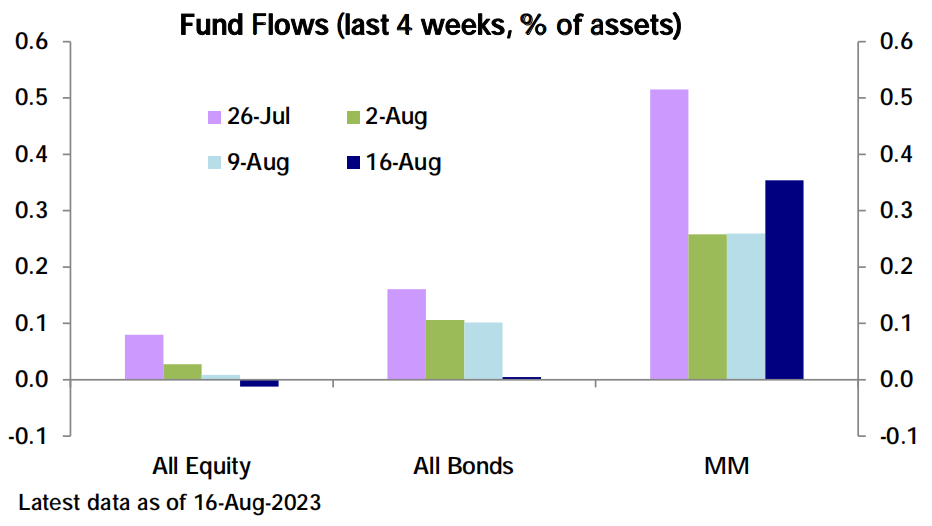
Global equity funds had a net outflow of US$2.1 billion, mainly driven by a net outflow of US$5.2 billion from the United States. The European market had a 23rd consecutive week of net outflows (-1.3 billion), while emerging markets (US$3.7 billion inflow) received net inflows for a sixth consecutive week, mainly Inflows into Chinese funds were slower than last week; currency fund inflows accelerated, reaching $21.8 billion, the fifth consecutive week of inflows; bond fund net inflows slowed sharply to a five-month low (+$30 million).
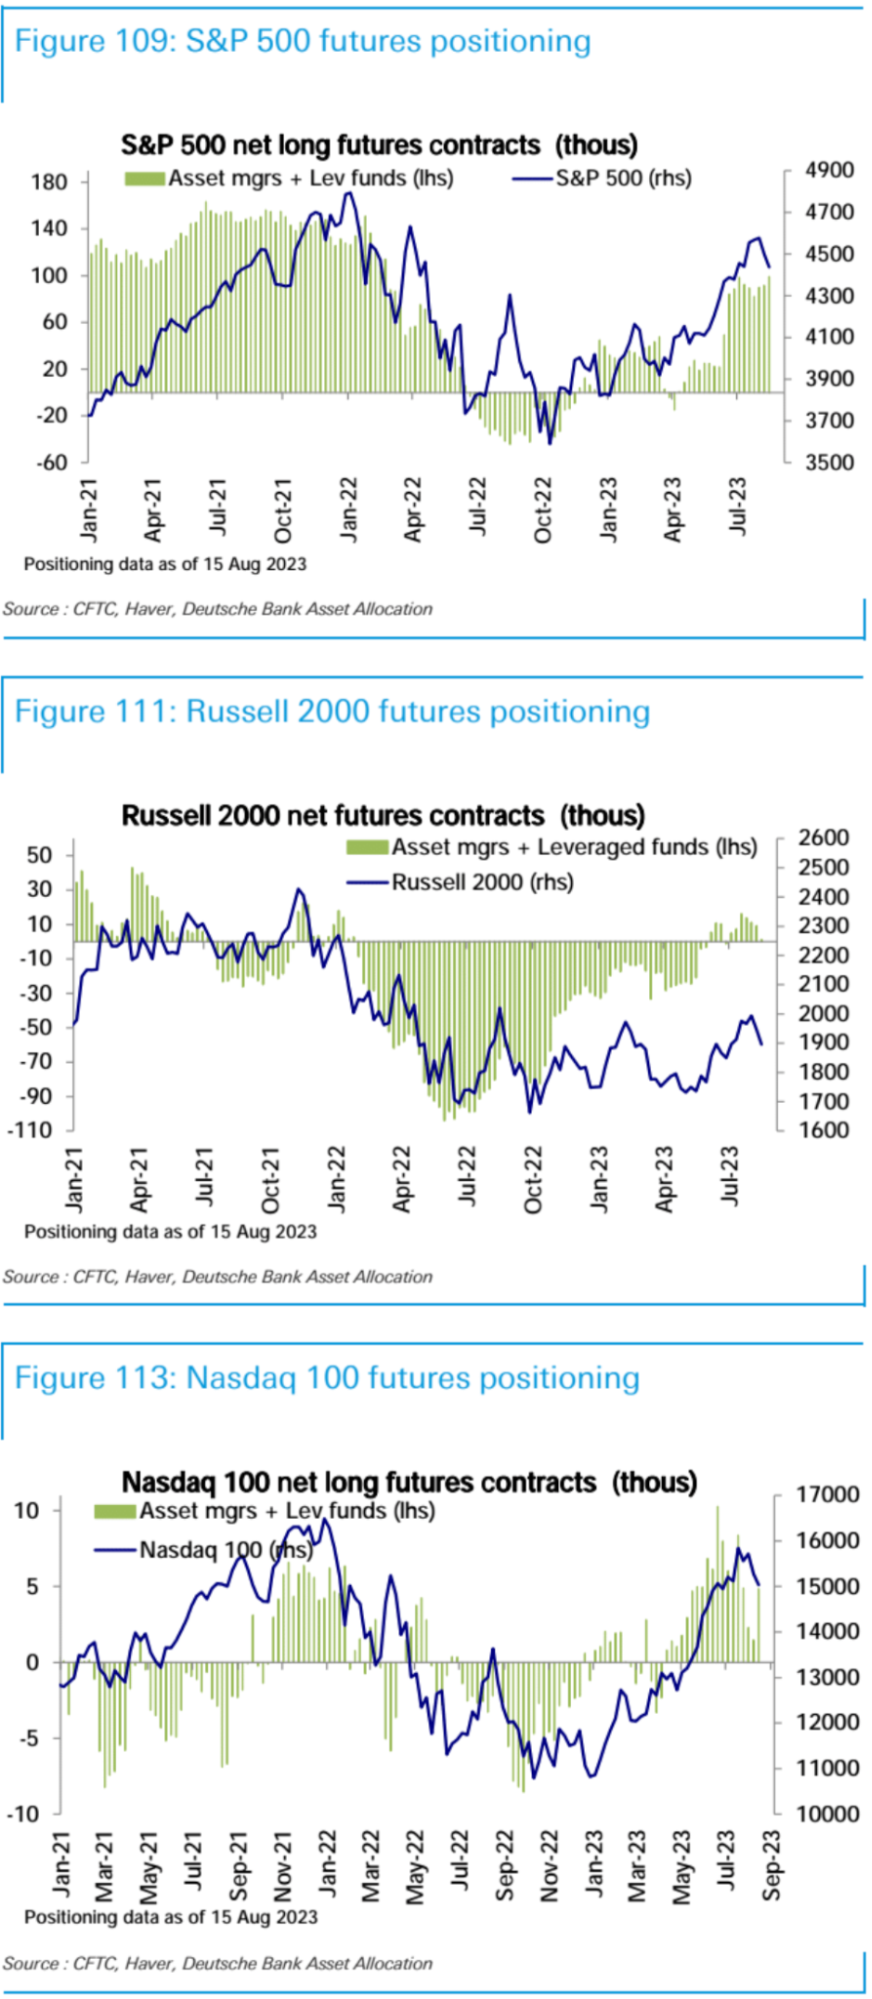
Futures Data: Despite the pullback in the physical market, U.S. stock futures net longs rose for a third consecutive week as of last Tuesday, led by increases in net longs in the SP 500 and Nasdaq 100 and decreases in net longs in the Russell 2000, very close to neutral.
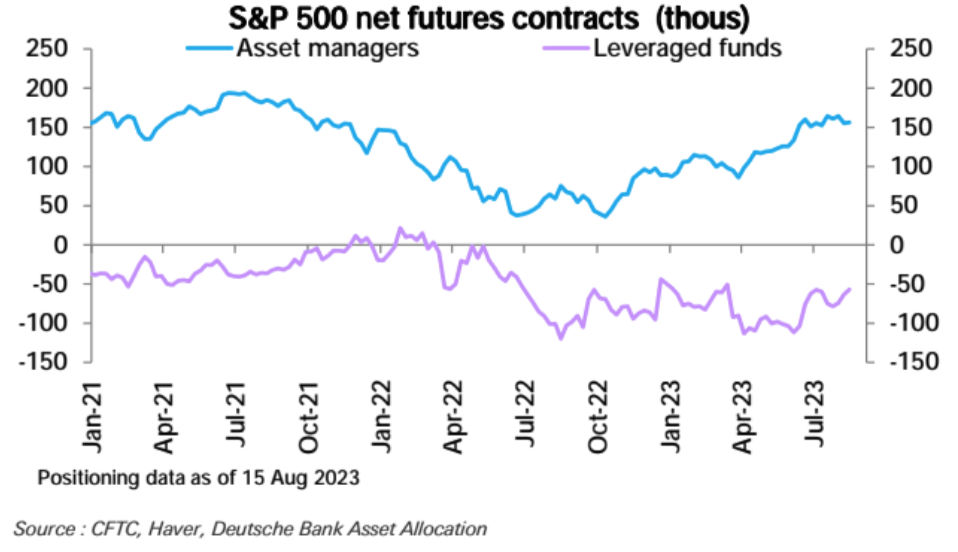
It is particularly worth noting that the increase in net longs last week was mainly driven by more responsive but leveraged funds:
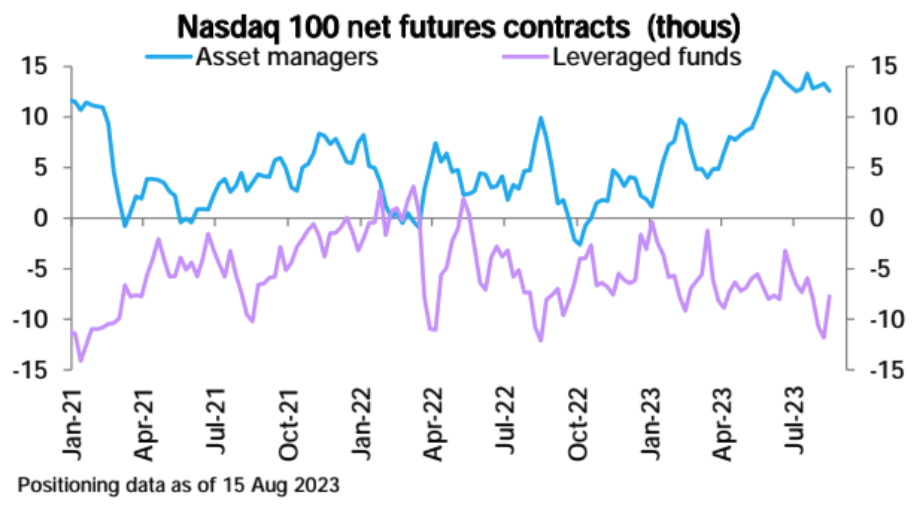
In other futures markets, the net short position in bonds fell for the second consecutive week, mainly due to a decrease in the net short position in the 5-year and 30-year bonds, and an increase in the net short position in the 2-year and 10-year bonds. In the foreign exchange market, the net short position of the US dollar increased, mainly due to the increase in the net long position of the euro and the British pound, and the decrease of the net short position of the Swiss franc and the yen. CAD net shorts increased, as did AUD net shorts. Among commodities, crude oil net longs fell slightly. Silver and gold net shorts increased, cutting gold net longs for the fourth week in a row, while copper net shorts also increased.
Goldman Sachs PrimeBook Data
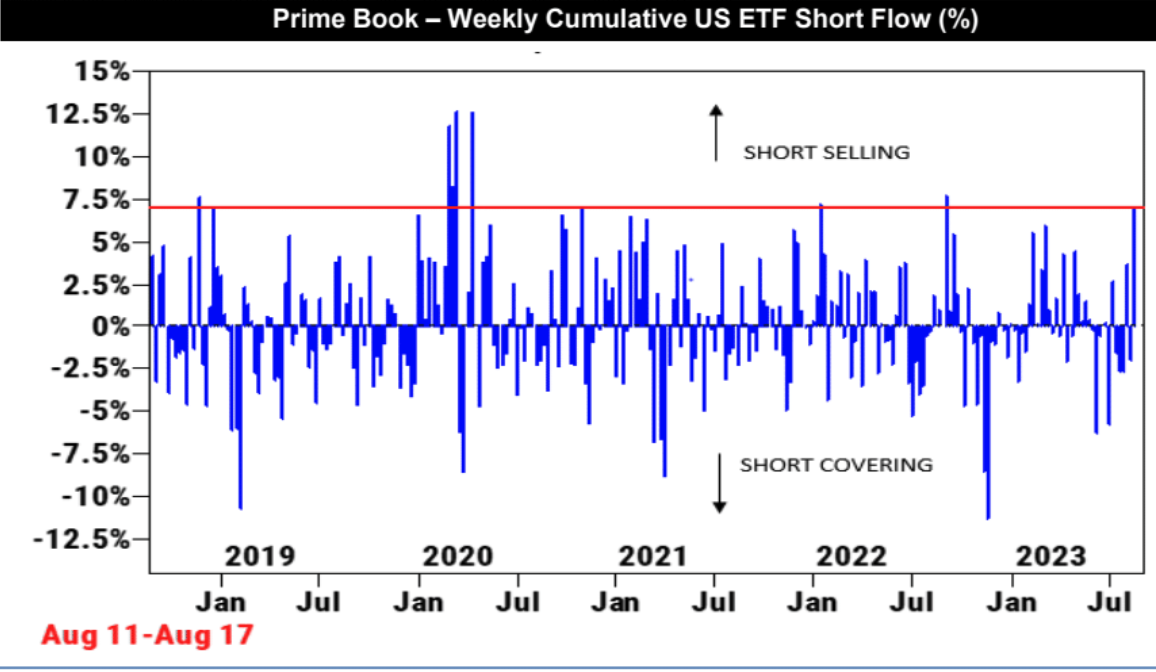
Amid the market decline, hedge funds shorted U.S. ETFs last week at the fastest pace since September 2022, adding more than 7% of market capitalization in a single week. But this may not necessarily be a bearish sign, as they have observed increased trading activity in U.S. stocks over the past few trading days, with investment managers increasing exposure to individual stocks while also increasing beta hedges, while ETFs generally represent the broader market or sector but beta.
Crypto market stablecoin flows
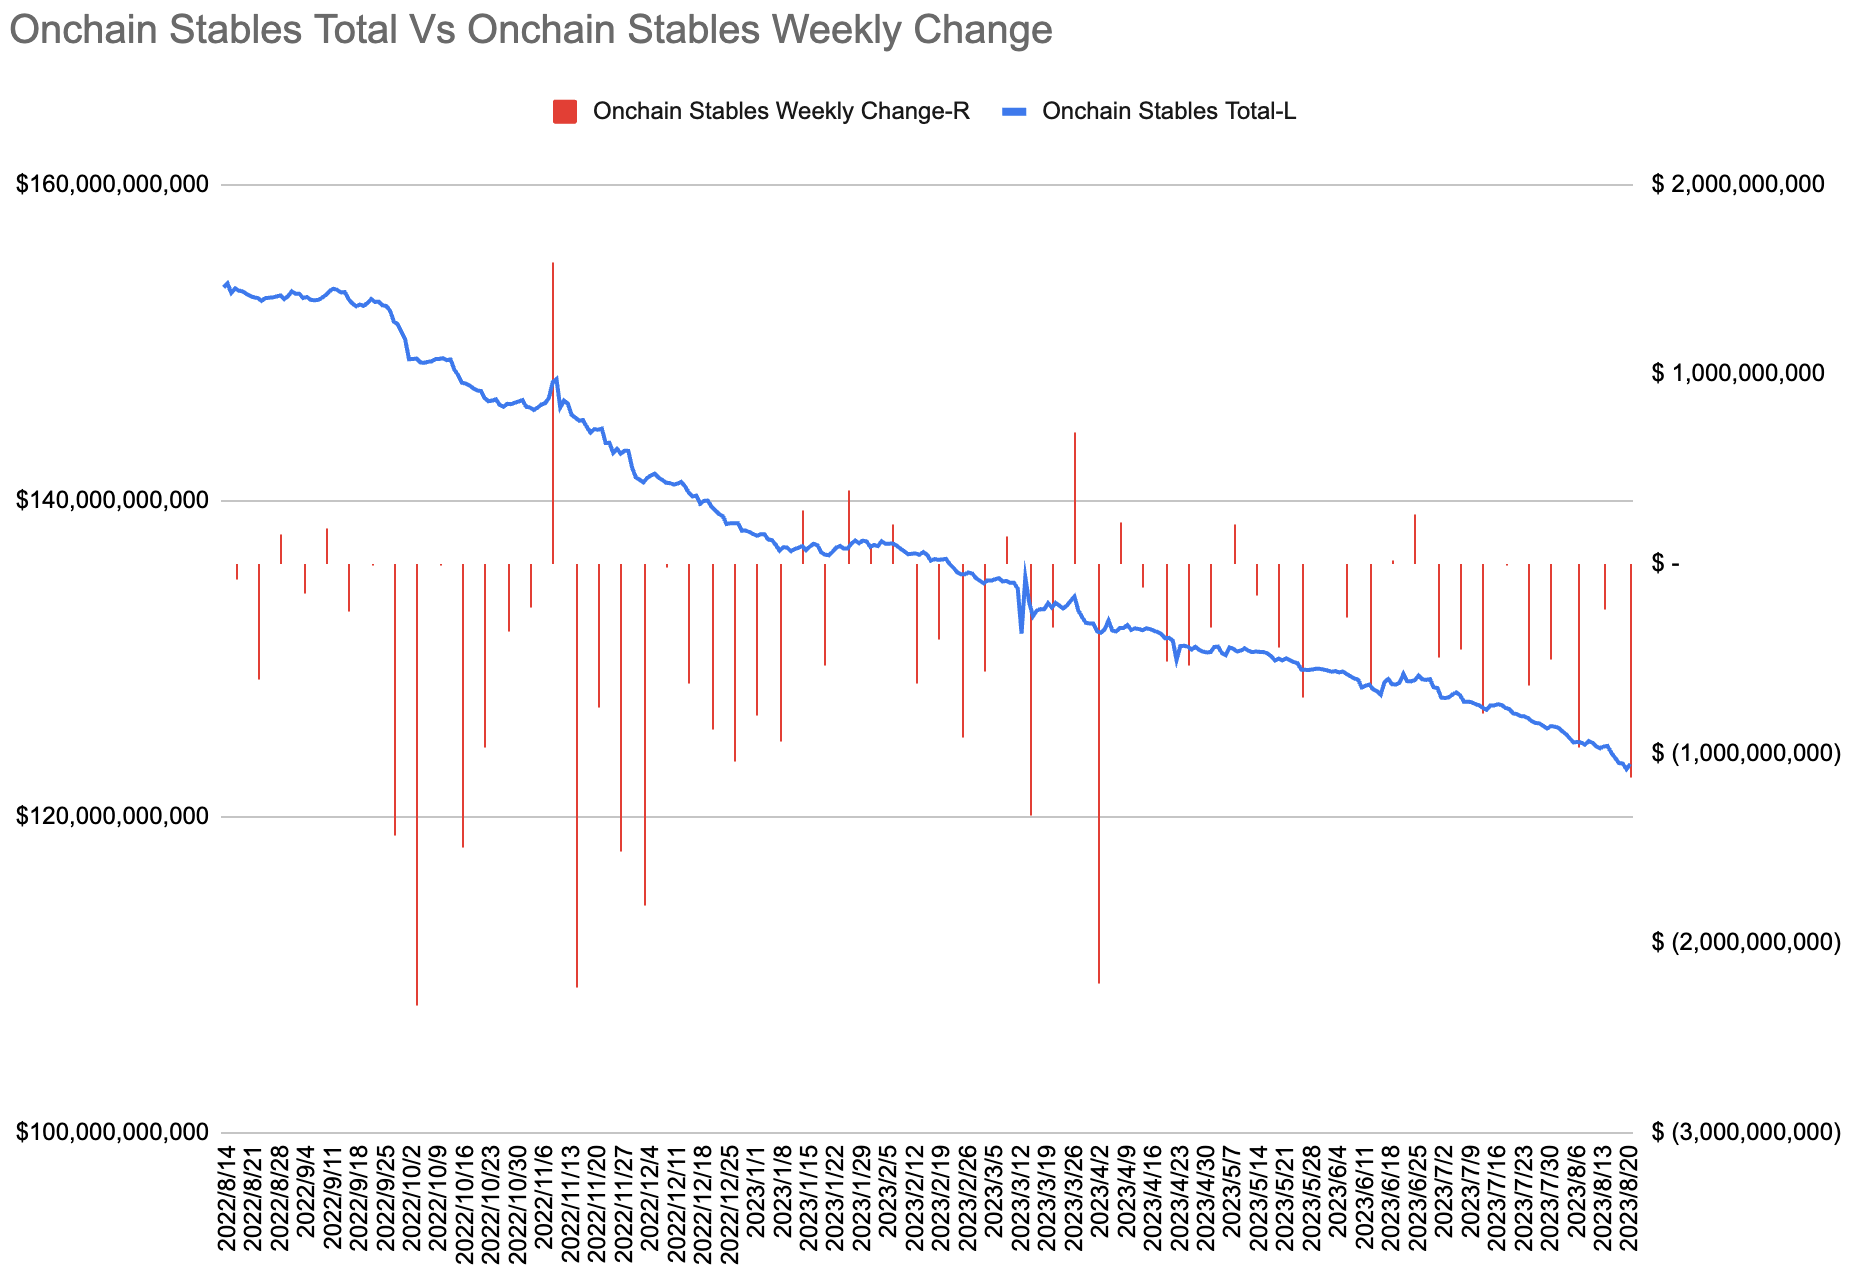
On-chain stablecoins saw net outflows for the ninth consecutive week, with a massive outflow of $1.13 billion last week, the largest weekly outflow since the week of April 2 this year:
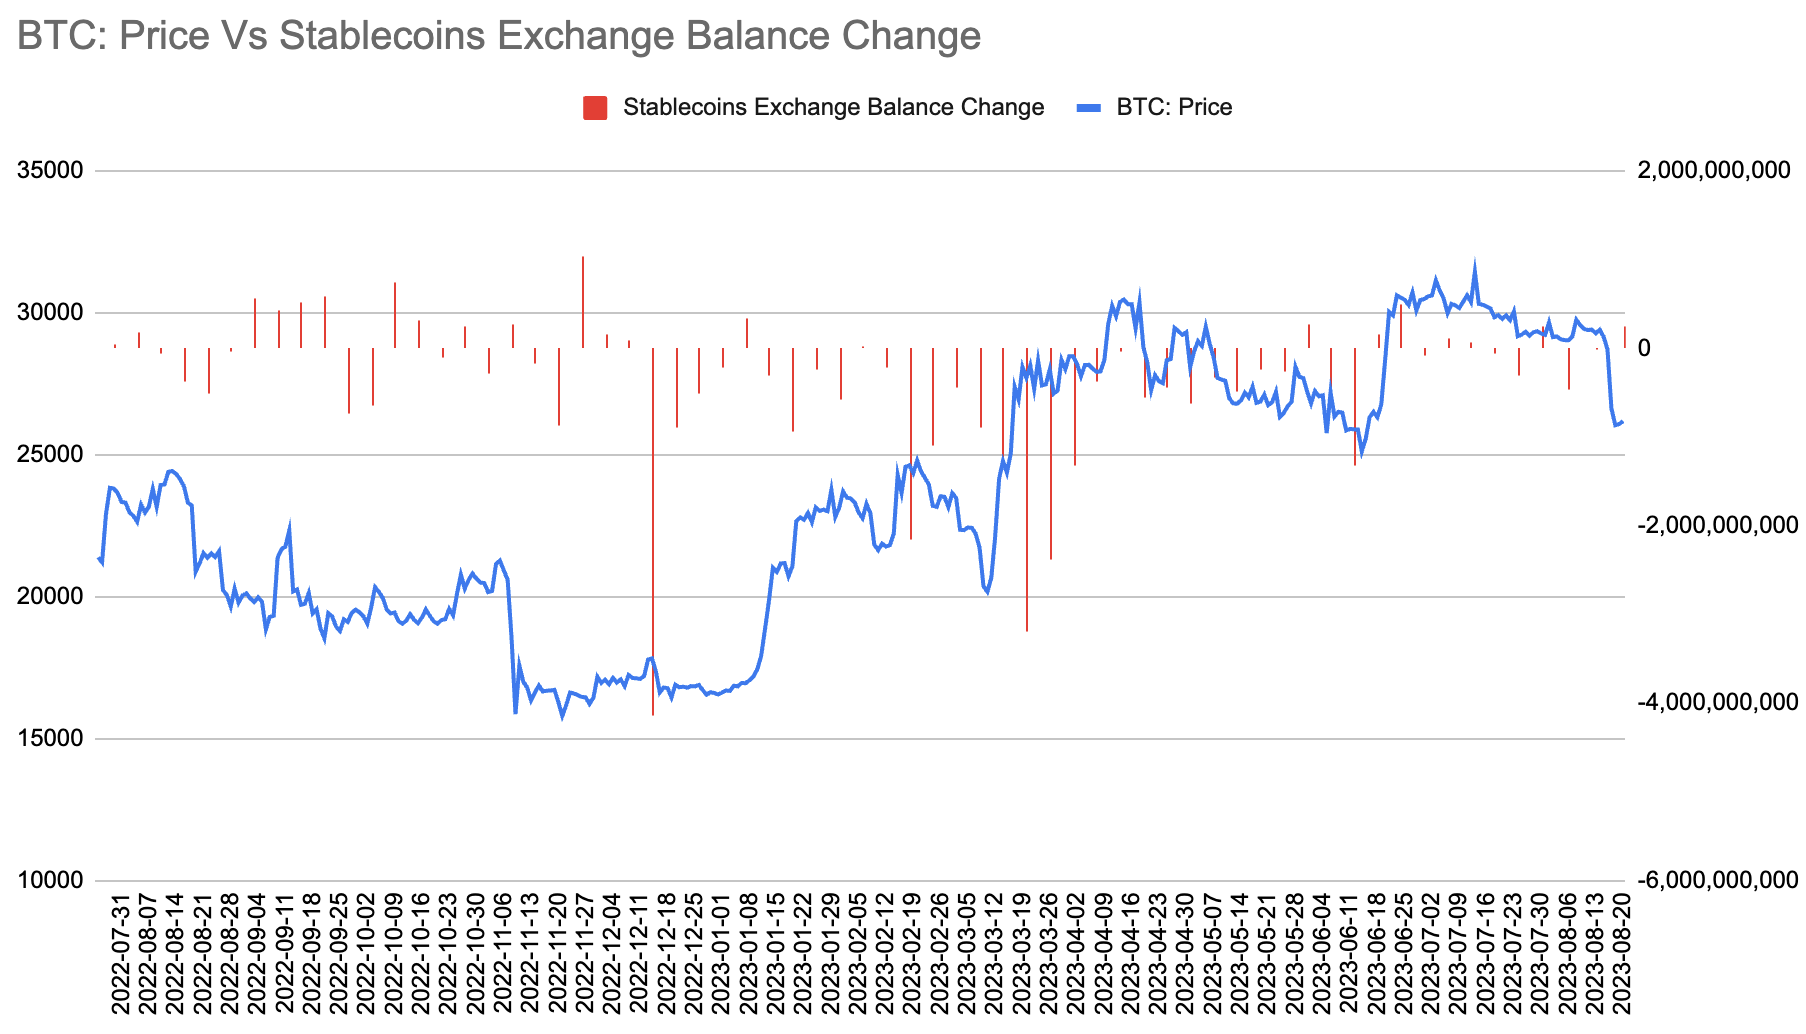
However, the balance of stablecoins on the exchange increased after two weeks, with a net increase of 240 million US dollars:
follow this week
The main catalysts for the market this week are Powells speech at the Jackson Hole Economic Symposium on Friday and Nvidias (NVDA) second-quarter report on Wednesday.
Jackson Hole Symposium Preview
It will be held August 24-26. This years theme is Structural Changes in the Global Economy, with particular focus on the strength of the global economy and potential inflation risks. The Jackson Hole symposium could be a defining moment as markets will be closely watching to see if the Fed signals expectations for a higher neutral rate, as this could be interpreted by markets as a hawkish stance suggesting higher rates to slow the economy.
Highlights of the FED Chairman’s speech:
Powell is expected to rely heavily on recent data, including the latest CPI and core private consumption expenditures (PCE) inflation reports.
He is expected to highlight some progress in the fight against inflation but stick to his recent comments about the need for vigilance. He is likely to be relatively optimistic about the state of the economy and will continue to emphasize completing his price stabilization work, including achieving below-trend growth.
UBS thinks Powell may remain hawkish enough to open the door to more rate hikes, but is confident he wont put a rate increase on the table in September.
Bank of America said Powell would likely reiterate the Feds commitment to its 2% inflation target and push back against the markets pricing in the extent of rate hikes next year. The bank said it did not expect to see any major shifts in the Feds neutral rate at this meeting, given the large uncertainty surrounding its estimate of the neutral rate.
Nvidia earnings preview
Nvidia (NVDA) will report its second-quarter report after the U.S. close on Wednesday, in what will be the biggest test yet of the artificial intelligence hype cycle. It will show whether the AI boom that has swept the market over the past 8 months is actually delivering economic value. Because even though Google and Microsoft posted positive earnings growth last quarter, they didnt attribute the growth to AI, they attributed it to increased earnings from their existing businesses. Revenue at Microsofts AI-powered New Bing division also fell 4% last quarter.
Indicators that NVDA needs to pay attention to include the following:
Revenue: Analysts expect revenue of $11.1 billion, up from $6.7 billion a year earlier, implying a 65% year-over-year increase in sales.
Gross profit margin: It declined last year and started to recover to 66.8% in the first quarter.
Data center revenue: Always growing. Continued growth would quantify Nvidias momentum in AI.
Game revenue: A sharp drop in the second quarter of last year, and the downward trend will continue until the end of fiscal 2023.
Earnings per share: Second quarter EPS is expected to be $2.07, up 305% from $0.51 EPS in the same period last year.
Nvidias current price-to-earnings ratio is: 146 times TTM price-earnings ratio, 222 times GAAP price-earnings ratio, 43 times price-to-sales ratio and 45 times price-to-book ratio. Thats a very steep valuation. Of course, Nvidias projected growth is also very high, and if the company lives up to expectations, growing at a compound annual growth rate of several hundred percent in just a few years, it could really quickly outpace its extreme valuation.
Market comments
Wall Street warns that 5% U.S. bond yields may become the new normal, and inflation may cause the Fed to raise interest rates to 6%
Bank of America warned investors to prepare for a return to 5% U.S. Treasury yields, a return to pre-financial crisis U.S. bond markets. With PCE inflation averaging 3.7% in the second quarter, the Fed may be forced to tighten its policy benchmark to at least 6%. At the same time, the inversion in yields shows that in the short term, the risk of a U.S. recession still exists.
JPMorgan Chase warns that the U.S. economy may lose a big boost and consumers excess savings will be exhausted
JPMorgan Chase estimates that U.S. consumers’ accumulated excess savings peaked at US$2.1 trillion in August 2021 and were -US$91 billion in June this year; the household liquidity surplus supported by cash and cash-like assets is currently about 1.4 trillion US dollars. The U.S. dollar will be exhausted next May, and liquidity may not be able to support current above-trend consumption.