






SignalPlus: Analyzing combination strategies for options sellers in low IV market conditions.


Original Author: Li Kun Sober
Most mosaic market option players believe that when the current IV is around 30 or below (as shown in the figure below: IV vs RV, source from: signalplus), the seller can no longer continue to duck, and at this time long Gamma or long Vega should be on the scene !
But is this actually the case? I dont think so, let me tell you in detail.
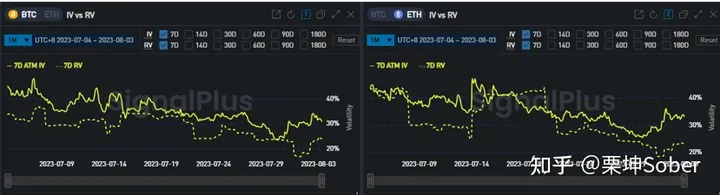
Comparison of mosaic market IV and RV in the past 1 month
1. Whether IV is low or high depends on what is the reference?
We usually do transactions, what is the value of the transaction? Yes, the transaction is price, that is, relative value, and the essence of investment or transaction is also the best cost-effective choice. At this moment, it doesn’t make much sense to say that there was no risk 10 years ago (at that time, it was equivalent to risk-free and just exchanged, of course, this statement is not so rigorous academically) 15% income trust, or 5% Yu’e Bao .
The situation with relative value trading can get very complicated, especially when executing this strategy, so lets briefly describe relative value. For example: Many players use the IV of the historical pie when trying to measure the IV of todays pie, and that is indeed gone forever.
Use the past to measure today!(In the investment industry, we know that we must not confuse historical industries with cyclical industries. The same is true for option IV and pricing)
The fundamentals of things have changed (in a bit of philosophical terms: I cant step in the same river twice). Therefore, instead of using the past as a benchmark, it is better to use another underlying asset (for example: US stock chip stocks) as a benchmark. Everyone will compare in this way, but we have to have a steelyard in our hearts, so it doesnt make much sense. Just like the current Internet of A-shares, if you still use the valuation method 18 years ago to study, that is seeking a sword in a boat.
In fact, many institutions now do volatility arbitrage, and one of the ways is to compare the IV modeled by themselves with the current IV, and conduct volatility arbitrage transactions (high sell, low buy, balance delta). However, institutional models of different professional levels are very different, and there are still some private equity funds selling dog meat under false pretenses. As ordinary investors, we still need to identify them.
2. Look at the actual situation in the past six months
Looking at the data of IV and RV on Duck.com in the past 6 months, we can find through data observation that although everyone called the IV too low for half a year this year, the actual profit of sellers is higher than before, but if you do not become a seller, the same Can level players really make money as buyers? Dont look at it once or twice, but show long-term results. [Leaving you to think, open-ended questions]
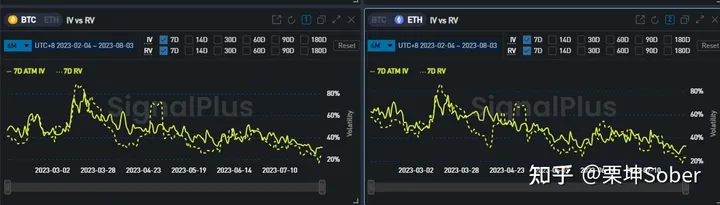
Comparison of mosaic market IV and RV in the past 6 months
In fact, in the long run, IV cannot be too far away from RV. Matching each other is the way to survive in the long run. Otherwise, the buyer will become a big victim?
Therefore, I think it is more meaningful to do some relative value analysis to price the current reasonable value of IV. As long as it is above the reasonable value level, even if it is lower, then sell it. Looking at the IV and RV trends of Dabing over the past six months, although the Gap value is small, most of the time IV has a premium. What does the seller earn from selling insurance? Thats the premium price.
In the past 1-2 months, many sellers have complained about the low IV. Doing some long gamma strategies will actually lead to even worse losses. This is what I want to say, whether it is low or not, depends on the relative pricing of IV and the competence circle of individual option strategies.
3. What are the typical strategies
Recently, after thinking and actual combat, I feel that the anti-calendar strategy will be a very cost-effective strategy. From the figure below, we can see that the IV of the pancake at the end of August is still relatively low, and there is a clear upturn in September, which can also be clearly observed in the surface graph. .
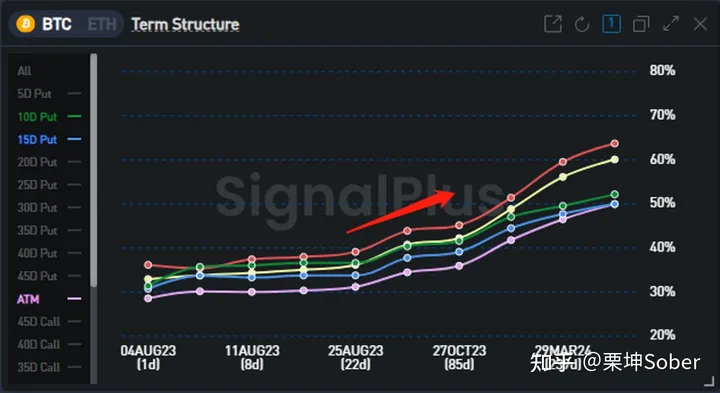
Pie Term structure
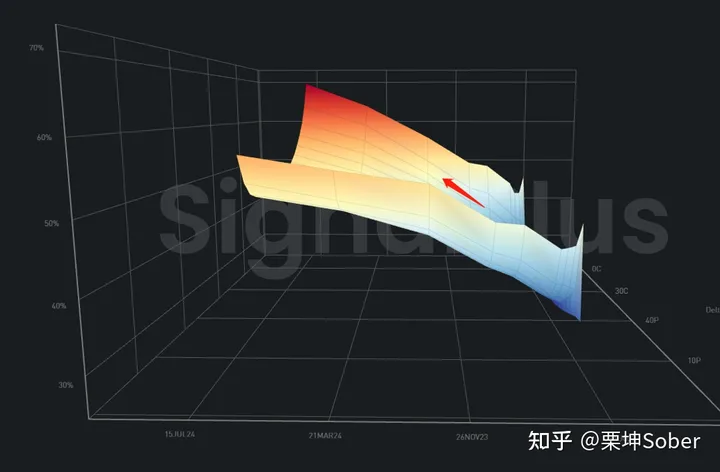
pie surface
Combination strategy construction is relatively simple. Take todays Thursday, August 3rd as the opening day
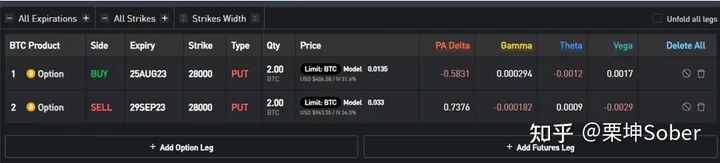
Strategy specific buying and selling options
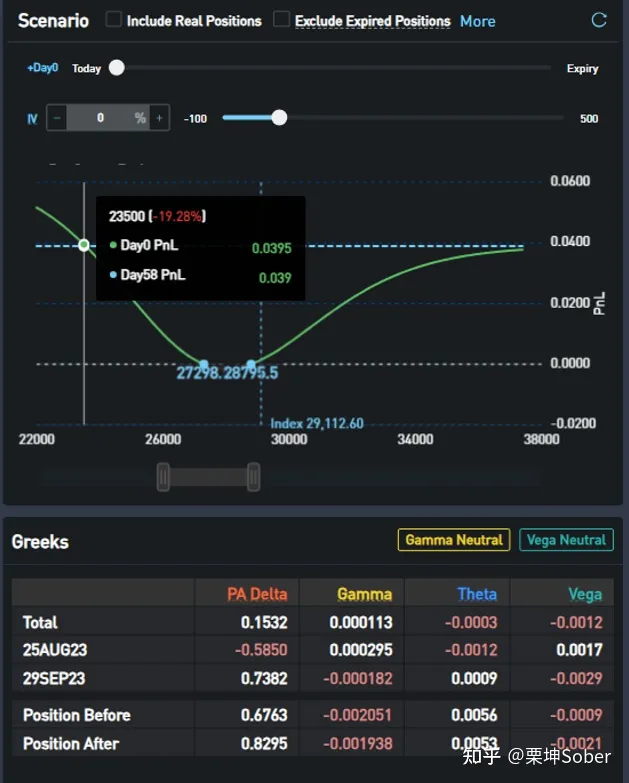
Breakeven & Greeks
The method is as follows: buy the 2.8w put at the end of August, and sell the 2.8w put at the end of September. The portfolio is structured on a premium revenue basis. Since it is a cross-month combination, there is a one-way put margin. An upward trend in IV means that September can be sold at a premium (relative to the maximum closing of Theta), and a downward trend in August means that August can be bought at a bargain price.
The portfolio is fully hedged with no significant exposure until the contract expires at the end of August.
Lets analyze itThree future scenarios:
1: The big pie rose sharply, reaching more than 2.8w yuan.
At this moment, both PUTs become deeply empty. As long as the payout of the double draw is lower than the income from opening the position, it is successful. If this rises, it is possible that both options will return to 0. We will discuss contingency before this expires at the end of August. Anyway, holding the put (2.8 W) sold in September is +delta, and there are various countermeasures that can be used.
2: The big pie fell sharply, reaching below 2.8w.
At this moment, if you buy put, you can close the position with profit first, and wait for the market to rebound before selling put in September. If the market falls seriously, the put changes from shallow virtual to deep real value, and the two options become the same price, or even have a price inversion at the low level! That is, the far month is lower than the near month! In this case, closing both positions may still result in a profit!
3: The pie continues to consolidate.
This is an initial judgment error (because the anti-calendar still has large fluctuations in the forecast direction), then we will weigh whether to continue this strategy before the expiration in August. Because our initial royalty income strategy has more room for maneuver than the calendar, and the anti-calendar strategy itself is also obviously an anti-fragile strategy from breakeven.
I feel that this strategy is completely different from the risk characteristics of the bull market spread on the put side, so it should be easier for risk-averse players to accept. The biggest difference from everyone’s habitual thinking is that even if it is long gamma or long vega, I still recommend building a premium income strategy, just like the “reverse proportional spread” strategy written in the previous article. In this way, the initial pressure of establishing a strategy is very low, and at the same time, the continuous accumulation of Theta can provide long-term tail risk protection. This also plays an important role in long-term investing in options and the process of increasing odds.
howlow cost,longDo a good job of tail risk protection? This is a difficult problem for many institutional investors, but on the contrary, it is actually not that difficult for retail investors to make good use of the delta exposure we can expose and spend a certain amount of theta to protect the tail.Our advantage。
In terms of coping methods, I basically don’t do double-leveling after I get moving. Because it is a waste of opportunity to close the opposite position at a price, because the price will definitely fluctuate within a period of time, and there are very few unilateral market conditions. Close a favorable position and wait to close another position, or there is a trading system. It is even simpler for players to close a certain leg according to the system settings.
4. Do you suggest that you be a seller or a buyer?
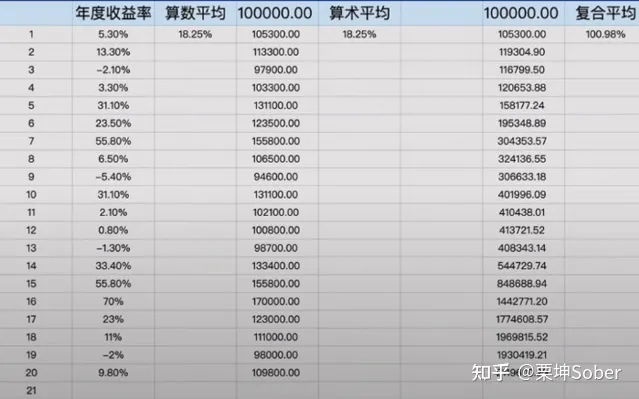
(Robust) low drawdown strategy 20-year arithmetic average return and compound return
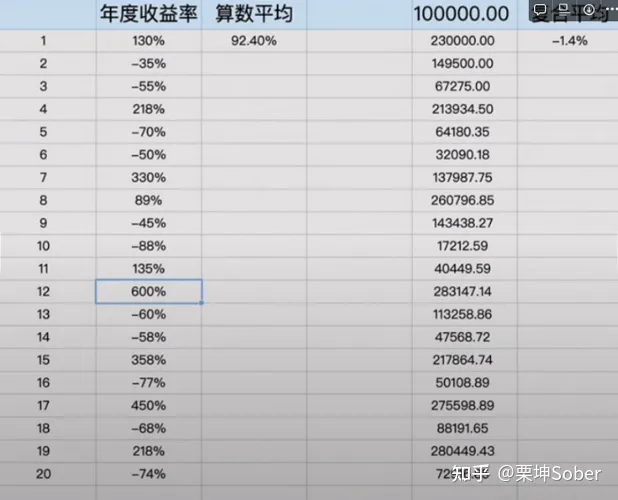
(Aggressive) high burst strategy 20-year arithmetic average return and compound return
The two pictures above show the annual profit of 20 years of trading, with arithmetic average and compound interest calculated respectively. Why compound interest is the eighth wonder, I believe these 2 charts reveal the truth.
In the current market environment, using the premium income strategy recommended in the article as an option seller, whether it is an anti-calendar or an inverse proportional spread, can cover the tail. If you are interested in tail risk management, you can read my previous article How to Use Options for Tail Risk Management. You can choose an option strategy that is suitable for you and has good compound interest effects based on your own circle of competence. Everyone has different opinions and there is no standard answer.
Conclusion
Dialectically look at whether IV is high or low, dialectically look at sellers and buyers, and dialectically look at longs and shorts.
Dialectically look at the conclusions drawn by many predecessors. In the world of trading, we just need to be cunning, continue to iterate the trading system, and win by correcting, not predicting!
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption information. If you want to receive our updates immediately, please follow our Twitter account @SignalPlus_Web 3, or join our WeChat group (add assistant WeChat: chillywzq), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website:https://www.signalplus.com





