Mint Ventures: In-depth analysis of LSD interest rate market service provider Pendle


Original Author: Colin Li
secondary title
1.1 Core investment logic
With the deepening of the LSD narrative, the call for developing more complex DeFi tools based on LSD, paying attention to and deducing the bond market narrative has gradually increased, including Pendle, which has begun to be recognized by the market and explored new trading strategies.
From the perspective of the transaction model, in the V2 version of Pendle, based on the AMM model proposed by Notional Finance, the reconstructed AMM has significantly improved the transaction efficiency;
From the perspective of underlying assets, Pendle has gradually built four layers of fixed-income markets with different risk levels, which can basically meet the needs of four different user roles: low-risk investors, arbitrageurs, liquidity providers, and yield speculators;
secondary title
1.2 Main Risks
Contract risk: If such an event occurs, it will have a significant impact on the normal operation of the project and the capture of token value. This risk is not limited to Pendle itself. Since Pendle’s underlying assets come from other DeFi projects, any contract risk in other projects will also implicate Pendle.
Strategic risk: If you do not select the assets and the public chain where the assets are located, you may be left behind by competitors in the next stage of competition. The project team needs to figure out what kind of underlying assets should be selected, and have an accurate understanding of the brutality of public chain competition.
secondary title
1.3 Valuation
Judging from the indicator of "total market value/locked position", the current valuation of PENDLE is lower than that of the other two projects that have already issued coins on the same track.
secondary title
2.1 Project business scope
Based on the income tokenization market, Pendle splits the interest-earning assets into principal token PT (principle token) and income token YT (yield token) after the lock-in period, which satisfies users' low-risk liquidity management and also provides Some traders who can keenly grasp the volatility of yields provide tools to earn high returns.
Regarding the interest rate market in the encrypted business world, the author wrote two special articles not long ago, discussing the business logic and development deduction behind the encrypted interest rate market, namely:
secondary title
2.2 Past Development and Roadmap
In March 2021, the name was changed from Benchmark to Pendle, and the testnet was launched that month;
In June 2021, the Pendle mainnet will be launched on Ethereum;
In November 2021, Pendle will be deployed in Avalanche;
In March 2022, the Project Permissionless plan was proposed, that is, anyone can open an asset pool on it;
In November 2022, the V2 version will be launched;
secondary title
2.3 Team situation
2.3.1 Overall Situation
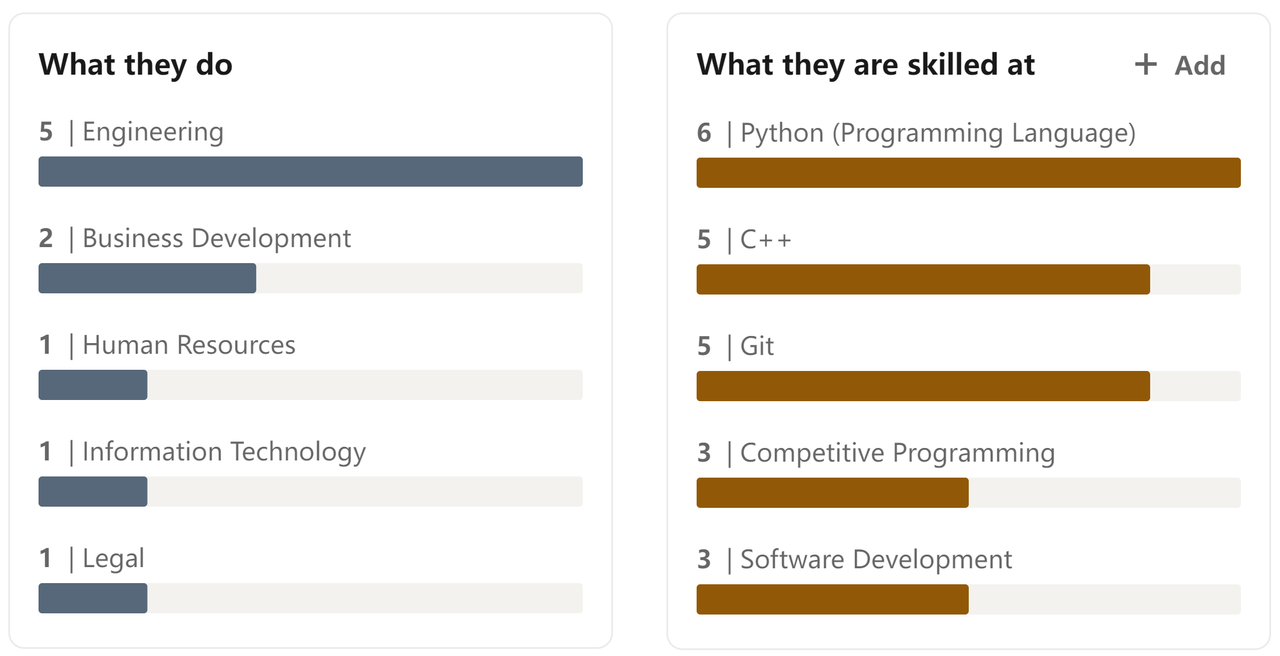
According to LinkedIn data, the Pendle team has a total of 13 employees, mainly composed of engineers and BD personnel.
source:
source:https://www.linkedin.com/company/pendlefinance/people/
2.3.2 Founders
TN Lee is the founder of Pendle. Before founding Pendle, he founded the data analysis company DSR, and entered the development of the blockchain industry in 2017, becoming a member of the founding team of Kyber Network, responsible for market and business development. Served as a RockMiner mine consultant in 2019. In the same year, TN Lee founded Pendle and Dana Labs, a research and development company focused on FPGAs.
2.3.3 Core members
Long Vuong Hoang: Head of Smart Contract Development at Pendle, graduated from the National University of Singapore. Prior to that, he worked as a trainee software development engineer at Jump Trading.
secondary title
source:
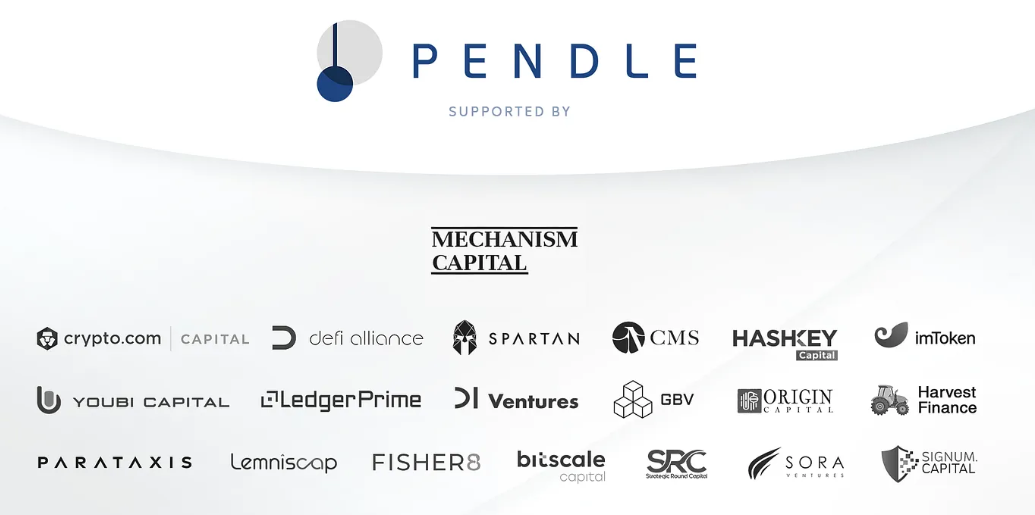
In April 2021, Pendle announced that it had received US$3.7 million in financing, led by Mechanism Capital, and other well-known institutions including Hashkey Capital, Spartan Group, etc.
In April 2023, Bixin Ventures announced to invest in Pendle through OTC. The specific transaction price and amount were not disclosed.
secondary title
3.1 Service object
Pendle can provide corresponding product services for four different investment groups: low-risk investors, interest rate traders, liquidity providers and arbitrageurs.
Low-risk investors can purchase principal tokens (PT, principle token) to earn fixed income. PT is similar to zero-coupon bonds, that is, bonds that do not pay interest during the holding period and are sold at a discount. approaching, the price will rise, and the payment will be made according to the face value after maturity;
Interest rate traders can buy yield tokens (YT, yield token), and when the yield rises as scheduled, they can earn high returns;
Liquidity provider (Liquidity provider), if the expected rate of return does not fluctuate too much, you can choose to provide liquidity, earn transaction fees, underlying asset income and incentives;
secondary title
3.2 Business Classification
Since its launch, Pendle has been focusing on revenue tokenization. So far, there have been two versions, V1 and V2. Through the changes in the underlying assets of the two versions, we can see the adjustment of Pendle's business strategy.
In the early days of the V1 version, Pendle chose to focus on the deposit certificate of lending DeFi, and the underlying assets were "stable coins + public chain tokens". For example, on the Ethereum chain, the underlying assets are Aave and Compound’s stablecoin lending assets as interest-earning assets: aUSDC and cDAI; on Avalanche, Trader Joe’s xJOE, BenQi’s qiUSDC, qiAVAX, etc. are selected. Such target selection is in line with the narratives of "institutional investors entering the market" and "treasury fund management" at the time: The big bull market that started in 2020 has attracted many traditional investment institutions to the encryption market. With the expansion of the market size, some projects The DAO treasury is also filled with a large amount of funds. It can take into account the categories familiar to traditional investors and how to better make the DAO treasury funds earn more income, which has become the focus of some investors and entrepreneurial teams. For example, in October 2021, Multicoin Capital began to discuss interest rate management tools for such a vision. At the same time, cooperate with Rari Capital and Olympus to expand the application scenarios of some tokens.
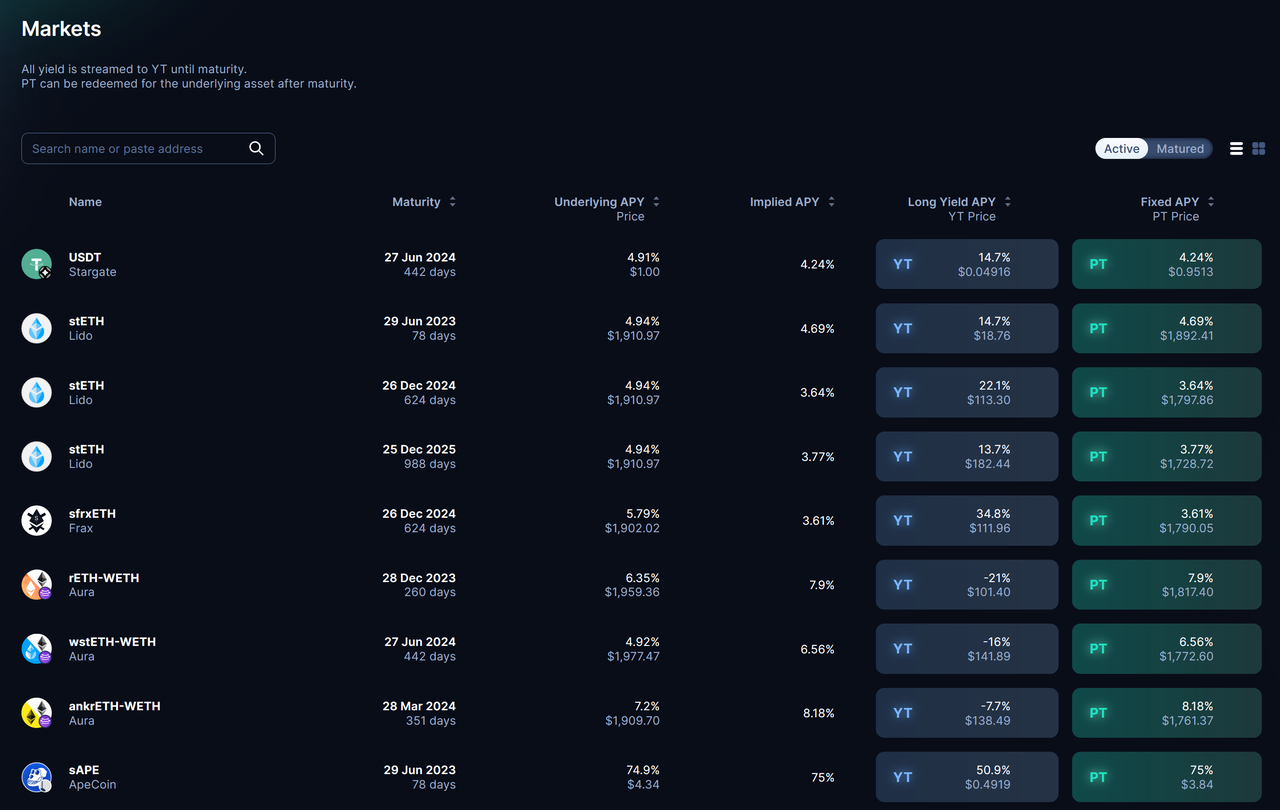
From the late version of V1 to the current version of V2, Pendle has been adjusted, closed the business on Avalanche, and started to deploy on Arbitrum. At the same time, the target is no longer limited to public chain tokens and stable coins, but has mainly become 4 directions. Among them, Ethereum involves 3 directions:
On the Ethereum chain, liquid pledged derivatives LSD are used as the main underlying assets, such as stETH, ankrETH, etc.;
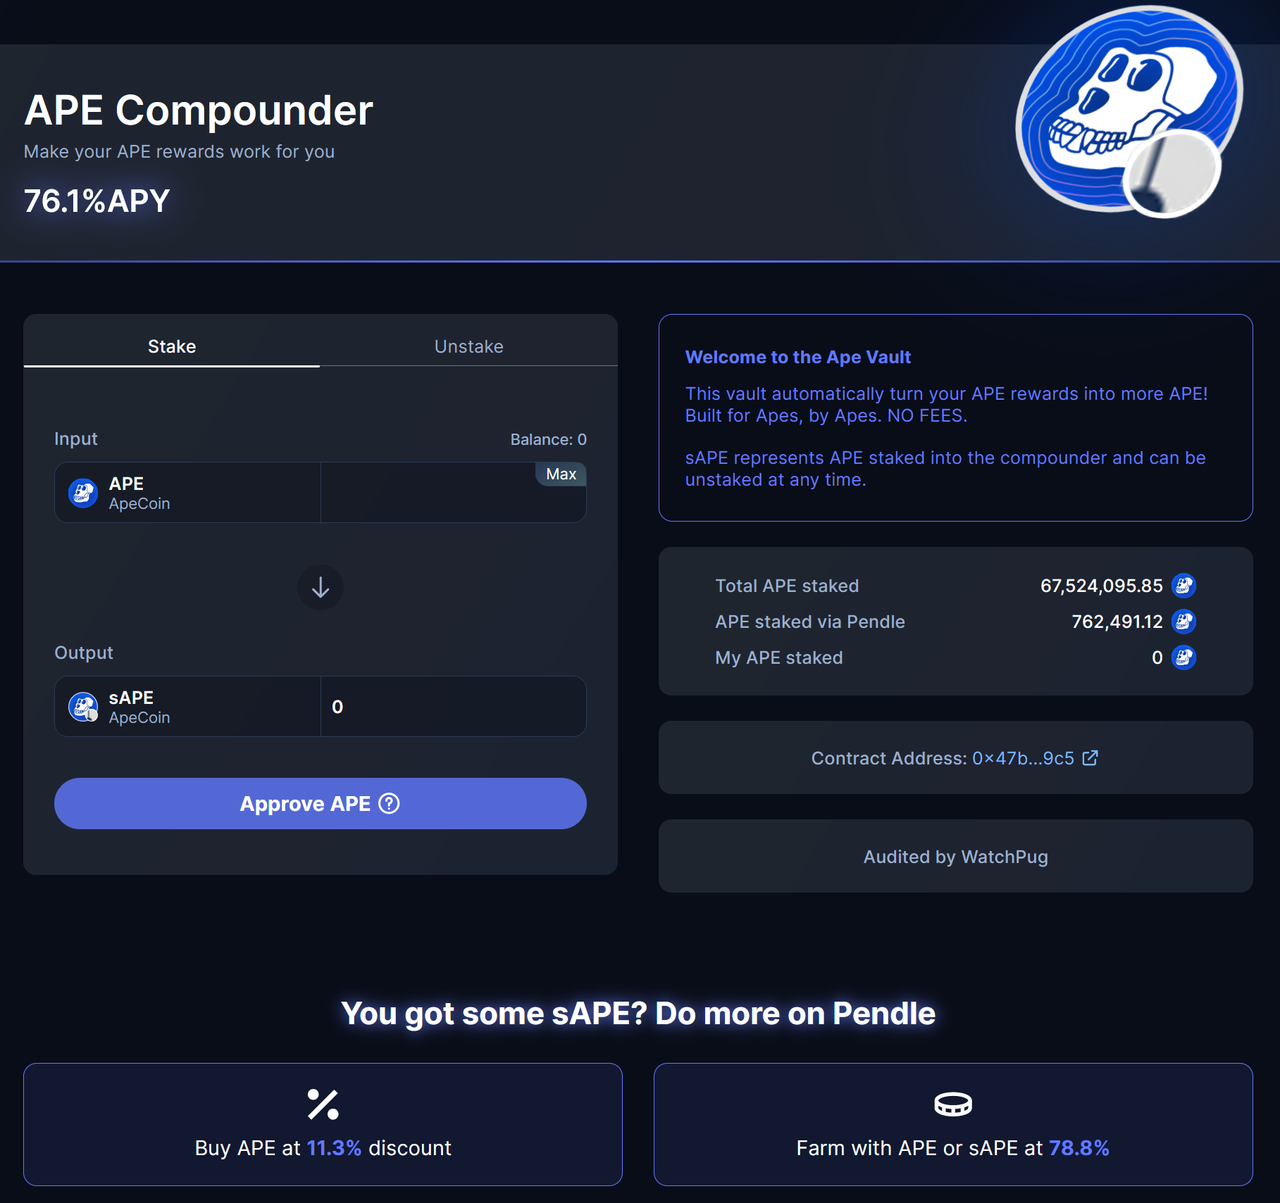
Expansion of relatively popular tokens with high staking returns, such as APE and LOOKS;
source:
source:https://app.pendle.finance/pro/markets? utm_source=landing&utm_medium=landing
source:https://app.pendle.finance/utilities/ape
source:
source:https://app.pendle.finance/pro/markets? utm_source=landing&utm_medium=landing
So far, Pendle has not expanded the application scenarios of its own tokens, such as inviting other DAOs to manage treasury funds. This may be because Pendle hopes that users come here to directly use its services.
The previously estimated PP (Project Permissionless) plan, although affected by the closure of the partner Rari Capital and the strategic adjustment, has not been interrupted: a new token standard that can encapsulate most interest-earning assets: ERC-5115 has been launched to solve It solves the problem of LP tokens that were difficult to be packaged and tokenized in the past.
In addition, LayerZero, a cross-chain solution, and Kyber Network, a decentralized exchange, are also integrated to support products with higher yields that may appear on other chains.
3.3 Business Details
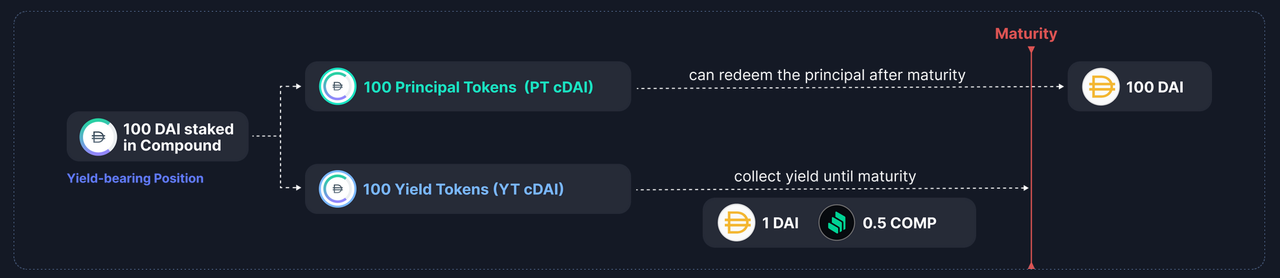
Pendle's income tokenization business, simply put, is to split the interest-bearing tokens into two parts: cost and income.
Taking DAI as an example, when a user deposits 100 DAI into Pendle, Pendle will first deposit DAI into compound to become 100 cDAI. Then, Pendle will package 100 cDAI into a standardized income token sy-cDAI (Standardized Yieldsource:
source:https://app.pendle.finance/pro/learn? level= 1
We can think of the principal token PT as a zero-coupon bond. The closer to the expiration date, the closer the price of PT is to the face value; the income token YT will get any income during the holding period. For example, YT-cDAI has loan income during the holding period, and also has the COMP incentive provided by Compound.
It is worth noting that in the above steps, YT+PT=SY.
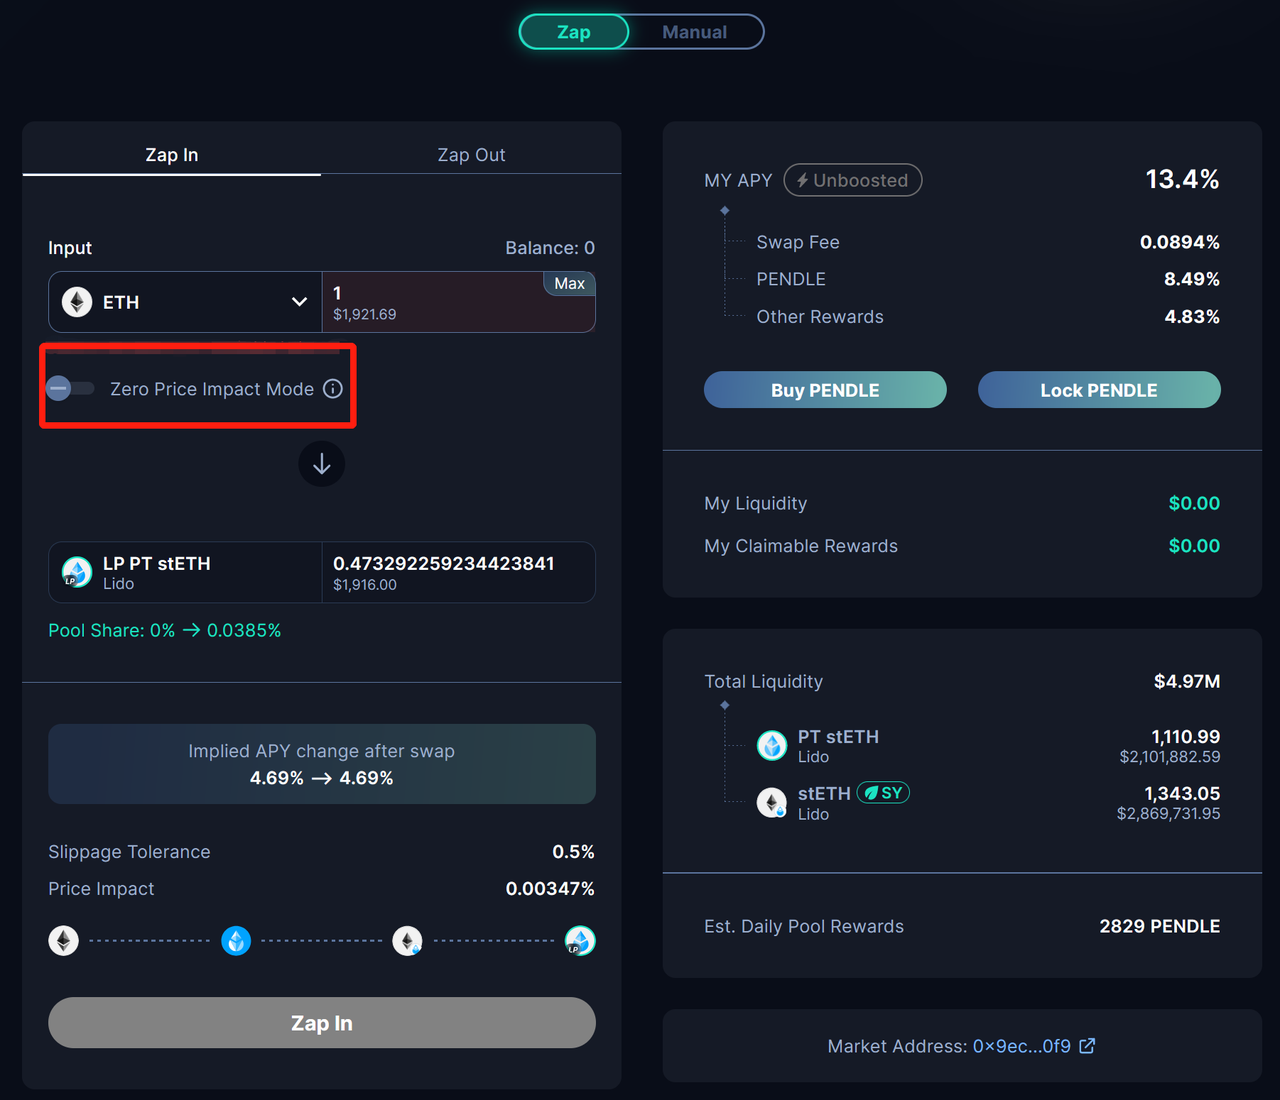
From the perspective of business process, after the user deposits assets in Pendle, there will be several changes in total. Here we take the asset deposited by the user as ETH as an example:
The user deposits ETH, in the "Zap" mode, Pendle will automatically exchange ETH for stETH through Kyberswap;
Pendle encapsulates stETH into sy-stTH. Standardized Yield Tokens (Standardized Yield, abbreviated as sy) is a token under the ERC-5115 standard, which can encapsulate most of the interest-earning assets. The token agreement is also the token standard designed by the Pendle team;
source:
source:https://app.pendle.finance/pro/pools/0x54e28e62ea9e8d755dc6e74674eabe2abfdb004e/zap/in
In addition to directly depositing assets to form LPs, users can also purchase PT and YT directly through Pendle.
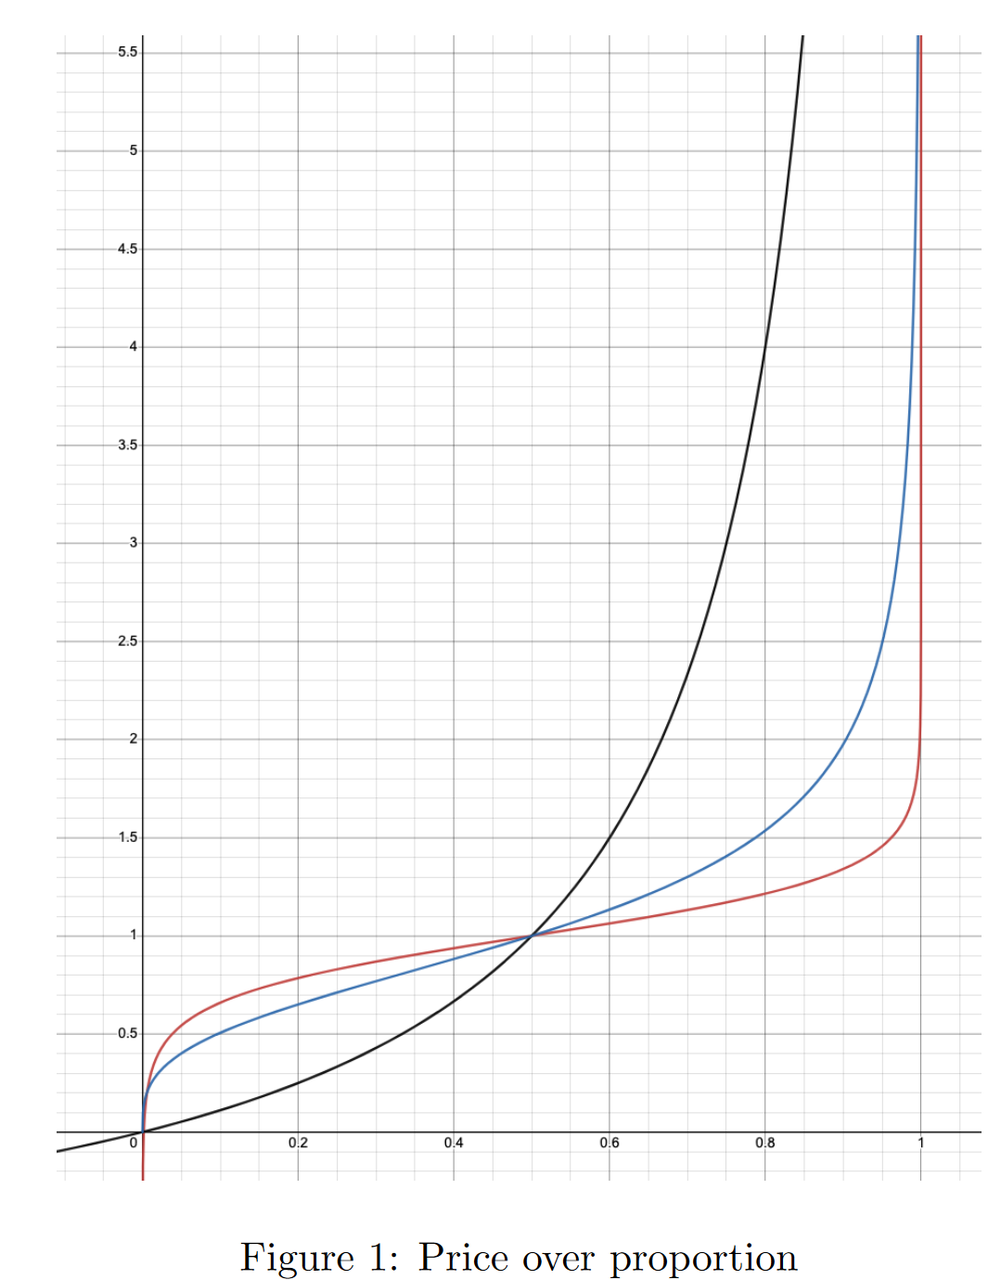
Pendle uses the AMM mechanism for trading PT and YT, but this AMM mechanism needs to consider the PT, SY prices, and interest rate levels under the passage of time, which is different from the traditional Uniswap AMM mechanism.
source:
source:https://raw.githubusercontent.com/pendle-finance/pendle-v2-resources/main/whitepapers/V2_AMM.pdf
source:
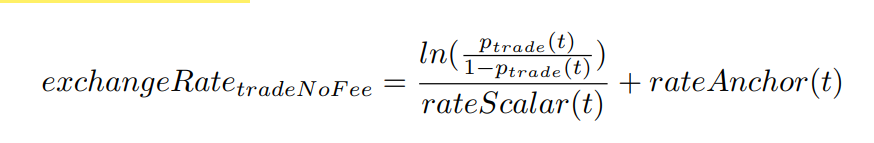
source:https://raw.githubusercontent.com/pendle-finance/pendle-v2-resources/main/whitepapers/V2_AMM.pdf
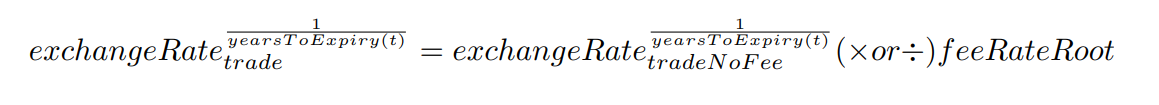
source:https://raw.githubusercontent.com/pendle-finance/pendle-v2-resources/main/whitepapers/V2_AMM.pdf
In the above model, adjusting the "rate scalar" can set the maturity time, which can improve capital utilization efficiency. If the maturity time is shorter, the liquidity will be more concentrated and the capital utilization efficiency will be higher. By adjusting the "rate anchor" to set the interest rate range, the efficiency of capital utilization can also be improved.
source:
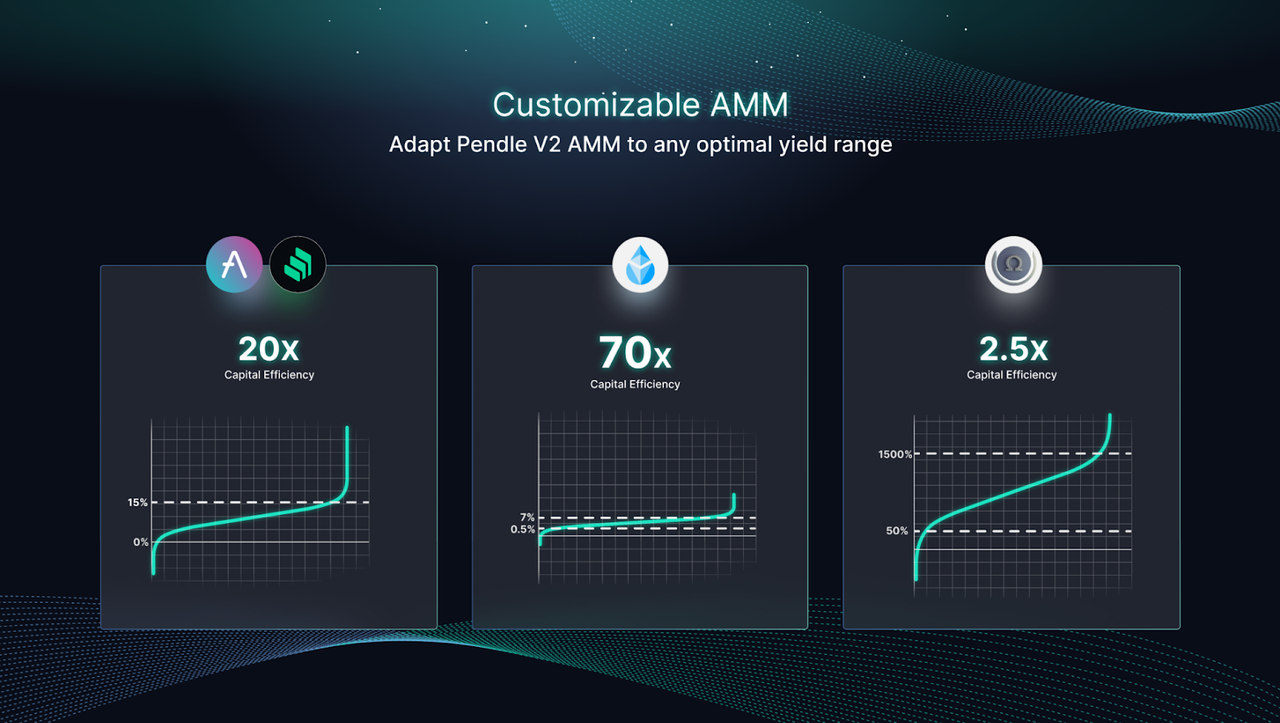
source:https://docs.pendle.finance/PendlePro/HowItWorks/AMM
The original intention of this AMM model is to trade the principal token PT and the standardized income token SY. However, because YT+PT=SY, YT=SY-PT, this AMM model also supports the transaction of revenue token YT.
If the user wants to buy YT, the transaction process is as follows:
The buyer sends 1 SY into the transaction contract, hoping to buy YT;
The trading contract will draw N SY from the pool;
Split N SYs into N PTs and N YTs;
Send N YTs to buyers;
source:
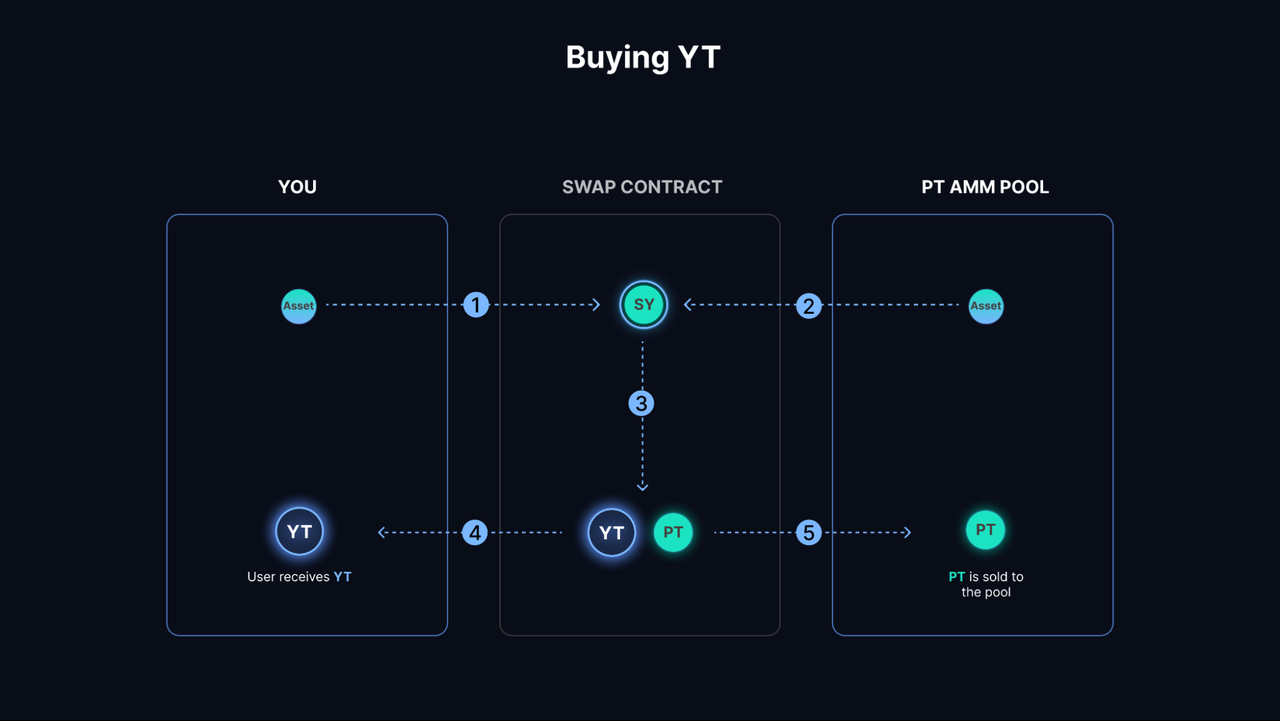
source:https://docs.pendle.finance/PendlePro/HowItWorks/AMM
If the user wants to sell YT, follow the steps below:
The seller sends N YT into the transaction contract, hoping to sell YT;
The contract will lend N PT from the pool;
The contract synthesizes N YT and N PT into N SY;
A part of SY will be exchanged for PT and sent to the contract to repay the PT lent in step (2);
source:
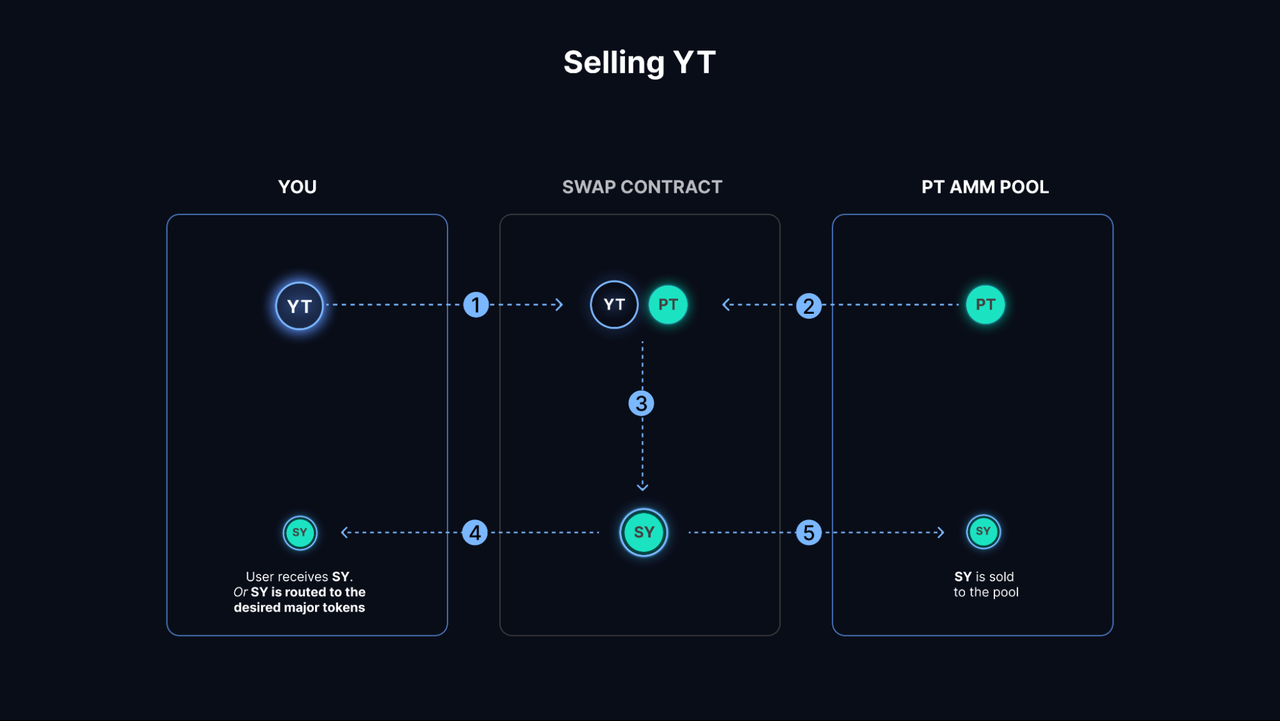
source:https://docs.pendle.finance/PendlePro/HowItWorks/AMM
Therefore, although Pendle's AMM model supports the transactions of YT, PT and SY tokens, but when no YT transaction occurs, there are only two types of assets in the pool, SY and PT.
source:
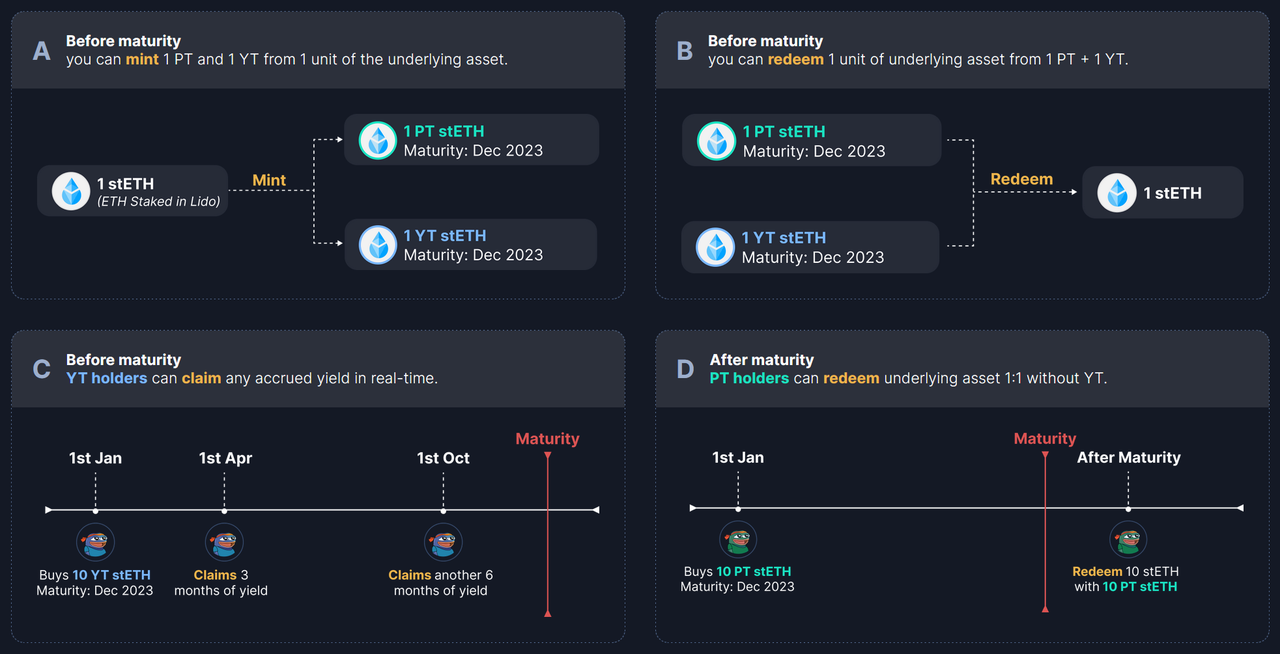
source:https://app.pendle.finance/pro/learn? level= 1
First of all, users can add liquidity to do LP, earn service fees and token incentives.
Because there are only two types of assets, PT and SY, in the pool, and the price of 1 PT before maturity is less than 1 SY, and the relationship between PT and SY is based on the interest rate. Therefore, if you are a liquidity provider on Pendle, it can actually be regarded as providing a type of asset, that is, SY. Because LP=PT+ST=SYf(r)+SY=SY (1+f(r)), here 1+f(r)<2, f(r) represents a function of interest rate and is inversely related to interest rate , because the higher the interest rate, the lower the PT price; the lower the interest rate, the higher the PT price. Therefore, as an LP in Pendle, it can be regarded as only providing SY assets, and it is believed that the interest rate level will decrease in the future, that is, the short interest rate.
At maturity, LP=PT+SY= 2 SY-YT.
Therefore, before maturity, there are 4 sources of income for LP:
Appreciation of PT
Partial transaction fee
excitation
SY The interest-earning income brought by the underlying interest-earning assets
If LP is held to maturity, there will be no impermanent loss. Secondly, users can deposit interest-paying assets, sell YT after splitting into PT and YT, and lock in the yield; third, users can directly buy PT, which is equivalent to buying zero-coupon bonds, and make stable investments; fourth , users can buy YT directly, and gain greater profits by predicting the direction of yield changes.
In order to better guide users' transactions, Pendle gives two data for the probability of "interest rate":
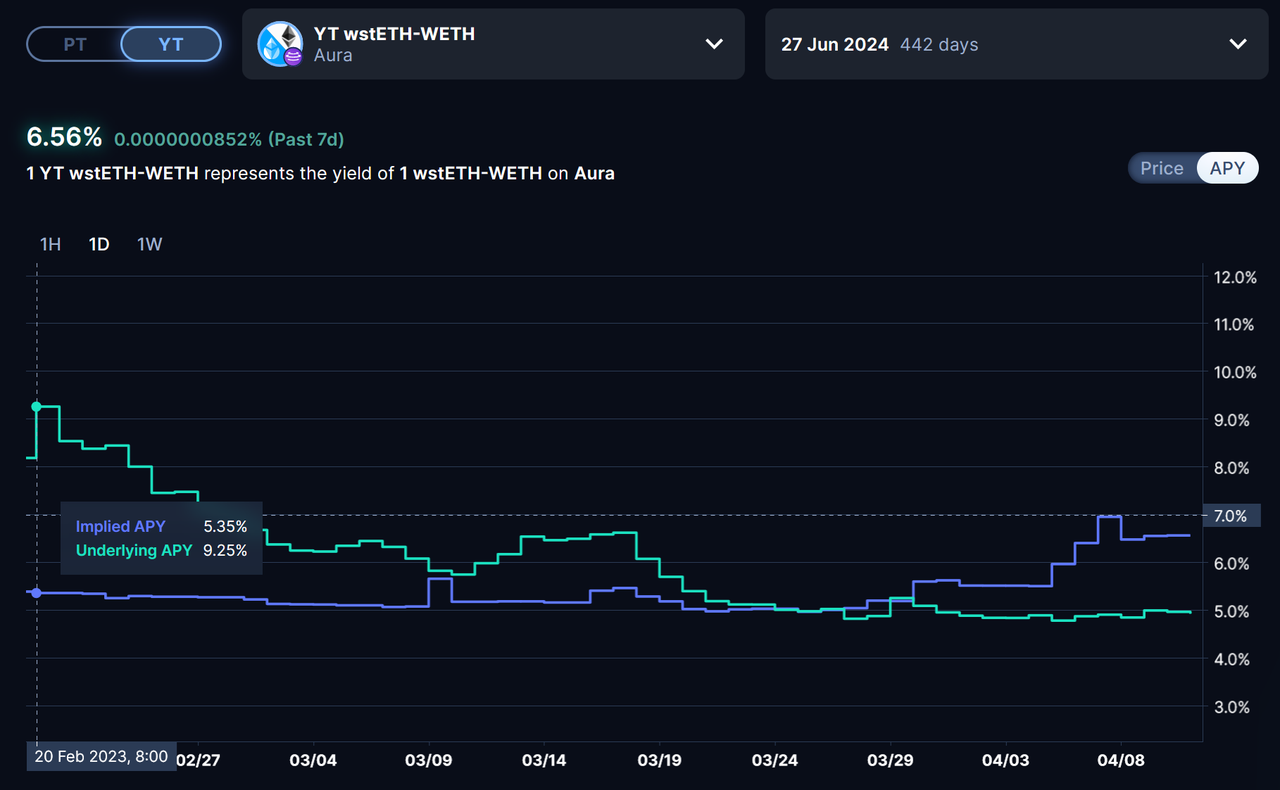
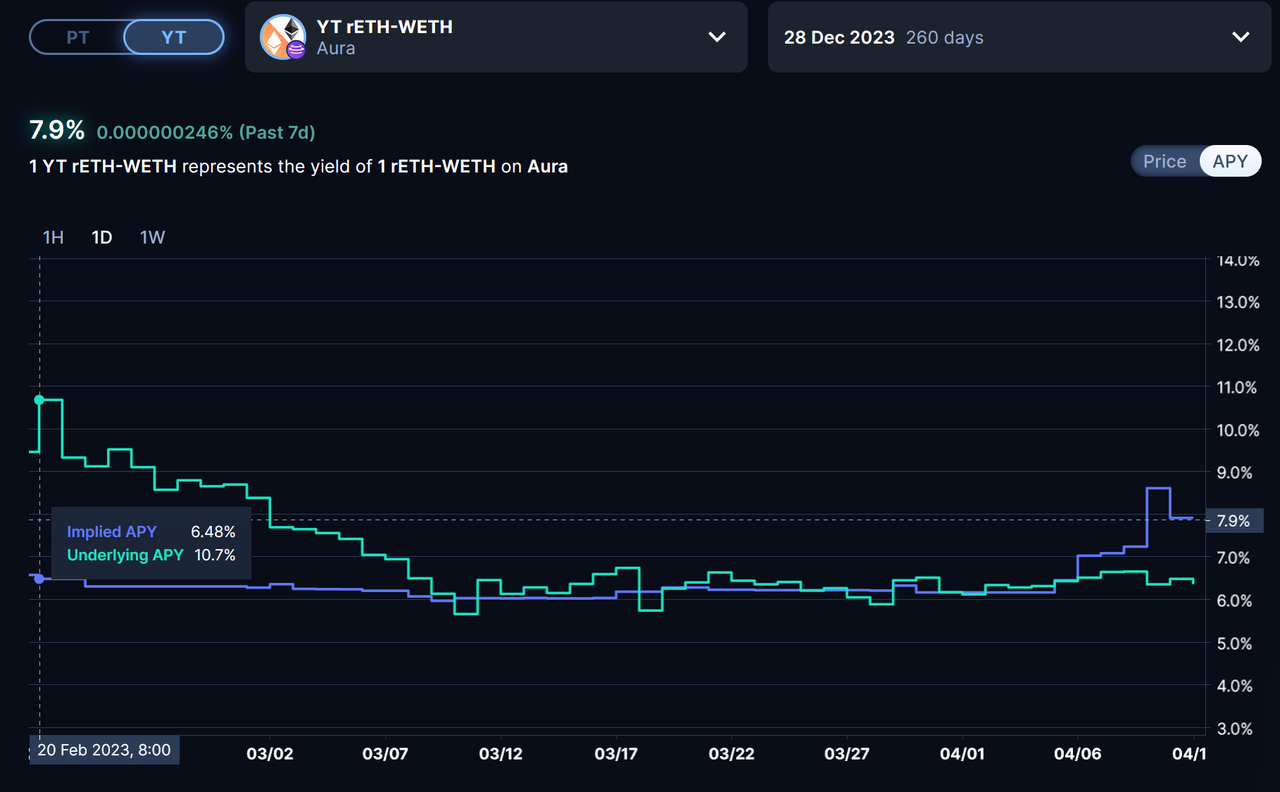
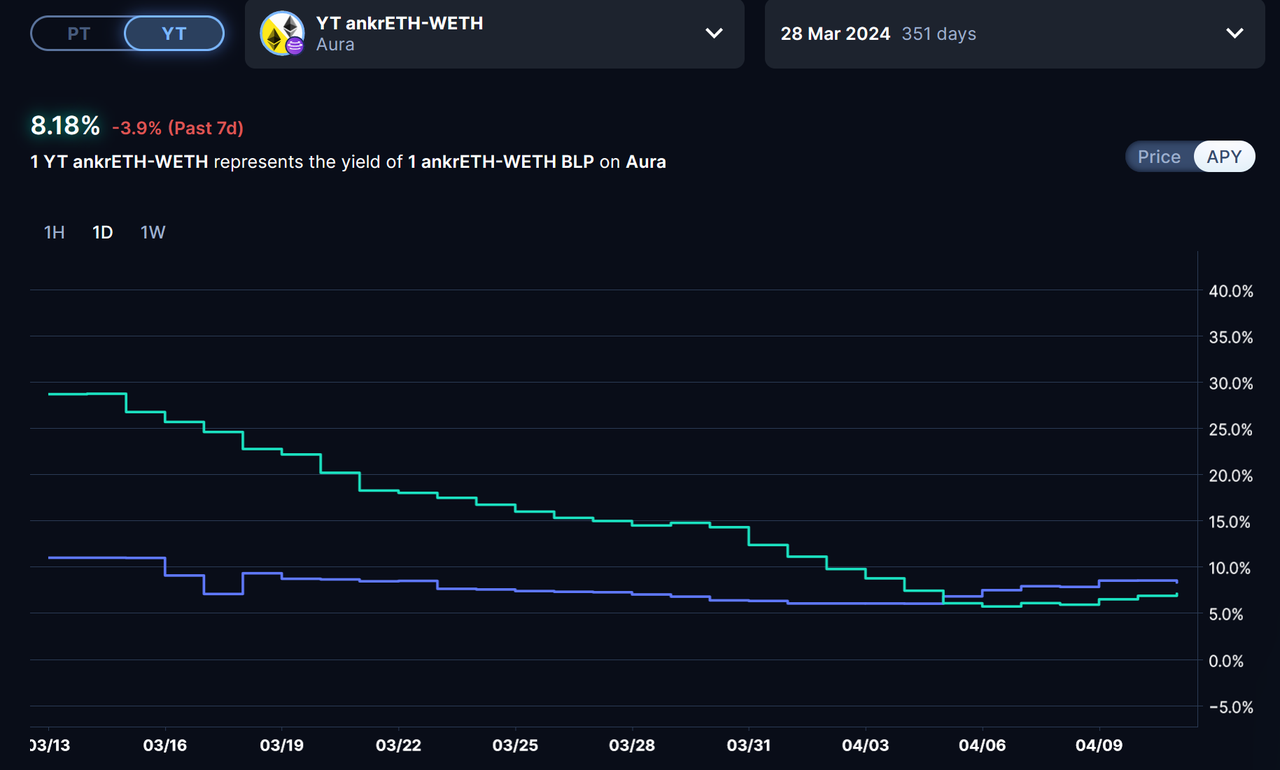
underlying APY, that is, the rate of return on holding assets;
implied APY, that is, the implied rate of return, which is the result of market transactions and is the expectation of future APY.
source:
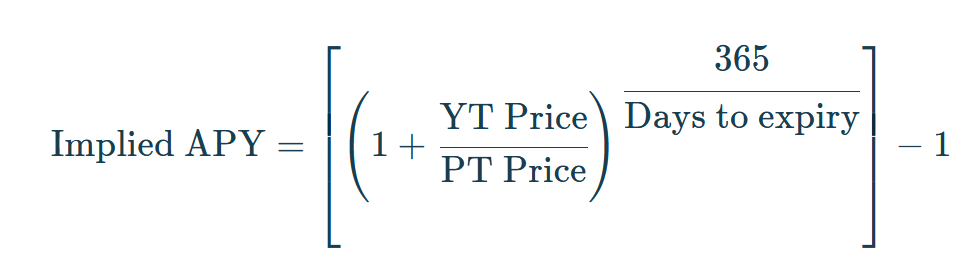
source:https://docs.pendle.finance/FAQ/General#glossary
When underlying APY>implied APY, you can consider buying YT at this time, or selling PT and doing LP. However, it is possible that the underlying APY converges with the implied APY through a decrease in the underlying APY rather than an increase in the implied APY;
source:
source:https://app.pendle.finance/pro/markets/0xfcbae4635ca89866f83add208ecceec742678746/swap?view=yt
source:https://app.pendle.finance/pro/markets/0x5546d0f27bed4075ea03a22c58f7016e24c94ea7/swap?view=yt
source:https://app.pendle.finance/pro/markets/0x9a76925dd91a7561b58d8353f0bce4df1e517abb/swap?view=yt
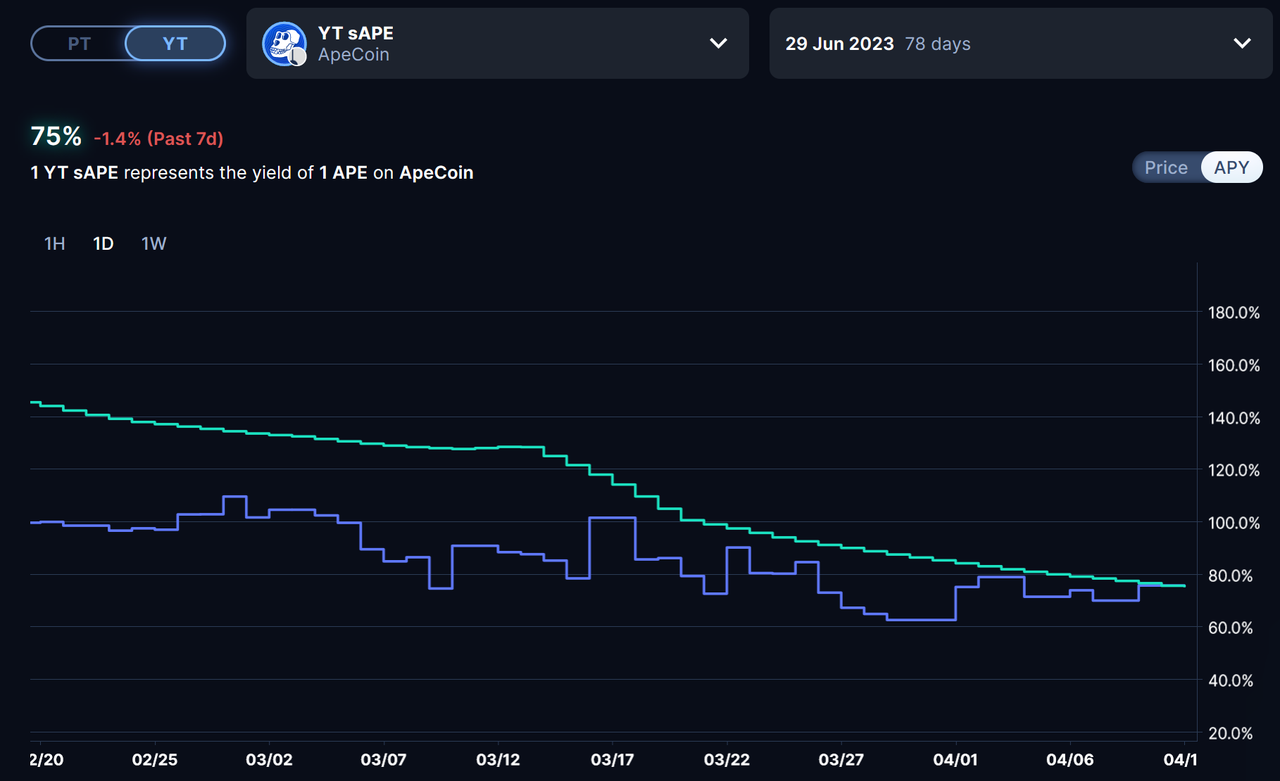
source:https://app.pendle.finance/pro/markets/0x9a76925dd91a7561b58d8353f0bce4df1e517abb/swap?view=yt
The core of the relationship between implied APY and underlying APY is to consider the actual situation of the market. To predict the direction of APY, it is necessary to analyze the factors that affect the rate of return of the underlying assets.
source:
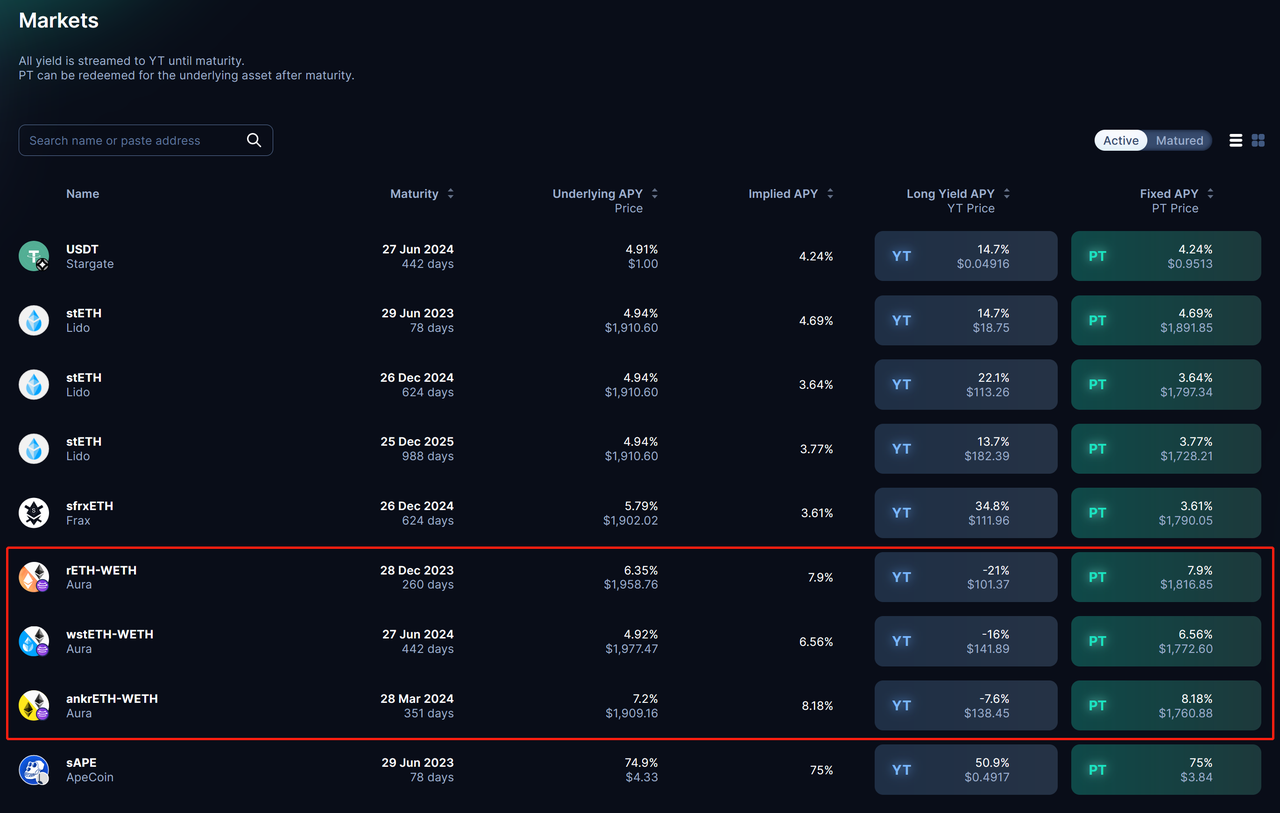
source:https://app.pendle.finance/pro/markets
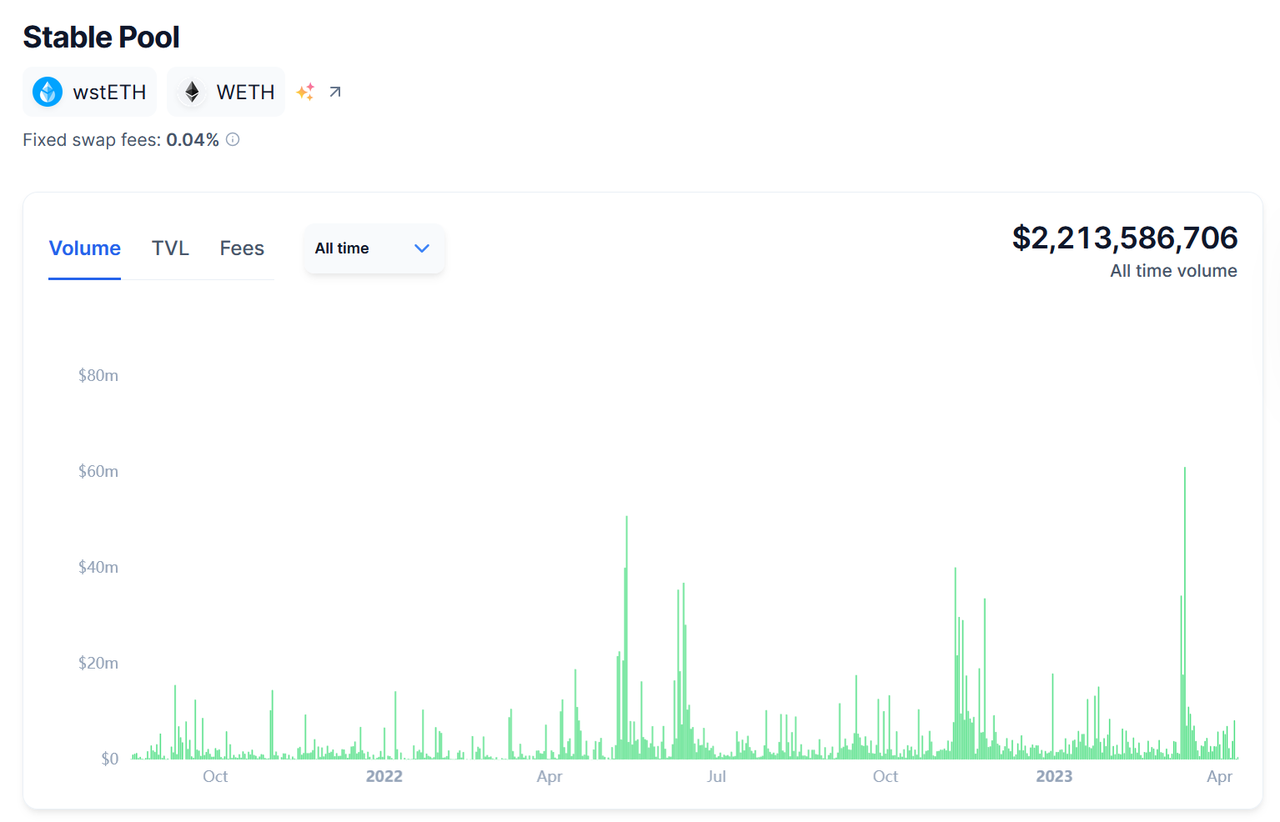
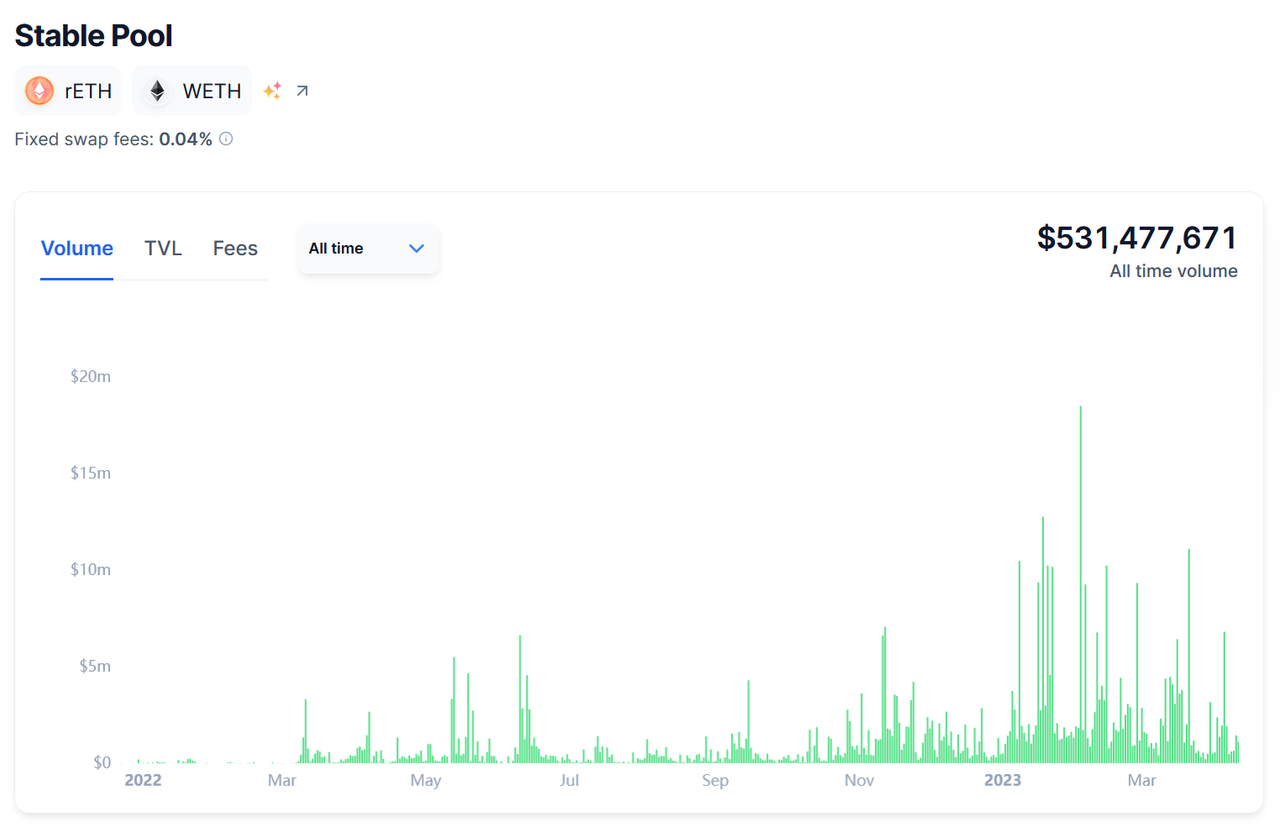
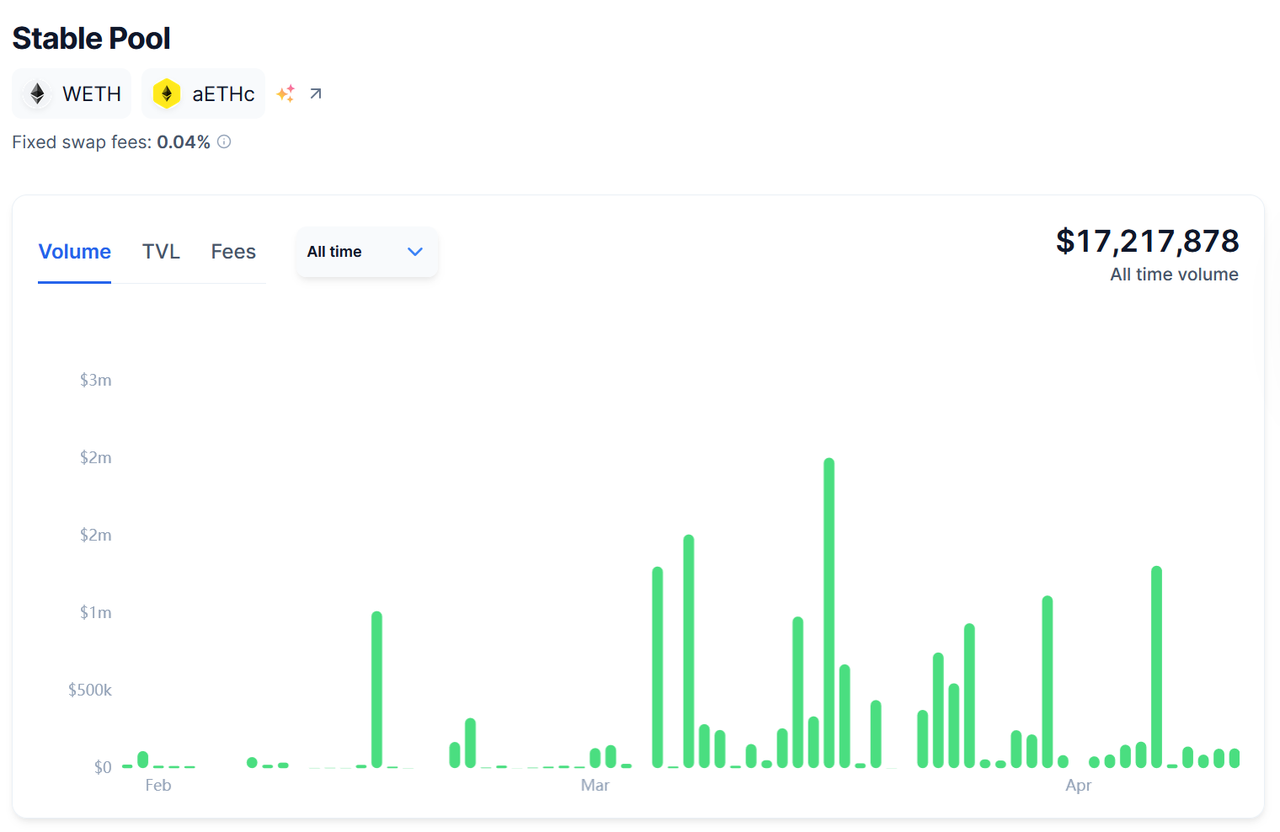
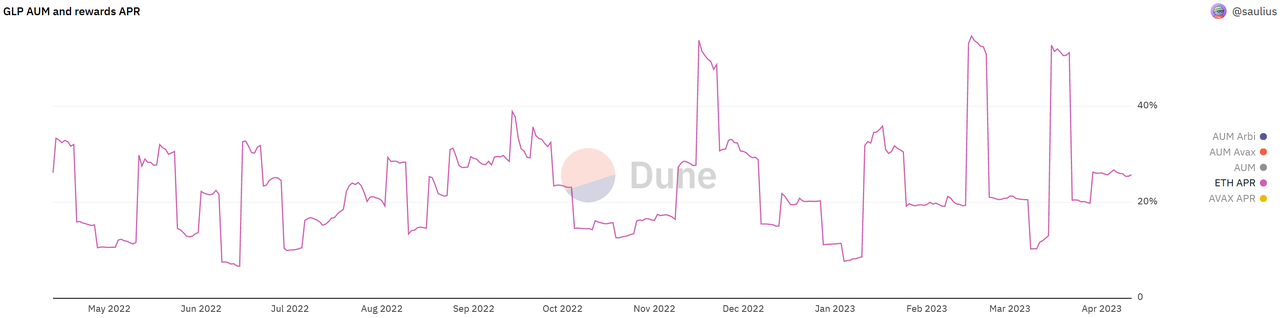
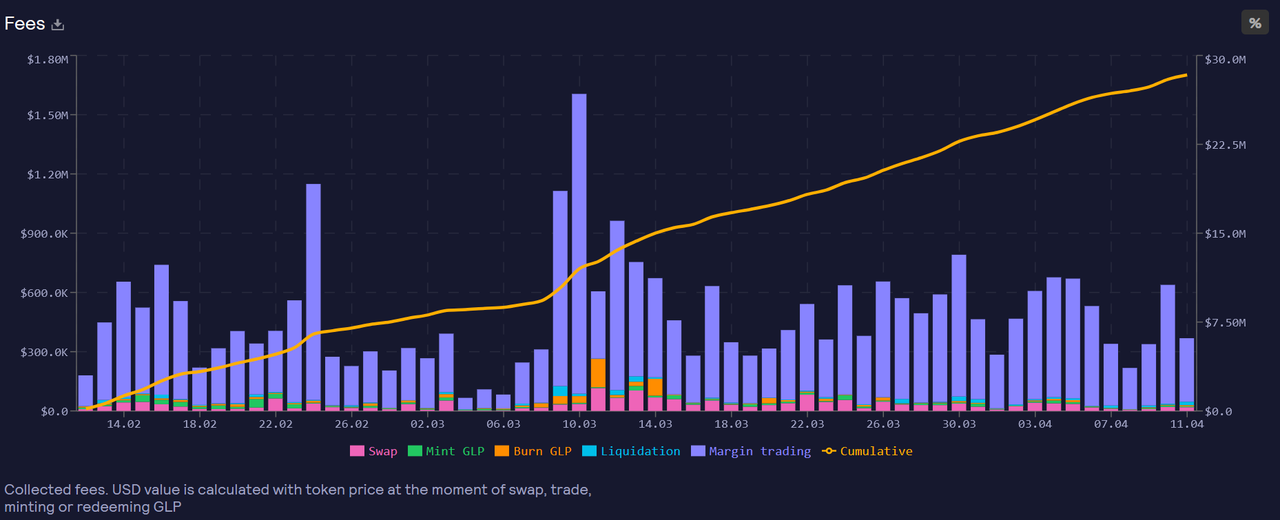
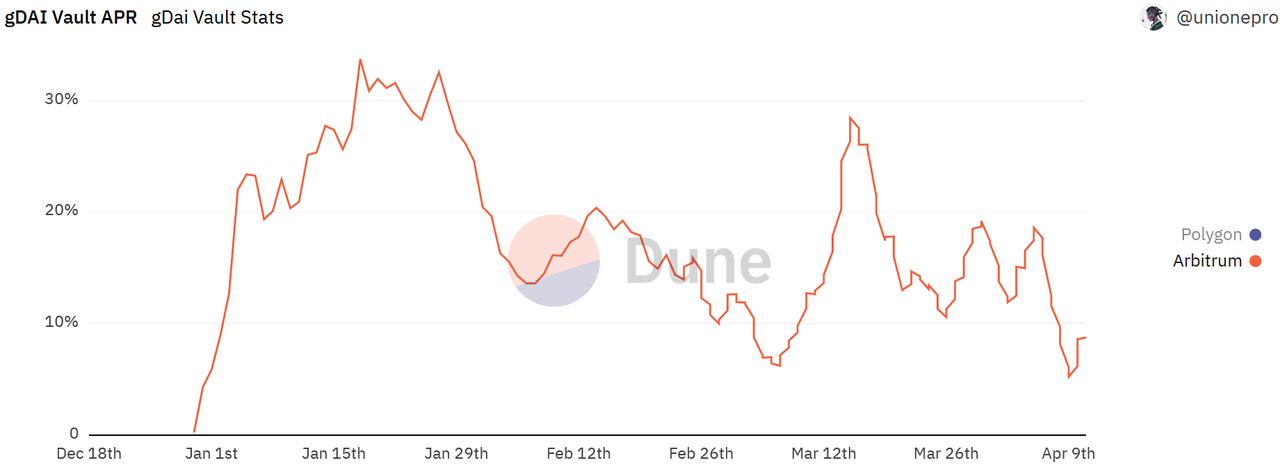
Observing the trading volume of the three trading pairs may be able to guide our judgment on the direction of yield.
image description
source:
source:https://dune.com/saulius/gmx-analytics
source:https://stats.gmx.io/
source:https://dune.com/unionepro/Everthing-Gains-Network
source:https://dune.com/unionepro/Everthing-Gains-Network
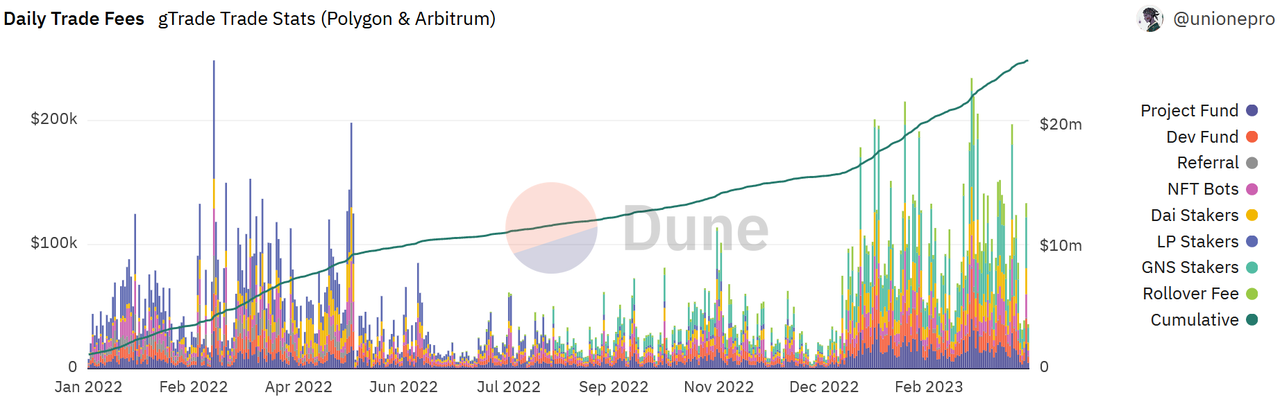
The same principle also applies to the transaction of GLP and gDAI, but the net rate of return of GLP and gDAI, in addition to considering the transaction fee income brought by the transaction volume, also needs to consider the profit of the trader. If the overall profit of traders is more in the short term, the net income of GLP will be reduced, or even a loss.
source:
source:https://dune.com/ponzidope/apecoin-staking-apy
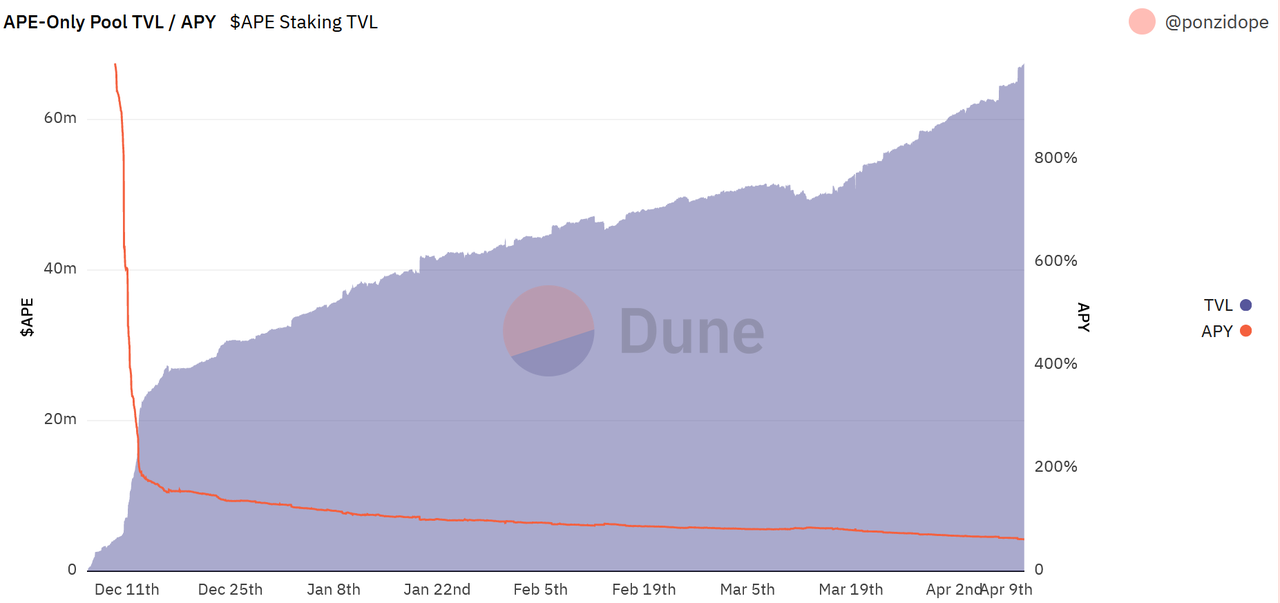
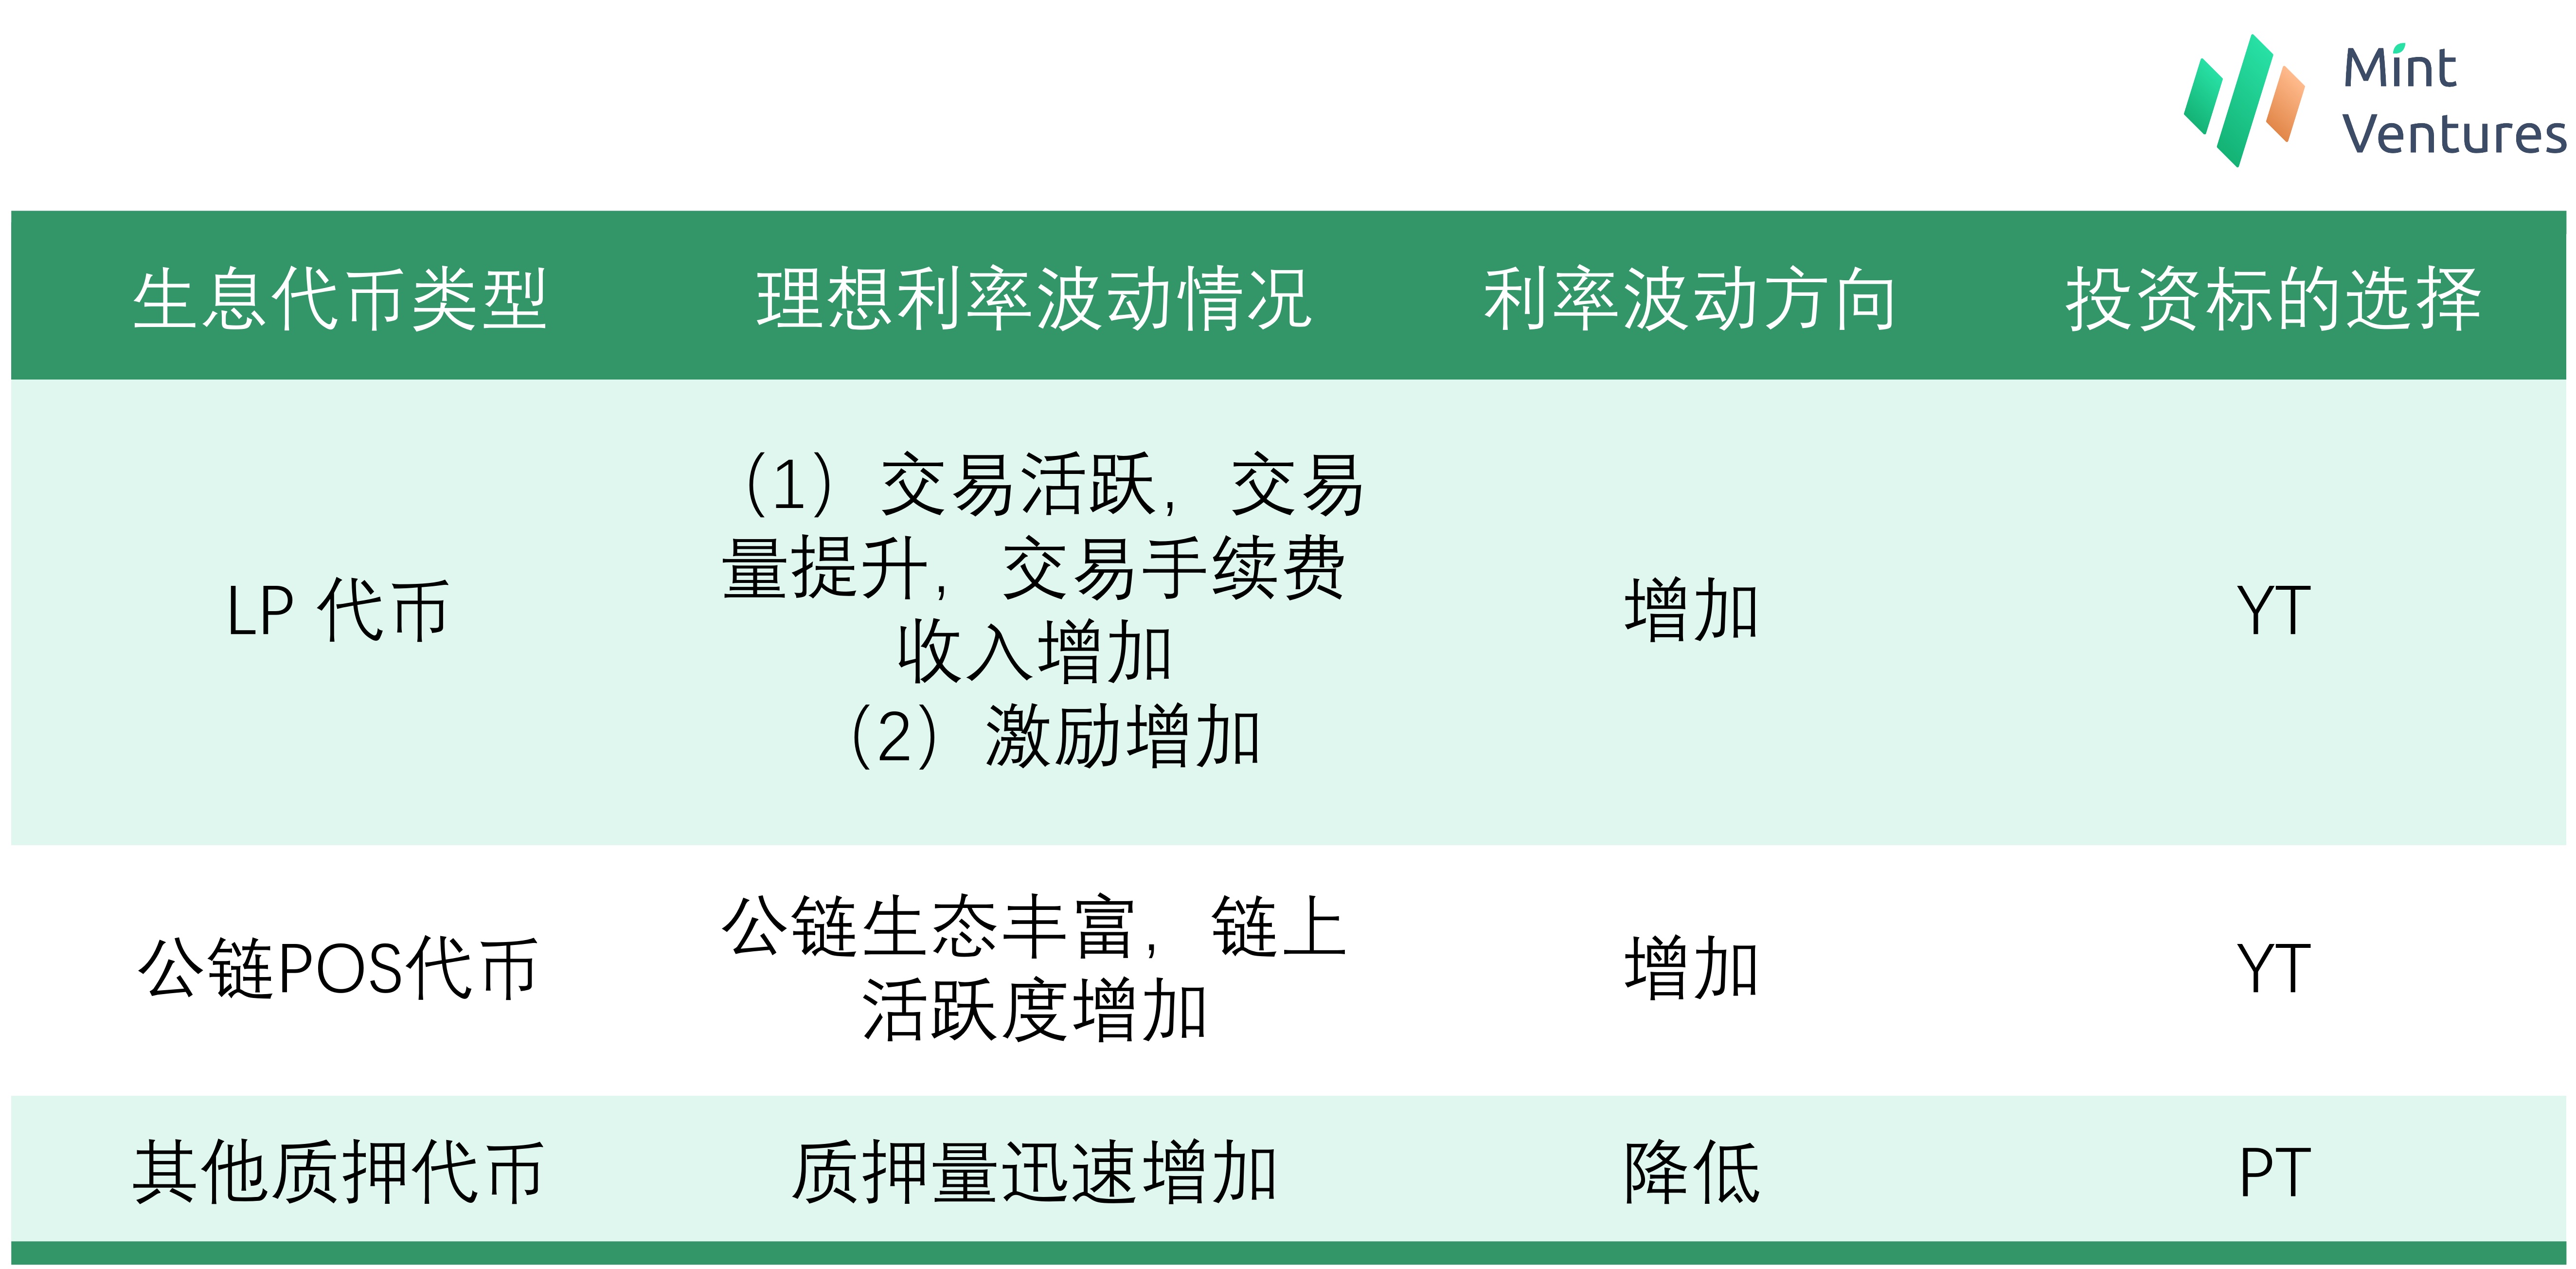
Because PT and the rate of return show a negative correlation, and YT shows a positive correlation with the rate of return, so the investment strategy for this type of token is to choose to observe the number of pledged tokens and the pledge rate of return. If the rate of return falls rapidly, PT will rise significantly relative to SY in the short term.
image description
secondary title
3.4 Multi-chain deployment
In the V1 version, Pendle was deployed on Ethereum and Avalanche, and reached some cooperation with some projects on the two public chains.
For example, on Avalanche, it has reached a cooperation with BENQI and launched two pools, qiAVAX and qiUSDC. BENQI DAO has deployed USDC and AVAV worth USD 250,000 to Pendle's qiUSDC and qiAVAX pools; it has also reached a cooperation with Trader Joe, launched the xJOE pool, and established a PENDLE/AVAX pool on Trader Joe.
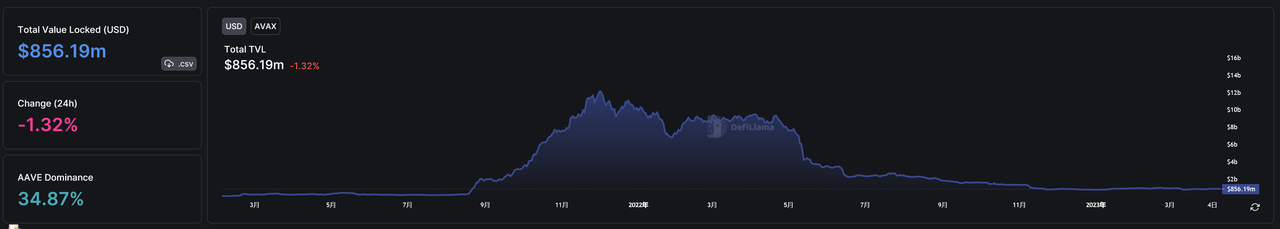
In the latest V2 version, Pendle is only deployed on Ethereum and Arbitrum at this stage. The reason for making such a choice may be related to the current ecological state of Avalanche:
image description
source:https://defillama.com/chain/Avalanche
secondary title
3.5 Industry Space and Potential
3.5.1 Classification
Although Pendle itself is positioned in the fixed income market, judging from the changes in the V2 version, the Pendle team seems to have stratified the "on-chain fixed income market":
Represented by LSD, as a low-risk fixed income market. The characteristics of this type of market are that the risk of the underlying assets is very low, the rate of return is relatively stable, and the cyclicality has little impact on the rate of return;
Represented by LSD's LP token and stablecoin LP token, it serves as a lower-risk fixed-income market. The characteristic of this type of market is that the risk of the underlying assets is low, but the cycle is relatively obvious, especially when there is high volatility in the market, the rate of return may be high at certain moments;
Represented by GLP and gDAI, as a medium-risk fixed-income market. This type of market is characterized by high returns and high risks at the same time. The returns are affected by derivatives traders on the chain and fluctuate violently with the market;
Represented by APE, as a high-risk fixed income market. The characteristic of this type of market is that it fluctuates violently following the target, and the yield is high but may also fluctuate greatly. With the frantic influx of single project pledge users, the yield may plummet.
3.5.2 Market Size
First look at the LSD market
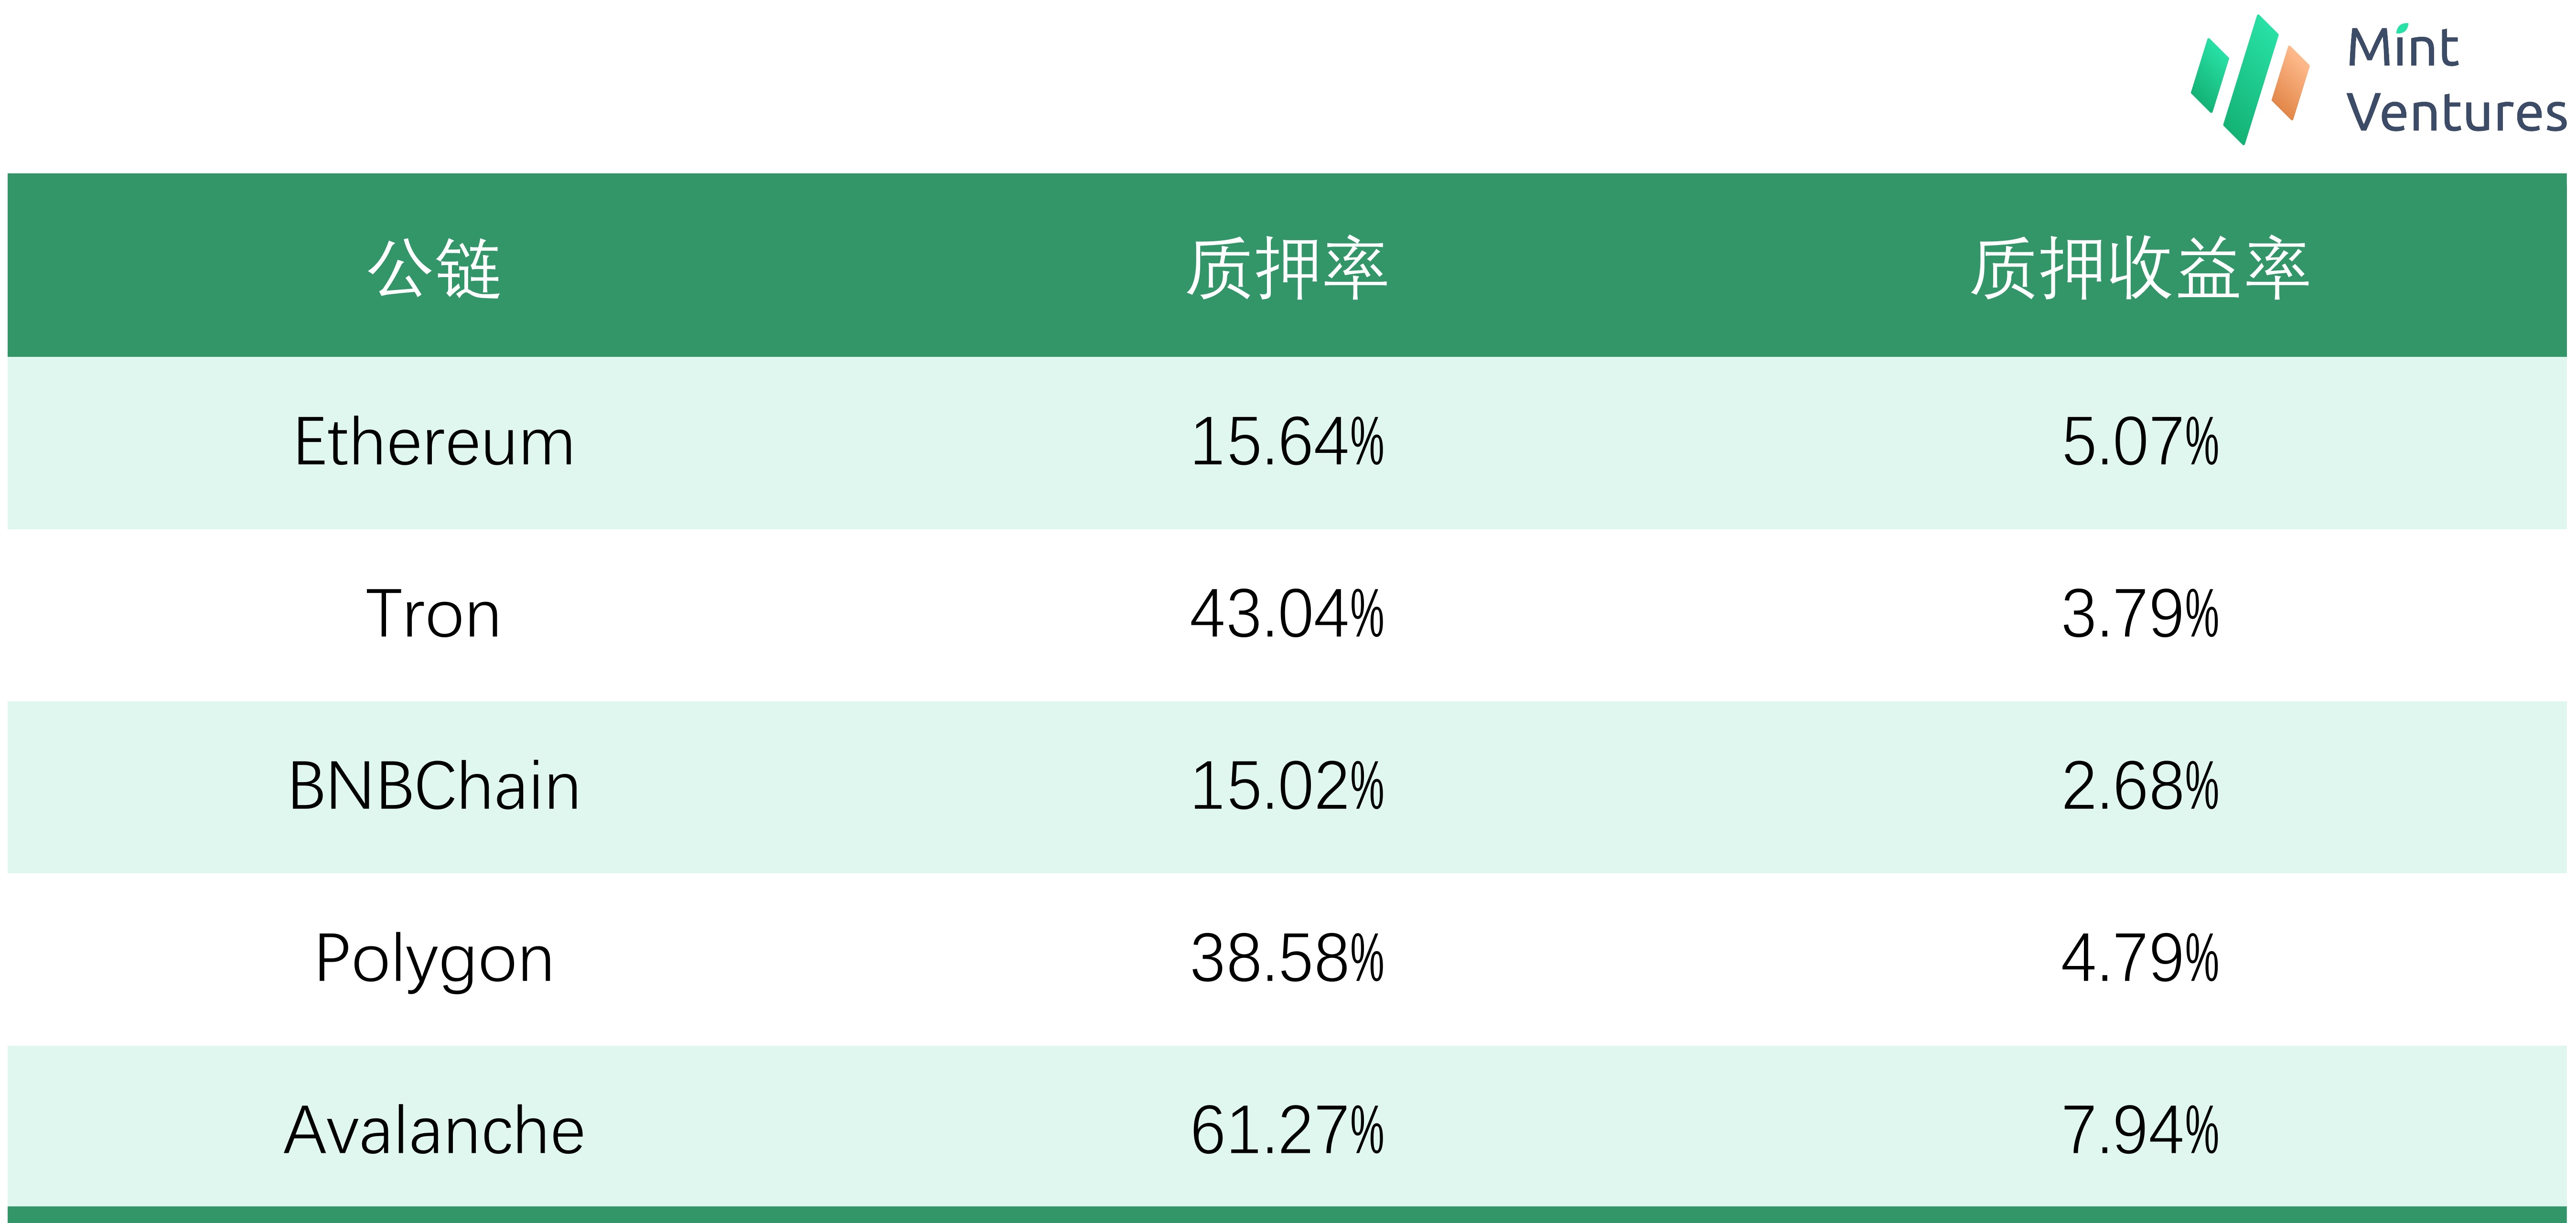
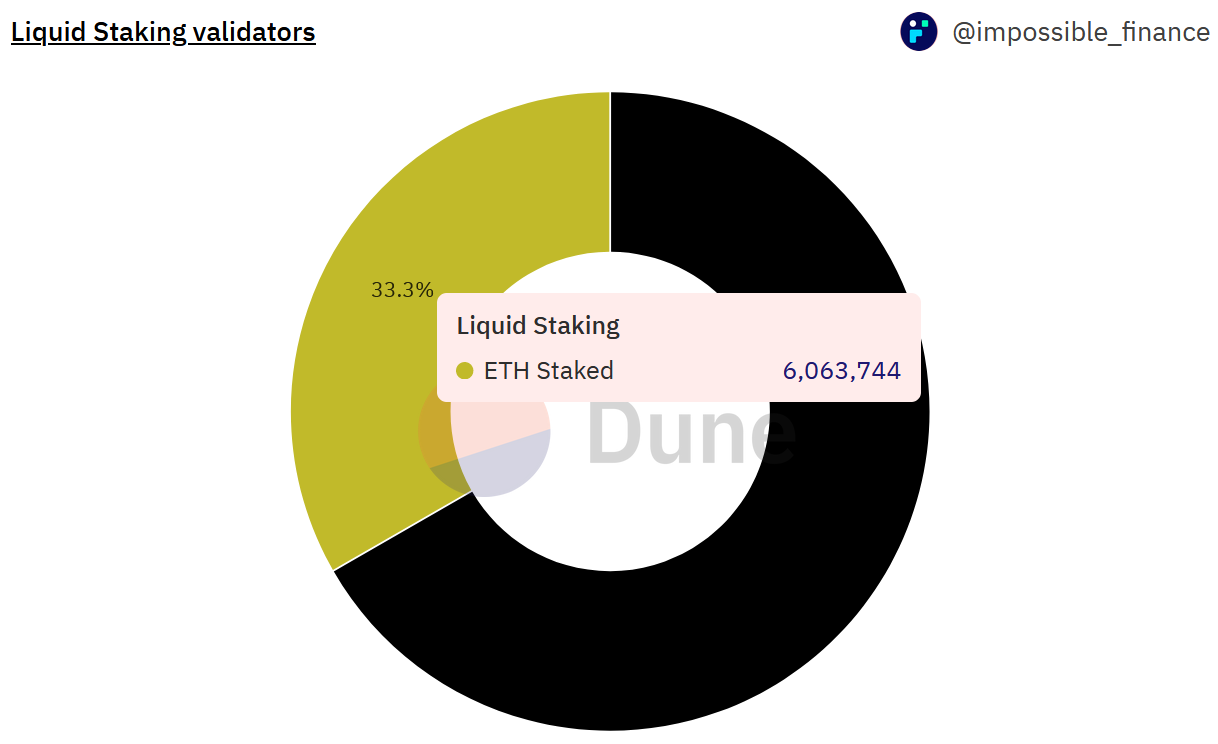
Judging from the TOP 5 public chain projects that currently have the highest TVL ranking and can be pledged, the average pledge rate at this stage is about 35%. Public chains including Ethereum still have a lot of room for growth.
image description
source:
source:https://dune.com/impossiblefinance/liquid-staking-derivatives
Second, let's look at the LSD LP token market
source:
source:https://dune.com/LidoAnalytical/Lido-Finance-Extended
source:https://dune.com/LidoAnalytical/stETH-deposited-per-protocol
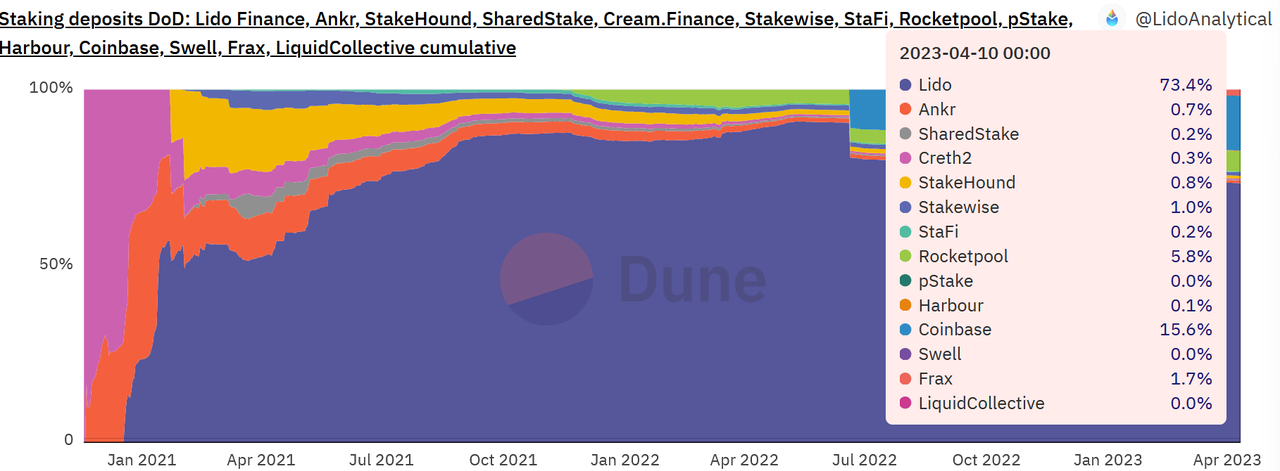
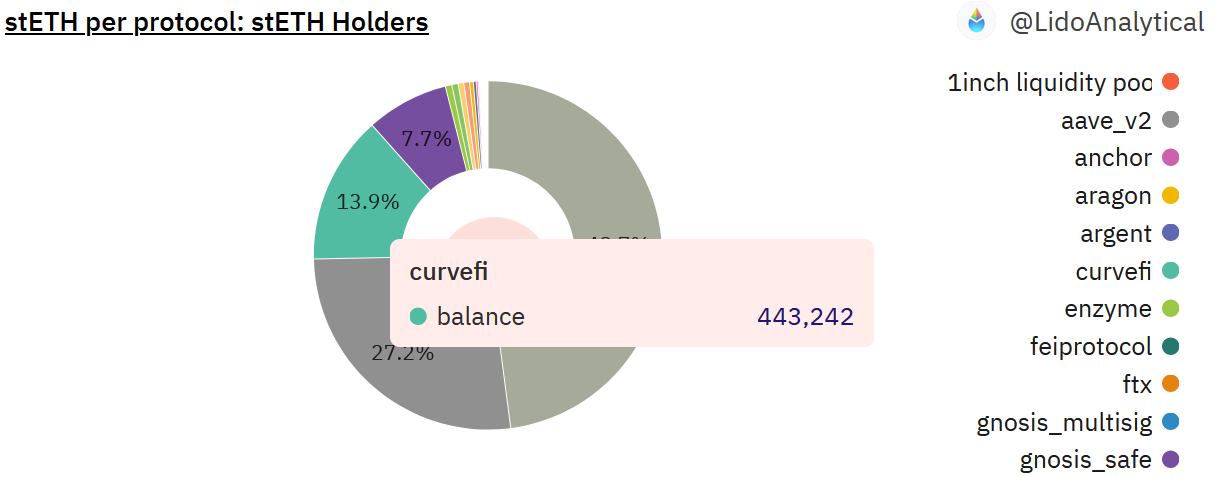
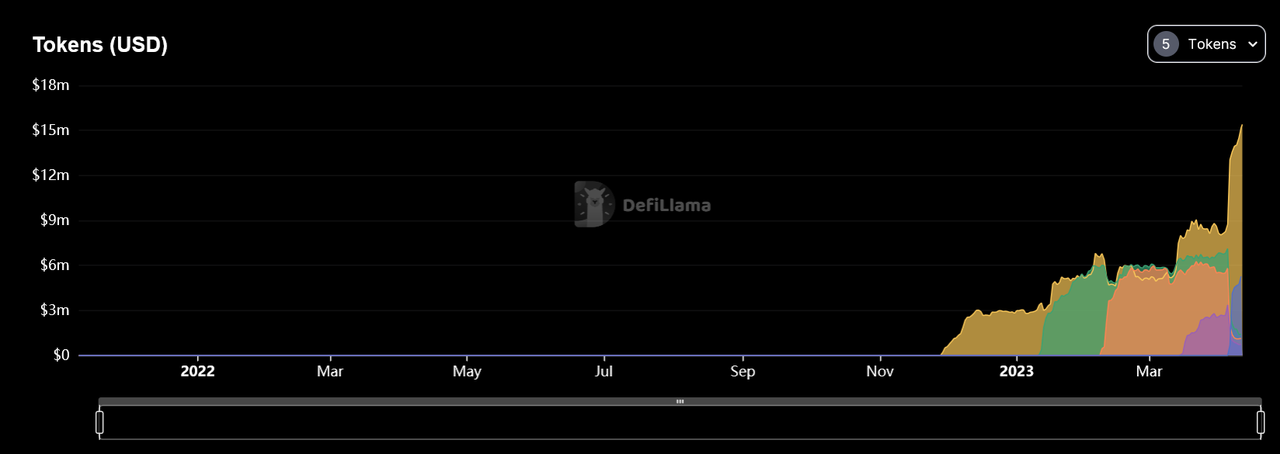
If Lido’s market share does not decline significantly in the future, and the destination of LSD in DEX is mainly Curve, then in the future, about 3.9 billion U.S. dollars of LSD will form LPs and exist in Curve, and the corresponding market value of LPs is about 7.8 billion U.S. dollars. Then the total size of LSD+LSD LP is close to $46 billion. This size will increase further as the market capitalization of Ethereum increases, the pledge rate increases, and more and more LSD will be added to the DEX.
source:
source:https://defillama.com/protocol/pendle
The third is the LP token market for stablecoins
source:
source:https://defillama.com/protocol/pendle
The fourth is the medium risk market of GLP and gDAI
source:
source:https://defillama.com/protocol/pendle
source:
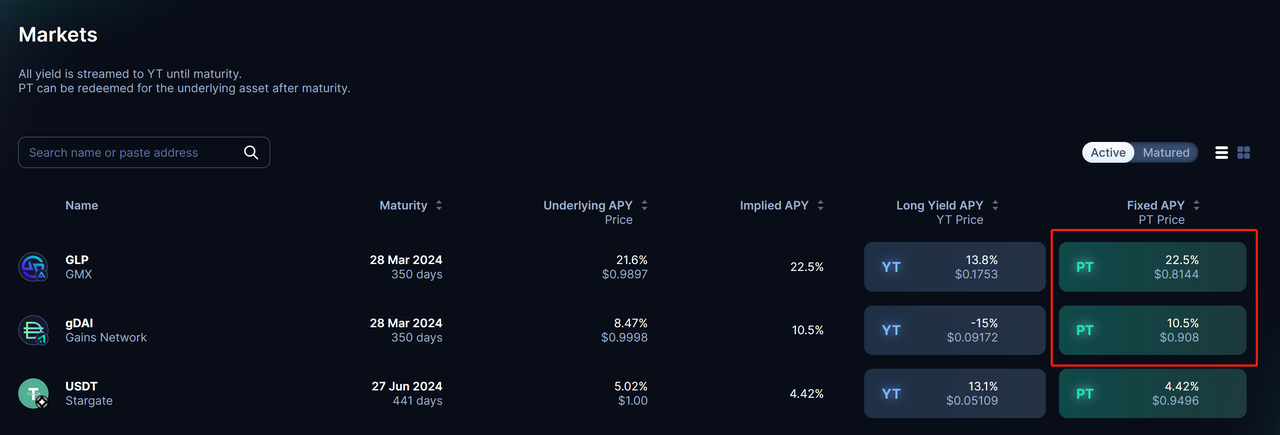
source:https://app.pendle.finance/pro/markets
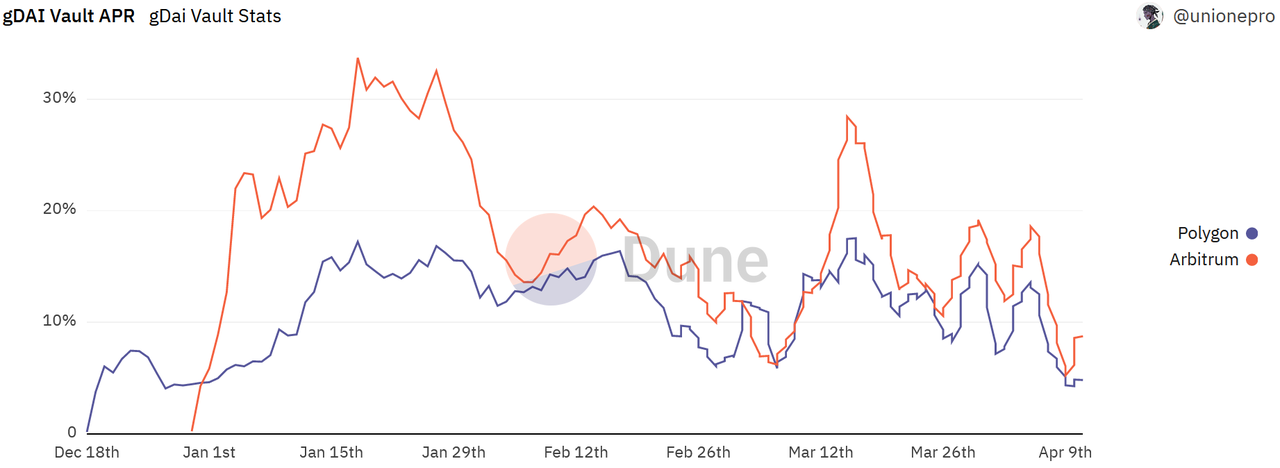
source:https://dune.com/unionepro/Everthing-Gains-Network
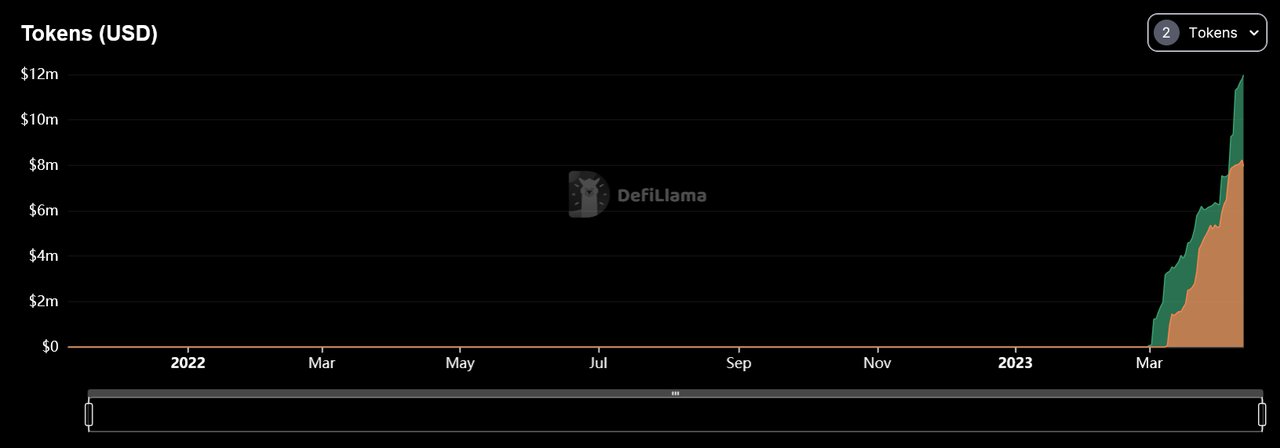
However, among similar derivatives at present, only GMX and its imitation disk have run through the business scale. Therefore, the development space of this part of the business is limited by the development of this type of project. In the short term, the market space may be within US$1 billion.
Finally, there are high-risk fixed-income markets such as APE and LOOKS
source:
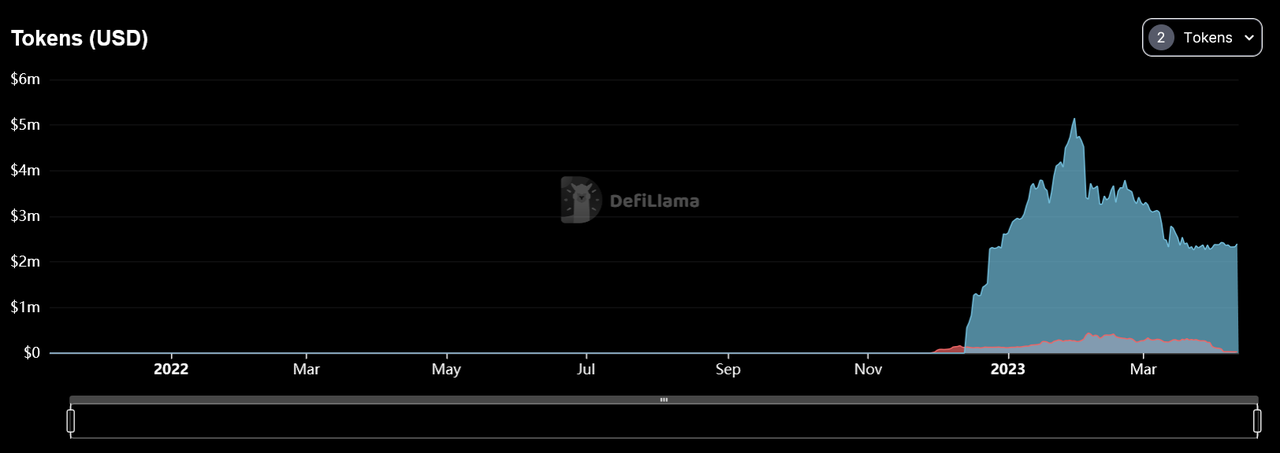
source:https://defillama.com/protocol/pendle
However, the strategy of this type of pool may not be to expect a single pool to grow to a large market value, but to compete for speed: once a token with a higher market value and higher pledge income appears, it should quickly deploy the fixed income of the token transaction pool. A single pool may end up with a TVL of only a few million to tens of millions of dollars, but since there are a series of similar pools, the combined TVL will be higher.
Whether it is low risk or high risk, there are other strategies with different risks and benefits in the market, which can be included in the scope of Pendle in the future.
3.6 Business data
source:
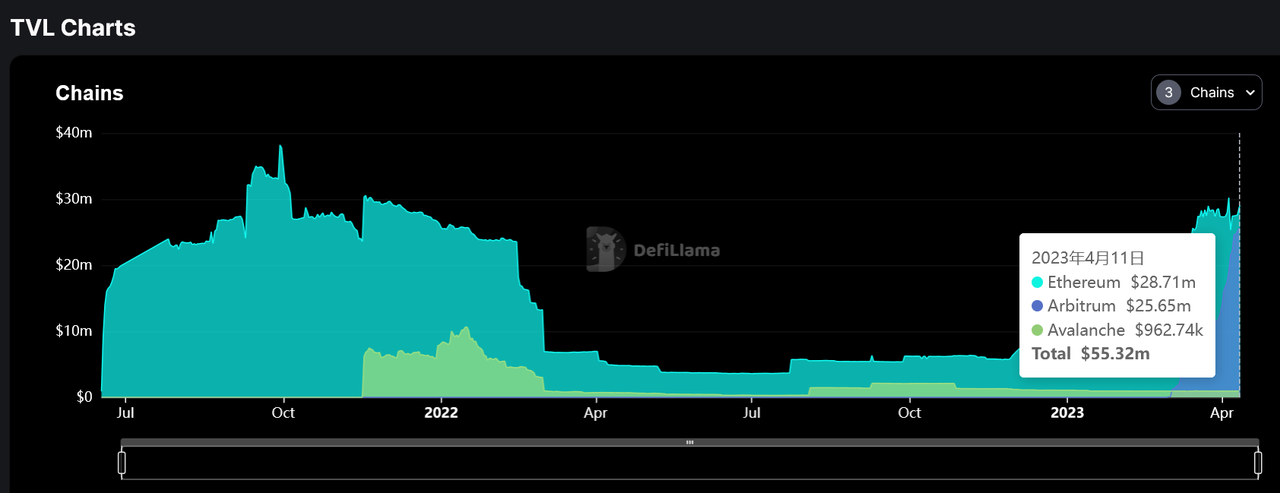
source:https://defillama.com/protocol/pendle
source:
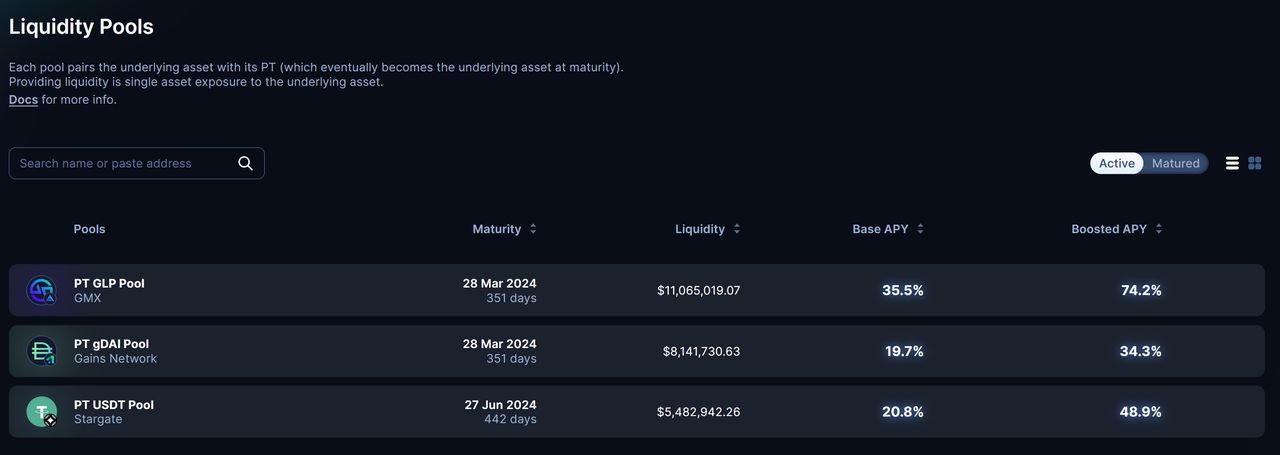
source:https://app.pendle.finance/pro/pools
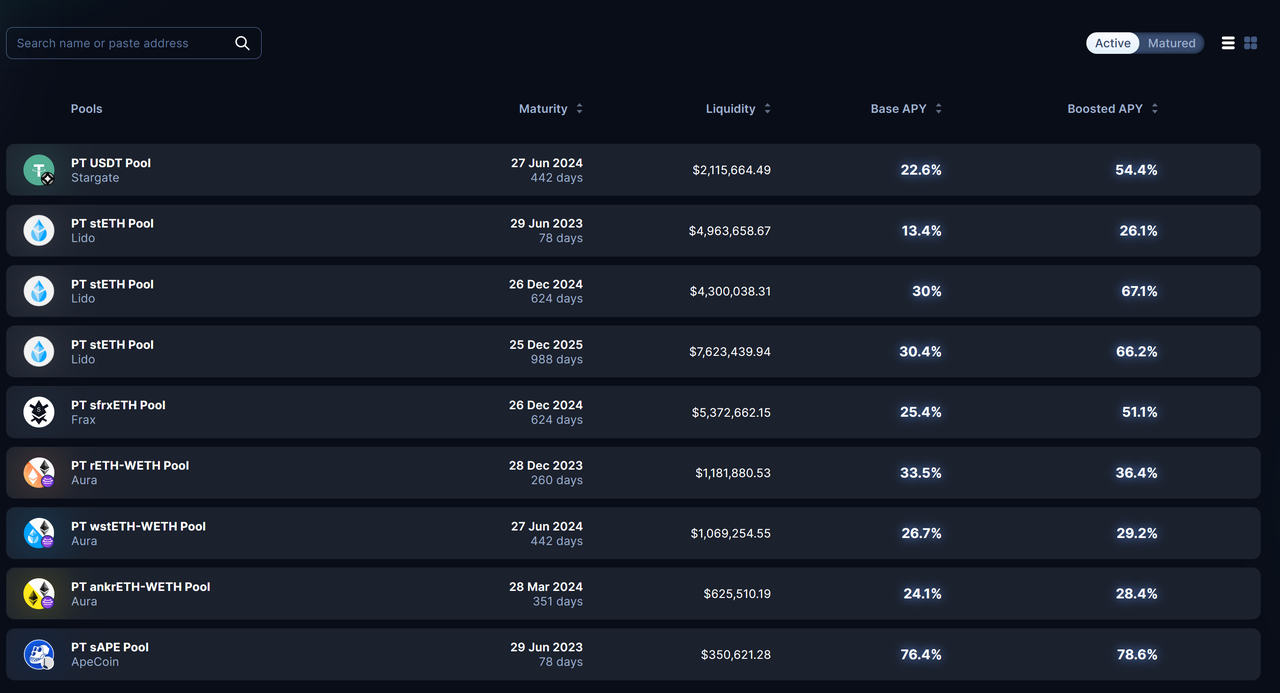
source:https://app.pendle.finance/pro/pools
secondary title
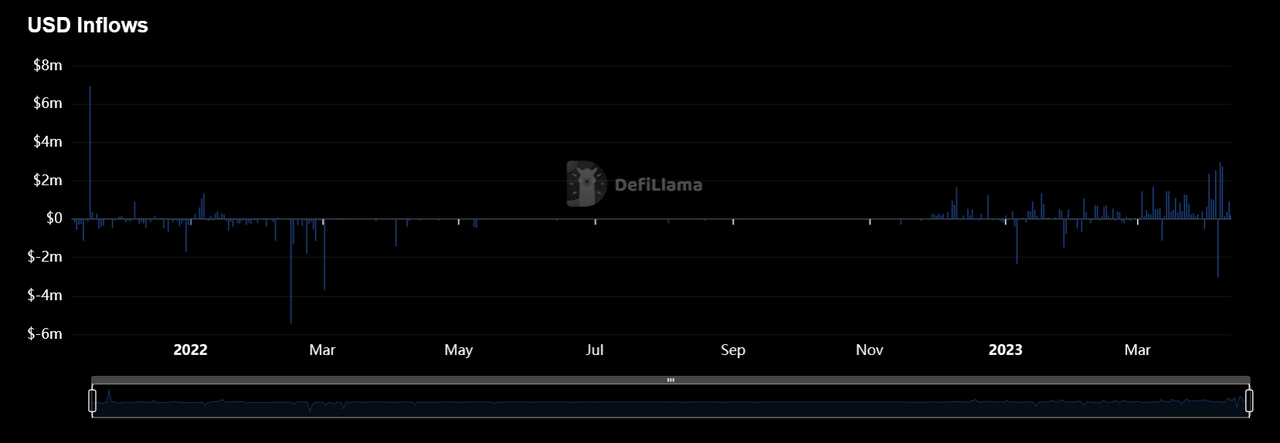
source:https://defillama.com/protocol/pendle
3.7 Project Competition Landscape
There are also Swivel Finance, Delv (Element Finance), APwine, and Sense Finance that are deeply involved in the fixed income market based on income tokenization. The differences between them can be seen from the two simple dimensions of TVL and product line.
3.7.1 TVL
image description
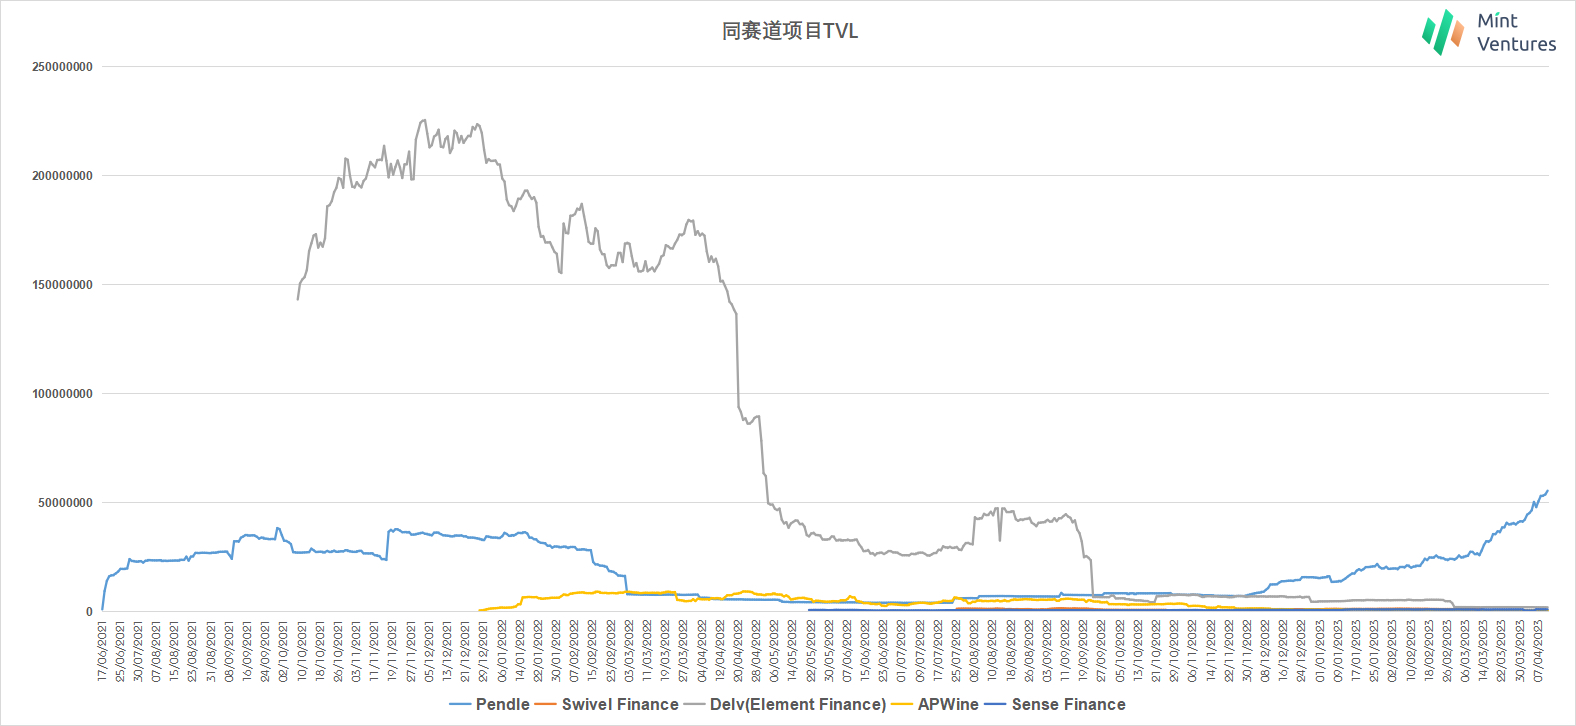
Source: DeFi Llima, Mint Ventures, data as of April 11, 2023
image description
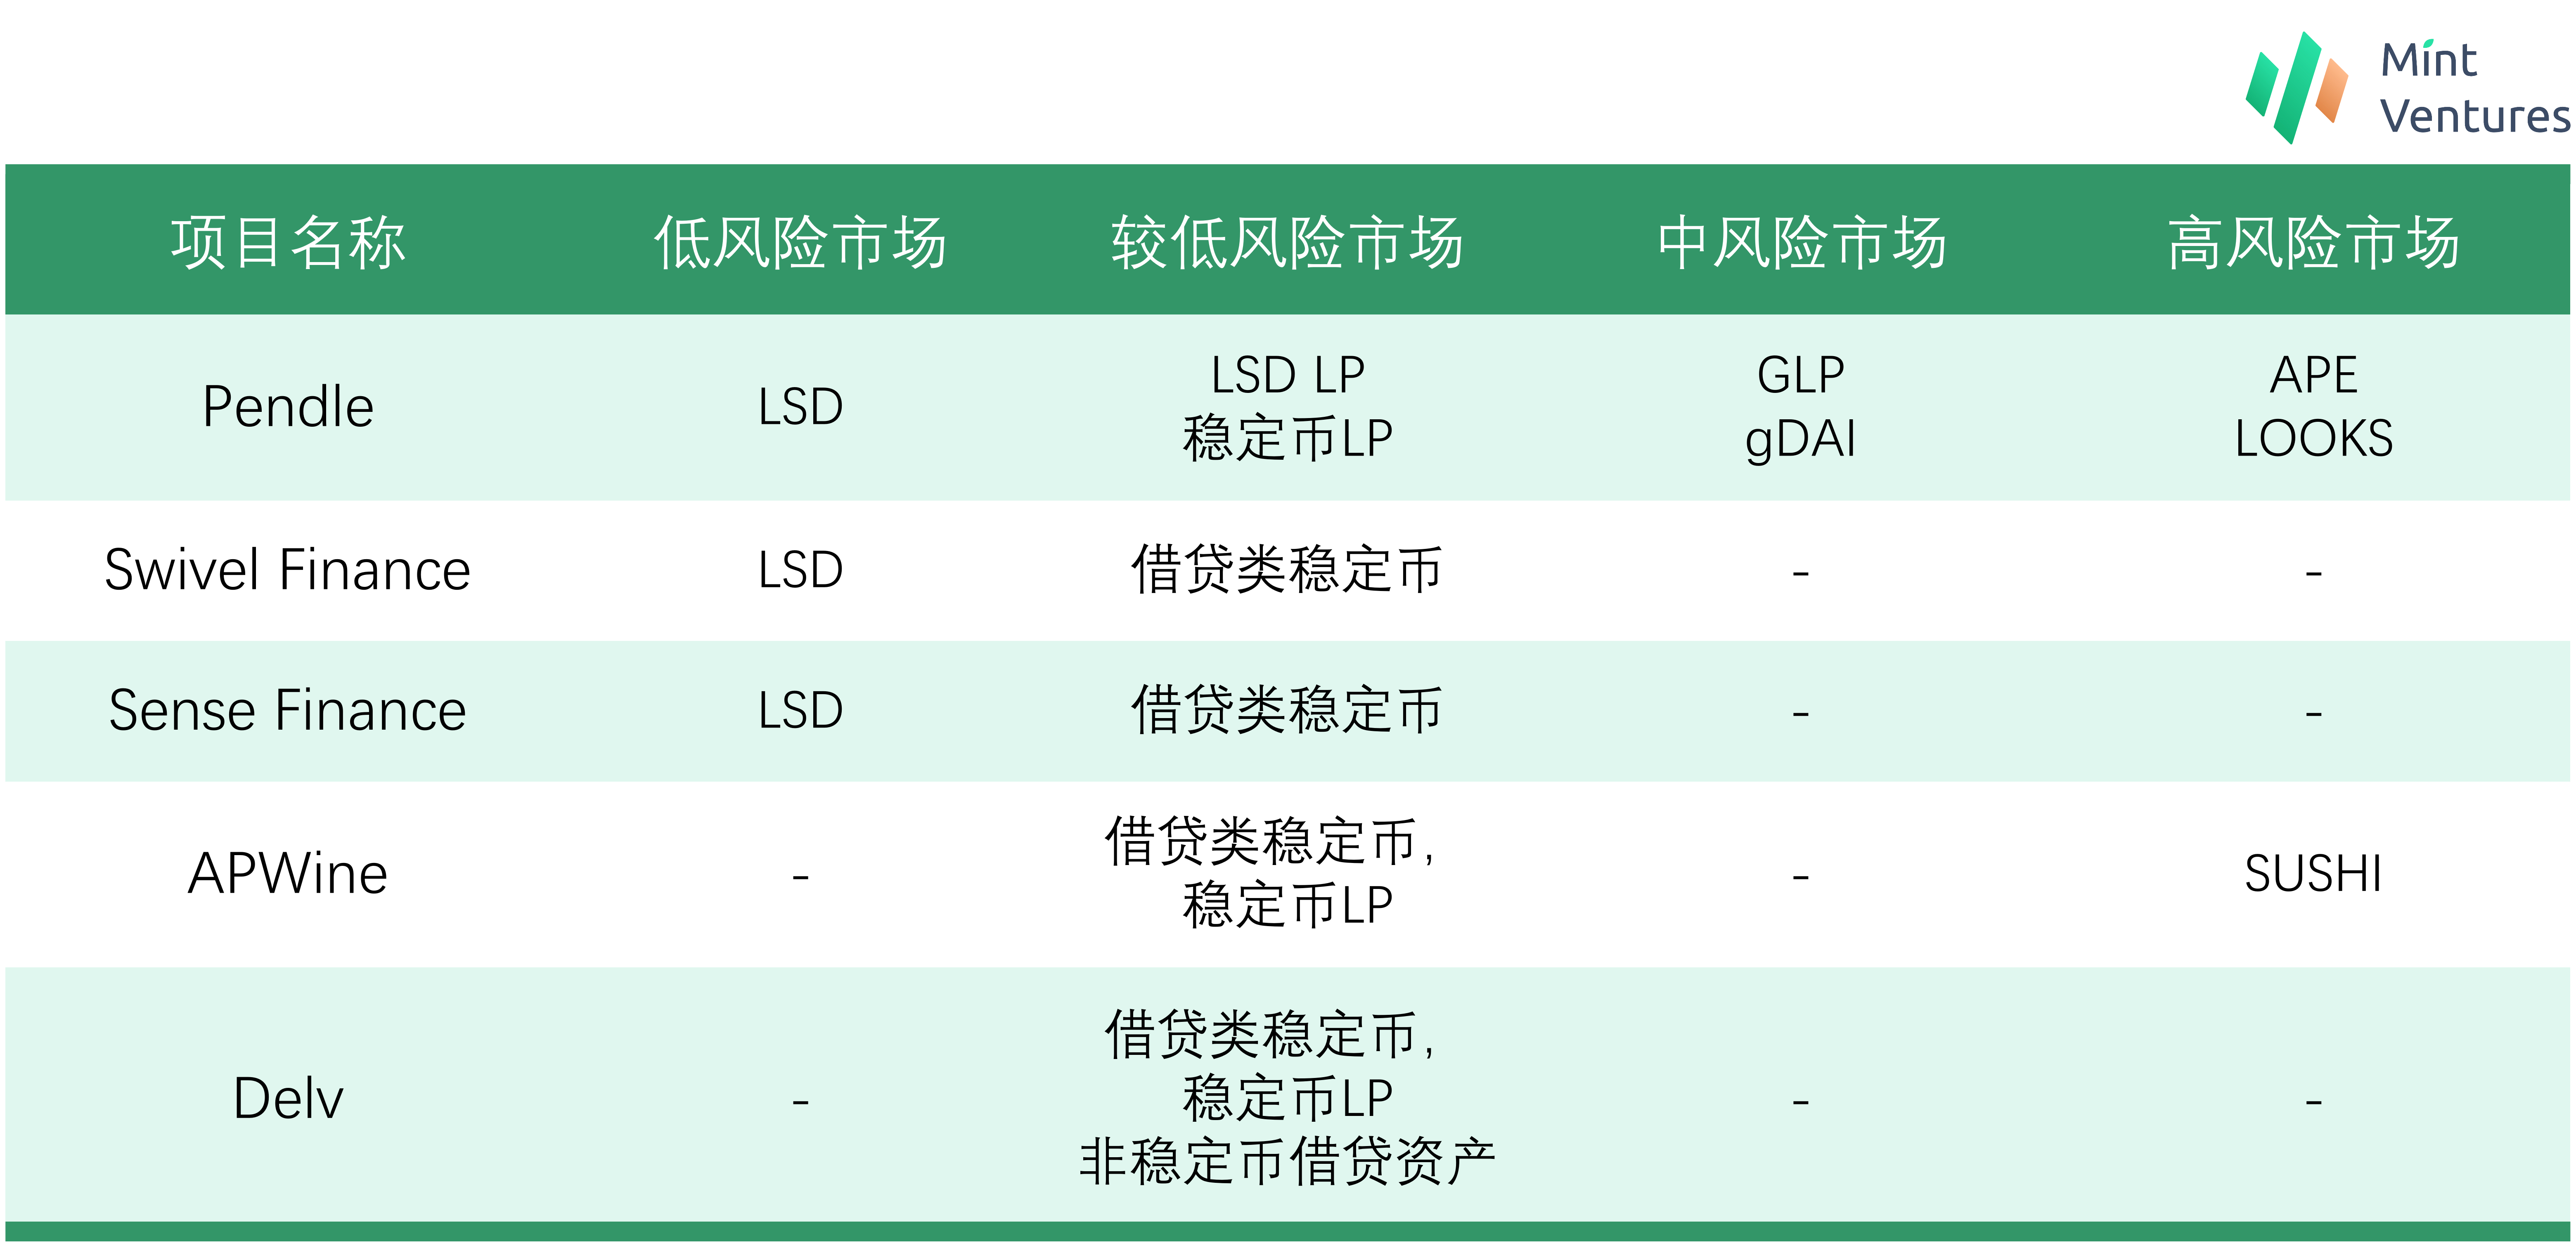
Source: Project websites, Mint Ventures, data as of April 11, 2023
Judging from the distribution of product lines, APWine and Delv did not choose the right target. In the current encryption ecosystem, only LSD has no counterparty risk and can support long-term value capture.
It is a good strategic move for Swivel Finance and Sense Finance to incorporate LSD into the underlying assets, but they can also try to incorporate LSD’s LP tokens or LSD’s lending tokens into the ecology. Taking Lido as an example, 15% of its stETH is in Curve As an LP in China, nearly 30% of stETH is used as collateral in Aave.
secondary title
3.8 Token Model Analysis
3.8.1 Total amount and distribution of tokens
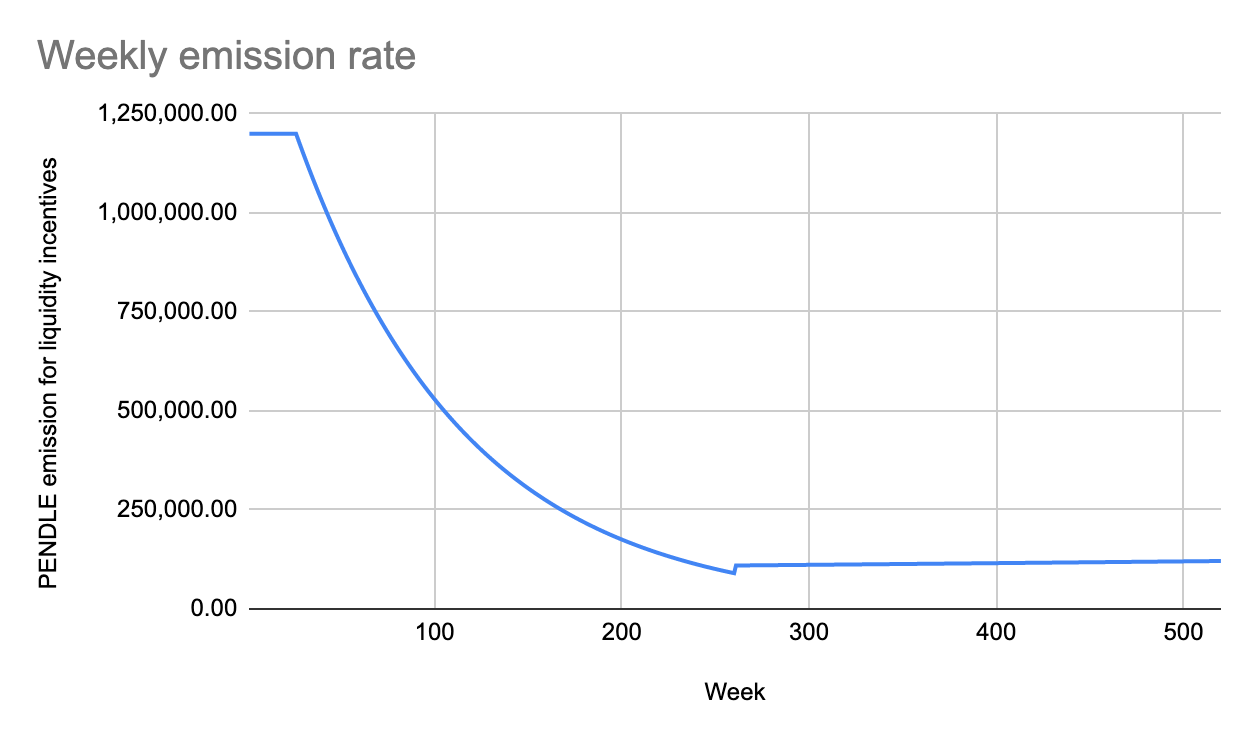
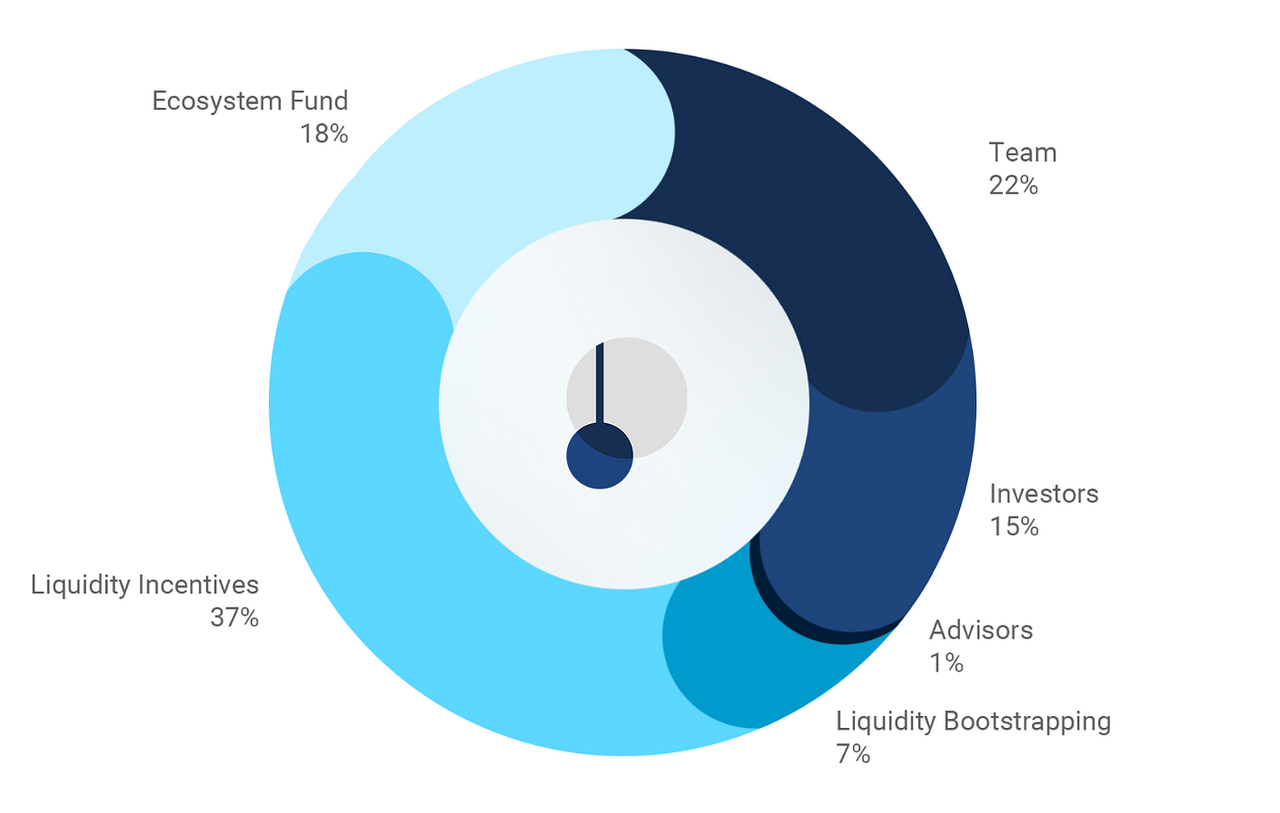
There is no upper limit on the token supply of PENDLE, and the release is divided into 3 stages:
First 26 weeks: release 1.2 million PENDLE per week;
Weeks 27 to 260: 1% reduction in weekly release;
source:
source:https://medium.com/pendle/pendle-tokenomics-3a33d9caa0e4
source:
source:https://medium.com/pendle/pendle-tokenomics-3a33d9caa0e4
Among this:
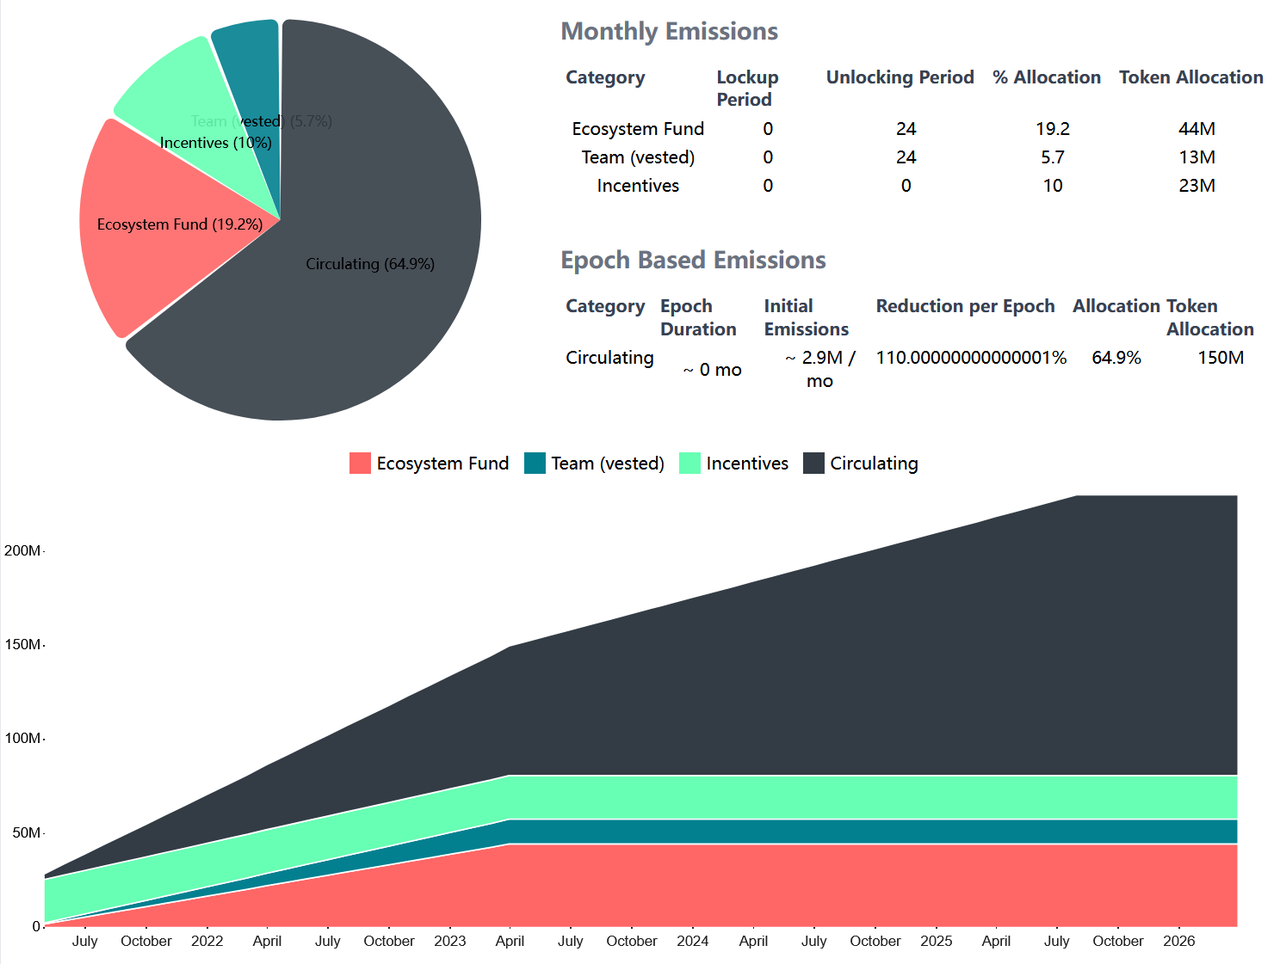
Tokens held by the team: will be unlocked quarterly linearly one year after the tokens are launched, and will be unlocked in two years. According to the latest situation, all will be unlocked in April 2023;
Tokens held by investors and consultants: 3 months after the launch of liquidity mining incentives, they will be unlocked linearly, and they have all been released;
source:
source:https://www.tokenomicshub.xyz/posts/pendle
3.8.2 Token Value Capture
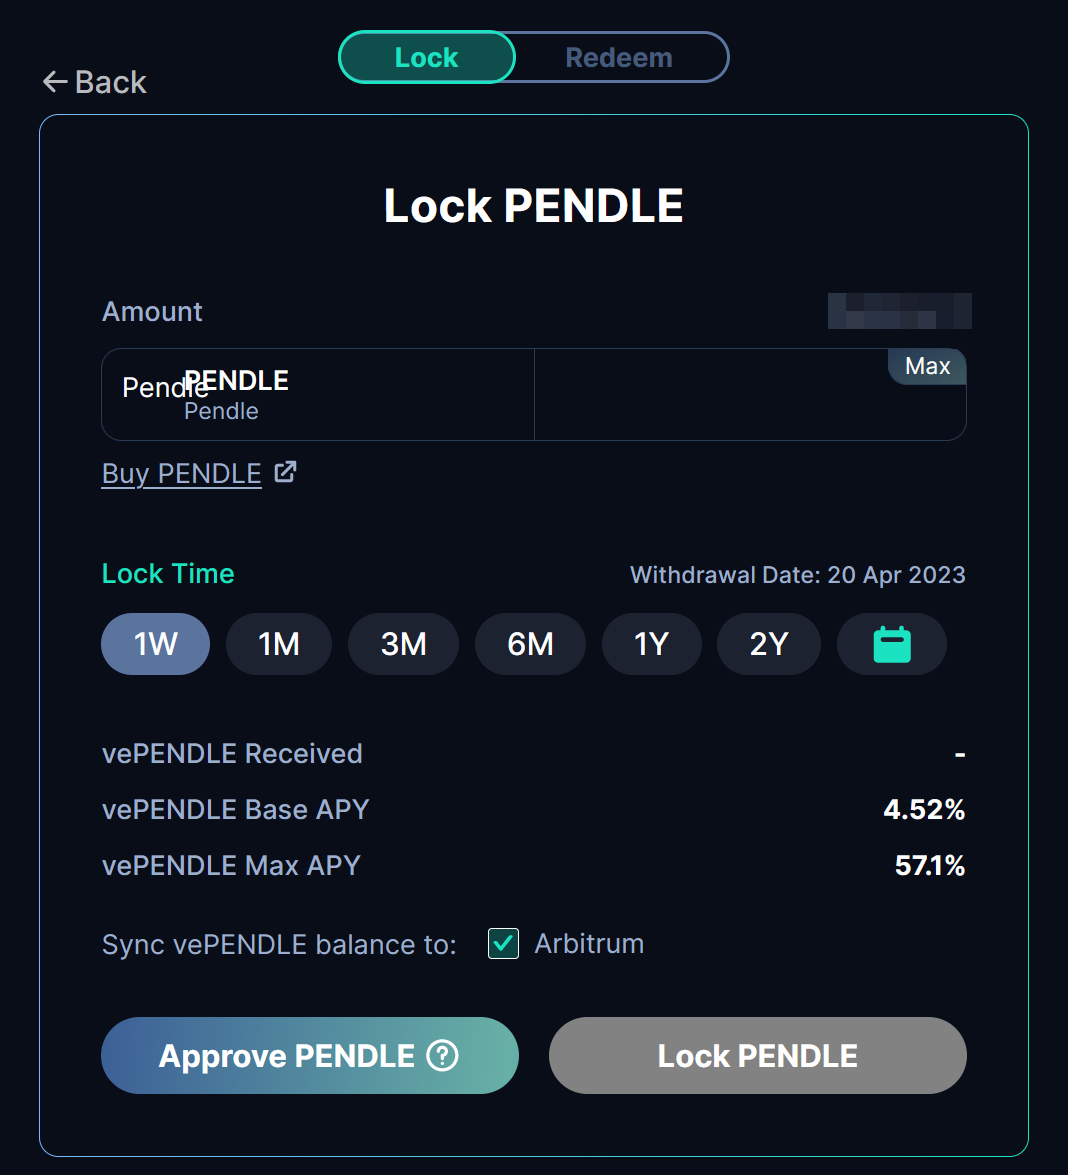
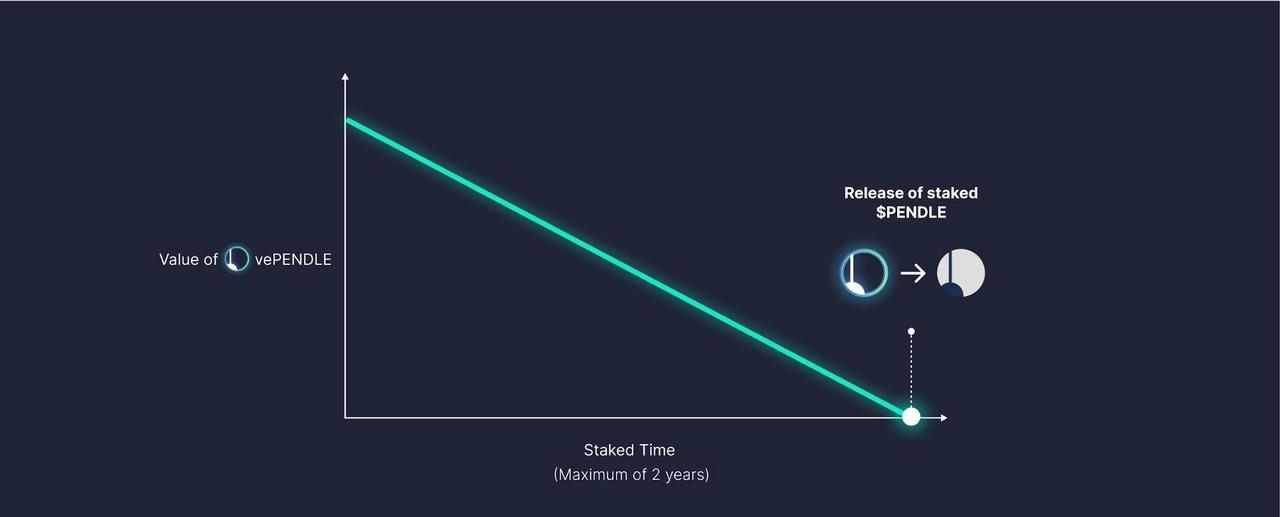
In the V1 version, PENDLE is just a utility and governance token, and its main function is to participate in project governance. However, at that time, the Pendle team had noticed the advantages of the Ve model in governance, and left a window for improving the token mechanism with reference to the Ve model.
source:
source:https://app.pendle.finance/vependle/lock/update
source:
source:https://docs.pendle.finance/Governance/vePENDLE
In terms of value capture, first of all, holders of vePENDLE can participate in the distribution of handling fees and income.
Holders of vePENDLE can vote to decide which pool to reward and get part of the income in the pool: 3% of the income generated from YT will be distributed to the vePENDLE holders who voted for the pool. If the PT is not redeemed by the user after the expiration, the income generated after the expiration will also be distributed to the vePENDLE holders who voted for the pool.
Currently, in the pool on the Ethereum chain, most of them are liquid mortgage derivatives of ETH, with a TVL of about 24 million US dollars. Assuming that these assets provide an annualized rate of return of 5%, vePENDLE holders can be allocated to: 2400* 5% * 3% = $36,000;
Currently, in the pool on the Arbitrum chain, there are only GLP and gDAI, and the TVL is about 20 million US dollars. According to the past data of the two projects, assuming that these two projects can provide an annualized rate of return of 15%, vePENDLE holders can distribute To: 2000* 15% * 3% = $90,000. In addition, 80% of the transaction fees generated by each pool will be distributed to the vePENDLE holders who voted for that pool.
Since the beginning of the year, the average daily trading volume of Pendle is about 400,000 US dollars, and the transaction fee rate is 0.1%. If the average daily trading volume remains unchanged and calculated according to this ratio, the annual income that can be provided to vePENDLE holders is: 40 **365** 0.1% * 80% = $117,000.
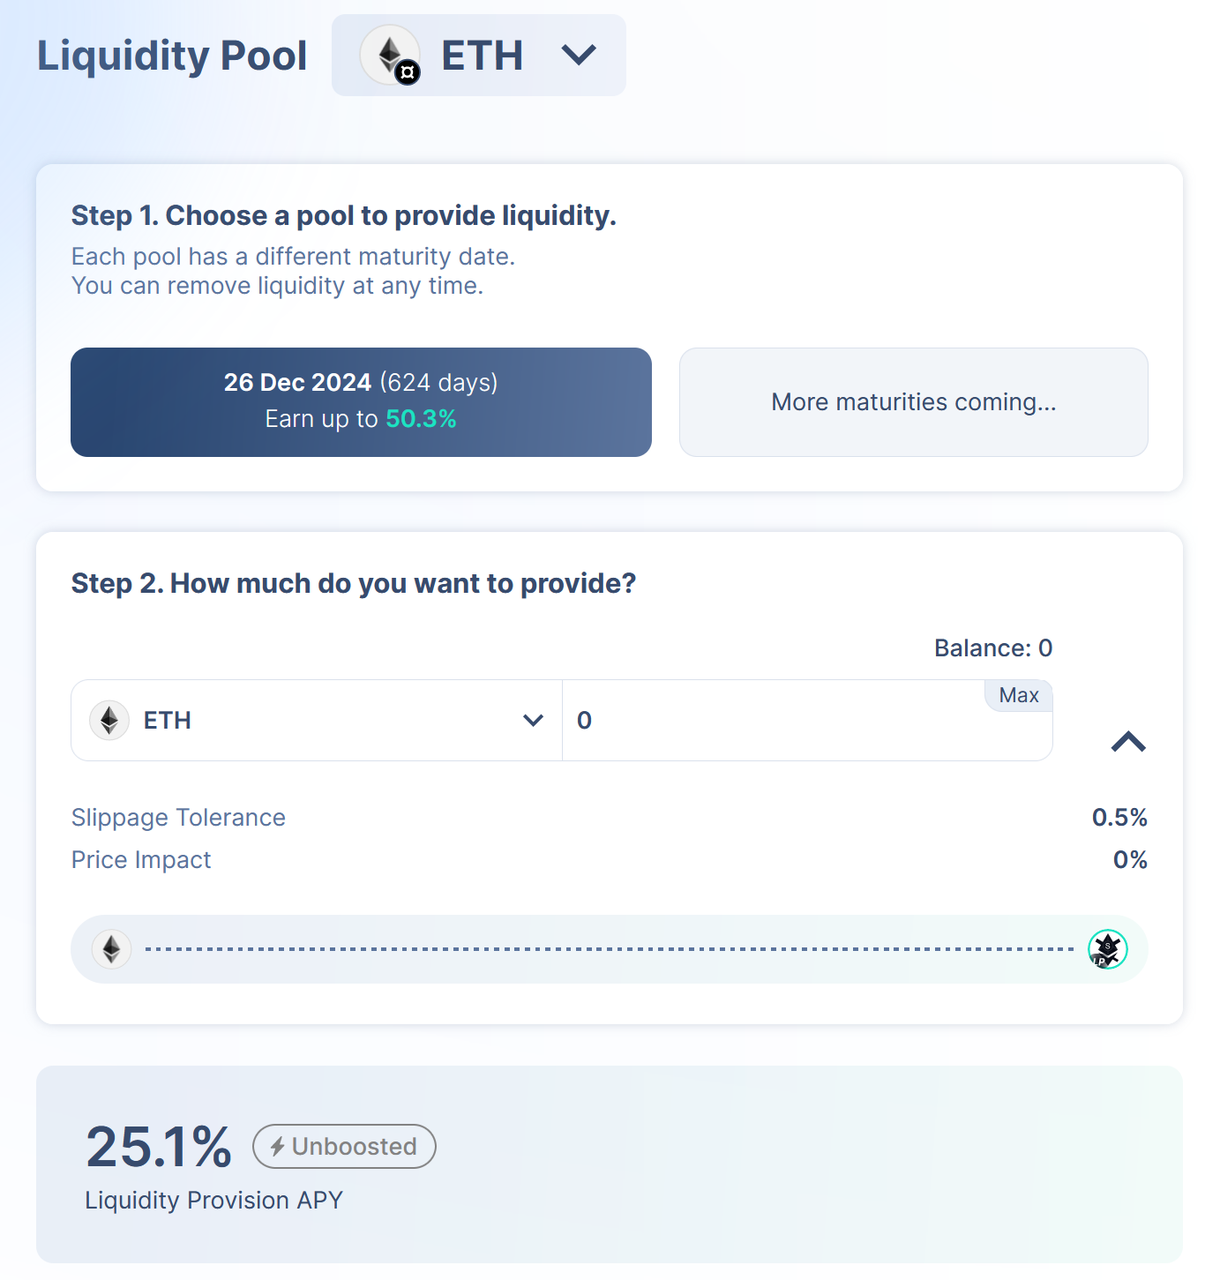
If there were no significant changes in the business, vePENDLE would generate approximately $243,000 in gross proceeds a year. Secondly, in addition to charging fees and benefits, if the holder of vePENDLE is also an LP, they can get up to 250% of Pendle emission incentives.
source:
source:https://app.pendle.finance/simple/pools/0xfb8f489df4e04609f4f4e54f586f960818b70041
source:
source:https://app.pendle.finance/vependle/overview
3.8.3 Token core demand side
After adopting the vePENDLE model, the demand side for PENDLE becomes more diverse:
Liquidity Provider (LP): For LPs, the adoption of vePENDLE will significantly increase the rate of return. Some investors may choose to buy PENDLE and lock their positions. At the same time, vePENDLE can also obtain the income of the pool and some handling fees;
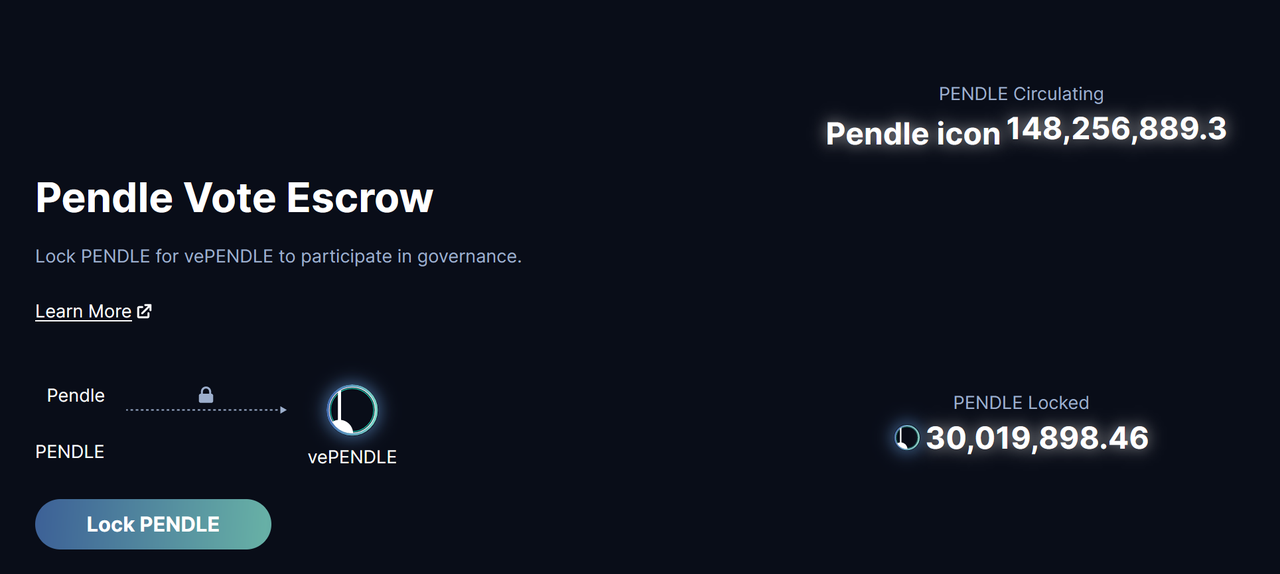
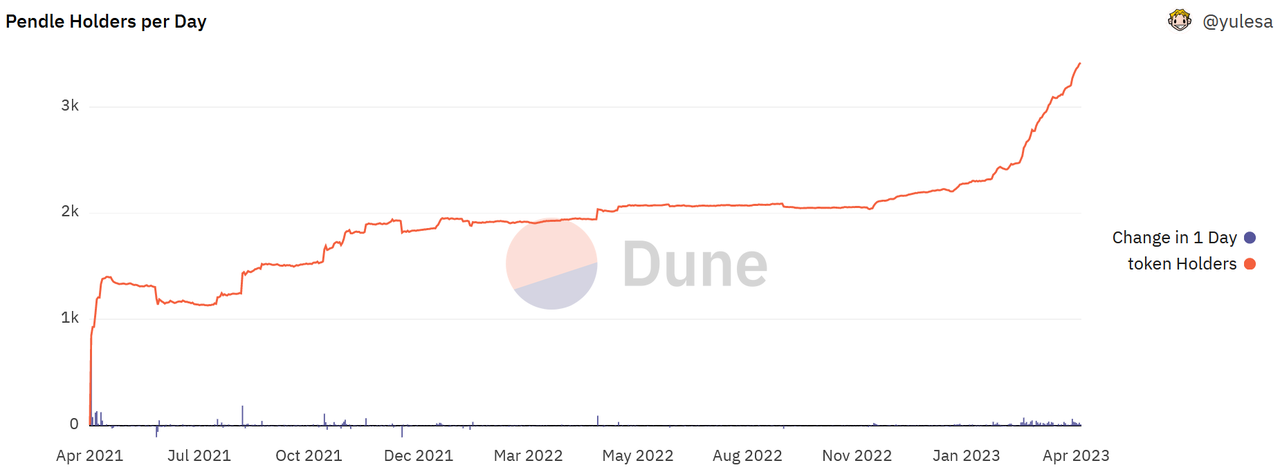
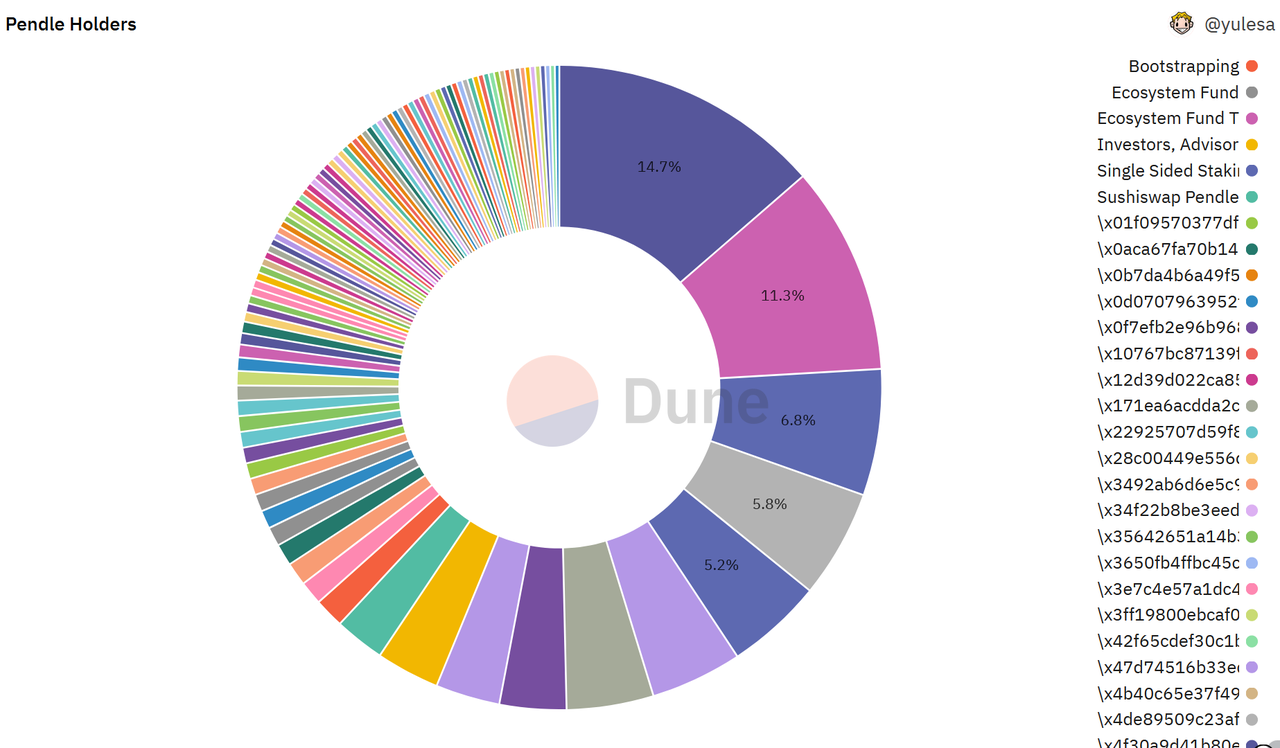
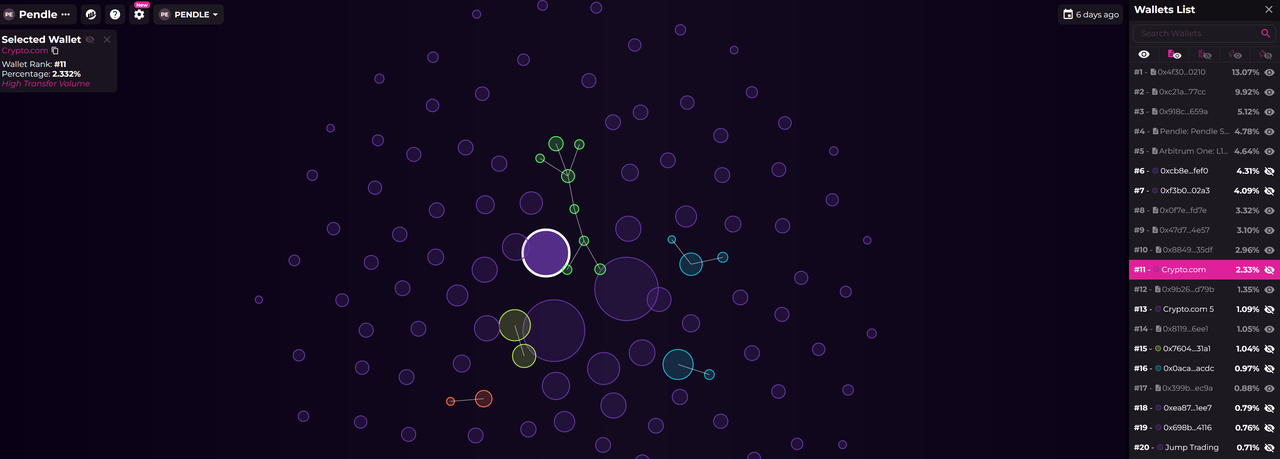
Long-term investors of PENDLE tokens: Since PENDLE can obtain service fees and revenue sharing, PENDLE has become attractive to some investors who want to obtain long-term cash flow, and this part of investors may also include PENDLE tokens own investment scope. However, considering that the current estimated annual income of vePENDLE is only about US$200,000, which is insignificant compared to this part of locked PENDLE, holders of PENDLE are more likely to care about future growth.
source:
source:https://dune.com/yulesa/Pendle
source:
source:https://dune.com/yulesa/Pendle
source:https://app.bubblemaps.io/eth/token/0x808507121b80c02388fad14726482e061b8da827?mode=3
3.8.4 Summary of Token Model
secondary title
3.9 Risk Analysis
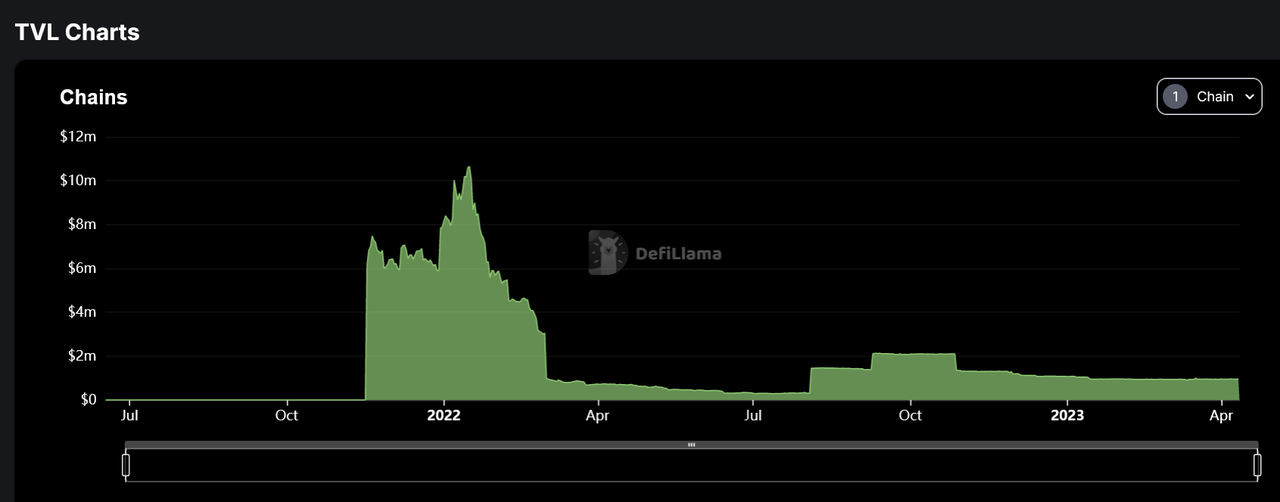
Contract risk: There have been many hacking incidents recently, and the stolen amount is also in the hundreds of millions of dollars. The types of stolen projects are not limited to decentralized exchanges and lending agreements. If such an event occurs, it will have a significant impact on the normal operation of the project and the capture of token value. This risk is not limited to Pendle itself. Since Pendle’s underlying assets come from other projects, any contract risks in other projects will also involve Pendle, resulting in the shrinking of Pendle’s business and operations.
source:
source:https://defillama.com/protocol/pendle
Market risk: The price of some underlying assets, such as GLP, is not anchored to the US dollar or public chain tokens, and is in a relatively floating state, and it is not easy to hedge. This is not friendly to U-standard investors. If the market drops sharply during the operation of the project, resulting in a drop in the price of GLP denominated in U.S. dollars, especially YT investors, may suffer large losses, which may cause users to lose to other relatively safe projects.
secondary title
4.1 Core Issues
What operating cycle is the project in? Is it a mature stage, or an early and middle stage of development?
After about 2 years of development, the project team’s ability to select underlying assets has been improved. By learning other excellent AMM models, it has also improved the user’s transaction experience and reduced costs. Compared with other projects on the same track, the product is in period of rapid growth. However, the tokenization of income and the track of fixed income are still in the early stages of DeFi.
Does the project have a solid competitive advantage? Where does this competitive advantage come from?
Part of the core strengths of DEXs come from trading models and asset classes. Judging from the current AMM model mechanism adopted by Pendle, it has certain advantages. In the choice of asset class, LSD is used as the basic market, which ensures that the project will have a relatively stable income even in a bear market, and can retain some investors. The Pendle team also needs to further improve the innovation ability of the model and the identification ability of the underlying assets, so that it is possible to continue to maintain a leading position in the competition of the revenue tokenization track.
Is the long-term investment logic of the project clear? Is it in line with the general trend of the industry?
The rate of return of PT is close to the annualized return of low-risk arbitrageurs, and YT can satisfy high-risk investors' game on the market. The current "low-medium-high" asset class is suitable for selection, which is relatively close to the composition of investors in the current market.
What are the main variables in the operation of the project? Is this factor easy to quantify and measure?
The main variables remain the optimization of the AMM model and the choice of asset class. Both of these factors can be observed through transaction and product popularity.
How will the project be managed and governed? How is the DAO level?
secondary title
4.2 Valuation level
image description
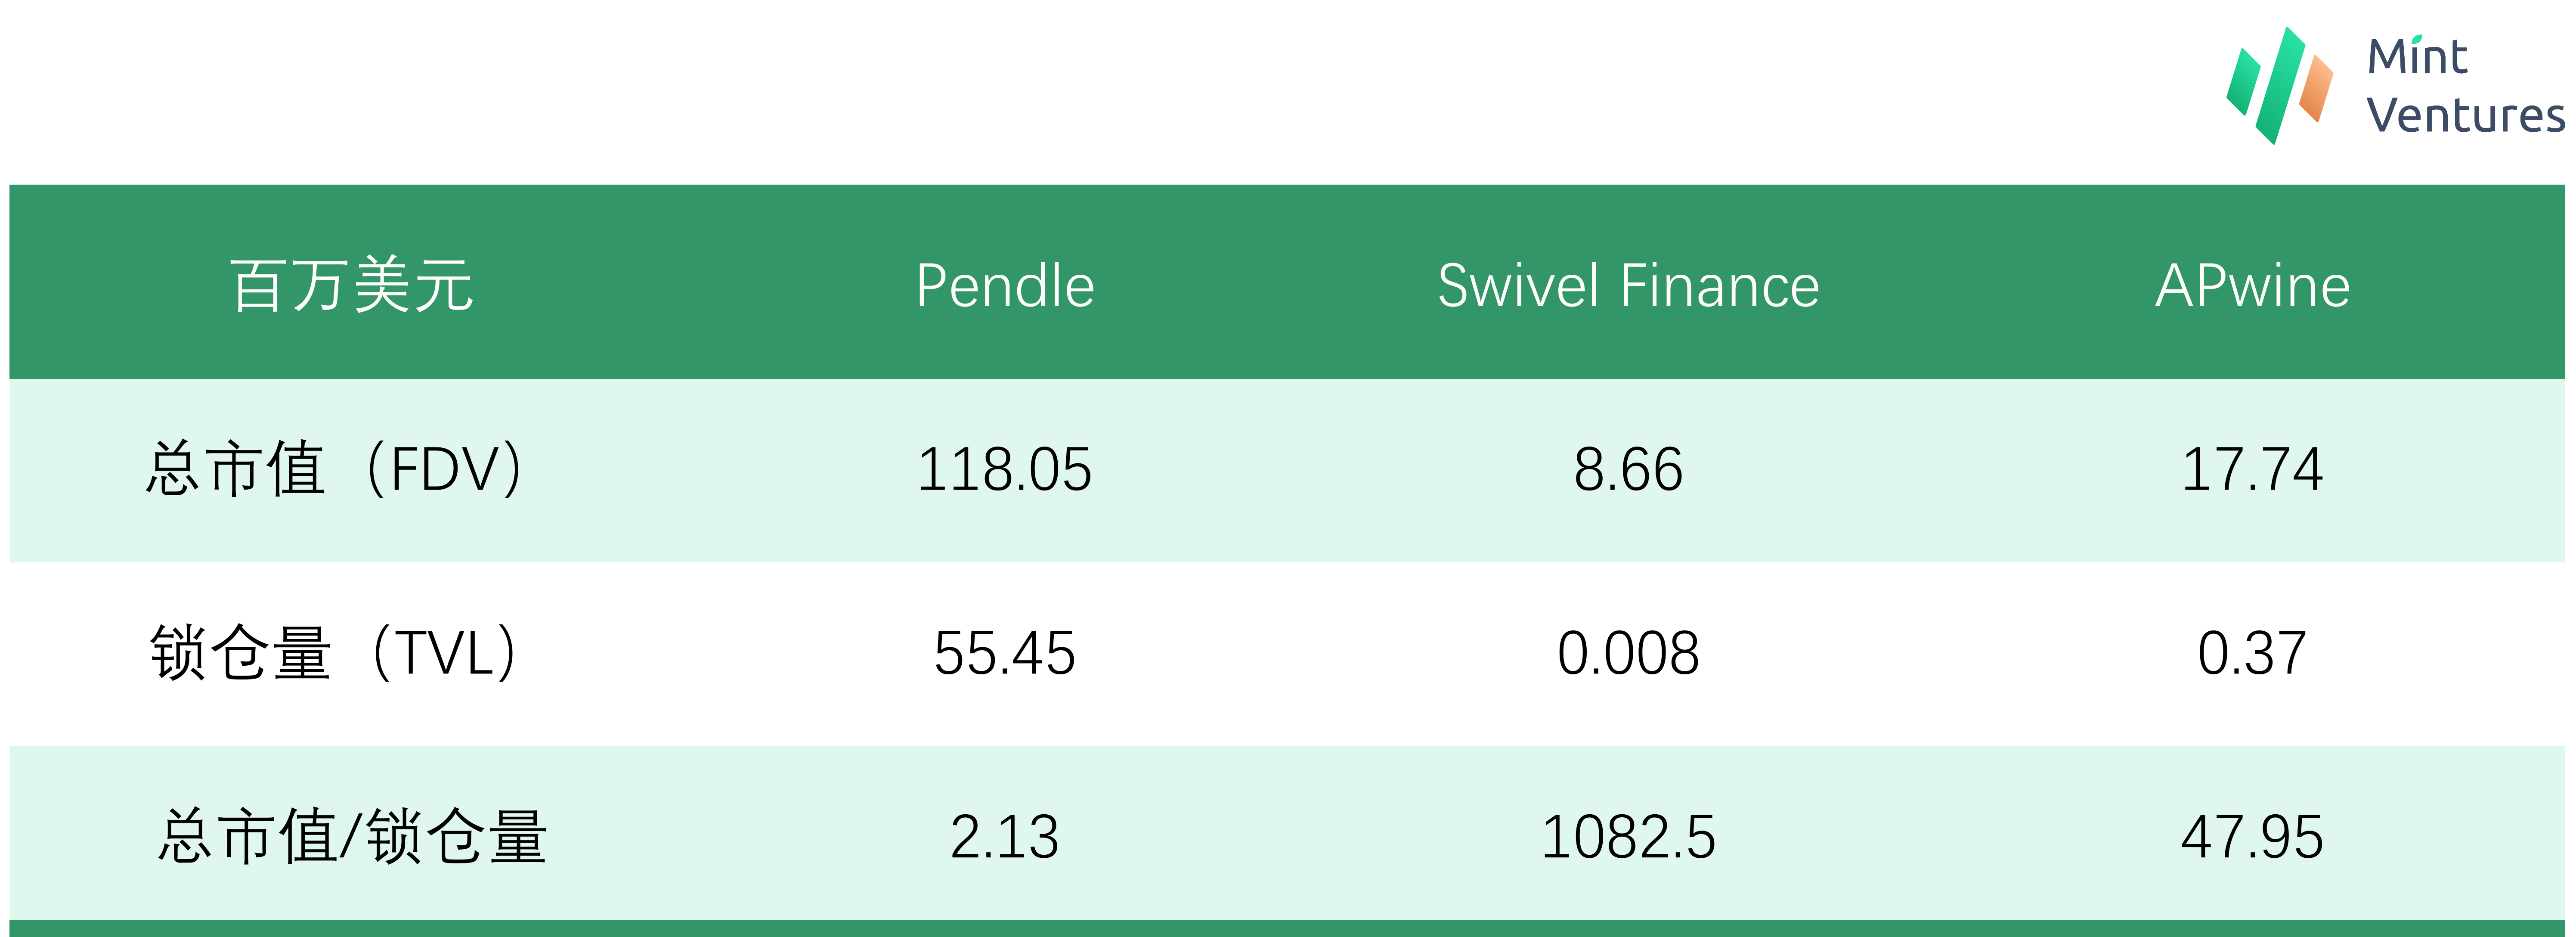
Data sources: Coingecko, DeFi Llama, Mint Ventures, data as of April 11, 2023
5. References
https://medium.com/pendle/pendle-tokenomics-3 a 3 3d 9 caa 0 e 4
https://medium.com/pendle/treasury-management-with-pendle-x-benqi-f 495250940 a 2
https://medium.com/pendle/pendle-and-the-qi-musketeers-8 f 08435 2c 249
https://medium.com/pendle/pendle-and-the-3-joesephs-dee 7 c 645 ff 12
https://medium.com/pendle/pendle-x-rari-fuse-pool-6016713 a 0 d 2
https://medium.com/pendle/pendle-x-olympus-pro-6 abc 640 f 4730
https://medium.com/pendle/apecoin-market-launch-f 39294872976
https://medium.com/pendle/apecoin-compounder-by-pendle-af 5 bd 60814 f 1
https://medium.com/pendle/pendle-2021-wrapped-c 91 b 805 2d efb
https://medium.com/pendle/pendle-on-avalanche-8028 fc 42957 e
https://ethereum-magicians.org/t/eip-5115-super-composable-yield-token/9423
https://medium.com/pendle/pendle-v2-part-1-3-foundation-6 e 1773 a 1 d 2 f 4
https://medium.com/pendle/pendle-v2-part-2-3-open-access-25 c 1783 a 0 b 4 f
https://medium.com/pendle/pendle-v2-launch-part-3-3-updated-tokenomics-b 6 c 6501 b 8286
https://medium.com/pendle/pendle-v2-part-1-3-foundation-6 e 1773 a 1 d 2 f 4
https://raw.githubusercontent.com/pendle-finance/pendle-v2-resources/main/whitepapers/V2_AMM.pdf
https://handbook.pendle.finance/liquidity-provision/simple-lp-zap
https://dune.com/impossiblefinance/liquid-staking-derivatives
https://dune.com/LidoAnalytical/stETH-deposited-per-protocol