


Gate Institutional Weekly Report: BTC Briefly Breaks $81,000, SOL Staking Assets Outperform ETH (August 24 – August 30, 2026)


- Core View: Hawkish rate expectations and elevated inflation have once again dominated macro pricing. The crypto market has shifted from broad momentum chasing to high-level structural rotation, with capital moving from BTC leveraged momentum plays toward ETH, SOL staking assets, and Meme retail frontends, while institutional allocation has become more selective.
- Key Elements:
- U.S. July PCE came in at 3.7% year-over-year and core PCE at 3.3%, both unchanged from the prior reading. Warsh's hawkish remarks boosted September rate hike expectations, pushing the 2-year U.S. Treasury yield up to approximately 4.36%.
- BTC ETF weekly net inflows fell to approximately $925 million (-51.79% week-over-week), while ETH ETF inflows rose to approximately $816 million (+17.77%), reflecting cooling institutional appetite for chasing BTC and stronger absorption of ETH.
- BTC OI declined from approximately $13.4 billion midweek to approximately $12.4 billion, with funding rates mildly positive. The long structure has not reversed, but incremental leverage momentum has weakened.
- Total stablecoin supply increased by approximately $1.73 billion for the week, with incremental growth spreading toward institutional settlement and yield-bearing assets such as RLUSD, USD1, and BUIDL.
- SOL staking assets clearly outperformed ETH, with the Bitwise Solana Staking ETF surpassing $1 billion in scale. Proposal SGP-0002 is expected to reduce SOL issuance by approximately 18.9 million tokens over six years.
- Pump revenue rose to approximately $16.28 million (+19.0%), approaching Hyperliquid's $16.77 million, with Meme frontends becoming a major source of profit growth.
- BTC DVOL declined from around 43 to approximately 37, and 25D Skew recovered to approximately -3%. Short-term protection increased, but the volatility risk premium converged.
Summary
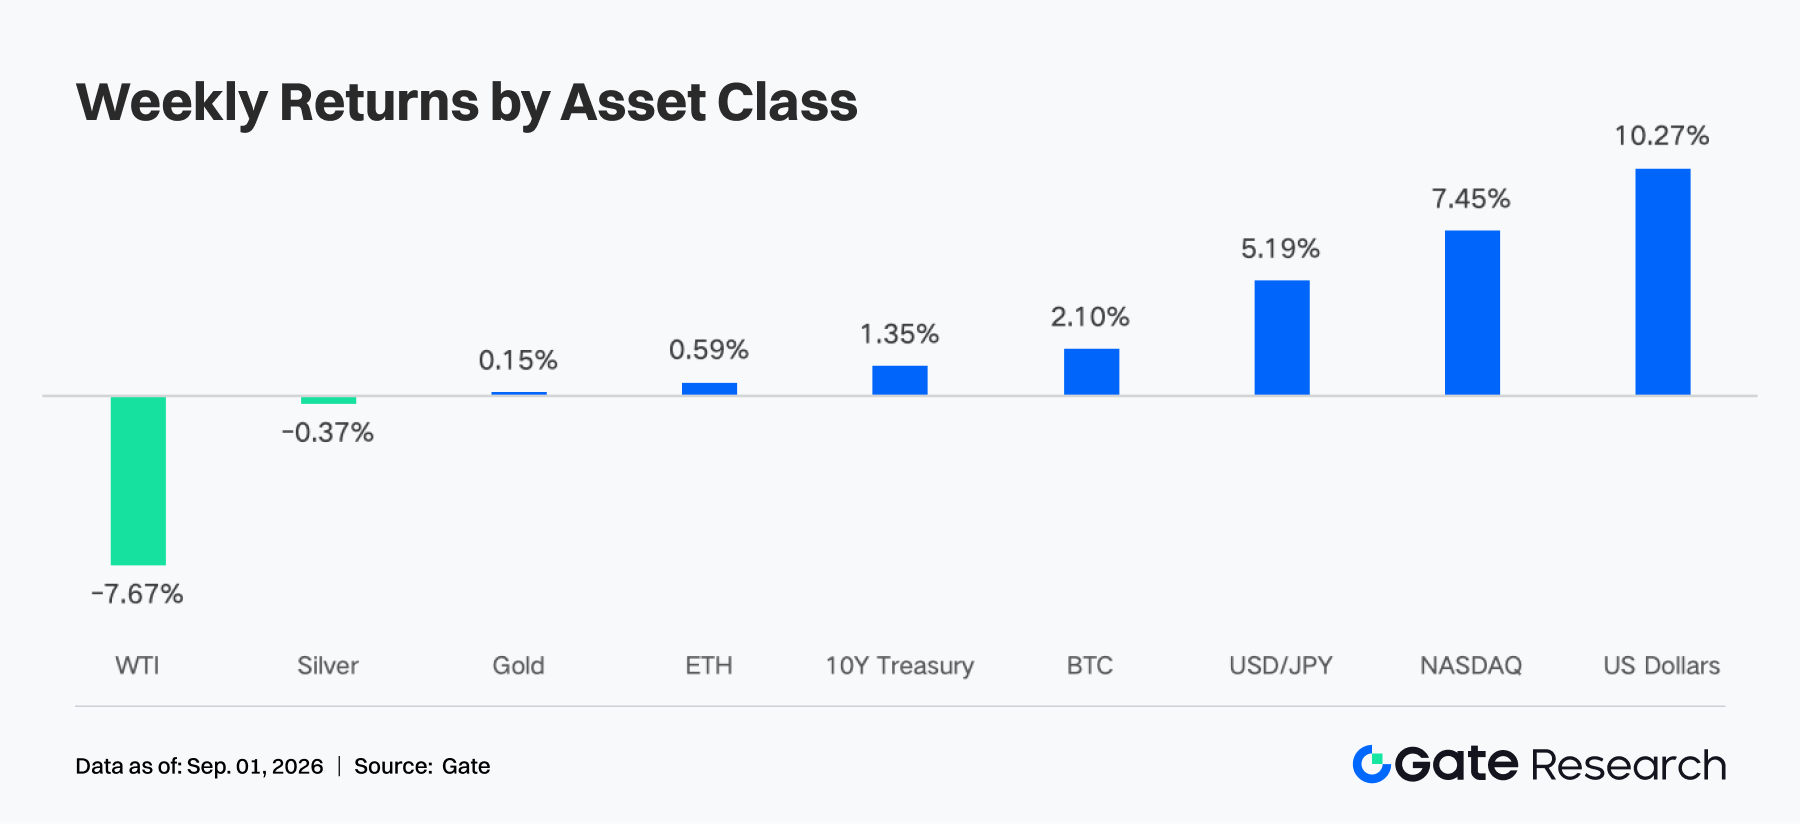
• Hawkish expectations have once again dominated macro pricing, with PCE inflation remaining elevated. Warsh's hawkish remarks boosted expectations for a September rate hike, pushing short-end US Treasury yields and the dollar higher. The crypto market entered a phase of high-level structural rotation, with BTC briefly breaking above 81,000 USDT; BTC and ETH posted weekly gains of 2.10% and 0.59%, respectively.
• ETF flows shifted from chasing rallies to selective allocation. BTC ETF weekly net inflows fell to approximately $925 million, down 51.79% from the prior week, while ETH ETF net inflows rose to approximately $816 million, indicating cooling institutional appetite for chasing BTC higher and stronger capital absorption into ETH.
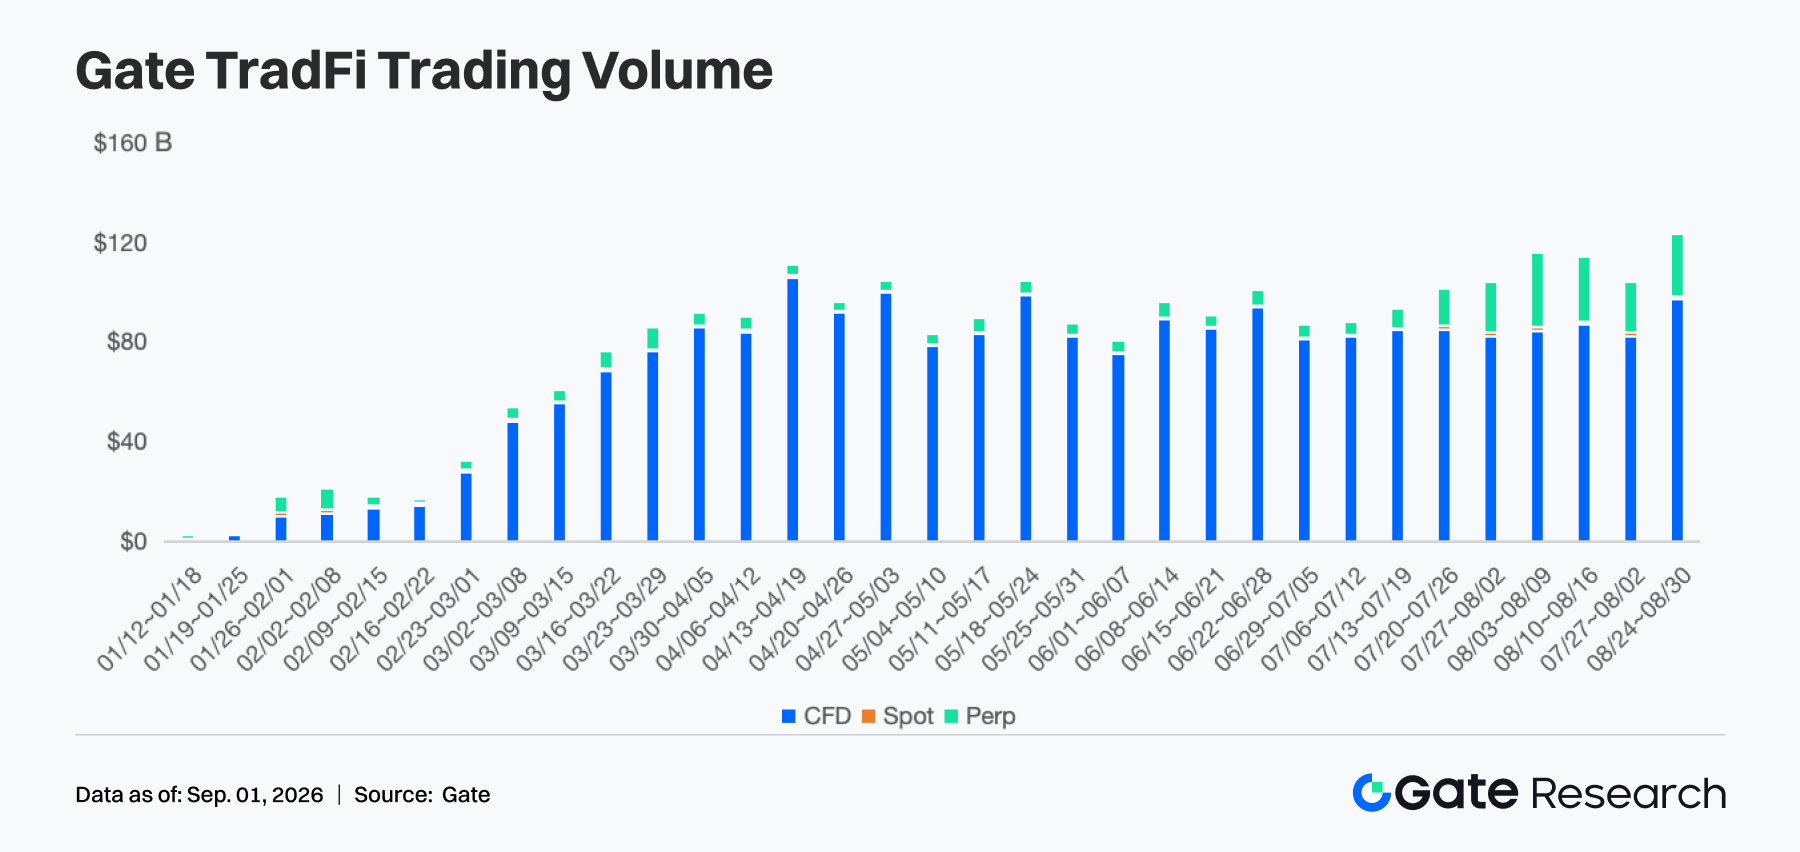
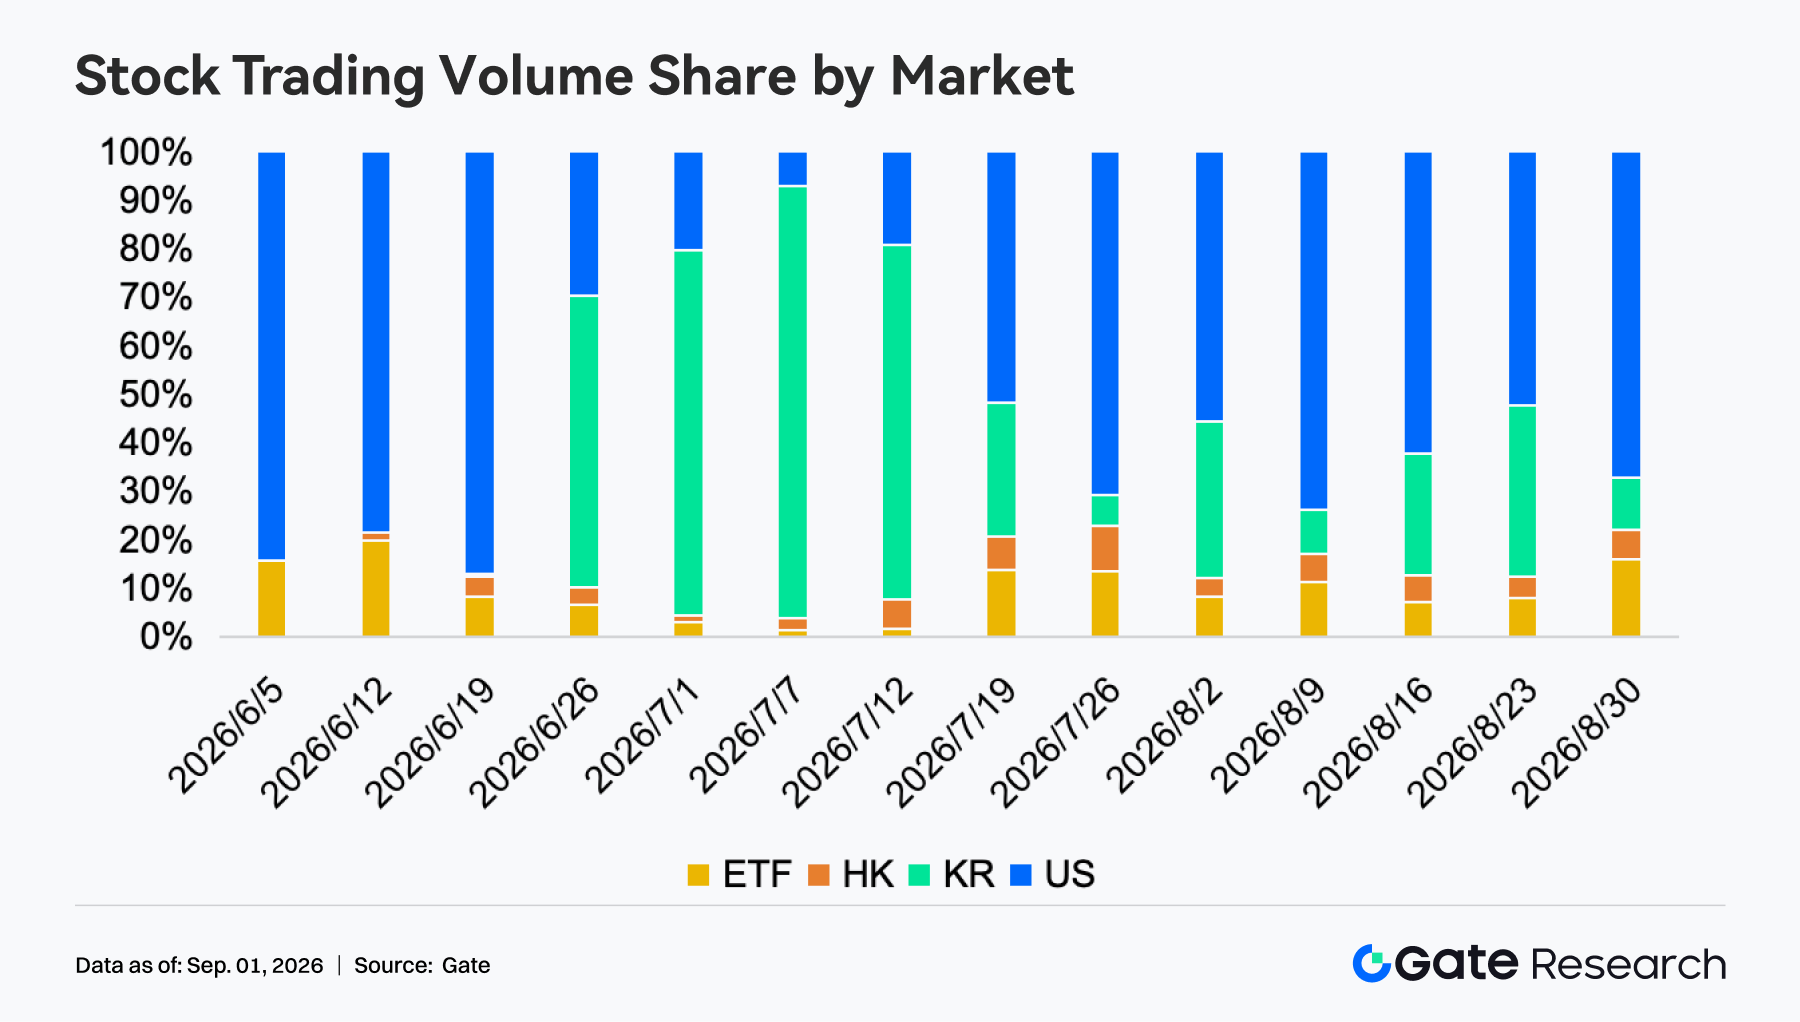
• TradFi activity rebounded and shifted back toward US equities. Gate TradFi weekly trading volume rose to approximately $123 billion, up about 17%, with CFD and Perp expanding in tandem. Within equity trading, the US stock share rebounded to approximately 67%, ETF rose to 16%, while Korean stocks fell from 36% to approximately 11%.
• On-chain trading shifted toward Meme and high-frequency retail scenarios. Uniswap's large transaction pulse faded, but transaction counts continued to grow; PumpSwap, Pump.fun, and Meme front-ends saw increased activity, with Pump revenue rising to approximately $16.28 million, making retail trading the primary revenue increment this week.
• Capital favored stable yield and SOL staking assets. Stablecoin supply increased by approximately $1.7 billion, with increments spreading to institutional settlement and yield-bearing assets such as RLUSD, USD1, and BUIDL; SOL staking assets significantly outperformed ETH, with ETF inflows, staking yields, and supply contraction expectations jointly reinforcing demand.
• BTC leveraged rally-chasing cooled notably. BTC OI fell from approximately $13.4 billion mid-week to approximately $12.4 billion, while funding rates remained mildly positive, indicating that the long structure has not yet reversed but new leverage momentum has weakened.
• Short-term protection increased, but the volatility risk premium declined. Medium- to long-term options positioning remains bullish, but short-end Put volume increased notably; 25D Skew recovered to approximately -3%, and DVOL fell from around 43 to approximately 37, showing that while the market added short-term protection, overall pricing of severe volatility actually stabilized.
1. Market Focus Analysis
Last week (August 24 – August 30, 2026), the market repriced around US inflation, the Jackson Hole meeting, and Middle East tensions. US July PCE rose 3.7% year-over-year, and core PCE rose 3.3% year-over-year, both unchanged from the prior reading; with inflation persistently above the 2% target, Fed Chair Kevin Warsh said on August 28 that policymakers still had "work to do" if underlying inflation did not fall fast enough, sharply raising market expectations for a September rate hike. The 2-year US Treasury yield rose to approximately 4.36% that day, the dollar strengthened, and gold came under pressure. Despite a pullback on Friday, Nvidia's earnings supported the AI supply chain, and US equities still posted modest weekly gains: the S&P 500, Dow Jones, and Nasdaq rose 0.5%, 0.5%, and 0.8%, respectively, while the Russell 2000 fell 1.5%, reflecting continued preference for large-cap tech stocks. In commodities, Iran and Oman signaled easing tensions over Strait of Hormuz transit arrangements, and Brent crude fell about 5% for the week to approximately $89.7 on Friday, temporarily easing imported inflation pressure. The crypto market continued to benefit from improved liquidity and short covering in the first half of the week, with BTC briefly breaking above 81,000 USDT; in the second half, hawkish rate expectations and profit-taking weighed on prices, but BTC and ETH still posted weekly gains of 2.10% and 0.59%, respectively.
2. Liquidity Analysis
2.1 Institutional stance on BTC shifted from aggressive accumulation to selective allocation
Last week, US spot BTC ETFs recorded total net inflows of approximately $925 million, down 51.79% from $1.918 billion the prior week. Flows remained net positive, but rally-chasing momentum weakened markedly. IBIT led with approximately $938 million in net inflows, contributing almost all of the increment; ARKB saw approximately $85 million in net outflows, the weakest performer. On Friday, the entire market turned to approximately $202 million in net outflows for the day, indicating that after prices consolidated around $77,000, some institutions began taking profits. Based on the August 21 public AUM baseline, combined with price changes and estimated net subscriptions, BTC ETF AUM rose from approximately $96.070 billion to approximately $96.940 billion, up about 0.91% week-over-week.
Spot ETH ETFs recorded total net inflows of approximately $816 million, up 17.77% from $693 million the prior week. ETHA led with approximately $567 million in net inflows; no product saw net outflows on a weekly basis, QETH had no flow change, and EZET saw only approximately $1 million in inflows, the smallest among non-zero products. Despite ETH's price falling 1.88% for the week, sustained subscriptions still pushed estimated AUM from approximately $14.300 billion to approximately $14.850 billion, up about 3.83% week-over-week. Overall, institutional stance on BTC shifted from aggressive accumulation to selective allocation, while capital absorption into ETH strengthened notably; sentiment remains positive, but Friday's BTC outflows and ETH's price weakness indicate that risk appetite has shifted from broad rally-chasing to product concentration and buying on pullbacks.
2.2 TradFi Liquidity
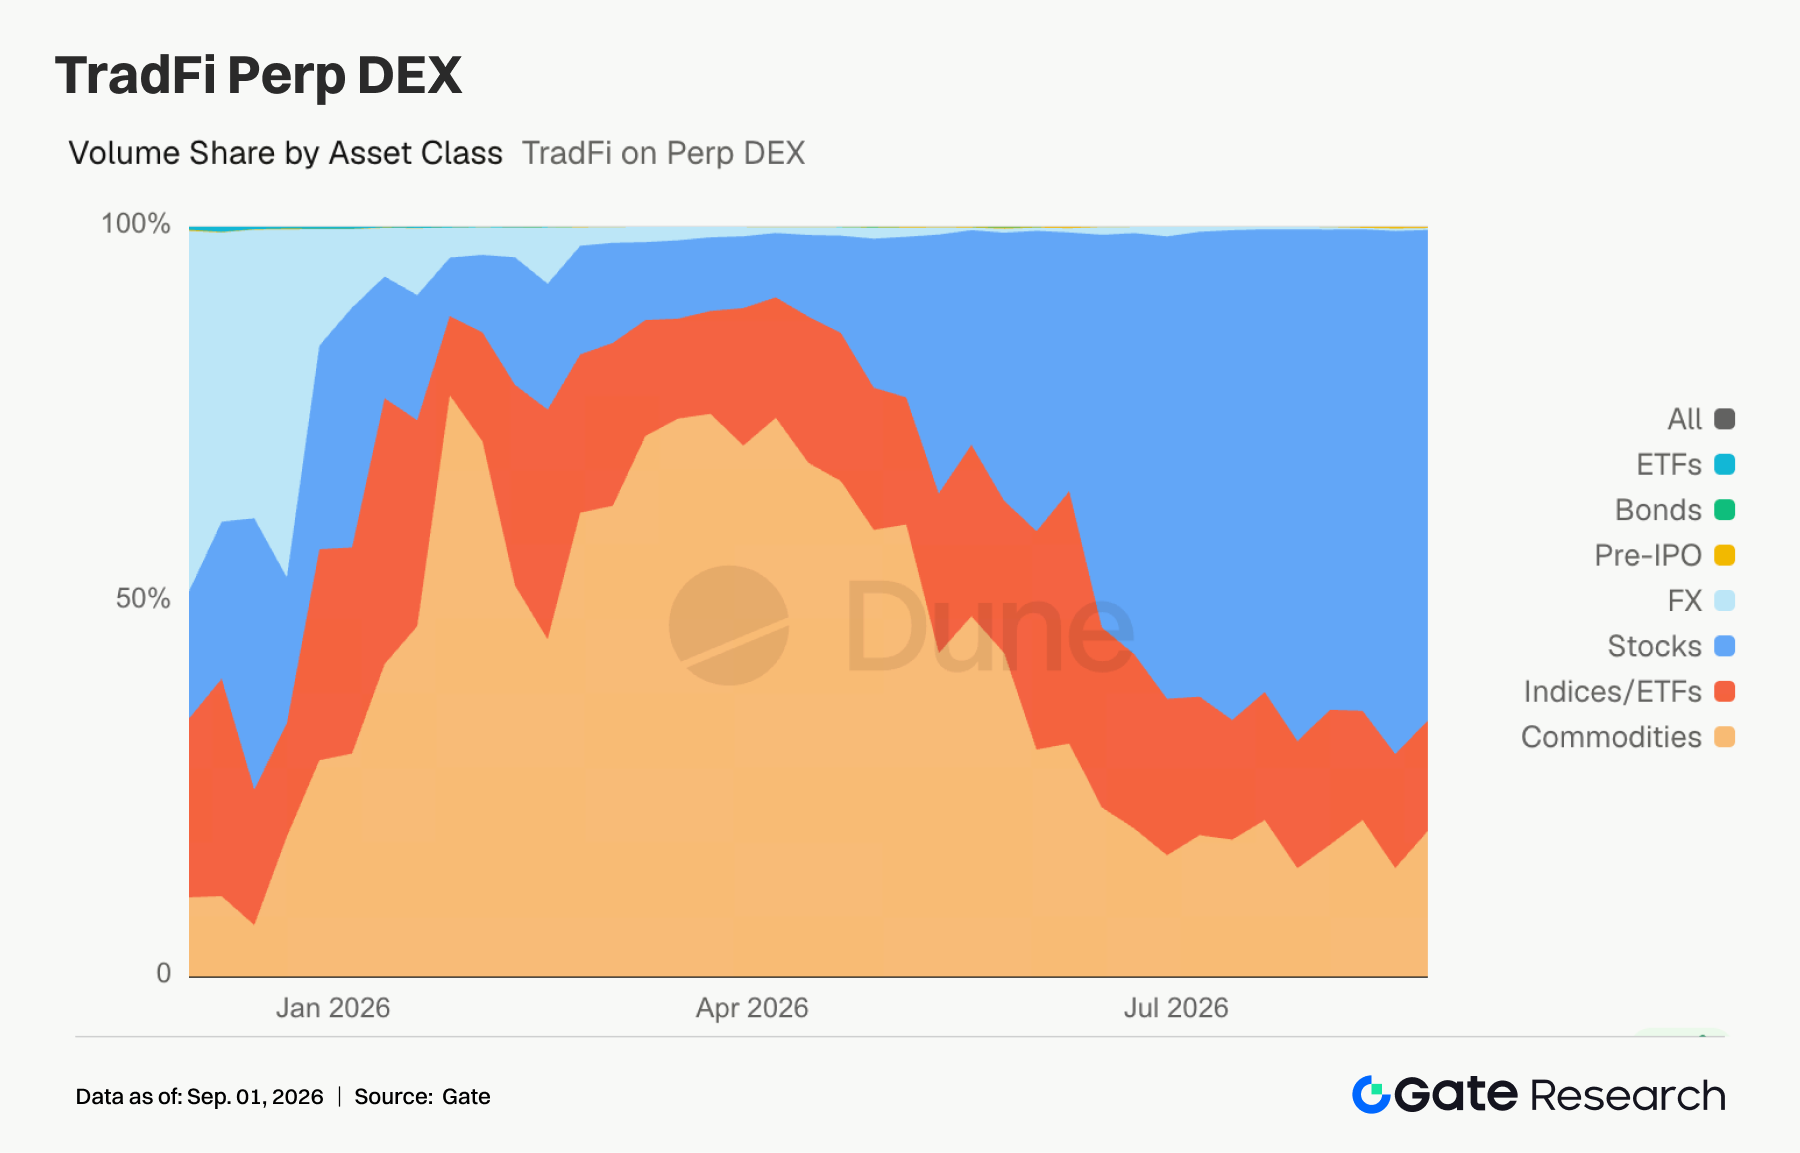
• TradFi Perp DEX: Last week, the broader TradFi Perp DEX market continued its pattern of "equities dominance, with commodities and indices/ETFs sharing the remainder." Equity trading share remained at approximately 65%–70%, continuing to hold absolute dominance, a marked reversal from the commodity-heavy structure in the first half of the year. Commodity share fluctuated during the week, recovering to around 20% at the latest reading, but still far below the peak above 60% seen in March–April; index/ETF share was approximately 10%–15%, remaining relatively stable. FX, bonds, and Pre-IPO categories remained near marginal levels. Overall, the trading focus of on-chain TradFi derivatives has stabilized toward equities, with commodities reflecting more of a phased macro event-trading demand.
• Gate TradFi Trading Volume: Last week, total Gate TradFi trading volume rebounded notably to approximately $123 billion, a recent high, up about 17% from approximately $105 billion the prior week. CFD remained the core base, with weekly volume of approximately $95 billion, accounting for nearly 80%; Perp rose to approximately $27 billion, up significantly from approximately $22 billion the prior week, continuing to be the primary source of incremental growth beyond CFD; Spot remained relatively small. Notably, since August, Gate TradFi's weekly trading scale has been gradually rising from around $100 billion, and this week CFD and Perp grew in tandem, indicating that trading activity is re-expanding and the business scale center is shifting further upward.
• Gate Equity Asset Trading Volume: Last week, Gate's equity trading structure refocused on US stocks. The US stock share rose from approximately 52% the prior week to approximately 67%, again approaching two-thirds and remaining the largest market; the Korean stock share fell notably from approximately 36% to approximately 11%, a marked cooling after two consecutive weeks of rapid expansion. The ETF share rose from approximately 8% to approximately 16%, another highlight of this week's structural shift; Hong Kong stocks accounted for approximately 6%, still at a low level overall. Compared with the prior week's "US and Korean stocks dual-core" pattern, capital flowed back to US stocks and ETFs this week, reflecting a phased rotation from high-beta Korean stocks back toward more liquid US equities and diversified index instruments.
• TradFi Order Book Depth: We selected XAUT, which has the highest TradFi trading volume, to analyze its order book depth (Delta). Last week, XAUT's price experienced a notable pullback, falling from above 4,600 USDT to around 4,450 USDT. During the decline from the 25th to the 28th, the ±1% order book Delta remained negative for an extended period, reaching a low of nearly -$3.3 million, indicating persistent seller depth dominance that resonated with weakening prices. After the 28th, the structure changed notably, with Delta briefly surging above +$3 million, then remaining positive most of the time, with buyer depth generally around +$200,000 to +$800,000 on the 29th–31st and breaking above +$1 million several times. Although prices have not yet rebounded notably, the order book has shifted from persistent selling pressure to buyer dominance, indicating that low-level absorption is improving; going forward, it remains to be seen whether positive Delta can persist and drive price stabilization.
3. On-Chain Data Insights
3.1 Uniswap's large transaction pulse fades, Robinhood Chain reaccelerates over the weekend
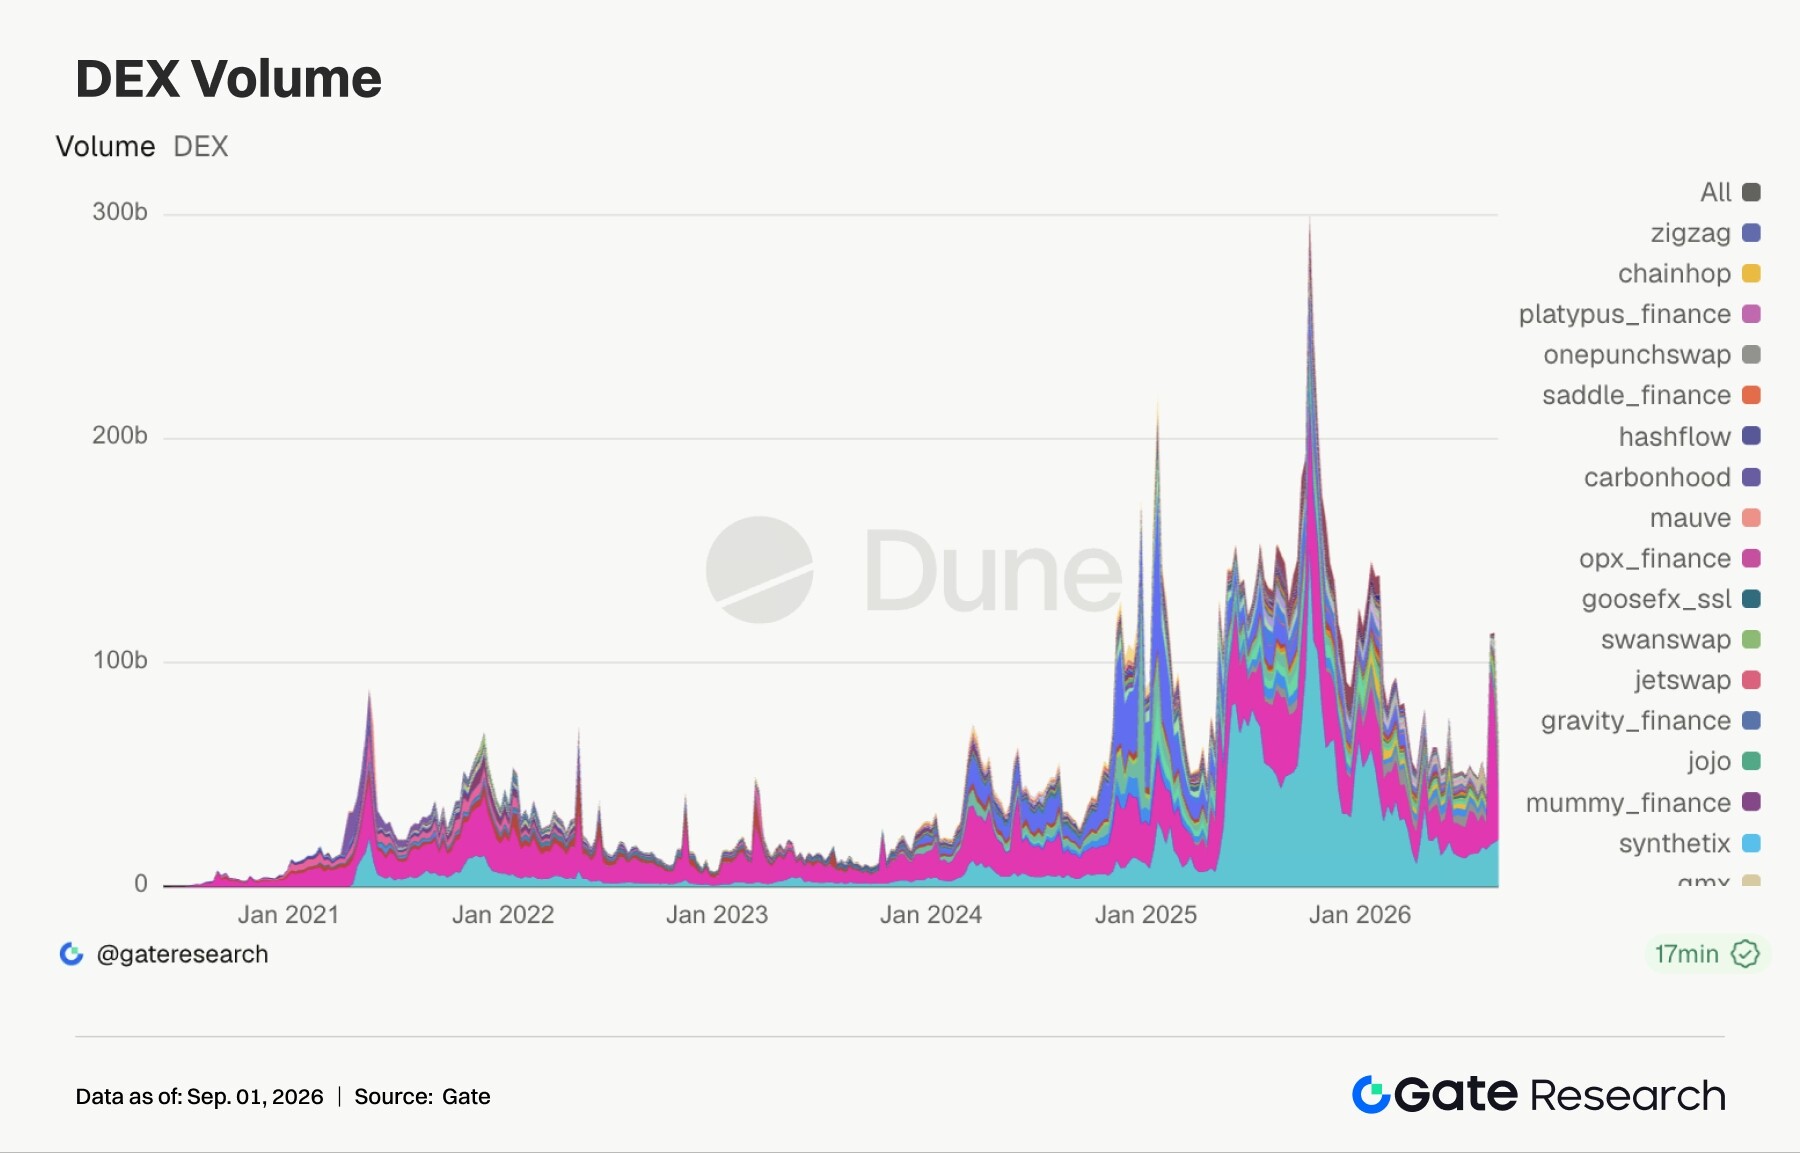
Uniswap's weekly trading volume fell 72.9% week-over-week, but transaction counts rose 29.2% and trader numbers rose 8%. The divergence between volume and activity indicates that the prior week's large transaction pulse driven by Robinhood Chain stock tokens and Meme assets has faded, but small-value, high-frequency trading continues to expand. PancakeSwap overtook Uniswap again with $21.36 billion, up 7.5% in volume, while transaction counts fell 19.8%, indicating larger average trade sizes. Robinhood Chain did not cool in tandem. The chain's single-day DEX volume broke above $1 billion over the weekend, with TVL up about 17.8% for the week; Meme assets such as PONS and CASHCAT, along with stock tokens, jointly drove trading; however, of the more than 11,000 tokens issued in a single day by the Uniswap launchpad earlier, only about 1% still had trading activity by month-end, showing that high traffic growth coexists with a high asset elimination rate. PumpSwap volume grew 28.3%, Pump.fun Bonding Curve volume grew 27.8%, and Solana Meme coin weekly spot volume broke above $5.2 billion, a new high for the year. Capital is rapidly rotating among Memecoins on Solana, Robinhood Chain, and BNB Chain. Aerodrome and BisonFi fell 13.6% and 26.9%, respectively, as Base failed to sustain the prior week's breakout.
3.2 Stablecoin supply increased by approximately $1.7 billion, with increments shifting toward institutional settlement and yield-bearing dollars
Total supply of stablecoins and on-chain dollar assets rose by $1.73 billion for the week, an increase of 0.56%, with USDT rising slightly; USDC increased by approximately $283 million; RLUSD increased by approximately $296 million, up 14.3%; USD1 increased by approximately $180 million to $4.19 billion; BUIDL and USDTB increased by $205 million and $196 million, respectively. Meanwhile, USDS decreased by $275 million, USYC decreased by $149 million, and PYUSD decreased by approximately $92.4 million. Supply growth spread toward payments, institutional settlement, and tokenized Treasury yield products. Event-side developments were broadly consistent with supply changes. RLUSD's market cap broke above $2 billion this week, with supply on Ethereum and XRP Ledger each approaching $1 billion; USD1 was natively issued on Canton Network and can serve as the cash leg and derivatives collateral for tokenized asset trading.
3.3 SOL staking assets significantly outperform ETH, with ETF and supply reform reinforcing staking demand
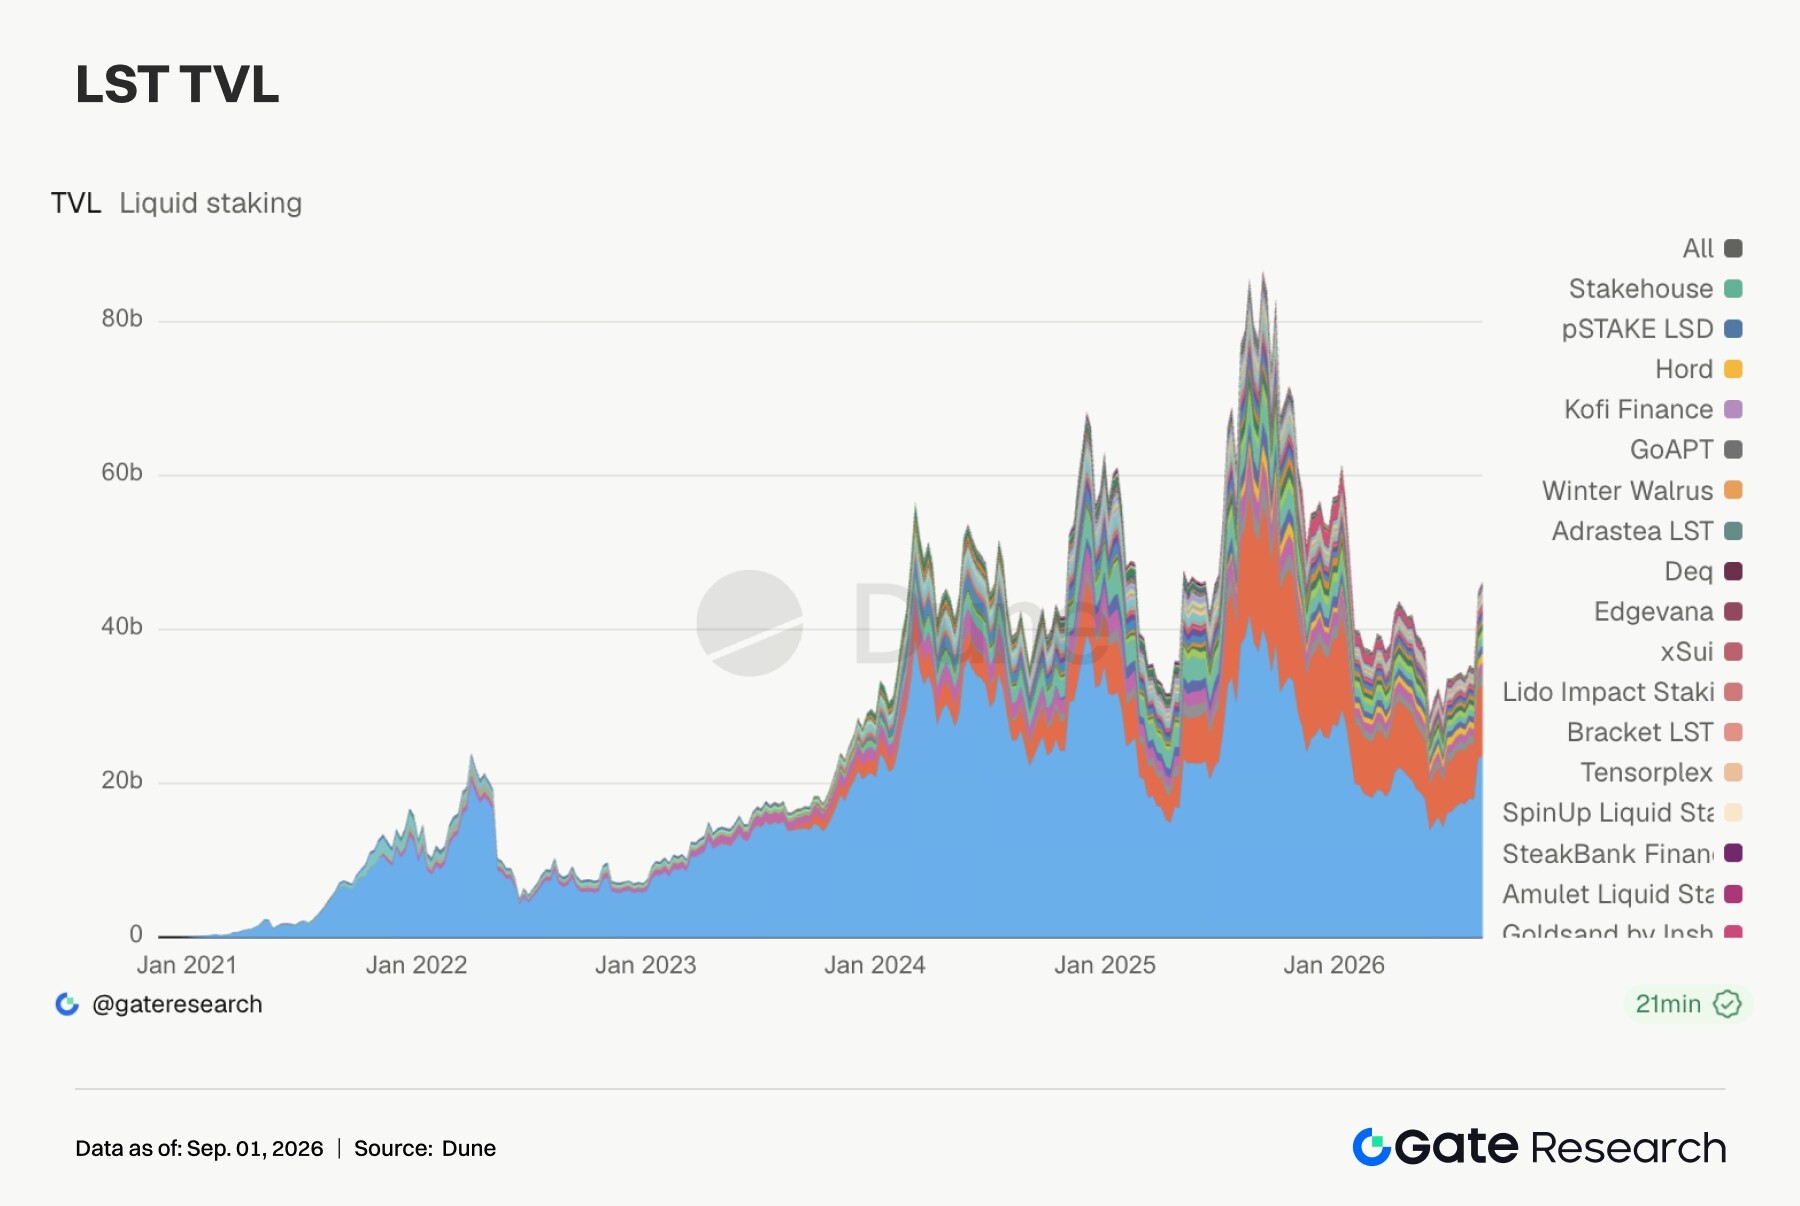
On the ETH side, LSTs entered a phase of moderate growth. Lido TVL grew 1.9% to $23.71 billion, Rocket Pool grew 1.5%, and StakeWise was essentially flat. Lido cut the fixed management fee on its EarnETH Vault from 1% to 0.2% this week and raised the performance fee to 15%, reflecting the protocol's effort to compete for yield aggregation capital by lowering holding costs. On the SOL side, elasticity was notably stronger. Sanctum grew 14.1% to $1.61 billion, Jito grew 9.8%, and Jupiter Staked SOL grew 13.1%. Bitwise Solana Staking ETF's AUM broke above $1 billion this week, with approximately $138 million in net inflows over the past 10 days and about 96% of assets used for staking; meanwhile, Solana validators passed the SGP-0002 proposal to accelerate inflation decline, which is expected to reduce SOL issuance by approximately 18.9 million tokens over the next six years. The rise in SOL LSTs is not just a price factor but also reflects ETF inflows, staking yields, and supply contraction expectations. On the HYPE side, activity cooled somewhat, with Kinetiq kHYPE up 2.4% and stHYPE down 2.8%, corroborating the decline in Hyperliquid volume and revenue.
3.4 Aave total borrowing enters sideways trend, V4 growth has yet to transmit to protocol-wide credit expansion
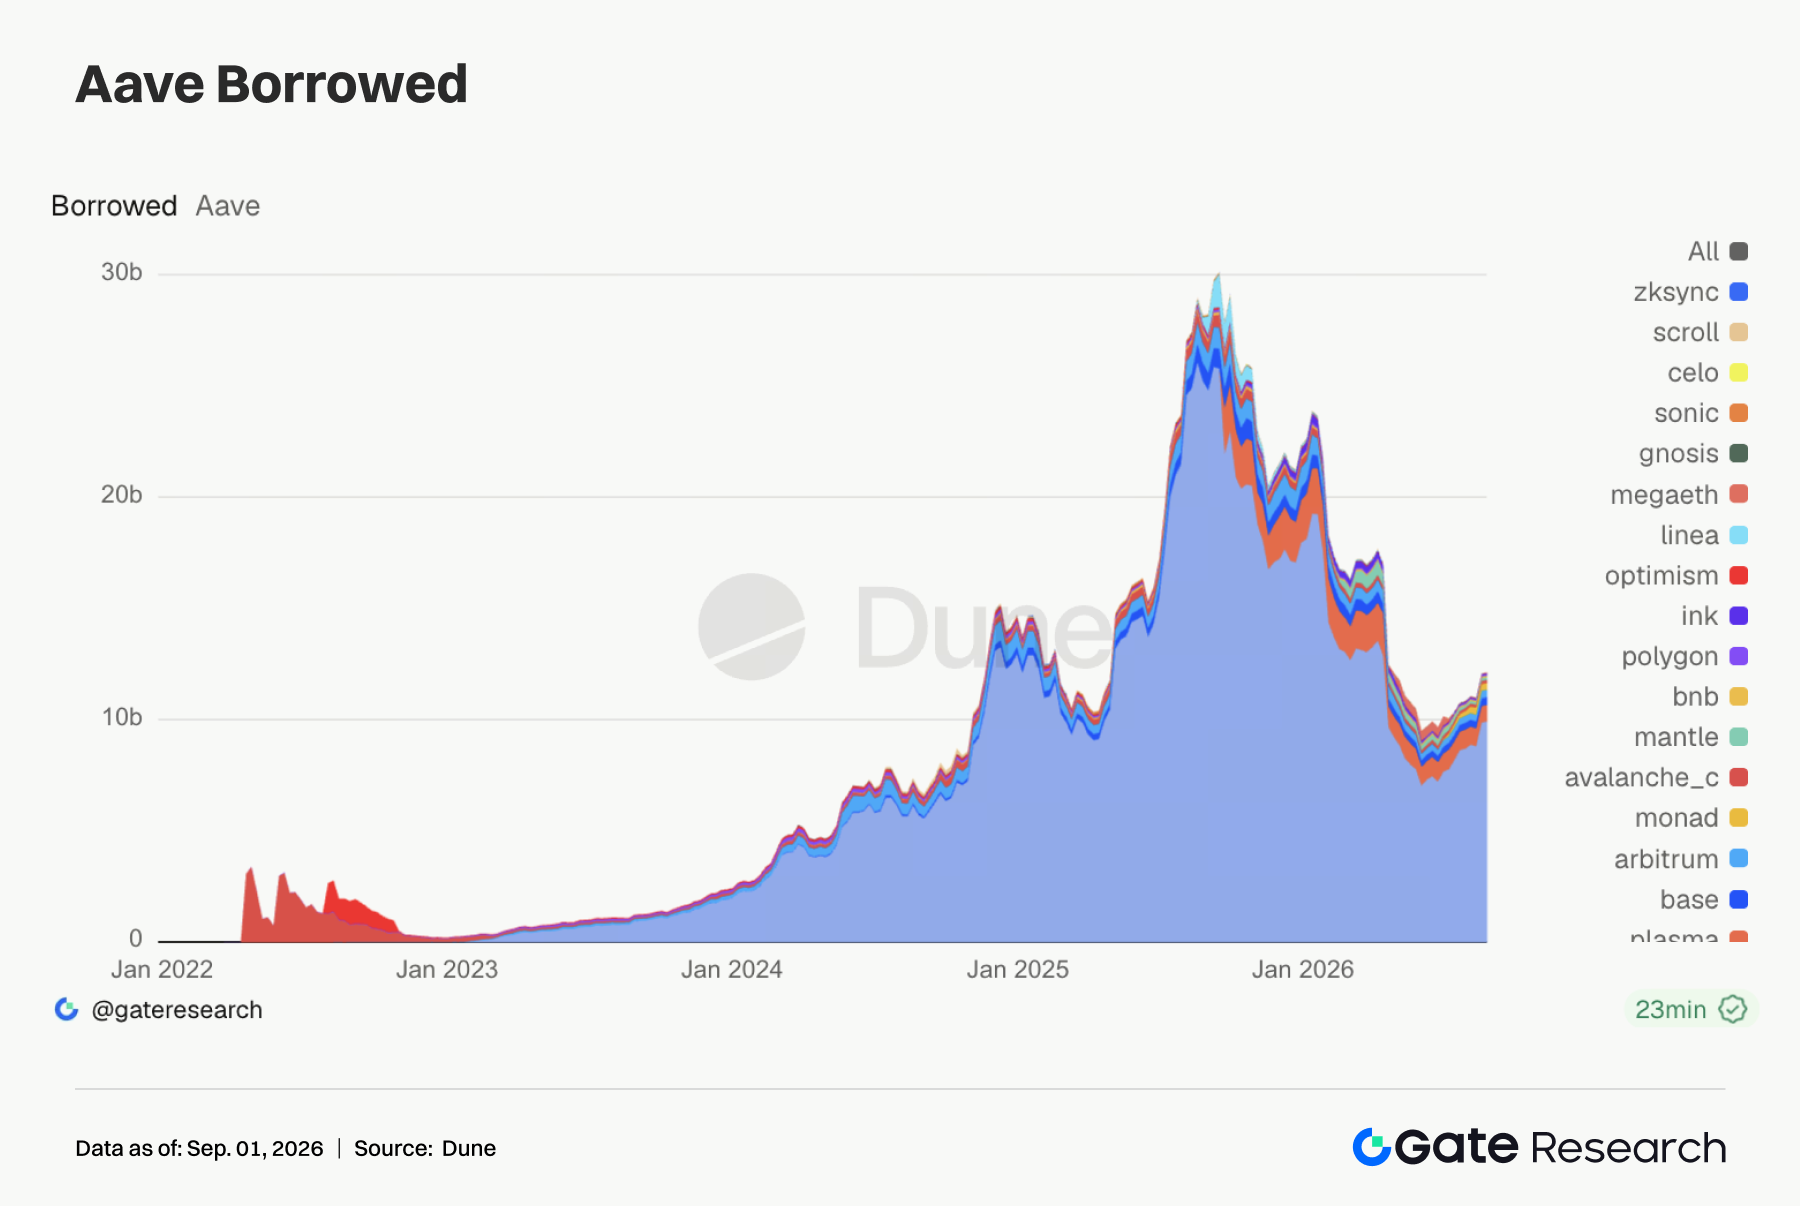
Aave's total borrowing across chains was approximately $12.15 billion, up only 0.35% week-over-week. The Ethereum market rose from $9.887 billion to $9.936 billion, an increase of approximately $49 million; Base, Arbitrum, Plasma, and Monad all declined slightly, with Mantle down 2.6%. Ink bucked the trend with 10.6% growth to $48.2 million, but its absolute scale remains small and cannot change the overall sideways trend in multi-chain borrowing. Internal structural migration is occurring within the protocol. Aave V4 deposits rose to approximately $806 million, up 30% over 7 days, with active loans of approximately $216 million, and capital mainly distributed across Ethereum Core, EtherFi Cash on Optimism, and independent markets such as Global Dollar. V4's Hub-and-Spoke architecture is attracting deposits, but a considerable portion of new capital remains on the supply side and has not yet formed corresponding borrowing demand. Institutional capital needs continued observation of V4's loan utilization rate, the risk isolation effects between different Spokes, and whether new RWA collateral can generate actual borrowing.
3.5 Stablecoin borrowing costs continue to rise, USDT liquidity tightens marginally
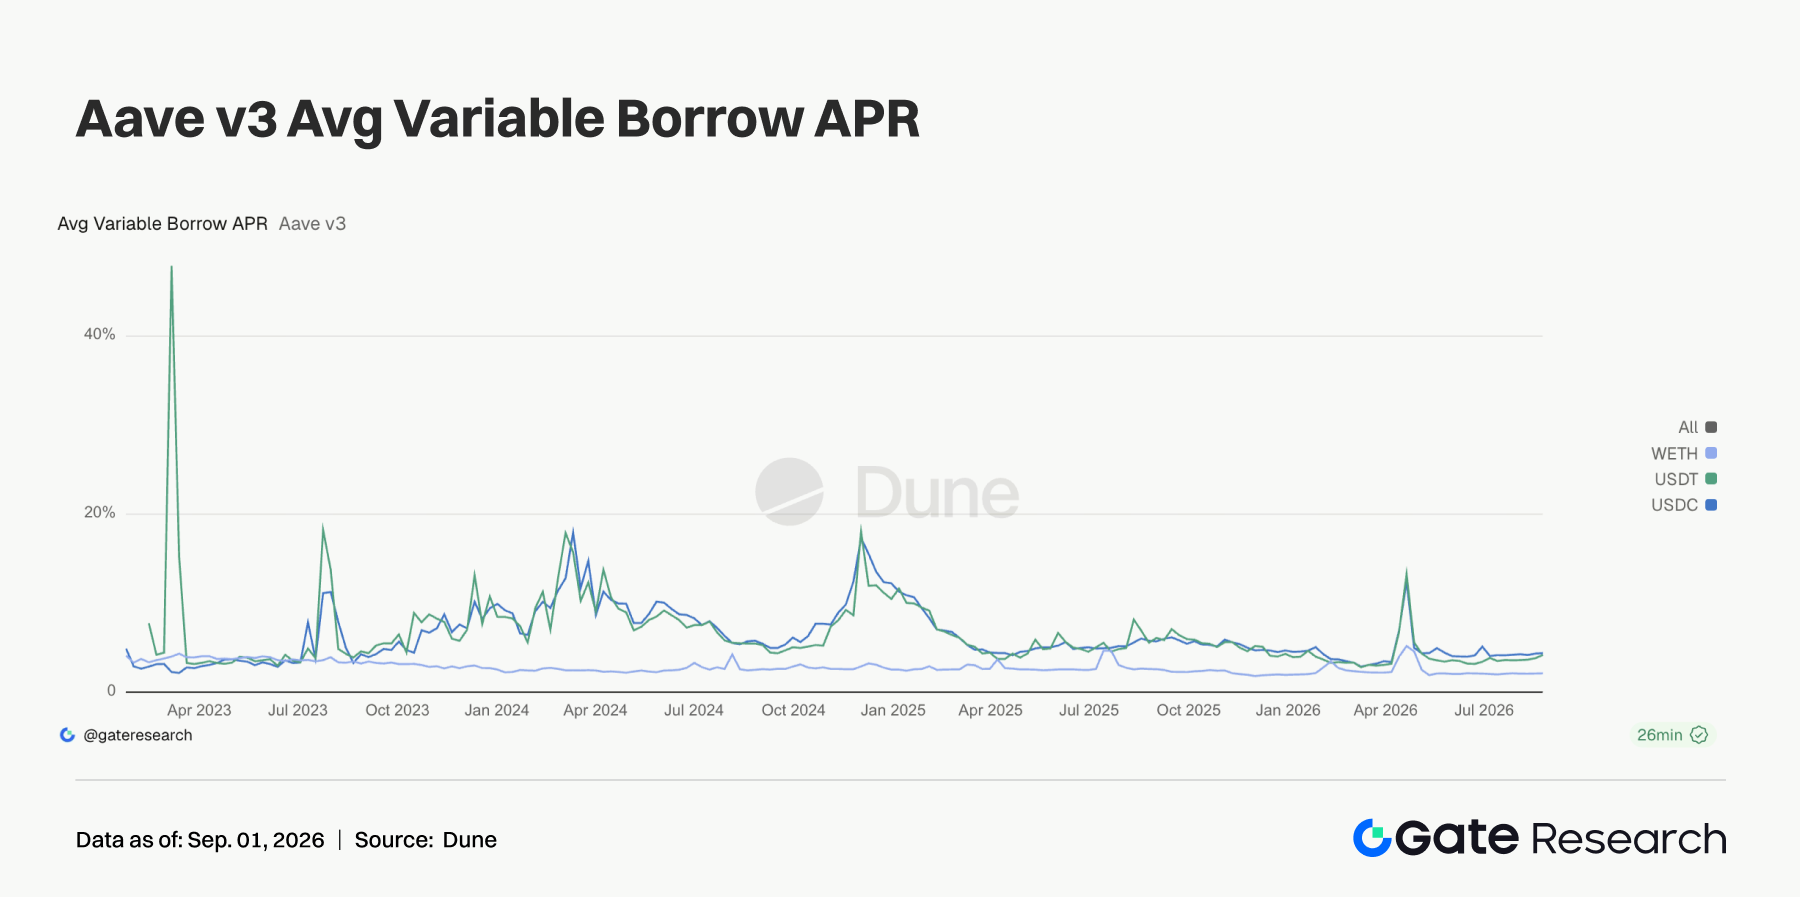
USDC's average borrowing rate rose from 4.37% to 4.42%, an increase of approximately 5 basis points, with the weekly high rate approaching 14%; USDT's average rate rose from 3.85% to 4.22%, an increase of approximately 37 basis points, with the high rate rising from 4.52% to 5.39%. WETH's average rate rose slightly from 2.13% to 2.15%. Borrowing balances were essentially flat while USDT rates rose notably, indicating that the change mainly came from local capital utilization rates and stablecoin structure. USDC has deeper institutional and cross-chain liquidity, so although tail rates are high, average costs remain relatively stable; USDT's previous cost advantage is narrowing. WETH rates remain low, and ETH directional leverage is relatively restrained. This week's rise in staking assets came more from spot valuation and yield strategies rather than borrowing leverage.
3.6 Pump revenue approaches Hyperliquid, Meme front-ends become the main profit increment this week
Hyperliquid's weekly revenue fell from $19.33 million to $16.77 million, down 13.2%; Pump revenue grew 19.0% to $16.28 million, narrowing the gap between the two to less than $500,000. GMGN revenue grew 40.6% to $7.48 million, Axiom Pro grew 23.9%, and Jupiter grew 22.1%, indicating that Meme trading and retail front-ends are the clearest revenue increment this week. Pump.fun Bonding Curve volume has now grown for 5 consecutive





