






Re-staking is back on the horizon, what is the liquidity of LRTs?


Original author: Kairos Research
Original compilation: Deep Chao TechFlow
Key summary:
LRT may integrate with centralized exchanges and introduce market makers to the risk/reward of being a liquidity provider in these centralized venues.
Liquidity The liquidity of recollateralized tokens is not amazingly good. The overall liquidity is acceptable, but each individual LRT has greater nuances associated with it. This difference will only increase with the long-term agency strategy. Different and continue to grow.
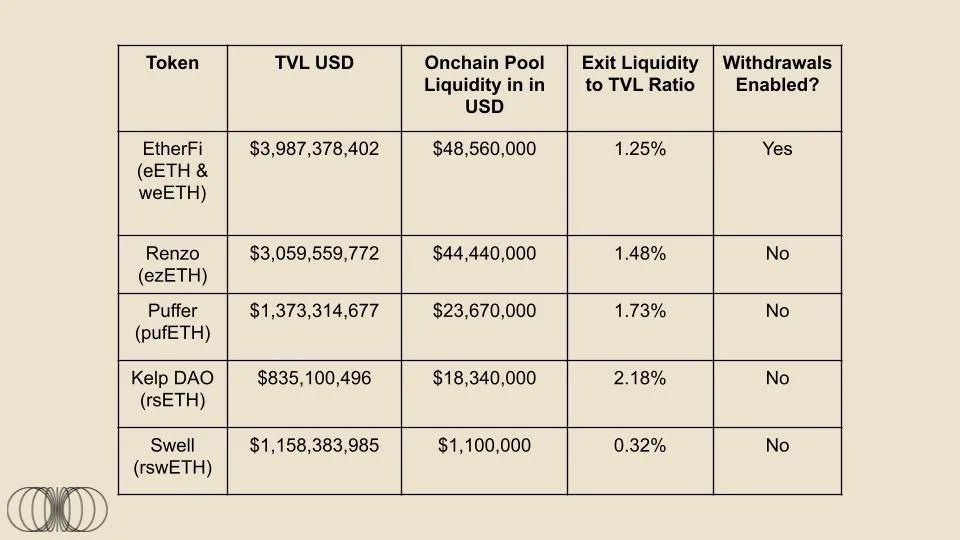
With the exception of EtherFi, all these LRT providers do not have withdrawal functionality enabled.
It is expected that liquidity re-hypothecation will be a winner-take-all market structure, and liquidity will bring more liquidity.
text:
EigenLayer’s first AVS is officially launched on the mainnet.
Today EigenLabs’ data availability AVS – EigenDA was released on the mainnet, officially marking the beginning of the re-staking era. While the EigenLayer market still has a long way to go, one trend is already very clear: Liquid Re-staking Tokens (LRT) will become the main avenue for re-stakers. Over 73% of all EigenLayer deposits are made through LRT, but how liquid are these assets? This report dives into the issue and explains the nuances surrounding EigenLayer.
Introduction to EigenLayer and Liquid Re-Staking Tokens
EigenLayer enables the reuse of ETH on the consensus layer through a new cryptoeconomic tool called “restaking.” ETH can be re-staking on EigenLayer in two main ways: through native re-staking of ETH, or using Liquid Staked Tokens (LST). The re-staking ETH is then used to secure other applications, known as Active Validation Services (AVS), allowing re-stakers to earn additional staking rewards.
The main complaint users have about staking and re-staking is the opportunity cost of staking ETH. This problem is solved for native ETH staking using Liquid Staked Tokens (LST), which can be thought of as liquid receipt tokens that represent the amount of ETH staked by the user. The LST market on Ethereum is currently approximately $48.65 billion, making it the largest DeFi sector. Today, LST accounts for approximately 44% of all Ethereum staking, and as restaking grows in popularity, we expect the liquid restaking token (LRT) space to follow a similar, if not more aggressive, growth pattern.
While LRTs share some characteristics with LSTs, they are significantly different in mission. The end goal of every LST is essentially the same: stake users’ ETH and provide them with liquid receipt tokens. However, for LRT, the ultimate goal is: delegate staking representation of users to one or more operators and then support a basket of AVS. Each individual operator can choose how to distribute their delegated staking among these various AVS. Therefore, the operator to which LRT delegates its staking has a large impact on the overall liveness, operational performance, and security of staking ETH. Finally, they must also ensure that appropriate risk assessments are conducted for the unique AVS supported by each operator, as the risk of curtailment may vary depending on the service provided. Note that the curtailment risk will be essentially zero in the early stages of most AVS launches, but over time we will slowly see the “training wheels” being removed and the staking market becoming increasingly permissionless.
Editors note: Training wheels refer to protective measures provided in the initial stage to avoid or reduce risks. As time goes by and the capabilities of participants increase, these protective measures will be gradually removed, making the system or market more open and free. .
However, despite the differences in structural risk, one similarity remains the same: LRT reduces the chance of re-pledged capital by providing liquid receipt tokens that can be used as productive collateral in DeFi or exchanged for reduced withdrawal periods cost. This last point is especially important because one of the main advantages of LRT is that it circumvents the traditional withdrawal period, which EigenLayer alone has a withdrawal period of 7 days. Considering this core principle of LRT, we expect that with the entry barrier to re-hyping being so low, but the exit barrier being so high, we will naturally see net selling pressure on them, and therefore the liquidity of these LRTs will be that they lifeline.
Therefore, as EigenLayer’s total staked value continues to climb, it’s important to understand the drivers behind the protocol’s growth and how these factors will impact inflows/outflows in the coming months. At the time of writing, 73% of EigenLayer deposits are made via liquid restaking tokens. To put this into context, on December 1, 2023, LRT had approximately $71.74 million in deposits. Today, April 9, 2024, they have grown to approximately $10 billion, a staggering 13, 800%+ growth in just under 4 months. However, as LRT continues to dominate EigenLayer’s rehypothecation deposit growth, there are some important factors to consider.
Not all LRTs are composed of the same underlying assets
LRT’s staking delegation to AVS will be different in the long term, but not much in the short term
Most importantly, liquidity characteristics vary widely among various LRTs
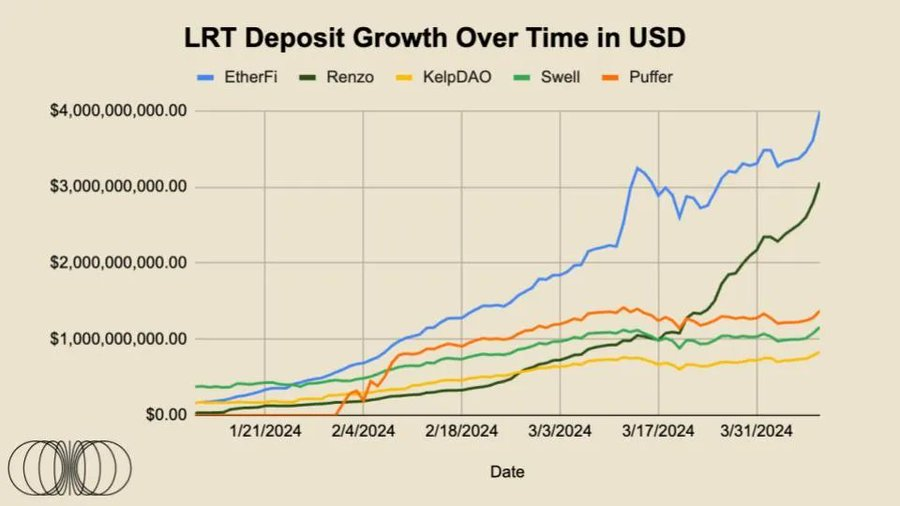
Given that liquidity is the most critical advantage of LRT, much of this report will focus on this last point.
The speculative nature of Eigen Points has greatly fueled the current bull run on EigenLayer deposits, and we can assume that this will translate into some form of airdrop allocation for potential EIGEN tokens. There are currently no AVS rewards going on, meaning there are no incremental benefits on these LRTs other than natural staking rewards. To drive and sustain a total staked value of over $133.5 billion, the AVS market must naturally find a balance between the incremental returns required by re-stakeholders and the natural price AVS are willing to pay for security.
For LRT depositors, we’ve seen huge success from EtherFi in launching an airdrop of the ETHFI governance token, which is currently valued at around $6 billion. Taking all of the above factors into consideration, it can be expected that some capital flows may gradually increase following the launch of EIGEN and other anticipated LRT airdrops.
However, in terms of reasonable returns, users may have a hard time finding higher returns in the Ethereum ecosystem that dont involve EigenLayer. Several interesting revenue opportunities exist within the Ethereum ecosystem. For example, Ethena is a synthetic stablecoin backed by collateralized ETH, while also having a hedged short position in ETH futures. The protocol currently offers an annualized yield of approximately 30% on its sUSDe product. Additionally, as users become more familiar with interoperability and cross-chain bridging, yield chasers may look elsewhere, potentially driving productive capital outflows from Ethereum.
While somewhat complex, overall we think it’s reasonable to assume that there won’t be any larger incremental staking yield events than this, aside from potential EIGEN token airdrops to re-stakeholders, and in the private placement Large, blue-chip AVS in the market that have raised at high multi-billion dollar valuations may also issue their tokens to re-hypothecaters. Therefore, it can be assumed that after these events some proportion of ETH will flow out of the EigenLayer deposit contract via withdrawals.
Given that EigenLayer withdrawals have a seven-day cool-down period and the vast majority of funds are re-hyped through LRT, the fastest exit route will be to convert from your LRT to ETH. However, liquidity characteristics vary widely among various LRTs, and many LRTs may not be able to conduct large-scale exits at market prices. Additionally, at the time of writing, EtherFi is the only LRT project with withdrawals enabled.
We believe that LRT trading at a discount to the price of its underlying asset could create a painful arbitrage cycle for the restaking protocol. Imagine if an LRT traded at 90% of its underlying ETH value, market makers/arbitrage Investors may purchase the LRT and continue the redemption process. Assuming that the price of ETH is hedged, they are expected to obtain a net profit of approximately 11.1%. The general rule of supply demand is that LRT is more likely to experience net selling pressure as sellers may avoid the 7-day withdrawal queue. Conversely, users looking to re-stake may deposit their ETH immediately, so buying LRT on the open market will do little good for the ETH they already own.
Incidentally, we expect that once multiple AVS come online along with in-protocol rewards and slashing is fully implemented, the further choice of whether to exit or continue to restake will ultimately depend on the incremental yield provided through restaking. We personally believe that many people underestimate the incremental benefits provided by re-staking. However, this is a story for later.
Data tracking
The data portion of this months report, starting below, will track the growth, adoption, and liquidity conditions of the top five LRTs, as well as any noteworthy news we think should be noted.
LRT Liquidity and Trading Volume
While staking via LST and LRT offers key advantages over traditional staking, this usefulness is almost completely destroyed if LRT itself is not sufficiently liquid. Liquidity refers to “the efficiency or convenience with which an asset can be converted into cash without affecting its market price.” Issuers of LRT must ensure that there is sufficient liquidity on the chain so that large holders can prepare Good asset value is almost 1:1 for exchange receipt tokens in liquidity pools.
Each existing LRT has very unique liquidity characteristics. We expect these conditions to persist for a number of reasons:
Certain protocols will have investors and users provide liquidity to their LRT at an early stage
Incentivize liquidity through subsidies, token issuance, through on-chain bribery systems, or in anticipation of these events through points
Some protocols will have more complex and centralized liquidity providers who will keep their LRT close to the peg level with less total USD liquidity
It is important to note that concentrated liquidity can only work within a smaller price range, and any price movement outside the selected range will have a significant impact on the price.
Below is a very simple analysis of on-chain pool liquidity for the top five largest LRTs on Ethereum mainnet (+ Arbitrum). Exit liquidity refers to the cash-like USD value in the LRT liquidity pool.
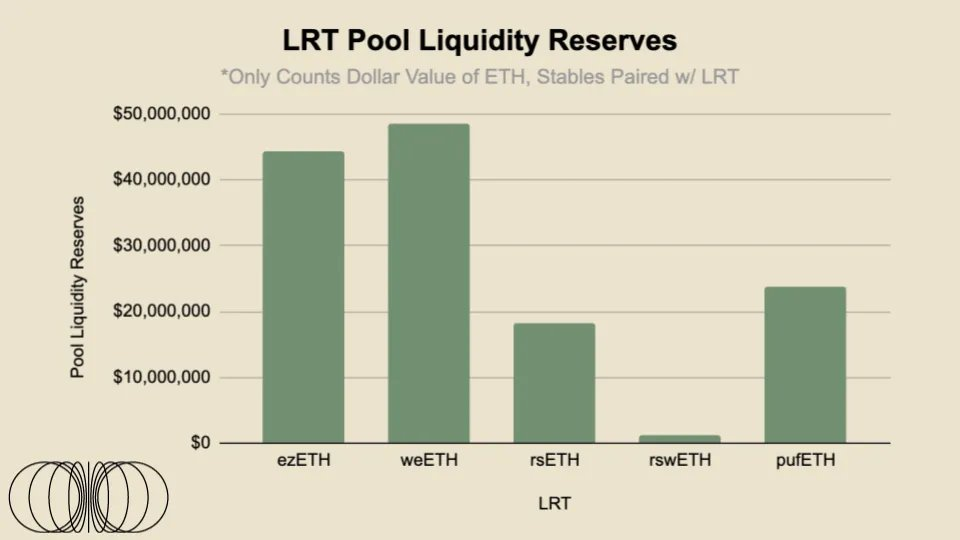
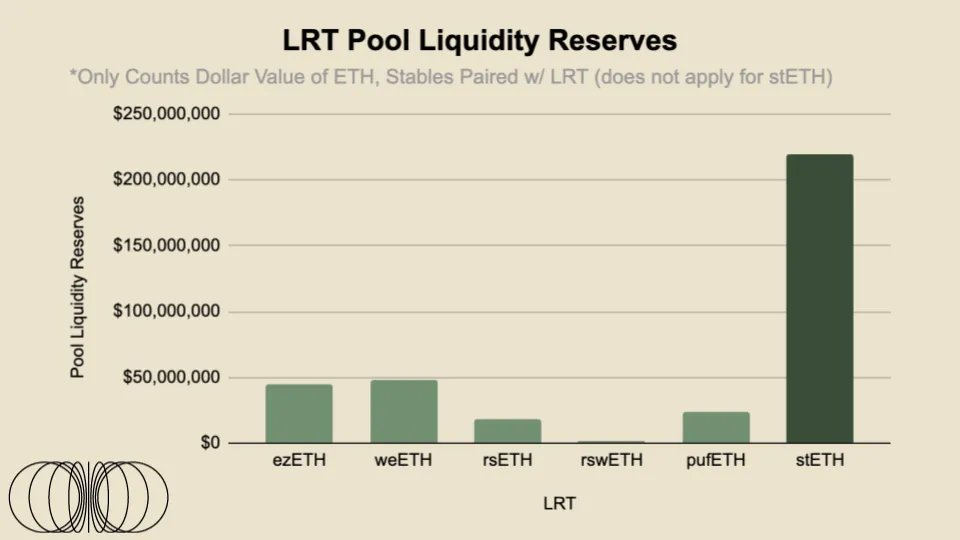
For the pool liquidity of these five largest LRTs, there is a total of over $136 million in liquidity available across Curve, Balancer, and Uniswap. However, to get a clearer picture of how liquid each LRT is, we will apply a Liquidity/Market Cap ratio to each asset.
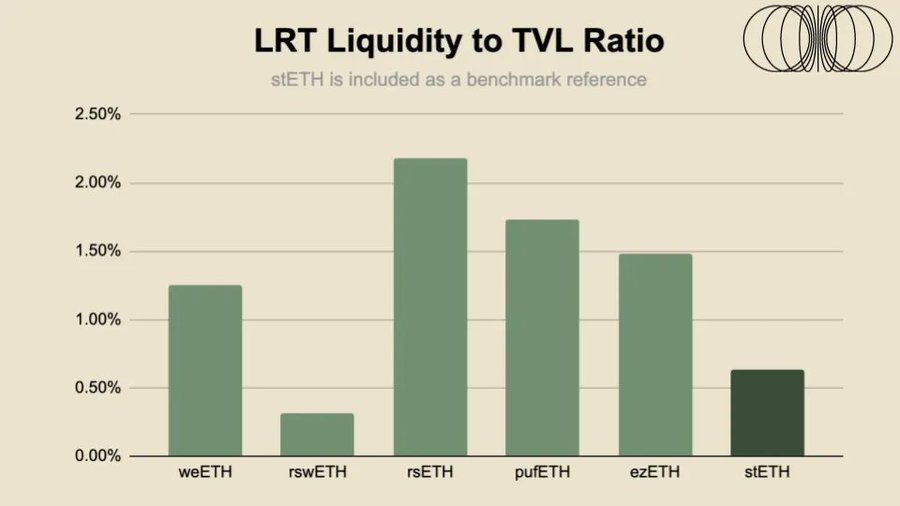
LRT liquidity ratios are not overly concerning compared to the top LST – stETH. However, LRT’s liquidity may be more important than LST’s liquidity, given the increased re-hypothecation risk and Eigenlayer’s addition of a seven-day withdrawal period on Ethereum’s unlock queue. Additionally, stETH is traded on several large centralized exchanges, with order books managed by professional HFT firms, meaning there is much more liquidity to stETH than what is seen on-chain. For example, on OKX and Bybit, there is approximately +-2% order book liquidity of over $2 million. Therefore, we believe LRT may also explore this avenue of integrating with centralized exchanges and introducing market makers to the risks/rewards of being a liquidity provider in these centralized venues. In next month’s article, we will dive deeper into the distribution of pool liquidity, x*y=k liquidity, and centralized liquidity among top LRT trading pairs.
LRT anchor data
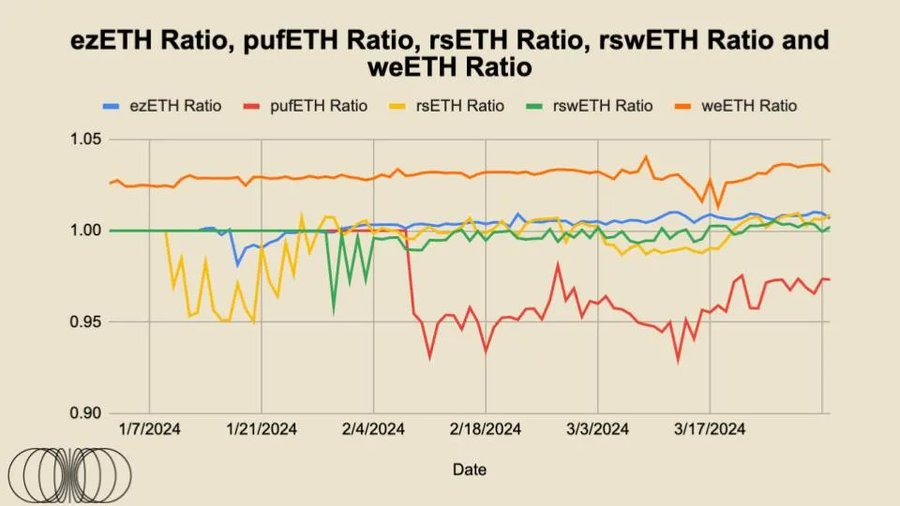
As can be seen from the figure above, the trading prices of rsETH, rswETH and ezETH are relatively close to the 1:1 ratio of ETH, with a slight premium. Given that these tokens are non-interest-bearing tokens, unlike stETH, they will automatically compound. Interest rewards are then reflected in the token price. This is why the current price of 1 wstETH is around 1.16 ETH. Theoretically, the fair value should continue to increase over time, as this is determined by time*staking rewards, which will then be reflected in the increasing fair value of these tokens.
The anchoring of these LRTs is very important because they essentially represent the level of trust that market participants have in the project as a whole, which is directly driven by the capital invested or the willingness of arbitrageurs to trade these premiums and discounts to maintain the trading fair value of the token. Decide. Note that all of these tokens are non-benchmark tokens, meaning they compound interest automatically and instead trade based on a redemption curve.
It can be seen that for ezETH and weETH, the two most liquid LRTs, their transactions have been relatively stable over a period of time, and most of them are at par with fair value. The reason why EtherFis ezETH deviates slightly from its fair value is mainly due to the launch of its governance token. Opportunistic airdroppers swapped out this token, and naturally other market participants also joined the transaction to exchange it. Discount arbitrage. We may see something similar happen after Renzo launches its governance token.
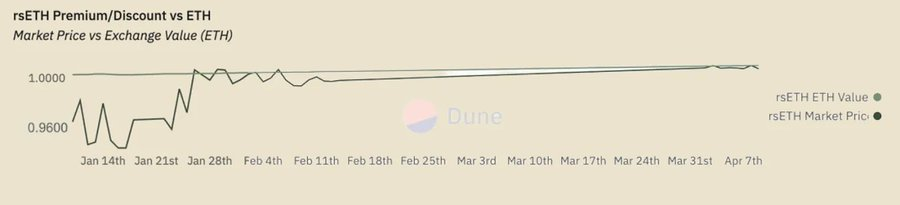
KelpDAO’s rsETH traded at a discount to fair value at launch but has gradually and steadily returned to parity with fair value.
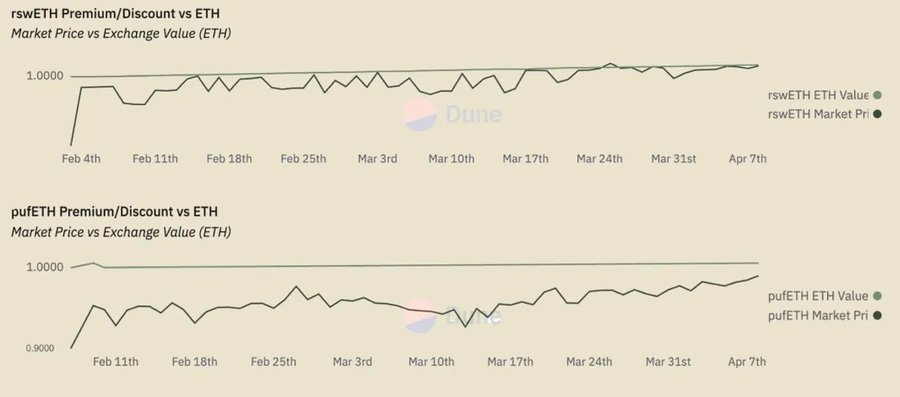
As for rswETH, it has traded at a discount to its fair value for most of the time, however it appears to have reached parity with its fair value recently. Among all these LRTs, pufETH is the major outlier as they only trade at a discount. However, this trend appears to be coming to an end as it moves towards parity with the value of its underlying assets at fair value.
It’s important to point out again that with the exception of EtherFi, none of these LRT providers have withdrawals enabled. We believe that ample liquidity combined with the ability for users to withdraw funds at any time will provide a strong attraction for market participants, which means that a large portion of liquidity needs to be obtained from the entire DeFi ecosystem.
LRT in the broader DeFi ecosystem
Once LRT is further integrated into the broader DeFi ecosystem, especially the lending market, the importance of its peg will increase significantly. For example, taking the current currency market as an example, LST (especially wstETH/stETH) is the largest collateral asset on Aave and Spark, with supply of approximately US$4.8 billion and US$2.1 billion respectively. As LRT becomes more integrated into the broader DeFi ecosystem, we expect these numbers to eventually exceed the supply of LST, especially as the broader market’s understanding of risk and product structure deepens, and as Over time they become more long-term credible. In addition, both Compound and Aave have joined Renzos ezETH governance measures.
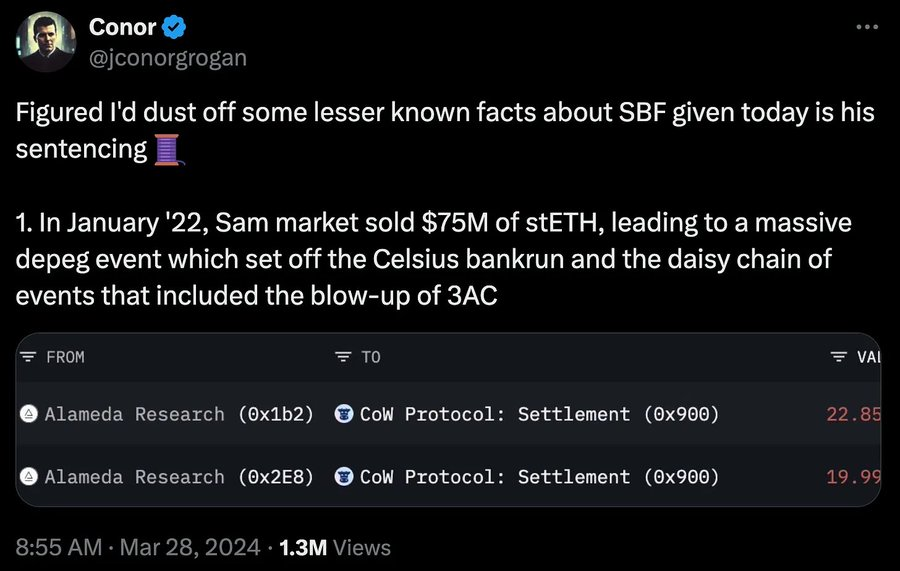
However, as mentioned earlier, liquidity will remain the lifeline of these products to ensure the breadth and depth of their DeFi integration and long-term vitality. We have already seen that LST decoupling can trigger a chain of chaos,Click here to read more.
Closing Thoughts
While stETH gained an early advantage and dominated due to its first-mover advantage, the series of LRTs mentioned in this report were all launched at roughly the same time and have strong market momentum. We expect this to be a winner-take-all market structure, as the law of power applies to most liquid assets; simply put, liquidity begets liquidity. This is why Binance continues to dominate CEX market share despite all the doubts and turmoil.
All in all, Liquidity Rehypothecation token liquidity is not amazing. Liquidity is acceptable, but each individual LRT has greater nuance associated with it, which will only continue to grow as agency strategies vary over the long term. From a mental model perspective, it may be easier for first-time users to think of LRT as a mortgage ETF. Many will compete for the same market share, but allocation strategy and fee structure may be the difference between winners and losers in the long term. Additionally, as products become more differentiated, liquidity will become more important due to the length of withdrawal periods. In the cryptocurrency world, seven days can sometimes feel like a month in normal time because global markets operate 24/7. Finally, as these LRTs begin to consolidate into the loan market, pool liquidity will become even more important as liquidators are only willing to take acceptable risks due to varying liquidity profiles of the underlying collateral. We believe token incentives may play an important role in this, and we look forward to delving into different token models following possible airdrop campaigns by other LRT providers.





