






SignalPlus Macro Research Report (20231211): The U.S. economy is better than expected


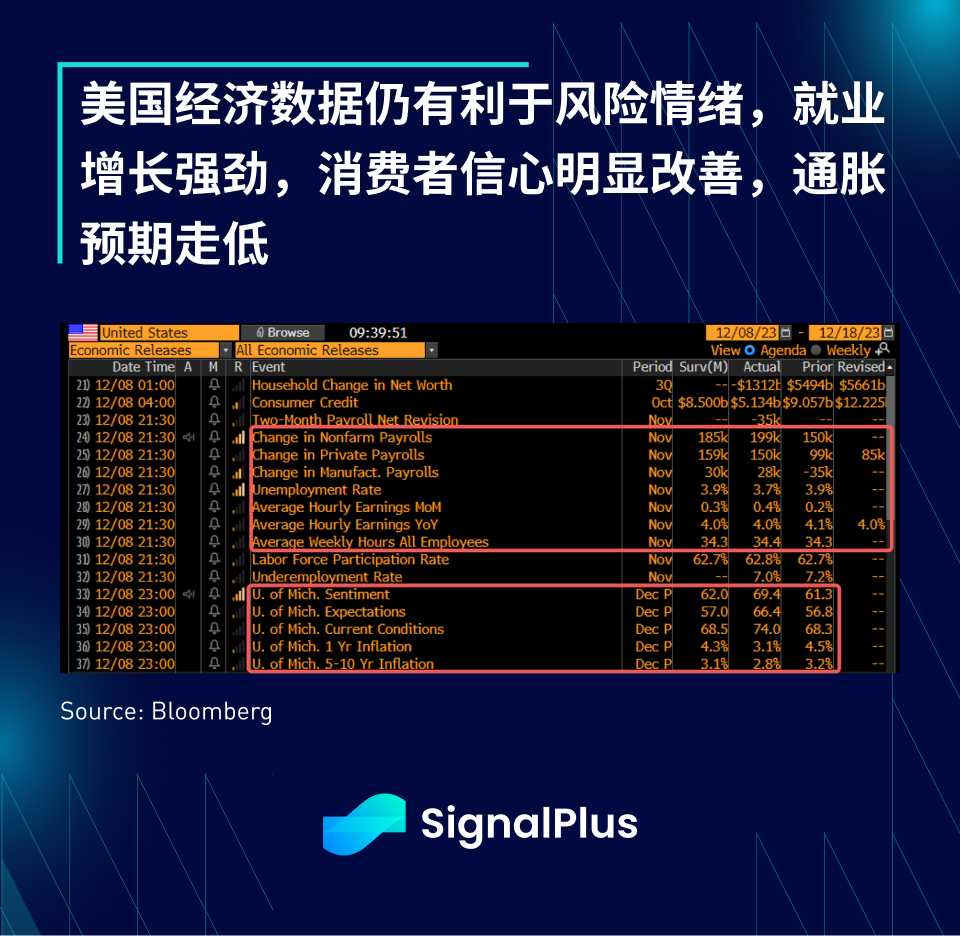
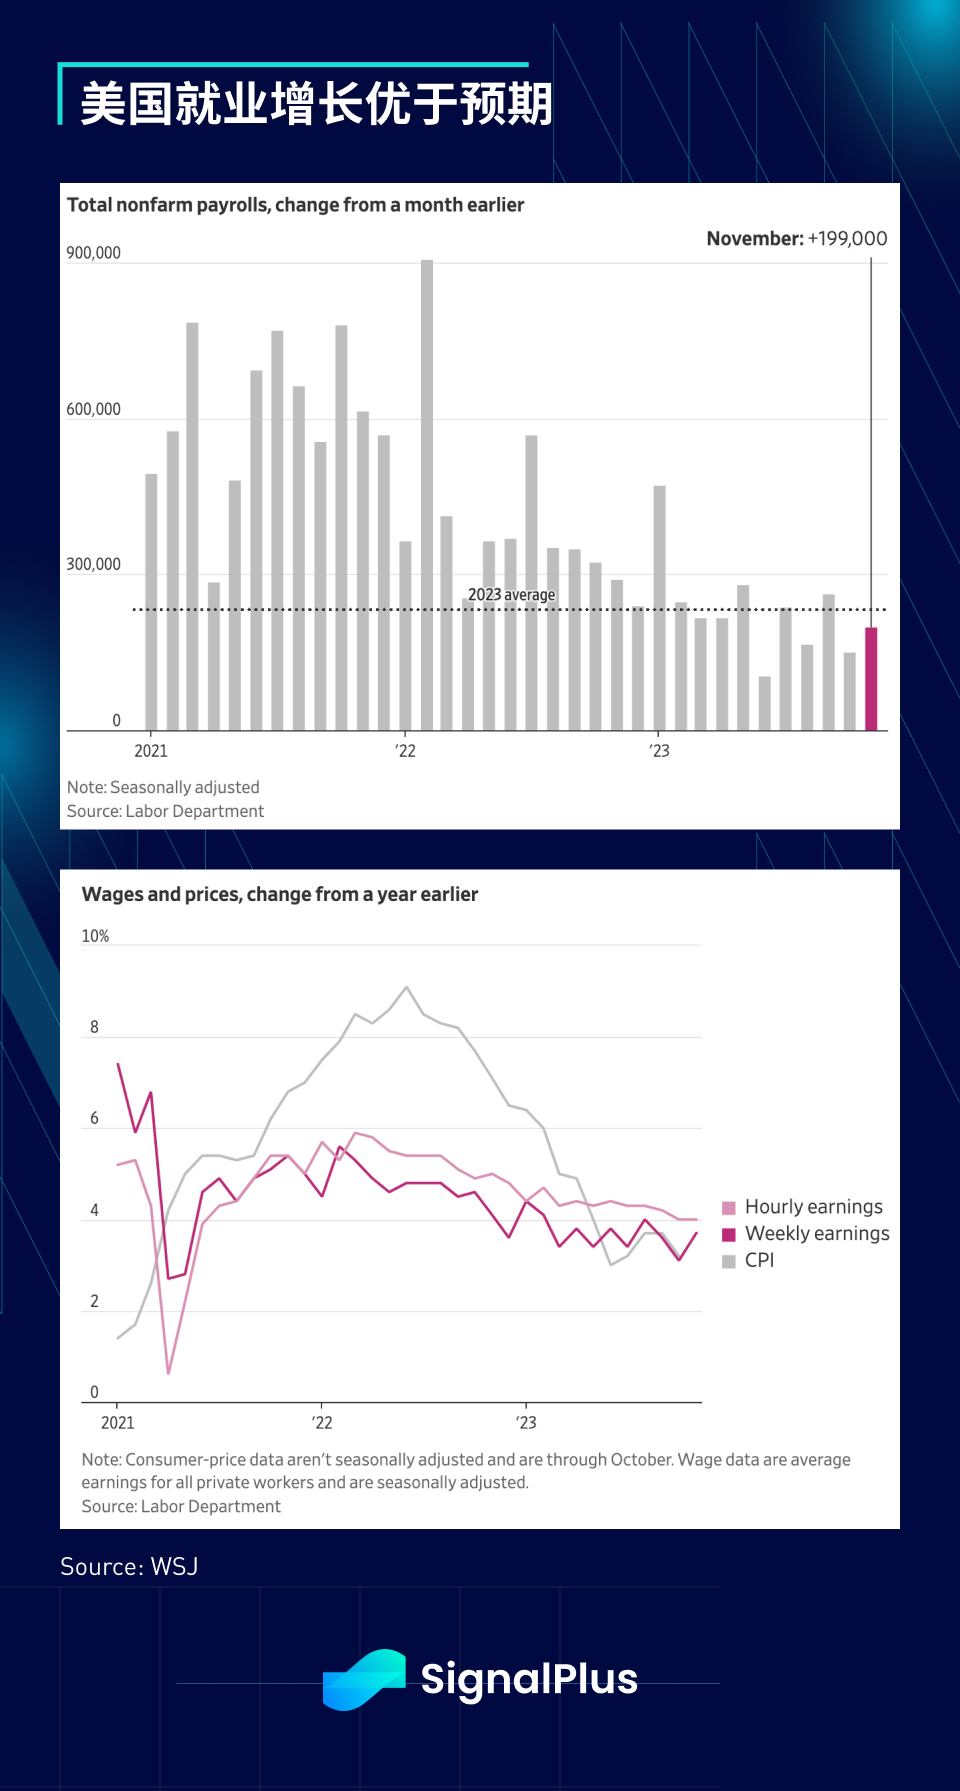
The U.S. non-farm payrolls increased by 199,000 in November, which was better than expected. The unemployment rate dropped from 3.9% to 3.7%. The hourly wage growth rose to +0.4% month-on-month. The average weekly working hours rose to 34.4 hours. Household employment continued to increase. After falling by 348,000 in October, there was a surge of 747,000 in November; the subsequent UM consumer survey also significantly exceeded expectations, with the confidence index jumping 8.1 points to 69.4, both the current situation index (74 vs 68.5) and the expectations index (66.4 vs 57). Better than expected, in addition, the 1-year inflation expectation fell to 3.1%, the lowest level since January 2021, while the 5-year inflation expectation also slowed sharply from 3.2% to 2.8%.
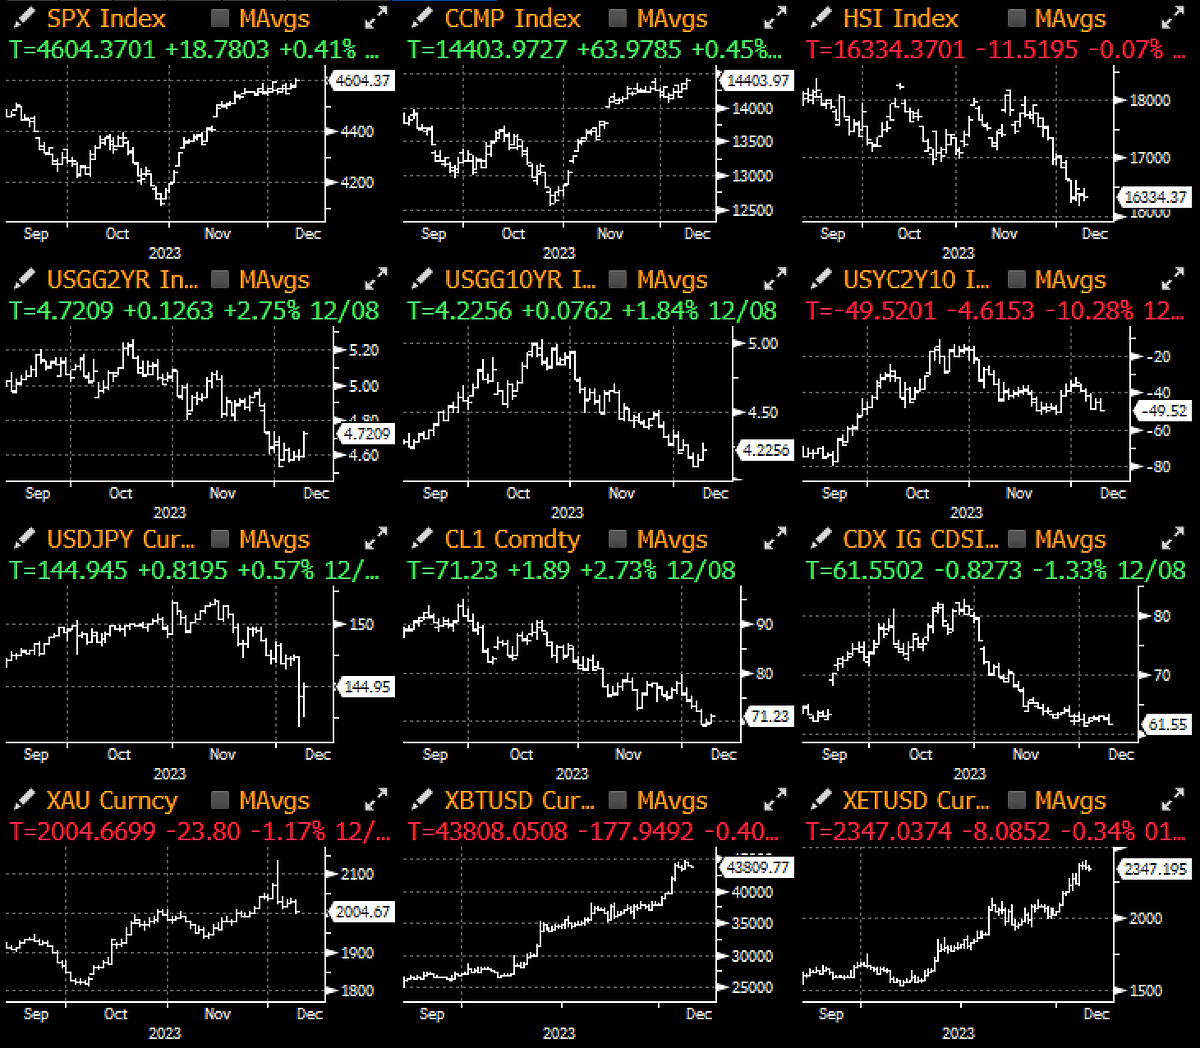
U.S. Treasuries have been at a disadvantage throughout the trading day on the back of the data, with the Japanese government bond market already softening overnight, while interest rate markets have been volatile ahead of the data release, with better-than-expected employment data and a lower-than-expected unemployment rate triggering a sharp rise in yields There was a bearish trend, with the 2-year yield jumping 13 basis points, SOFR futures falling 20 basis points in the afternoon, and the possibility of a March interest rate cut also falling from 65% to below 50%.
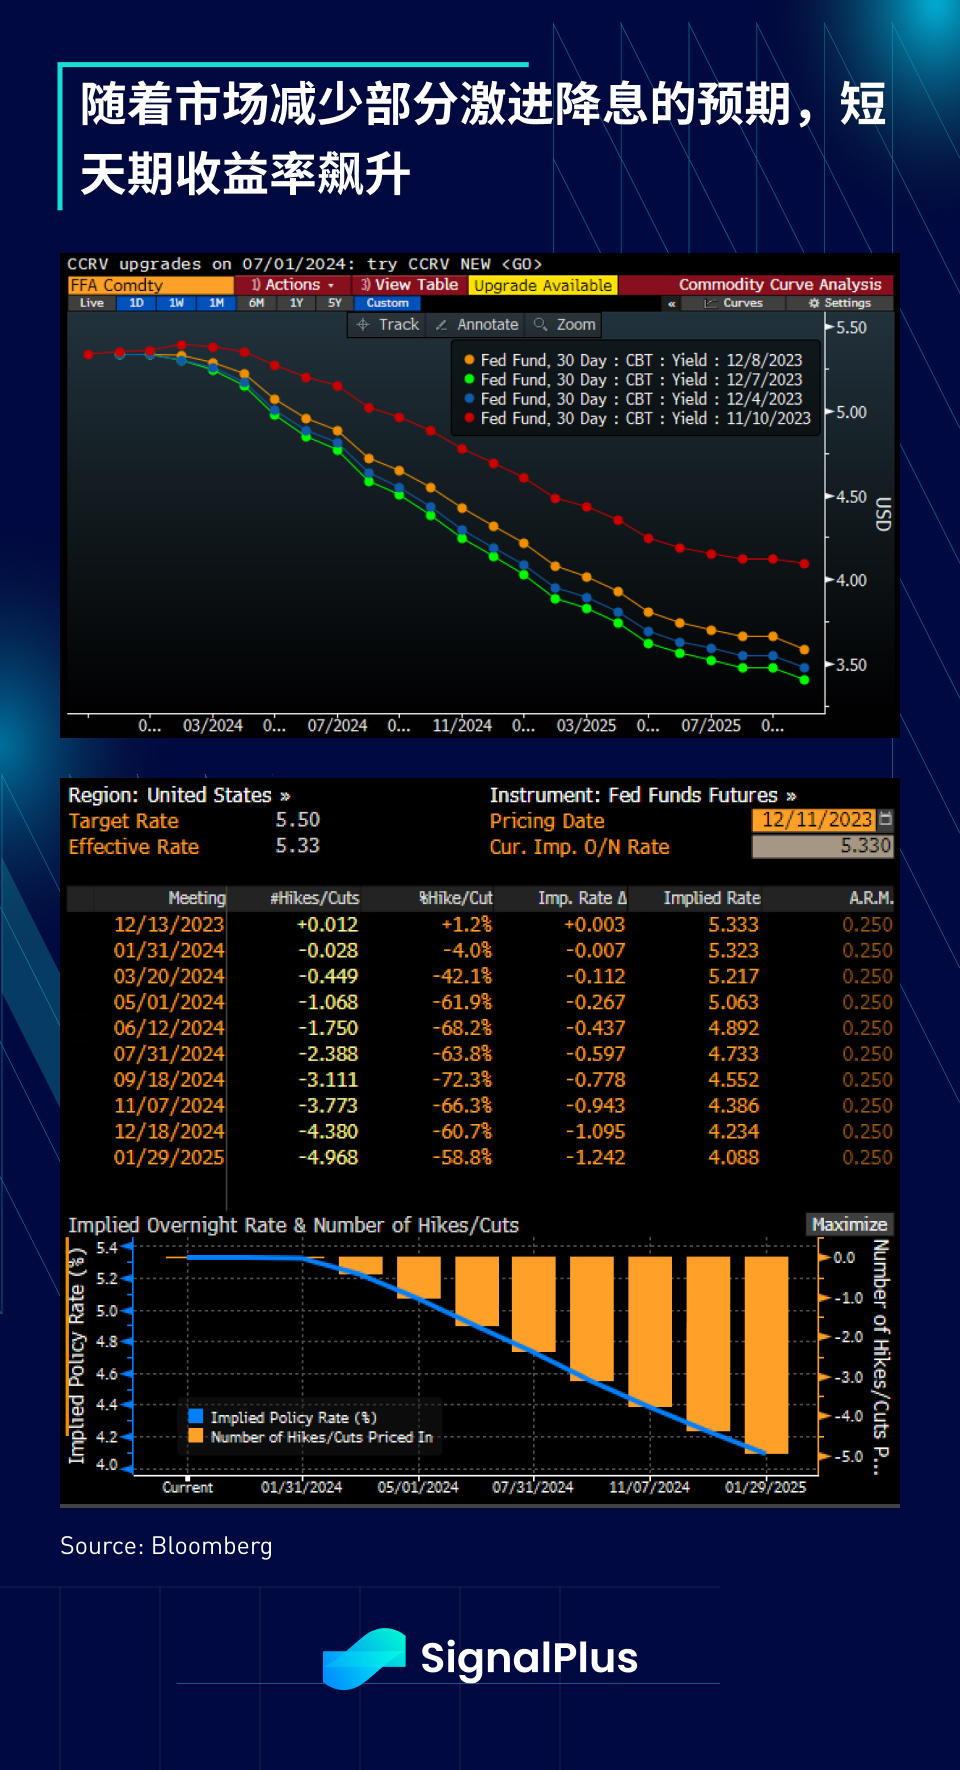
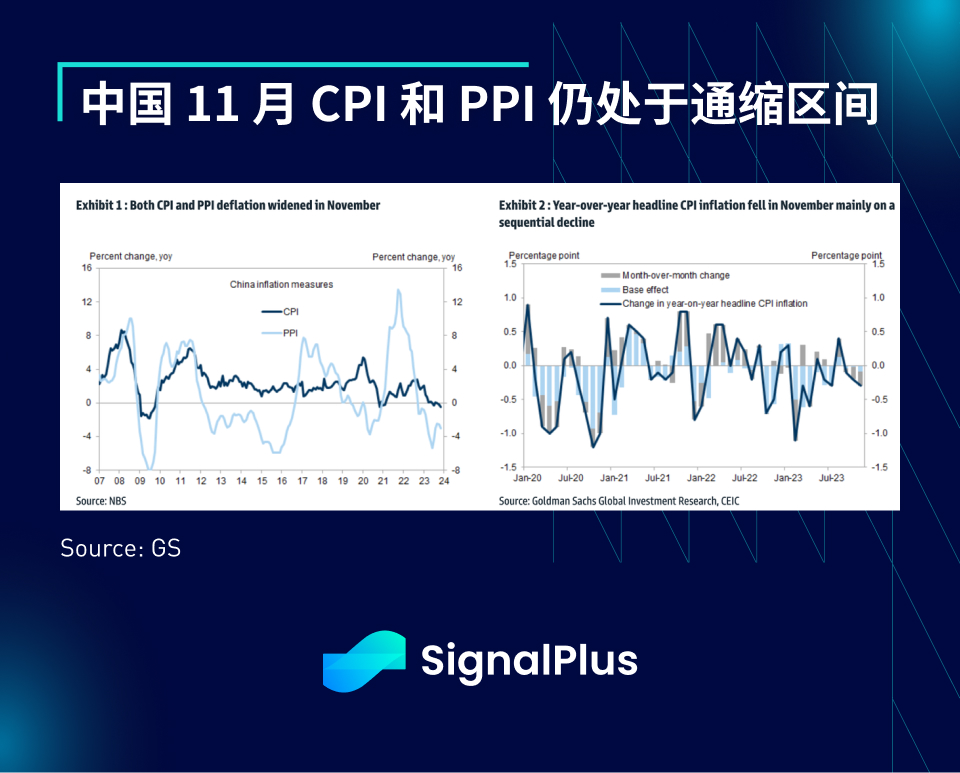
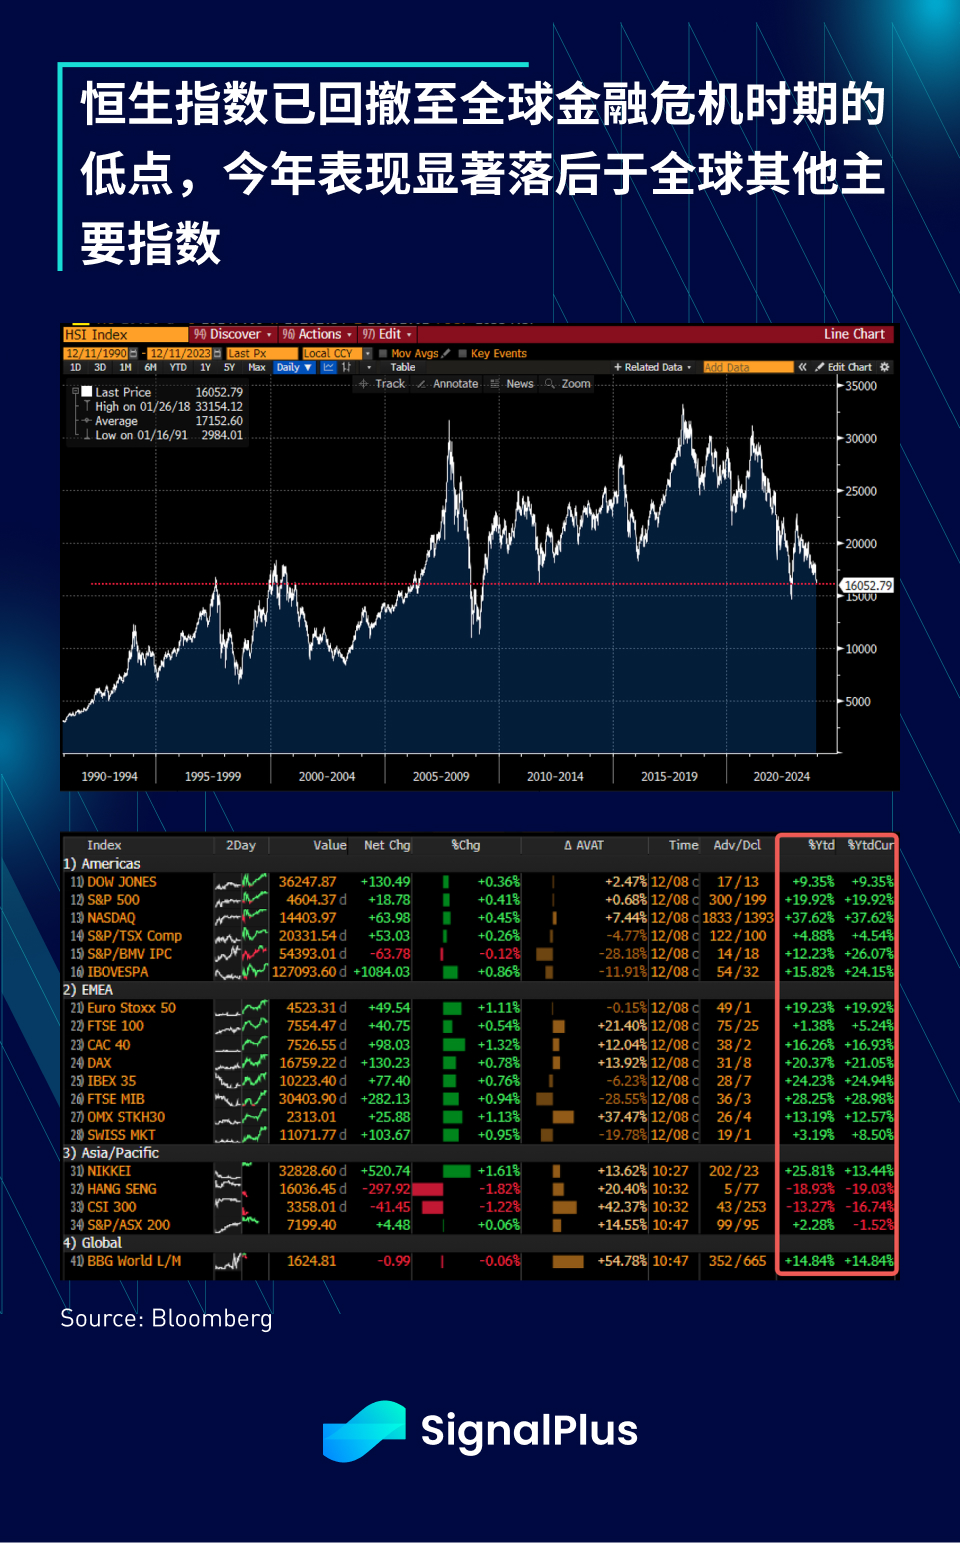
Ignoring the rise in interest rates, stocks instead chose to focus on the sharp decline in consumer inflation expectations, continuing to move higher after early losses. The market will face the challenge of CPI data tomorrow, but the market still has the opportunity to gain from the options expiry later this week. Support; SPX closed at the highest level since March 2022, oil prices fell for 7 consecutive weeks, DXY rebounded above 104, and as market expectations for the cancellation of ZIRP at the Bank of Japan meeting next week continue to grow, USD/JPY continues to hover below 145 On the other hand, Chinas CPI and PPI released over the weekend were still far below expectations, and CPI was completely in the deflationary range, causing the Hang Seng Index to fall nearly 2% in early trading today, close to the global financial crisis and the level before 2000.
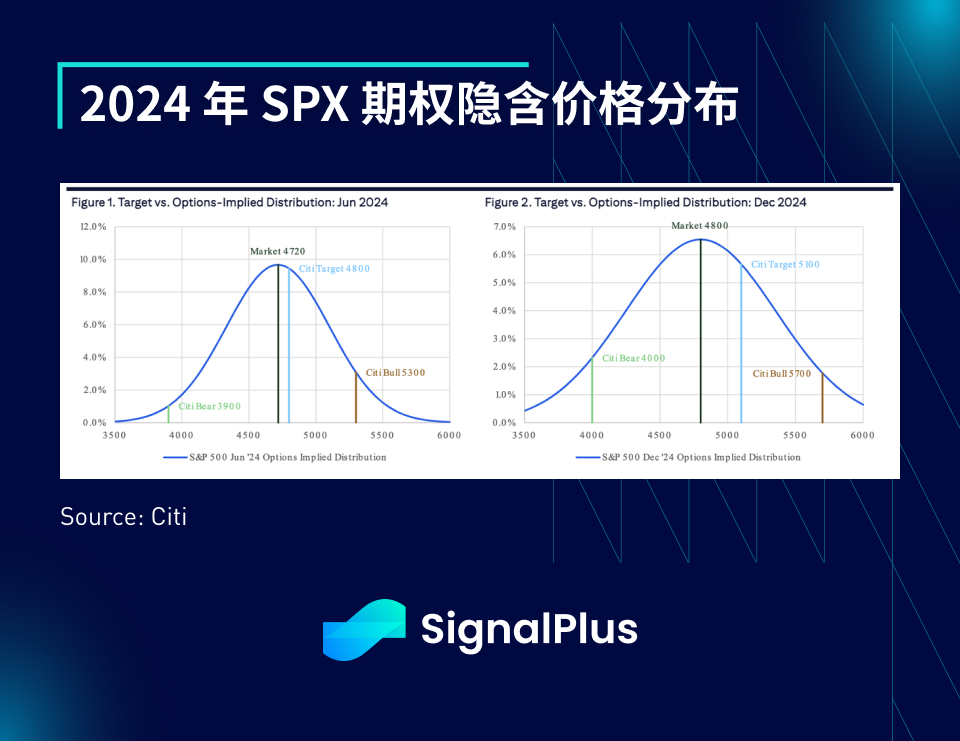
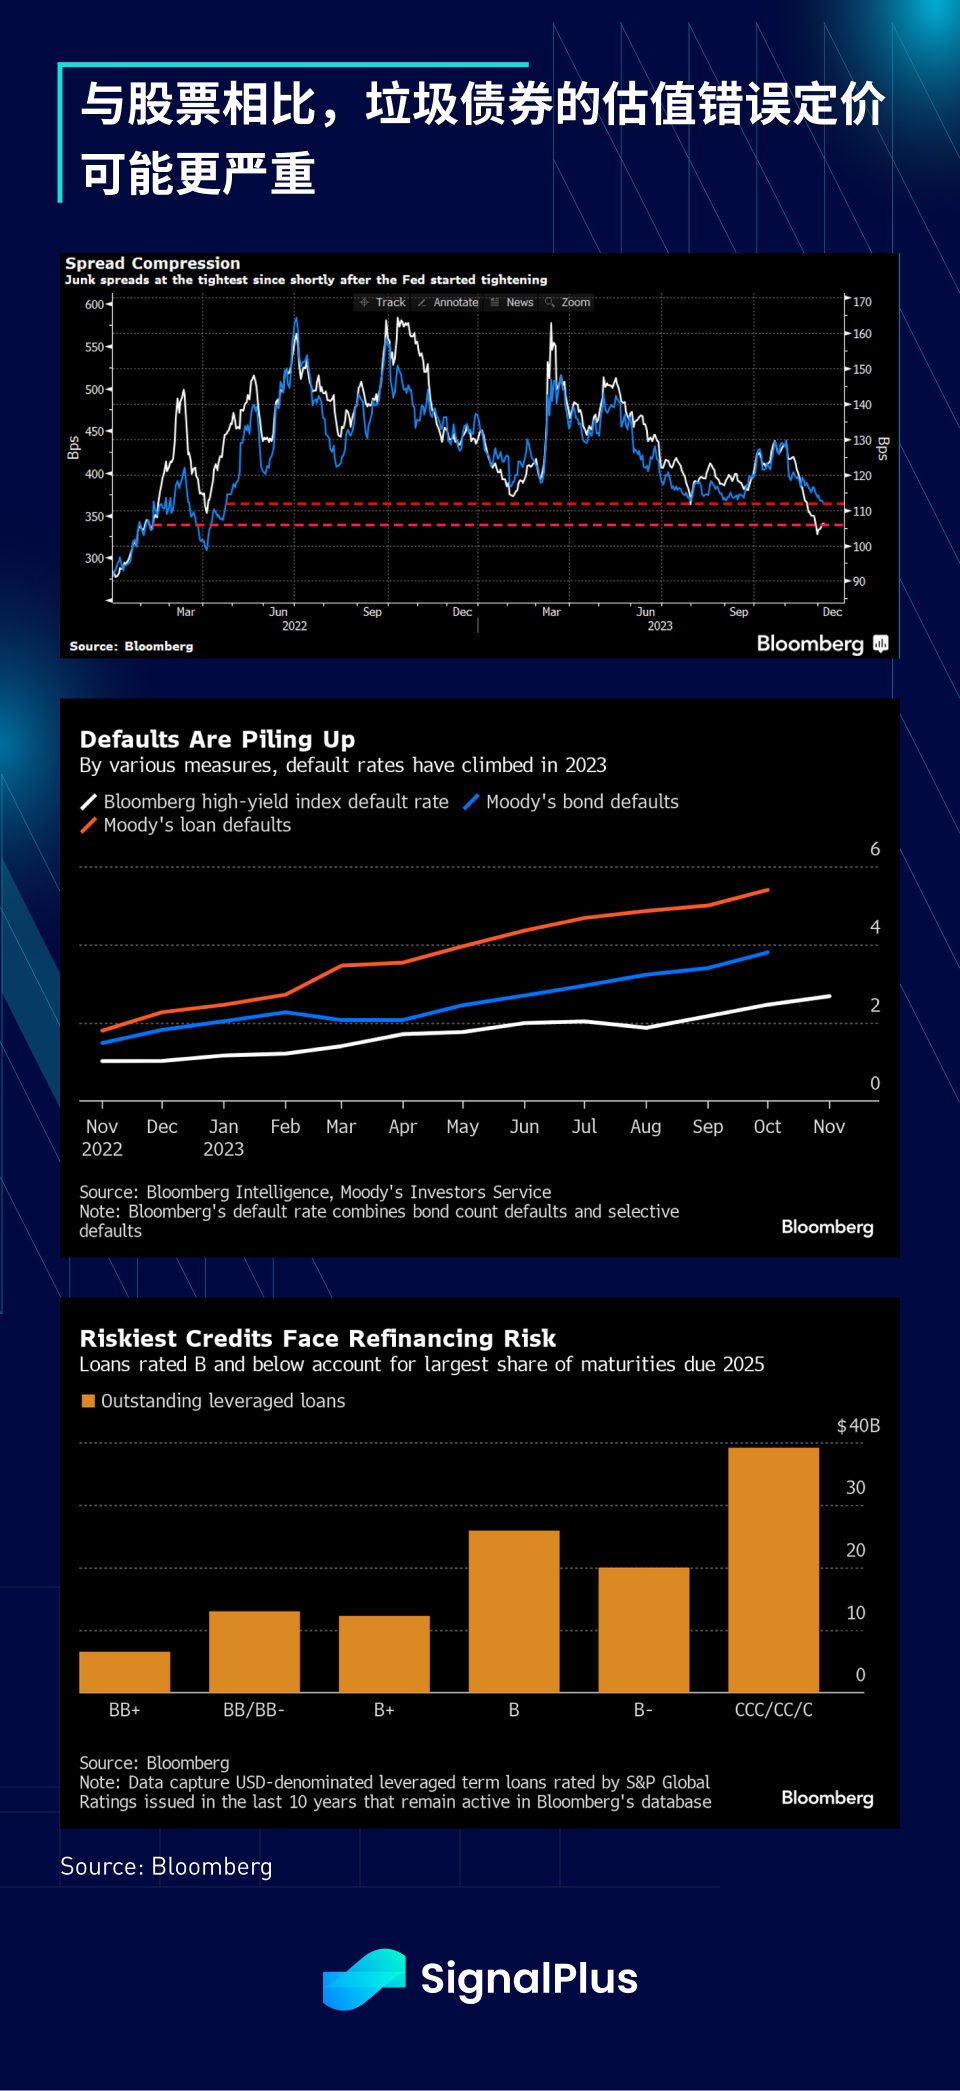
Looking ahead, the SPXs 2024 option-implied price distribution still looks quite good, with options expiring in June and December both expecting 3% upside, but credit bonds are more aggressively valued than equities, although this year Default rates have actually increased, and there are more refinancing risks in 2025, although junk bond spreads have still fully tightened to levels seen since the Feds first rate hike.
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption information. If you want to receive our updates immediately, please follow our Twitter account @SignalPlus_Web3, or join our WeChat group (add assistant WeChat: xdengalin), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website:https://www.signalplus.com





