






SignalPlus Macro Research Report Special Edition: Risk-On


Santa Claus came very early this year, nearly two months early.
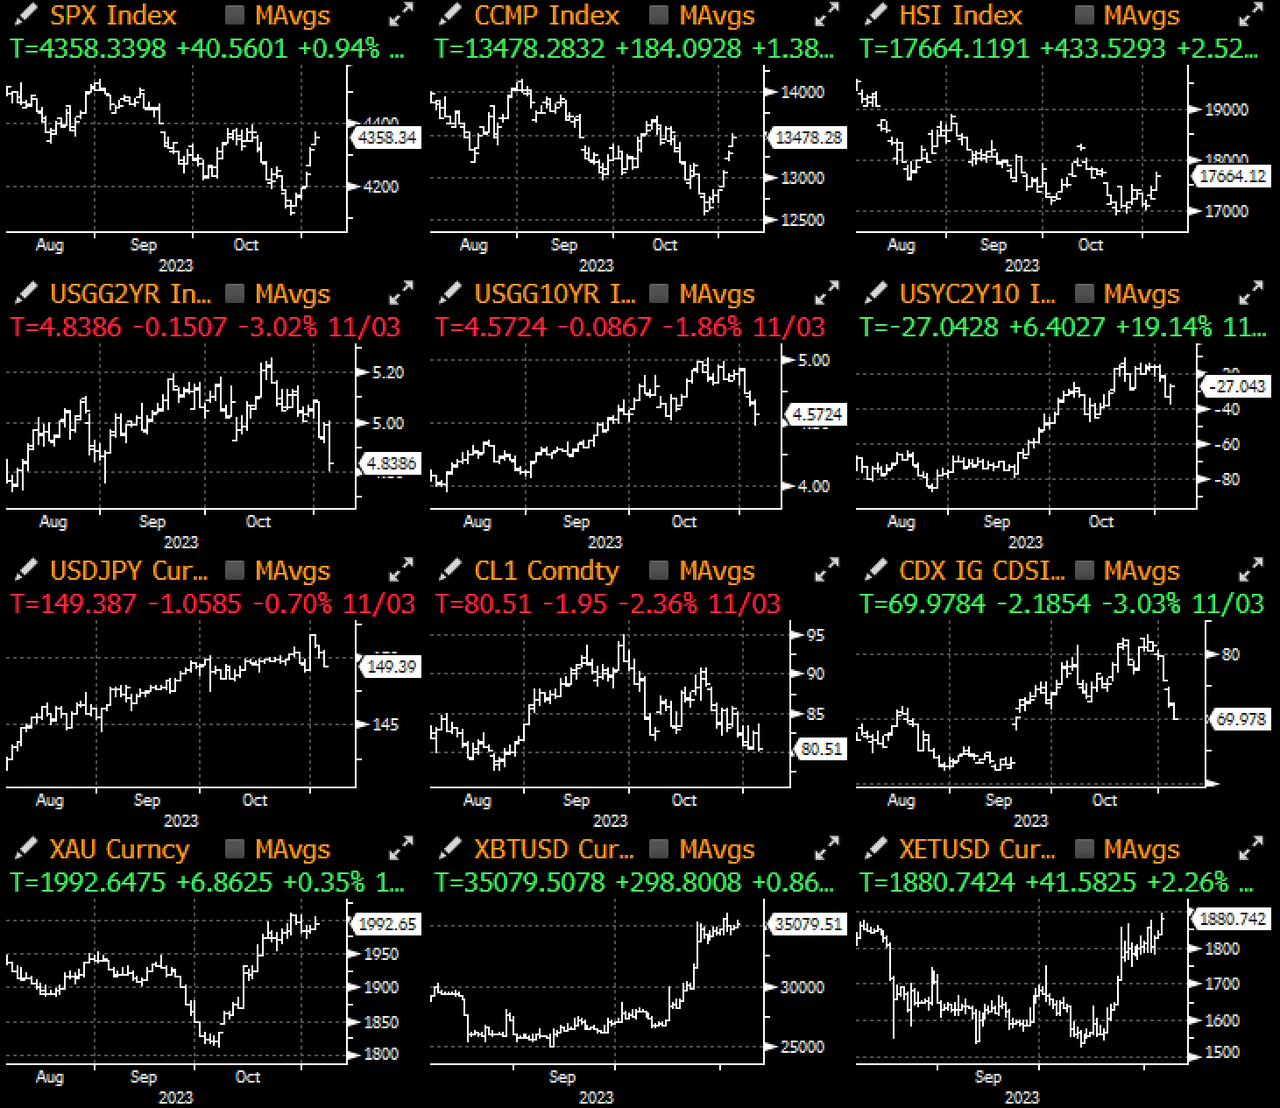
Yellens quarterly refinancing announcement was more dovish than expected and the relatively balanced FOMC outcome, coupled with lower-than-expected non-farm payrolls data, sparked a traditional risk-on rally across asset classes with stocks higher (+1.5%) , bond yields moved lower (-15 basis points for 2-year), DXY fell (-1.1%), investment grade CDS tightened (back to September lows), and the possibility of a rate cut resurfaced (possible in Q1 2024 Rate cuts started), cryptocurrency prices remained stable (BTC > $35k, ETH +2.3%), and even SBF was quickly convicted.
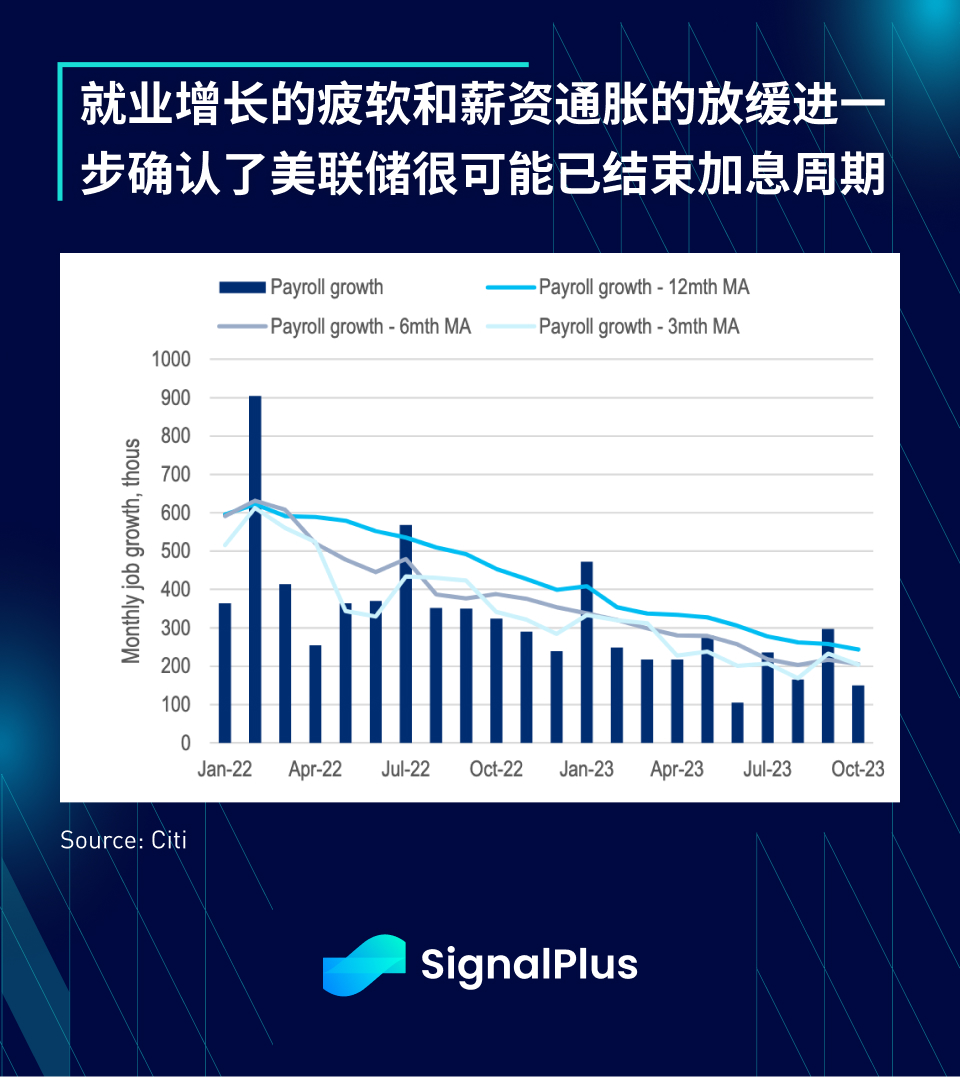
The U.S. non-farm payrolls increased by 150,000 in October, lower than market consensus. Data for the first two months were also revised down by 101,000. The unemployment rate rose to 3.9%, while hourly wages fell to 0.2% month-on-month. , year-on-year, fell to 4.1% from 4.3%, the lowest level since June 2021. The auto workers strike reduced the employment population by 33,000 people, while the weakness in manufacturing dragged down private sector employment.
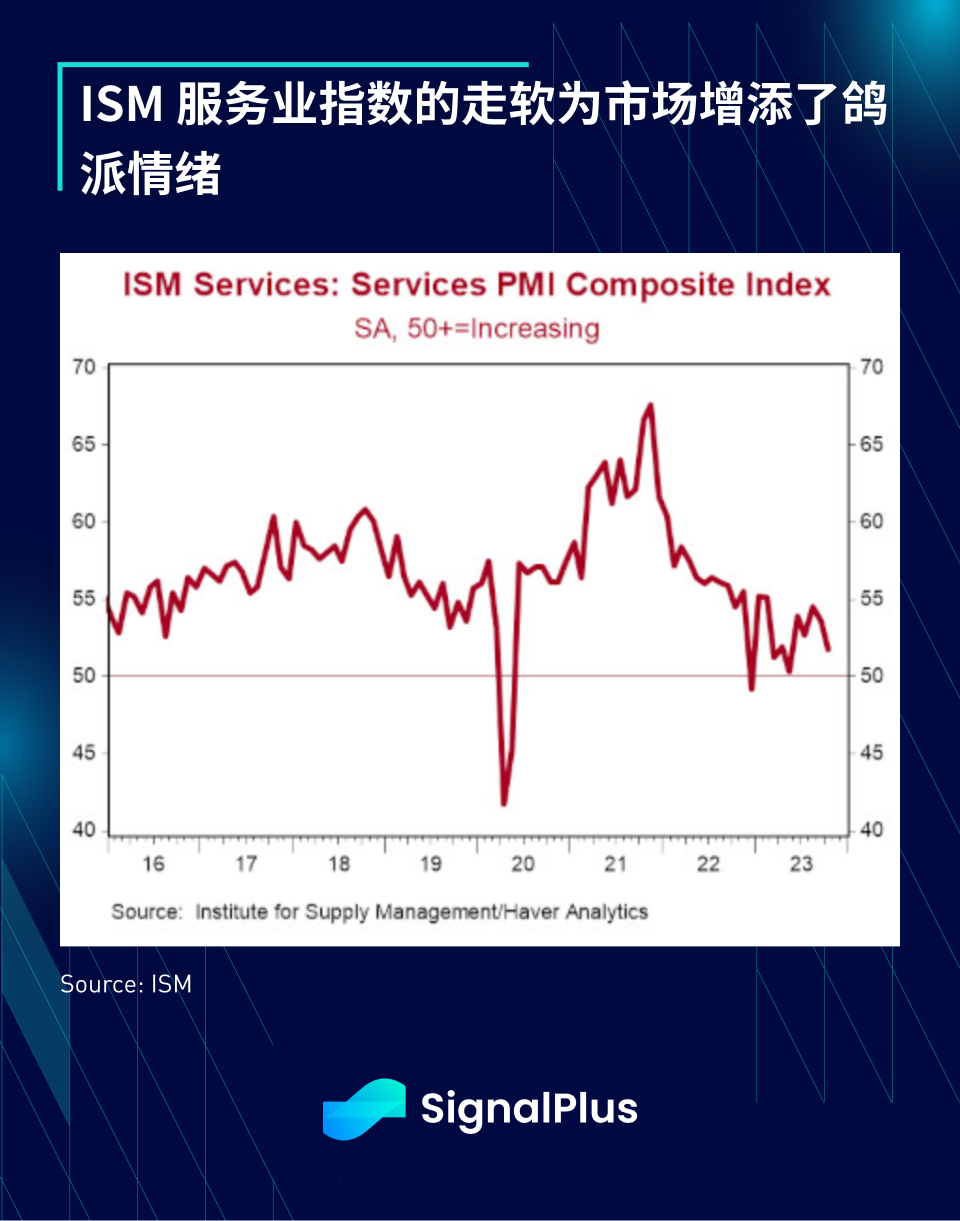
The subsequently released ISM services index was 51.8, a dismal performance that was far lower than expected, exacerbating the dovish interest rate outlook, with both employment (-3.2%) and new export orders (-14.9%) falling sharply.
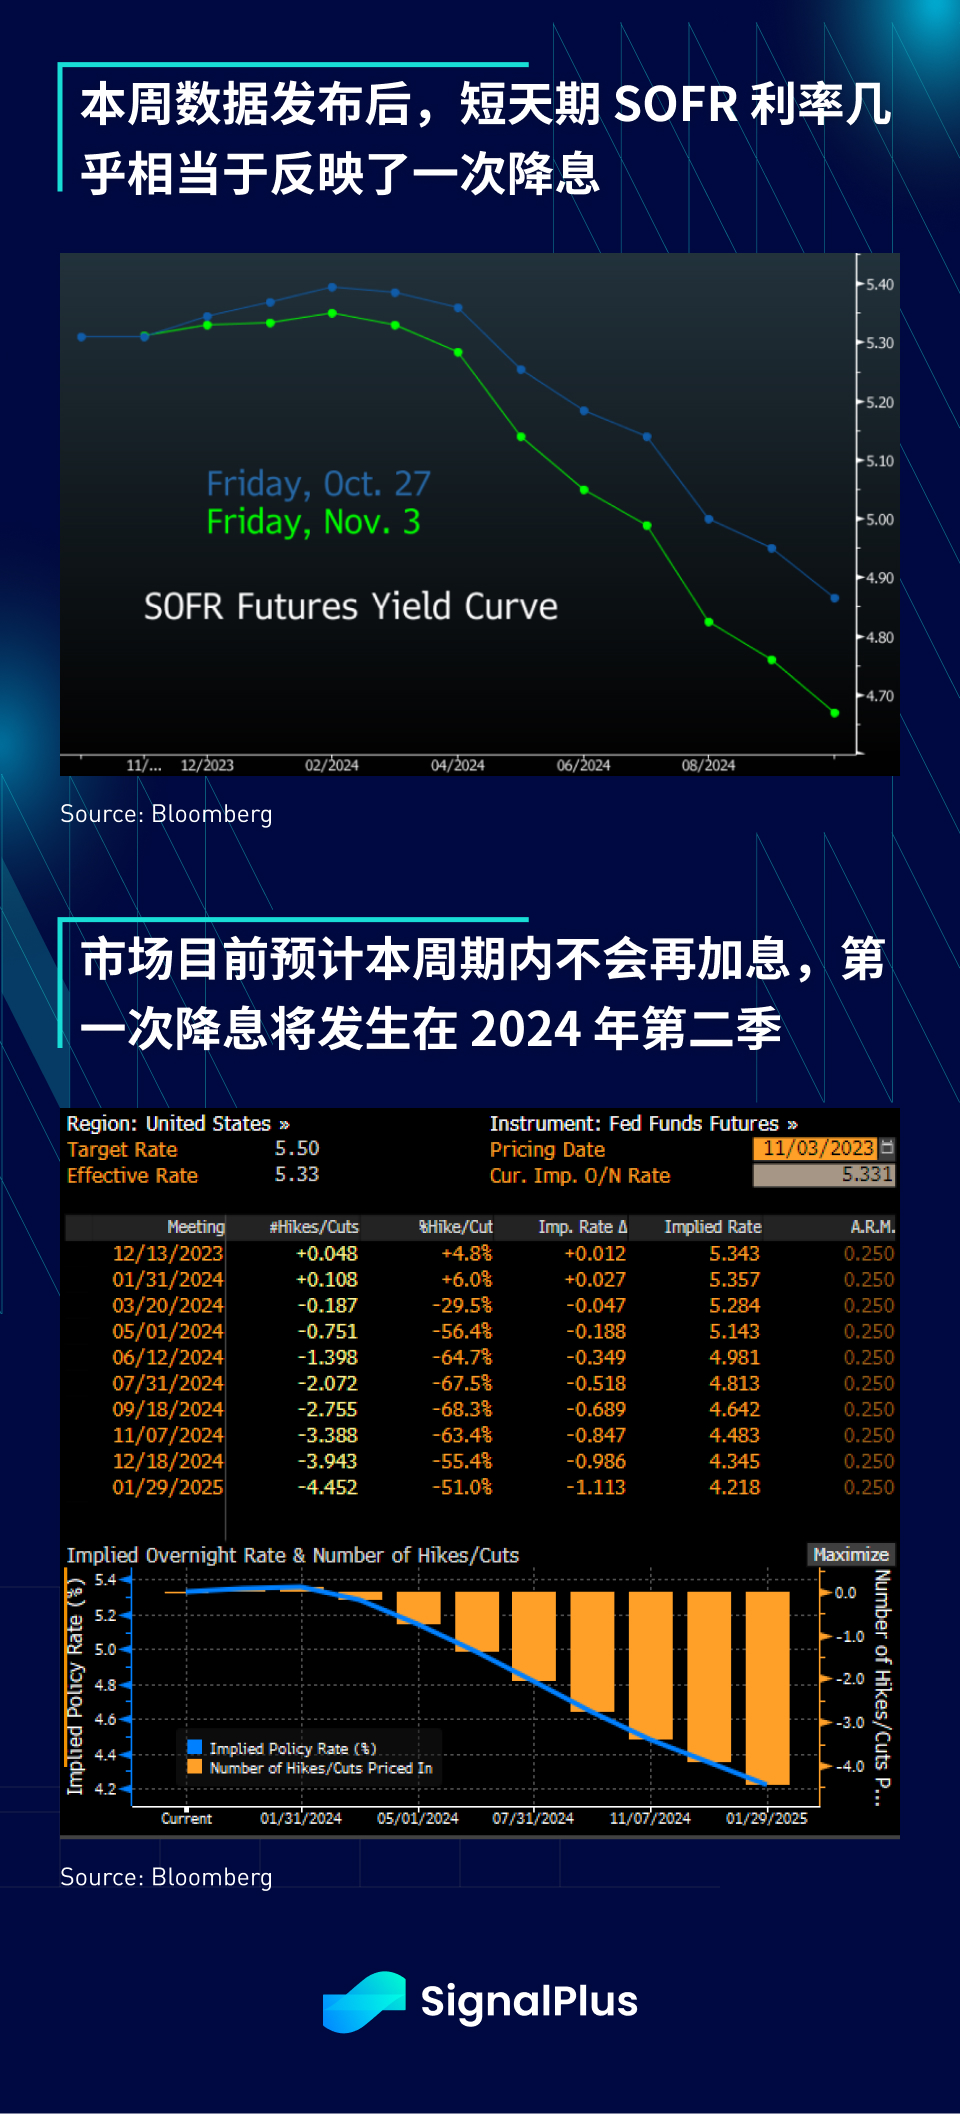
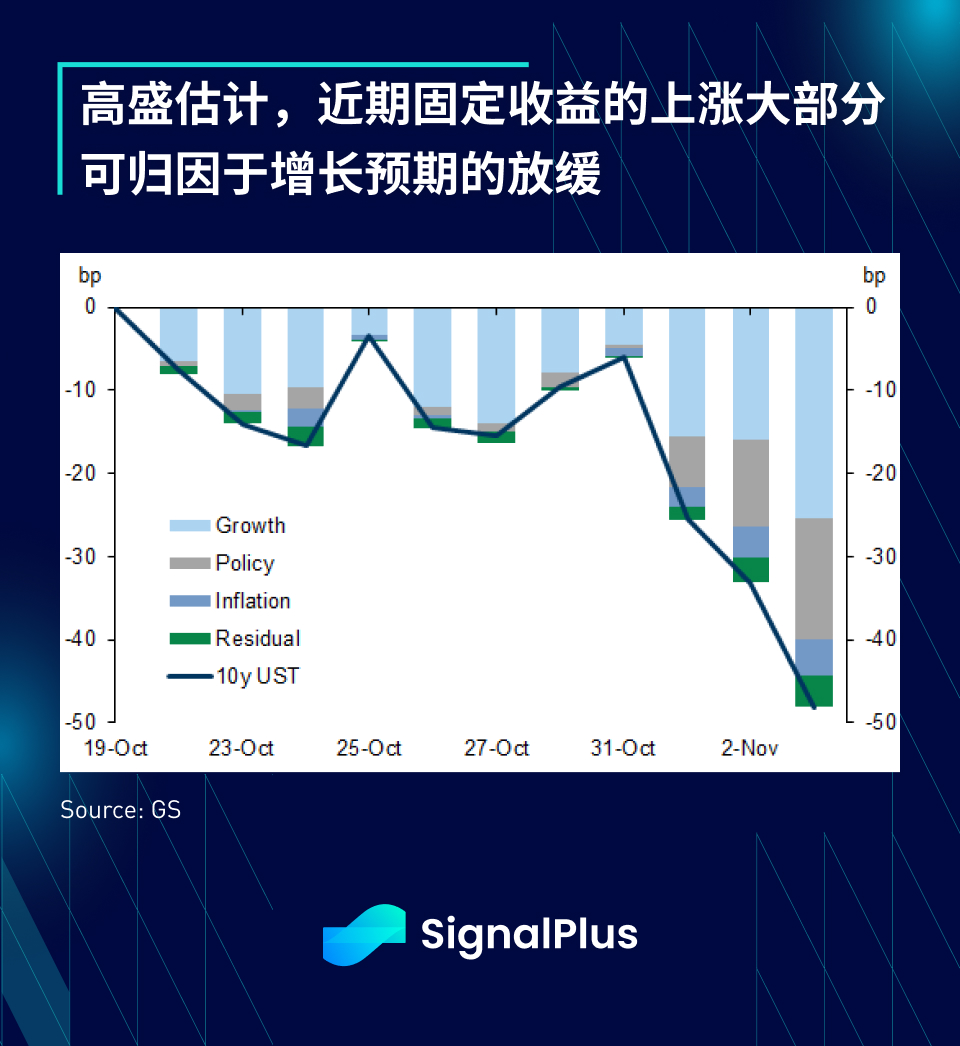
Fixed income markets got a blanket green light following the release of the non-farm payrolls data, with short maturities slipping 15 basis points and never to return, with sub-one-year rates falling about 20 basis points (almost as much) over the past week. (after one interest rate cut), the market currently does not expect to raise interest rates again during this cycle. The first interest rate cut will occur between March and June 2024. As economic activity weakens and price pressures continue to slow, the market generally expects that the Federal Reserve will Achieve a soft landing.
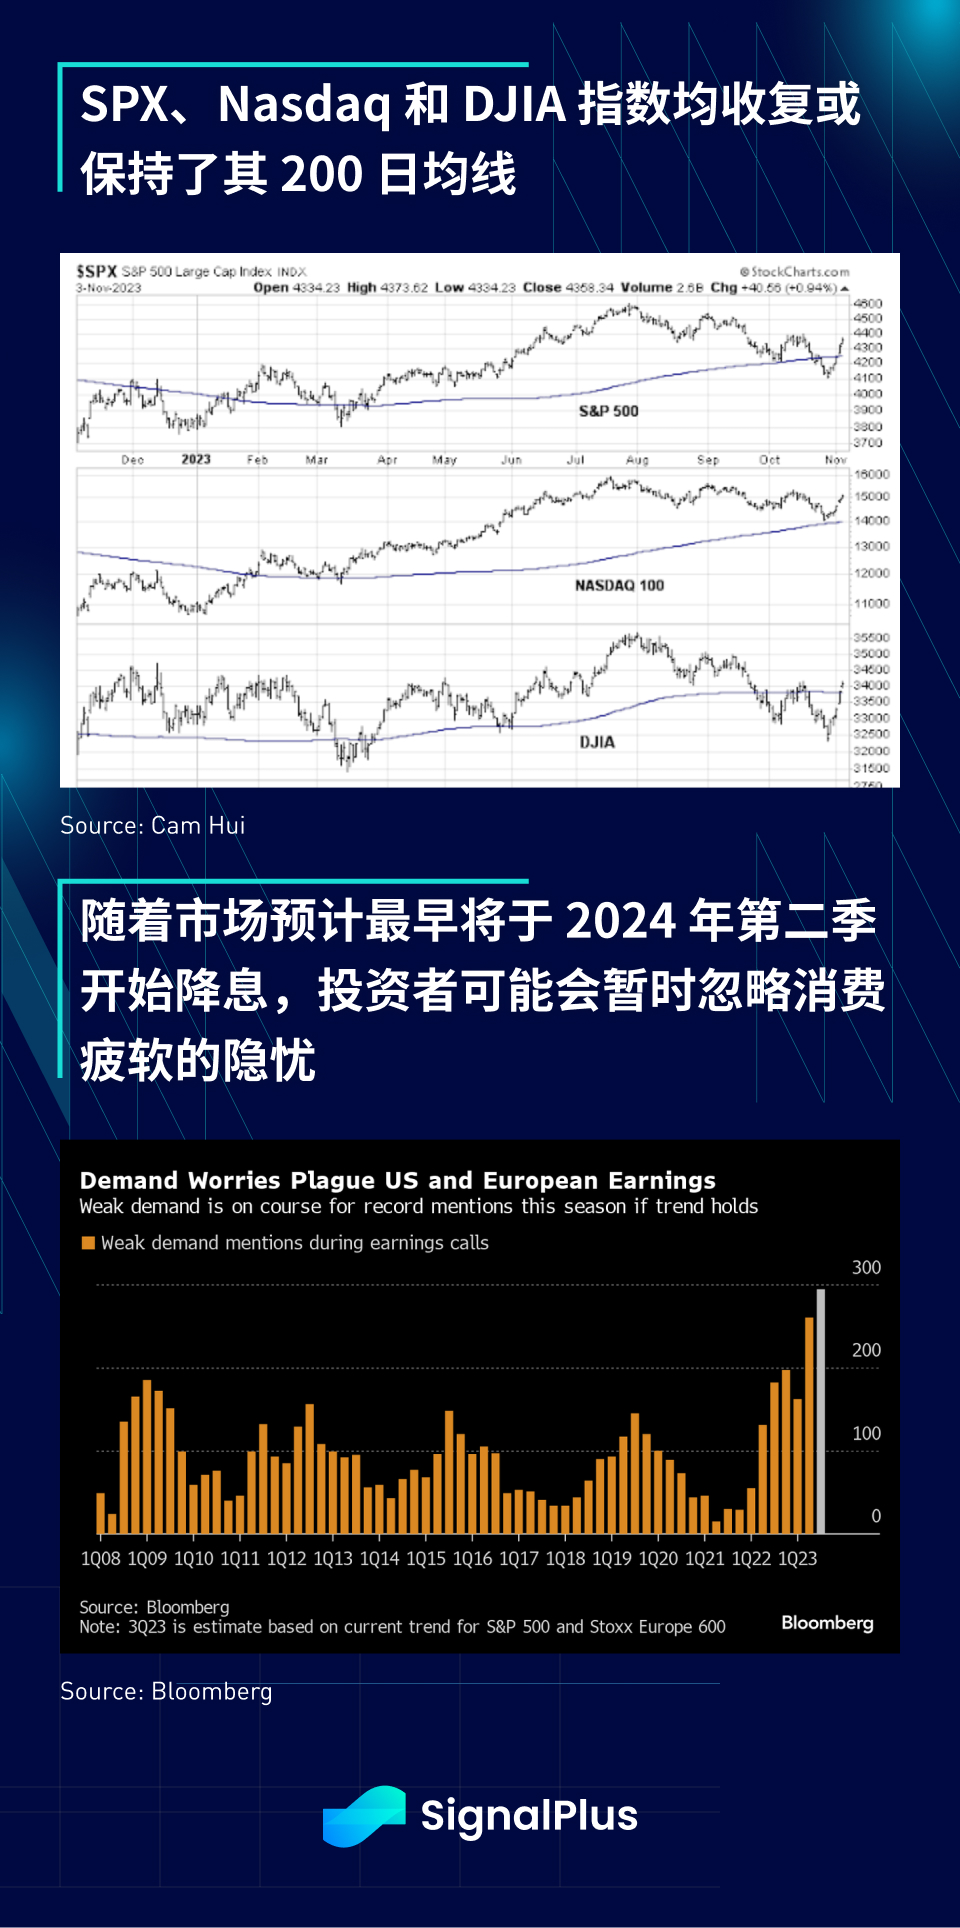
On the stock market, positive technical signals (SPX back to its 200-day moving average) and an oversold rebound have energized the rally, with investors likely in buy the dip mode and a lack of bearish factors, the Feds Uncertainty is low until at least early 2024, bond supply concerns have been postponed for at least another quarter, corporate earnings are mostly okay, and ongoing geopolitical conflicts (so far) have not caused negative knock-on effects In response, risk markets are likely to remain strong in the near term; in addition, while credit card spending data and managements forward guidance are beginning to show weakness in consumer demand, investors may temporarily ignore consumption given market expectations that the Federal Reserve will ease policy next year. The problem with weakness is that, for now, a lackluster market could be a good market.
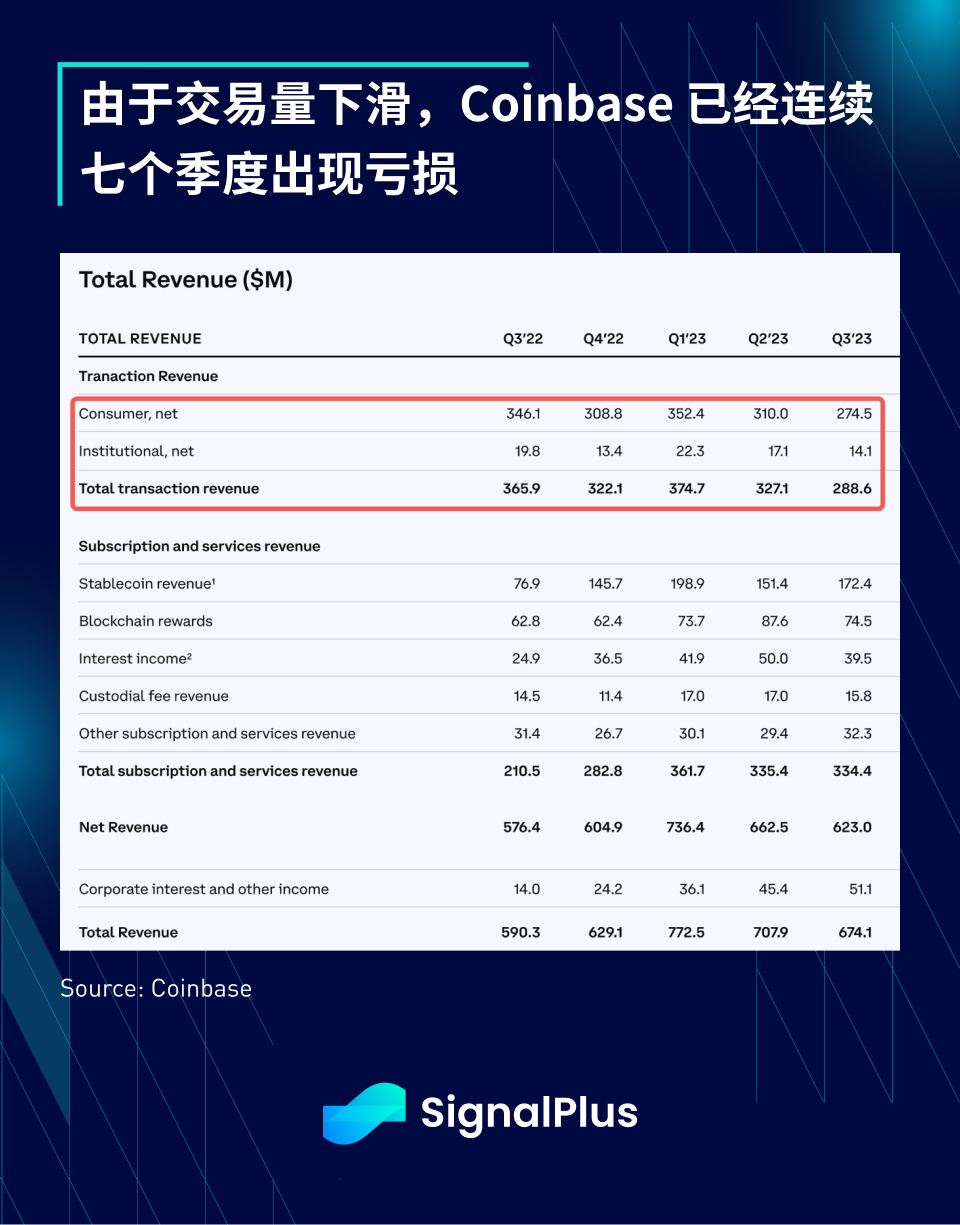
On the crypto side, given the price action to date and higher option volatility, we remain positive on prices, and with relatively low positioning exposure, further increases in risk sentiment should help lift crypto prices. On the other hand, although both retail and institutional trading volumes continued to decline, Coinbases third-quarter earnings still exceeded analysts lowered expectations. However, despite raising retail fees last quarter, this is Coinbases seventh consecutive quarter. A loss occurred.
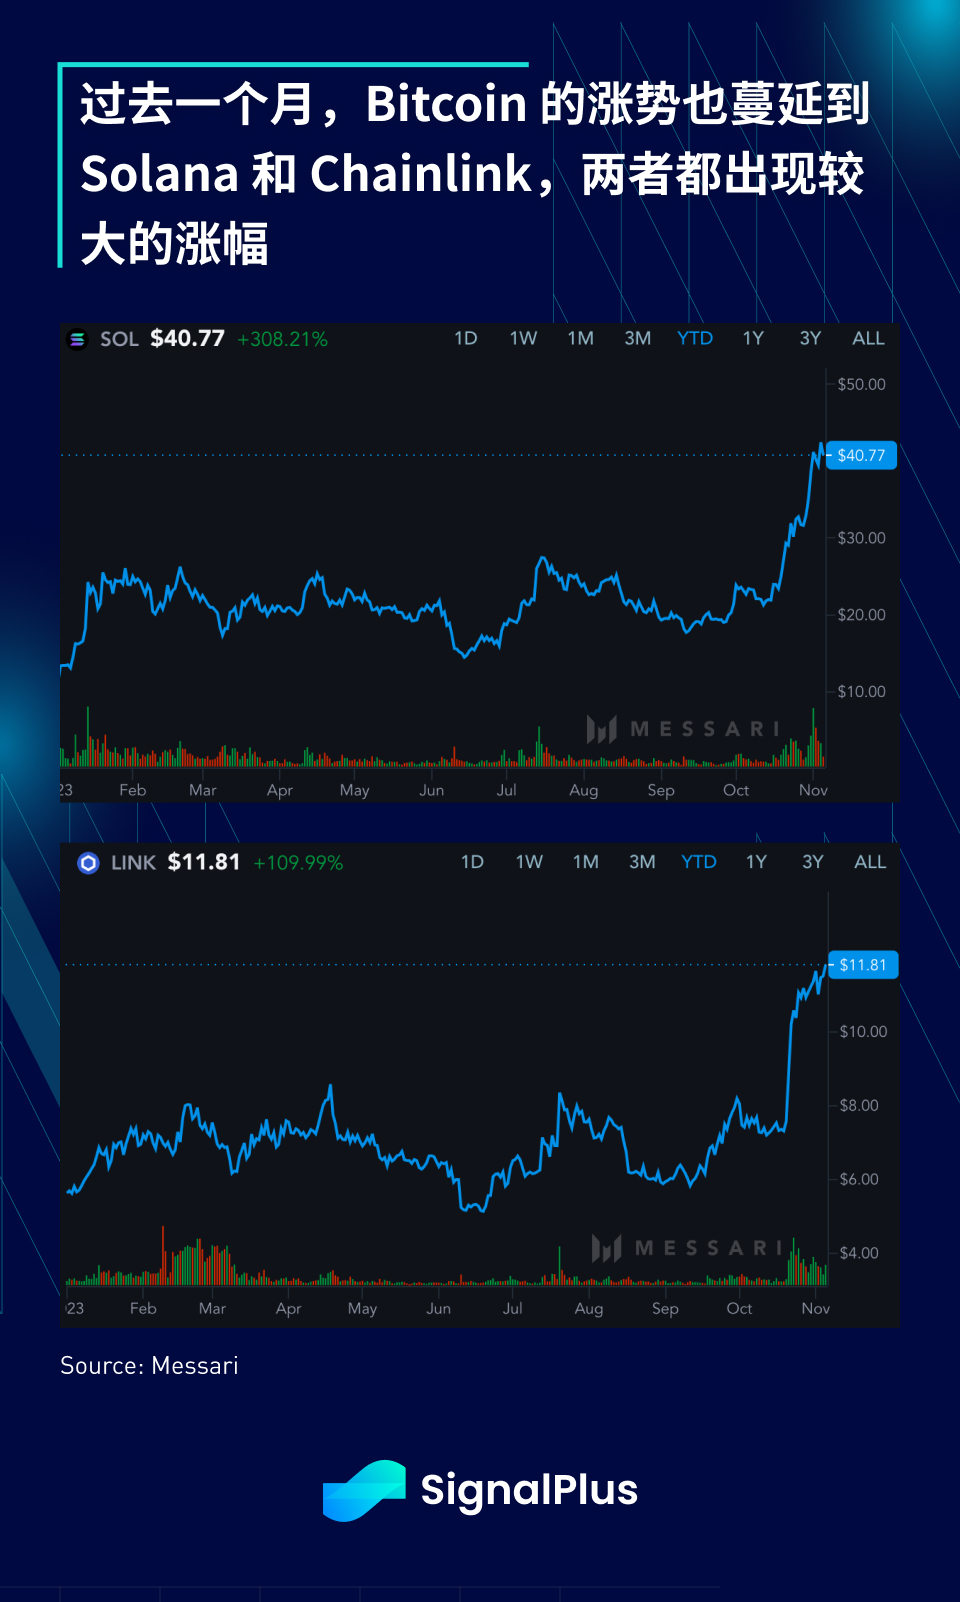
Outside of the major coins, Solana and Chainlink tokens have seen a dramatic rally over the past month, nearly doubling in price, with Solana’s network statistics improving (NFT minting volume up 300% month-on-month, DeFi TVL 30% increase (and maybe SBF convicted premium?), and Chainlink is benefiting from the narrative and craze of RWA tokenization. After all, the huge market potential is everyone’s favorite story, hoping for market momentum this time be able to keep it up.
You can search for SignalPlus in the Plugin Store of ChatGPT 4.0 to get real-time encryption information. If you want to receive our updates immediately, please follow our Twitter account @SignalPlus_Web3, or join our WeChat group (add assistant WeChat: xdengalin), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website:https://www.signalplus.com





