






Interpretation of Coinbases third quarter financial report: Total revenue is higher than market expectations, and the intensity of bargain hunting is increasing


Original author: Phyrex (X: @Phyrex_Ni)
Editors note: Recently, Coinbase announced its third quarter financial report for 2023. The report showed that Coinbases revenue in the third quarter was US$674.1 million, exceeding analysts expectations, a decrease of 4.7% from the previous quarter, but a year-on-year increase of 14.2%. Coinbase had a net loss of $2 million in the quarter, compared with a loss of $545 million in the same period last year. Coinbase wrote in a letter to shareholders: The third quarter was a strong quarter for Coinbase. Although we incurred a net loss in the third quarter, we are on track to achieve positive Adjusted EBITDA in 2023, which Reflects the direction we set at the beginning of the year to become a company that can generate (positive) Adjusted EBITDA under all market conditions.
Analyst Phyrex published an article interpreting Coinbases third quarter financial report for 2023, and judging the current investor status through Coinbases financial report, Odaily compiled it as follows:
Total revenue topped market expectations and losses fell to $2.3 million
After the U.S. stock market opened last night, I have been noticing that Coinbases stock price jumped up and jumped by nearly 9% by the close of trading. I originally thought that there were unknown benefits to be released, which led to a large number of investors snapping up, but after reading the financial report, I just It can be described as mixed. Let’s talk about the results first and then look at the details. After the financial report was released, Coinbase’s stock price fell by more than 4% in pre-market. Generally speaking,BlackRocks application for a Bitcoin spot ETF in June did stimulate market trading volume and user sentiment, causing Coinbases revenue to increase by 14% to $674 million, higher than market expectations of $654 million, but the trading volume was only US$76 billion, lower than market expectations of US$80.4 billion.It was also down from $92 billion in the second quarter. This is the main reason why Coinbase’s stock price fell.
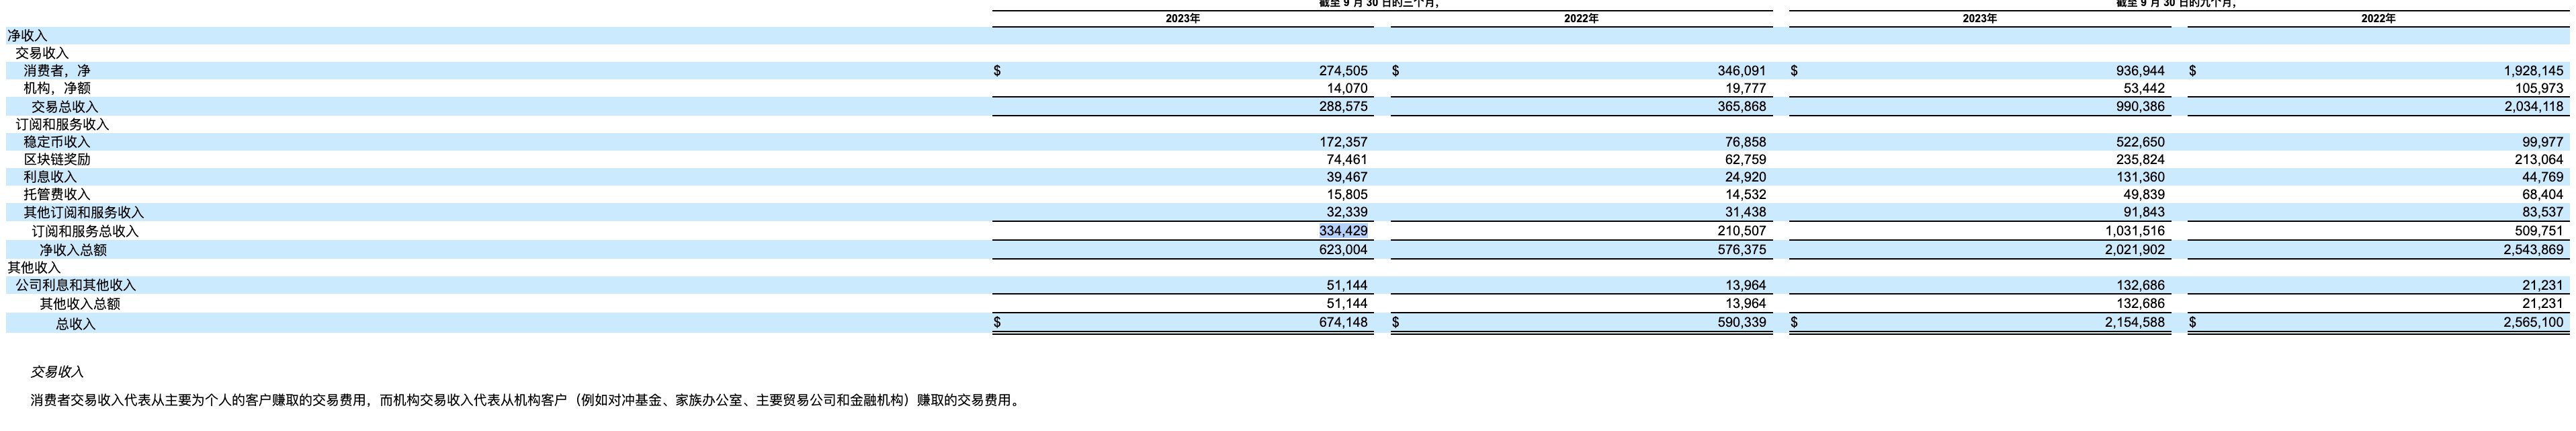
However, although Coinbase has lost money for seven consecutive quarters, its loss this quarter dropped to $2.3 million from $545 million in the same period last year.Considering that the fourth quarter is likely to bring greater trading volume and user sentiment, it is very likely that Coinbase can turn a profit in the fourth quarter. andThe main reason for Coinbases profit this time is to jointly operate USDC with Circle, and enjoy the benefits obtained from USDC reserves purchasing U.S. bonds.In particular, Circles reserves are mostly based on short-term U.S. bonds, and the yield on short-term U.S. bonds is generally around 5.3% even now. This week, it even released the function that qualified U.S. investors can trade futures. Of course, these are not the focus. The point is that we use detailed data to see the true reaction of American investors.
Stablecoin returns were higher than the same period last year, and market makers left the market
The first is that the main trading gains can be seen in the data as of September 30.Ordinary users contributed US$274 million in fees, down from US$346 million in the same period in 2022, while transaction revenue in the first nine months of 2023 was less than US$937 million, significantly lower than the US$1.928 billion in the same period last year.That is to say, the total user transaction volume in the first three quarters of 2023 decreased by one billion US dollars compared with the same period last year.This represents a decline in user sentiment and a shortage of liquidity in the market.The situation is the same as what we are analyzing together. Moreover, user transaction fees in the third quarter were lower than the average of the first three quarters, which is normal. After all, sentiment improved only in one month from mid-June to the end of July.
Another important data comes fromThe income of institutions (including market makers) was only US$14.07 million, which was lower than the level of nearly 20 million in the same period last year. At the same time, the revenue contributed by institutions in the first three quarters of 2023 was only less than US$100 million, which was lower than the same period last year. half ofMoreover, the contribution of institutional income in the third quarter was lower than the average of the first three quarters, which also illustratesAs regulation by the SEC and CFTC intensifies, not only are market makers leaving the market, but even the investor enthusiasm of institutional investors continues to decrease.The biggest benefit in terms of revenue is the revenue from stablecoins. It can be seen that the revenue in the third quarter was US$172 million, which was nearly US$100 million higher than the same period last year.Stablecoin earnings in the first nine months of 2023 were $522 million, more than five times higher than the same period last year.Stablecoin gains in the third quarter were slightly lower than the average of the previous three quarters.
We can even see that Coinbases non-trading revenue, including stablecoin revenue, block rewards, interest and custody revenue, was $334 million in the third quarter, exceeding 16% of the $288 million in trading revenue. If purelyCalculating only trading profits, Coinbase has lost money to the point where it is just underwear. Not only is it significantly lower than the level of the same period last year,Moreover, the trading income in the third quarter was also lower than the average income in the first three quarters, and this data is telling us,American small-scale investors, American institutions, and American market makers are gradually moving away from cryptocurrency trading.Of course, this data was before the hot spot ETF speculation in October. It is expected that the data in the fourth quarter will improve, but judging from the current forecast data, the help is limited.
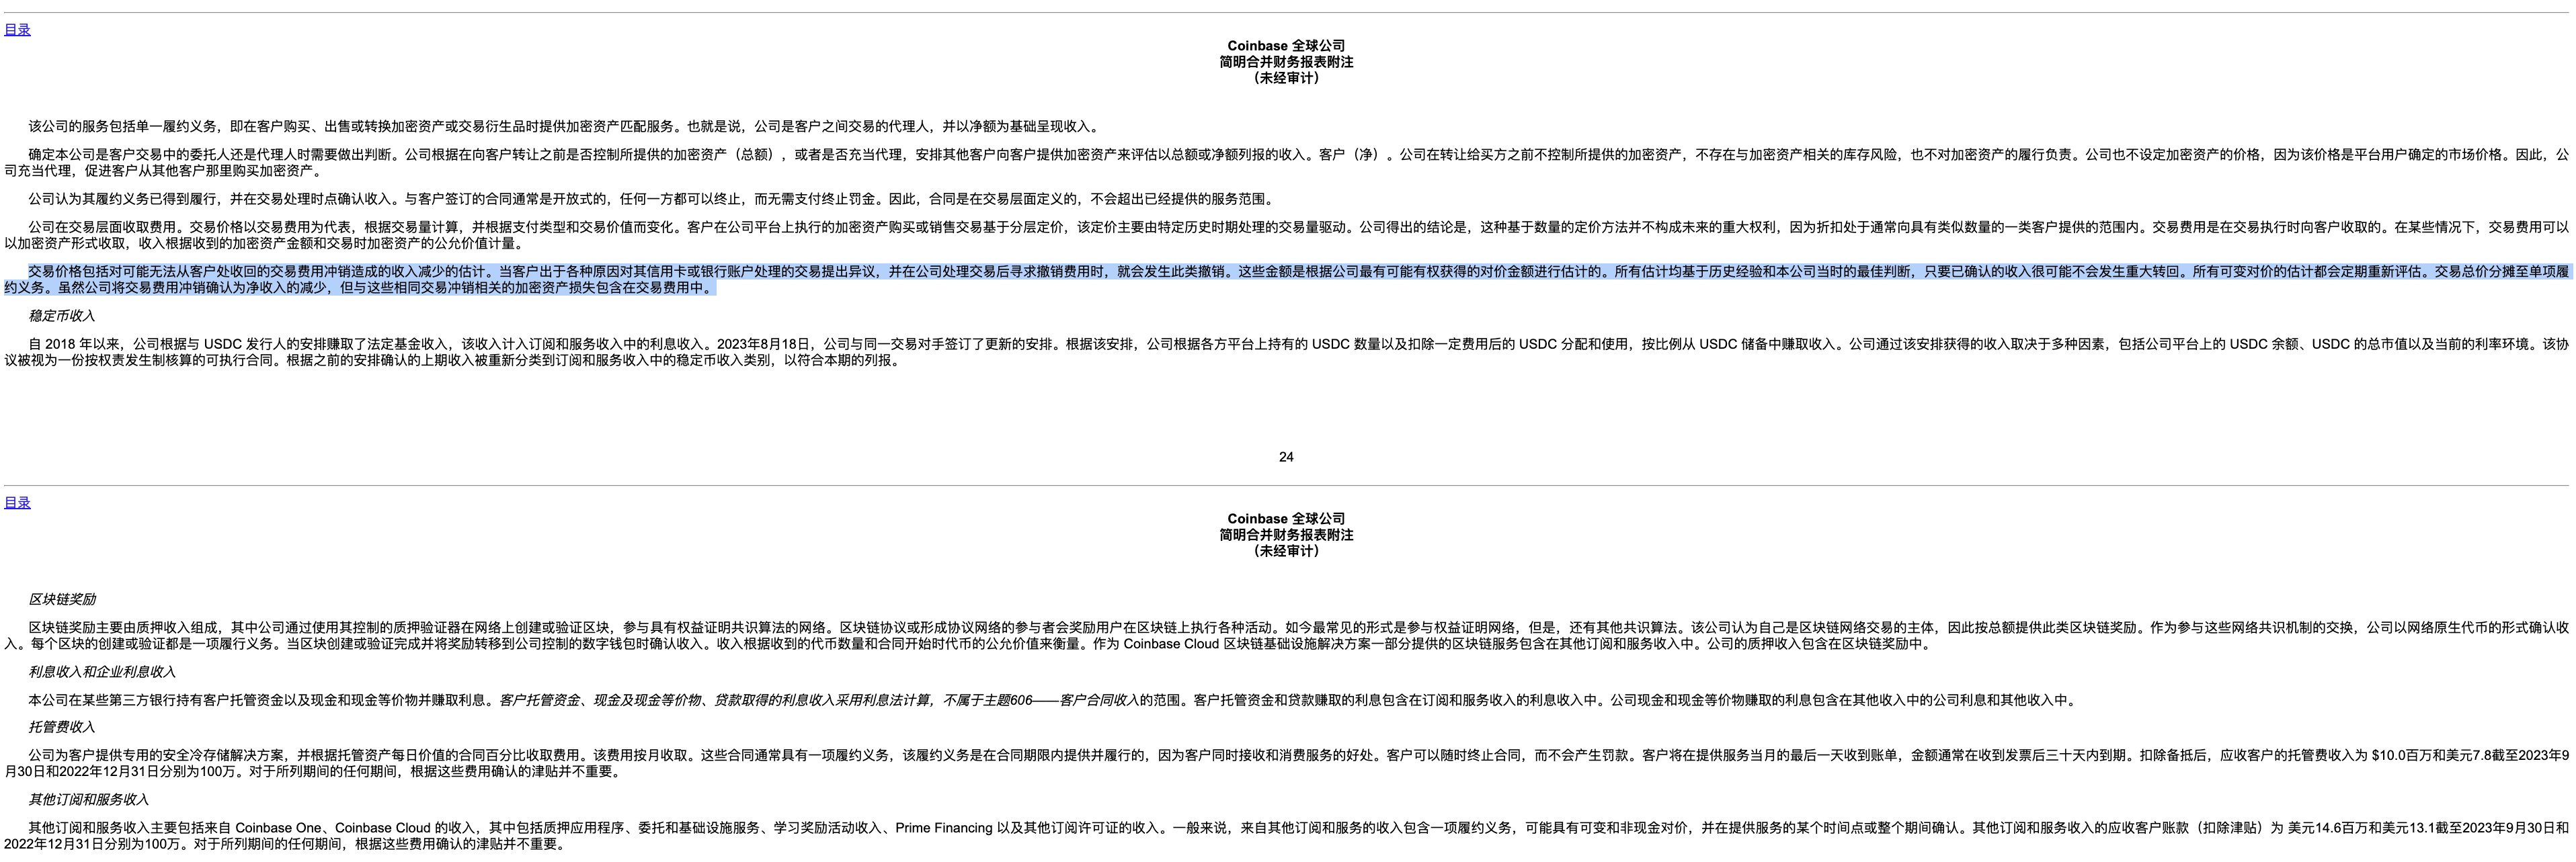
However, we saw a very interesting phenomenon through Coinbases financial report. With the compliance of US dollar recharge, Coinbase supports direct deposits from credit cards and bank accounts, which gives some speculators an opportunity to take advantage of it. Although there is no clear explanation, I think I invested through a credit card deposit.If you make a profit, everyone will be happy. If you lose, you will complain about fraud, and the bank will withdraw the funds from Coinbase, and this loss will also be borne by Coinbase.Of course, if such users want to come to Coinbase, they will strengthen management even if they are not blacklisted. However, if Coinbase has a separate explanation, there are also many speculators who want to come to this kind of wool.
BTC is still the first choice for high-net-worth and institutional users to hold positions
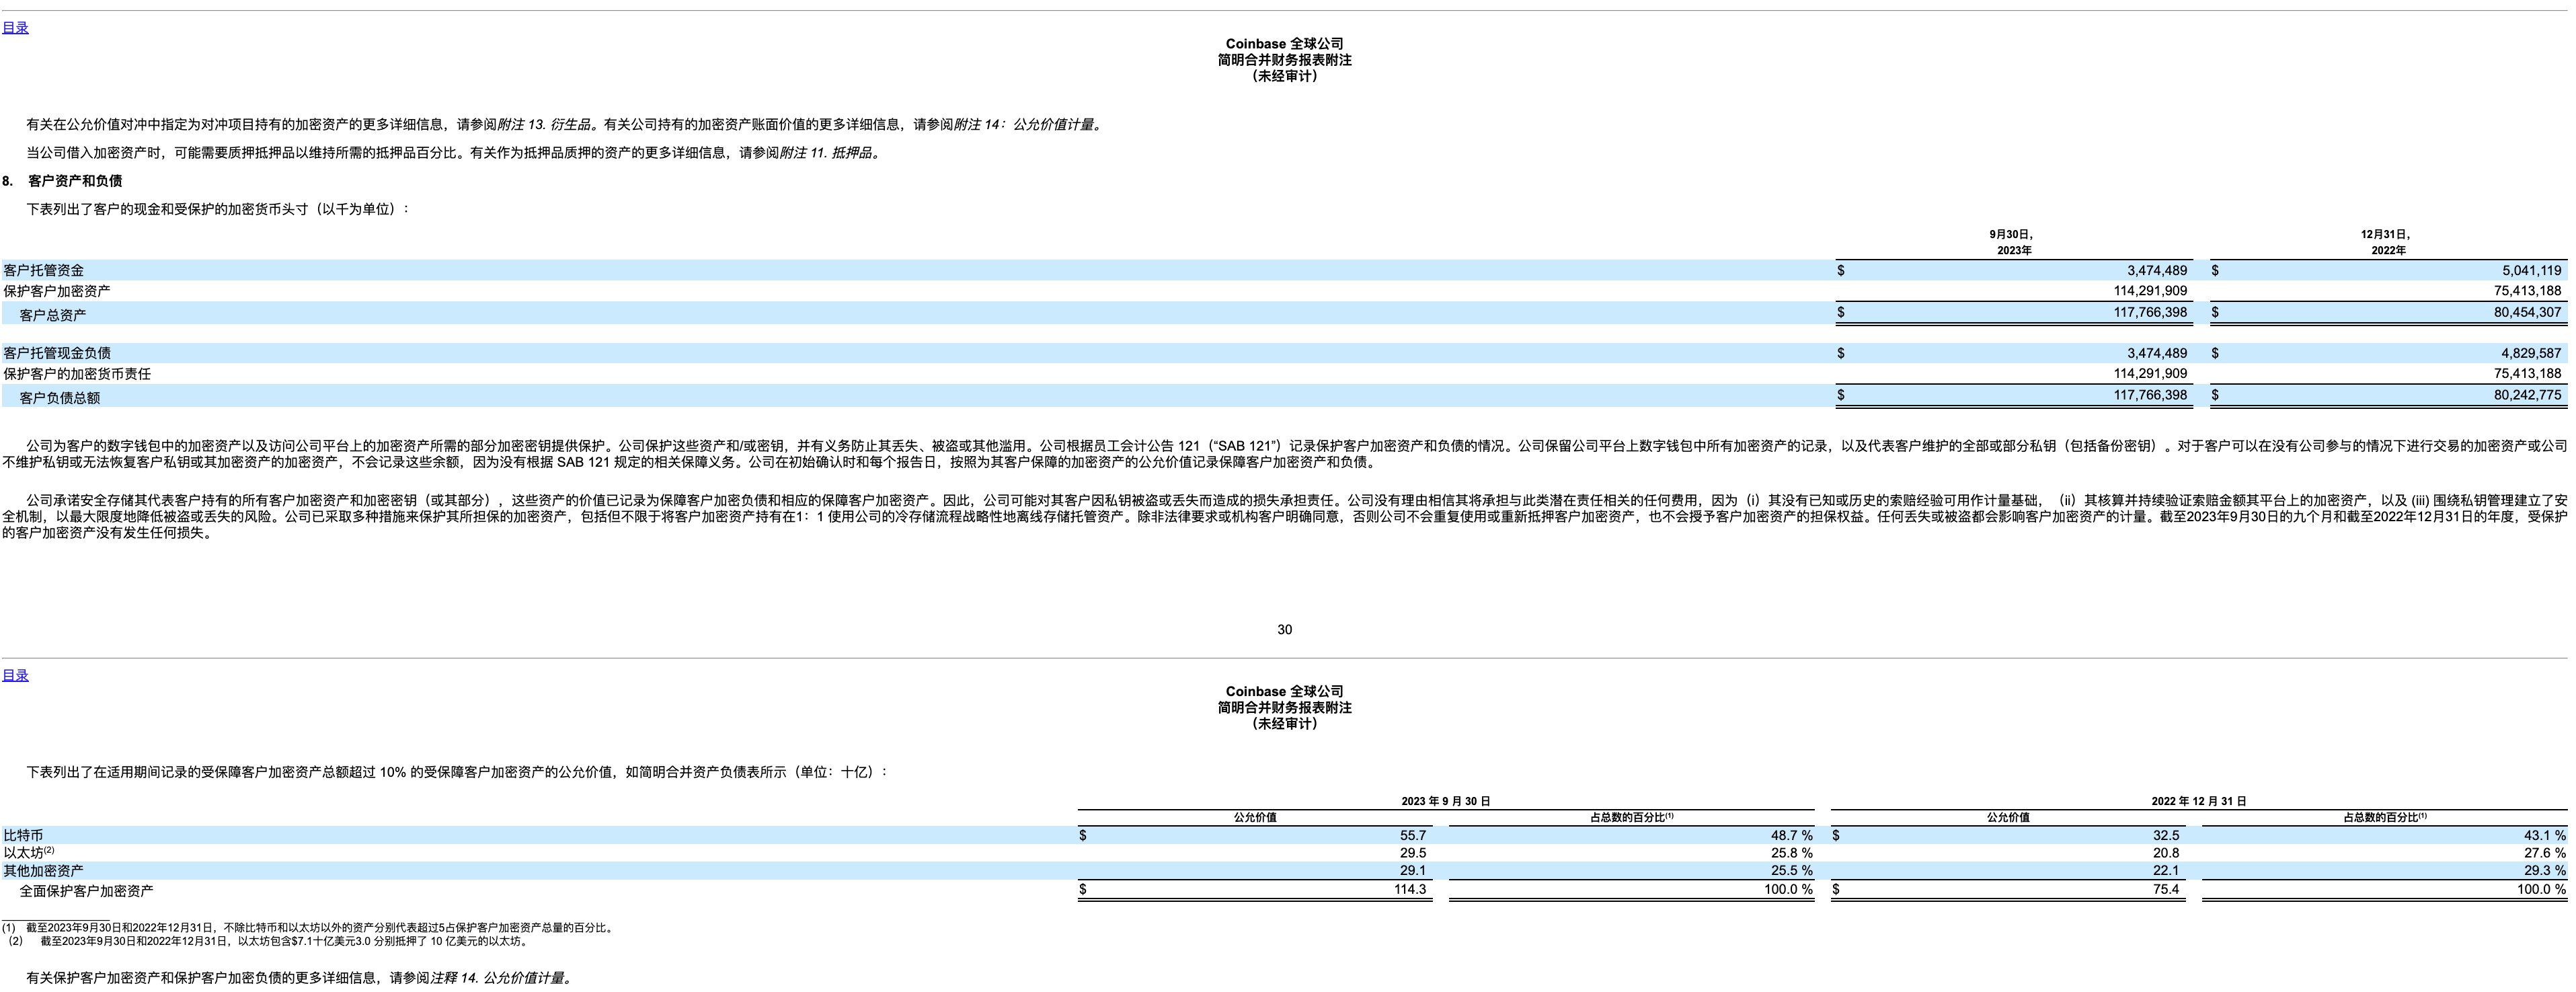
Another thing to pay attention to is,Coinbase has increased its custody and asset protection for customers. As of the first nine months of 2023, the total customer assets held exceeded $117.76 billion, up from $80.45 billion for the whole of last year.You must know that the current market value of the entire cryptocurrency is 1.28 trillion. This is the result of the sharp rise in the overall market driven by BTC and ETH. At the end of September, it was just over 1 trillion US dollars, and Coinbases user storage accounted for 1.28 trillion U.S. dollars. It is ridiculous to say that it accounts for more than 10% of the overall market value of the city. What this mainly represents isAt present, more users do not trust decentralized storage, but trust centralized storage more.Of course, Coinbase also buys insurance and provides full compensation, and the hosting fee is indeed not high.
I think this is the first choice for high-net-worth users and institutions. It is also limited to fully compliant and regulated exchanges. I know what many friends want to say. There are also many institutions in Hong Kong that provide custody, but it seems that KYC and AML are also required. Yes, interested friends can find out for themselves. Returning to Coinbase’s hosting, you can also see that there arenearly halfThe assets of high-net-worth and institutional users in custody are BTC, accounting for nearly half, and ETH accounts for more than half of the remaining half.So the current pattern can still be very clear, for high net worth users and institutions,BTC is still the first choice for holding positions, followed by ETH.Moreover, ETH’s holdings can reach about 53% of BTC, and it is still the cryptocurrency most favored by high-net-worth and institutional users after BTC.
The assets for bargain hunting are mainly BTC and ETH, and I am more optimistic about the price growth of ETH.
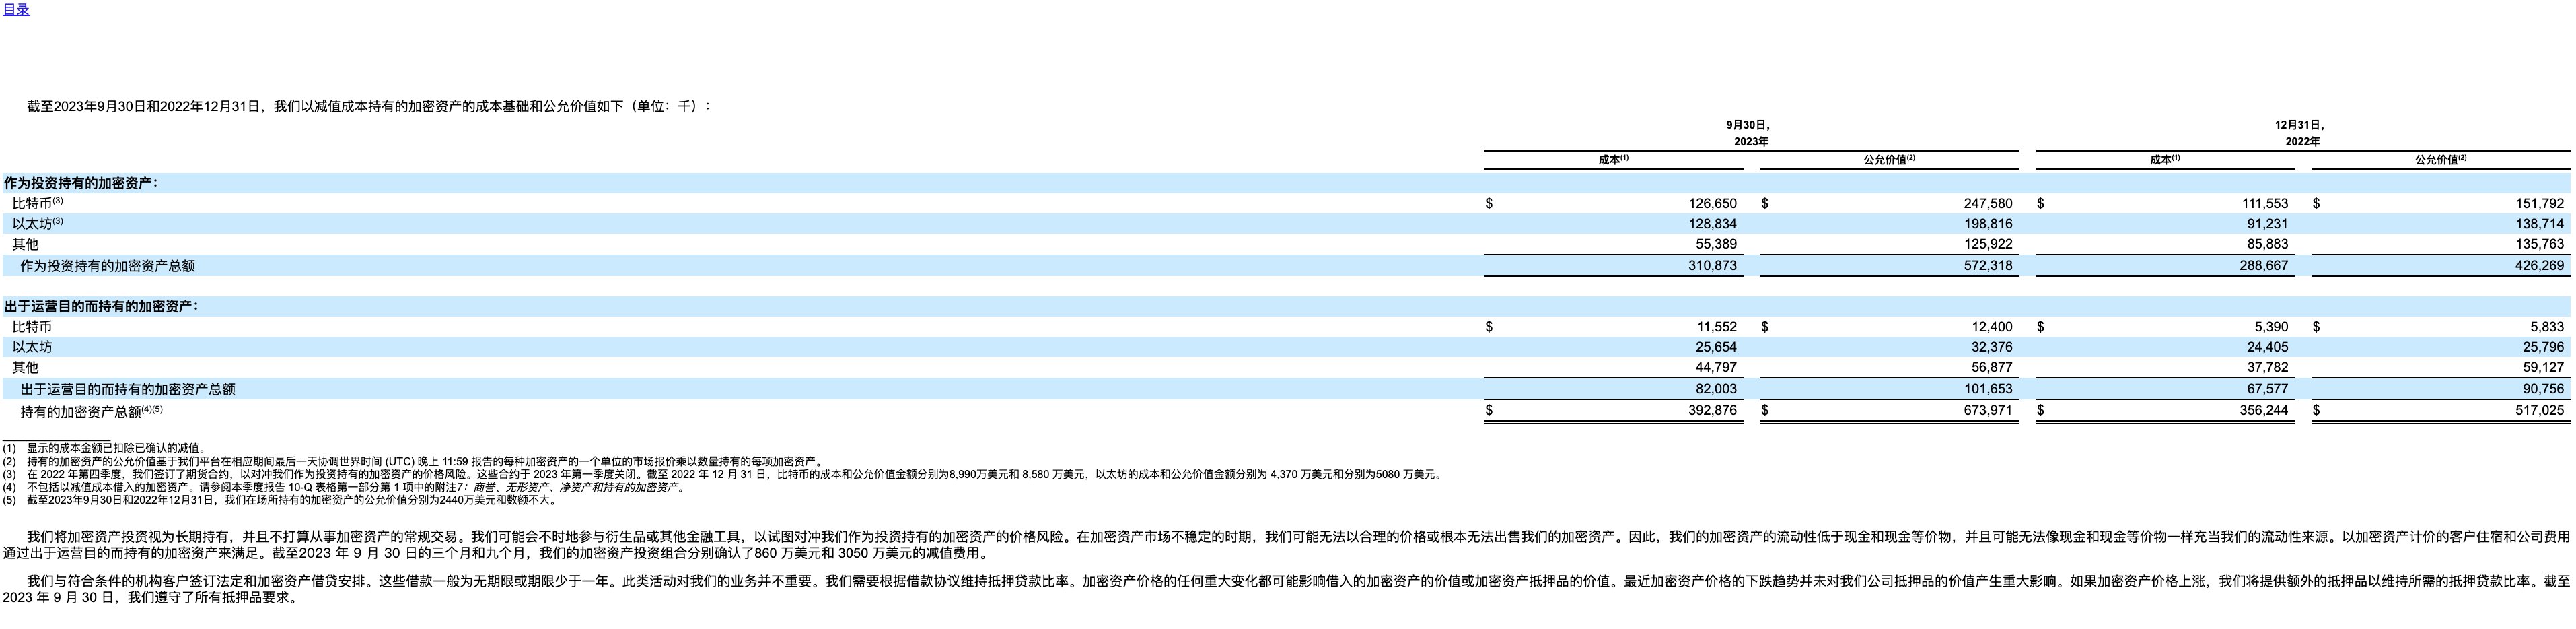
The next data is the total amount of cryptocurrency assets held by Coinbase, which provides data for many friends to judge whether they are dog farms. As of September 30, 2023,The total value of Coinbase’s holdings of cryptocurrencies as investments is $572 million, with a cost of $310 million.At the same time, there is also a special explanation for investing and holding Coinbase, which generally meansCoinbase does not plan to frequently trade these assets, and will also use derivatives or other financial instruments to hedge, and may even lend these assets out.The total holding cost and fair value of the current nine months have exceeded the data for the whole of last year. In human terms, it is entered.After 2023, Coinbase has stepped up its hunt for cryptocurrency, bought more assets, and has made more than $260 million in profits, higher than last years revenue of less than $140 million.
Among them, Coinbase’s bargain-hunting assets are mainly BTC and ETH.This is within expectations, but although the costs of BTC and ETH, which Coinbase bargains for, are very similar, the cost of investing in ETH of US$128 million is slightly higher than the US$126 million of BTC. This shows thatCoinbase is optimistic about both BTC and ETH assets, but is slightly more optimistic about the price growth of ETH.Of course, judging from the current financial report data, the net income from investing in ETH is indeed not as high as that of BTC. The total investment volume of BTC and ETH accounts for more than 82% of Coinbase’s investment. However, from the perspective of income, the current income of BTC and ETH , accounting for only 78% of the total return, it is true that the increase of BTC and ETH is lower than that of ALT.
But judging from the data compared to 2022, Coinbase has increased its investment income in BTC and ETH. Even in 2022, when ALT contributed the most income, it has also reduced the amount of investment in ALT. This also tells us an important reason,The larger the investment, the more likely you are to choose assets with lower returns but higher stability. At the same time, you can use small positions to make high-risk investments.This is exactly the same as the investment strategy I posted yesterday. Of course, how to choose depends on your friends. In addition, ALT accounts for the majority of the cryptocurrencies held by Coinbase for operational purposes, with more than 44 million US dollars. , followed by ETH accounting for more than 2,500 US dollars, and the least BTC accounting for about 1,100 US dollars, and these assets will be used to pay gas fees and other expenses.
User analysis: Institutions, market makers and high-net-worth investors are Coinbase’s main sources of revenue
Finally, Coinbase analyzed its users and believed that a large part of the transaction volume came from a relatively small number of customers.The loss of these customers or reductions in trading volume could adversely affect Coinbases business, results of operations and financial condition. A relatively small number of institutional market makers and high-volume consumer clients account for a significant portion of the trading volume and net revenue on Coinbase. This actually reveals a very important data, and it may also bring fatal consequences to Coinbase, that isMore institutions, market makers or high-net-worth investors are the main source of income for Coinbase, but the main reason why these investors choose Coinbase is that it is sufficiently compliant and a regulated listed company, but if BTC and ETH The adoption of spot ETF is likely to significantly weaken Coinbase’s profitability。
Although this has little impact on more ordinary investors, it can see the future development direction of the exchange.The more compliant exchanges are, the more they will be impacted by spot ETFs, and the revenue of compliant exchanges has shifted from trading revenue to peripheral revenue.This situation will inevitably reduce the exchanges attributes as a trading, but it will indeed increase the exchanges financial attributes.
summary
The most important takeaway after reading all of Coinbase’s third-quarter earnings report isCoinbases efforts to hunt for the bottom are increasing, and hunting for BTC and ETH is still the main method. It will buy more ETH than BTC. According to financial report data, Coinbase will hold 9,629 new BTC and 144,450 ETH in 2023. , and several ALTs accounting for 22%.





