LD Capital Track Weekly Report (2023/10/30): The lending sector is active, and derivatives positions have increased significantly.


Summary
DeFi lending: As the market conditions improve, funds in the lending sector are also extremely active.
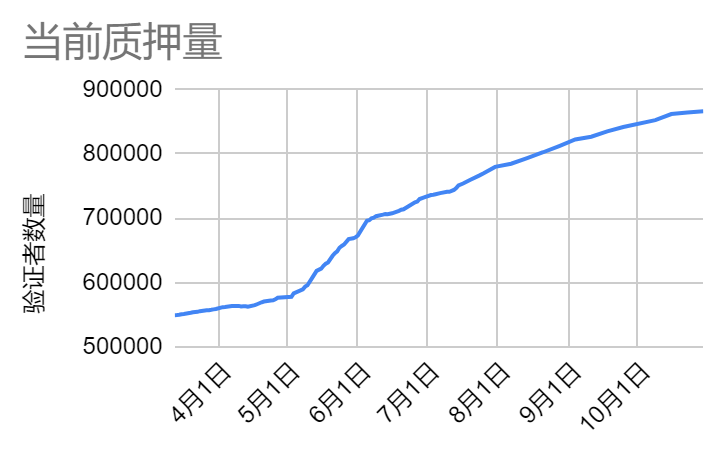
LSD: The ETH pledge rate rose to 23.28% last week, a month-on-month increase of 0.26%. Last week, 28 million ETH were locked in the beacon chain, corresponding to a pledge rate of 23.28%, a month-on-month increase of 0.26%; of which there were 866,300 active verification nodes, a month-on-month increase of 0.21%.
Ethereum L2: The total amount of Layer 2 TVL is US$11.89 billion, and the overall TVL has increased by 7.20% in the past 7 days. The 173rd ACDE meeting of Ethereum was held on October 26. The meeting gave an update on the progress and schedule of the Cancun upgrade. The mainnet upgrade is expected to be carried out in 2024.
DEX:Dex combined TVL 11.56 billion,An increase of 600 mln from last week. Dex’s 24-hour trading volume is 1.45 billion, and its 7-day trading volume is 19 billion, an increase of 7 billion from last week.
Derivatives DEX: BTC broke through the yearly high of 31,500 in mid-October, reaching a new yearly high near 35,500, and has since fluctuated between 33,500 and 35,500. This breakthrough led to a surge in bullish sentiment in the market, with significant growth in both open interest and trading volume.
DeFi Lending
Aave
The Aave community launched a new proposal, proposing that Aave DAO cooperate with TokenLogic to develop various smart bridge contracts from Avalanche, Optimism, and Arbitrum across the chain to Ethereum. Once created, these contracts will become public goods within the Aave ecosystem. This means that any participant will be able to draft payloads to move DAO funds between different networks.
Once the Avalanche to Ethereum bridge contract is completed, TokenLogic intends to propose migrating funds to Ethereum vaults to support the DAO’s continued financial stability.
The Aave whale address 0x355e has withdrawn a total of 153,000 tokens from Binance since October 23. The current AAVE holdings of this address total about 237,000 tokens, making it the largest personal address holding of AAVE. This address initially opened an AAVE position in January this year, and the comprehensive cost of opening the position was around $70.
Galaxy Digital appears to be going long BTC and ETH on Aave and Compound. On October 28, Galaxy Digital deposited a total of 4,168 WBTC ($142 million) and 16,000 ETH ($28.6 million) into Aave and Compound, and then borrowed 71.6 million USDT and 21.9 million USDC.
Liquity
Liquity’s stablecoin LUSD has been launched on Starknet. The integration is currently in the alpha phase, with collateral deposits capped at 0.2 ETH. The cap will be lifted over time.
LQTY has experienced large price fluctuations in the past week, rising from $1.47 to $2.22, an increase of more than 50%. As DWF withdrew its 1.27 million LQTY from the staking pool and transferred 100,000 of them to Gate, the LQTY rally ended and the LQTY price fell from $2.22 to $1.79.
MakerDAO
The whale address starting with 0x 8 af withdrew a total of 4,077 MKR (approximately $5.88 million) from Bitget at an average price of $1,442 on October 29. The whale then deposited these MKR to Aave and borrowed 1.84 million USDC. Afterwards, he converted USDC to DAI and deposited it into MakerDAO. The current DAI deposit interest rate (DSR) is 5%.
FalconX has deposited a total of 9,085 MKR (approximately $12.8 million) into OKX and Binance in the past seven days, and currently holds 7,261 MKR (approximately $10 million).
LSD
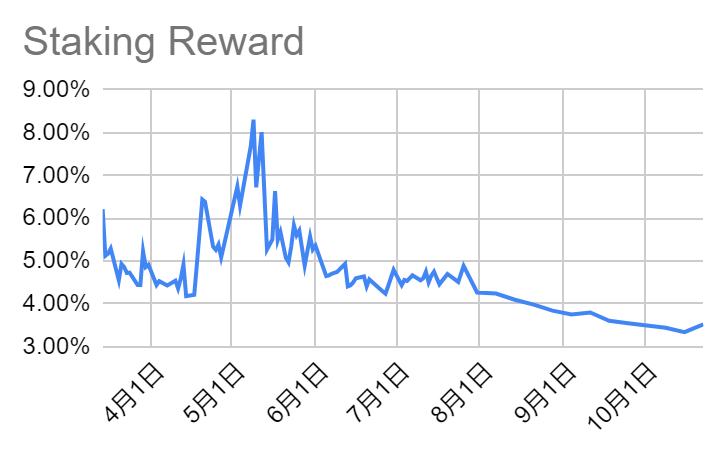
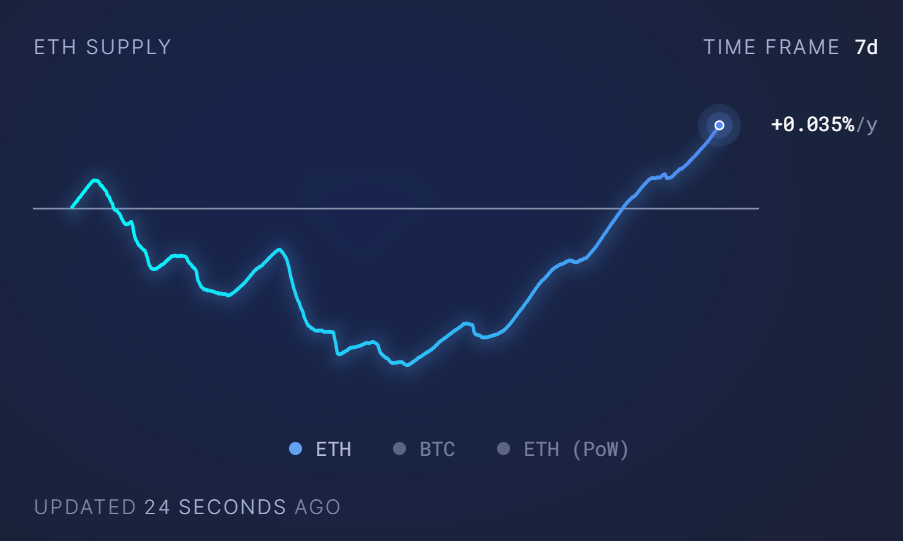
Last week, the ETH pledge rate rose to 23.28%, a month-on-month increase of 0.26%. Last week, 28 million ETH were locked in the beacon chain, corresponding to a pledge rate of 23.28%, a month-on-month increase of 0.26%; of which there were 866,300 active verification nodes, a month-on-month increase of 0.21%. This week, the ETH staking yield rebounded to 3.61%; the on-chain Meme market is gaining momentum. Uniswap and BananaGun were the applications that consumed the most gas in the past week, and the annualized inflation of ETH dropped to 0.04%.
ETH staking increased by 0.26% month-on-month this week
ETH staking yield rebounded to 3.52% this week
ETH annualized inflation this week is 0.035%
Among the three major LSD protocols, in terms of price performance, LDO increased by 4.4% in the week, RPL increased by 17.2%, and FXS increased by 10.5%; from the perspective of ETH pledge volume, Lido decreased by 0.35% in the week, Rocket Pool increased by 1.07%, and Frax increased by 1.75%. The price of ETH increased by 5.8% last week. The mechanism design of RPL as node collateral in Rocket Pool essentially anchors the price of RPL to ETH to a certain extent. The superimposed RPL lack of effective mortgage last week, TVL increase, small market value, poor liquidity, etc. Factors in several dimensions have led to a large increase in its price; the current Rocket Pool deposit pool balance is 19,272 ETH, the RPL pledge rate is 50.79%, and the effective pledge rate is 91.81%; FXB is currently in the test network stage, and is paying attention to the open redemption of frxETH and FXS. Emissions have been halved. The current size of sFRAX is 42.96 million, with a yield of 6.37%.
Ethereum L2
TVL
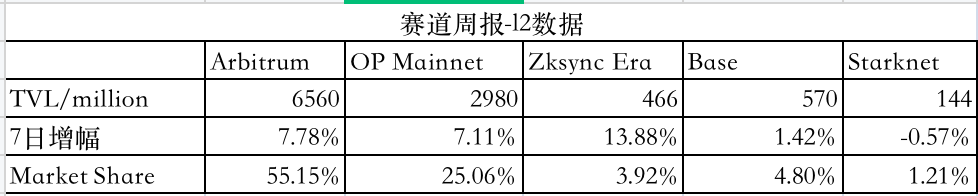
The total amount of Layer 2 TVL is US$11.89 billion, and the overall TVL has increased by 7.20% in the past 7 days.
Cancun upgrade
The 173rd ACDE meeting of Ethereum was held on October 26. The meeting gave an update on the progress and schedule of the Cancun upgrade. The mainnet upgrade is expected to be carried out in 2024.
(1) Devnet 10: Developers launched Devnet-10 on Monday, October 23, to test the Cancun/Deneb (Dencun) upgrade. The development network created 330,000 active validators to trigger changes to the validator churn limit
(2) Dencun test schedule: The Dencun upgrade will not be activated on Goerli until the end of November at the earliest. Historically, testnet activation intervals for Ethereum upgrades have been two weeks. For example, on Wednesday, November 22, Decun was activated on Goerli at the end of November, which means that the next two testnet upgrades on Sepolia and Holesky will be carried out in early and mid-December respectively.
Tim Beiko pointed out that even under the most ideal schedule, Decun’s mainnet would be activated during the holidays in late December. Most likely, the developers will delay the mainnet activation of the Dencun upgrade until early 2024.
(3) Development details such as Deneb’s simplification, EIP 7523, KZG ceremony verification and second-layer standardization were also discussed at the meeting.
OP
At 12:00 on October 30, Optimism (OP) will unlock 24.16 million pieces (approximately $34.31 million), accounting for 2.74% of the circulating supply
ARB
Blockworks Research has launched a community proposal in Arbitrum to establish the Arbitrum Alliance, led by Blockworks Research, Gauntlet and Trail of Bits, for a period of 12 months to help bring Arbitrum DAO members’ ideas to life. The total cost of the alliance for one year will be based on the 30-day VWAP price of ARB the day before the on-chain proposal. It is estimated that it will cost about 2.2 million ARB, of which 1/4 will be paid in advance to each ARB 91 days after the execution of the AIP. Alliance members, the next 3/4 will be paid out within 274 days. Fund flow will remain under DAO control and can be cut off at any time via an on-chain DAO proposal
On-chain activity
DEX
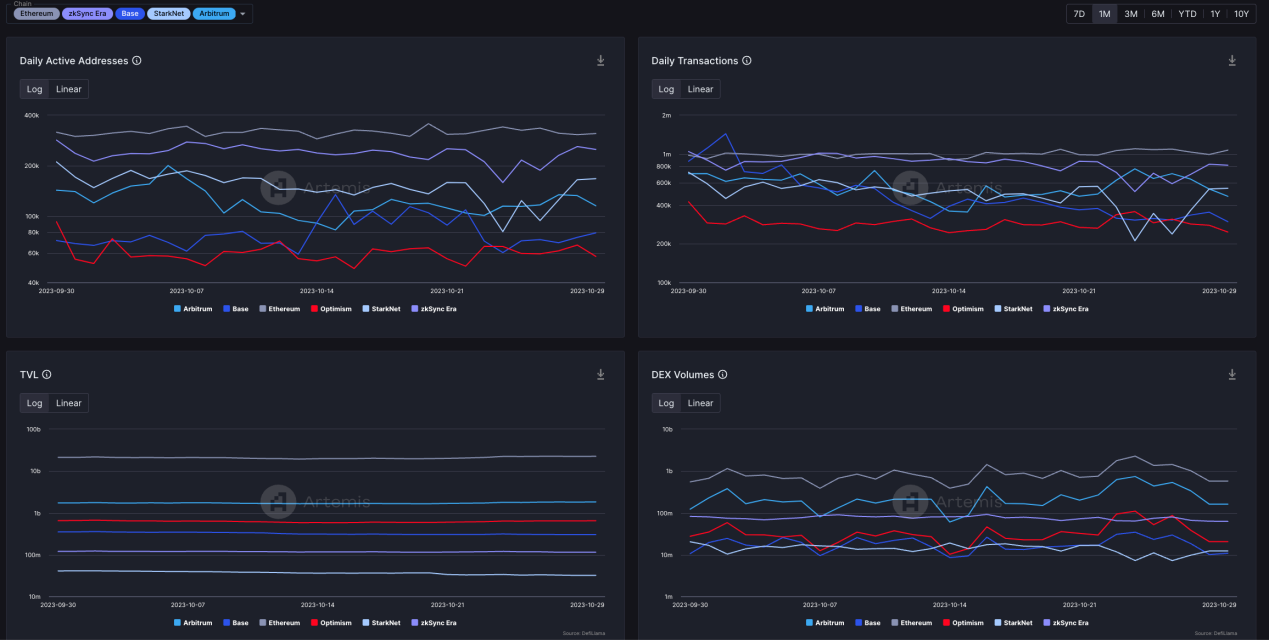
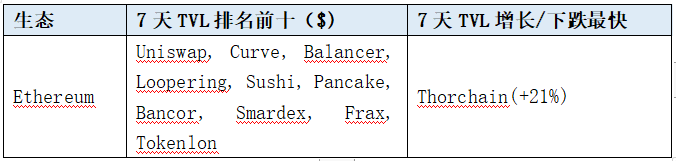
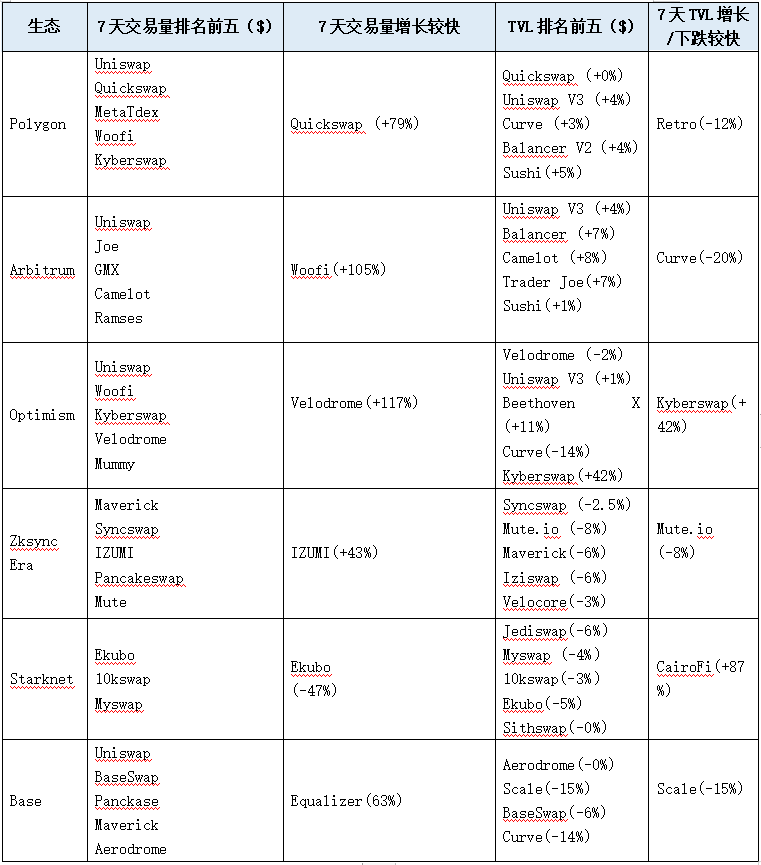
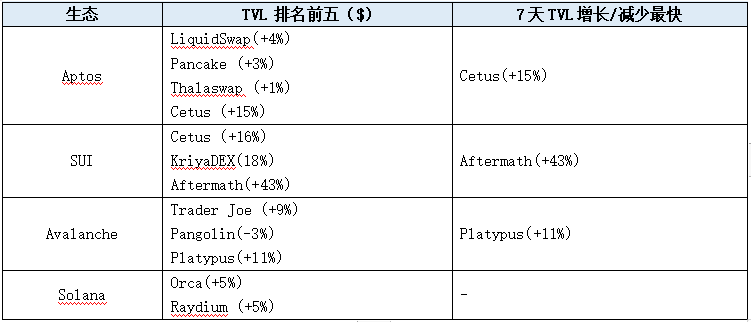
Dex combined TVL 11.56 billion,An increase of 600 mln from last week. Dex’s 24-hour trading volume is 1.45 billion, and its 7-day trading volume is 19 billion, an increase of 7 billion from last week.
Ethereum
ETH L2/sidechain
BTC L2/Sidechain
Affected by the rise in BTC prices, the BTC L2 Stacks ecological DEX ALEX 7-day TVL increased significantly (+62%)

Alt L1
Derivatives DEX
BTC broke through the yearly high of 31,500 in mid-October, reaching a new yearly high near 35,500, and has since fluctuated between 33,500 and 35,500. This breakthrough led to a surge in bullish sentiment in the market, with significant growth in both open interest and trading volume.
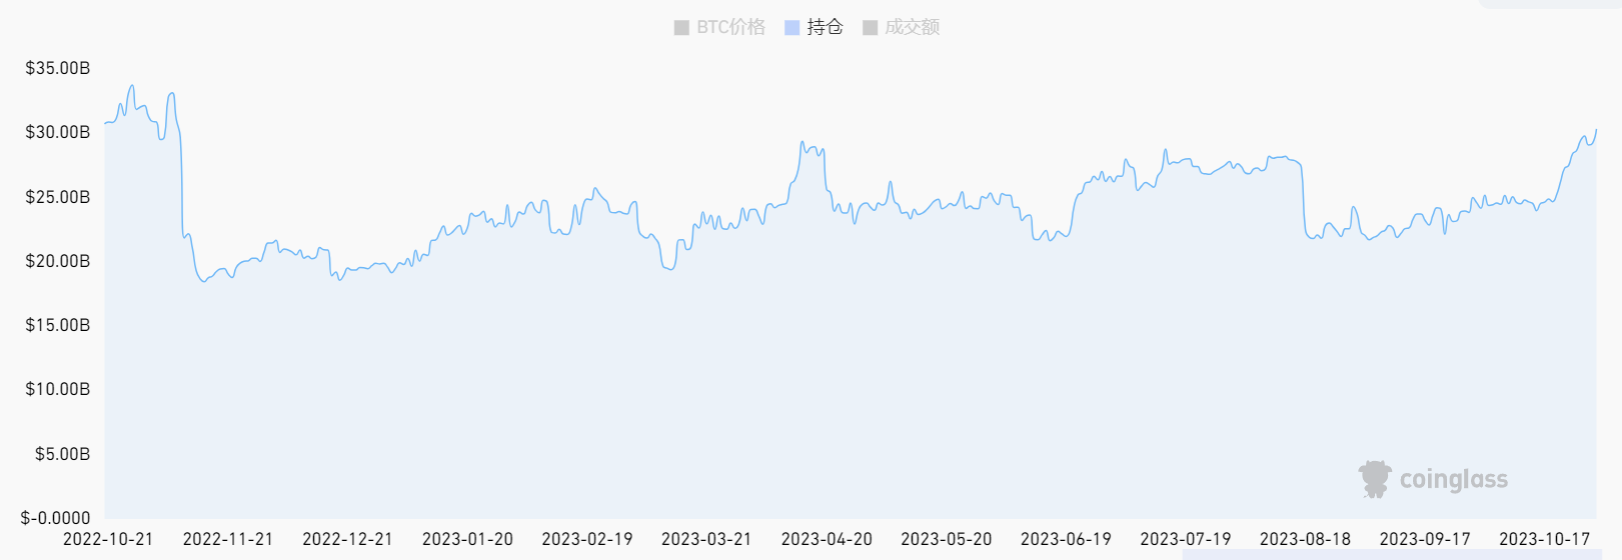
Current contract open interest is $30.3 billion, which has already reached the 2023 annual high and is close to recovering the open interest between the 2022 FTX event. The market took nearly a year to repair.
The trading volume on October 23 and October 24 reached more than 150 billion US dollars, which is a high level in 2023. There has been some pullback in the following days, but trading volume has nearly doubled from the previous August-September period.
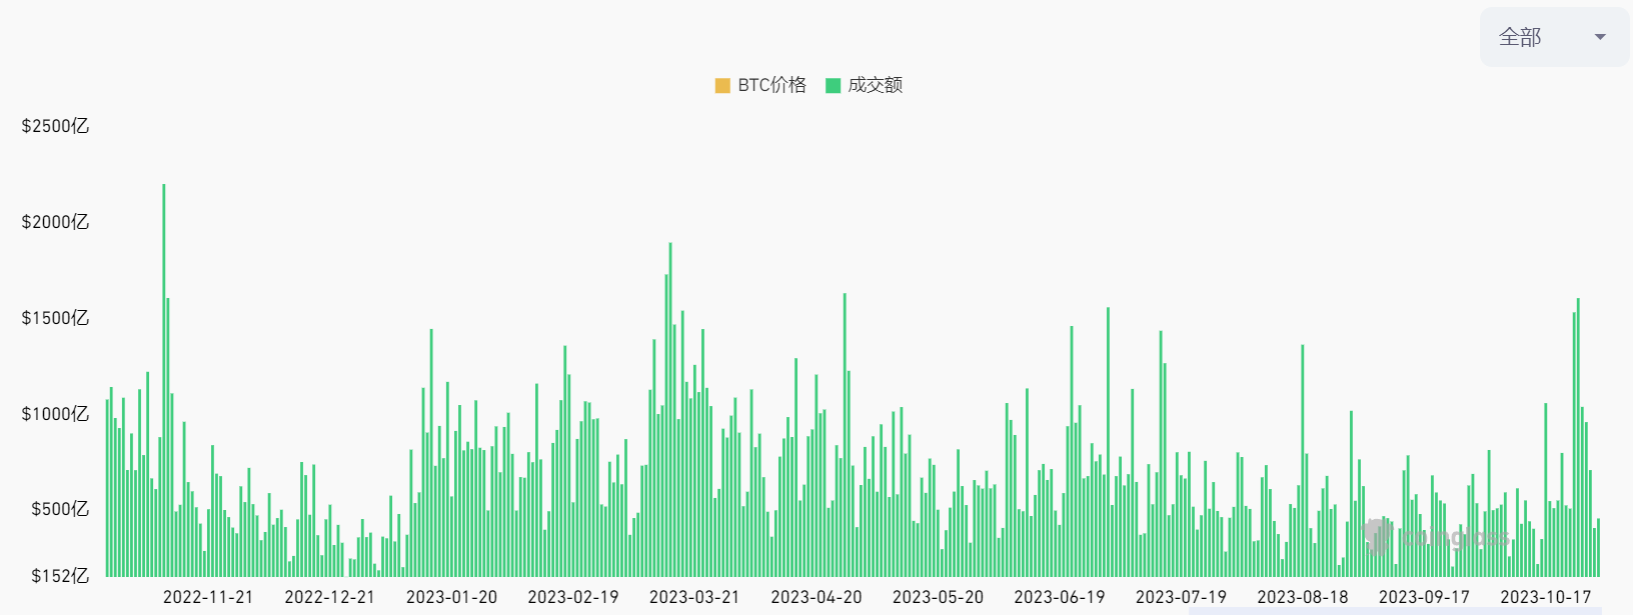
There has also been a significant recovery in trading volumes on derivatives DEXs. The daily trading volume of DYDX on October 23 and 24 was approximately US$2 billion, and it was also around US$1 billion in the following days; the total daily trading volume of derivatives DEX in the capital pool model was also around US$2 billion during the peak period. DYDX occupies approximately 50% of the market share in terms of transaction volume; followed by protocols such as GMX, Kwenta, ApolloX, Vertex, and HMX.
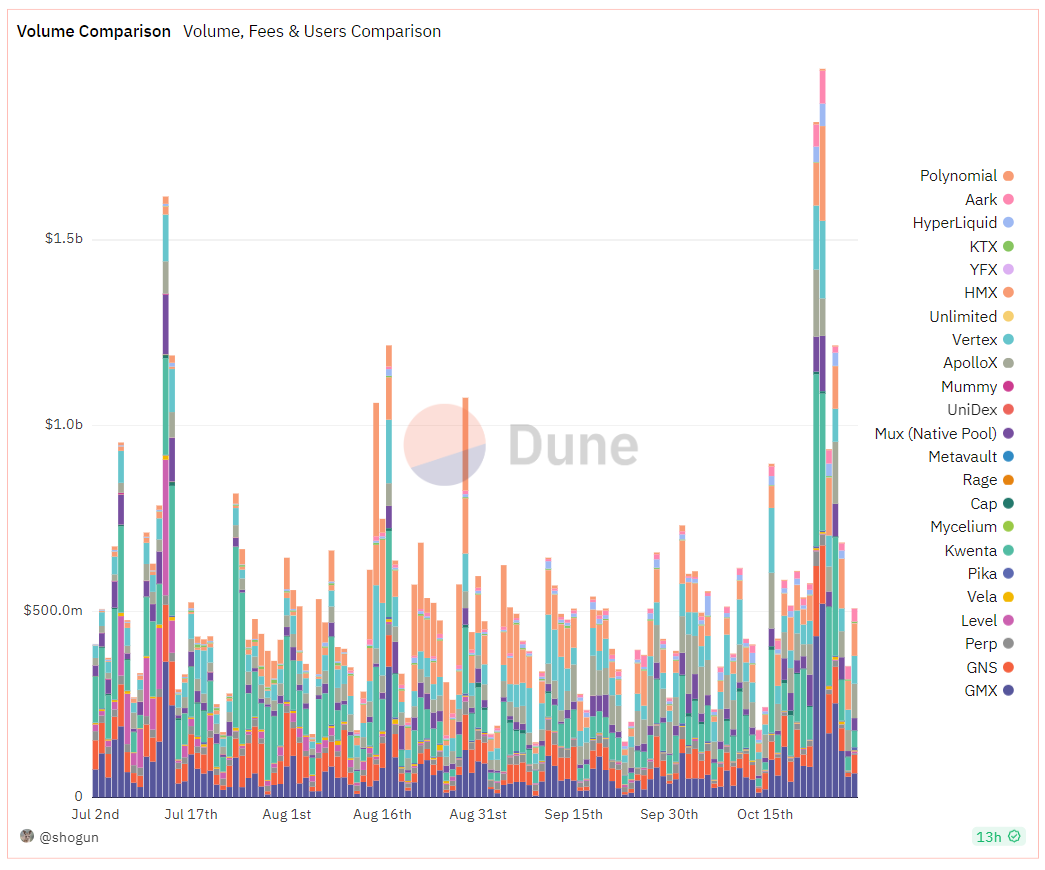
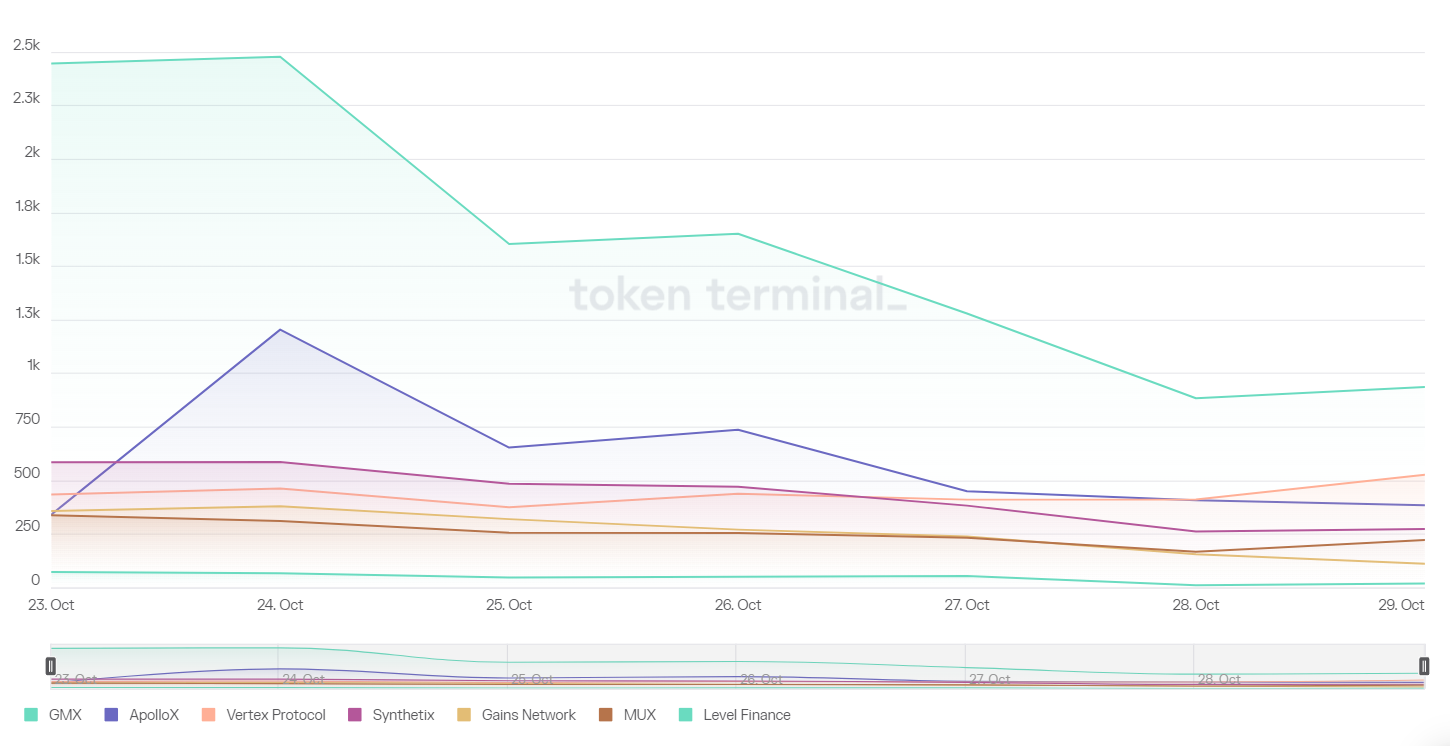
The number of users of derivatives DEX has also recovered. During the peak trading period, the number of daily active users of GMX reached 2,500, and after the decline, it was around 1,000; Vertex/ApolloX had around 500 users; and the remaining protocols had between 300 – 500 users. DYDX’s weekly active users reached 3,700. Judging from the number of users, DYDX and GMX still have the most active user groups.