SignalPlus Volatility Column (2023.07.04): Investors Begin Long-term Positioning


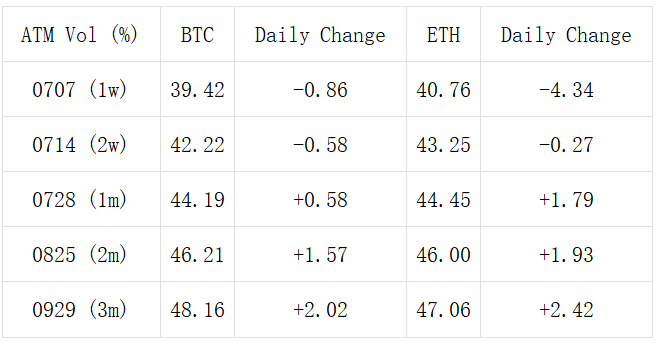
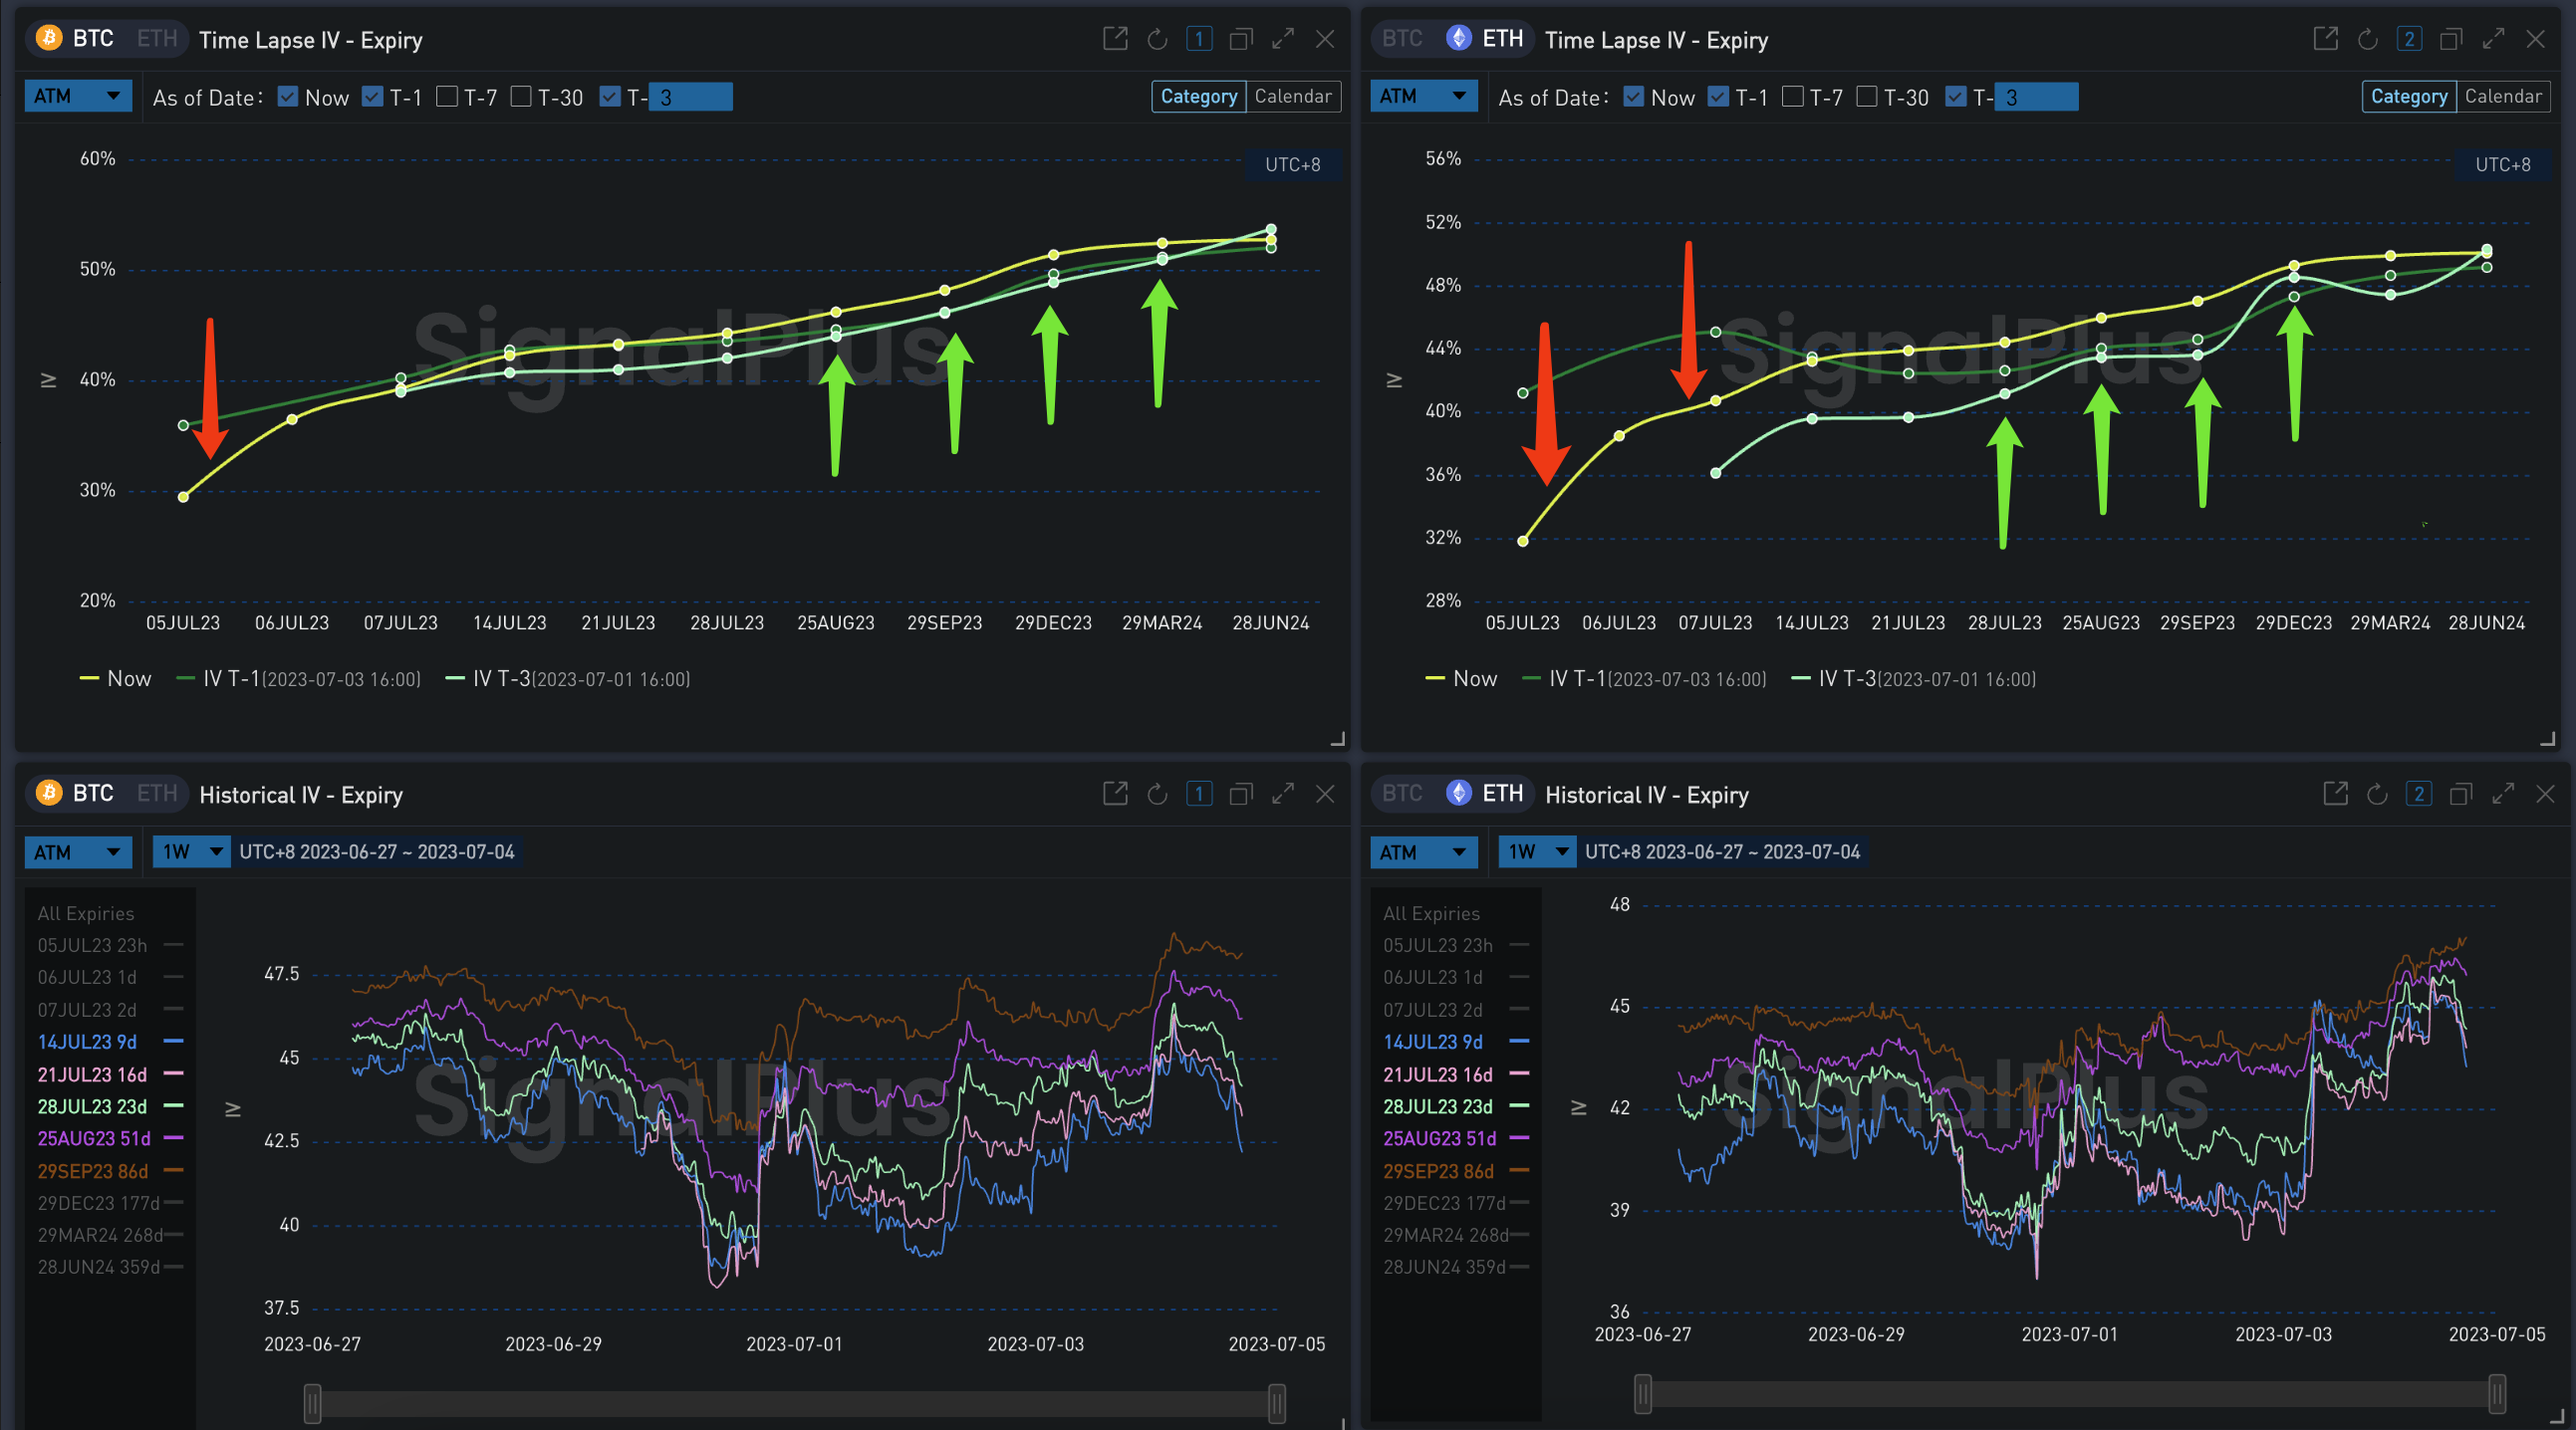
Yesterday, ETH did not break through the highly anticipated 2000 level. After rising to 1980, it lost momentum and slowly fell back to around 1950. The options market also expressed clear disappointment, with a collapse in short-term volatility that had briefly spiked, and the ATM IV dropping 4.34% to 40.76%. The implied volatility estimate for the date options only showed around 30% volatility. BTC, on the other hand, changed from the calm of a few days ago and experienced a small wave of rise (+2%), reaching a high of 31400. Although the price has since fallen back slightly, it remains stable around 31000.
The overall trading volume distribution in the market is showing a shift towards medium to long-term investments, with investors increasingly focusing on long-term investment strategies. The BTC/ETH volatility surface shows a similar trend of becoming steeper, with front-end IV decreasing and medium to long-term IV increasing.
Source: Deribit
Source: SignalPlus
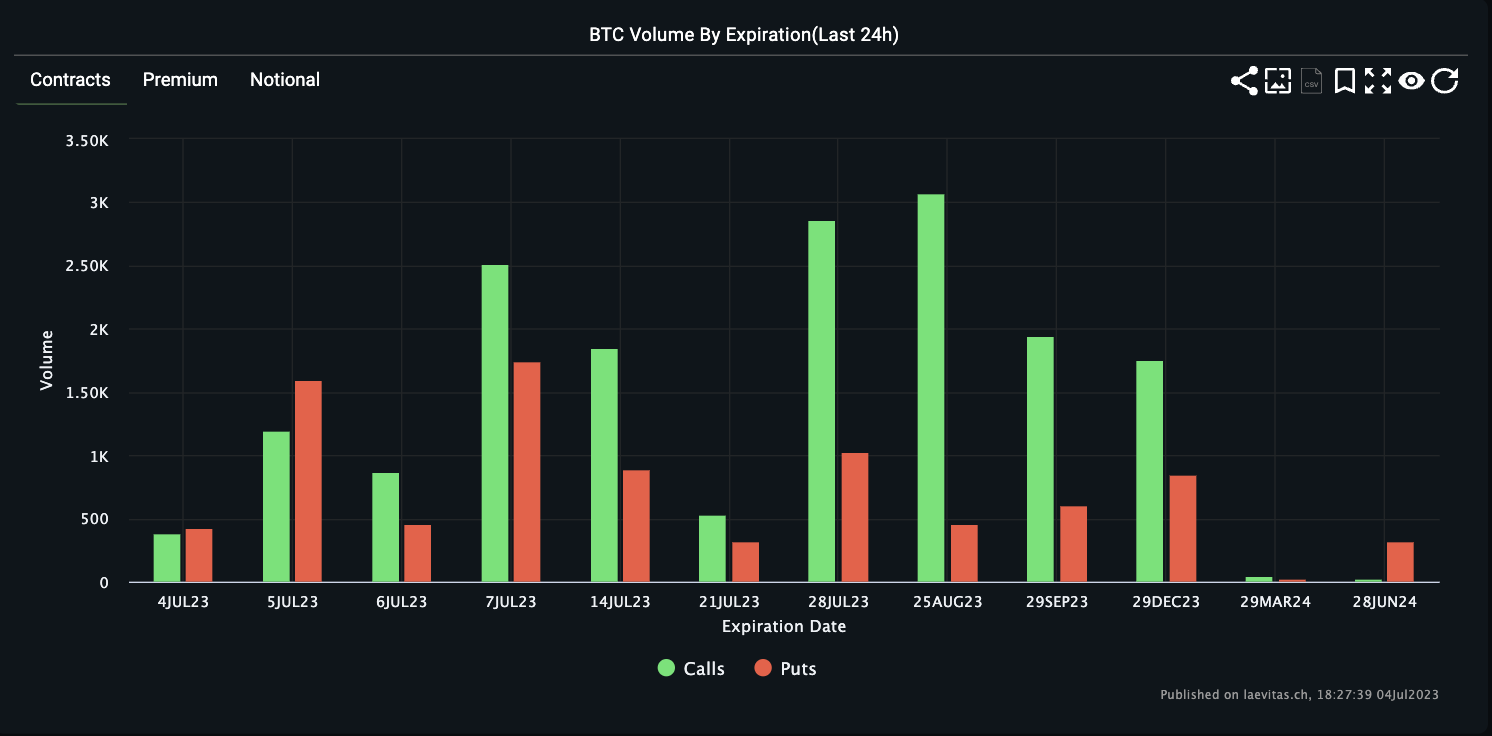
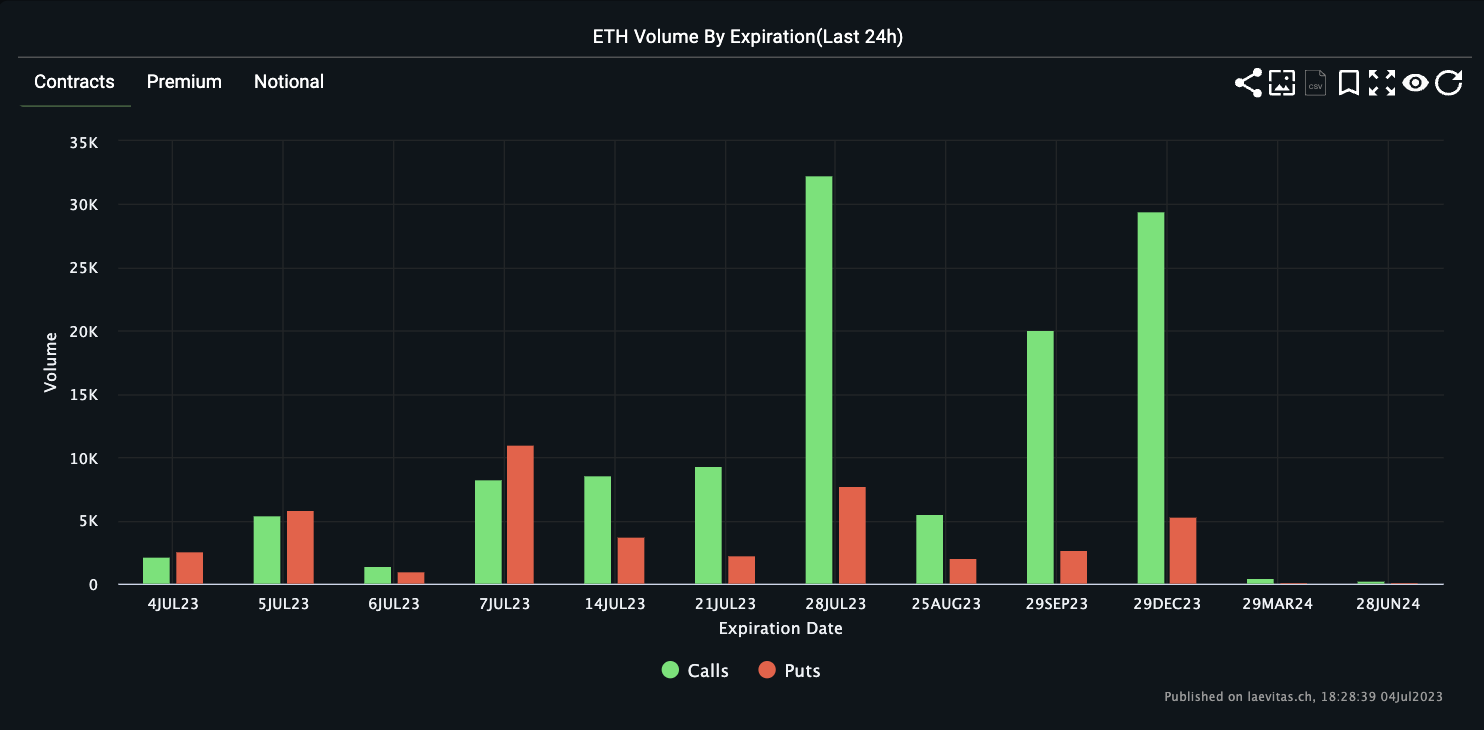
Source: Laevitas
The flow of block trades also consistently confirms these changes. In the past 24 hours, the most active trading strategies for both currencies have been Short Strangles used to short volatility. A total of 1,733 sets of ETH 7JUL23-1900-2050 have been sold, significantly suppressing front-end implied volatility. There are also 900 sets of ETH-28JUL23-1800-2200 and 150 sets of BTC-28JUL23-29000-34000 that will expire at the end of the month.
In addition to Short Strangles, Bull Call Spreads and Bear Diagonal Call Spreads have also been major components of block trades today. Call Spreads are mostly concentrated in the later period, and Diagonal Call Spreads involve selling short-term calls and buying longer-term calls, reflecting a reduced expectation of short-term price breakthroughs while still holding hopes for the rise of digital currencies in the second half of the year.
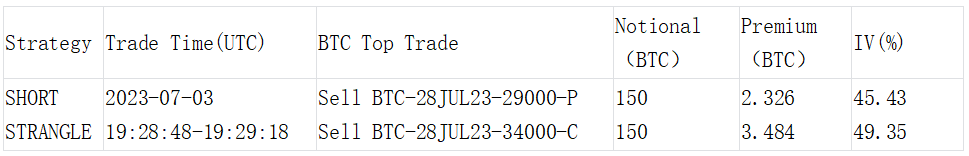
Source: Deribit Block Trade
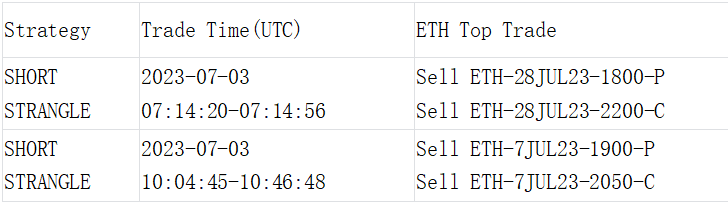
Source: Deribit Block Trade