






SignalPlus Macro Research Report 20230605: The probability of raising interest rates in June decreases, and the Nasdaq index continues to soar


Dear friends, welcome to the SignalPlus macro research report. SignalPlus macro research reports update macro market information for you every day, and share our observations and opinions on macro trends. Welcome to track and subscribe, and follow the latest market trends with us.
Dear friends, welcome to the SignalPlus macro research report. SignalPlus macro research reports update macro market information for you every day, and share our observations and opinions on macro trends. Welcome to track and subscribe, and follow the latest market trends with us.The market is eagerly awaiting the release of non-farm payrolls data,Employment Population Change Shockingly Bigger Than Expected(+ 339,000 vs 195,000), but the interpretation of various indicators is controversial,Allow observers from different positions to draw their own conclusions
, the respective summaries of the two parties are as follows:
For the Hawk camp:
Employment rose by 339,000, well above expectations of 195,000
Private payrolls rise by 283,000, beating expectations for 150,000
Results beat expectations for 14th straight month
The value of the first two months was revised up + 93,000
Services added 257,000 jobs, above expectations for 225,000, goods sector added 26,000 and government added 56,000
The labor force participation rate held steady at 62.6%
For the dove camp:Due to different methods,
Employment actually fell by 310,000 in household surveys
Unemployment jumps to 3.7% from 3.4%
Hourly wages fell from 0.4% to 0.3% MoM and from 4.4% to 4.3% YoY (lowest since June 2021)
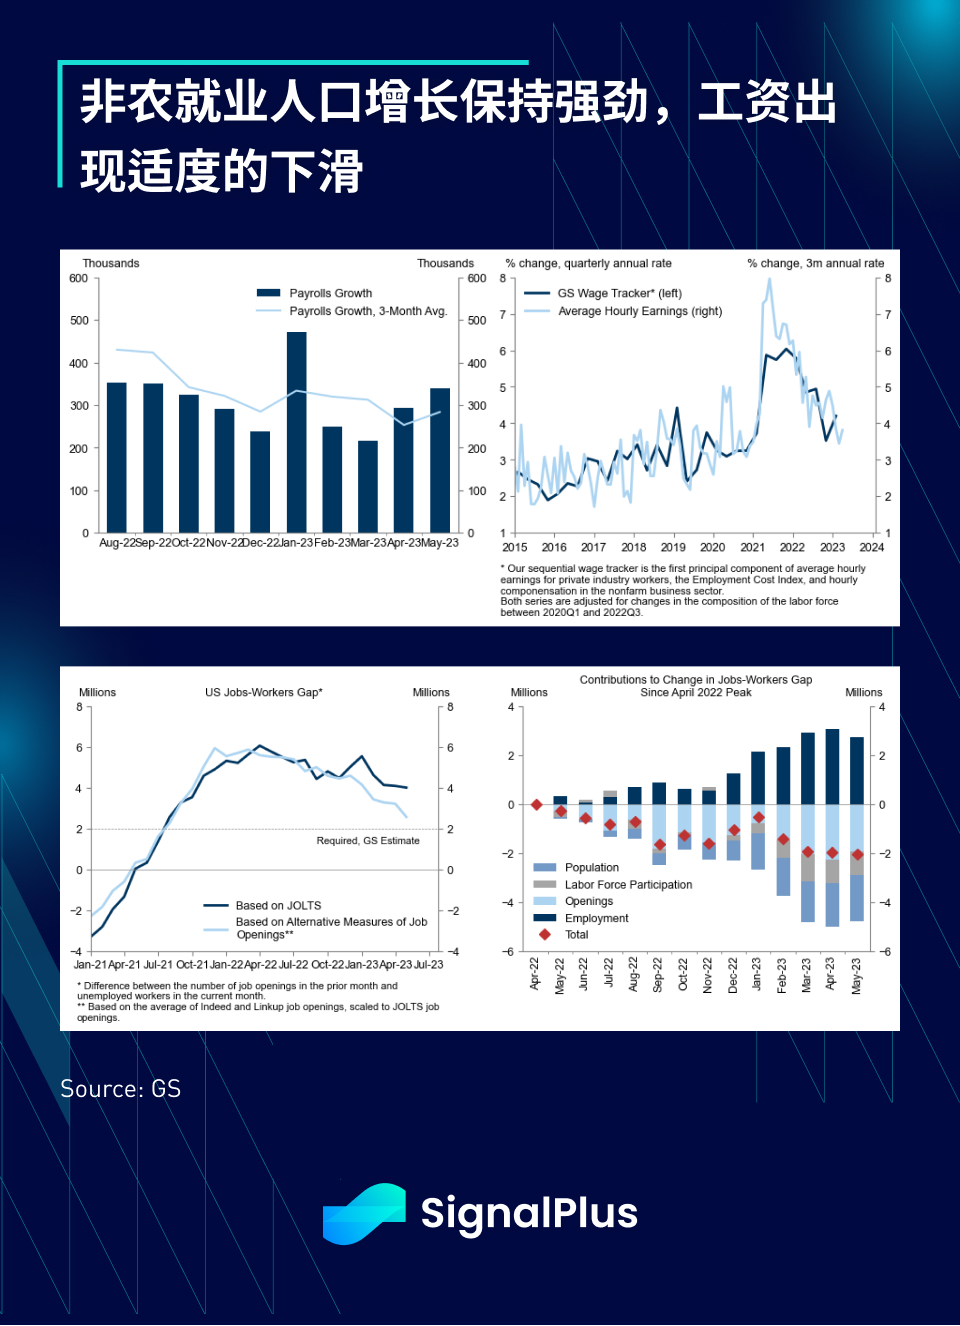
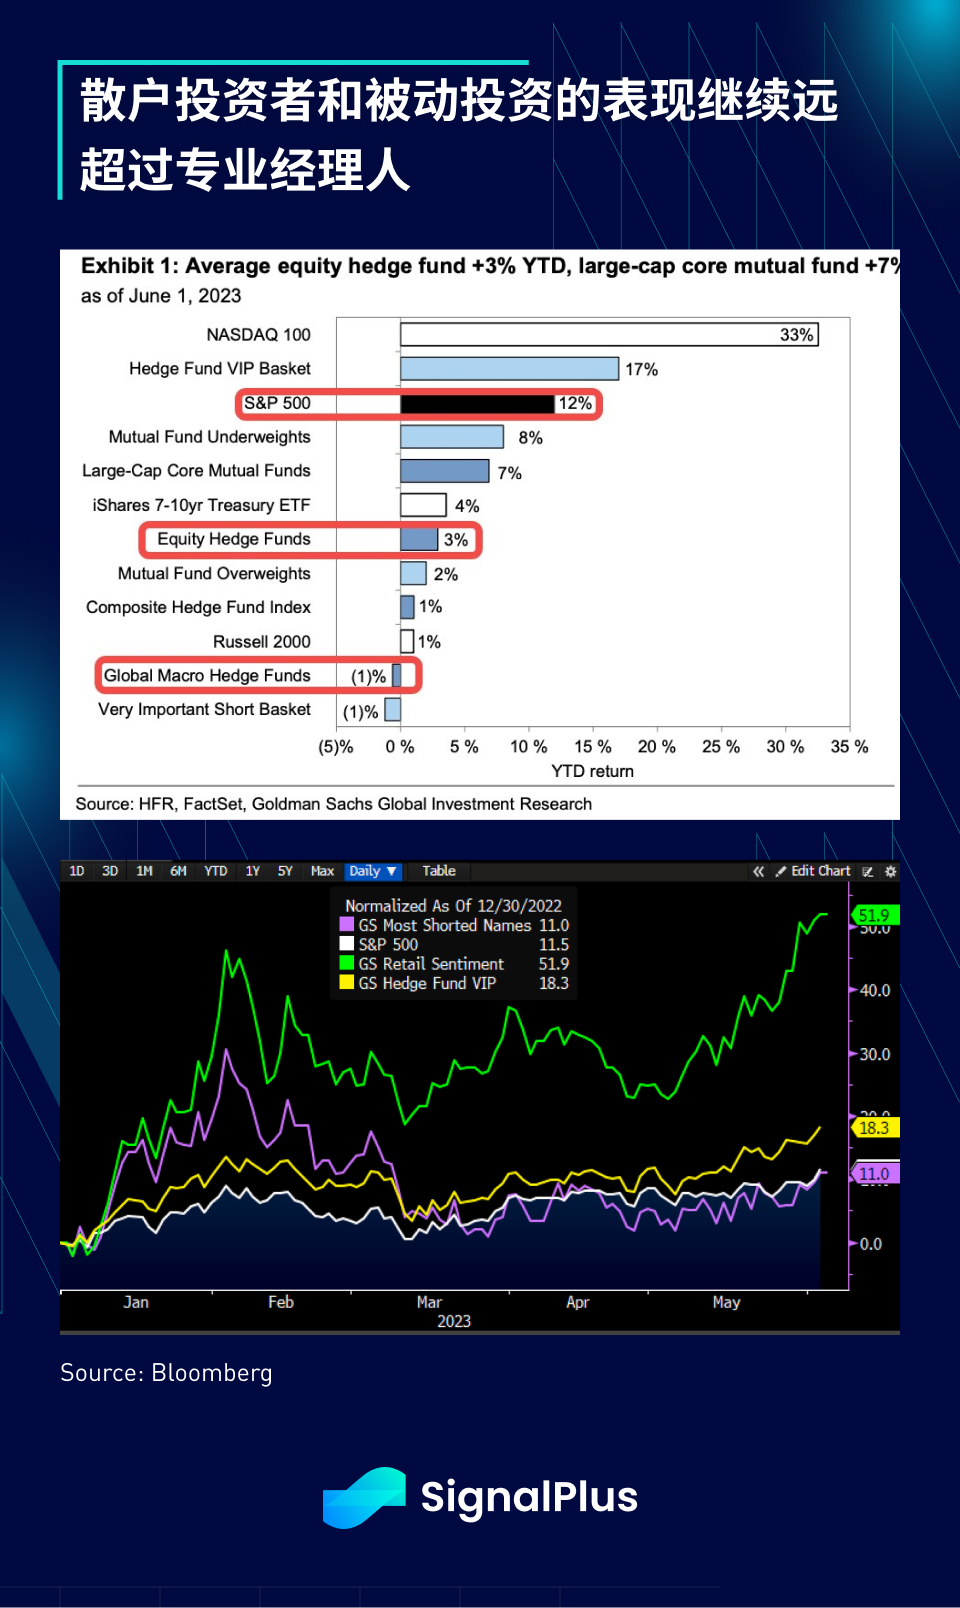
The average workweek fell to 34.3 hours from 34.4 hours, the lowest since April 2020However, overall,The market's judgment on the data favored rising unemployment and continued wage declines, helping to reduce the chances of a June FOMC rate hike to only about 30%, while the SPX continued to move higher, with 92% of constituent stocks in the red
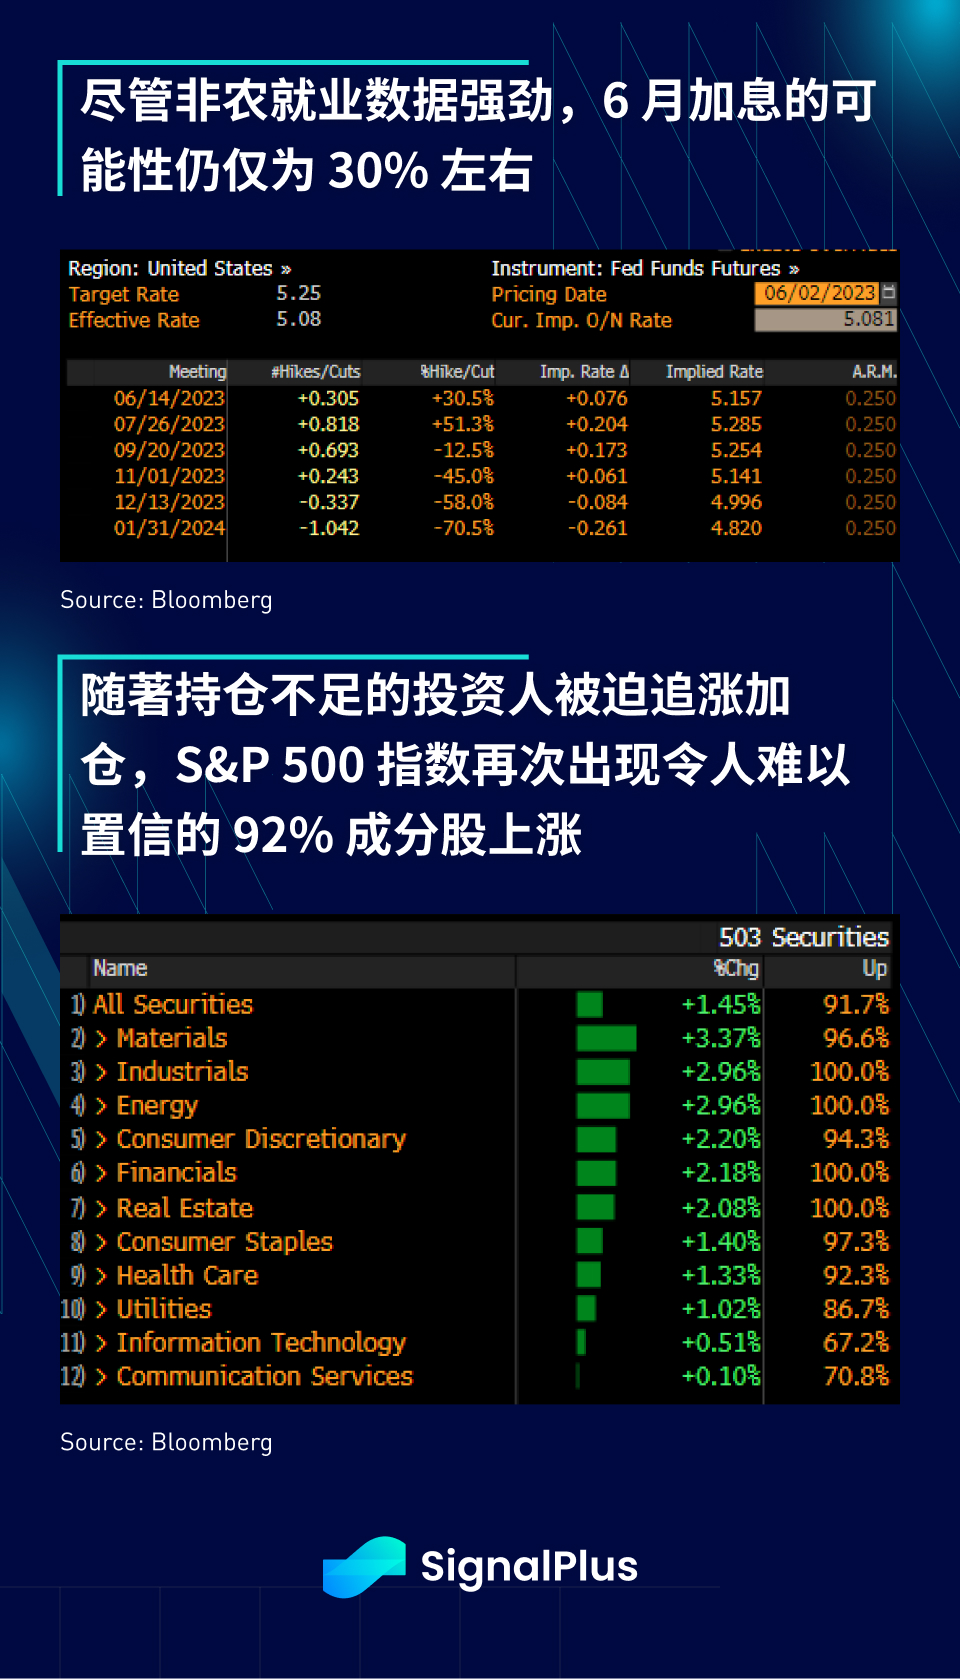
, prices reached the highest level since August last year, indeed a boom.
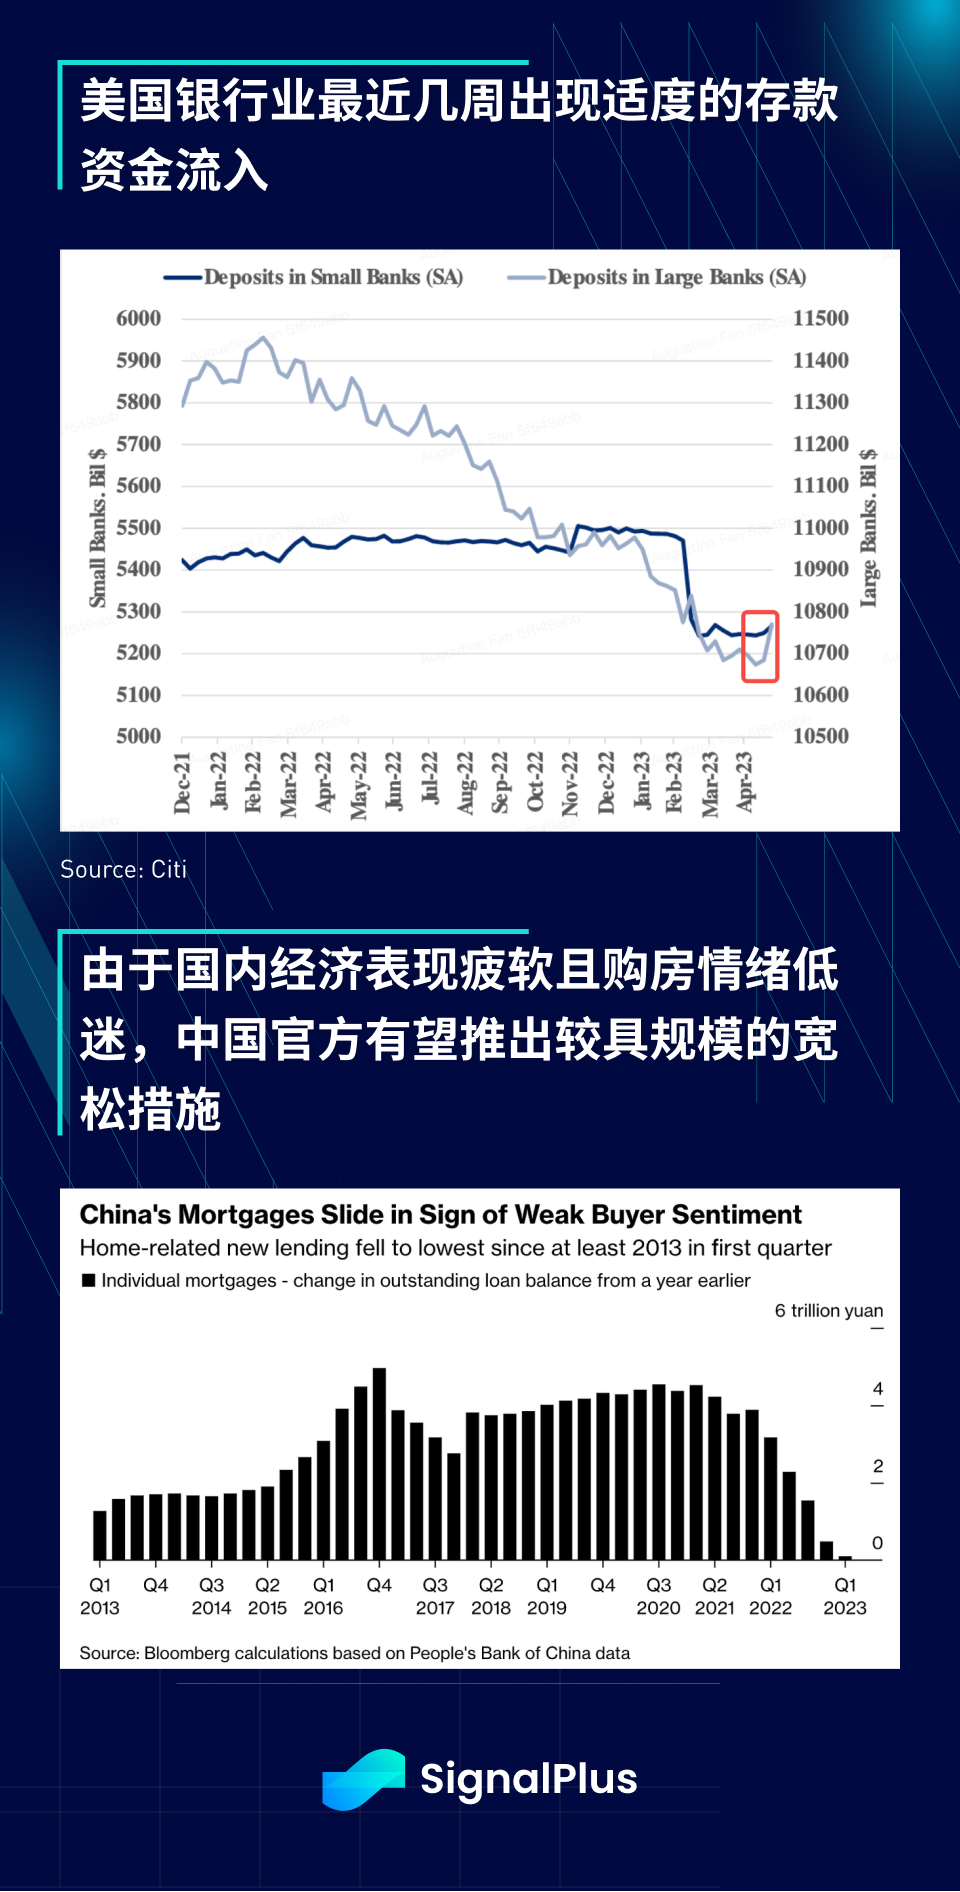
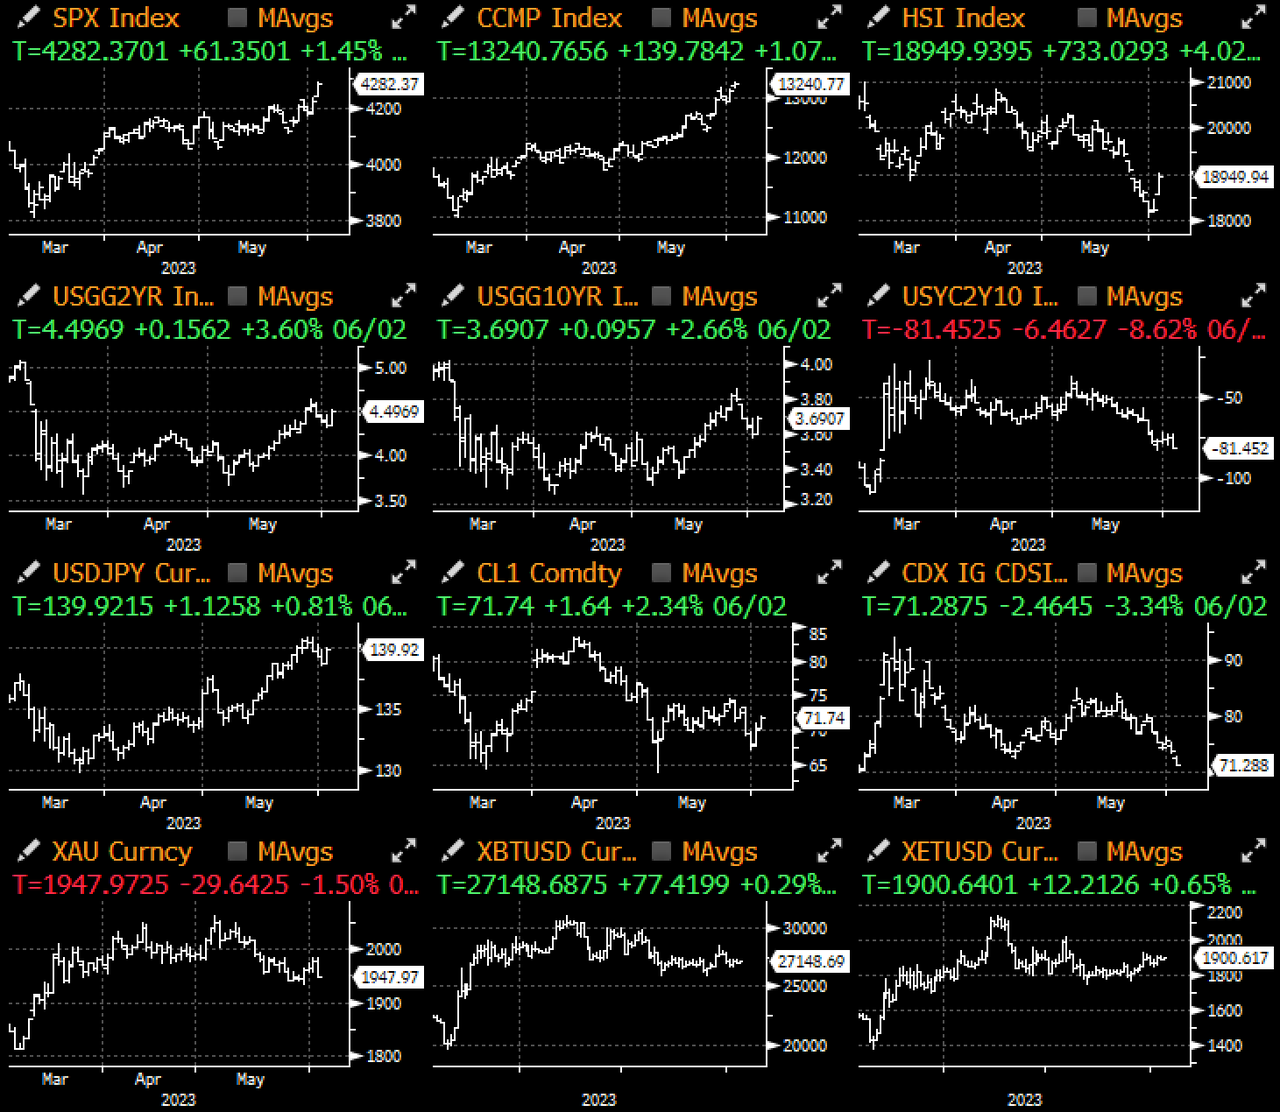
Elsewhere, the March banking crisis appeared to be well behind us, with U.S. banks continuing to see modest deposit inflows, while China again hinted at easing, fueling risk appetite and spurring a rebound in the Hang Seng after weeks of underperformance 4%; As China's economic performance remains unsatisfactory after reopening, the People's Bank of China and SAFE are now under intense pressure to provide large-scale easing measures, especially given the weakness in China's domestic real estate market, aggressive easing measures are expected to Expected to revive buyer sentiment.In stark contrast is the U.S. housing market, where activity has rebounded in 2023 despite mortgage rates hovering around 15-year highs around 7%, where affordability is poor but extremely low housing inventory is limiting the extent to which dwelling prices have fallen; moreover, despite very high borrowing costs, the exact opposite of what we saw during the global financial crisis,Home foreclosures at lowest level since 1985, further confirming that the financial position of the U.S. consumer remains very strong,
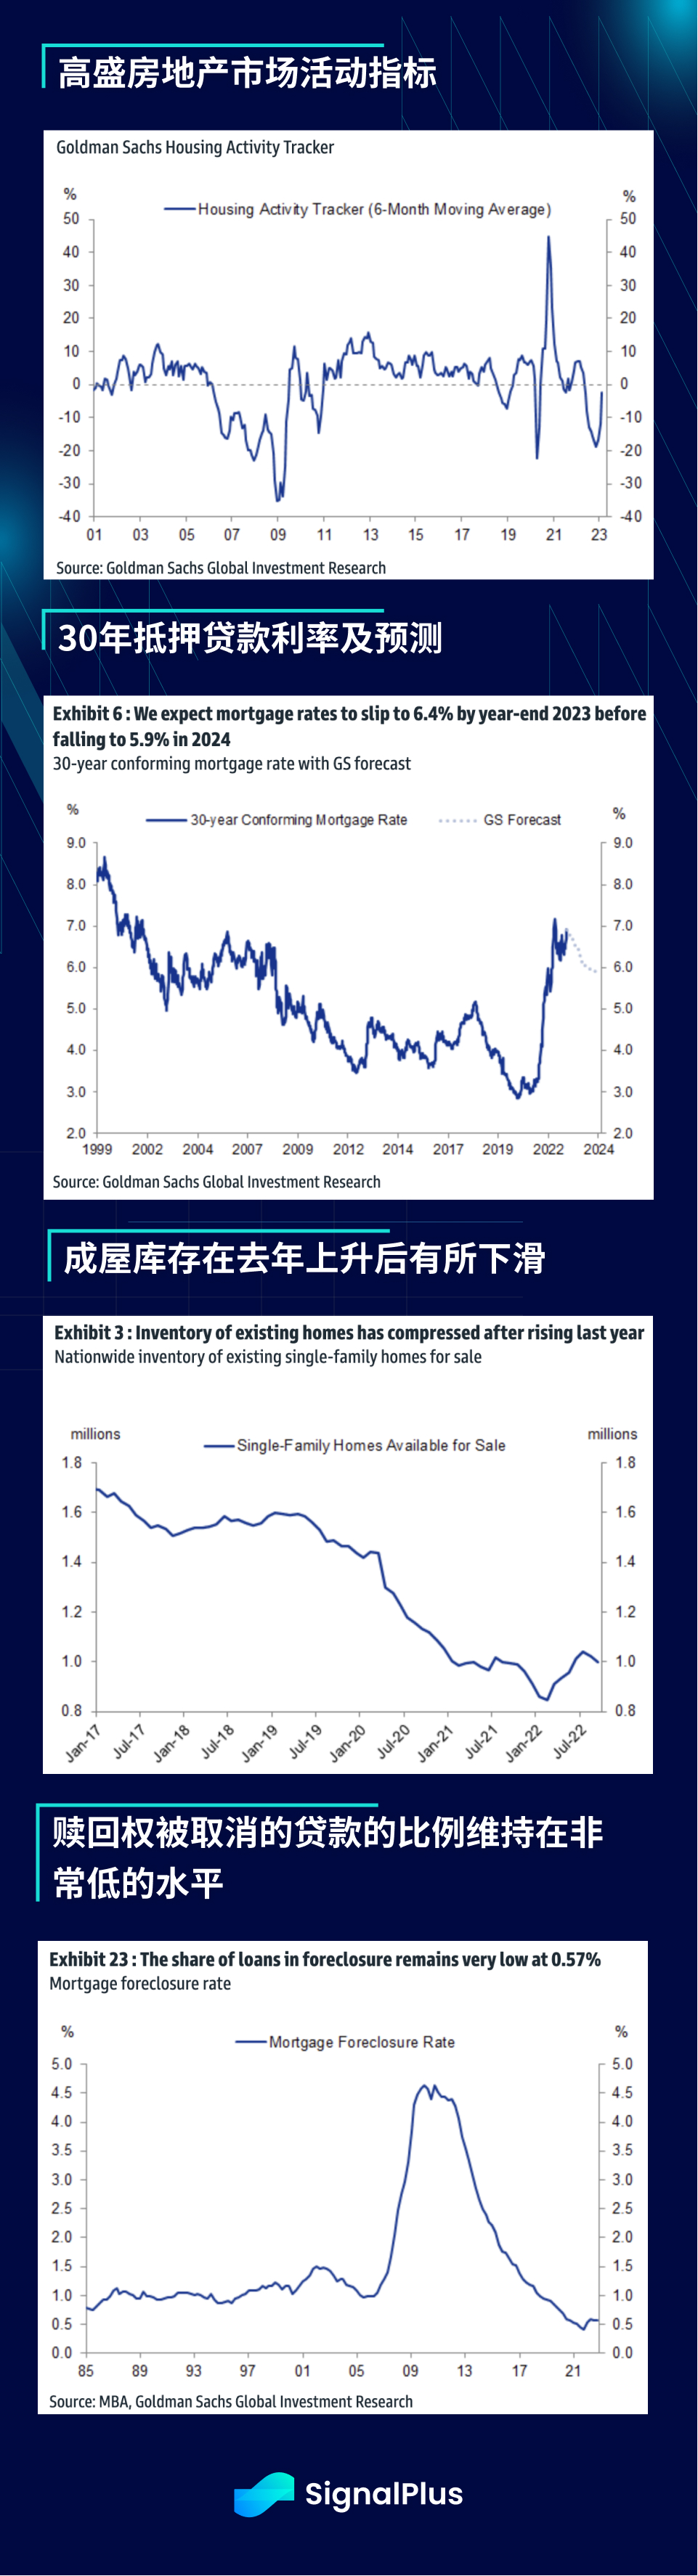
It also reinforces our view that the Fed is more likely to raise interest rates than cut them at the end of the year.Next week's data will be relatively light.The CPI will be released before the FOMC meeting and may be the only data that has a chance to move the market
— -
Registration link: https://t.signalplus.com/competition-okx?locale=zh-CN
Registration link: https://t.signalplus.com/competition-okx?locale=zh-CN
If you want to receive our updates immediately, welcome to follow our Twitter account @SignalPlus_Web 3 , or join our WeChat group (add a small assistant WeChat: chillywzq), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website: https://www.signalplus.com/





