






SignalPlus Macro Research Report 20230601: U.S. Debt Ceiling Vote Passed, Will Consider Suspension of Interest Rate Hike in June


Dear friends, welcome to the SignalPlus macro research report. SignalPlus macro research reports update macro market information for you every day, and share our observations and opinions on macro trends. Welcome to track and subscribe, and follow the latest market trends with us.
Dear friends, welcome to the SignalPlus macro research report. SignalPlus macro research reports update macro market information for you every day, and share our observations and opinions on macro trends. Welcome to track and subscribe, and follow the latest market trends with us.
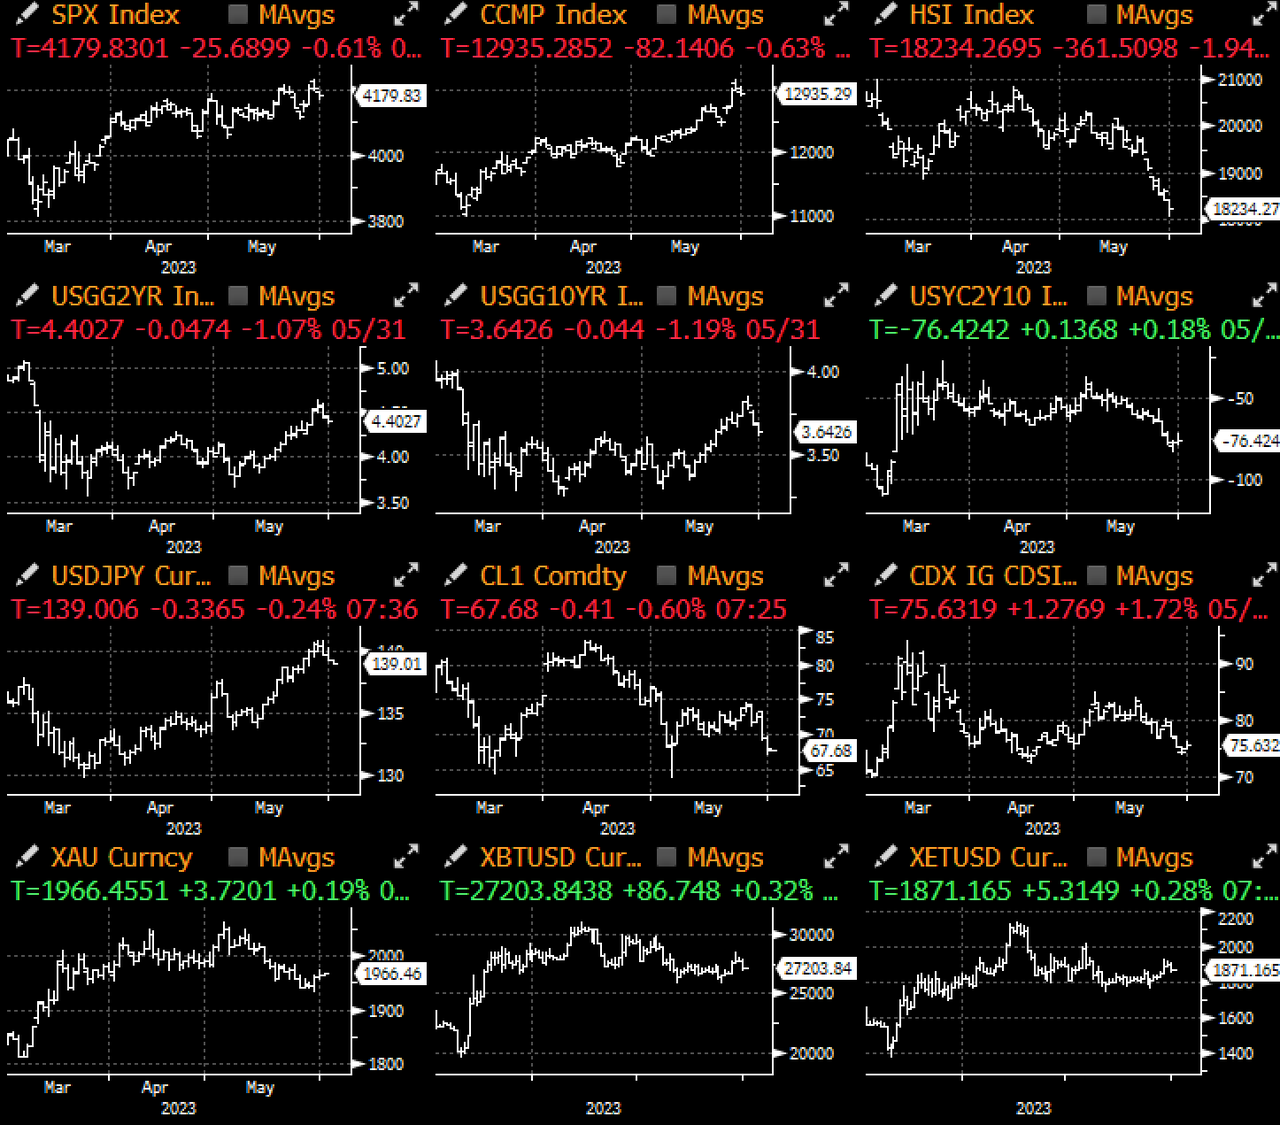
Data showing moderating inflation offset strong JOLTS data, helping bond yields stay under control in yesterday's month-end rebalancing. The economic data started with China's weak PMI (48.8), the lowest since December last year, South Korea's industrial production also fell by 8.9% year-on-year, followed by weaker-than-expected inflation data released by Germany and France during the European session. Chicago PMI fell to 40.4, close to the lowest level in the past 3 years (November 2022 and May 2020), leading some Wall Street investment banks to urgently downgrade today's ISM forecast.
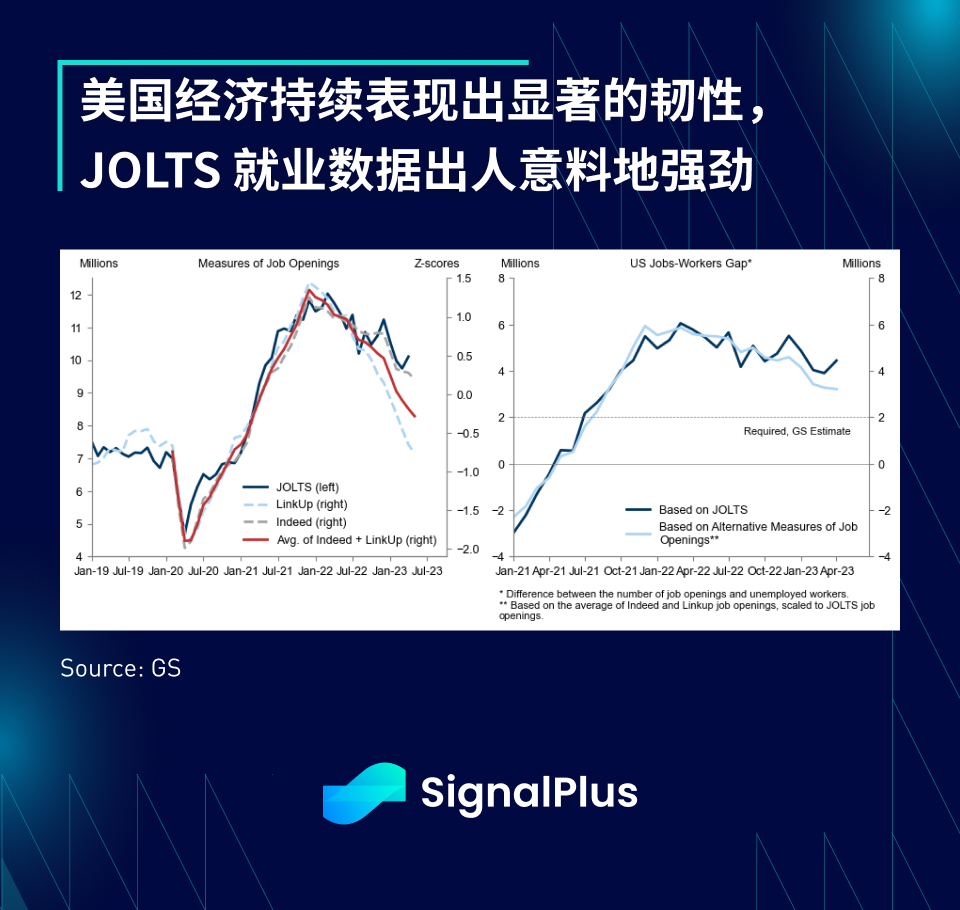
The most unexpected data result was JOLTS, with 10.1 million job vacancies compared to the expected 9.4 million, which is more than 4 standard deviations. -2.6% slipped to 2.4%, while Powell's preferred "jobs to unemployment" ratio also rose to 1.8 times, in contrast to other weak employment data.
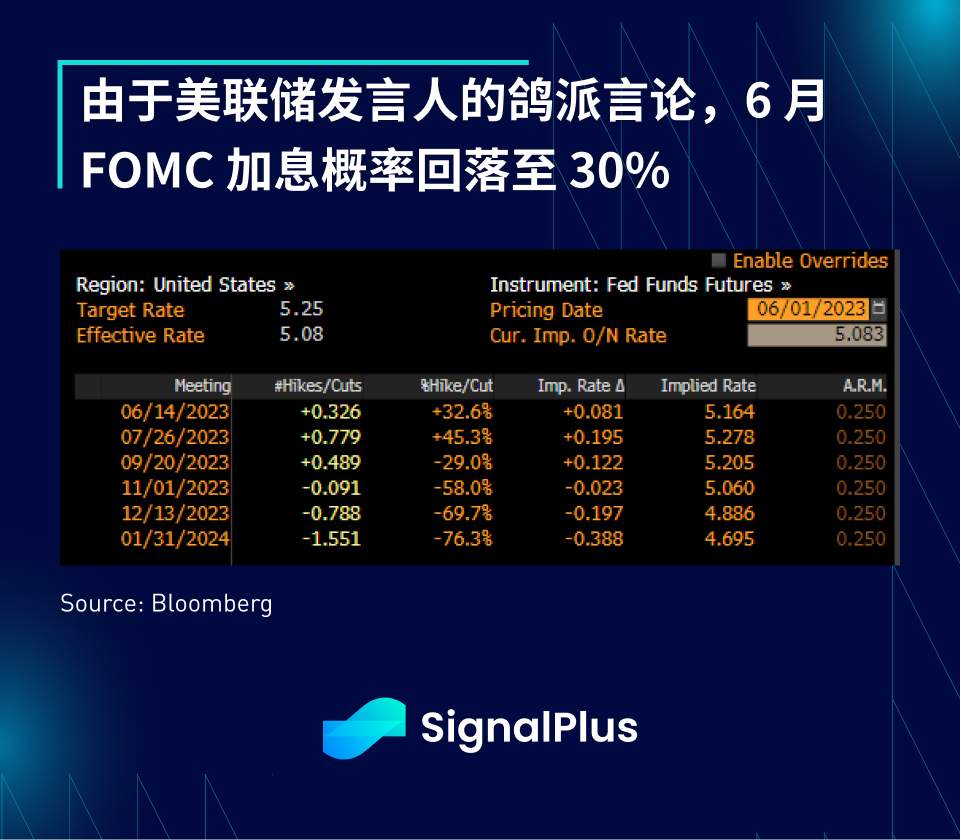
However, U.S. bonds rose again on the day, with yields falling about 6 basis points across the board. The strong employment data was offset by a series of dovish remarks advocating skipping interest rate hikes in June. Not enough to feel the full impact of [the Fed's tightening policy]", so skipping a rate hike in June would "give the FOMC more data before making a decision", a sentiment echoed by Philly Fed President Harker, who said Pointing out that the FOMC "should really skip" a June rate hike, these comments have sharply reduced market expectations for a rate hike this month to around 30%.
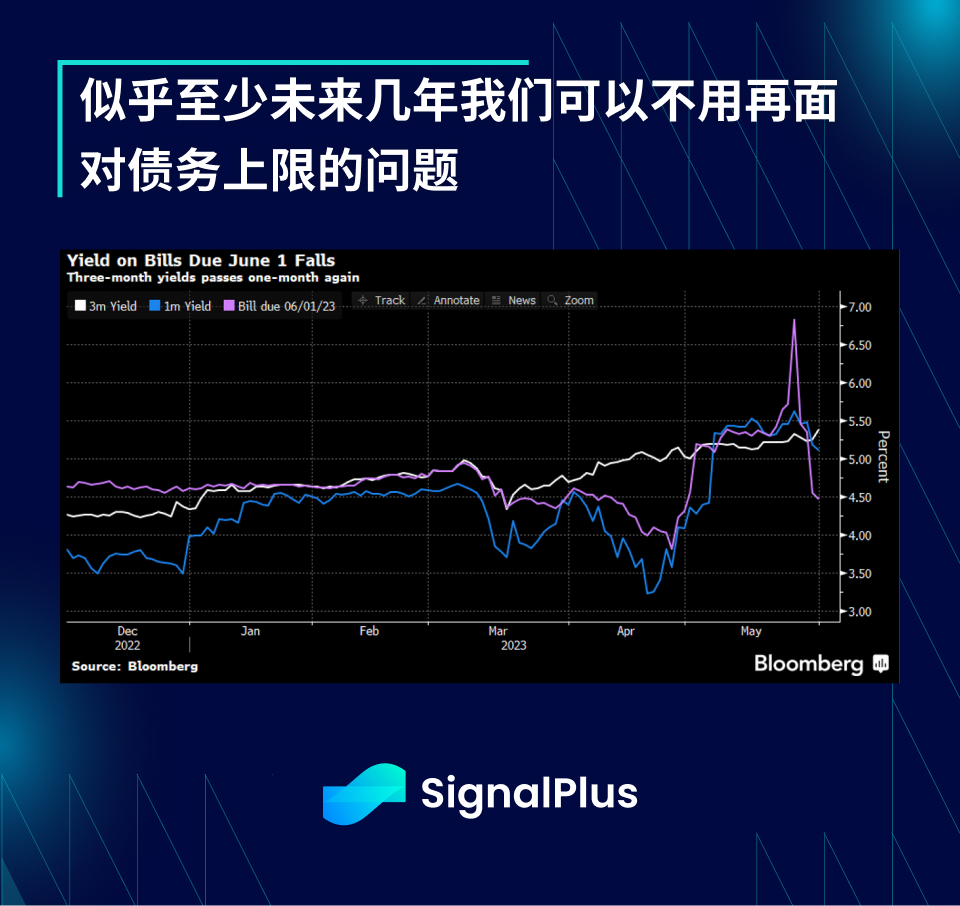
On the political front, the debt ceiling debate appears to be finally coming to an end, with the Republican-controlled House just passing a vote and the bill should pass the Democrat-led Senate before reaching the Oval Office by a possible X-date next week; markets Pricing apparently sees this issue as "a foregone conclusion," with T-bills falling back into base rate territory and the rest of us happy to finally be out of these embarrassing gigs.
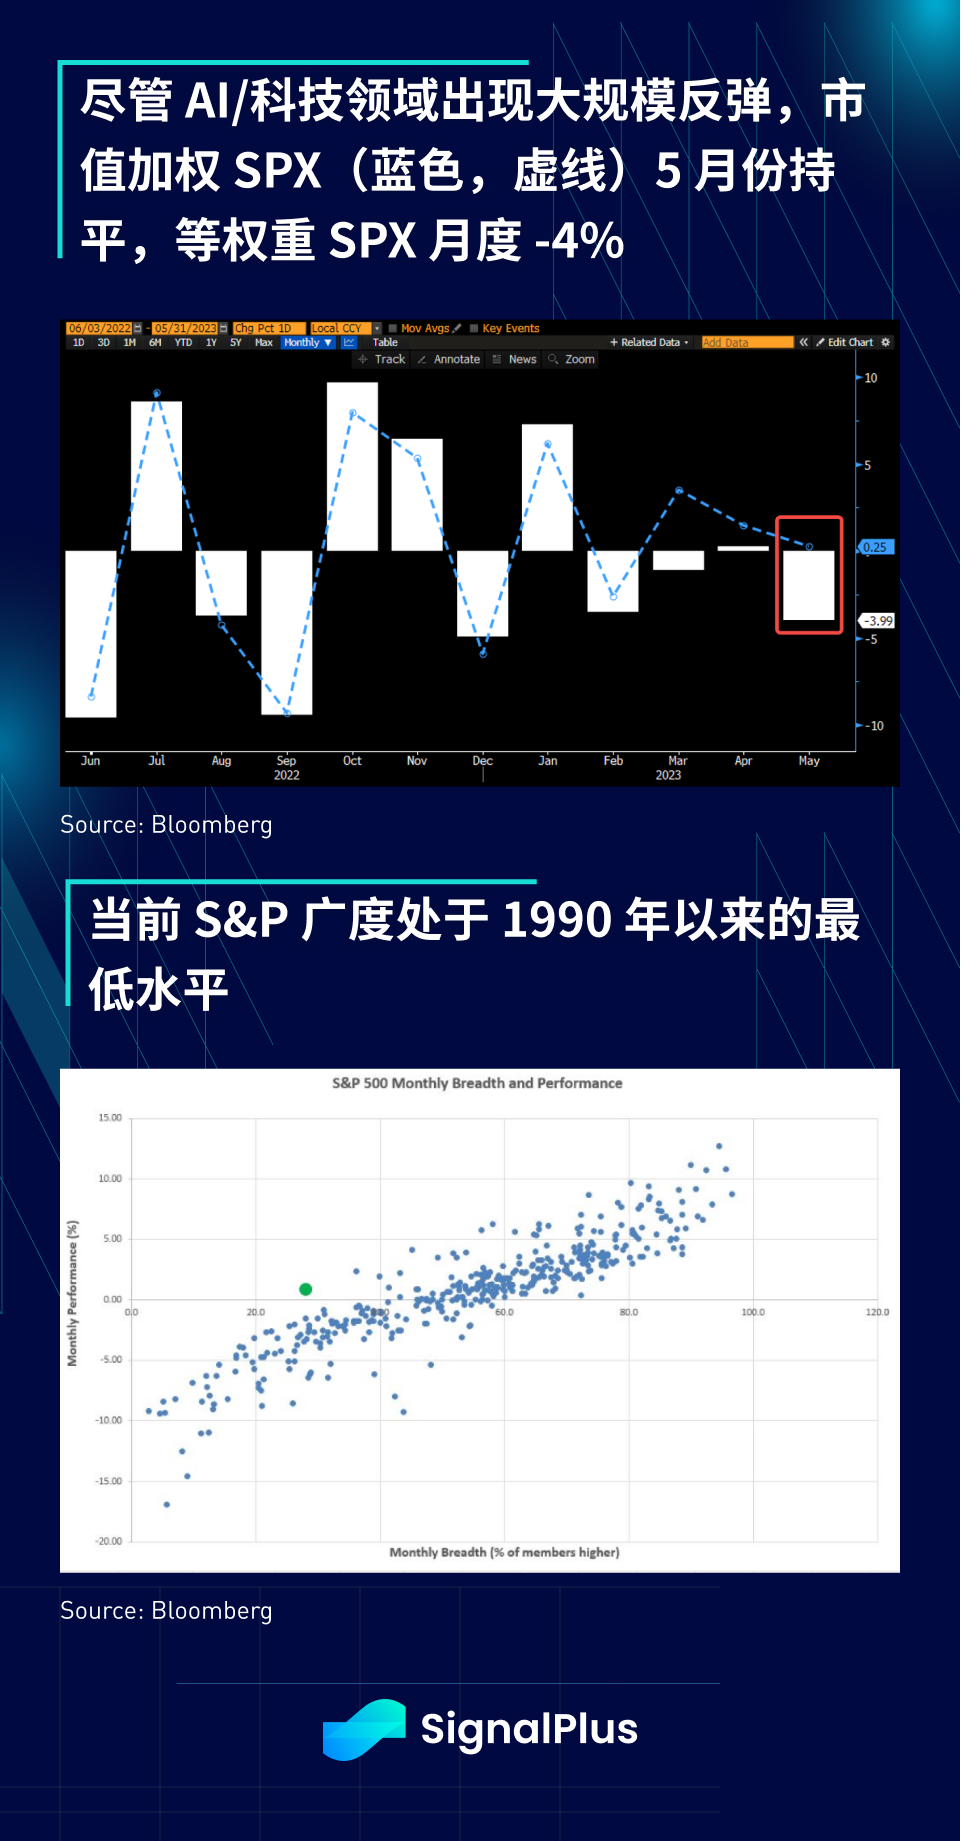
While big tech and AI-related stocks staged a huge rally in May (Nvidia rose 36% in May alone), the market-cap-weighted SPX index was only flat in May, while its equal-weighted version was actually up fell 4% for the month. Poor market breadth has been much discussed in this rally, but current data shows that narrowness is indeed at historically extreme levels not seen since 1990, which may be one reason why the current rally is so "nasty" to the general public , as a winner-take-all situation means average investors are underperformed in rewards, and market narrative is everything.
Registration link: https://t.signalplus.com/competition-okx?locale=zh-CN
Registration link: https://t.signalplus.com/competition-okx?locale=zh-CN
If you want to receive our updates immediately, welcome to follow our Twitter account @SignalPlus_Web 3 , or join our WeChat group (add a small assistant WeChat: chillywzq), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website: https://www.signalplus.com/





