






SignalPlus Macro Review (20230518)


Dear friends, welcome to the SignalPlus macro review. SignalPlus macro reviews update macro market information for you every day, and share our observations and opinions on macro trends. Welcome to track and subscribe, and follow the latest market trends with us.
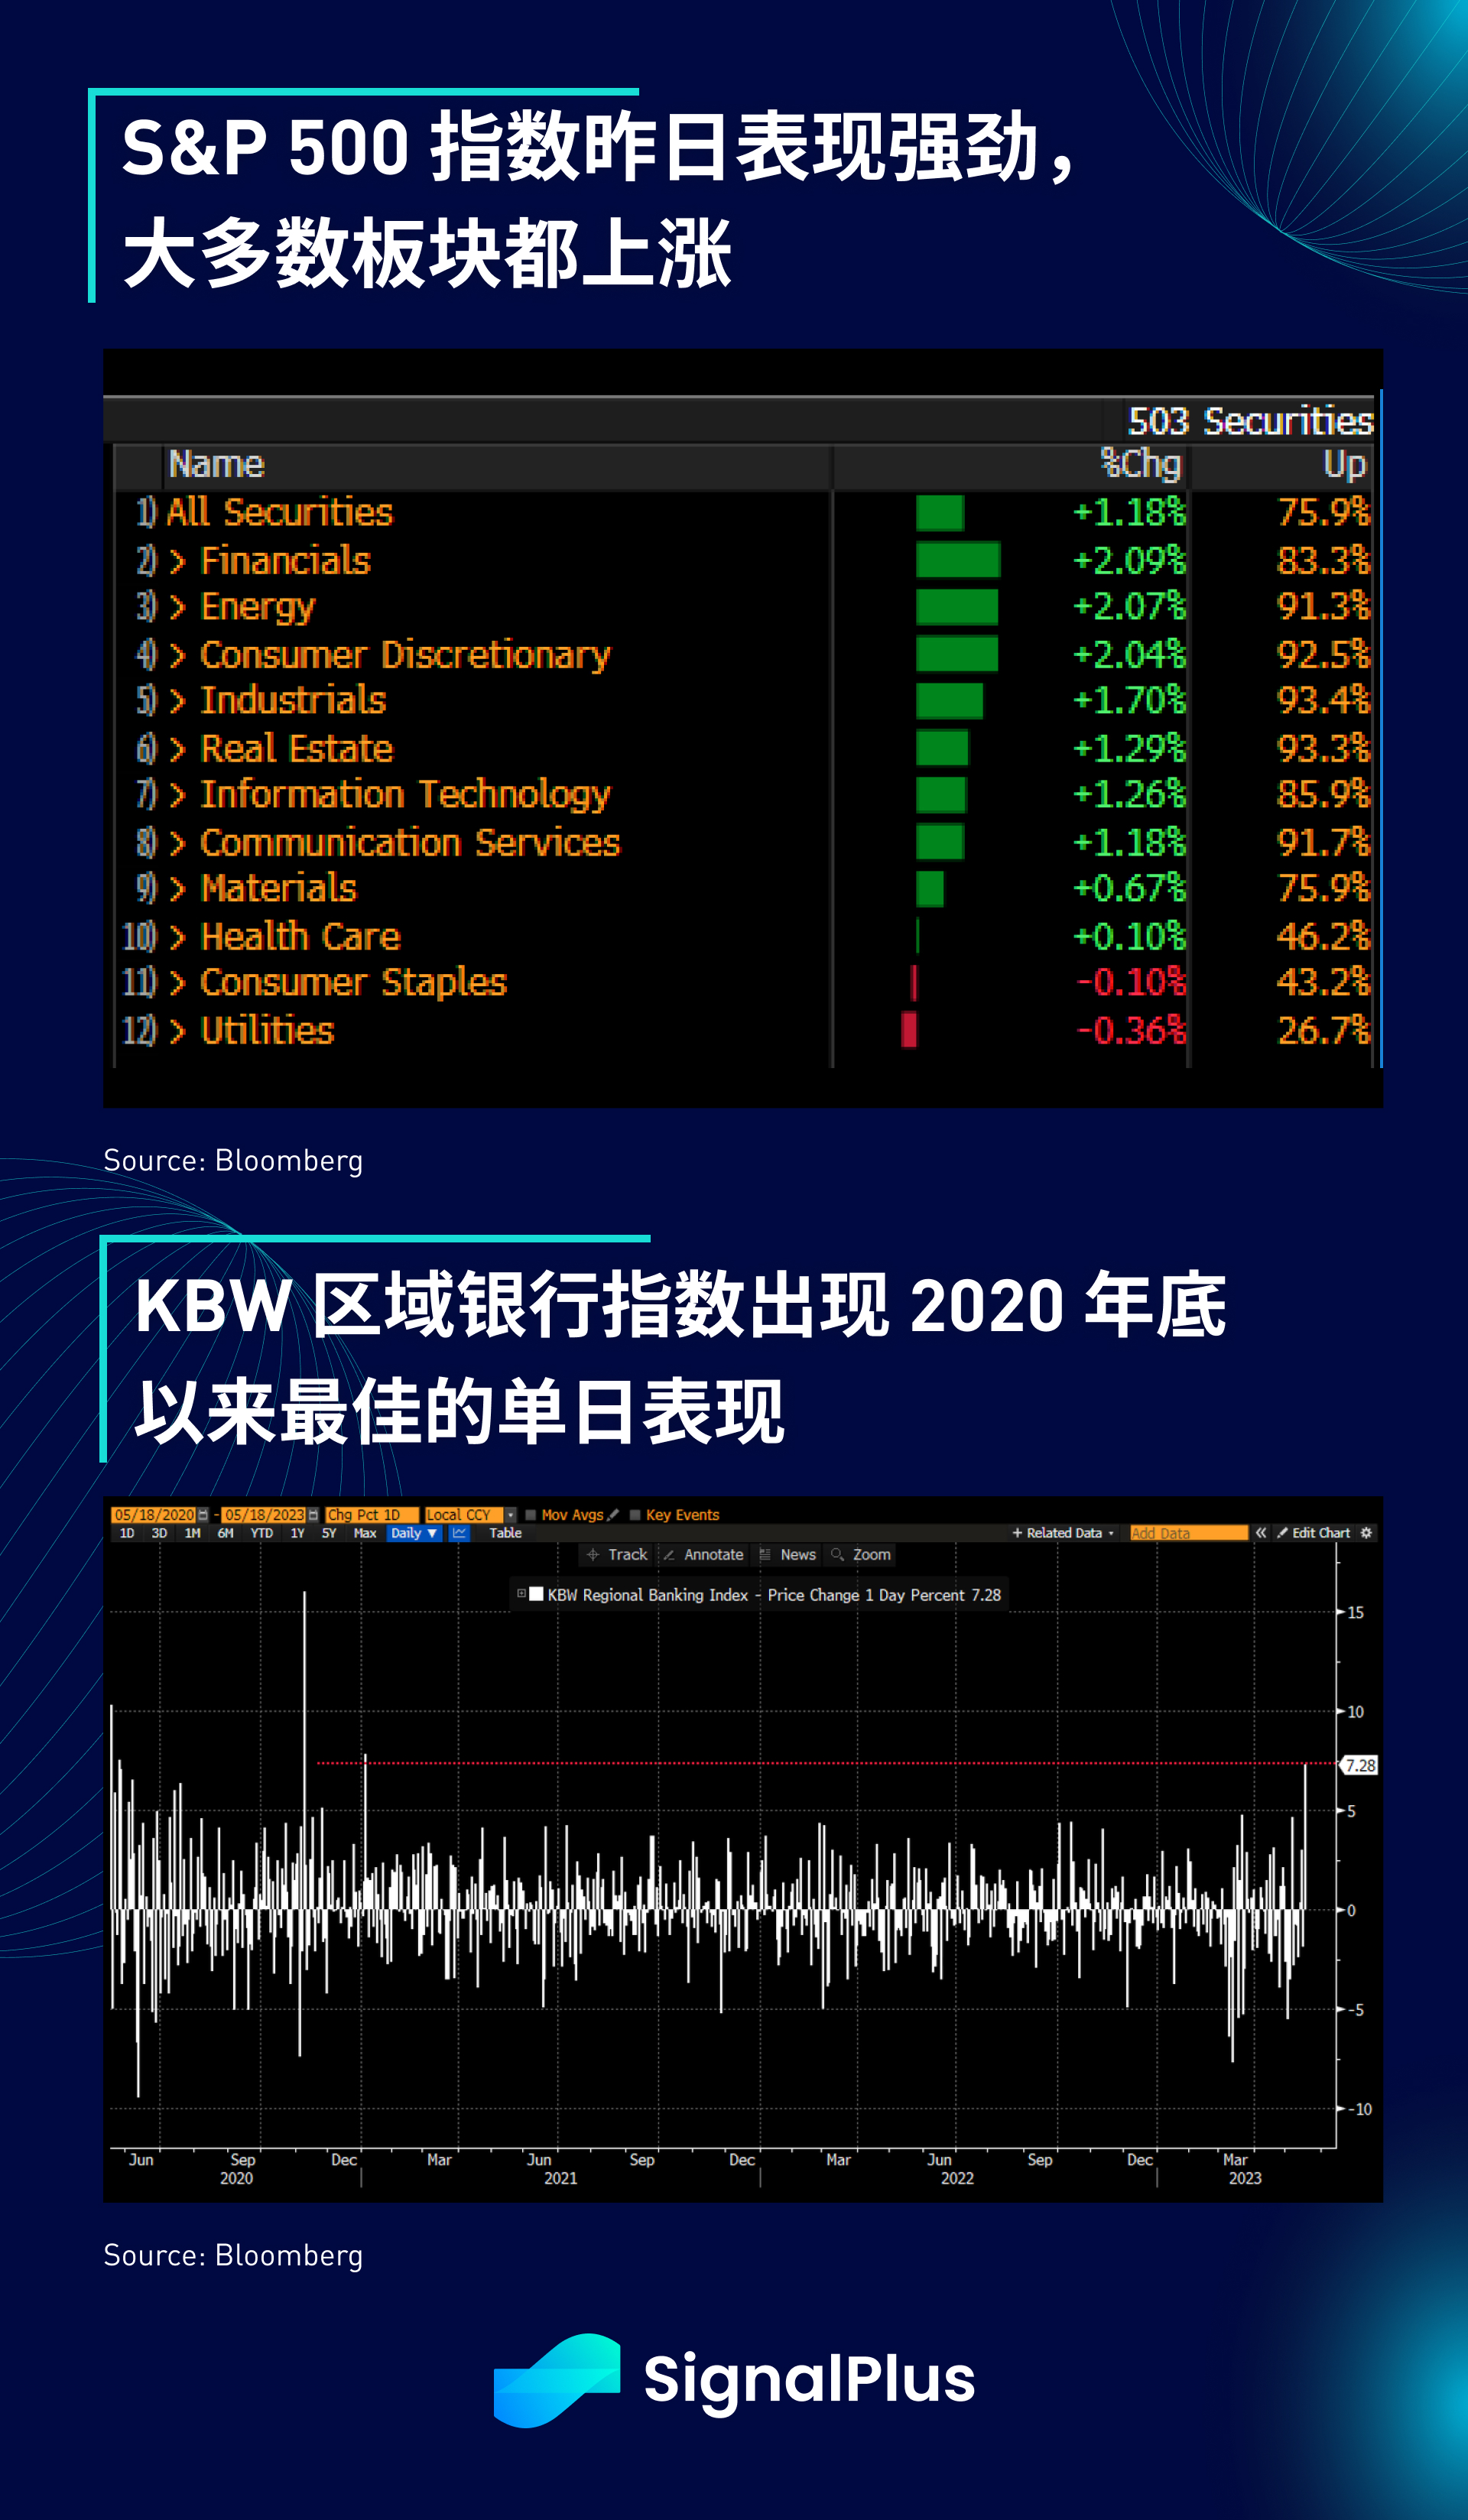
U.S. stocks showed signs of a positive breakout for the first time yesterday, buoyed by a strong rally in regional bank stocks and a possible debt ceiling deal this week. Western Alliance Bancorp led the gains in bank stocks after announcing that deposits rose more than expected in the past week, with the KBW regional bank index rising more than 7.2%, its best day since January 2021.
On the congressional front, talks between President Biden and House Speaker McCarthy on Wednesday turned out much better than expected, with the two sides agreeing to more intensive talks on spending curbs, which should pave the way for an eventual increase in the debt ceiling; McCarthy further said that while Negotiations remained "very divided," but he saw the possibility of a deal "by the end of the week," with all parties agreeing to avoid a possible technical default by the U.S. in early June.
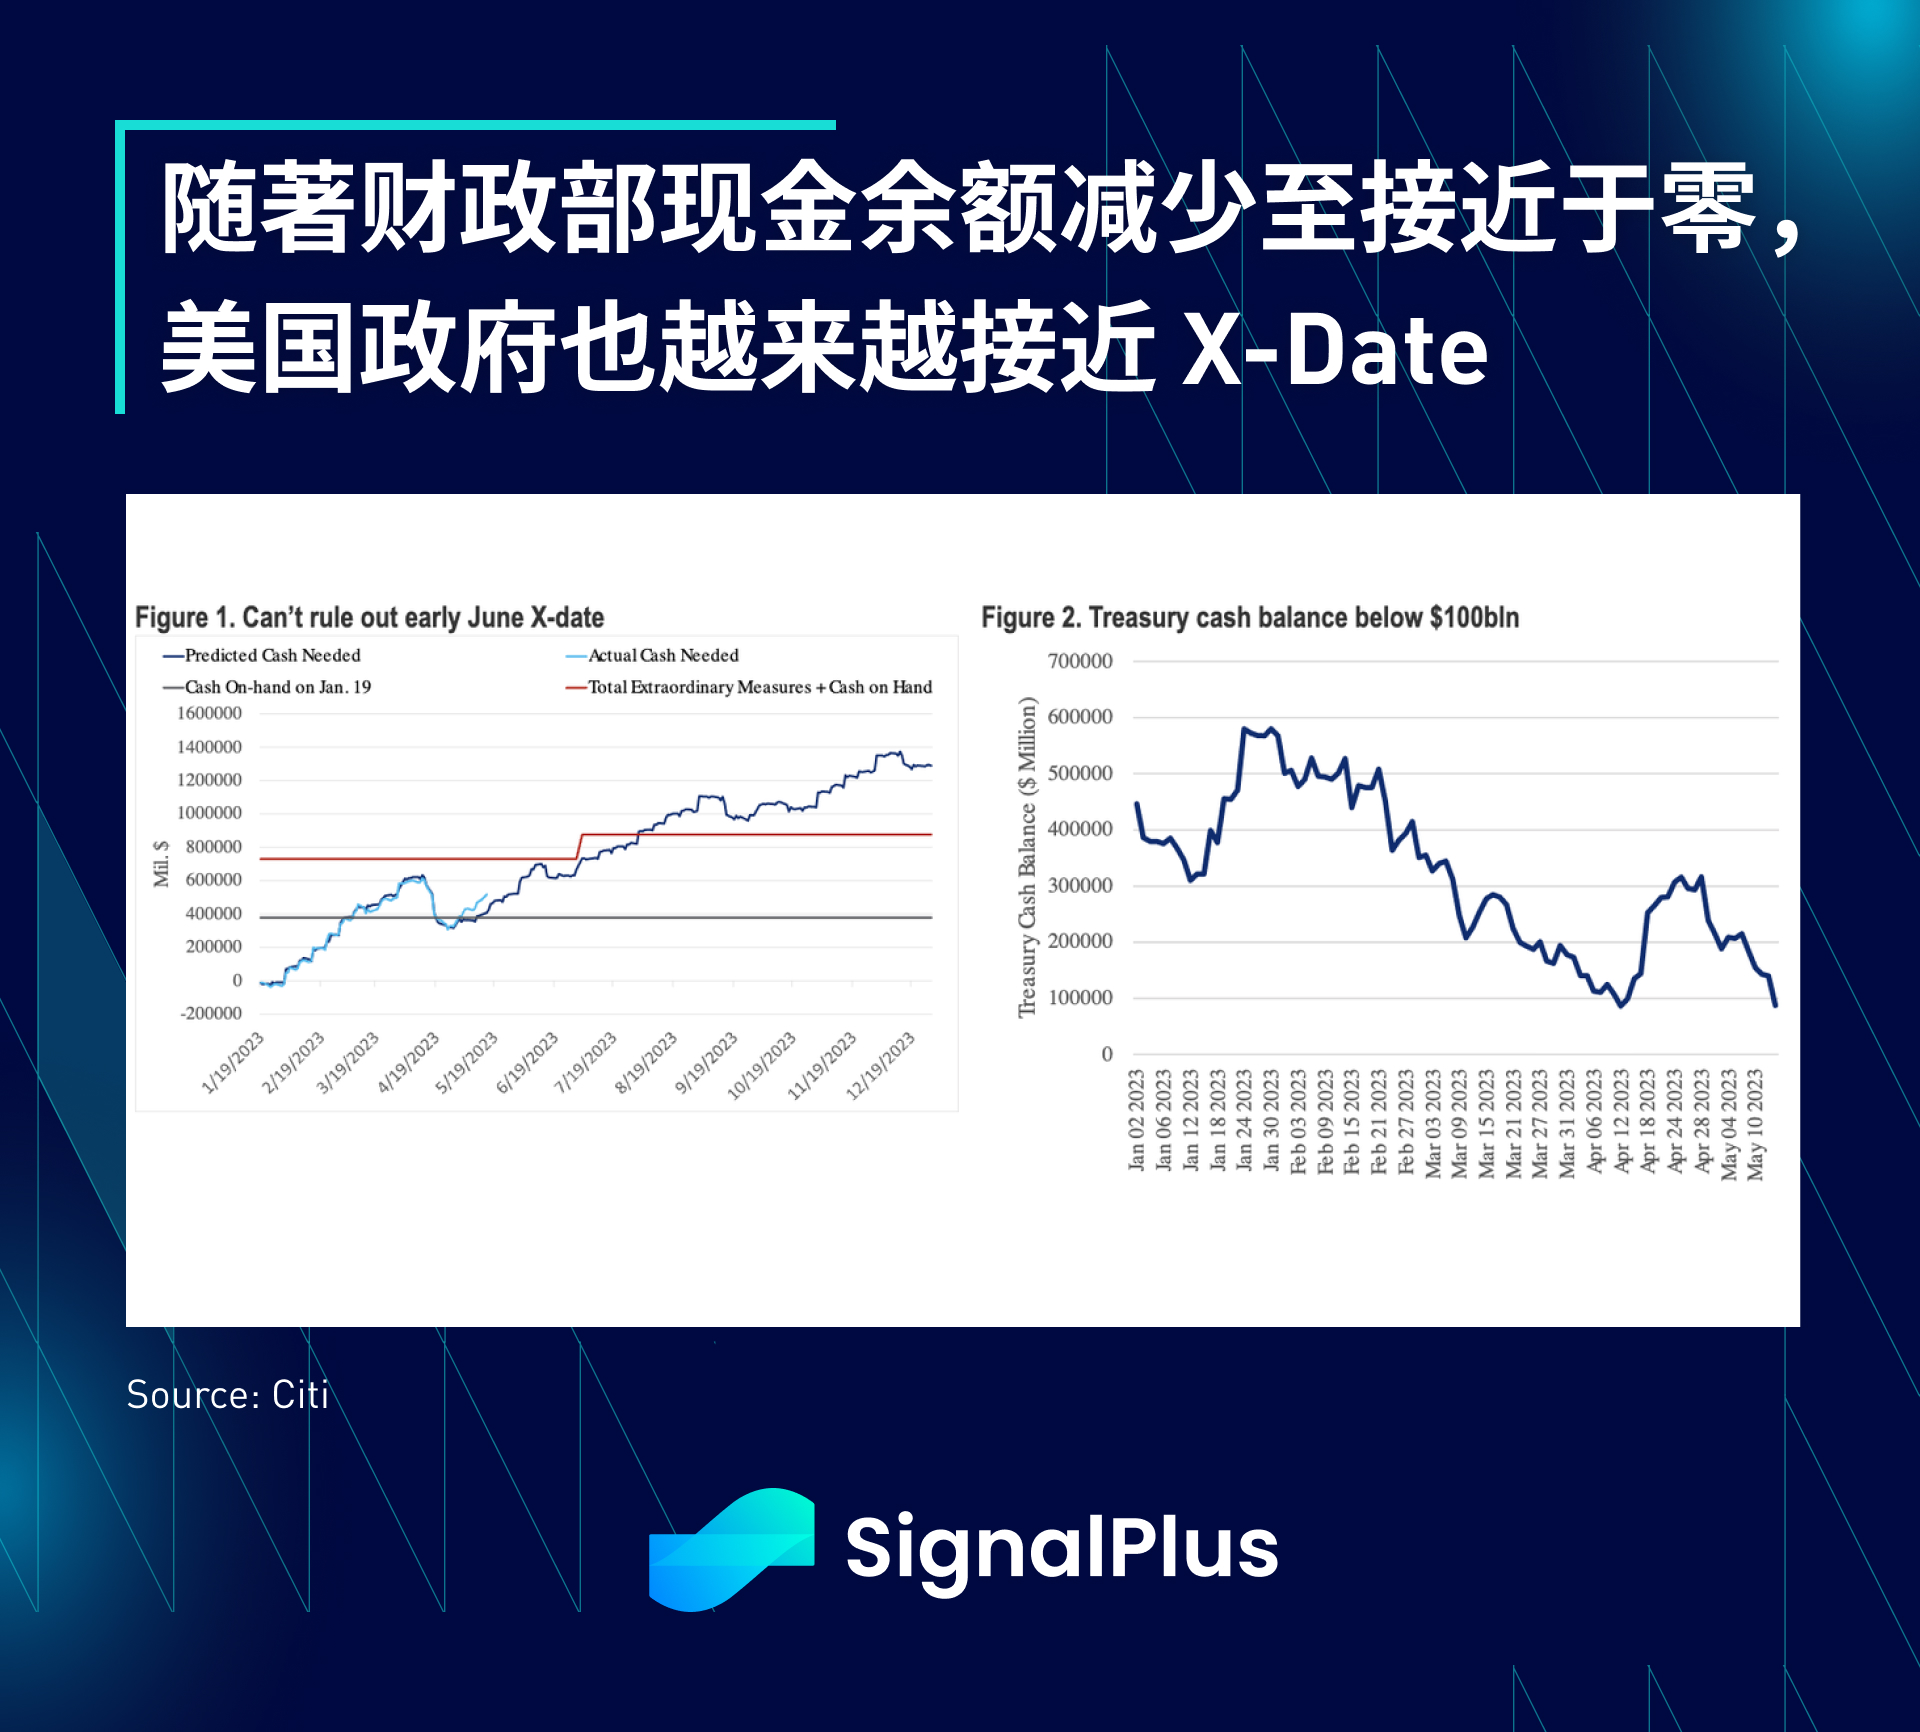
While the headlines are positive, we can also consider possible details of a potential deal, with Republican concessions likely to include some caps on government discretionary spending through 2025 while clawing back unused funds previously set aside for COVID-19 prevention measures Partly, as we head into the 2024 election year, this will be somewhat of a fiscal drag (lower spending) and pressure on GDP, and the Treasury will also be looking to significantly replenish its TGA (working capital) account, which Now down to less than $100 billion, replenishing the TGA would require drawing liquidity from the system (cash back to the Treasury) and could require as much as $600-800 billion over the next few months, eventually The amount can only be finalized after determining whether the source of funds is RRP (reverse repurchase) or direct outflow.
All in all, a deal would avoid an embarrassing technical default, but would likely result in a fiscal drag on GDP and an immediate drain on overall liquidity from the system.
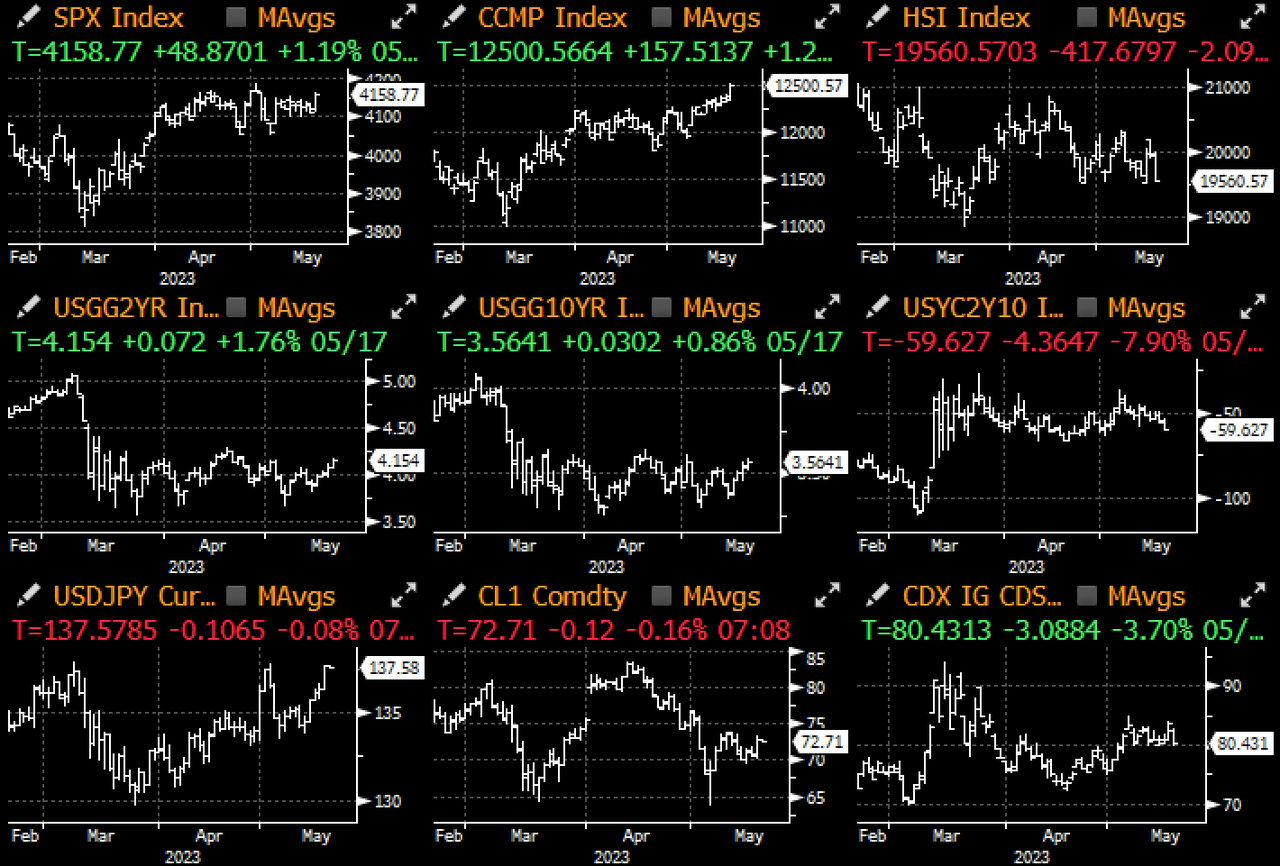
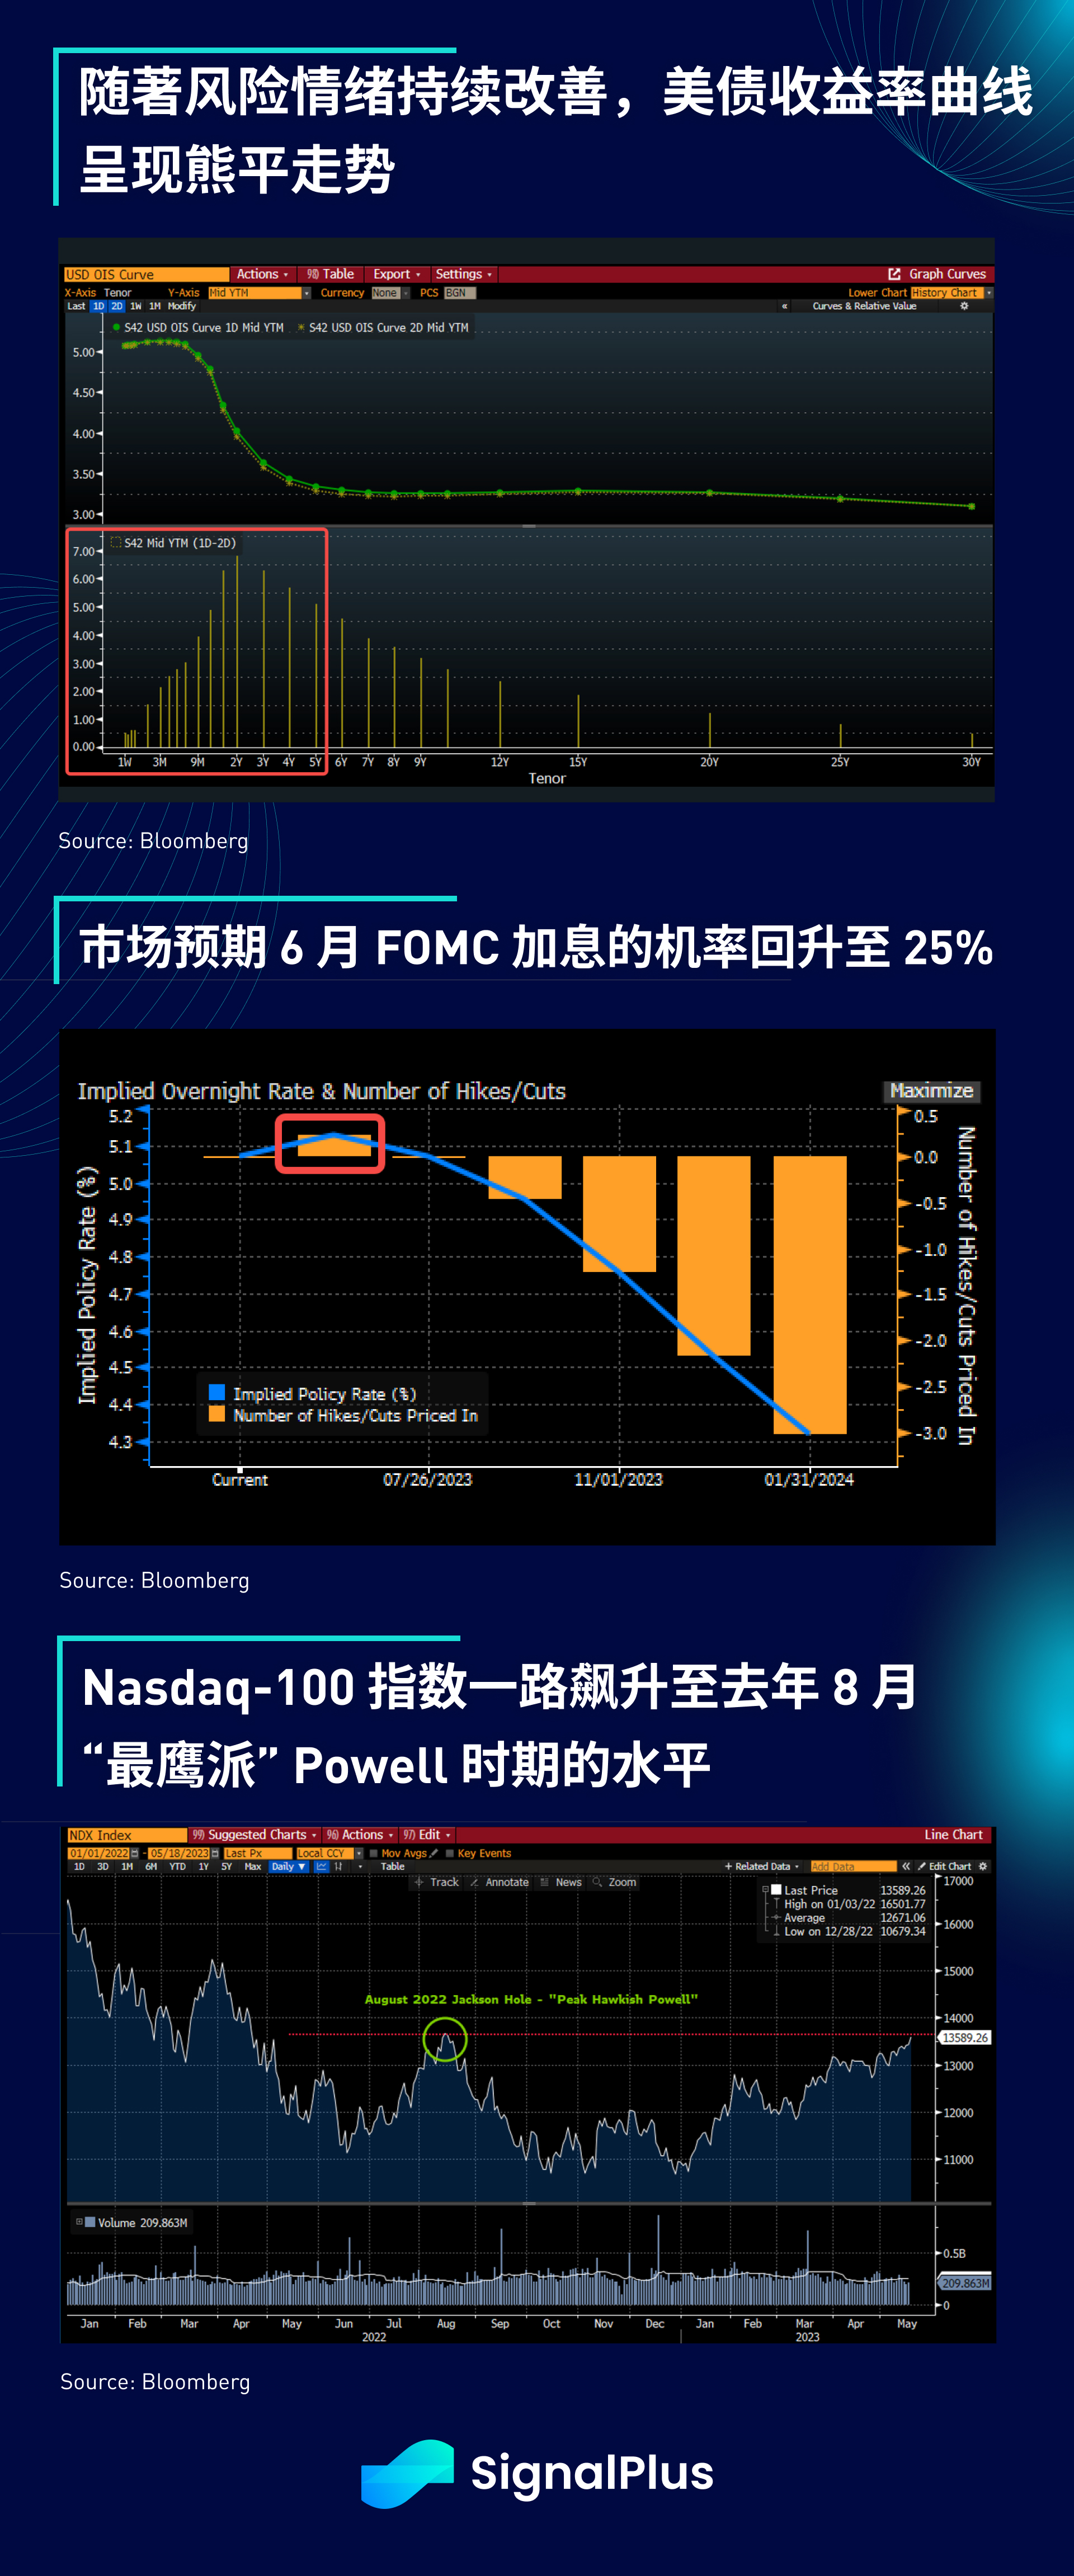
A marked improvement in risk sentiment, strong stock price action and positive momentum from recent economic data and debt ceiling talks pushed short-dated U.S. Treasury yields up about 6 basis points in a bearish-flat move; With 11 issuers announcing new debt offerings on Wednesday, this week's corporate paper supply has reached about $50 billion, leading to some duration indigestion; moreover, the likelihood of an FOMC rate hike in June has now returned to 25%, essentially 0% a week ago, though interestingly the market still expects the rate trajectory to shift immediately after June and still expects a 75 basis point cumulative rate cut by the end of the year. The Nasdaq 100 is now back at its mid-term highs from Jackson Hole in August, when the “most hawkish” Powell fired in full swing, sending asset prices lower, thanks to a strong stock market performance and expectations of Fed rate hikes resurfacing, we It is recommended to pay close attention to the risk of bond yields breaking higher from current levels in the coming weeks.
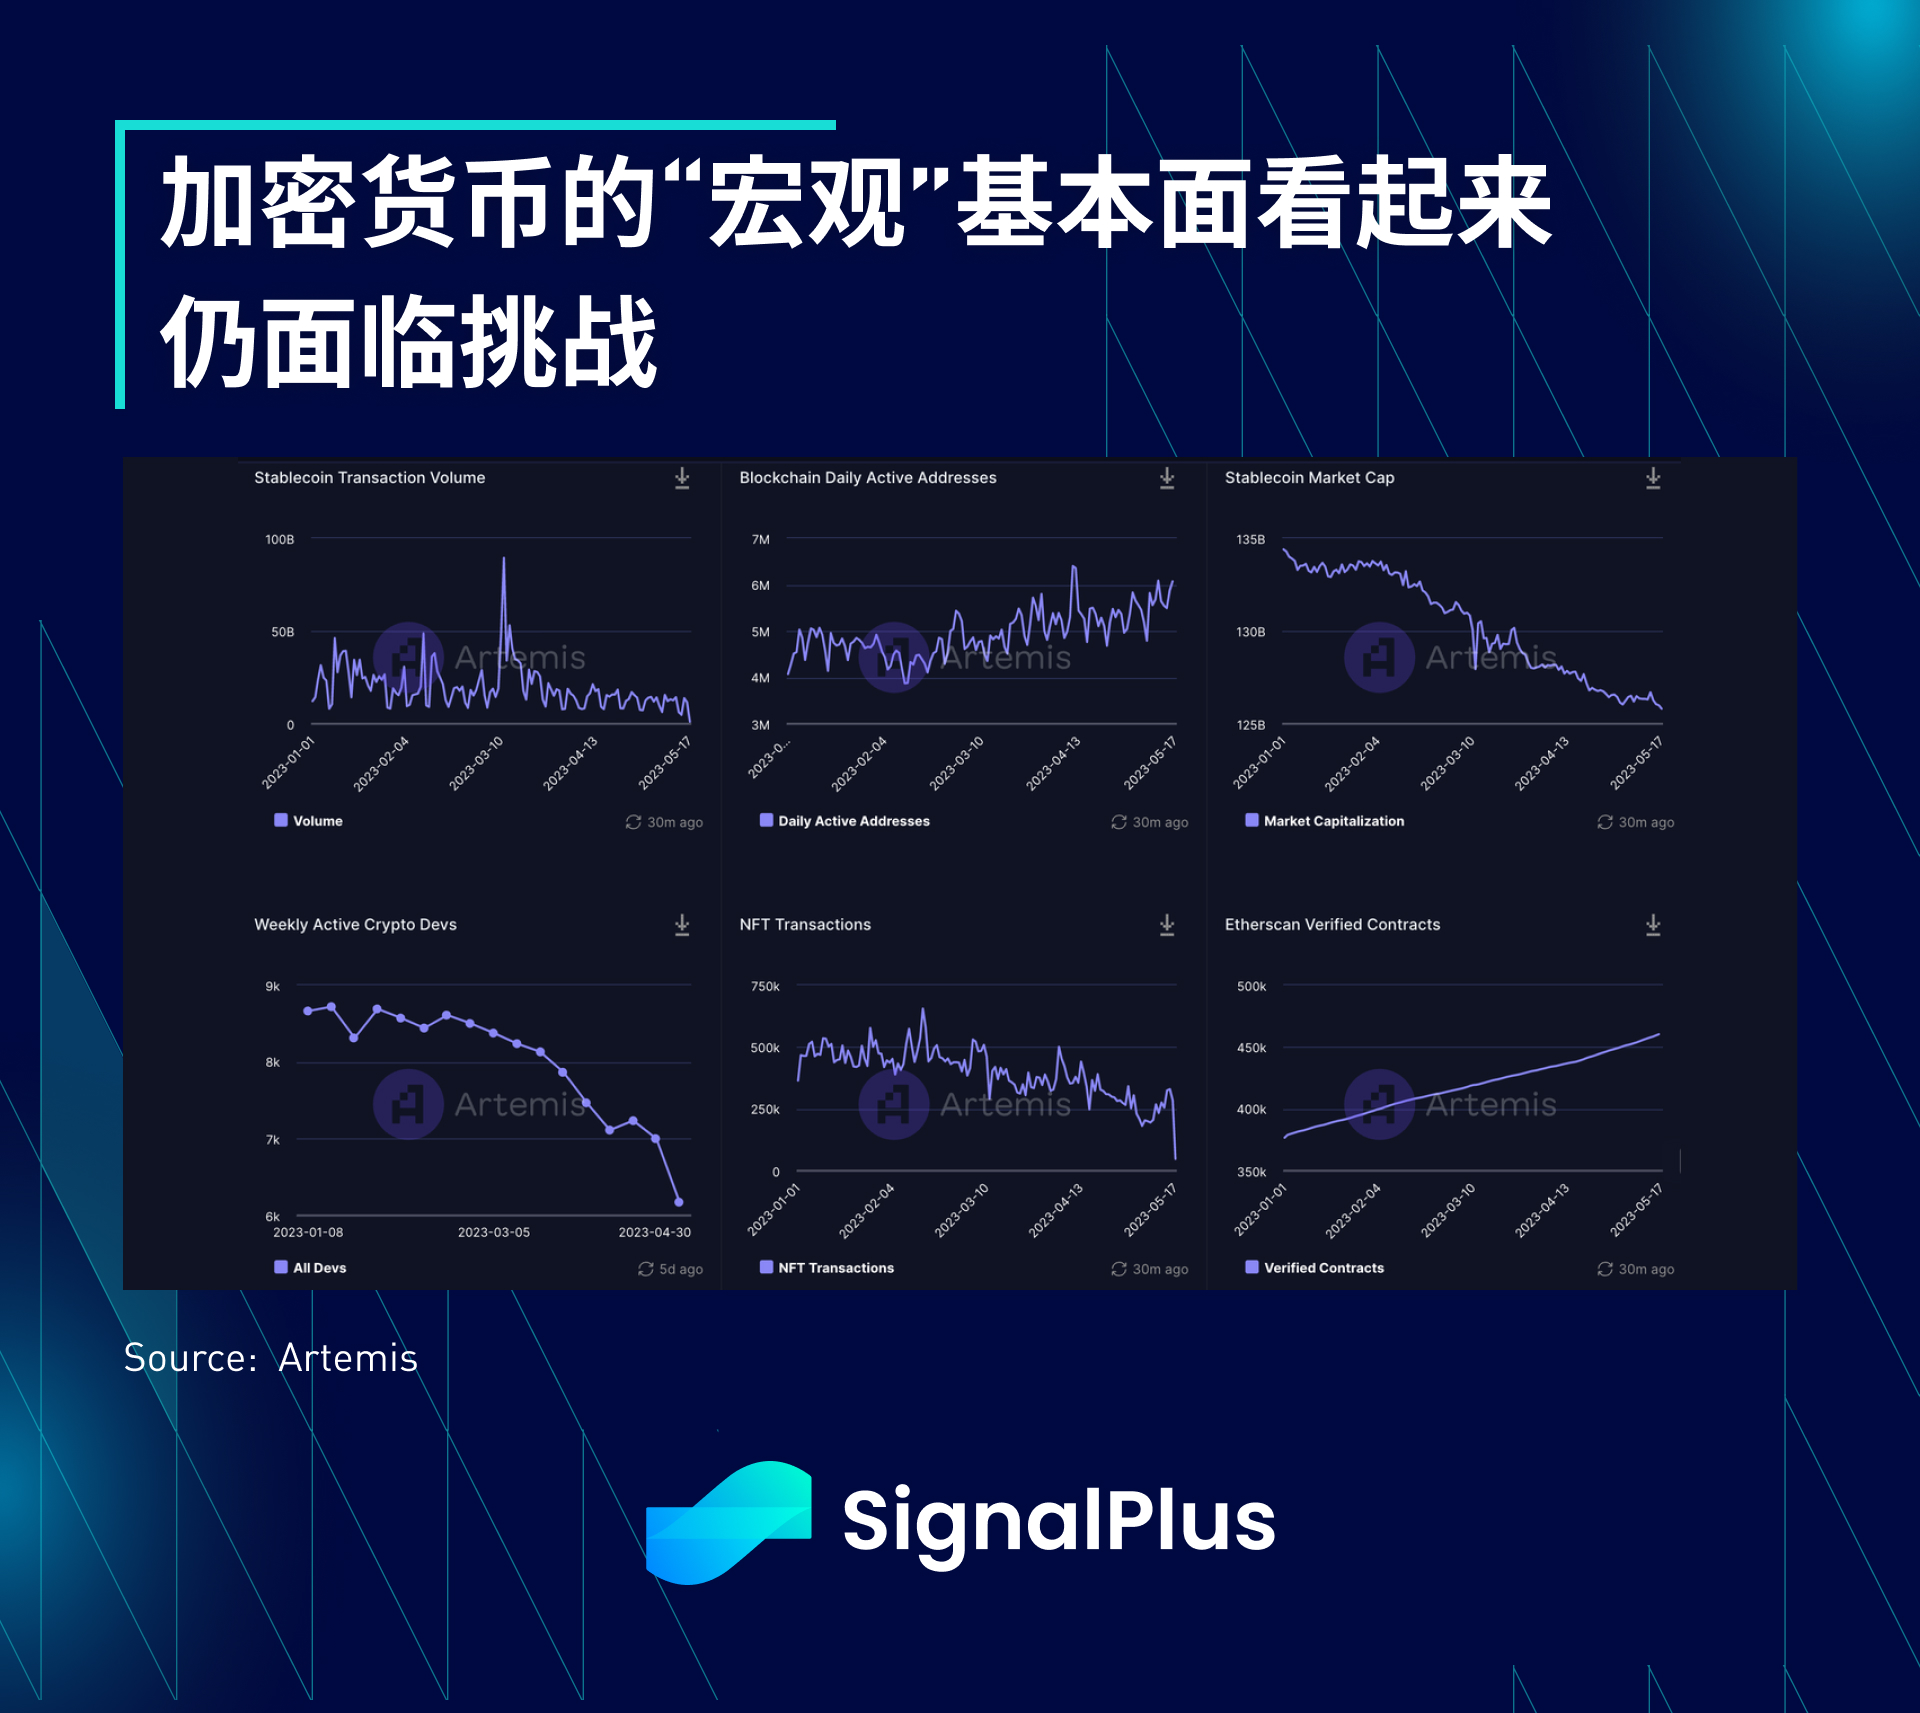
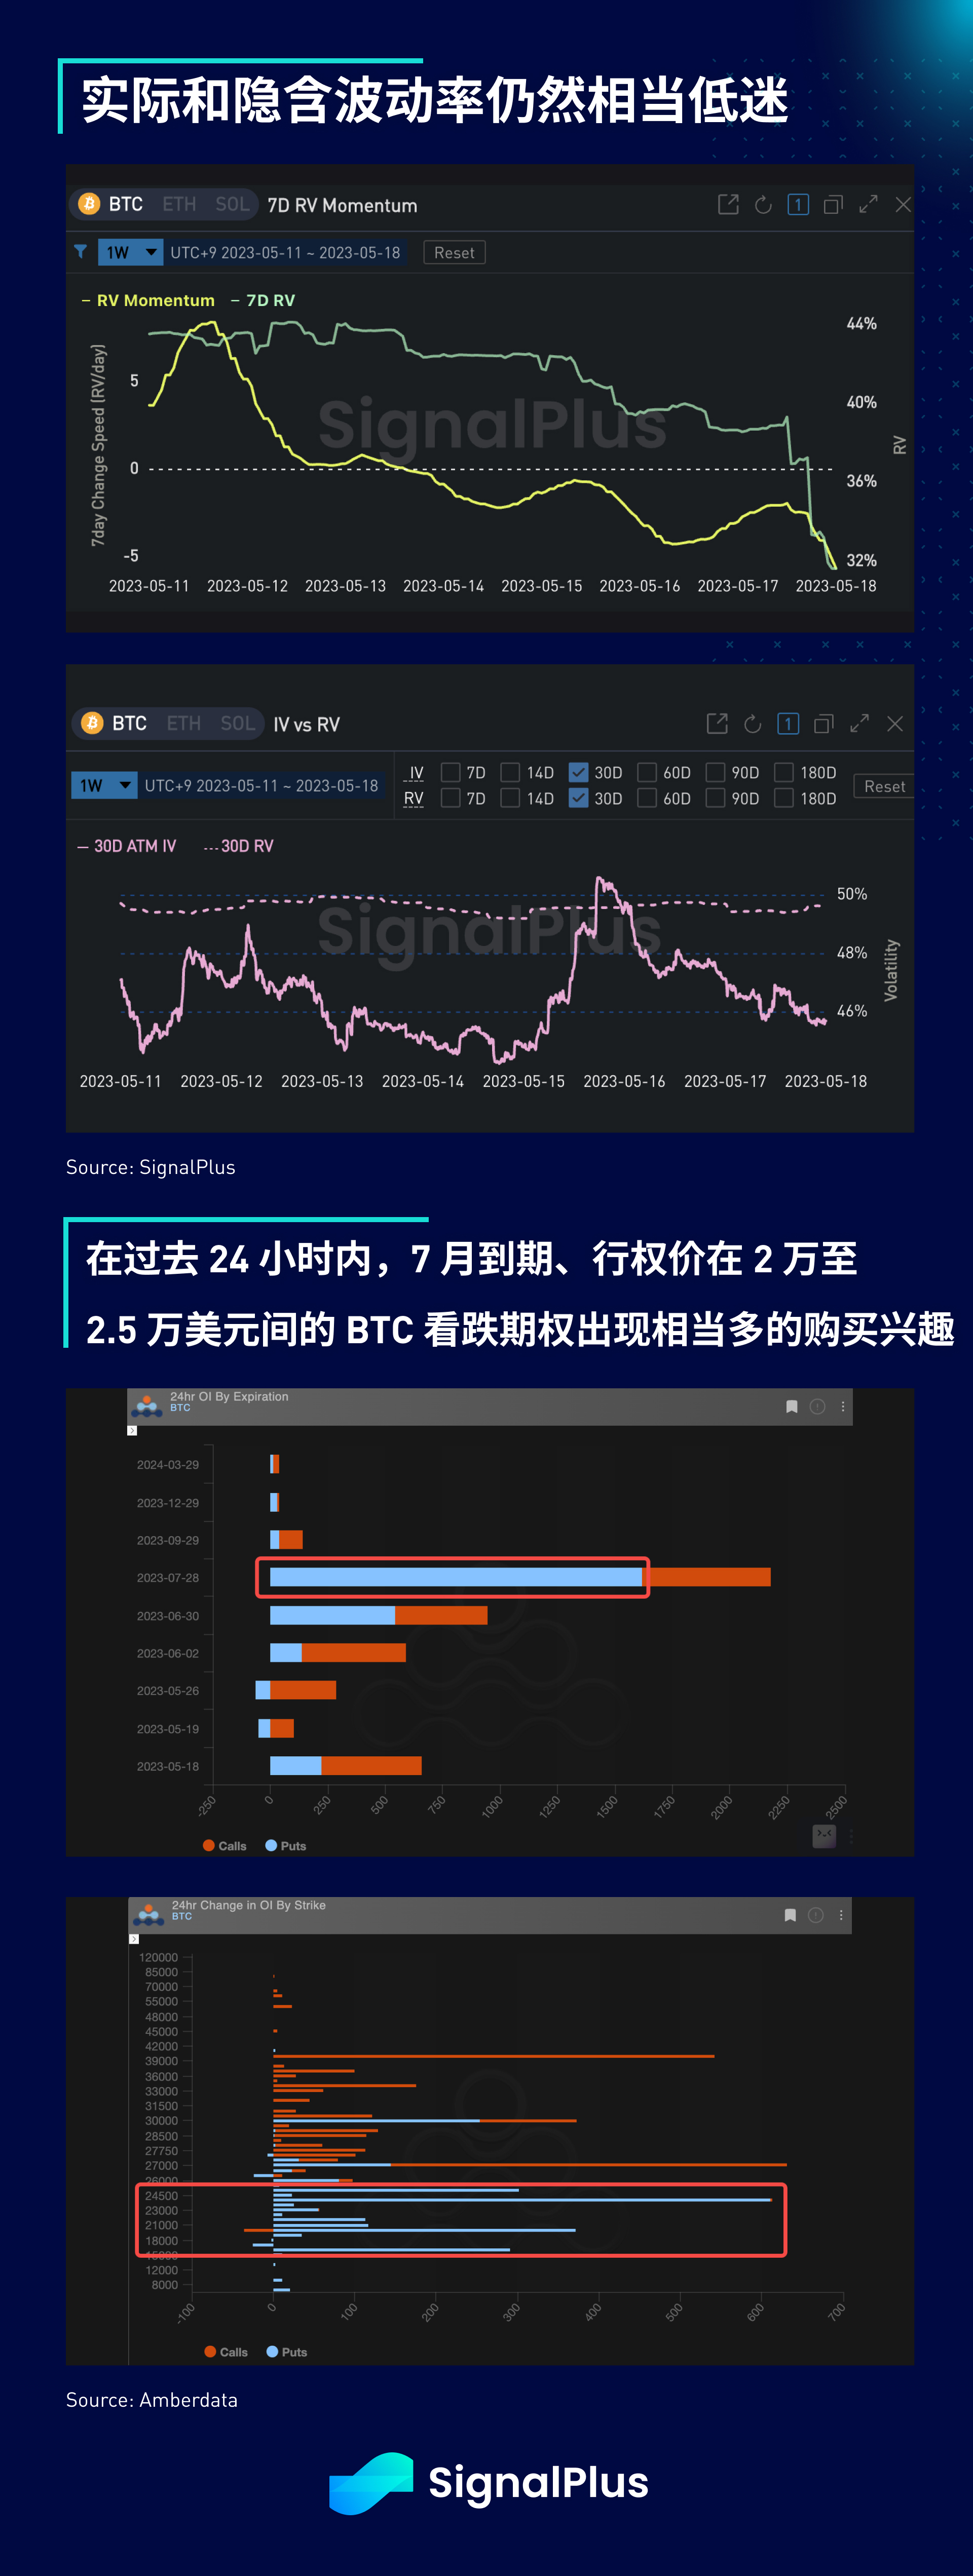
Unlike the rise in the stock market, Bitcoin remained weak as gold fell below $2,000, and the potential drying up of liquidity from the debt ceiling agreement also weighed on prices. Additionally, the “native” macro fundamentals of cryptocurrencies still look poor, with stablecoin balances, market capitalization, NFT transactions, and active developer activity all in freefall. Volatility also remains fairly subdued, with BTC realized volatility and volatility momentum falling sharply, and implied volatility failing to rebound as realized volatility slumps. However, we agree with the fact that there has been quite a bit of buying in July puts in the $20,000 to $25,000 strike range over the past 24 hours, expecting lower resistance for the current price. Small.
If you want to receive our updates immediately, welcome to follow our Twitter account @SignalPlus_Web 3 , or join our WeChat group (add a small assistant WeChat: chillywzq), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Website: https://www.signalplus.com/





