






Exploring NFT-Native Solutions: Infrastructure and Opportunities for NFT MEV


Compilation of the original text: Deep Tide TechFlow
Compilation of the original text: Deep Tide TechFlow
TL;DR
The NFT market structure is very different from the FT market structure. In the NFT market, capital formation events (minting) are more frequent, secondary trading volumes are low, bid liquidity is challenging, and there are many off-chain order books.
Because of these differences, NFT MEVs are also different. In particular, there are fewer arbitrage opportunities and more MEV extracted during the minting process. We also identified several forms of MEV unique to the NFT market: floor price scanning and re-listing on bid walls (artificially creating arbitrage high volume), feature sniping, and extraction from inactive listings.
Think of the DeFi market as a more mature market and use it as a proxy for where NFTs might go. This helps illuminate the gaps that exist today and the infrastructure areas that can address these challenges. These opportunities include MEV-aware minting solutions, more open pricing data, dynamic on-chain order books, experimenting with new auction formats, and providing additional communication channels for traders.
At present, the value circulation around NFT usually occurs when it is initially minted, traded or lent on the secondary market. Both types of value circulation may have MEV, the economically inefficient cost extracted from users when transacting on-chain. How these MEVs are handled may impact the business model and beneficiaries of market activity — from traders to marketplaces, wallets, and creators.
However, MEV seems to be a little-known topic in the NFT space. In my opinion, this is because the structure of the NFT market is very different from DeFi. Importantly, these fundamental differences—including more primary activity, smaller token supply, and less secondary liquidity—affect the flow of value.
This article will attempt to shed light on some of the emerging MEV opportunities in the NFT market, how changing market dynamics impact these opportunities, and the infrastructure that can be built to take these factors into account.
State of the NFT market
Understanding the current structure of the NFT market is a useful basis for identifying how MEVs might behave in the market. The process starts with a user minting an NFT, which I call a capital formation event, analogous to an airdrop or release of a fungible token (by creating a new asset on-chain). However, there are at least three aspects to the difference between homogeneous and non-homogeneous markets:
Capital formation events are more frequent in non-homogeneous markets. This is because in a non-homogeneous market, minting a new NFT is often seen as creating a new work of art or collectible, and these are unique and scarce. Therefore, creators and collectors tend to create and acquire as many NFT works as possible.
For non-fungible markets, minting order can be important, as minting serial numbers can represent a financial value, such as a rare attribute or a status symbol.
The supply of non-fungible collectibles is usually much smaller. A collection might only have 10,000 NFTs minted, while fungible tokens typically launch with a supply of 1 billion or more. This may affect liquidity on the secondary market.
When users decide they no longer own their NFTs, they can sell them in marketplaces (such as the many supported by OpenSea, Blur, Reservoir). These orders are usually placed in an off-chain order book, where they wait until the order is fulfilled or canceled. For these off-chain order books, the actual on-chain activity has several touchpoints: first listing an order (i.e. setting listing approval), canceling an order, and fulfilling an order. Changing the listing price requires the seller's signature, but does not require additional gas fees. There are also some order books that run directly on-chain, such as Zora and Sudoswap.
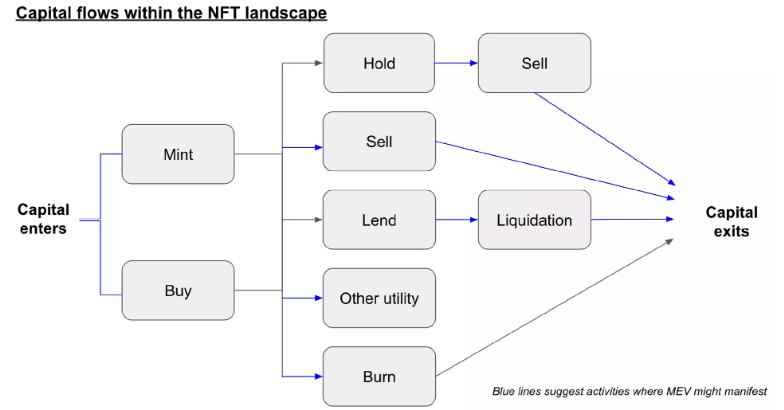
In addition to the primary market and secondary trading, it is worth noting that there is also an emerging NFT utility market. On-chain utility could involve staking NFTs for rewards, delegating to upcoming airdrops, burning (destroying) NFTs when using them as game assets, and more. But to put "emerging" in proper context: In February, primary and secondary market volume was close to $2 billion, while the NFT lending market was only a few hundred million dollars in borrowing. Markets for utilities other than lending are even more immature. Therefore, minting and trading will continue to be the focus of this article.
What are NFT MEVs?
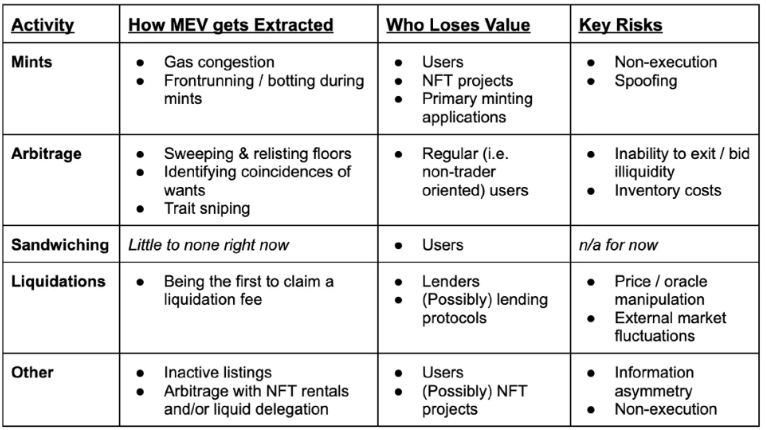
I define MEV as any form of inefficiency within a marketplace that causes transaction originators (users, wallets, applications) to leak value down the stack (searchers, block builders, validators). This is a broad definition, but broadness is helpful when considering different value capture and/or value redistribution opportunities. Common forms of MEV include arbitrage, sandwich attacks, and liquidations.
arbitrage
Arbitrage and pinching typically require high volumes and deep liquidity as spreads are often tight and arbitrageurs want to get in and out of their positions quickly. NFT markets generally do not have these conditions. Additionally, there are liquidity challenges in the market: oftentimes, there are no ready buyers on the other side of each listing. This means that even if someone spots an arbitrage opportunity, exiting (i.e. relisting and selling) can be risky.
Some NFT-native forms of arbitrage, and the risks associated with them, are as follows:
Scan and relist floor prices for higher prices. Many traders claim to make a profit, taking advantage of a wall of bids that may sit above the floor price. In this case, traders are almost artificially creating the high volumes needed for arbitrage. The main risks involved with this type of arbitrage include high capital costs and inventory requirements.
Find coincidences that haven't been seen as similar needs. For example, someone lists their CryptoPunk red/blue glasses for 1 ETH, while someone else bids 2 ETH for any CryptoPunk with red/blue glasses. The searcher can step in and call Seaport's MATCH function to satisfy both orders and earn the difference as a tip (reward). This is a low-risk arbitrage opportunity for me, although not too often. Here, non-execution is the main risk for searchers.
Trait sniping is a unique form of arbitrage in NFT "non-homogeneous" components. If someone sees an NFT with a certain trait being traded for X, but knows that other NFTs with the same trait are traded for X+Y, they can buy it and relist it for a higher value. MEV is achieved if Seekers pay a large amount of gas to ensure their bids are processed first. In this case, the searcher faces the risk of exiting: there may not be a bid waiting on the other side of their list. Therefore, the searcher must take the risk of holding inventory for an unknown period and accept the risk of long-term fluctuations in the characteristic price.
sandwich attack
Right now, there doesn't seem to be much of a sandwich attack in the NFT market. This is partly because most NFTs do not dynamically reprice when the available supply changes.
In a homogeneous market, large orders will affect the market. For NFTs, buying 10% of floor price NFTs will not directly change the pricing of other floor price NFTs.
NFTs are usually priced individually rather than aggregated. It is worth noting that some dynamic pricing infrastructure (such as NFT automated market maker "Uniswap for NFTs" Sudoswap) is emerging. Sudoswap solves the NFT liquidity problem by ensuring that there are at least some bids for pooled NFTs. The trade-off is that dynamic, automated pricing also expands the surface area for sandwich attacks.
Liquidate MEVs
Another common form of MEV exists in the lending market, called "clearing MEV" - where searchers profit by being the first to find it and earning a clearing fee. More and more lending transactions are being built on-chain (e.g. directly housing liquidation engines on protocols like Seaport), with a falling price auction mechanism that triggers liquidation when the price crosses the reserve collateral price. I imagine there will be a group of searchers dedicated to manipulating floor prices/certain NFT collateral prices so that they can pre-empt or control when NFTs are liquidated.
Other types of NFTs
May include:
Congestion during casting. Hot minting can cause users to pay millions of dollars in gas fees: this is the value created by NFT projects, but ultimately extracted by validators.
Robots are used in the casting process. Seekers can discover the first minting transaction in the mempool, check the supply of tokens that will be minted, and pre-bid some or all of the remaining minting.
Accidentally leaving untraded orders (commonly known as an inactive list). Because canceling an order incurs a fee, sometimes users will simply transfer the NFT to a new wallet to end the order. The tricky part is that this technically preserves the original order — which would reappear if that person re-transfers the NFT back to the original wallet. By that time, the floor price may have risen above the original pending order, and a wise third party can snatch up the undervalued NFT. MEV is generated due to the possibility of a searcher bribing validators with high gas fees to ensure that their bids for the listing are given priority.
Arbitrage related to NFT leasing. We see a trend towards untethering NFT rights/utility from the asset itself. In other words, the AirBnb of NFTs is emerging: Own the asset (the house) but have someone else pay for temporary use/enjoy the benefits the owner normally enjoys. This liquid order is especially useful for arbitrage related to airdrops - the right to buy a large number of NFTs (rather than trying to buy the NFT itself) in anticipation of the airdrop requires less capital, limits floor price spikes, and provides an opportunity to capture airdrop supply important part of . If we start to see higher eligibility requirements for airdrops (as we have already seen in homogenized markets), then those who hold these NFTs may have asymmetric information about the likely size of their NFT claimable airdrops .
Finally, there are probably more forms of NFT MEV that I didn't mention, including counterfeiting, inefficiencies related to burn and redeem functions, and pre-bid minting (just one of them). This list is meant to be creative and inspiring, hopefully sparking ideas/projects related to slashing or seizing NFT MEV opportunities.
infrastructure opportunities
Based on the current state of the market and where MEVs specifically exist, the following may offer interesting opportunities to build NFT-native infrastructure.
MEV-aware foundry solutions. In particular, auctions built for NFTs could help projects capture more of the value they are creating: having users bid for minting access and order could provide a way to help projects differentiate pricing while mitigating high gas prices. If the order itself happens off-chain or pre-minted, projects can spread the minting process over several days or choose other times when there is less on-chain activity.
Enhanced pricing infrastructure. This could take various forms - better data showing how traits are priced (e.g. helping searchers identify trait sniping opportunities), dynamic pricing mechanisms like Sudoswap to help aggregate rather than price NFTs individually, continuous auctions to improve prices Discovery, or some other form.
Build infrastructure to reduce exit (liquidity) risk. I generally believe that NFT pricing is difficult, so fewer people are willing to bid. Bargaining mechanisms might be one way to help. If a user lists their NFT as 2 ETH, and a buyer bids 1 ETH, there may be some middle price. Having a negotiation channel increases overall liquidity while advancing a better understanding of how to price NFTs. In fact, there may be significant overlap between this category and the above (pricing infrastructure).
epilogue
epilogue
Looking ahead, I firmly believe that we will see more developments around NFTs. The current situation is that most NFTs are heterogeneous and therefore difficult to serve as substitutes. Shared features or floor price tokens are closer to alternatives, but consumer preferences may still vary.
In contrast, NFTs serve as field passes for golf events - in this case heterogeneity may exist as certain characteristics (such as dates) cause differences in preferences, but in general they serve as approximate Substitutes, as consumers will differentiate between tickets on a given day (assuming all tickets provide equal access to the event).
As the spectrum develops and NFTs start to represent everything from on-chain art to tickets, affiliate links, IP licenses, title certificates, and more, I think we'll see more MEVs emerge.
Overall, it feels like we're still in the early days of NFTs.
I like thinking about NFTs because I think they are an excellent way to introduce exogenous capital into the crypto ecosystem, and I think the design space is completely open. But in the early stages of any market, there will always be some inefficiencies.
I hope that exploring how MEVs exist across the market—and what opportunities this exploration presents for building more enjoyable user experiences—will help pave the way for wider adoption.





