






SignalPlus Daily Morning News (20230306)


Dear friends, welcome to SignalPlus Daily Morning News. SignalPlus Morning News updates macro market information for you every day, and shares our observations and opinions on macro trends. Welcome to track and subscribe, and follow the latest market trends with us.
Dear friends, welcome to SignalPlus Daily Morning News. SignalPlus Morning News updates macro market information for you every day, and shares our observations and opinions on macro trends. Welcome to track and subscribe, and follow the latest market trends with us.
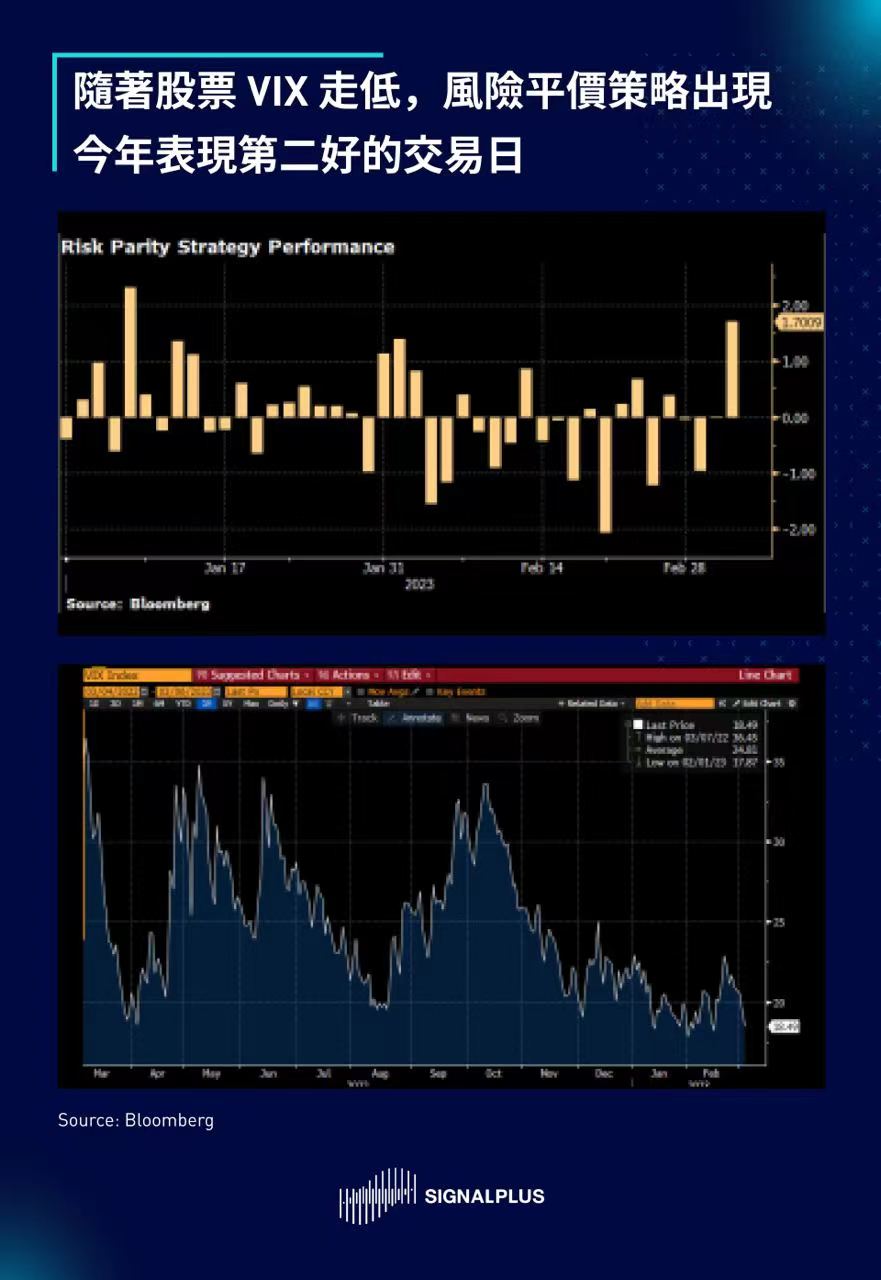
The risk market ended last week with a sharp rebound across the board. The S&P 500 closed above 4050 points, the 10-year U.S. bond yield was about 3.95%, the 5-year investment-grade CDS fell at about 70 basis points, and crude oil futures were close to $80 /barrel, almost completely recouping a week's losses and forming a technical reversal pattern in just 12 hours. The risk-parity strategy had its second-best session of the year, rising as much as 1.7% on a single day, as the stock VIX fell near record lows again.
The U.S. economic data continued to show that the economy is very strong. The ISM non-manufacturing index remained stable at 55.1, well above the 50 line of expansion and contraction. Among them, the employment item index rose to 54, and new orders rose to 62.6, the highest since November 2021 However, prices paid fell to 65.6, the lowest level since January 2021. The U.S. S&P global services PMI index was 50.6, falling in the expansion range, breaking the contraction for seven consecutive months, with employment and output expected to rise to a six-month high.
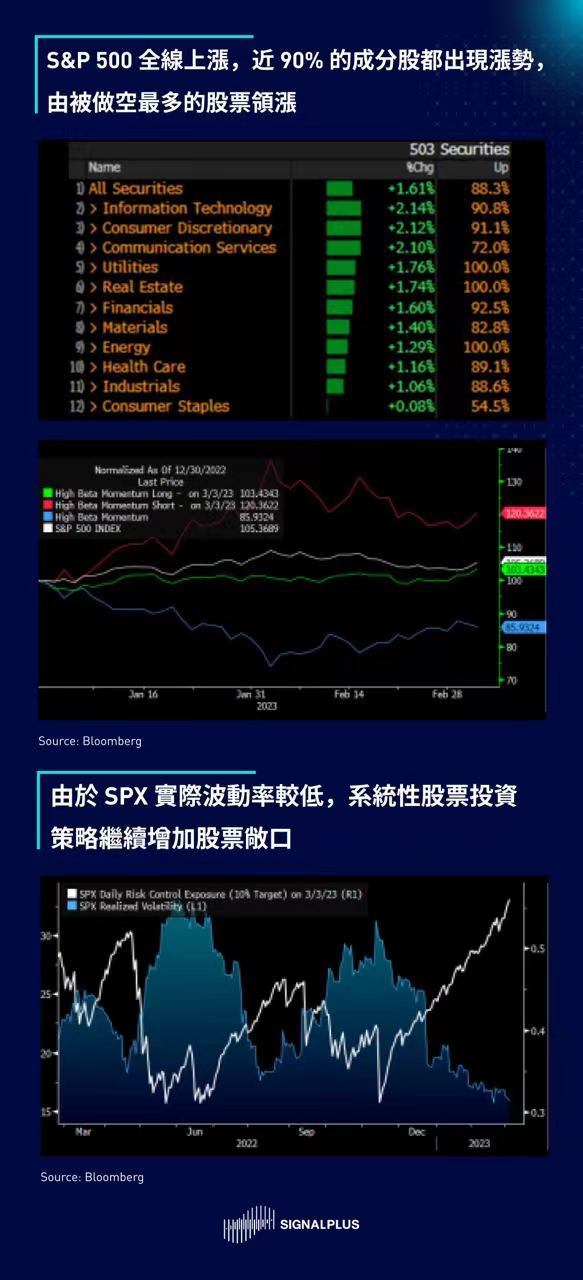
Economic growth data is still quite positive, terminal interest rate pricing has risen to a reasonable 5.45% or so, coupled with traders being aggressively short all week, the stock market has an old-school short squeeze, and nearly 90% of the S&P 500 constituent stocks are up , each sector showed an upward trend. Unsurprisingly, the rally was led by the most shorted stocks, while low realized volatility has enticed systematic equity strategies to continue increasing their long exposure to equities.
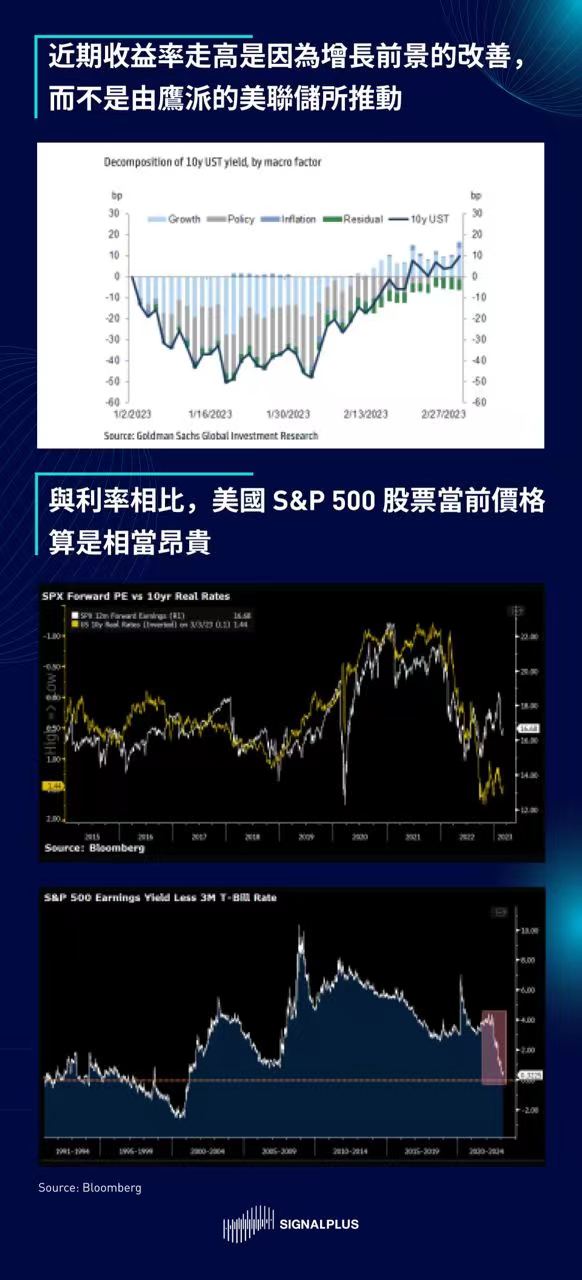
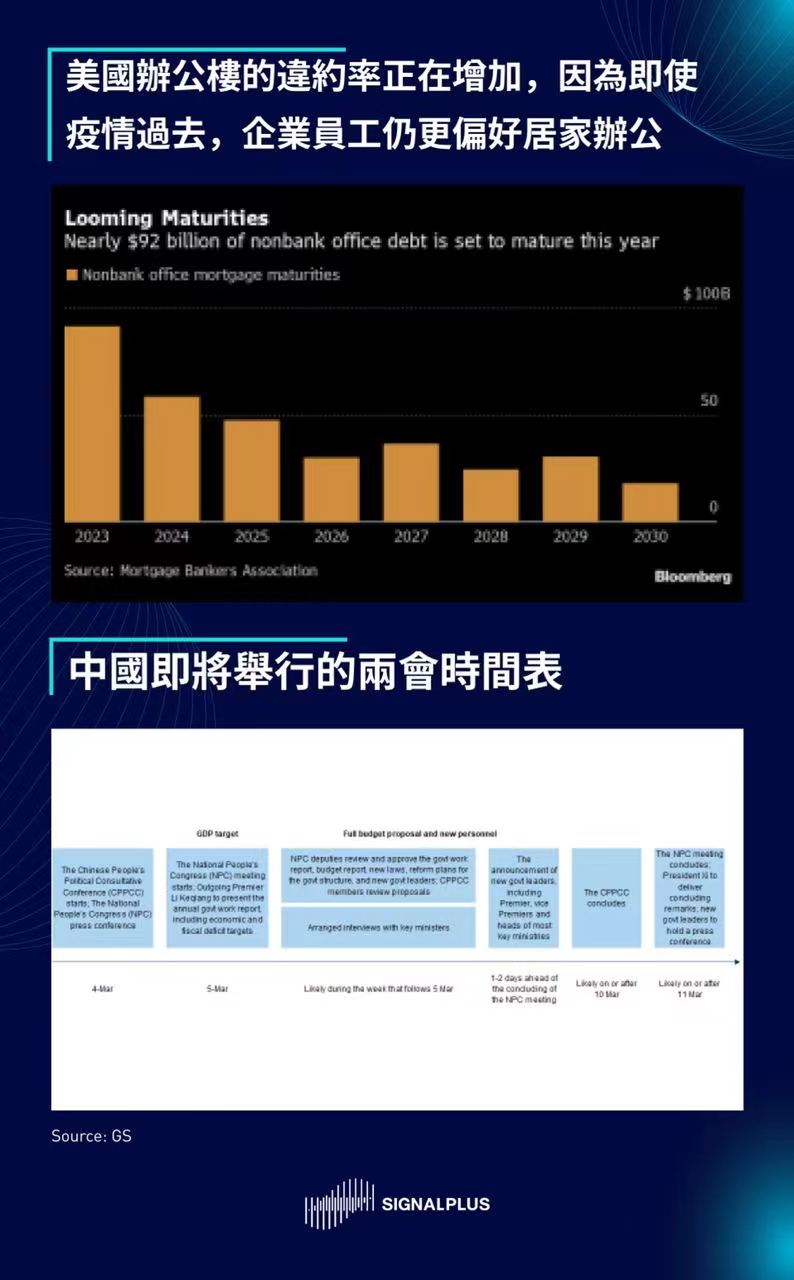
While there were a lot of "fundamental" reasons to be bearish for the market last week (increasing inflation, rising US office defaults, rising auto loans, poor investor days for Goldman Sachs and Tesla, etc.), we saw more Before the results of important economic data, capital flows and market positions will continue to dominate price changes. The week starts with more important data releases and other macro events including the JOLs, ADP, non-farm payrolls and Powell's testimony before Congress on Tuesday, as well as China's annual National People's Congress this week, as well as Japan, Canada and Australia The interest rate decision will also be a busy week on the policy front.
From a valuation standpoint, the SPX is currently trading at levels seen in early May 2022, when the terminal fed funds rate was priced at 3% (5.45% today), and forward earnings estimates were largely flat around $225, implying A 245bp increase in the fed funds rate and a 100bp rise in 10-year yields had no effect on US equity prices, suggesting that the SPX is now much more expensive than it is in H1 2022. In addition, factor analysis shows that the rise in U.S. bond yields is due to a reasonable reflection of an improving growth outlook, rather than being driven by an overly hawkish Fed. Another upside surprise and further gains in yields are not out of the question.
A senior mentor used to say, "You pay price, you get value" and we should all take it to heart as risk free deposit rates will soon exceed 5% for any investment strategy It is not easy to exceed the 5% compensation threshold in the long-term and sustainably.
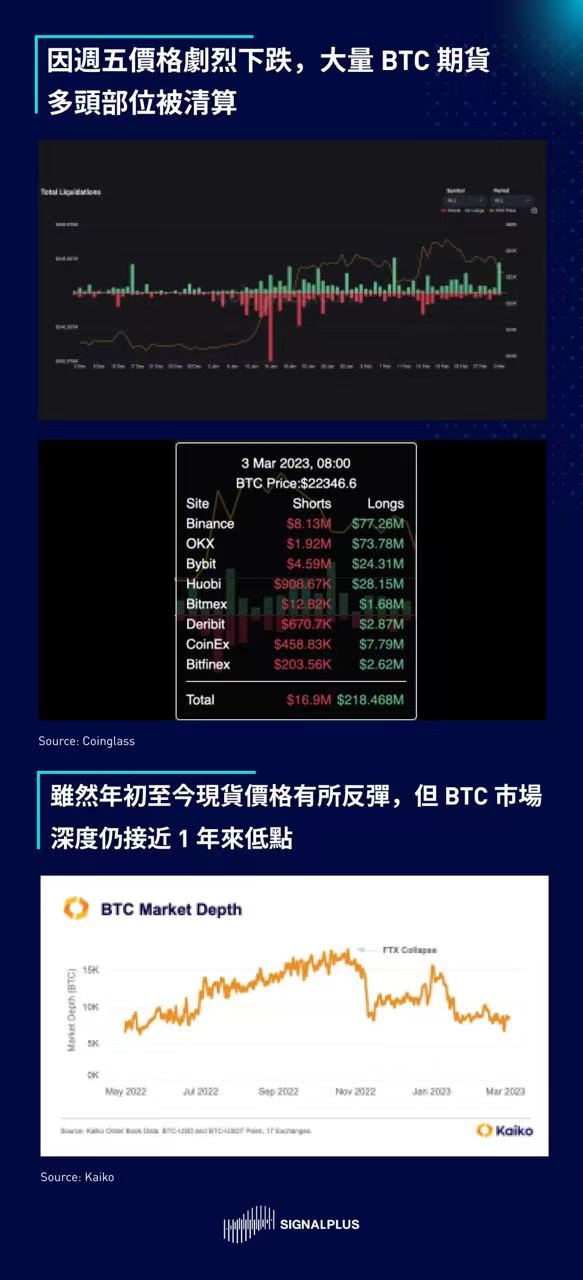
In terms of cryptocurrencies, the fortunes reversed, and the price of the currency fell sharply. Both BTC/ETH plummeted by 5%, and about 220 million US dollars of futures long positions were liquidated. While it's hard to attribute the decline to any single factor, it's hard to ignore that the fundamentals of the market this year remain shaky (lack of volume and open interest, lack of depth in secondary markets, sharp drop in stablecoin balances, lack of institutional participation, Insufficient liquidity in the volatility market), there are still many structural resistance ahead.
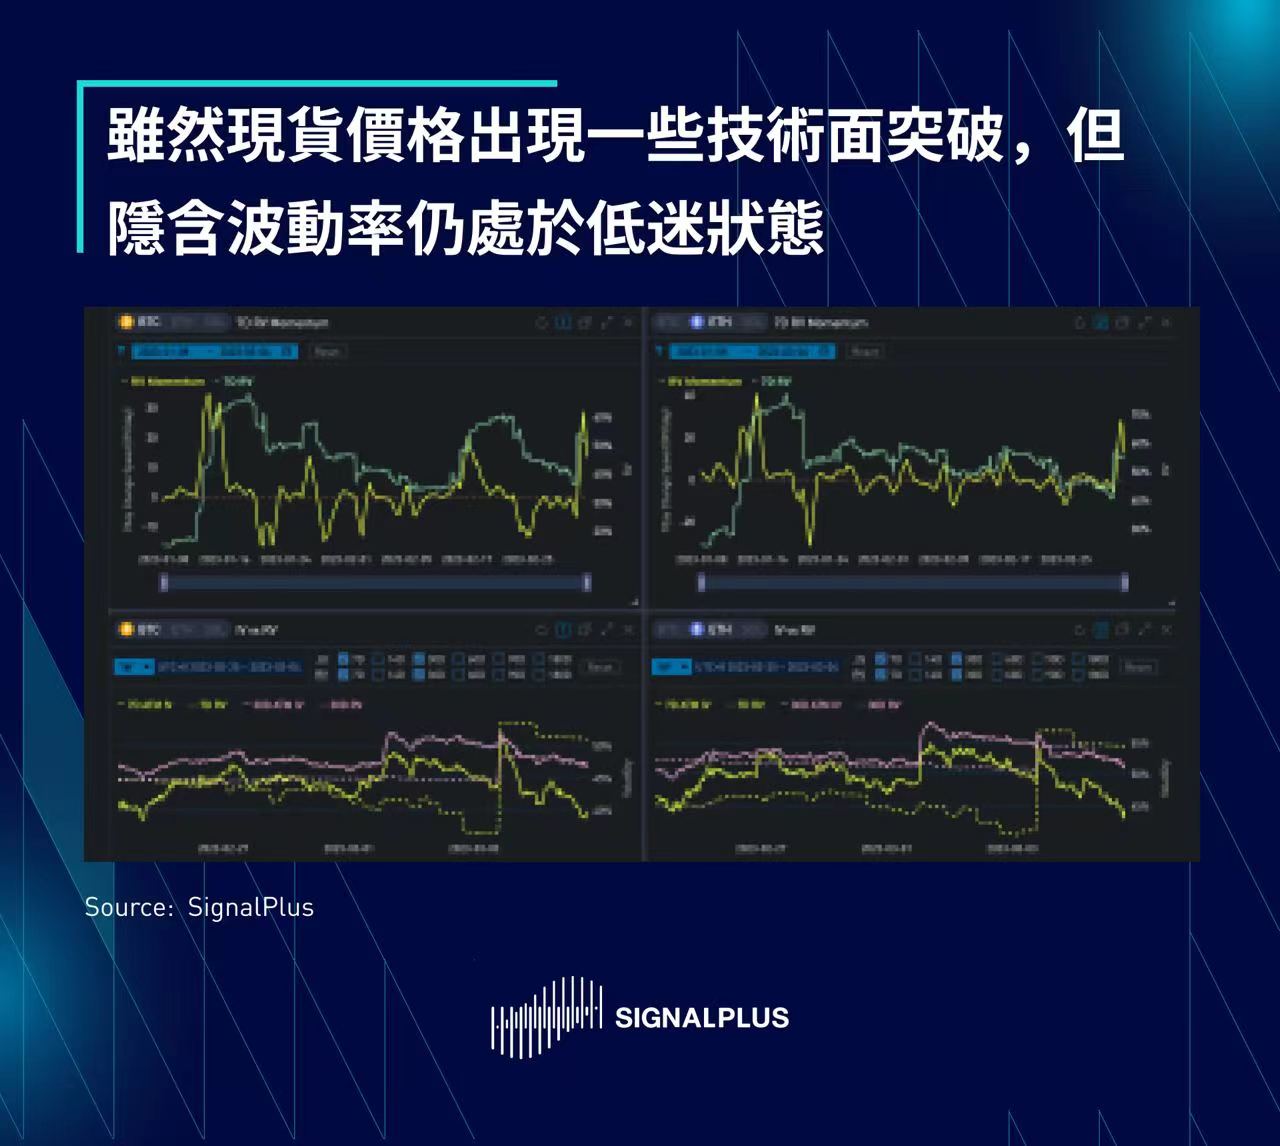
With TradFi heading into a busy week, we expect risk sentiment to be volatile and upside for cryptocurrencies may be limited. Implied volatility is still subdued, but from a technical point of view, the price has the opportunity to move lower, we have not seen any obvious positive factors that have the opportunity to push the market price higher in the short term, take some action in the next few weeks Strategies for market downturns may be good options
If you want to receive our updates immediately, welcome to follow our Twitter account @SignalPlus_Web 3 , or join our WeChat group (add a small assistant WeChat: chillywzq), Telegram group and Discord community to communicate and interact with more friends.
SignalPlus Official Links:
Website: https://www. signalplus. com/





