






NFT Market Development and Royalty War


Original title: The Royalty Wars
Original source: Decentralised.co
Original Author: Joel & Siddharth
Original compilation: Kxp, BlockBeats
When I think about our economy and society today, I often liken it to a vast biological system made up of interconnected actors such as workers, SMEs, banks, customers and regulators. Among them, each participant plays its own key role. When a business or employee is no longer beneficial to the system, it leaves the system due to competition, lack of resources, or self-interest. For example, if a rational actor believes that his investment is doomed to fail, he will choose to stop the loss immediately, which is to protect his own interests.
Of course, the parallels between markets and biological evolution are not a new concept. Adam Smith's economic writings, which inspired Darwin to become a naturalist and redefined modern biology, inspired me endlessly. I often imagine having discussions with both of them, delving into the parallels of market and ecosystem evolution. However, since time travel has not yet become a reality, I can only continue to use it as a beautiful fantasy in my spare time.
first level title
Early life
It was the Crypto winter of 2019, and the bear market made most people lose interest in Crypto, and even the girl you matched on Bumble was no longer interested in your Bitcoin. Decentralized finance (DeFi) was just a group of financial geeks discussing in a hidden corner of the Internet at the time. People were keen to use their "useless" Tokens to obtain Internet loans. At that time, the most common type of NFT was the Simple Agreement for Token in the Future (SAFT). For venture capitalists, this was an investment contract for them to obtain more Token in the future.
However, most founders postponed their token issuance, and venture capitalists pretended to continue to support the founders while looking for buyers to purchase their token agreements. The only NFT collectible series most people know of is a cat-themed series NFT that repeatedly clogs the Ethereum network. The consultants who tried to bring new use cases to businesses and authorities are now gone, people no longer believe that using a blockchain to store land records is a good idea, and a decentralized version of Uber for rides just didn't materialize.
Cryptokitties were one of the earliest NFT primitives that captured public pysche. Source : Quartz
The NFT market faced major challenges in 2019. Although Token became popular due to the ICO craze in 2017, users have become accustomed to transferring, trading, and even losing their Crypto in cyber attacks. In contrast, NFTs have not been widely adopted, only a small group of people in Silicon Valley are discussing them, and even avid Crypto enthusiasts have not paid much attention to these non-fungible assets.
In the real world, artists can only sell their works once and earn one income, so they must continue to produce works to make a living; on the other hand, NFT transforms art into financial assets, and every time someone trades artwork , it will create value for creators.
How is this done? Royalty is key to its operation. Below I will use an example to explain to those who are not familiar with the NFT market: Let's say you buy a pizza painting from someone for $100, and the artist gets $100 from this sale . Now, by some chance, a hedge fund manager comes to your office the next day and decides to bid up the price of the pizza painting to $1,000. You sold it to this manager for a $900 profit. Unfortunately, the artist was not compensated for this sale.
If the next day, a friend of the hedge fund manager (who just happens to be good at speculative Crypto investing) notices the artwork, thinks it's worth $1 million, and buys it, neither the artist nor you get any compensate. While you may regret underestimating your assets, regret alone won't help.
Royalty is a percentage of income an artist receives from each sale of his work, usually between 3% and 5%. When tens of thousands of NFTs are released for a new collectible series, the amount of royalties can be substantial enough to support an entire team. Due to speculation, these NFT assets may be traded hundreds of times a day, similar to the stock market. The aforementioned pizza painting artist would have made $50,000 on the million-dollar deal had he minted his creations into NFTs that would bring in creator royalties.
Before you decide this is a classic Ponzi scheme, consider that only the artist earns royalties from the sale of his art, and the intermediary dealer earns only the difference in the price of the asset. While this seems like a good example of the Boss theory, I should be stretching it too far.
Such incentives have played a major role in driving the NFT market over the past few years, bringing in hundreds of millions of dollars. In fact, Yuga Labs, creator of the Bored Ape Yacht Club, raked in $107 million in revenue last year alone.
image description
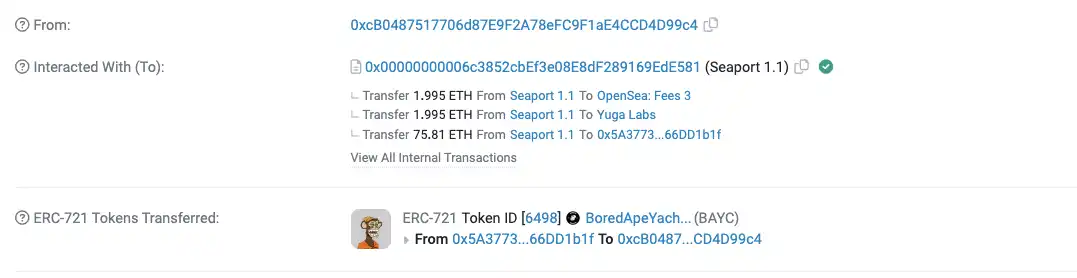
Image source: Etherscan
As you can see from the fee breakdown above, OpenSea made about 2 ETH, while Yuga Labs made about the same amount by selling the Bored Ape NFT for almost 80 ETH. In my opinion, this recurring income should not be underestimated by anyone. Buyers willing to pay $140,000 for a picture of an ape may not be buying just for its artistic value; rather, they are more likely to be looking to make a profit, or to speculate on its potential value. They want to use today's consumption to obtain higher income in the future, so as to achieve a win-win situation for all parties. However, this could change if the market changes.
OpenSea introduces the concept that NFTs can enforce royalties and empower creators, which has a lot of appeal for everyone, and we see nothing against it. The problem, however, is that NFTs cannot transfer royalties to end users on their own.
Typically, royalties are passed through smart contracts created by marketplace platforms such as OpenSea. The reason for this is that it is difficult to discern a simple assignment from a transaction. If users are being charged a 5% fee on every transfer, they will no longer want to move their precious NFTs to cold wallets. As such, royalties are generally collected by the marketplace platform that facilitates the transaction.
first level title
market star
In 2022, driven by sufficient liquidity and incentive fees, the NFT market has undergone major changes and explored many new models. It all started in January when LooksRare released its token with a simple value proposition that users who get the token can use it to transact on the platform.
Users of LooksRare can use Token to manage the platform and earn benefits as Token holders instead of spending money on brand building, advertising and educating users. Additionally, the token has a liquid market. I was before《Token Market Platform》The game theory of the platform is analyzed in this article.
“Every trader on the platform needs to pay the artist a platform fee of 2% and a royalty of 5-10%. Fake traders can use these mechanisms to acquire assets at discounted prices in the spot market. If the platform fee and royalties paid And the reward price is greater than Token, users have no incentive to continue trading on the platform. LooksRare generated about 11 billion US dollars in transaction volume and 220 million US dollars in revenue, although they are only a small fraction of OpenSea users.”
At that time, LooksRare gained a lot of attention due to its highly liquid Token, while OpenSea failed to do so. Despite a poor initial product (limited ability to sort NFTs by price), LooksRare has gained traction. However, due to the arrival of the bear market and the decline of Token rewards, it is difficult for this product to compete with OpenSea this year.
Perhaps recognizing the potential threat to the company's dominance from new-age platforms, OpenSea's management acquired Gem a few months later. As of the acquisition, Gem was one of the fastest growing deal aggregators in the market.
At this time, the market has made many attempts with Token. It is well known that using tokens as an incentive to transact on the platform can help improve metrics. However, we still have another aspect to explore: creator royalties. During this year, several exchanges began to gradually reduce the percentage of creators’ promotion points.
DeFi markets offer tools to explore this idea, such as SudoSwap, which makes it possible to build Uniswap-like NFT pools. Users can buy or sell large quantities of specific NFTs by trading them in the pool. In order to compete with major players such as OpenSea, the platform's cut is reduced to 0.5%.
Assuming you are a trader interested in buying Bored Ape NFTs, if you can cancel the 2 ETH paid to the creator and reduce the 2 ETH paid to the platform, other traders may therefore move to your platform.
And that's exactly what happens in reality.
On certain markets outside of OpenSea, the purchase price of NFTs can be reduced by 5%, resulting in significant cost savings. Suddenly, the traditional royalty model of empowering artists began to fall apart, and the previous vision and narrative no longer existed.
Despite the disruption caused by low-priced NFT market platforms, OpenSea, the dominant player in the NFT world, has not been significantly affected. A few hundred traders and their small trades pose little threat, and most of them are fake trades. Financial incentives are the main drivers of trading activity on OpenSea. One might think that as incentives are reduced, transaction activity for new competitors such as X2Y2 will also decrease. However, in October 2022, the industry is about to face a formidable opponent - a new player is about to enter the market with a superior product tailored for traders, and it is Blur.
Blur has been optimized in several ways, including:
1. Provide users with the possibility of airdrops to increase the liquidity of buyers and sellers, which closely corresponds to the settlement price of NFT and ETH, attracting traders to flock to it.
2. Focus on professional NFT traders rather than retail traders, and provide several advanced trading options that traditional platforms cannot provide, similar to turning from an altcoin spot market to a comprehensive set of trading products, satisfying all professional trading requirements.
3. Integrate a series of charting and data functions into its core product, similar to what Gem did at launch, allowing traders to obtain historical pricing, book depth, rarity and general volume trends, etc. through the same platform they trade information.
While you might think these improvements are insignificant, the strategy of playing around with tokens and building great products has allowed Blur to achieve about 40% of weekly NFT transactions on the Ethereum network. As of February 2023, Blur accounted for approximately 77% of transaction volume, compared to 16% for OpenSea during the same period.
image description
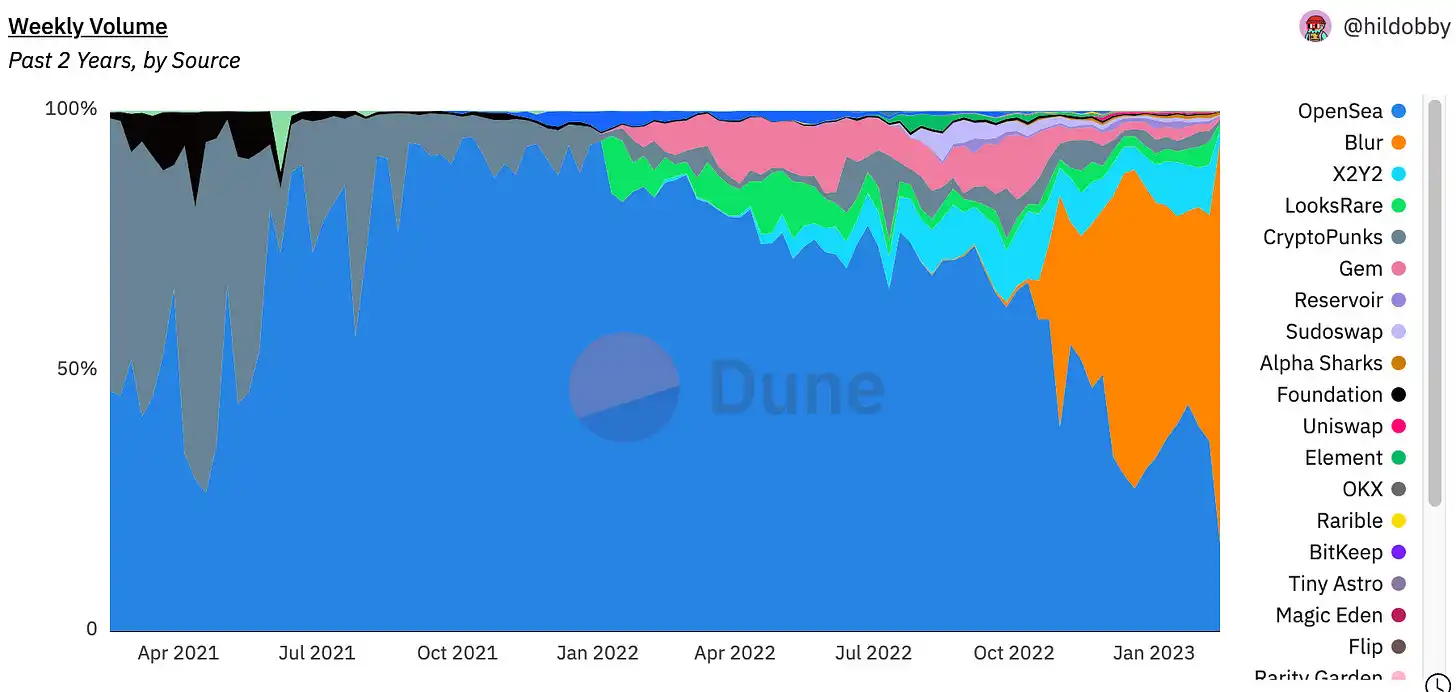
Data from @hildobby's profile on Dune.xyz
In one quarter, Blur accomplished two important things. First, it erases the need for royalties for a short period of time, and traders have become more and more accustomed to not paying creators royalties in market transactions. Paying creators royalties on every transaction doesn't seem reasonable when you just want to speculate. Second, Blur has eliminated its royalty program entirely, with no royalties at all on the platform until December 2022. After that though, they switched to a 0.5% royalty model.
To understand Blur's long-term impact, it's worth looking at how royalties have changed. A user named Beetle created aDune Dashboard . Beetle defines the Effective Royalty Rate (ERR) as "the total royalties earned across all marketplaces divided by the total volume traded across all marketplaces." Since marketplaces like Blur were initially launched with no royalties, an increase in transaction volume coupled with a decrease in royalties would lead to a downward trend in ERR - which is exactly what is happening now.
image description
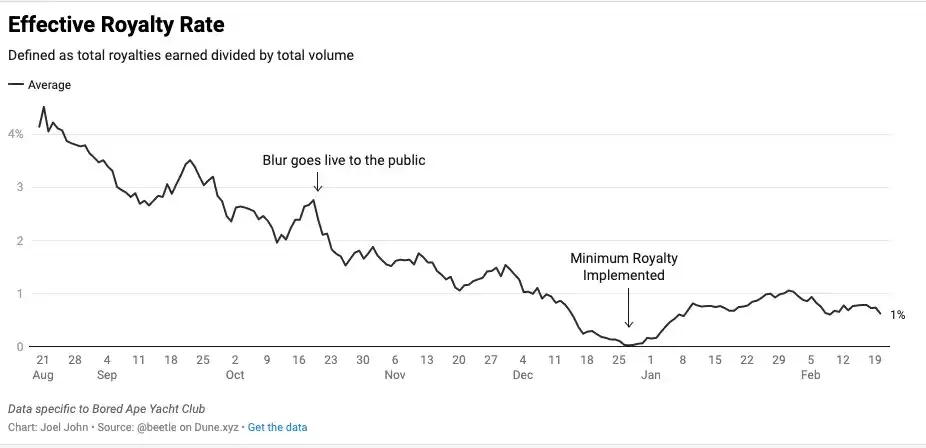
Data from 1 kBeetleJuice
first level title
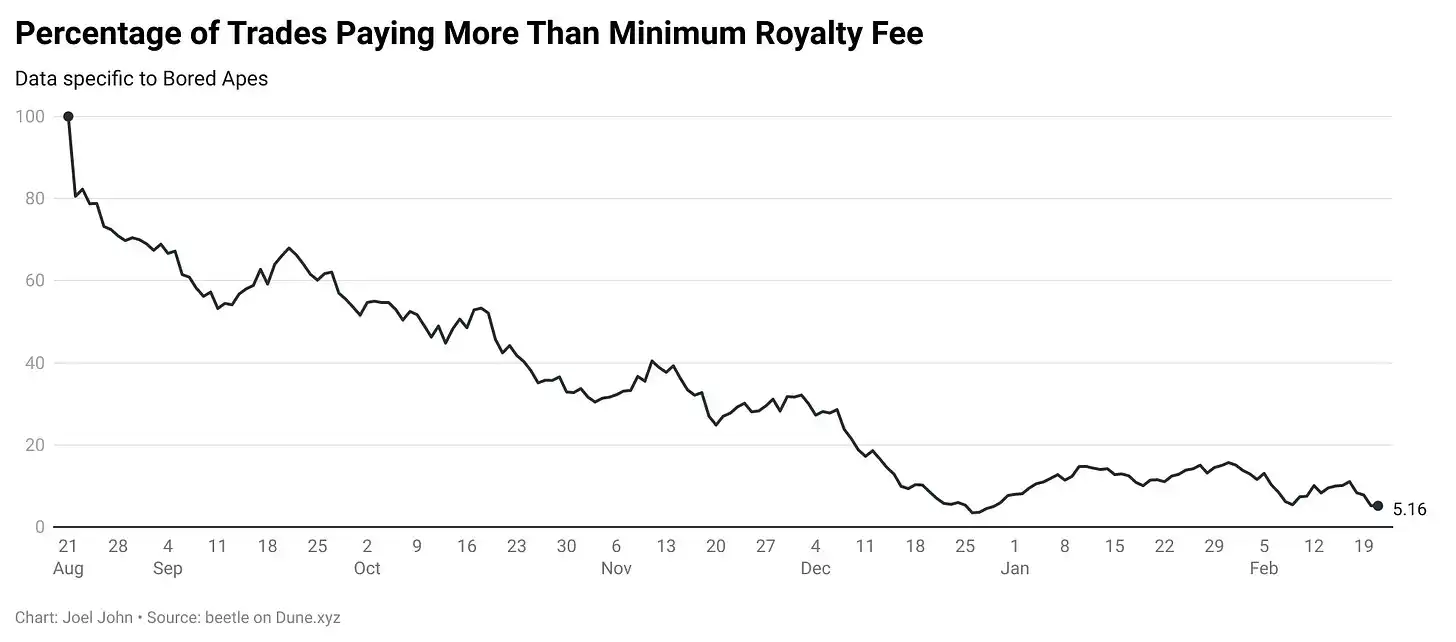
royalty evolution
Those involved in the NFT ecosystem are in the midst of a major upheaval right now. A new player enters the market, takes away your users and transaction volume, and upends your business model. Several NFT marketplace platforms briefly took a commendable stance, guaranteeing creators income.
OpenSea maintains an operator filter registry, and platforms such as Blur are included if they allow users to avoid paying creator royalties for the same item on OpenSea.
image description
We might need to hire someone to make better mysteries
Despite the turmoil, OpenSea is not a helpless bystander. In fact, the platform launched a full protocol and acquired an aggregator to cater to the market. Seaport, launched by OpenSea in May 2022, is a pure market contract, similar to DeFi's 0x. It functions as a communication protocol for finding liquidity and routing orders across markets. In Web2 terms, this is equivalent to an API for listing the same item on eBay, Amazon, and other regional e-commerce platforms.
Why does a market platform like OpenSea publish a protocol? This is how they want to create more avenues for more people to join the NFT market. If the whole market develops and OpenSea remains the largest market platform, they will get more users.
However, this decision had unintended consequences for OpenSea. Previously, creators could easily blacklist Blur; now, whenever a collectible series bans Blur, Blur provides liquidity for that asset through OpenSea's protocol. Also, we basically have no way to prevent Blur from entering the protocol and finding liquidity for this asset. Twitter user PandaJackson ata tweetimage description
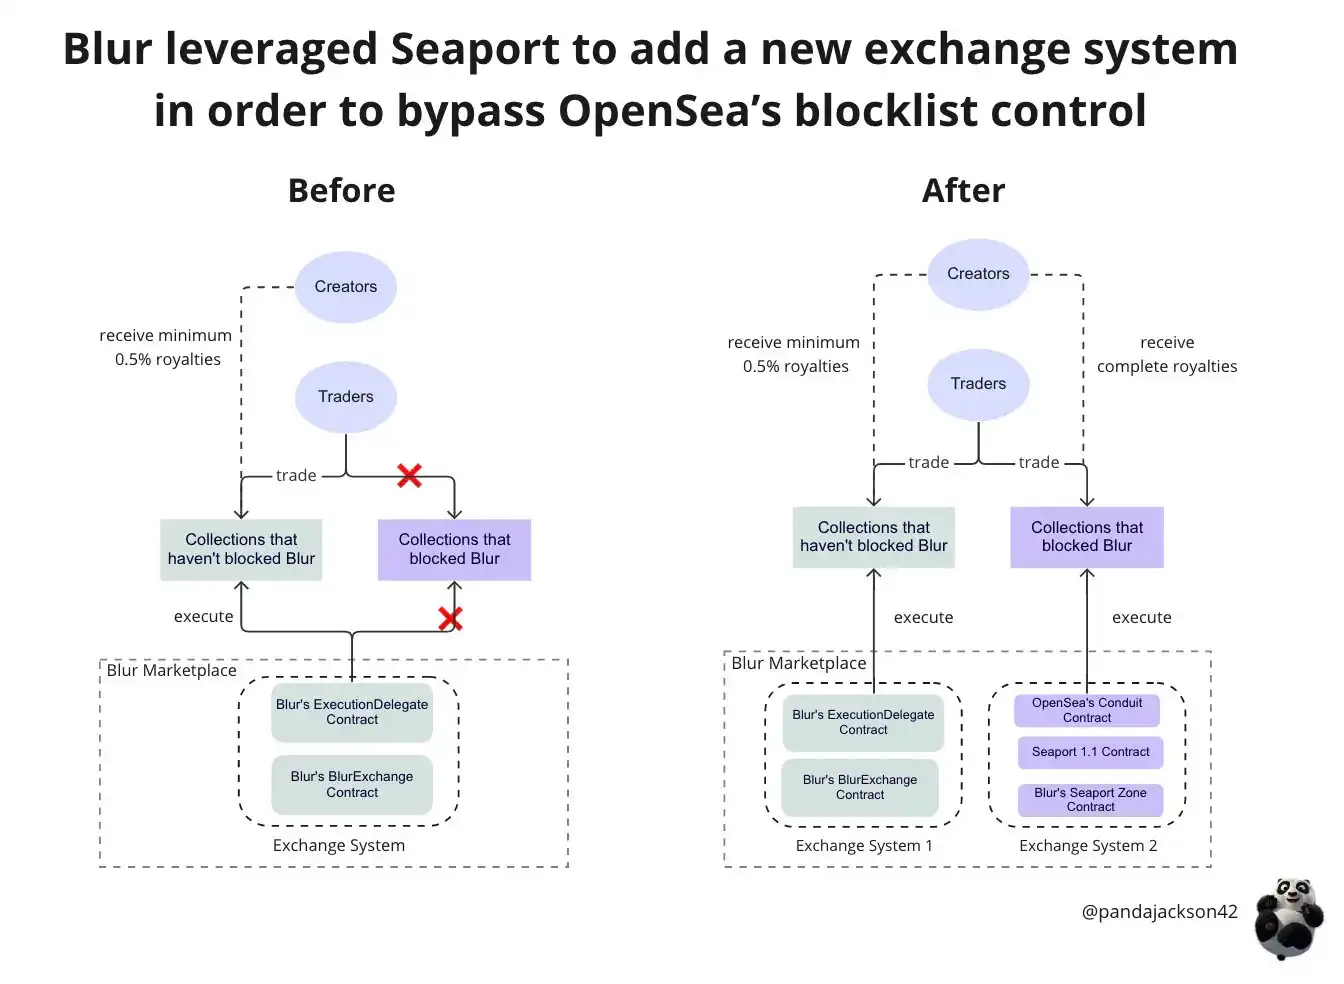
PandaJackson has some great tweets, be sure to follow him
Blur completed more than 4,000 transactions of Sewer Passes without paying OpenSea a fee of $220,000, resulting in a loss of approximately 40%. This use of Seaport to circumvent the Blocklist registry is a clear mockery of the mechanism. Even if OpenSea found a way to prevent Blur from querying Seaport for liquidity, that would defeat the reason why they introduced Seaport in the first place. (Also, OpenSea cannot modify Seaport on a whim)
image description
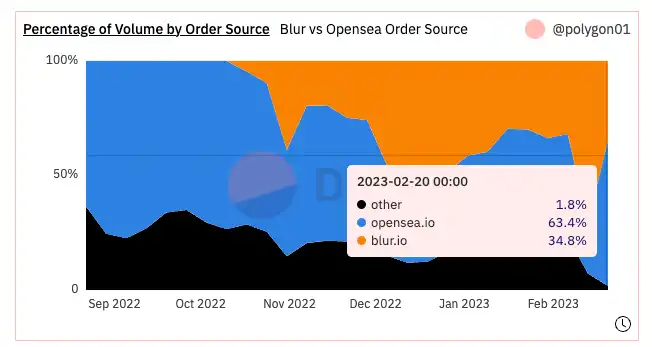
fromSeaLaunchimage description
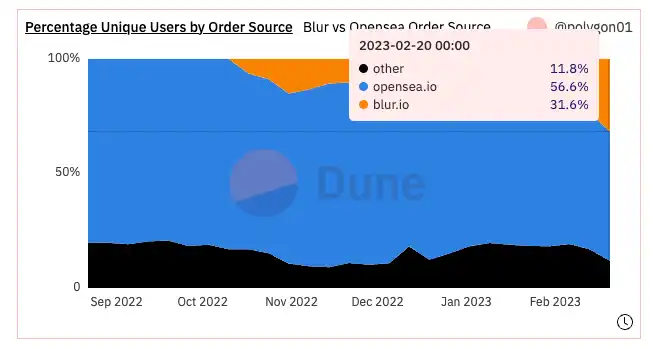
fromSeaLaunchA forked dashboard of
The first chart shows the percentage of trading volume by order origin, that is, which market platform the order originated from. As the chart shows, when Blur opens to the public in October 2022, it dominates nearly 60% of order sourcing. However, as of February 2023, it has dropped to about 21%. This shows that more and more users are using Blur's marketplace platform to place orders. Still, this is not a significant threat, as users can place orders through any aggregator, and liquidity can be sourced elsewhere.
From a B2C investor's perspective, Blur probably won't pose a significant threat to OpenSea. As the second graph shows, most independent users are still using OpenSea. As a new platform, Blur couldn't immediately replicate OpenSea's brand equity. The problem, however, is that Blur has transitioned from a platform for initiating orders to one where users can find liquidity within a quarter.
In the data shown below, Blur is the orange part, which accounted for 83% of the trade execution volume on February 19th. However, on February 20th, this value dropped to 26%, and the reason for this drop is that Blur's initial token had just ended its airdrop.
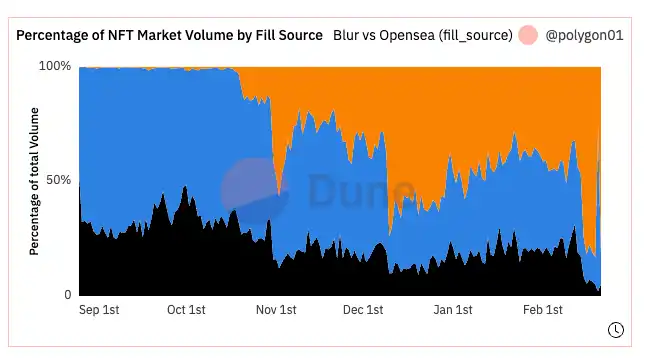
The chart above provides a clear breakdown of this fact. Wherein, the term "execution source" refers to the market from which the order is fulfilled. If your platform is an emerging aggregator, you may be able to fulfill orders, but orders may also be executed through third parties. When a platform has the ability to do most of the order matching itself, it becomes a marketplace in its own right. As of February 2023, only 16% of orders on Blur were fulfilled using liquidity on OpenSea.
Blur's transformation from an aggregator to a platform is at the heart of jeopardizing OpenSea's future. With the massive loss of market volume to third-party platforms, these marketplace platforms are no longer willing to maintain high fees. OpenSea has transitioned from publishing a registry, which blacklists marketplaces that fail to enforce creator royalties, to an optional royalty fee structure.
first level title
future development
A year ago, when we first discussed LooksRare, it was thought that the introduction of tokens could revolutionize the NFT market. The strategy seems simple: remove the commission and introduce tokens. This allows teams to profit from issuing tokens, rather than from any revenue they generate. Over the past year, however, the platform has seen a sharp drop in daily active users, down to around 200.
Blur posed an even bigger threat to the market because, at the time, it accounted for more than 70% of volume, compared to LooksRare's roughly 11%. OpenSea has gone from testing a registry to block marketplaces that don't offer fees, to minimizing its own platform's cuts, in response to the threat posed by Blur. At the same time, this also proves Blur's efforts from the side. What we are not sure, however, is whether Blur's transaction volume and users will remain at that level as the market develops.
Opinions are divided on this issue: Some argue that Blur makes a better product for traders, and that users will stay loyal. A great product plus the ability for users to "own the product" through Token will allow Blur to achieve amazing growth. But others believe that this may just be a blip and that OpenSea may regain its dominance in a few months, for the following reasons:
OpenSea has kept its fees to a minimum, so users who left for financial reasons may now consider coming back. Additionally, an OpenSea IPO may no longer be viable given the current state of the tech stock market. In this case, OpenSea can consider issuing Token.
Rather than tokenizing OpenSea itself, the company could explore tokenizing its assets, such as the aggregator Gem acquired a year ago.
If tokenizing its assets wasn't enough, OpenSea could explore tokenizing Seaport, a protocol it launched a year ago. Tokenizing the protocol and incentivizing small markets may be beneficial to OpenSea. As long as Seaport becomes the industry standard for NFT transactions, the protocol could enforce royalties at the protocol level and blacklist bad actors.
Similar to Ronin, any protocol published by OpenSea could be governed by a consortium of game studios, large NFT publishers, and traditional retailers to determine how the shared standard will evolve.
The market has stalled because both major players have raised large amounts of venture capital, enough to keep them afloat for several years without revenue. This situation negatively impacts creators and smaller products that rely on the royalty model. As mentioned earlier, NFT royalties promise to enable a market for user-generated game content.
Without NFTs, this market could fall apart. Games will operate their own closed marketplaces to avoid regulation and circumvent app store policies on digital assets.
Another point to consider is that intellectual property plays an important role in the NFT market. Companies like Yuga Labs and Nike are motivated to continue developing their NFTs because they earn revenue from royalties. In fact, over the past year, the two companies have earned more than $100 million from royalties alone. Without this revenue model, no company would want to improve these primitives. Therefore, we will only set back the development of the current market by several years by blindly staying away from royalties.
Artists can choose to launch their own marketplace, using existing tools to create a storefront and publish royalty rules. However, this may inevitably leave artists in the same situation as in the past, with gatekeepers and intermediaries taking a cut of their earnings. A lack of industry understanding of two important factors may be at the heart of this problem:
Transactions play an important role in the digital asset ecosystem, and most of the funds invested and revenue generated come from financial applications, which will continue to trend towards lower fees to acquire users and transaction volume.
Not all assets are subject to substantial transactions, especially non-fungible assets like music album rights. Higher royalties are only justified when assets are traded less frequently.
image description
Back when Jay-Z realized that royalties were one of his 99 problems
Ironically, this sort of thing is nothing new. In 2015, Jay Z launched Tidal to solve the problem of music artists earning less money from streaming. Although it has the support of almost every major artist in the US, the €25 app has failed to take off. For a while, people could only get some old Jay-Z albums by paying on Tidal. As a result, the app quickly struggled, dropping 700 positions within a month of its launch. A few years later, Jack Dorsey from Square bought it for $300 million.
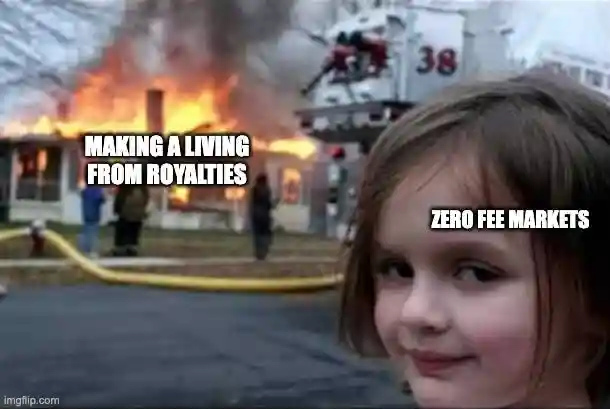
The idea is that as an artist, you want to earn income, but not at the expense of distribution of your work. Typically, artists optimize their work for streaming on YouTube because it counts towards their ranking on the Billboard charts. However, once a platform gains a lot of attention, it begins to dominate creators. If you want to get more distribution, you need to make it easy for users to discover your work, such as listing on OpenSea, or not setting a payment threshold for your content.
(We don't have any plans to charge, but we would like to give a big thank you to the person who paid us $200 for our work over the weekend, you surprised us.)
Currently, Blur is valued at $3.2 billion, which is higher than some protocols. This phenomenon has sparked a discussion about whether we are moving from the era of "fat protocols" to the era of application value accumulation. The success of the team behind Blur shows that standalone applications can often outperform entire protocols in terms of user numbers and services. This has led to an emerging trend of launching a marketplace with minimal or no fees, incentivizing user volume through tokens, and using tokens to provide ownership to users in exchange for their activity on the platform.
Essentially, instead of building what people might build, focus on building what people actually need. In today's market, we have finally reached the stage where we have optimized our products to attract professional users.
We do not believe that a market without royalties will ultimately succeed. As mentioned earlier, iteration is the norm in the market, and apps will continue to evolve and compete for niche users. The hype around Blur may subside in a few months and the NFT market will return to normal. Of course, there is also a possibility that the creators no longer issue NFTs, leaving us with only some previous works, despite the many innovations and developments the industry has experienced in the past three years.
The current market situation is difficult to predict. However, if we follow the advice of a contemporary rocket technologist and a Dogecoin enthusiast,The most interesting outcome may be the most likely thing to happen。
Original link





