






Has the Crypto Market Bottom? Let’s learn these 5 on-chain indicators


This article comes from BanklessThis article comes from
, the original author: Jack Inabinet, compiled by Odaily translator Katie Koo.
Concerns about the fate of the cryptocurrency market peaked in November. One of the leading cryptocurrency exchanges, FTX, valued at $32 billion, has gone bankrupt. Despite market turmoil, major cryptocurrencies have shown surprising resilience. So is the market currently at the bottom of the cycle?
Today we will study 5 “bottoming out” signals from on-chain data.
Since June 9, total returns in DeFi have been on the rise.
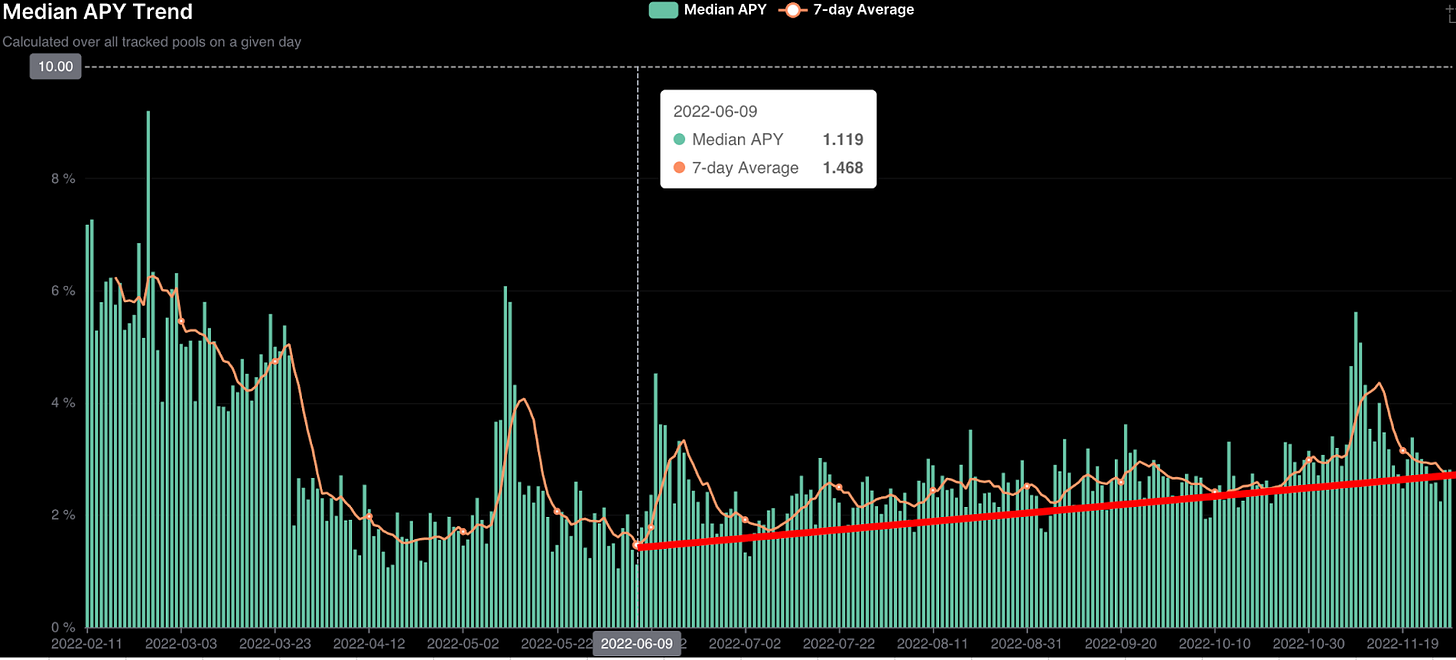
image description
ETH reached a cycle low a week and a half later on June 18.
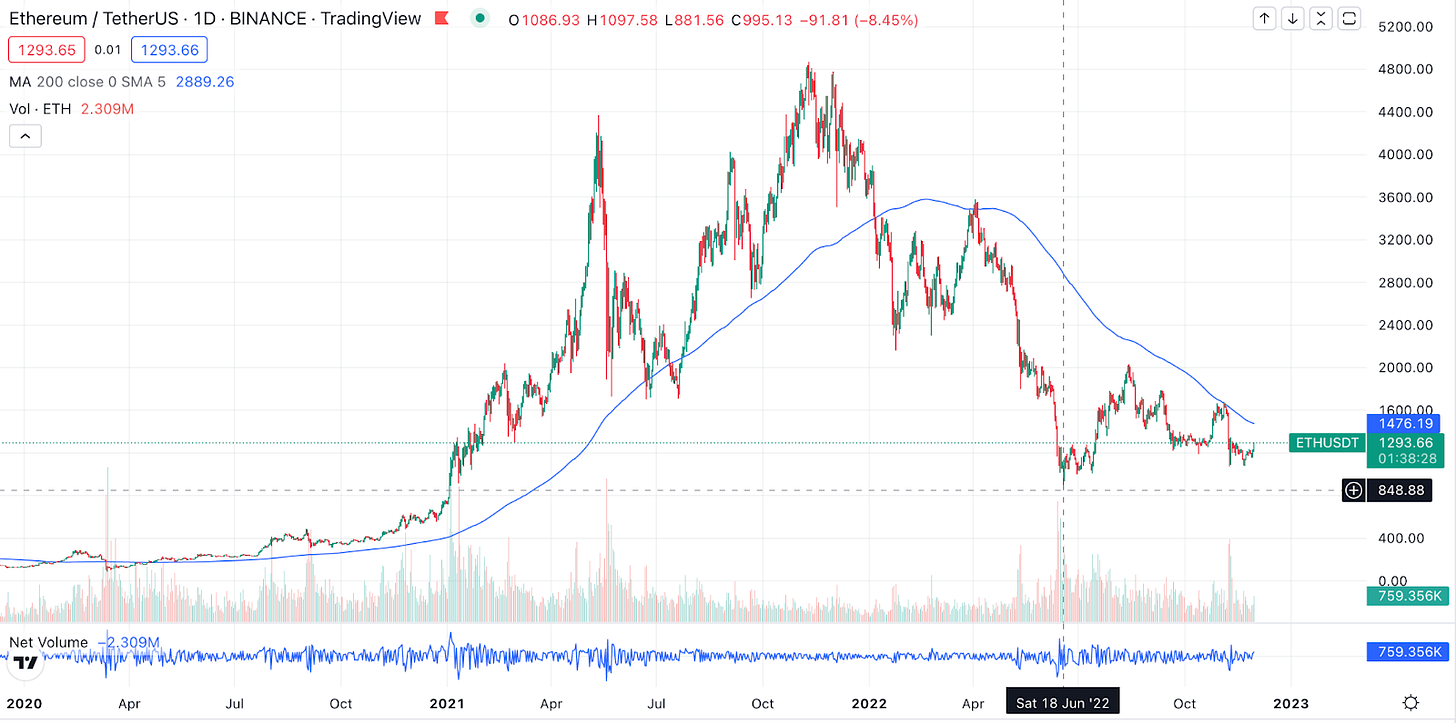
image description
Source: TradingView
The rise in yields between June 9 and 18 reflected increased borrowing demand for crypto assets from users who established short positions. Since then, the 7-day moving average yield peaked on June 19, the day the market witnessed a drop in ETH prices.In traditional financial markets, yields on debt instruments ranging from mortgages to commercial paper to U.S. Treasuries are driven primarily by macroeconomic interest rate conditions and the Federal Reserve's interest rate target,
Whereas cryptocurrency yields are generated by asset demand.
Higher DeFi yields generally correlate with higher crypto asset prices.
Because individuals and institutions mainly obtain leverage through borrowing or implement market-making or other income-generating strategies. Higher yields imply that borrowers are willing to pay a higher cost of capital, which indicates that borrowers are generally more capitalized. In addition, higher borrowing yields indicate that borrowers are shifting to higher investment risks, which is good news for risky asset classes such as cryptocurrencies.
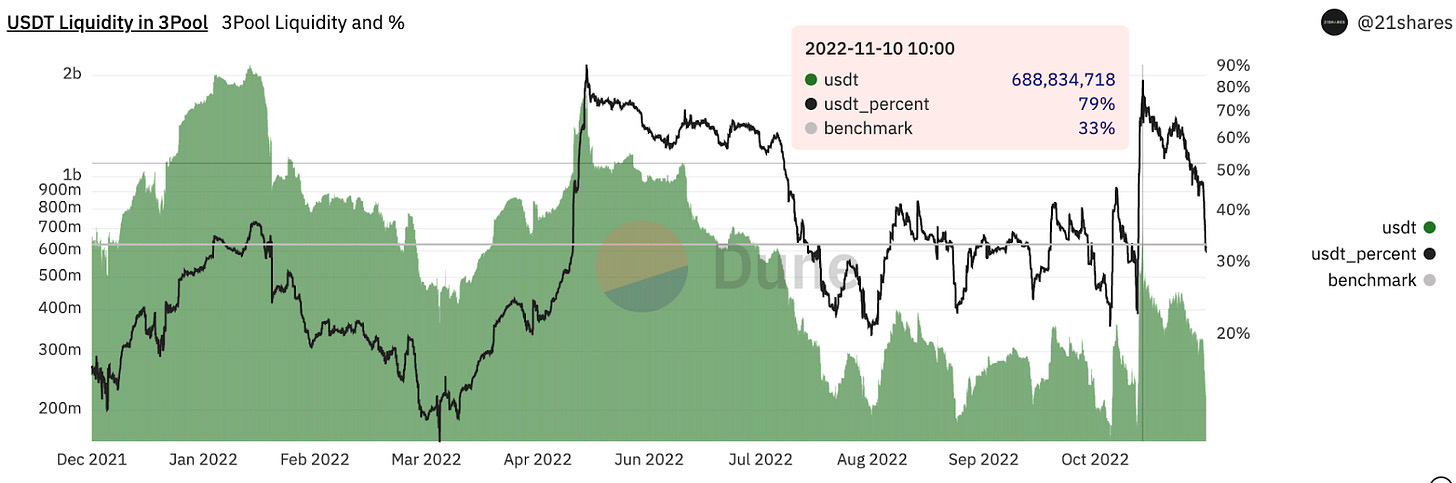
Alameda allegedly shorted USDT when FTX crashed, causing USDT to temporarily depeg (purple).
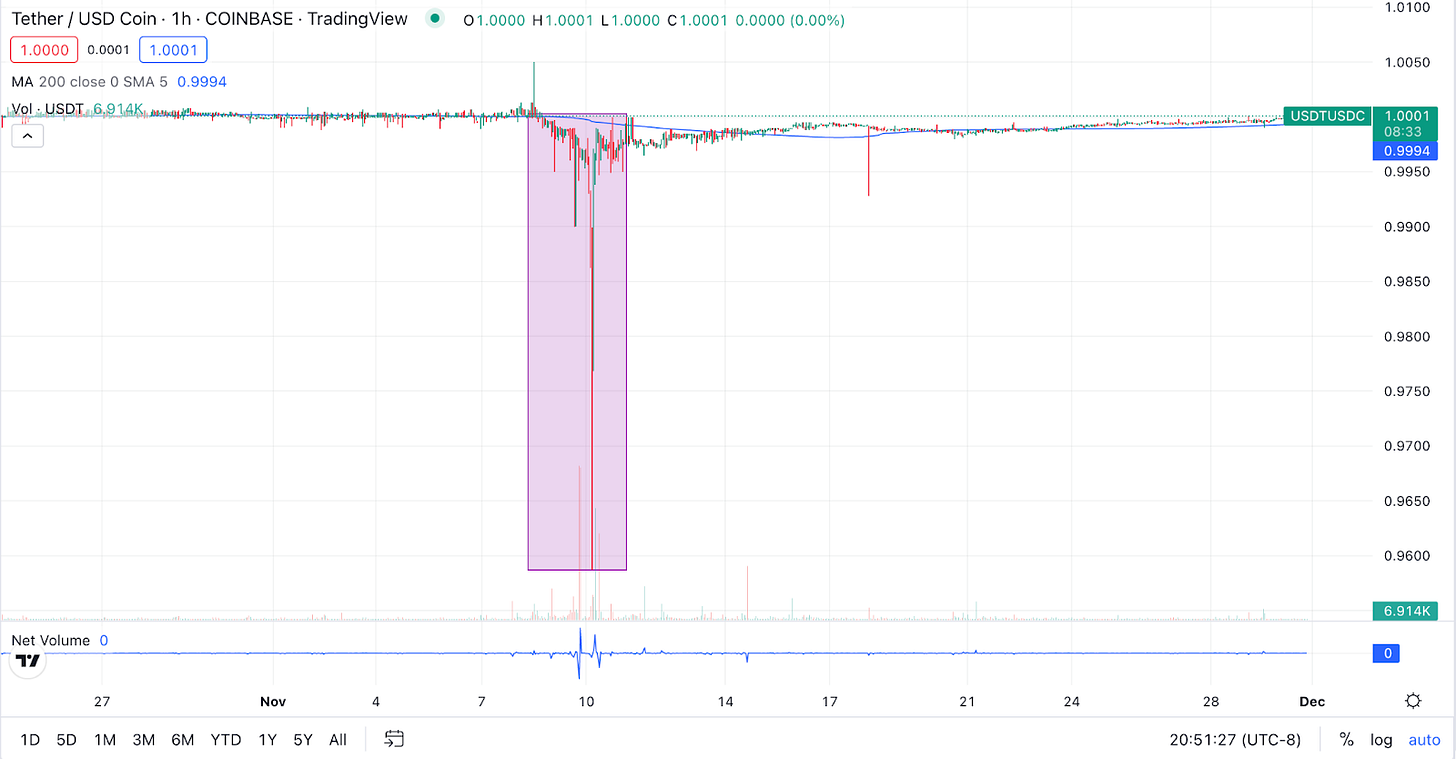
image description
Source: Dune Analytics
Source: Dune Analytics
Increased supply from shorting, selling pressure from relevant holders, and lack of demand to absorb the increased supply increased the proportion of USDT in 3Pool.
During major market declines, stablecoin balances typically fluctuate around a 1:1:1 target level between USDT/USDC/DAI. The recent USDT inflow has brought the pools to the expected level, with 38% of the Curve 3Pool pool composed of USDT, USDC, and DAI, accounting for 31% each. The stability of Curve 3Pool, especially after periods of extreme volatility, shows confidence in supporting major stablecoins.
3Pool is a "barometer" of panic in the industry, and the recapitalization of USDT balances is a bullish on-chain signal.
While the ratio between USDT, USDC, and DAI in 3Pool is still subject to rapid fluctuations, the stability of the ratio suggests that the market expects stable or positive performance in the near future.
3. The funding rate is negative and the price is stable
When there is a large amount of open short interest, the price of the perpetual instrument will be lower than the price of the underlying (underlying asset). In this case, users with short positions are compensated for long positions by the funding rate. When the futures price is higher than the underlying spot price, the longs will pay the shorts through the funding rate. This mechanism encourages financial instruments to track the spot price of an asset.
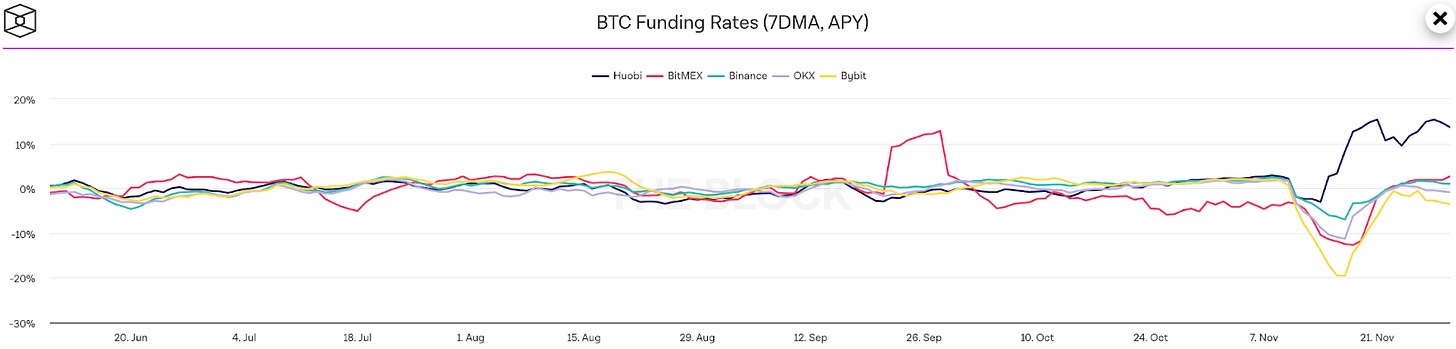
image description
Source: The Block
Throughout November, BTC’s funding rate was largely negative across all major exchanges tracked by The Block. Generally speaking, a positive funding rate implies positive price action and a negative funding rate implies negative price action.
However, persistent negative funding rates coupled with stable market pricing offer hope to bulls, showing resistance to further declines in asset pricing despite unusually high selling pressure on crypto assets.
After peaking at $126.02 during the FTX crash on Nov. 9, the Crypto Volatility Index (CVI) has been on the decline, reaching a near-baseline level of $80.71.
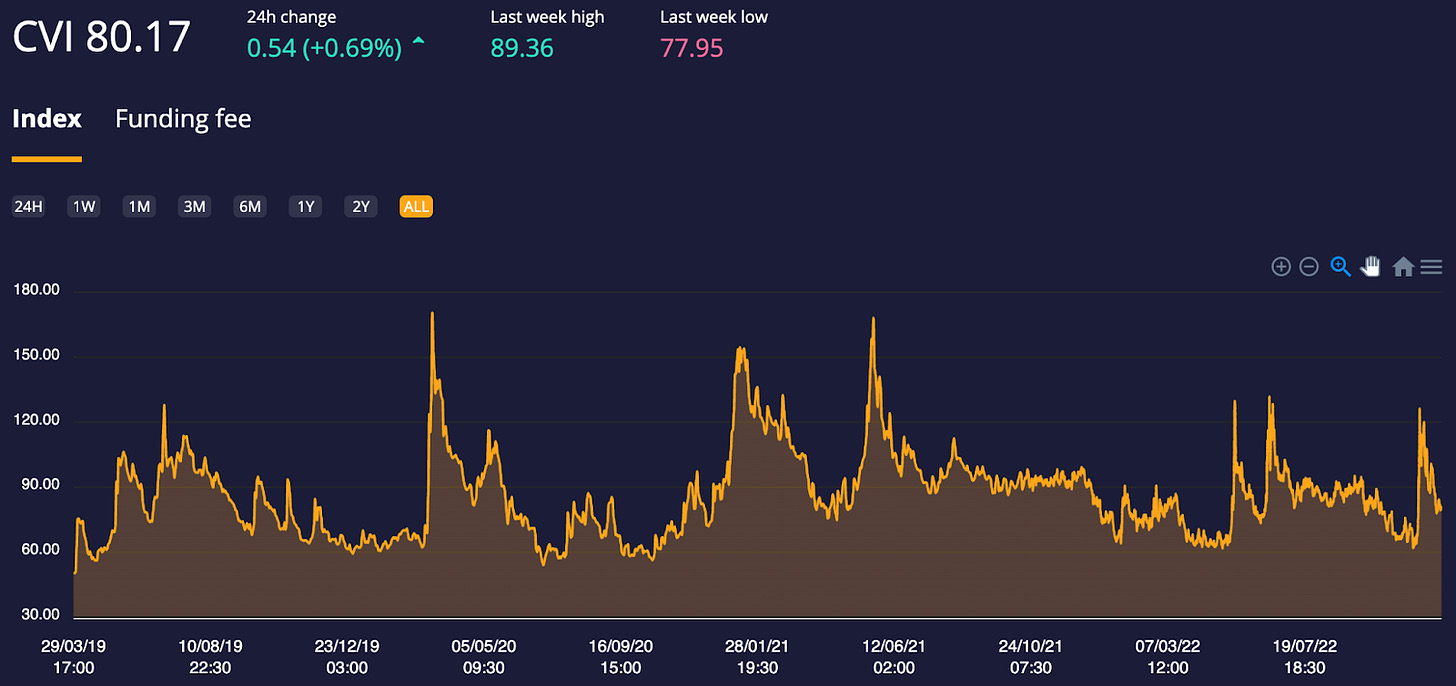
image description
Source: Cryptocurrency Volatility Index (CVI)
To form a bottom, reduced volatility and uncertainty in the crypto market is necessary. Lower CVI readings confirm this lower volatility.
If a bottom does form, we expect the CVI to continue falling, as it did before November 7th, the day the events at FTX really started to play out.
Smart Money’s allocation to stablecoins has been declining since peaking at 38% on Nov. 9.
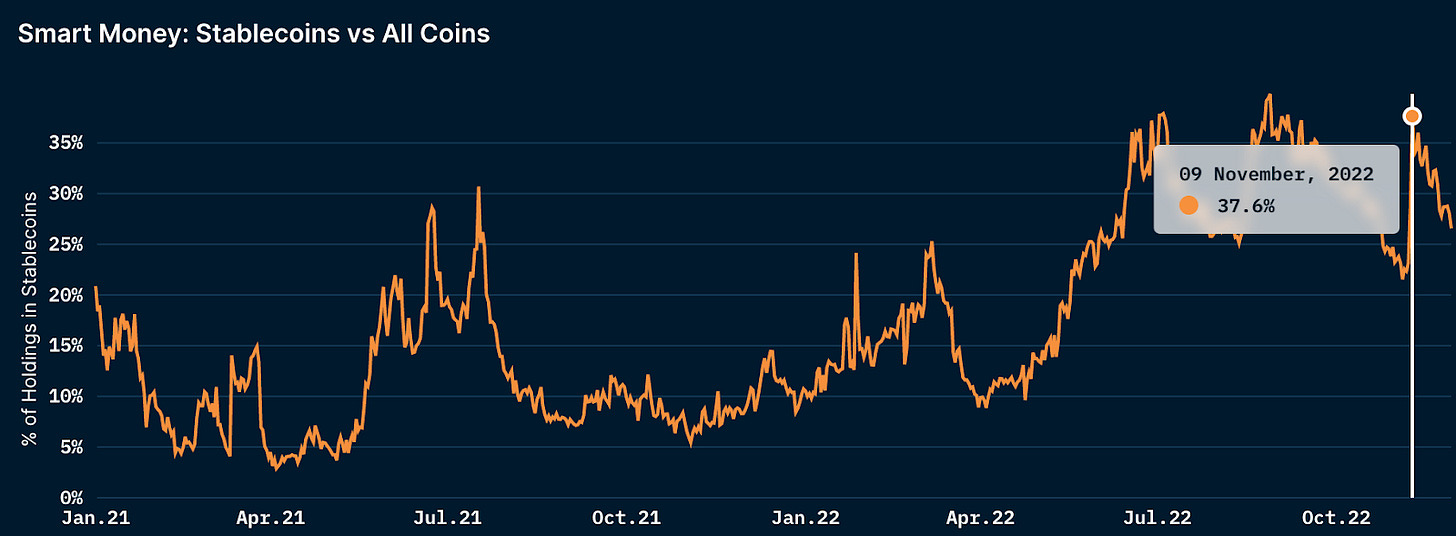
image description
Source: Nansen
The rest of November saw the “smart money” transition from a higher proportion of stablecoins in their portfolios to where it is today. Currently, stablecoins account for 27% of smart money’s wallet balances. Just like stablecoin holders ditch Tether, crypto asset holders turn to “embracing” stablecoins when the future value of their crypto assets is in question.
Investing in stablecoins allows cryptocurrency holders to reduce risk and limit potential portfolio drawdowns, while keeping funds on-chain, allowing whales to easily reallocate capital when market conditions are more attuned.





