


In the era of rising interest rates, how does Circle solve the dilemma of declining USDC supply?


Original author: Matías Andrade Kyle Waters
Original compilation: Deep Chao TechFlow
The momentum of stablecoin growth is a strong indication that demand for digitized dollars on public blockchains is booming – platforms that operate 24/7, 7 days a week, 365 days a year, across borders and time zones. Among the stablecoin giants, Circle’s rise as the operator of the largest domestic stablecoin USDC is impressive. However, the start of 2023 brings with it a new set of challenges. The USDC supply on Ethereum (which accounts for the majority of the total USDC supply) has dropped from $41.5 billion at the beginning of the year to approximately $23 billion now, a 44% drop as redemptions exceed new issuance.
In this article, we will analyze the USDC supply loss and its impact on Circle. We break down the current USDC supply into various categories to pinpoint the areas where the decay is most pronounced. A pressing question remains: Is this supply shrinkage a cause for concern? Furthermore, can this business model remain resilient in a macroeconomic environment of rising interest rates?
By blending on-chain analytics and off-chain financial insights, primarily from public SEC filings and Circle’s verification reports, we take a comprehensive look at the impact not only on the blockchain ecosystem, but also on Circle as a corporate entity, especially given that Circle The vision to go public. Through this off-chain and on-chain data synthesis, we assess crypto-native aspects and the broader business implications for Circle.
The missing $18 billion USDC
Although currently at $23 billion, USDC’s supply landscape is complex. That still represents a nearly 10x increase compared to supply just three years ago, but its also down significantly from a high of over $47 billion in early 2022. The most dramatic phase of USDC supply losses in 2022 occurred in Q1, coinciding with the collapse of Silicon Valley Bank (SVB) – an event we have dissected in depth before. Following this event, USDC supply dropped by a staggering $10 billion in March alone.
But SVB is not an isolated incident; escalating government and regulatory scrutiny of domestic stablecoin operators (some call it “Operation Suffocation 2.0”) adds another layer of complexity. Foreign issuers such as Tether benefited greatly, with its supply rising from $70 billion to $77 billion in the March 2023 time period alone.
The current pattern of rising interest rates is also an important variable. For USDC holders, this shift comes with clear opportunity costs. Existing operators of stablecoins such as Circle do not pass the interest generated on reserves directly to on-chain USDC token holders – this is something we will explore in depth later.
However, the massive drain on USDC supply appears to be slowing down, as shown in the chart below. However, daily trading volumes for redemptions and issuances remain well below pre-SVB collapse levels.
The structure of the USDC supply contraction in 2023 presents a multifaceted narrative, but several trends stand out. Here we break down supply by different categories:
By EOA and smart contracts
First, we compare the USDC held in the smart contract to the USDC held in a normal Ethereum account (also known as an externally owned account EOA in Ethereum terminology). Currently, approximately $7.6 billion in USDC, approximately one-third of the total, is held by smart contracts. This marks a 44% decline from $13 billion at the start of 2023. EOA experienced a similar contraction, falling from $28 billion to $15 billion. Interestingly, since the immediate aftermath of the SVB crisis has eased, a greater proportion of supply losses have come from smart contracts.
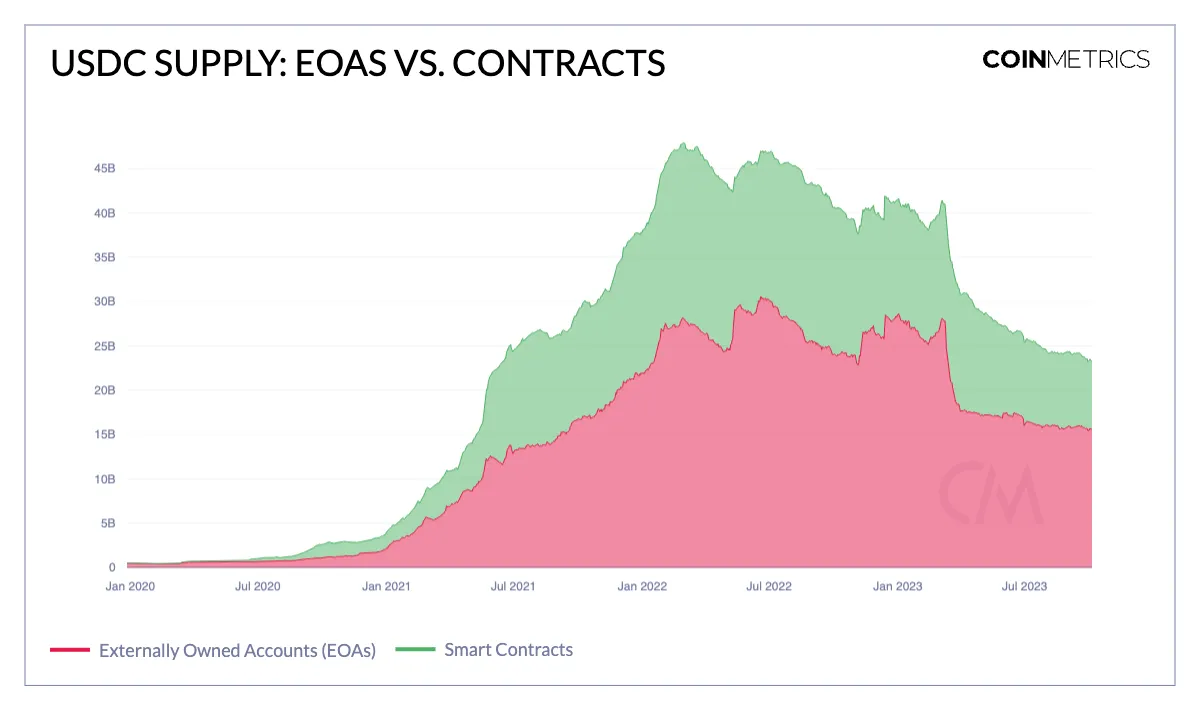
Divided by address balance size
We can also break down the USDC supply by various wallet sizes. As expected, the segments with the biggest losses were larger. Wallets currently holding more than $10 million in USDC account for $12.5 billion, compared with $22.5 billion earlier this year. While this decline is partly a function of the skewed distribution of wallet holdings, the largest wallets witnessed the most significant contraction in terms of percentages. In comparison, wallets holding USDC between $100 and $1,000 have collectively seen their USDC supply grow by 28% year-to-date. Most of the losses in the large wallet category occurred during the SVB collapse, which makes sense for large holders to diversify their investments.
top holder
We further examine the top holders of USDC. The top 1% and top 10% of addresses now account for a larger proportion of the total USDC supply than they did at the beginning of 2023. This concentration peaked around the SVB crisis, likely due to USDC being funneled into decentralized exchange pools or exchange wallets. However, the total number of accounts holding USDC has increased from 1.6 million to 1.8 million this year.
The supply landscape for USDC in 2023 is complex, but is driven primarily by two overarching trends: the post-SVB migration to offshore stablecoins and rising interest rates incentivizing capital to chase higher yields. While uncertainty may be clouding the supply side, rising interest rates are boosting Circles business operations.
Circles treasury
One advantage of stablecoin design is supply transparency, which is auditable in real time (at least as far as data on the blockchain is concerned). However, if we also consider Circles financial statements and monthly verification reports, we can begin to build a model of Circles USDC treasury and how it operates, particularly its profitability.
If we look at BlackRocks Circle Reserve Fund, we see that it lists the portfolio broken down by investment asset maturity, with all assets with maturities within 2 months, and 65% with maturities within Assets between 1-7 days. This estimate is based on a constant proportional portfolio allocation to overnight reverse repos and 4-cycle notes of 70% and 30% respectively.
The size of the portfolio is estimated to be exactly the current USDC supply, which may not be fully representative of Circles treasury operations, especially redemption operations, but should be proportional and consistent. However, this should constitute a naive estimate of the expected daily returns on these investments, as it ignores transaction costs, rollover costs and management fees that would be incurred in managing this portfolio.
Using FREDs data, we can estimate the returns these securities will generate using the effective federal funds rate to estimate the return on the overnight reverse repo investment and the 4-cycle Treasury rate to estimate the return on the remainder of these assets at 70% and 30%, respectively.
As shown in the chart above, daily returns are highly correlated with interest rates. Although USDC supply peaked in early 2022, estimated daily revenue actually peaked in early 2023 — after the supply dropped by nearly $7 billion. Even today, with supply $18 billion below levels earlier this year, interest income is still well above where it was in 2021, when USDC supply was comparable to current levels. This speaks volumes about the business model of fiat-collateralized stablecoins, showing that interest rate sensitivity is increasingly becoming a decisive factor driving their profitability.
Using the quarterly data in the chart above, we can compare these numbers to Circles reserve interest income disclosed in its earnings report. We can see that they reported interest income of $274 million in Q3 2022, similar to our estimate of $240 million -- but when we factor in all the data and redemptions for the current year, this simple The model just doesnt seem to work. The absence of public financial statements after 2022 hinders our model validation. Still, its worth noting that Circle reported higher revenue in the first half of this year alone (considering all of Circles businesses) than in all of last year, at $779 million versus $772 million.
Even as interest in stablecoins grows, spurred by news about Paypal’s stablecoin, the structural factors driving stablecoin adoption are changing, the most important of which is rising interest rates. The increasing opportunity cost of holding cash may drive stablecoin users toward income investments such as money market funds, which offer substantial returns in excess of 5%, compared with annualized returns of less than 2% over the past few years. Additionally, yield stablecoins are starting to gain adoption, such as sDAI and sFRAX, and Coinbase is offering 5% yield on USDC.
Summarize
Severe fluctuations in USDC supply in 2023, including the fallout from the SVB crisis and increased regulatory scrutiny, create a challenging environment for business. Circle has successfully leveraged the exact same interest rate dynamics to boost its business operations despite its significant decline in supply. Changing macroeconomic conditions and the evolving stablecoin landscape, alternatives represented by yield stablecoins, highlight the need for adaptability and innovation. Circle’s strategic partnership with Coinbase, which offers competitive returns on USDC, demonstrates the need for proactive measures in this rapidly evolving environment. As Circle considers going public, its ability to weather these turmoils will be a testament to its business acumen and vision for the future of digital currency.





