






LD Capital: THORChain借贷-揭示Terra LUNA的隐影


Original author: Yilan, LD Capital
Introduction
In-depth exploration of the new lending module launched by Thorchain on August 22nd, we discovered the shadow of Terra LUNA, and the similarity between LUNA is mainly reflected in the fact that the collateral deposited by users is converted into RUNE. The actual inflation and deflation of RUNE are determined by the fluctuation of the RUNE-collateral exchange rate, just like how LUNA absorbs the volatility of UST. However, there are differences in the forms of expression (participation in borrowing, destruction and minting during loan opening and closure for RUNE; participation in stablecoin anchoring, destruction and minting through arbitrageurs during UST depegging for LUNA) and the underlying risk exposure (LUNA has no upper limit for minting, while RUNE has upper limits for inflation and deflation, and only 50% of the collateral for synthetic assets is RUNE). Moreover, the lending protocol has strict risk controls and risk isolation measures, so the overall risk is relatively low and will not generate systemic risks similar to Terra LUNA, even if negative spirals occur, they will not affect other functions of Thorchain.
I. Understanding Thorchain Lending Mechanism
The characteristic of Thorchain lending is that it has no interest, no liquidation risk, and no time restriction (during the initial period, the minimum loan period is 30 days). For users, it essentially means being long on USD and short on BTC.
/The collateral assets for ETH are essentially short BTC/ETH and long USD for the protocol. The debt is denominated in TOR (Thornchain's USD equivalent), so users are effectively buying OTM call options on BTC with their holdings of the protocol/RUNE. Opening a new loan has a deflationary effect on $RUNE assets, while closing a loan has an inflationary effect on $RUNE assets. The BTC collateral is first exchanged for RUNE, then burned, and finally minted into the assets needed to redeem RUNE. In this process, the difference between the collateral value and the debt, minus fees, corresponds to the net burn value of RUNE. If the collateral appreciates at the time of repayment, then, assuming a constant RUNE price, more RUNE needs to be minted to redeem the required assets, resulting in inflation. On the other hand, if the price of RUNE increases, it wouldn't be ideal to mint as much RUNE. If the price of RUNE decreases, inflation becomes even more severe. If the collateral depreciates at the time of repayment and the RUNE price remains constant, users might choose not to repay, thus avoiding minting. If the value of RUNE relative to $BTC remains constant during the opening and closing of a loan, then there would be no net inflationary effect on $RUNE (the quantity burned would be equal to the quantity minted minus the exchange fee). However, if the value of the collateral asset relative to RUNE increases between loan opening and closing, then there would be net inflation in the supply of $RUNE.To tackle inflation, loan control measures have been put in place - if minting results in a total supply exceeding 5 million RUNE, there is a circuit breaker design. In this case, reserves will intervene to redeem loans (rather than further minting), the entire lending design will cease and be phased out, but other aspects of THORChain will continue to operate as usual. Therefore, the impact of the entire lending process on the inflation and deflation of RUNE is significant, but within the context of a relatively low lending cap, both inflation and deflation have upper limits. When the RUNE-collateral ratio rises infinitely, deflation is capped at a maximum of the current maximum open position of 15 mln * 0.33 (0.33 is the lending lever, might change), which is 4.95 mln (may increase in the future). In the case of an infinite drop in the RUNE-collateral ratio, inflation is also controlled within 5 mln by the circuit breaker. Specifically, if a user overcollaterizes 200% of collateral and borrows 50% of the desired asset, the other 50% is minted based on the RUNE-collateral ratio upon redemption. This step is essentially similar to LUNA, except that under the Thorchain Lending mechanism, due to only having 50% of Rune back, the product capacity is also smaller, hence the overall risk is relatively lower and does not generate systemic risks similar to Terra LUNA. This portion of risk is isolated, so even in the event of a negative spiral, it will not impact Thorchain.Other functions of p; have an impact.
1. How to understand that the design of lending is similar to a deep virtual value and a callable option with a resettable exercise price for users?
When Alice gives 1 BTC, she also receives 50% cash (assuming CR is 200%) and the opportunity to purchase 1 BTC with this cash.
If BTC rises when it's time to repay (let's say after a month), Alice will repay the debt (equivalent to 50% of the value of BTC a month ago) and spend the price from a month ago to buy 1 BTC. If it drops a lot, exceeding 50%, Alice chooses not to repay, and the protocol won't generate inflation due to mint rune (meaning her long position failed).
2. How to understand the absence of loan interest?
It can be regarded as users paying multiple swap fees instead of an interest rate, which essentially is a CDP product. If loan interest is charged, the attractiveness of this product to users will be reduced.
The entire process of borrowing and lending is as follows:
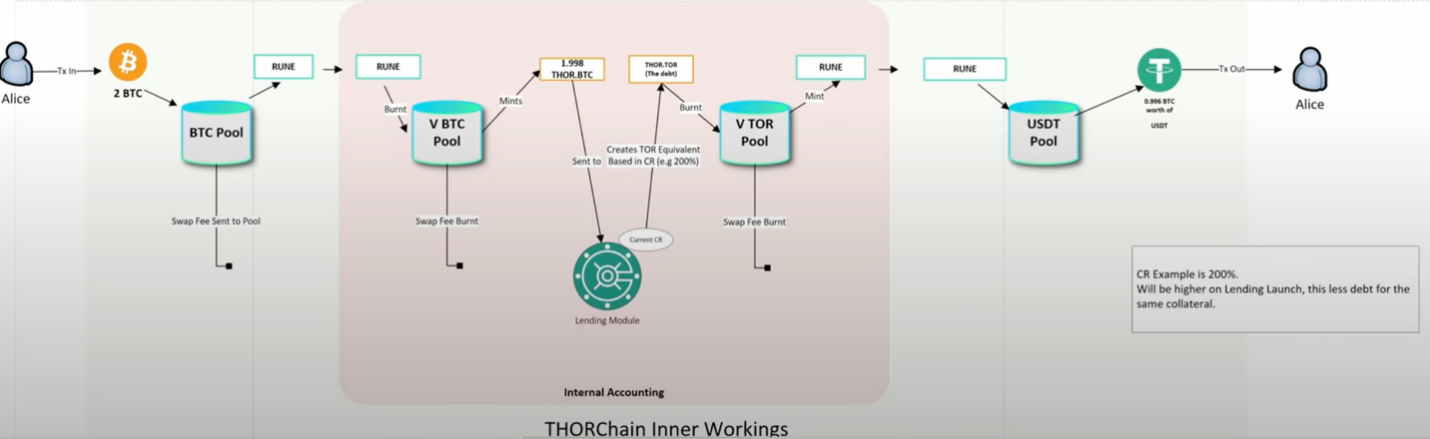
Collateral for depositing native assets by users (BTC, ETH, BNB, ATOM, AVAX, LTC, BCH, DOGE), initially, the collateral is limited to BTC and ETH. The maximum amount of collateral (debt ceiling) that a position can accept is determined by the hard cap (15 mln), lending lever, and pool depth coefficient. Excessive collateral generates debt, and the proportion of debt received is determined by the CR.
Borrowing: Alice deposits 1 BTC, which is first exchanged for RUNE in the BTC-RUNE swap pool. These RUNE enters a V BTC pool where they are burned and converted into a synthetic asset called Thor.BTC. The collateral for the synthetic asset is a constant product liquidity, always 50% of the asset, with the remaining 50% being RUNE. Then, the synthetic asset Thor.BTC is sent to an Internal module, where a dynamic CR (Collateral Ratio) determines how much loan can be obtained, and Thor.Tor (similar to USD) tokens are generated as an accounting mechanism for the loan creation. The steps taking place here are solely for internal accounting use, and afterwards, a USDT loan is generated and given to Alice for her disposal.
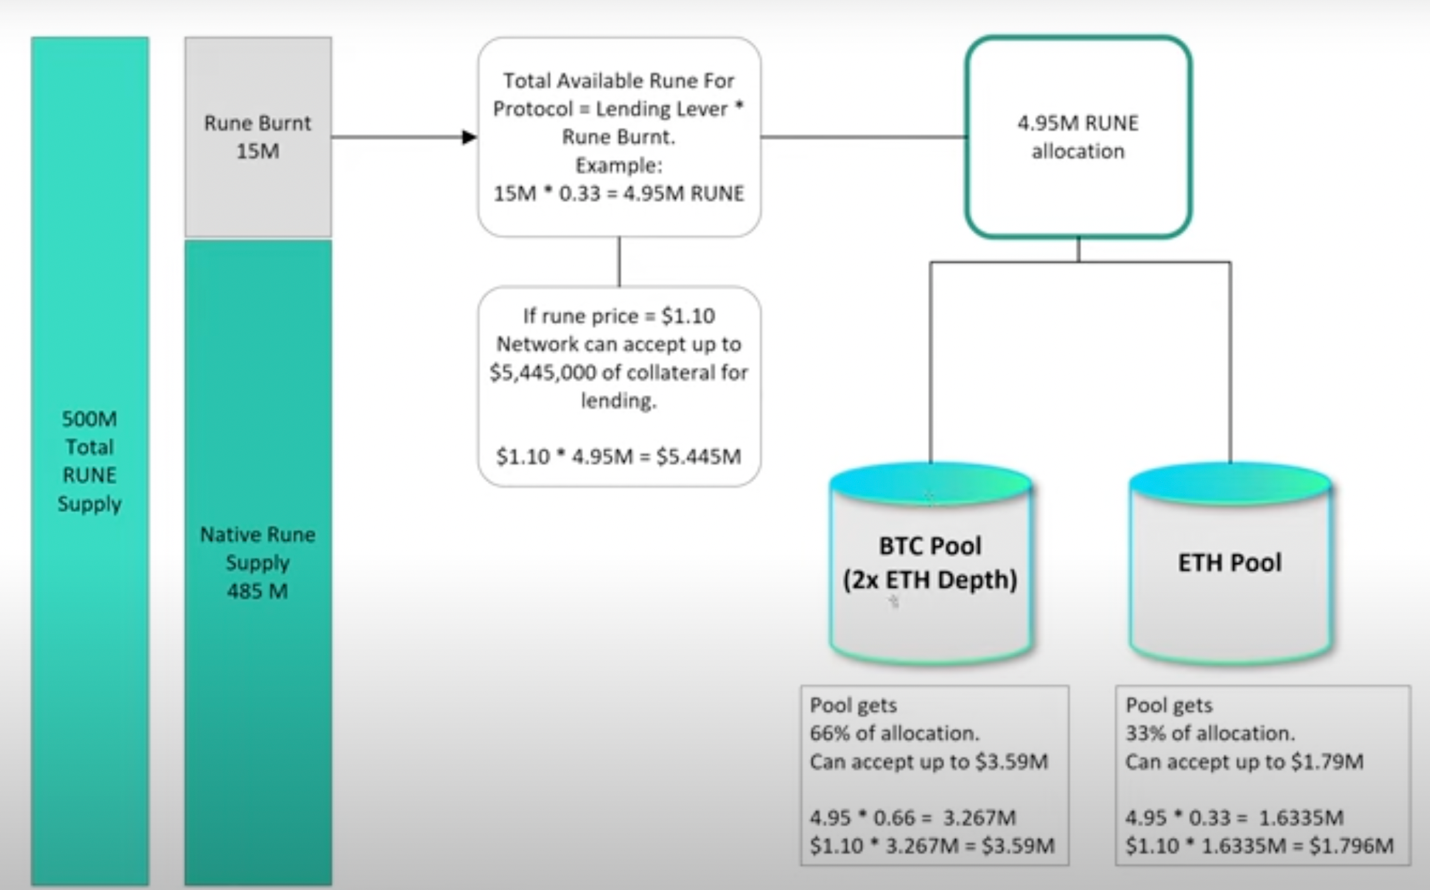
Source: GrassRoots Crypto
The entire Reserve's RUNE Burnt is the buffer for all debt positions and serves as a last resort for inflation. The total value of the RUNE Burnt * Lending lever in the Reserve (currently 4.95 million) is allocated based on the depth of each debt pool. The deeper the depth of a pool, such as the BTC Lending pool being twice as deep as the ETH Lending pool, the more buffer in the Reserve is allocated. Therefore, the value of the Rune Burnt * Lending lever depth coefficient in this lending pool represents the maximum collateral limit it can accommodate. Thus, as the price of RUNE rises, the lending pool can accept more collateral. It can also be observed that the Lending lever and the price of RUNE jointly determine the maximum collateral limit of the lending pool.
The THORChain protocol and all RUNE holders are counterparty to each loan. The burning/minting mechanism of RUNE means that RUNE is involved in the opening and closing of debts, which allows for
condense/dilute (among all RUNE holders). When the RUNE-staking ratio falls, inflation occurs, and vice versa, deflation occurs.5. Is the CDP protocol a good on-chain absorption model?
For Lending introduced by Thorchain, it is a disguised absorption model that uses RUNE as an essential medium in the borrowing and repayment process, increasing the scenarios of destruction and minting.
So is this absorption model advantageous? Let's first look at some other absorption models in different tracks.
CEX is the most obvious beneficiary of the absorption model because, as a custodian, this portion of funds can generate more income in many cases (after the reserve requirement is made public, this income is reduced compared to before), and how to protect the security of user funds is something that regulatory frameworks need to clarify. Regulators usually expect exchanges to fully reserve funds.
The situation on the chain is completely different.
After DEX absorbs liquidity, it needs to provide high incentives for LP. Therefore, the purpose of absorbing liquidity is to deepen liquidity, and cannot directly generate profits using the "deposits" provided by LP, but forms a liquidity moat through a large reserve.
Pure Lending, like Aave or Compound, requires paying interest costs for absorbing liquidity. The entire model is no different from traditional lending, such as actively managing loan positions and having repayment deadlines.
In comparison, the CDP model of absorbing liquidity is a healthier model. Since the collateral assets are highly volatile, most of the over-collateralized CDPs on the market are users over-collateralizing certain assets to obtain stablecoins/other assets. In this process, the CDP protocol actually obtains more "deposits." And there is no need to pay interest on this portion of the deposits.
Thorchain also belongs to this CDP model. Where is the collateral held? In fact, the collateral is exchanged for RUNE through liquidity pool. Therefore, no one "stores" collateral. As long as the THORChain pool is healthy and operating normally, any collateral deposited will be exchanged for RUNE, and then arbitrageurs will rebalance the pool as usual. This can be seen as the collateral being deposited in the RUNE pool of Thorchain against other currency pairs. Because assets such as BTC enter the circulation market instead of being held in the protocol, although the generated debt is 100% collateralized, the difference between the collateral value and the debt is covered by RUNE.The value of nbsp; is determined, thus casting a shadow similar to Terra LUNA over the entire mechanism.
Capital Sink may be one of the goals that Thorchain lending wants to achieve, using users' collateral assets to settle into the asset liquidity of the swap pool. As long as users do not close the loan and the price of RUNE does not plummet, the protocol retains the assets, causing a deflation of RUNE and forming a good positive cycle. Of course, the opposite will create a negative spiral.
6. Risks
BTC and other collateral assets enter the circulation market instead of being held in the protocol, so although the generated debt is 100% collateralized, the difference between the collateral value and the debt is determined by the value of RUNE, thus casting a shadow similar to Terra LUNA over the entire mechanism. Due to RUNE burned when opening a loan and RUNE minted when closing a loan not necessarily being equal, there can be both deflation and inflation. This can also be understood as when the price of RUNE rises during repayment, deflation occurs, and vice versa for inflation. If the price of RUNE falls below the lending lever multiple at the time of opening the position, the circuit breaker will be triggered. Throughout the lending process, the price of RUNE plays a decisive role in deflation and inflation. When the price of RUNE goes down, there is still a high risk of many users choosing to close their loans and causing inflation. However, the protocol has strict risk control and risk isolation measures, so the overall risk is relatively small and will not pose systemic risks similar to Terra LUNA, even if a negative spiral occurs, it will not affect other functions of Thorchain.
However, in fact, the reverse market trend can lead to inflation and negative spirals. To control risks, the use of Thorchain lending is limited and has a small capacity. In terms of overall deflation and inflation, the current capped volume does not fundamentally affect the price of RUNE (at most, an impact of 5 million RUNE).
In addition, for users, Thorchain's capital efficiency is also not high, with a CR ranging from 200% to 500% and may ultimately fluctuate between 300% and 400%. Purely from a leveraged perspective, it is not the best product. And although there are no borrowing costs, multiple internal transaction costs erosion is also unfriendly to users.
Evaluating only the lending product does not represent the overall development of Thorchain's defi product matrix. There will be a series of analyses on other Thorchain products in the future.





