Edit: Southwind
Edit: Southwind
"A market that can function freely is like a wheel that can turn freely: it needs a shaft and well-lubricated bearings. How to provide this shaft and keep the bearings well lubricated is the focus of market design."
—Alvin E. Roth, Nobel Laureate
01 Overview of the block space market
Blockspace is the commodity that powers all cryptocurrency networks. In the block space market, miners are producers, mining pools are auctioneers, and users are bidders. The impact of the block space market is so pervasive that it touches almost every aspect of the cryptocurrency ecosystem.We know that in a blockchain network, after a user initiates a transaction, the transaction will be broadcast in the memory pool of each node in a peer-to-peer (P2P) manner. Every transaction comes with a transaction fee (fee). This transaction fee indicates the willingness of the trader to purchase block space so that his transaction can be processed (by the miners) and included in a block.At any moment, there will be countless blocks proposed by miners in the "Schrödinger state", that is, between the "unconfirmed" and "confirmed" states. These blocks race to find the first hash output that meets the difficulty target. Each proposed block has a probability of being the next block on the blockchain. Through billions of calculations per second, miners will collapse this probability wave to form the history of the blockchain ledger.Since each block is capped in size, i.e., the number of transactions that can be included in it at a given time is limited, this gives block space an implicit time value. If a transaction has not been confirmed for a long time, it may be affected by market (price) volatility, or be preempted by arbitrage robots. The transaction fees (fees) that users pay to have their transactions confirmed reflect their willingness to bid for block space. The block space marketplace connects miners and users together.On the surface, the blockspace market looks complex and chaotic because of its lack of central coordination. It relies on detailed rules, procedures, and a confluence of supply and demand to self-regulate. How do we know if the current market design is optimal? Get a glimpse of it with Nobel laureate Alvin E. Roth.
Alvin E. Roth is considered a pioneer in the field of market design. In his seminal book "Who Gets What - and Why", he states that in order to function properly, markets need to do at least three things:
- Market Depth: There is a sufficient number of potential buyers and sellers to interact. In the block space market, suppliers (miners) are motivated by block rewards to provide hash rate (computing power); on the other hand, as more and more people (users) use the network for transactions, the block Block space requirements are also increasing.
- Security: Market participants must feel safe before disclosing or acting upon confidential information they may hold. Due to the transparency of transactions on the chain, transaction users who submit sealed quotations may not always get the results they want (that is, transaction users cannot know each other's transaction fee bids, and transactions with high bids are often confirmed by miners first) . Furthermore, transactions require a high degree of settlement assurance, i.e. there should be enough computing power to make block reorganizations costly.
- Overcoming the congestion problem: Transactions should be completed or canceled in a timely manner. When the market cannot effectively handle the congestion caused by the transaction volume, the transaction confirmation of participants (users) may encounter a large delay. Just as due to the recent popularity of Ethereum Dapps (decentralized applications), transaction congestion has led to a surge in Gas prices.
In the history of Bitcoin and Ethereum, how to optimize the design of the block space market structure has often sparked many heated debates. In the following sections, we will explain the structure of the Ethereum block space market from the perspective of supply side (miners) and demand side (users). We will look at whether the current blockspace market design provides depth, eases congestion, or is safe and easy to participate in. After that, we will discuss some popular proposals to optimize the structure of the block space market and how the block space market may develop in the future.
1. Supply side: the structure of Ethereum mining
The ultimate goal of the entire mining industry is to provide a decentralized transparent clearinghouse for a commodity, namely block space.This task is by no means trivial. In a distributed blockchain system that does not have a central authoritative coordinator and operates around the clock globally, the block space is auctioned anonymously, and miners need to provide a strong settlement guarantee for the block space, by investing a lot of money in hardware and energy To perform a large number of calculations to ensure the security of the blockchain network.Despite widespread concerns about centralization of computing power (e.g. triggering so-called 51% attacks), the mining industry is not a single organism. The fluctuations in the block space market affect the various participants to different degrees; and each miner is heavily affected by factors such as location, mining machine type, temperature, maintenance and mining strategy.Bitcoin and Ethereum mining have very different market structures: Bitcoin and some PoW coins have almost completely migrated to the ASIC mining era. On the other hand, despite Ethereum being the second largest market capitalization, there is almost no ASIC mining in the Ethereum mining space, and although there are rumors of new ASIC manufacturers every once in a while, it is estimated that there are currently about 80 -90% of Ethereum computing power is dominated by GUP mining.So structurally speaking, how is the block space supplier market mainly composed of GPUs mining different from the block space market mainly composed of ASICs mining?GPU mining started with NVIDIA and AMD. They either sell discrete graphics cards directly, or wholesale GPU chips and memory to downstream graphics card manufacturers. Instead, these manufacturers removed features not related to mining, hence the name "mining graphics cards". There are many brands of white label custom mining cards.
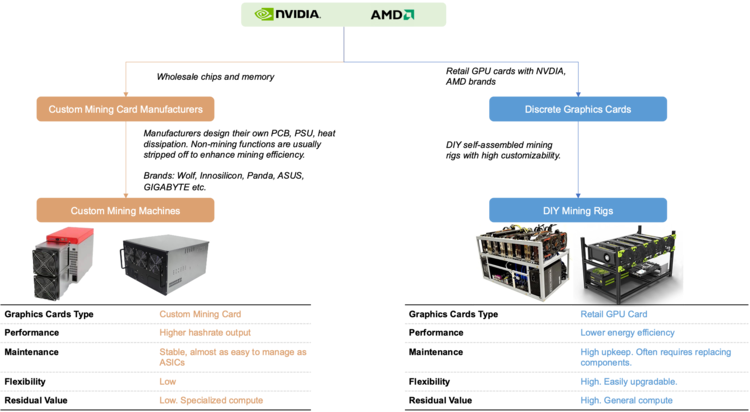
There are far more OEMs in the GPU market than in the ASIC market. Therefore, Ethereum's computing power composition is more diverse than that of a typical ASICs network (such as the Bitcoin network). This also brings challenges to the monopoly channel of mining machine distributors. GPU miners have more options as they don’t have to wait for ASIC manufacturers like Bitmain, Whatsminer, etc. to work out supply chain constraints for their equipment.
This means that the supply of GPUs is generally not as bottlenecked as ASICs that use advanced back-end processes. In addition, GPU miners are not tied to any specific blockchain network (can switch mining between different PoW blockchain networks), and miners engaged in speculative mining almost exclusively use GPU miners. And, consumer GPU graphics cards are also valuable in other areas of computing, such as gaming, data centers, and artificial intelligence work. In general, GPU miners have more flexibility in their choice of hardware.Structure determines properties. The hardware composition determines the capital expenditure and energy consumption of the mining industry. These two factors are key to calculating the cost of mining, which has knock-on effects on the rest of the mining ecosystem: from equipment manufacturing, distribution, hosting facilities, fluctuations in Gas costs, to EIPs (Ethereum improvement proposals), to the characteristics of the mining cycle.
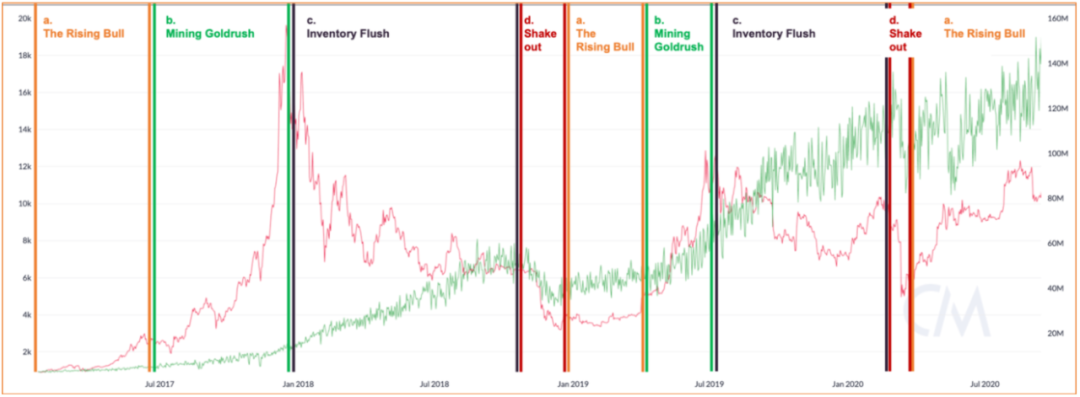
Historical changes in Bitcoin's price (red curve) and Bitcoin network hash rate (green curve), as well as the cycle of Bitcoin network mining cycles.
Due to the inherent illiquidity of mining hardware, changes in network hashrate often lag behind price changes. "Hardware reaction time" is determined by various external factors, such as the manufacturer's supply chain constraints, foundry wafer backlog, device performance, and even shipping logistics.This lag has been especially noticeable this year as the market is heading full steam ahead into a wild bull trend. Miners and investors are scrambling to order new machines; on the other hand, mining machine manufacturers are just recovering from supply chain disruptions during the COVID-19 outbreak, and a global shortage of integrated circuits has forced all industries that need semiconductors (chips) - mining Mining, automotive, consumer electronics, etc. — all waiting in long lines for wafer allocation.Additionally, NVIDIA recently announced that they will be artificially crippling the performance of their latest graphics cards running Ethash (PoW mining algorithm) to prevent miners from buying up all of their GPU inventory. This means that by the time the backlog of miners finally come online, the "clearing inventory" and "major reorganization" phases could be very painful for many miners, unless prices or fees continue to rise significantly.In Ethereum, there are three main sources of mining revenue:Built-in block reward (2 ETH per block reward + uncle block reward)
transaction fees, and
Miner Extractable Value (MEV)
The transaction fee in Ethereum as a percentage of the total block reward (that is, in a single Ethereum block, the transaction fee as a percentage of the total revenue brought by the block to the miners) is much higher than in Bitcoin (see the figure below ). This means that Ethereum miners not only pay attention to the currency price, but also pay attention to the trend of Gas. Even if the currency price remains unchanged, the increase in transaction fees will be enough to incentivize Ethereum miners to increase their computing power.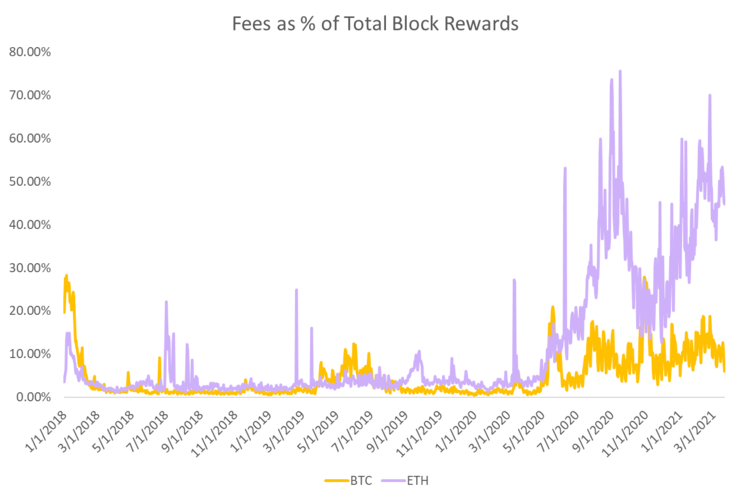
Above: the yellow line represents transaction fees as a percentage of Bitcoin block total return, and the purple line represents transaction fees as a percentage of Ethereum block total return. It can be seen that the proportion of the latter is obviously higher. Data source: Coinmetrics
image description
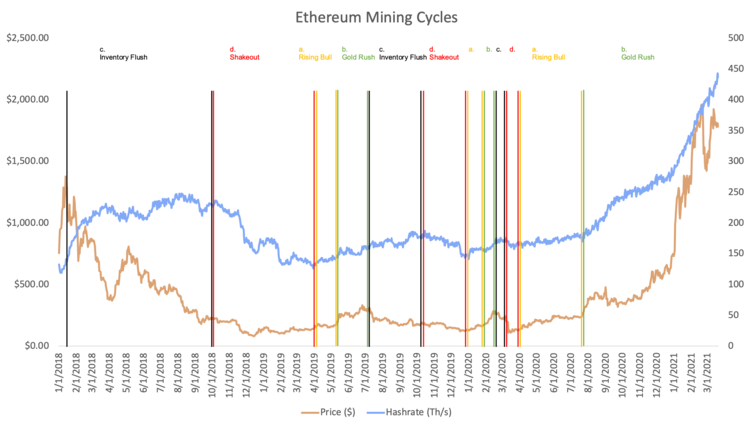
Above: Historical changes in the price of Ethereum (yellow curve) and the hash rate of the Bitcoin network (blue curve), and the cycle of mining cycles on the Ethereum network.
The shorter the mining period, it means that when the mining income is high, the competition intensifies faster; and the flexibility of GPU hardware selection means that when the mining income is low, the computing power is easier to release.The obvious rise in currency prices and transaction fees has attracted more miners to participate. However, unlike most commodity markets, more producers (miners) do not mean an increase in the supply of block space - the supply of block space is determined by the block size and the average block time. This means that the increase in network computing power does not reduce network transaction fees, but increases the security budget of the network: as more and more miners join the competition, the cost of reorganizing historical blocks becomes higher, This improves the settlement assurance of the network.2. Demand side: users want transaction fees to be minimized
Since the block size is limited, this means that users need to compete for the system's resources. The transaction fee model defines the core user experience for any user who initiates an on-chain transaction. Currently, the transaction fee model of the Ethereum network is the "highest price auction model".As the most popular platform for storing and executing smart contracts, Ethereum's utility is rising rapidly. DeFi's "currency Lego" has enabled many DeFi products and services to combine with each other in a permissionless manner, and has greatly promoted the innovation of new financial projects.Today's Ethereum users participate in the bidding of the block space market through the "highest price auction model". This is a simple auction model where users submit an offer for their transaction and pay miners in the form of transaction fees to have their transaction included in a block.Users can bid by setting the "Gas Price" of the transaction, which is denominated in gwei/gas (1gwei = 0.000000001 ETH). Our empirical observations on mining pool transactions show that more than 75% of mining pools follow the default strategy of only packaging transactions in descending order of transaction fees (transactions with higher transaction fees are included first, and transactions with lower transaction fees are included later) , without prioritizing transactions for any particular address. See below: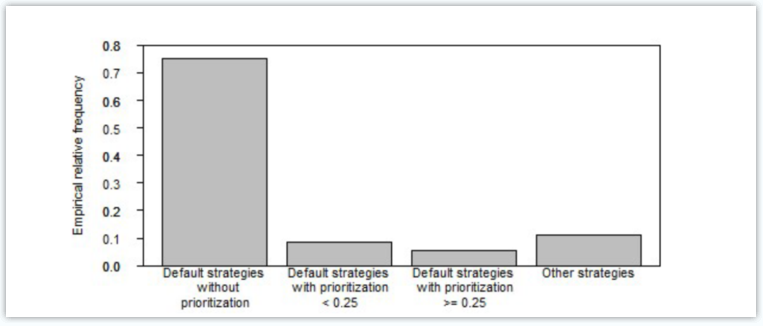
The market structure on the demand side of the block space is simple: users want to minimize the fees paid to miners to enjoy a smooth experience, while miners want to maximize their income, since they are profit-seeking entities.
It is an indisputable fact that the fees paid by users always follow the law of supply and demand: block space is the scarcest resource, so those users who want their transactions to be packaged into blocks faster are often willing to pay more transaction fees Higher than those users who are willing to wait until the next block is included.Blockspace is the closest thing to “digital real estate” in the crypto space. Block space has intrinsic value as "real estate" where economic activities take place.02 Network congestion and transaction fees
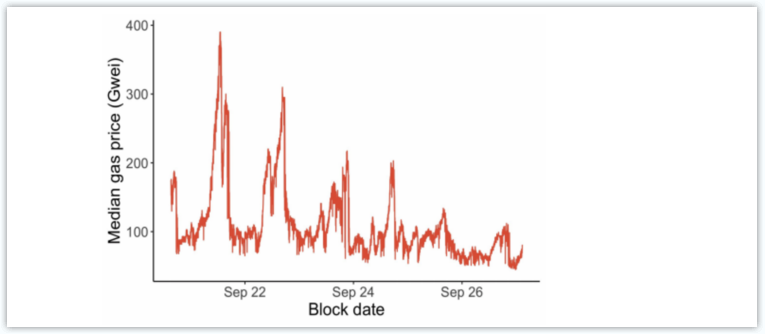
Above: The average gas price for an Ethereum block fluctuates from 100 Gwei to 400 Gwei over the course of a week.
Recall the Nobel laureate Roth's three requirements for a successful market design: market depth, security, and overcoming congestion. Obviously, during times of congestion, gas prices tend to rise too high for ordinary users. Where is the bottleneck?
The unpredictability of gas fees stems from the fact that users cannot coordinate on the "appropriate transaction fee" included in the next 1, 5, or 10 blocks. Today, most users use a "one-time bid" approach: they only broadcast the transaction once, and then wait for the transaction to be included.The first version of a new technology is always rough. Over the years, different versions will appear to solve the congestion problem. The market design of the block space involves balancing the interests of all parties in the ecosystem. At this juncture, three possible avenues for addressing congestion are discussed:Short-term: increase block size, but may compromise security;
Mid-term: Change the block space auction mechanism and require the community to reach a consensus;
Long term: Implement scalability solutions such as Rollups and Eth2.0.
first. Some might want to increase the block size so that more transactions can fit in a single block (i.e., increase the supply of block space, assuming demand remains the same). But this change only temporarily eases the pain of high transaction fees, as new demand quickly fills up blocks, pushing fees up again. In addition, the increase in block size makes the blockchain node software more resource-intensive, so this approach should be avoided to keep the system decentralized.Second, another approach is to restructure the bidding process. Today, the fee mechanism of all blockchains mostly implements a "highest price auction".EIP-1559The proposal proposes to change the fee mechanism to a fixed price sale when the system is not congested, allowing users to easily choose the "best" offer to meet their selection preferences. Variants of EIP-1559 have been deployed in blockchain networks such as Near, Celo, and Filecoin. This proposal is also scheduled to be activated in the Ethereum London upgrade in July 2021, which will be the largest fee market mechanism change ever to occur in a public blockchain.EIP-1559 is also one of the most controversial topics in Ethereum right now. More than 60% of the mining pools have expressed their opposition to the proposal, and EIP-1559 has evolved into a "trade war" between users and block space producers (ie miners). Although it is still difficult to quantify the exact impact this proposal will have on miners’ transaction fee income, the mining industry generally believes that Gas prices need to rise significantly to make up for the losses. A Jian of the Chinese Ethereum community "Ethereum Enthusiast" is an outspoken critic of the proposal, arguing that EIP-1559 "will lose the loyalty of miners." Kevin Pan, founder of Ethereum mining pool Poolin, believes that the proposal will not actually have much impact on mining revenue, but it is "extremely insulting."However, not all miners think so. The founders of Ethereum mining pool F2Pool (Fish Pool) are active users of DeFi products and they support this proposal. Even Jihan Wu, the notorious instigator of the Bitcoin block size “civil war” that led to the Bitcoin Cash fork, expressed support for Ethereum’s EIP-1559 proposal. Fundamentally, human coordination in an open ecosystem rooted in different parts of the world remains one of the greatest challenges.In the end, the appropriate solution in the long run is to allow the supply side to scale without significantly impacting the trust requirements of the Layer 1 (first layer) system. After all, users want low fees, and low fees are not an economic mechanism design issue, but a fundamental blockchain scalability issue. Notably, scalability also allows more demand to enter the system, which will offset the decline in average fees per transaction. Chief among these are so-called Layer2 (Layer 2) solutions such as Optimistic Rollup and ZK Rollup.03 Dark Forest and Dark Pool of Ethereum
If we were in the context of Bitcoin, the discussion around the demand side (users) would end here. In Ethereum, however, a financial system is being built that bends the rules of the game.
We know that for a limited period of time, there may be certain "opportunities" in the Ethereum network in the form of arbitrage, or the sale of a high-demand asset with limited participation (such as an ICO) form exists, etc. Similar to the way people line up to buy limited-edition clothing, developers have built software that intelligently competes for on-chain opportunities (such as arbitrage bots, or front-running bots), even competing with other peers via gas bidding. Robots compete with each other.This concept is called "Priority Gas Auction" (PGA for short), and was first described in the seminal paper "Flash Boys 2.0" [1] by Phil Daian et al. The "non-conventional" revenue stream generated by PGAs is called "Miner Extractable Value" (MEV for short).Currently, the MEV in the Ethereum ecosystem is mainly obtained by DeFi traders through structured arbitrage strategies (through arbitrage robots); while miners profit indirectly by obtaining the transaction fees paid by these traders.There is a potentially very lucrative opportunity for bots participating in PGAs to be willing to bid inflated gas prices so that transactions get confirmed as soon as possible for the profits they will be able to earn. By reordering transactions by gas fee when packaging transactions, these excessive gas fees end up in the hands of miners.This has led to the development of a dark forest (Dark Forest) in the Ethereum ecosystem. For example, Phil Daian described a value capture in the paper, in which about $12,000 worth of tokens fell into the "predator" hands. These predators are arbitrage bots that constantly monitor the activity of the Ethereum transaction mempool and attempt to run certain types of transactions ahead of time (front-running) according to a predetermined algorithm. DEX platforms such as Uniswap are likely to be flooded with arbitrage bots.As a result, some service providers have begun offering “dark pools” that allow transactions to bypass the Ethereum public mempool, and thus are invisible to the public until those transactions are packaged on-chain. Instead of broadcasting transactions to the network, these dark pools forward transactions directly to miners so that these transactions are not broadcast to other nodes on the network.These dark pools are not entirely used for the purpose of maximizing profits, and may also be used to escape from the dark forest of Ethereum. For example, during Escape from the Dark Forest [2], security researcher samczsun documented how his team used this technique to salvage 25,000 ETH from a problematic smart contract.Front-running and dark pools are not unique to the cryptocurrency market. They represent a financial driver as old as time: concealment. Wall Street has long embraced this controversial approach to investing. It is estimated that after 2015, dark pools accounted for 15-18% of trading activity in securities listed on U.S. exchanges.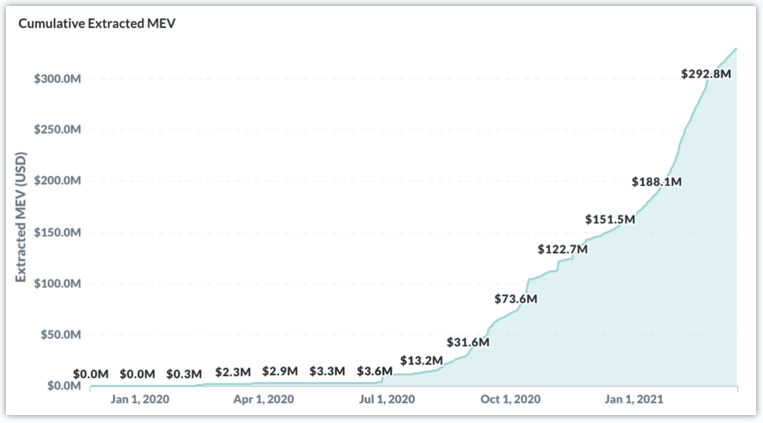
Above: Cumulatively extracted MEVs since January 1, 2020. Source: https://explore.flashbots.net
This butterfly effect is striking: arbitrage and liquidation opportunities create MEV. The fee estimator uses the gas price adjusted by the PGA auction as a reference, causing users to pay excessively high fees for their transactions.The core of this problem is that users and robots are in the same transaction mempool.Ideally, transactions involving MEV should be in a separate transaction pool from non-MEV transactions. This will allow bots withdrawing MEV to compete with each other; while all other transactions, such as transfers of cryptocurrencies, will take place in non-MEV transaction pools, which will allow users to enjoy a more stable Gas market.
But unfortunately for Ethereum, such breaking changes are difficult to implement. A simpler solution to this problem is to introduce a new API endpoint for miners, where they will accept transaction packages involving only MEV. In this way, arbitrage traders would submit their trades directly to the terminal, while users would continue to use the rest of the system as they do today. This is the approach Flashbots are taking [3].04 How will miners adapt to MEV?
In the past, when fees were a negligible percentage of the total block revenue, miners' main focus was to get as much block reward as possible (for example, the current Ethereum block reward is 2 ETH per block). Miners tend to choose a mining pool with enough computing power to host their computing power. After years of development, mining pools have been more or less optimized to the same performance range, and mining pools that lag behind their peers will be easily identifiable and soon be squeezed out by competitors.
Except for the basic parameters of some mining pools (such as income distribution plan, handling fee for joining the mining pool, etc.), miners don't care which mining pool they join; users don't really care which mining pool processes their transactions; and as long as Transaction fees are attractive, and mining pools don't care who the users are.But as MEV (miner-extractable value) as a percentage of total block revenue grows, the considerations of miners, mining pools, and users start to become more nuanced. With MEV, the block space market mechanism will change from a purely commodity market to include some elements of a matching market. When users submit transactions, they should be aware of the mining pool's ability to process their transactions in a timely manner.All else being equal, MEV will cause the gas price to be higher than it would be without MEV. This means that miners have indirectly captured a fraction of the total value of MEV extracted by arbitrage traders, currently estimated at around 12%. A recent analysis also suggests that fees earned by miners via MEV will eventually exceed “regular” revenue streams. That said, miners are profit-seeking entities that may wish to capture more MEV. By leveraging their power over the order in which transactions are processed, miners can choose to insert, reorder, and even censor transactions to maximize the profit of their included transactions.Theoretically, in extreme cases, miners would continually reorganize the blockchain as they try to extract MEV from blocks that have been included in the past. While possible, this scenario is not clearly credible: Miners are (mostly) structurally long-term holders of ETH, and this restructuring action would directly negatively affect their ETH investments.A more optimistic view is that miners will decide to outsource MEV extraction to arbitrage traders. Miners can use the Flashbots method described above, or rent out their computing power to specialized trading companies.We expect that Ethereum mining pools will inevitably start to become more active in the MEV extraction process as they seek to get the best yield for the hashrate they provide. As the MEV extraction race heats up, it remains to be seen how the (de)centralization of the Ethereum mining ecosystem will be affected by this change in market structure.05 How will users in the ecosystem participate in MEV?
The financialization of computing power is an important potential trend in the mining industry. For miners, selling their hashpower through hashpower instruments is a way for them to lock in future income. Similar to renting computing power on a cloud mining platform, forward contracts allow miners to sell a fixed amount of computing power for a certain period of time at a prepaid price. If the block space is similar to real estate, then the computing power is the equity of the real estate, and the forward contract of computing power is similar to mortgage.
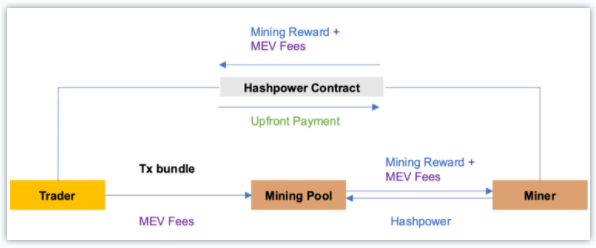
Active DeFi users who anticipate increased MEV activity on the network can speculate by purchasing these computing power tools. For example, a trader who expects a surge in MEV activity on the network in the next 15 days can purchase x amount of computing power at an upfront price for the next 15 days. During the contract period, the mining revenue plus the MEV income earned by the miner will then be sent to the trader.Both this computing power tool and MEV represent cutting-edge developments in the mining capital market. New tools are actively being developed in these directions. MEV and computing power tools close a complete loop for users and miners.
Ethereum blockspace market structure is an interesting topic to examine, and for good reason. In this analysis, we observed major differences between the GPU and ASIC computing power markets. We also identify key mechanisms that create demand-side dynamics and tie together the supply and demand sides of blockspace in terms of MEV (miner extractable value).
MEV is an inevitable consequence of the increasingly complex transaction types on Ethereum. As tools and knowledge bases for MEV become more mainstream, more interesting MEV patterns will emerge.Changing the way a good is marketed also changes how that good is produced. MEV creates new revenue streams for the mining industry, which in turn impacts how the mining industry interacts with buyers of block space (i.e. transaction users). A new pattern will emerge in the Ethereum mining cycle.Thanks to Tina Zhen, Tarun Chitra, Hasu, and Alex Obadia for comments on an early draft of this article.Links mentioned in the text:
[1]: https://arxiv.org/abs/1904.05234[2]: https://samczsun.com/escaping-the-dark-forest/[3]: https://ethresear.ch/t/flashbots-frontrunning-the-mev-crisis/8251










